
 Italy Food Preservatives Market | 2026-2036
Italy Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Preservatives Market Foresight
Ready-to-eat meat processing is shifting toward natural preservation systems as Italian consumers reject synthetic additives. Cargill Incorporated leverages its European ingredient network to supply fermented vinegars and cultured dextrose solutions. Kerry Group plc sustains competitive position through integrated taste-and-preservation platforms tailored to Mediterranean recipes. DSM-firmenich specializes in enzyme-based shelf-life extension, occupying a premium niche among Parma ham and salami producers.
Food preservatives encompass chemical and biological substances added to food matrices to inhibit microbial spoilage, enzymatic degradation, and oxidative rancidity, typically dosed at 0.01% to 0.5% by weight depending on water activity and pH targets. Their primary commercial purpose centers on extending distribution reach for perishable goods while maintaining sensory and nutritional integrity through controlled-release mechanisms. Antioxidant formulations now lead value generation as olive oil-infused products and omega-3 fortified lines require lipid stabilization against thermal stress during southern European transit. Acid-based preservatives, particularly buffered vinegar and citric acid blends, represent the fastest-expanding category as clean-label mandates from retail chains displace traditional sorbate systems in beverage and dairy applications.
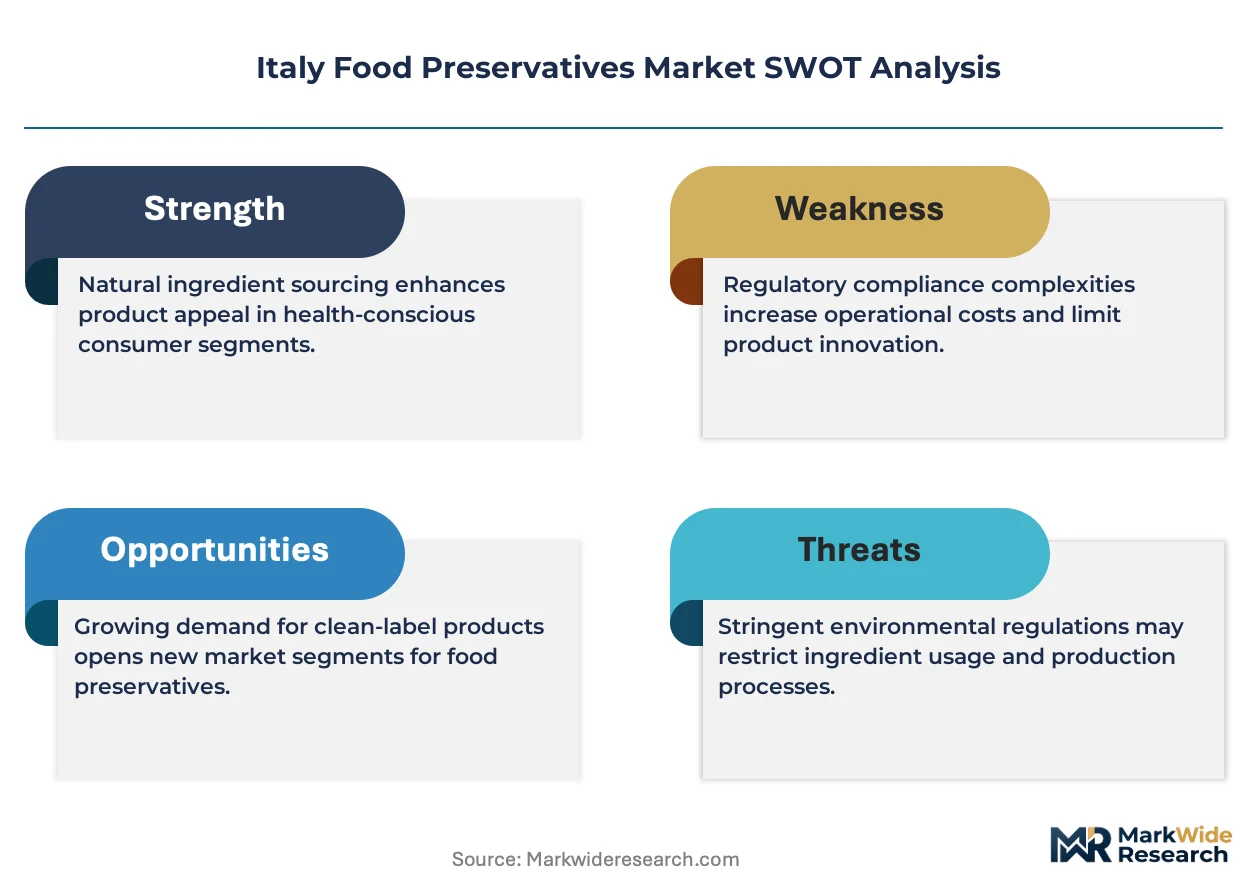
EU Regulation 1333/2008 on food additives governs permitted preservative categories and maximum levels across Italian formulations, while EFSA re-evaluations of nitrates in cured meats are tightening usage thresholds. Italy's National Institute of Health coordinates with ECHA to enforce REACH compliance on imported preservative raw materials, creating documentation burdens for non-European suppliers. Stakeholders must monitor pending EFSA opinions on benzoate alternatives and calibrate R&D pipelines toward fermentation-derived solutions that satisfy both regulatory stringency and consumer label expectations.
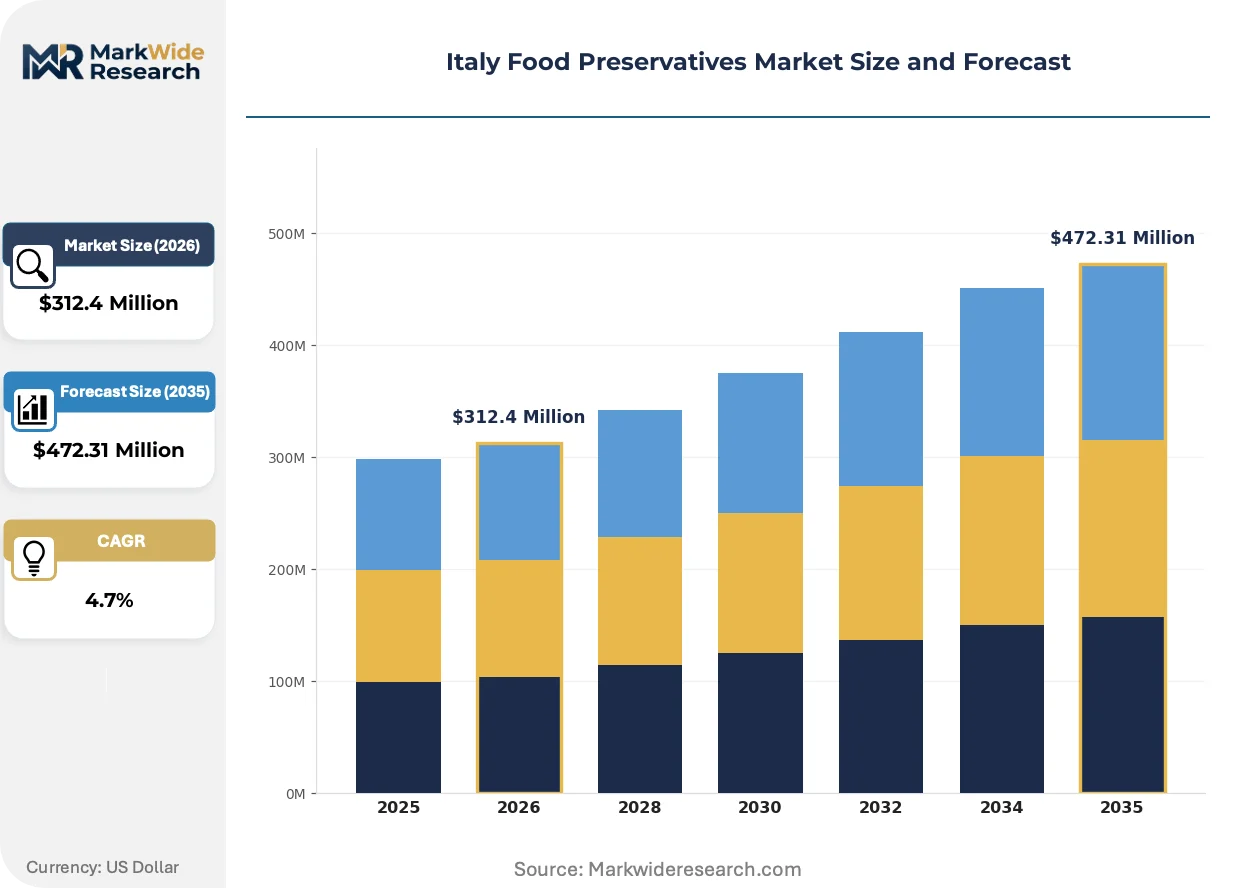
Market Dynamics
Clean-label reformulation mandates from Italian retail chains are forcing preservative suppliers to abandon synthetic sorbates and benzoates, compressing formulation windows while extending R&D cycles for fermentation-derived alternatives that satisfy both EU Regulation 1333/2008 and consumer label expectations.
Growth Catalysts
- EU Green Deal alignment:Italy's carbon-neutral packaging targets are accelerating demand for plant-derived antioxidant systems in olive oil and omega-3 fortified products requiring lipid stabilization during southern European transit.
- Parma ham and salami producers:Traditional cured meat manufacturers are deepening adoption of enzyme-based shelf-life extension to maintain export viability under tightening EFSA nitrate re-evaluations.
- Fermented vinegars:Buffered vinegar and citric acid blends are capturing formulation share in beverage and dairy applications as clean-label mandates displace potassium sorbate systems.
Market Restraints
- REACH documentation burdens:ECHA enforcement on imported preservative raw materials creates compliance friction for non-European suppliers seeking Italian market entry.
- Input cost volatility:Cultured dextrose and fermentation-derived acids face price pressure from agricultural feedstock fluctuations and energy-intensive bioprocessing requirements.
- Technical substitution limits:Natural alternatives cannot match synthetic preservatives in high-water-activity applications, constraining clean-label penetration in certain ready-to-eat categories.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily food manufacturing corridors remain underserved by integrated taste-and-preservation platforms tailored to Mediterranean recipes.
- Controlled-release mechanisms:Encapsulation technologies converging with pH-responsive delivery systems enable precision dosing in heat-stressed distribution environments.
- Retail chain private-label mandates:Coop Italia and Conad clean-label procurement specifications create captive demand for documented fermentation-origin preservative systems.
Industry Challenges
- Formulation chemist scarcity:Talent gaps in natural preservative stabilization expertise are extending product development timelines for SME ingredient suppliers.
- EFSA opinion uncertainty:Pending benzoate alternative re-evaluations force parallel R&D pipeline maintenance, inflating capex allocation for regulatory scenario planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Preservatives Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Nitrates, Acids, Antioxidants Application: Beverages, Dairy Products, Bakery, Meat Processing End User: Food Manufacturers, Retailers, Food Service Providers, Households Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Kerry Group plc, BASF SE, DSM-firmenich, Corbion NV, Jungbunzlauer Suisse AG, Tate & Lyle PLC, International Flavors & Fragrances Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Preservatives Market Shifts & Advancements
Fermentation-derived preservation systems are compressing synthetic incumbent positions while regulatory stringency and procurement centralization reshape competitive requirements across Italian food manufacturing corridors.
Bioprocessed organic acids from agricultural sidestream feedstocks are overtaking petroleum-derived synthetic equivalents in bakery and meat processing applications. Northern Italian industrial clusters around Milan and Bologna are adopting these systems at accelerated pace to satisfy retail audit requirements. This technology is overtaking traditional chemical preservation in premium positioning strategies, compressing margin structures for legacy sorbate suppliers.
EFSA re-evaluations of nitrates in cured meats are tightening maximum usage thresholds ahead of formal mandate adoption. Italian cured meat exporters are pre-emptively reformulating with celery powder and fermented plant extracts to secure continued market access. Parma ham and salami producers face the most acute compliance pressure, driving accelerated validation of alternative curing technologies.
Italian retail procurement teams are consolidating supplier relationships around integrated ingredient platforms that combine preservation with taste modulation. Beverage and dairy formulators are displacing single-function chemical purchases with multi-attribute solutions from European network suppliers. This concentration is most visible in northern industrial corridors where manufacturing scale enables volume-based partnership negotiations.
Italy Food Preservatives Market Segmentation
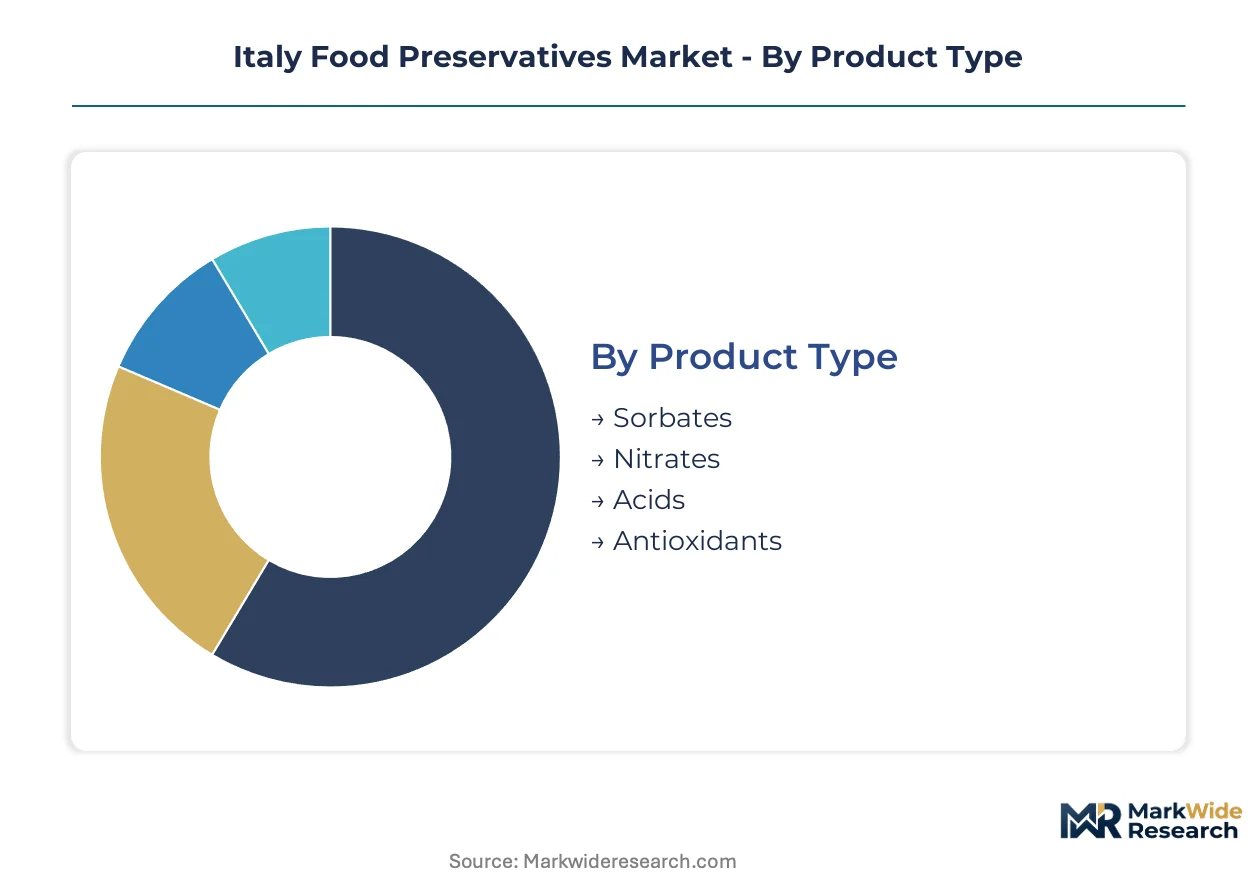
Preservative procurement patterns across Italian food manufacturing reflect divergent technical requirements between mass-market distribution and premium positioning strategies. Segmentation reveals how formulation specifications fragment across regional industrial clusters and end-use applications.
Product Type:
Supply concentration favors fermentation-derived alternatives in northern Italian manufacturing corridors around Milan and Bologna.
- Antioxidants:Lipid stabilization formulations dominate value generation as olive oil-infused products and omega-3 fortified lines require protection against thermal stress during southern European transit. Northern industrial clusters anchor procurement volumes for these systems.
- Acids:Buffered vinegar and citric acid blends are displacing traditional sorbate systems in beverage and dairy applications as clean-label mandates from Coop Italia and Conad reshape formulation requirements. Parma ham and salami producers drive specialized demand for pH-controlled acidification.
- Sorbates:Synthetic potassium sorbate faces compressed formulation windows under EU Regulation 1333/2008 compliance pressure.
- Nitrates:EFSA re-evaluations are tightening maximum usage thresholds in cured meat applications, forcing pre-emptive reformulation with celery powder alternatives.
Antioxidants absorb the bulk of installed capacity; acids are expanding most quickly.
Application:
Cost tier differentiation separates commodity preservatives from premium fermentation-derived systems across Italian food manufacturing.
- Meat Processing:Ready-to-eat meat processing is shifting toward natural preservation systems as Italian consumers reject synthetic additives. Parma ham and salami producers face acute compliance pressure from EFSA nitrate re-evaluations, driving accelerated validation of enzyme-based shelf-life extension technologies.
- Bakery:Bioprocessed organic acids from agricultural sidestream feedstocks are overtaking petroleum-derived synthetic equivalents in northern Italian industrial clusters seeking retail audit compliance.
- Beverages:Acid-based preservatives capture formulation share as clean-label mandates displace potassium sorbate systems.
- Dairy Products:Fermented vinegars and cultured dextrose solutions penetrate yogurt and fresh cheese applications under procurement specifications from retail chains.
Meat processing commands premium pricing tiers; bakery applications are climbing the fastest.
End User:
Customer type determines documentation burden intensity under REACH enforcement protocols.
- Food Manufacturers:Large-scale manufacturers in Milan-Bologna corridors consolidate supplier relationships around integrated ingredient platforms combining preservation with taste modulation.
- Retailers:Coop Italia and Conad procurement teams enforce clean-label mandates that compress formulation windows for fermentation-derived alternatives.
- Food Service Providers:Institutional catering operators face margin pressure from input cost volatility in cultured dextrose and fermentation-derived acids.
- Households:Consumer-packaged preservative sales concentrate in southern regions with lower industrial manufacturing density.
Food manufacturers absorb the bulk of installed capacity; retailers are gaining share fastest.
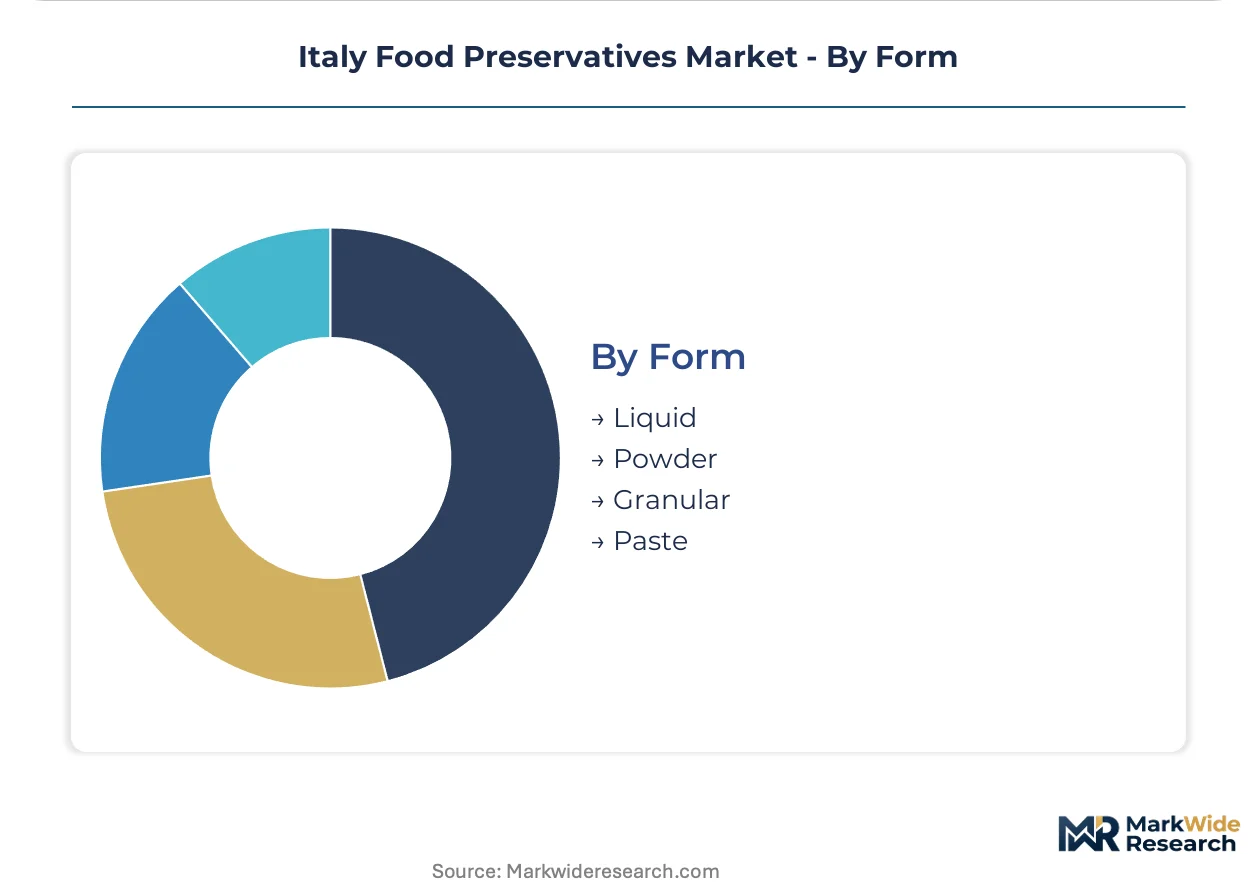
Form:
Volume throughput favors powder and liquid systems in high-throughput northern manufacturing facilities.
- Liquid:Buffered vinegar solutions enable precision dosing in beverage and dairy applications requiring homogeneous distribution.
- Powder:Granular acid blends serve bakery and meat processing lines with automated dosing equipment.
- Granular:Controlled-release encapsulation technologies converge with pH-responsive delivery systems for heat-stressed distribution environments.
- Paste:Concentrated fermentation-derived systems target small-batch cured meat producers in Emilia-Romagna.
Liquid formulations absorb the bulk of installed capacity; granular systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Zona Franca incentives in Lombardy and Emilia-Romagna concentrate preservative demand around Milan-Bologna manufacturing corridors, where food processing density exceeds southern regions by a factor of three.
Lombardy
Pharmaceutical-grade antioxidant production serves olive oil fortification lines requiring lipid stabilization against thermal stress. REACH enforcement through ECHA documentation protocols filters non-European raw material suppliers from Milan-hub procurement networks. Bergamo-based encapsulation specialists deploy pH-responsive delivery systems for heat-stressed distribution environments.
Emilia-Romagna
Parma ham and salami producers drive enzyme-based shelf-life extension adoption under tightening EFSA nitrate re-evaluations. EU Regulation 1333/2008 compliance audits concentrate in Bologna food technology parks. Modena vinegar fermentation clusters supply buffered acid systems displacing potassium sorbate in retail chain formulations.
Piedmont
Turin beverage manufacturers anchor demand for citric acid blends in clean-label reformulation mandates. Italy's National Institute of Health coordinates regional EFSA alignment workshops for benzoate alternative validation. Alessandria dairy processing corridors adopt cultured dextrose solutions under Coop Italia procurement specifications.
Veneto
Verona wine vinegar derivatives penetrate bakery applications seeking petroleum-free acidification. EU Green Deal carbon-neutral packaging targets accelerate plant-derived antioxidant trials in Padua food research institutes. Vicenza meat processing SMEs face margin compression from agricultural feedstock volatility in fermentation-derived inputs.
Campania
Naples food manufacturing remains underserved by integrated taste-and-preservation platforms relative to northern corridors. Regional development funds target bioprocessing infrastructure gaps for agricultural sidestream valorization. Salerno packaging converters test controlled-release mechanisms for southern European transit stress conditions.
Italy Food Preservatives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived platforms commanding premium positioning against synthetic commodity suppliers. The vendor base organizes around three strategic archetypes: integrated European ingredient networks, enzyme-based shelf-life specialists, and agricultural sidestream bioprocessors. Consolidation pressure intensifies as retail procurement centralization favors multi-attribute solution providers over single-function chemical vendors. Capacity expansion and backward integration into fermentation feedstocks represent the dominant competitive vectors reshaping supplier relationships.
Among integrated European ingredient networks, Cargill Incorporated and Kerry Group plc occupy positions exemplifying the taste-and-preservation convergence strategy. DSM-firmenich anchors the enzyme-based shelf-life extension archetype serving cured meat export compliance requirements. These three entities represent the competitive tier best positioned to absorb Coop Italia and Conad clean-label procurement centralization, while Corbion NV and Jungbunzlauer Suisse AG sit within the fermentation-derived acid specialization segment capturing formulation share from displaced sorbate systems.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Kerry Group plc |
| BASF SE |
| DSM-firmenich |
| Corbion NV |
| Jungbunzlauer Suisse AG |
| Tate & Lyle PLC |
| International Flavors & Fragrances Inc. |
| Others |
Supply & Pricing Matrix
Formulation chemist scarcity in Milan-Bologna corridors widens labor-cost spreads between premium fermentation-derived systems and commodity synthetic preservatives, compressing margin structures for mid-tier suppliers unable to command clean-label premiums.
Pricing Analysis
Short lead-time premiums for enzyme-based shelf-life extension systems command substantial markups over spot-market potassium sorbate inventories. Three-tier pricing structure across fermentation-origin premium, blended standard, and synthetic economy levels reflects certification grade and REACH documentation completeness. Cost compression in the economy tier intensifies because agricultural feedstock volatility feeds through to cultured dextrose production. Retail chain procurement teams exhibit lowest price sensitivity, while southern Italian SME meat processors face acute margin pressure from input cost swings.
Supply Chain Analysis
Inbound freight costs from Dutch and German fermentation facilities concentrate upstream supply for northern Italian manufacturing corridors. Raw material flows draw from agricultural sidestream feedstocks in France, bioprocessing intermediates from Belgium, and encapsulation-grade polymers from Switzerland. Single-source vulnerability around Modena vinegar fermentation clusters exposes formulation supply to regional weather disruption. Distribution runs through consolidated logistics hubs serving Coop Italia and Conad central procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's food preservatives sector sits in a technology-transition phase where fermentation-derived acidification systems displace legacy petroleum-derived sorbate platforms.
For Market Incumbents: Lock in backward integration into agricultural sidestream feedstocks to defend margin position against input cost volatility. Prioritize capacity expansion in Emilia-Romagna to capture Parma ham and salami reformulation demand under tightening EFSA nitrate thresholds. Certification investment in EU organic and clean-label standards creates switching costs for retail chain procurement relationships. For New Entrants and Emerging Players: Specialty distributors serving Campania and Sicily food manufacturing corridors represent the most accessible channel entry point. Target underpenetrated southern Italian regions with fermentation-derived paste formulations for small-batch cured meat producers. A co-development partnership with regional development funds bioprocessing infrastructure gaps enables asset-light market entry. For Investors and Strategic Acquirers: Re-rating potential sits with enzyme-based shelf-life specialists given EFSA nitrate re-evaluation timelines accelerating alternative curing technology adoption. Long-term viability favors platforms combining preservation with taste modulation capabilities. Monitor pending benzoate alternative opinions as the critical inflection signal for fermentation-derived valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | Captive agricultural sidestream supply insulates margin structures from commodity volatility in northern corridors. |
| Encapsulation Technology Licensing | pH-responsive delivery systems unlock premium positioning for heat-stressed southern European transit applications. |
| Retail Chain Partnership Program | Coop Italia and Conad clean-label procurement specifications create multi-year offtake visibility for fermentation-origin suppliers. |
| Regional Manufacturing Footprint | Campania production capacity addresses logistics cost disadvantages facing southern Italian food manufacturers. |
| Regulatory Pre-Approval Investment | Early EFSA engagement on celery powder alternatives secures first-mover positioning in cured meat reformulation. |
Research Methodology
Multi-period observation of formulation substitution rates, procurement contract tenors, and regulatory opinion timelines anchored the trend analysis, supplemented by interviews with plant managers at Milan-Bologna manufacturing facilities, procurement leads at Coop Italia and Conad, technical R&D directors at fermentation suppliers, and regulatory affairs specialists navigating EFSA re-evaluation protocols. Secondary validation drew from EU Regulation 1333/2008 amendment tracking, EFSA scientific opinion databases, REACH registration dossiers, and Italian National Institute of Health enforcement bulletins. Bottom-up segment sizing triangulated against top-down industrial production value estimates.
Input-output matrices mapped preservative demand across meat processing, bakery, beverage, and dairy applications against supply capacity from fermentation, chemical synthesis, and agricultural extraction routes. Segmentation dimensions modeled encompassed product type tier, end-use application, customer scale archetype, and regional industrial cluster. CAGRs were derived from slope analysis of annual volume trajectories adjusted for regulatory mandate adoption curves and retail procurement specification rollout schedules. Feedstock cost indices and energy price scenarios fed sensitivity testing across the projection horizon.
Caveats apply where EFSA nitrate opinion timing, EU Green Deal packaging mandate acceleration, or agricultural commodity price shocks could materially shift the outlook. Forecasts embed assumptions around clean-label procurement penetration rates and fermentation technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market