
 Non-GMO Citric Acid Market | 2026-2036
Non-GMO Citric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Non-GMO Citric Acid Market Insights
Modular packaging configurations across powder, liquid, and crystalline grades is pivoting procurement patterns for mid-size food manufacturers seeking batch flexibility. Jungbunzlauer Suisse leverages its Swiss fermentation infrastructure to sustain premium positioning in pharmaceutical-grade supply. Cargill anchors North American volume through integrated corn-sugar feedstock control. Citrique Belge differentiates via specialized granulated formats for European beverage clients.
Non-GMO citric acid denotes fermentation-derived citric acid produced from carbohydrate substrates verified free of genetically modified organisms through identity preservation and testing protocols, typically meeting purity specifications of 99.5 percent anhydrous basis and serving as an acidulant, preservative, and chelating agent across food, pharmaceutical, and industrial applications. Powder and liquid product types capture divergent margin structures, with liquid formats commanding premium pricing in automated beverage processing while powder dominates shelf-stable packaged goods volume. Food and beverages applications lead absolute consumption, though pharmaceuticals exhibits tighter certification requirements and corresponding price premiums.
FDA food labeling regulations and USDA organic standards shape domestic market access requirements for non-GMO claims in the United States, while REACH documentation and EU Green Deal sustainability metrics govern European import and formulation eligibility. Stakeholders must monitor evolving genome-editing regulatory classifications, as CRISPR-derived organisms risk challenging existing non-GMO certification boundaries across multiple jurisdictions.
Market Dynamics
Clean-label beverage procurement is restructuring supply relationships as mid-size manufacturers abandon spot-market purchasing for multi-year certification contracts tied to identity-preserved corn-sugar feedstocks.
Growth Catalysts
- EU Green Deal documentation mandates:REACH-aligned supply chain verification requirements are compelling pharmaceutical formulators to source certified non-GMO acidulants for European market access.
- Automated beverage processing expansion:Liquid citric acid formats are displacing powder in high-throughput bottling facilities seeking reduced handling labor and batch consistency.
- Germany:Regional beverage and pharmaceutical clusters in Baden-Württemberg and Bavaria are consolidating procurement through certified ingredient consortia.
Market Restraints
- Feedstock cost volatility:Non-GMO corn-sugar premiums fluctuate with identity-preservation logistics and seasonal harvest yields in North American growing regions.
- Supply concentration risk:Fermentation capacity clusters in Switzerland and Belgium create geographic vulnerability to regional energy price spikes.
- Genome-editing regulatory ambiguity:CRISPR-derived organism classifications threaten to erode existing non-GMO certification boundaries across FDA and EFSA jurisdictions.
Strategic Opportunities
- Pharmaceutical-grade certification gaps:Tighter USP and EP monograph compliance creates margin expansion potential for fermentation infrastructure investments.
- Granulated format specialization:European beverage clients are requesting free-flowing granules for automated dosing systems in carbonated soft drink production.
- Indian FSSAI clean-label adoption:Processed food exporters to European markets are building non-GMO acidulant inventories to satisfy importer documentation requirements.
Industry Challenges
- Identity-preservation testing bottlenecks:PCR verification protocols for GMO absence create 14-21 day lot-release delays that compress working capital cycles.
- Fermentation capex intensity:Pharmaceutical-grade stainless steel bioreactor installations require 36-48 month commissioning timelines that strain balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-GMO Citric Acid Market |
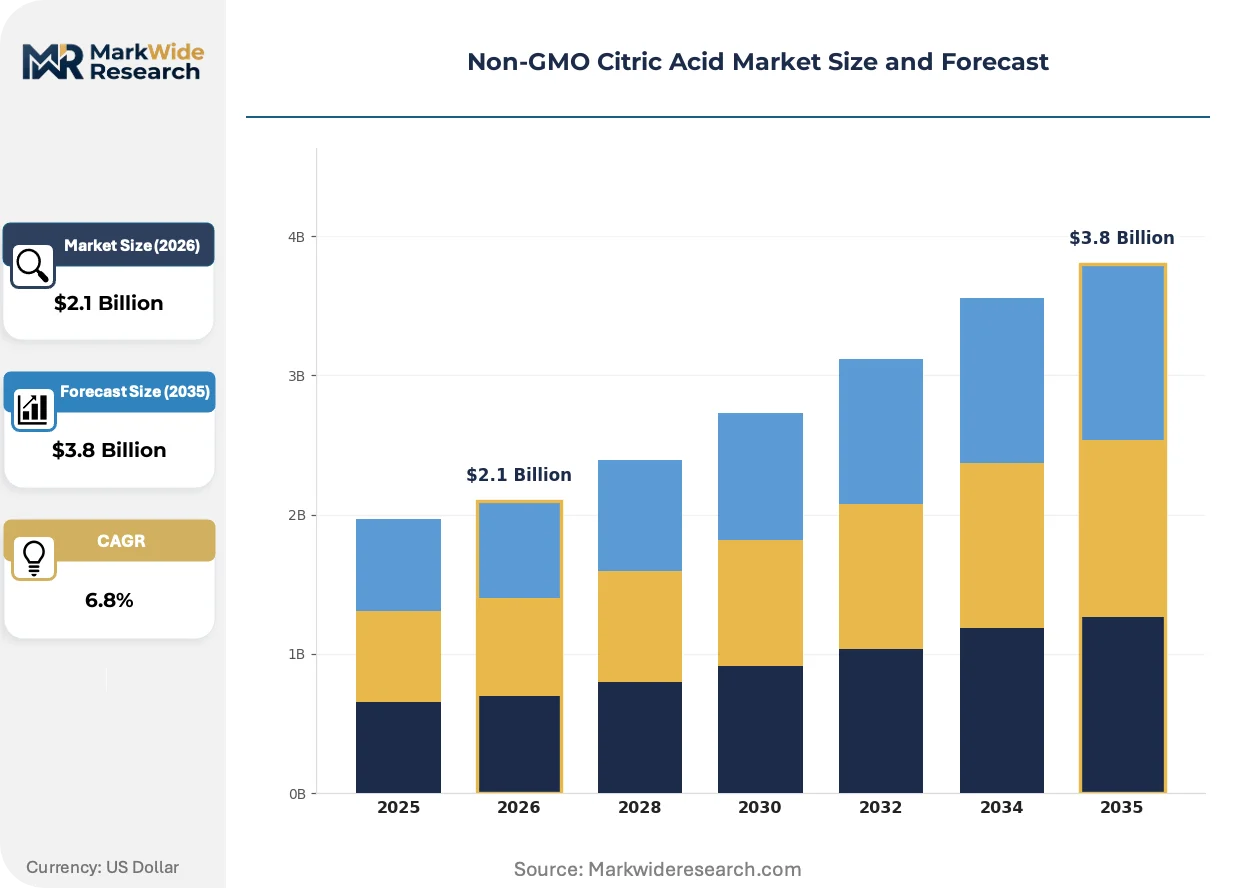
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granulated, Liquid, Crystalline Application: Food & Beverages, Pharmaceuticals, Personal Care, Cleaning Agents End User: Food Manufacturers, Beverage Producers, Cosmetic Companies, Industrial Users Packaging Type: Bags, Bottles, Drums, Bulk Containers |
| Companies Covered | Jungbunzlauer Suisse, Cargill, Archer Daniels Midland Company, Citrique Belge, Alpha Chemicals, Sucroal, American International Foods, Captain Drake, Ingredientsonline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-GMO Citric Acid Market Trends and Innovations
Continuous fermentation monitoring and blockchain-enabled provenance tracking are converging to compress certification timelines while expanding audit transparency for downstream buyers.
Membrane filtration technology for real-time metabolite analysis is electrifying process control in citric acid fermentation. Pharmaceutical manufacturers in Germany and Switzerland are adopting these sensor arrays to reduce batch-to-batch variation. The technology is compressing quality assurance overhead while enabling just-in-time certificate generation for regulated shipments.
REACH documentation expansion under EU Green Deal sustainability metrics is tightening supply chain disclosure requirements for genetically modified organism verification. Importers must now submit third-party testing protocols alongside traditional safety data sheets. Pharmaceutical applications face the steepest compliance burden as EMA inspections intensify scrutiny of acidulant excipient provenance.
Certification-driven contract structures are replacing spot-market purchasing among North American beverage manufacturers. Mid-size formulators in California and New York are locking multi-year supply agreements with embedded identity-preservation guarantees. This pattern is most visible in organic-certified product lines where USDA organic standards intersect with non-GMO verification requirements.
Non-GMO Citric Acid Market Segmentation
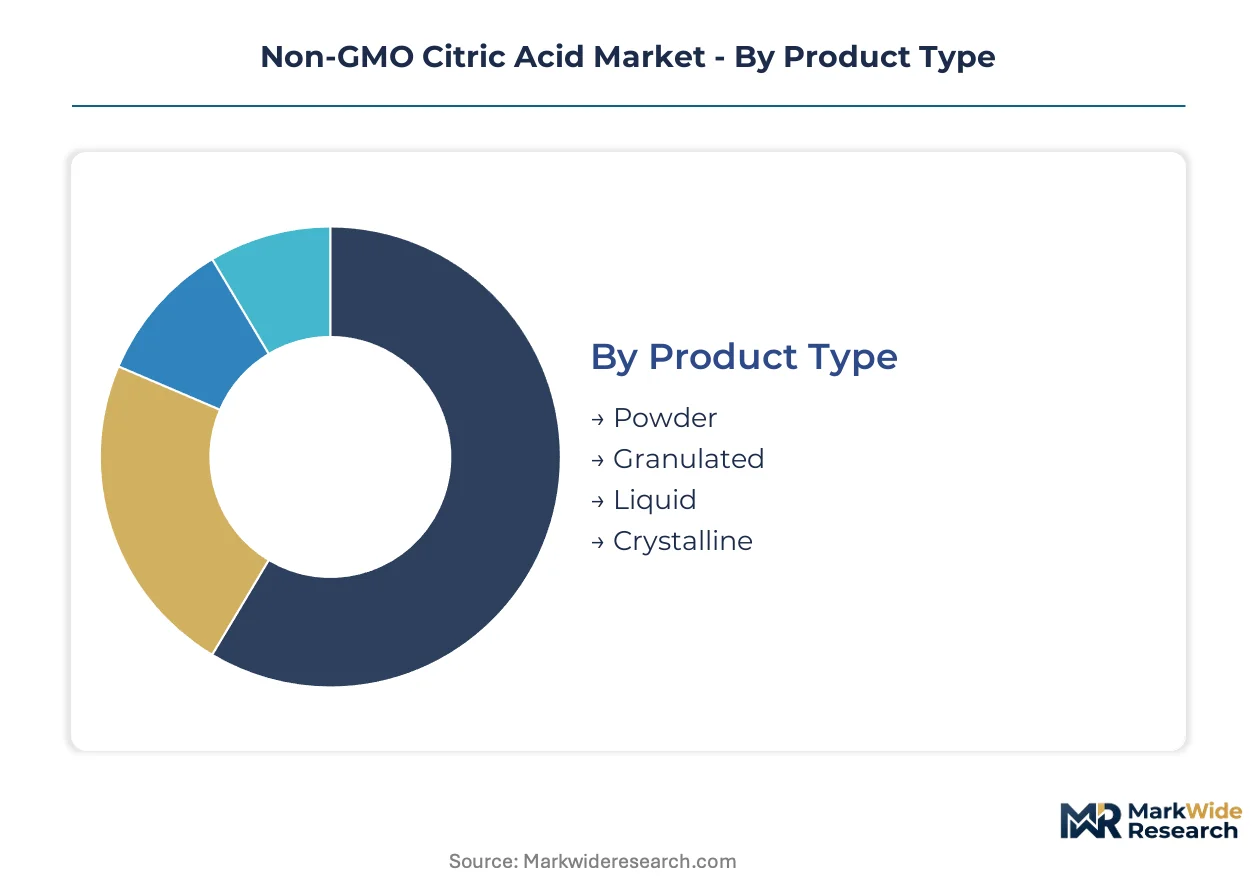
Non-GMO citric acid procurement patterns diverge sharply across product formats and end-use specifications. Certification requirements and processing automation are fragmenting demand into distinct supply contracts with divergent margin profiles.
Product Type:
Powder and liquid formats command the largest procurement volumes, though granulated variants are gaining traction in automated dosing systems.
- Powder:Anhydrous citric acid with 99.5% minimum purity serves shelf-stable packaged goods manufacturers seeking extended stability and precise batch control. US-based organic food processors in California and New York are locking multi-year supply agreements with embedded identity-preservation guarantees.
- Liquid:Aqueous solutions at 50% concentration displace powder in high-throughput beverage bottling facilities. German carbonated soft drink producers in Baden-Württemberg prioritize liquid formats for reduced handling labor and consistent acidification curves.
- Granulated:Free-flowing agglomerated particles enable automated dosing in European beverage production lines.
- Crystalline:Large crystal structures suit laboratory and pharmaceutical compounding applications requiring visual purity confirmation.
Powder leads on scale; granulated leads on momentum.
Application:
Regulatory scrutiny intensity varies across end-use categories, with pharmaceutical and food applications facing the steepest documentation burdens.
- Food & Beverages:Acidulant and preservative functions in processed foods, soft drinks, and confectionery. REACH-aligned supply chain verification requirements are compelling formulators to source certified non-GMO acidulants for European market access under EU Green Deal sustainability metrics.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications with USP and EP monograph compliance. Swiss and German manufacturers adopt membrane filtration technology with real-time metabolite analysis to reduce batch-to-batch variation and compress quality assurance overhead.
- Personal Care:pH adjustment and chelating functions in cosmetics and skincare formulations.
- Cleaning Agents:Industrial and household detergent applications leveraging chelation properties.
Food & Beverages dominates absolute consumption; Pharmaceuticals commands the steepest price premiums.
End User:
Scale and certification sophistication separate procurement behaviors across buyer categories.
- Food Manufacturers:Processed food producers requiring acidulants for preservation and flavor enhancement. Indian FSSAI clean-label adoption is driving processed food exporters to build non-GMO acidulant inventories for European importer documentation requirements.
- Beverage Producers:Carbonated and non-carbonated drink formulators with high-throughput automation needs.
- Cosmetic Companies:Personal care formulators seeking pH stability and metal ion chelation.
- Industrial Users:Cleaning product and industrial process applications with volume-driven purchasing.
Food Manufacturers anchor procurement volume; Beverage Producers are expanding contract terms fastest.
Packaging Type:
Handling automation and lot-size flexibility drive format selection across manufacturing scales.
- Bags:Multi-wall paper or woven polypropylene sacks for mid-volume powder shipments.
- Bottles:HDPE or glass containers for liquid and crystalline laboratory-grade products.
- Drums:Steel or fiber drums for liquid bulk shipments to medium-scale processors.
- Bulk Containers:Totes and tanker deliveries for high-volume beverage and pharmaceutical fermentation facilities.
Bulk Containers dominate pharmaceutical-grade logistics; Bags retain flexibility for mid-size food manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial fermentation for citric acid originated in Italian citrus processing facilities during the early twentieth century before Swiss and Belgian manufacturers scaled microbial production methods. Contemporary demand geography reflects this European heritage while incorporating North American feedstock advantages and Asian pharmaceutical growth.
United States
Midwest corn-belt processors leverage identity-preserved non-GMO feedstock networks stretching from Iowa to Illinois. FDA food labeling regulations and USDA organic standards enforce strict documentation for clean-label claims. California organic food manufacturers and New York-based beverage formulators are locking multi-year supply contracts with embedded certification guarantees.
Germany
Baden-Württemberg and Bavaria host dense clusters of carbonated beverage producers and pharmaceutical excipient formulators. REACH documentation mandates under the EU Green Deal require third-party GMO verification protocols alongside traditional safety data sheets. Stuttgart-area bottling facilities are displacing powder acidulants with liquid formats to reduce handling labor.
Switzerland
Swiss pharmaceutical manufacturers demand USP and EP monograph compliance with batch-to-batch variation controls. Swissmedic inspections intensify scrutiny of acidulant excipient provenance for regulated drug shipments. Basel-region fermentation facilities deploy membrane filtration technology with real-time metabolite analysis to compress quality assurance timelines.
India
Processed food exporters in Maharashtra and Gujarat are building non-GMO acidulant inventories to satisfy European importer documentation requirements. FSSAI clean-label adoption is accelerating among domestic manufacturers seeking export market access. Mumbai-based ingredient traders are consolidating procurement through certified supply consortia.
Belgium
Antwerp-area chemical processors specialize in granulated citric acid formats for automated European beverage dosing systems. ECHA-aligned supply chain verification requirements govern import eligibility for genetically modified organism documentation. Citrique Belge anchors regional fermentation capacity with specialized agglomerated particle production.
Non-GMO Citric Acid Market Competitive Landscape
The competitive structure tilts toward integrated fermentation specialists with captive feedstock control. Three to five dominant players anchor volume through backward integration into corn-sugar supply chains, while mid-tier regional processors compete on format specialization and certification speed. Strategic archetypes include feedstock-integrated multinationals, pharmaceutical-grade specialists with stainless steel bioreactor infrastructure, and regional format innovators serving automated dosing systems. Capacity expansion and multi-year certification contracting represent the dominant competitive moves as spot-market purchasing declines.
Among feedstock-integrated multinationals, Cargill exemplifies North American volume leadership through upstream control over corn-sugar substrates. Jungbunzlauer Suisse occupies the pharmaceutical-grade specialist position, leveraging Swiss fermentation infrastructure for premium excipient supply. Citrique Belge represents the regional format innovation archetype with granulated product development for European beverage automation. These three anchors illustrate how certification depth, geographic positioning, and format specialization stratify competitive advantage across procurement tiers.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse |
| Cargill |
| Archer Daniels Midland Company |
| Citrique Belge |
| Alpha Chemicals |
| Sucroal |
| American International Foods |
| Captain Drake |
| Ingredientsonline |
| Others |
Pricing and Supply Chain Analysis
Mid-size beverage manufacturers in Germany and California anchor procurement volume and enforce contract-based long-term offtake structures with embedded identity-preservation premiums. Their multi-year certification agreements compress spot-market liquidity and concentrate pricing power among fermentation specialists with captive corn-sugar networks.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels stratifies the market. Price differentiation hinges on USP/EP monograph compliance and REACH documentation depth. Cost compression in food-grade tiers intensifies because identity-preservation logistics inflate non-GMO corn-sugar premiums. Industrial users exhibit the sharpest price sensitivity; Swiss pharmaceutical formulators accept premium positioning for batch-to-batch variation controls.
Supply Chain Analysis
Regional distribution centers in Antwerp, Basel, and Chicago operate hub-and-spoke patterns for liquid and powder formats. Fermentation capacity clusters in Switzerland, Belgium, and the United States draw from identity-preserved corn-sugar feedstocks in Iowa and Illinois. Single-source vulnerability concentrates in Swiss stainless steel bioreactor infrastructure. Distribution runs through certified ingredient consortia serving Baden-Württemberg beverage clusters and Mumbai export processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal REACH documentation mandates drive structural demand for certified acidulants with third-party GMO verification protocols.
For Market Incumbents: Cement backward integration into identity-preserved corn-sugar networks to defend against feedstock cost volatility. Lock multi-year certification contracts with California organic food processors and Stuttgart-area bottling facilities to preempt spot-market erosion. Prioritize membrane filtration technology investments that compress 14-21 day PCR verification timelines. For New Entrants and Emerging Players: Enter via Indian FSSAI clean-label adoption corridors where processed food exporters seek European market access documentation. Target Maharashtra and Gujarat ingredient traders consolidating procurement through certified supply consortia. Lead with granulated format specialization for automated dosing systems in carbonated soft drink production. For Investors and Strategic Acquirers: Pharmaceutical-grade fermentation specialists with USP/EP monograph compliance are the most active acquirer targets in this space. Long-term viability rests on regulatory moat depth rather than volume scale. Watch EMA inspection intensity on acidulant excipient provenance as the inflection signal for certification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Cargill's corn-sugar control anchors North American volume against identity-preservation premiums. |
| Pharmaceutical-Grade Certification Investment | Jungbunzlauer Suisse leverages Swissmedic inspection alignment for premium excipient positioning. |
| Granulated Format Specialization | Citrique Belge captures European beverage automation demand with free-flowing agglomerated particles. |
| Long-term Supply Agreement | Mid-size California manufacturers lock multi-year contracts with embedded GMO verification guarantees. |
| Blockchain-Enabled Provenance Tracking | Membrane filtration convergence compresses certification timelines for REACH-aligned documentation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged fermentation plant managers, procurement leads at beverage OEMs, distribution channel partners in Antwerp and Mumbai, and regulatory affairs directors navigating FDA and ECHA requirements. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated corn processors, REACH registration databases, and FSSAI clean-label guidance documents. Bottom-up volume estimates triangulated against top-down industry association benchmarks.
Segment-weighting approaches modeled product type, application tier, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from identity-preserved feedstock availability curves and automated beverage processing adoption rates. Modeled inputs included PCR verification protocol penetration, stainless steel bioreactor commissioning timelines, and EU Green Deal documentation expansion trajectories.
Inputs from EMA inspection reports and Swissmedic batch-release records were available through the study window; gaps in CRISPR-derived organism regulatory classifications introduce uncertainty bands around genome-editing scenario forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
US Food Emulsifiers Market