
 Caramel Food Colors Market | 2026-2036
Caramel Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Caramel Food Colors Market Outlook
Asset-light contract manufacturing and toll-processing arrangements are reconfiguring competitive entry barriers for mid-tier caramel color suppliers. Cargill Incorporated leverages its integrated agricultural supply chain to secure consistent molasses and corn syrup feedstock for captive colorant production. DDW The Color House anchors its position through specialized expertise in double-concentrated liquid formulations for dark beer and spirits applications. Sethness Products Company sustains century-old brand recognition among North American beverage bottlers through dedicated technical service programs.
Caramel food colors comprise heat-treated carbohydrates derived from controlled pyrolysis or alkaline/ammonia-sulfite reactions of sugars, producing melanoidin pigments with color intensities measured by tinctorial power and specific absorbance at defined wavelengths. These colorants serve primarily to impart brown hues, enhance visual appeal, and mask variations in processed food and beverage base materials. Liquid caramel colors dominate beverage applications due to ease of dosing and uniform dispersion, while powder forms command premium positioning in dry bakery mixes and seasoning blends where moisture sensitivity governs formulation choice. The natural and organic grade segments attract margin concentration as clean-label procurement policies at retail chains and quick-service restaurant chains displace synthetic alternatives.
The FDA maintains GRAS status oversight for caramel colors under 21 CFR 73.85 while monitoring 4-methylimidazole levels, and the European Food Safety Authority enforces purity specifications through its re-evaluated opinion on caramel colors. India's FSSAI aligns with Codex Alimentarius standards while imposing additional labeling requirements for ammonia-processed variants. Stakeholders must monitor evolving maximum permissible limits for process contaminants and adapt extraction and purification investments accordingly.
Market Dynamics
Clean-label procurement mandates from multinational beverage and dairy processors are compressing demand for synthetic alternatives and elevating natural-grade caramel color premiums. EFSA's tightened purity specifications for 4-methylimidazole and process contaminants are forcing capital redeployment toward extraction and purification infrastructure.
Growth Catalysts
- EU Food Improvement Agent Package:Tighter Class III and IV caramel color specifications are accelerating displacement of non-compliant suppliers and consolidating procurement toward certified producers.
- Asia-Pacific beverage manufacturing:Clean-label formulation adoption across India's dairy and confectionery corridors is driving volume uptake of liquid and powder natural-grade variants.
- Double-concentrated liquid technology:Advanced formulation expertise for dark beer and spirits applications is creating technical switching costs that lock in processor relationships.
Market Restraints
- Molasses and corn syrup feedstock volatility:Agricultural commodity price swings constrain margin predictability for captive and merchant producers alike.
- EFSA process contaminant ceilings:Maximum permissible limits for 4-methylimidazole impose purification capex burdens that disadvantage smaller toll processors.
- Annatto and burnt sugar substitutes:Alternative natural brown colorants threaten premium positioning in clean-label bakery and seasoning applications.
Strategic Opportunities
- India's processed food corridor expansion:Underpenetrated regional dairy and confectionery markets offer volume scale for localized liquid caramel production.
- FSSAI-Codex alignment:India's harmonized ammonia-processed caramel labeling requirements create regulatory clarity that rewards early compliance investment.
- Direct-to-bottler technical service:Bypassing traditional distribution layers through embedded formulation support captures margin and locks in multi-year supply agreements.
Industry Challenges
- Pyrolysis control engineering talent:Scarce expertise in precise temperature and pH management for melanoidin pigment consistency limits capacity expansion.
- FDA GRAS substantiation timelines:21 CFR 73.85 compliance documentation for novel caramel variants extends product commercialization cycles.
- Legacy powder-to-liquid formulation integration:Dry bakery mix producers face moisture-sensitivity recalibration when adopting liquid caramel systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caramel Food Colors Market |
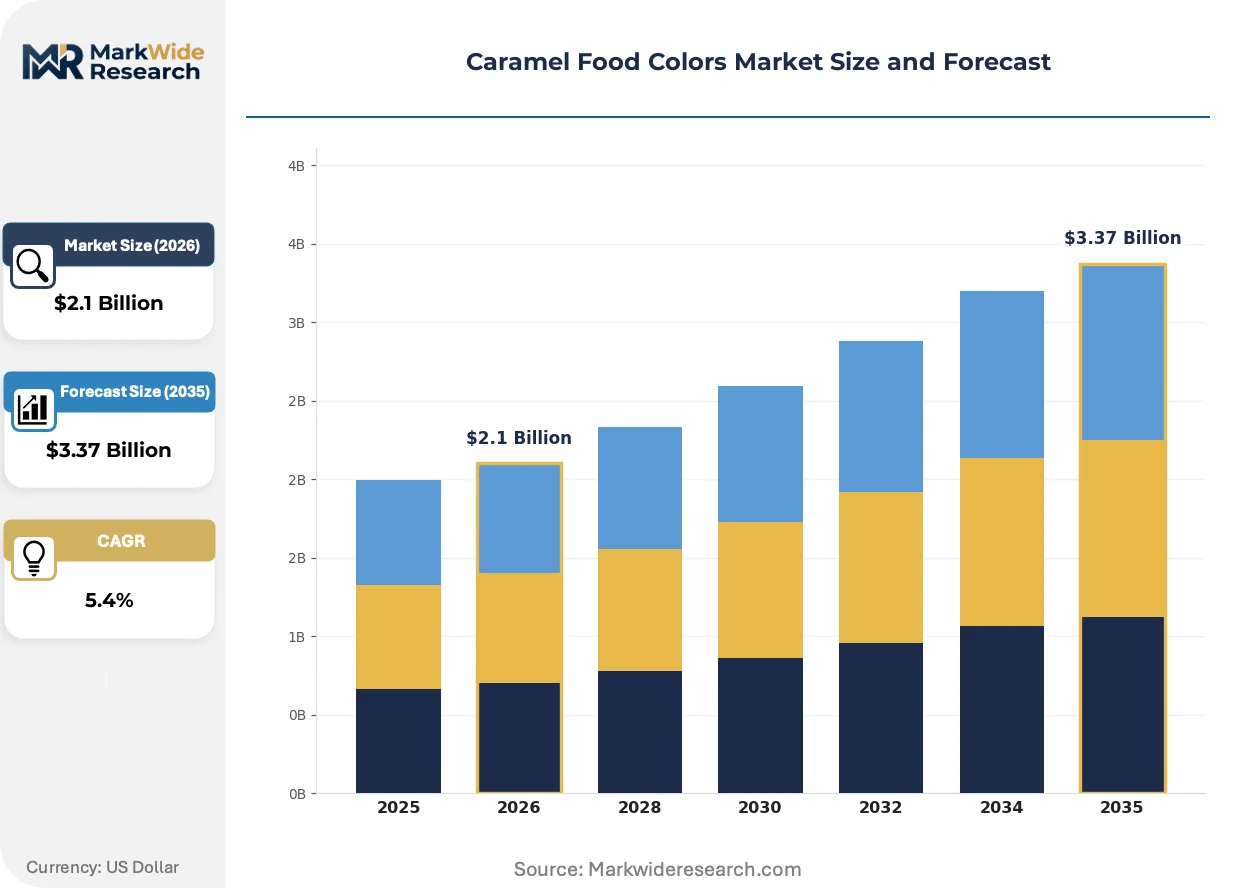
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Paste, Gel Application: Beverages, Bakery, Dairy, Snacks Grade: Synthetic, Natural, Organic, Non-GMO Form: Ready-to-Use, Concentrated, Emulsified, Spray-Dried |
| Companies Covered | Ingredion Incorporated, Cargill Incorporated, DDW The Color House, Nigay SAS, Döhler Group, Sethness Products Company, BASF SE, Aipu Food Industry Co. Ltd., Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caramel Food Colors Market Strategic Shifts
Process control digitization and regulatory purity convergence are compressing technical differentiation windows while elevating the strategic value of integrated feedstock security. These forces are reshaping competitive entry barriers across natural-grade supply tiers.
Spectrophotometric inline monitoring is digitizing color intensity measurement during alkaline and ammonia-sulfite reactions. Large-scale beverage bottlers in North America and Europe are retrofitting production lines with real-time tinctorial power feedback systems. This capability is digitizing quality assurance labor and compressing batch-to-batch variation penalties that previously eroded supplier relationships.
EFSA's re-evaluated opinion on caramel colors is mandating specific absorbance testing protocols and 4-methylimidazole quantification methods. European processors must now maintain dedicated analytical laboratories or third-party certification contracts to maintain market access. Class III and IV caramel suppliers serving EU-exporting food manufacturers face the steepest compliance cost escalation and are consolidating toward integrated agricultural-colorant conglomerates.
Quick-service restaurant chains and retail private-label programs are unbundling colorant procurement from compound ingredient purchasing. Beverage and dairy processors now issue direct specifications to caramel specialists rather than accepting distributor-formulated blends. This pattern concentrates most visibly in India's organized food retail expansion, where centralized procurement desks at modern trade chains bypass traditional spice and ingredient intermediaries.
Caramel Food Colors Market Segmentation
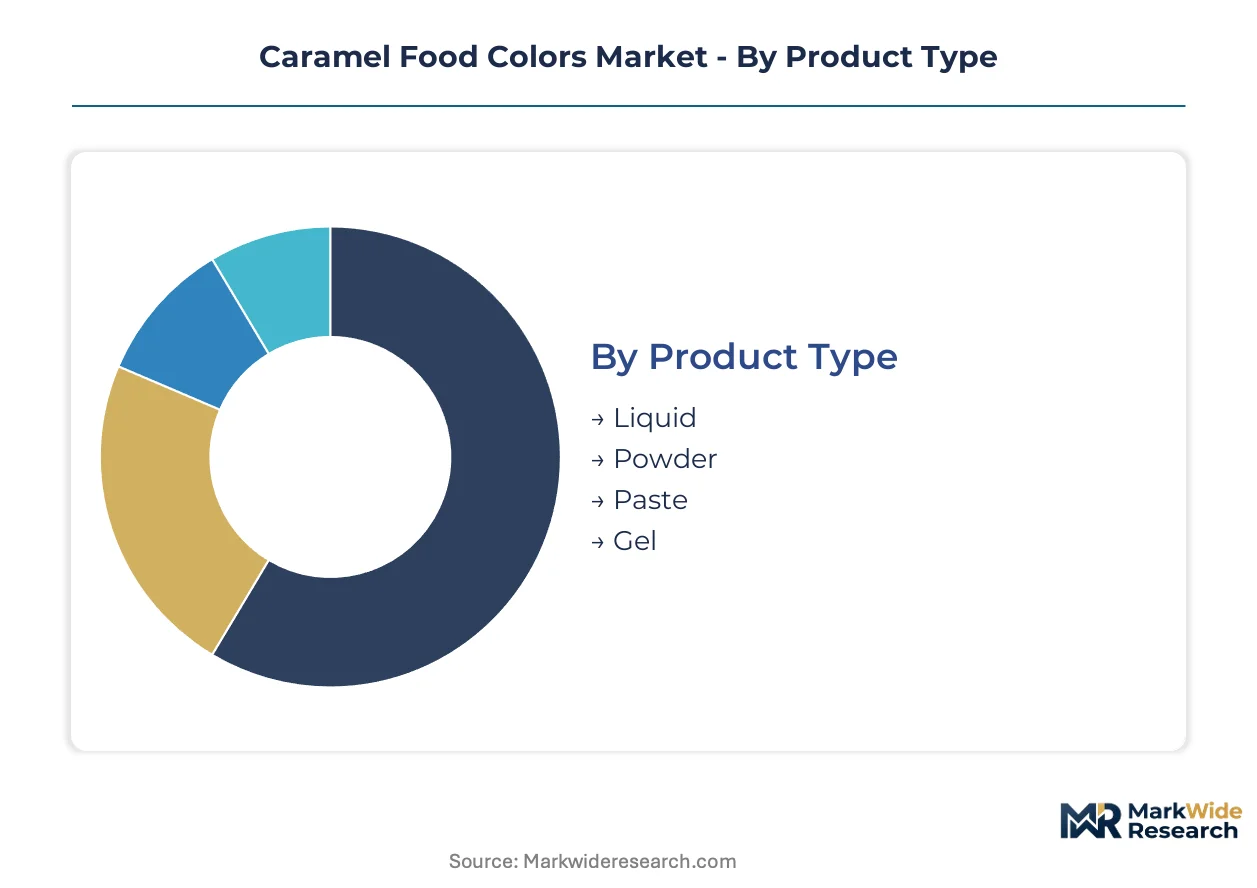
Caramel colorant procurement varies sharply across formulation requirements, with beverage bottlers prioritizing dosing precision while dry mix manufacturers demand moisture stability. Technical service intensity and specification complexity determine supplier relationship durability within each segment tier.
Product Type:
After-sales technical support intensity escalates with formulation complexity, as beverage processors require embedded dosing calibration and powder users need dispersion troubleshooting.
- Liquid:Pumpable solutions with standardized tinctorial power enable inline dosing systems at bottling facilities. Demand concentrates among North American and European dark beer and spirits producers seeking batch-to-batch consistency through real-time spectrophotometric feedback loops.
- Powder:Spray-dried or agglomerated variants with controlled particle size distribution suit moisture-sensitive dry mixes. India's organized retail chains and quick-service restaurant procurement desks drive volume uptake for bakery premix and seasoning blend applications where shelf stability governs selection.
- Paste:High-viscosity intermediate format bridges liquid convenience with concentrated pigment loading for artisanal confectionery processors.
- Gel:Thixotropic systems with suspended solids target specialized decorative icing and fondant applications requiring precise viscosity control.
By volume, liquid leads. By growth pace, powder is ahead.
Application:
End-use concentration patterns reflect divergent regulatory exposure and clean-label procurement maturity across food processing tiers.
- Beverages:Carbonated soft drinks, dark beers, spirits, and flavored waters absorb the majority of Class III and IV caramel volumes. EFSA's tightened 4-methylimidazole ceilings and India's FSSAI-Codex alignment are accelerating displacement toward certified natural-grade suppliers in carbonated and alcoholic segments.
- Bakery:Bread crust browning, cookie coloration, and cake decoration utilize powder and paste formats where moisture sensitivity limits liquid adoption. India's processed food corridor expansion and modern trade procurement centralization are driving volume scale for localized production.
- Dairy:Ice cream variegates, flavored milks, and yogurt coatings demand emulsified caramel systems with fat compatibility and heat stability during UHT processing.
- Snacks:Seasoning coatings for extruded and fried products require spray-dried powders with adhesion properties and resistance to lipid oxidation during high-temperature processing.
Beverage applications command the largest volume share. Dairy and snacks are climbing the fastest as clean-label mandates penetrate processed food categories.
Grade:
Margin stratification across certification tiers reflects raw material provenance, extraction complexity, and procurement policy enforcement at retail and foodservice chains.
- Natural:Heat-treated carbohydrate derivatives without ammonia or sulfite reagents, compliant with EU organic regulation and US NOP standards. Clean-label procurement policies at multinational beverage and dairy processors are compressing synthetic alternatives and elevating premiums for certified natural variants.
- Organic:Certified organic feedstock molasses or corn syrup with full chain-of-custody documentation. Quick-service restaurant chains and retail private-label programs in North America and Western Europe are unbundling colorant procurement from compound ingredients, concentrating demand toward certified organic specialists.
- Synthetic:Conventional Class I-IV caramel colors produced with standard feedstocks and process controls. EFSA purity specifications and FDA 4-methylimidazole monitoring are constraining volume growth in export-oriented applications.
- Non-GMO:Identity-preserved corn syrup or cane sugar derivatives with third-party verification. North American processors facing retailer non-GMO verification requirements are driving specification adoption.
Natural grade dominates current volume. Organic certification is gaining share fastest as procurement policies harden at chain scale.
Form:
Processing integration requirements and capital equipment compatibility determine form selection across manufacturing scale tiers.
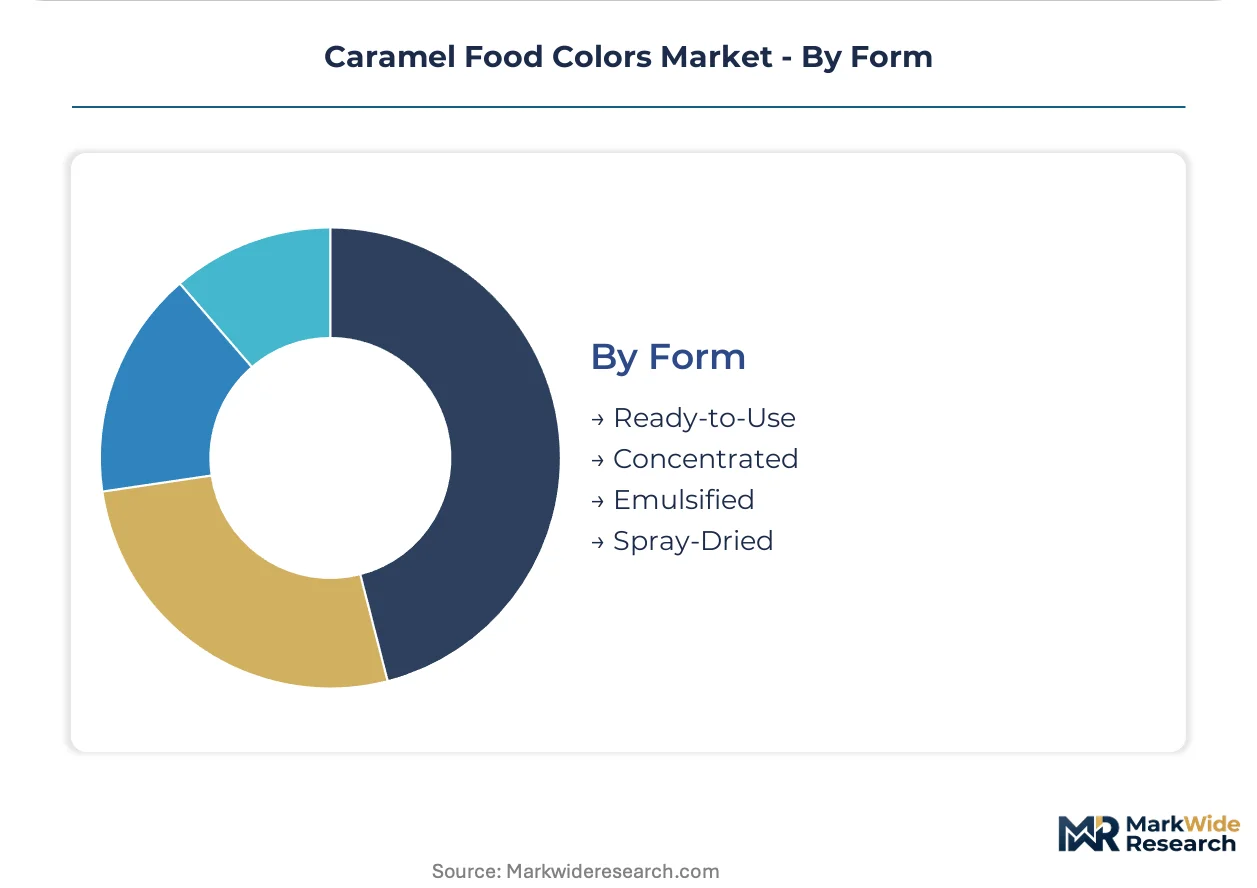
- Ready-to-Use:Standardized dilutions for immediate incorporation without additional hydration or dispersion steps. Small and mid-tier processors without dedicated colorant handling infrastructure favor this format for operational simplicity.
- Concentrated:Double-strength and higher tinctorial power variants reduce logistics costs and storage footprint. DDW The Color House anchors positioning through specialized expertise in double-concentrated liquid formulations for dark beer and spirits applications.
- Emulsified:Lipophilic systems with surfactant stabilization for fat-based applications including ice cream variegates and compound coatings.
- Spray-Dried:Atomized and dehydrated particles with rapid reconstitution properties for dry mix integration and seasoning adhesion.
Ready-to-Use leads by volume. Concentrated forms are expanding most quickly as large-scale processors optimize logistics and storage economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in caramel colorants tilt toward surplus regions with integrated molasses supply chains and deficit markets with expanding beverage manufacturing. The United States and Germany maintain production surpluses serving Latin American and Asian processors. India and Brazil absorb significant import volumes as domestic clean-label formulation accelerates.
United States
Dark beer and spirits bottlers in Wisconsin and Colorado drive concentrated demand for double-strength liquid formulations. FDA maintains GRAS oversight under 21 CFR 73.85 with 4-methylimidazole monitoring protocols. Chicago and Milwaukee host technical service hubs where caramel specialists embed dosing calibration teams directly at bottler facilities.
Germany
EFSA's re-evaluated purity specifications for Class III and IV caramel colors force capital redeployment toward extraction infrastructure across Bavarian and North Rhine-Westphalian production zones. The country's national food safety regulator enforces specific absorbance testing and process contaminant ceilings. Munich anchors specialized analytical laboratory networks certifying export batches to EU and Asian markets.
India
Dairy processors in Maharashtra and Gujarat expand procurement of natural-grade liquid caramel for flavored milk and ice cream variegates. FSSAI aligns ammonia-processed caramel labeling requirements with Codex Alimentarius standards while imposing additional declaration obligations. The Mumbai-Pune processed food corridor concentrates volume uptake as modern trade chains centralize procurement desks.
Brazil
São Paulo state beverage bottlers and confectionery processors absorb imported caramel colorants amid domestic clean-label transition. ANVISA maintains pharmaceutical-grade purity expectations that spill over into food colorant compliance culture. Campinas and Sorocaba industrial clusters attract toll-processing investments from multinational agricultural-colorant conglomerates.
China
Carbonated soft drink manufacturers in Guangdong and Zhejiang provinces scale natural-grade caramel adoption as quick-service restaurant chains harden procurement policies. SAMR enforces GB standards for food additives with tightening process contaminant surveillance. The Yangtze River Delta concentrates spray-dried powder production for seasoning blend exports to Southeast Asian markets.
Caramel Food Colors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation expertise and feedstock security. The vendor base organizes around three tiers: agricultural conglomerates with captive molasses supply, dedicated colorant houses with technical service depth, and regional toll processors serving price-sensitive segments. Strategic consolidation favors backward integration into feedstock control and forward embedding at bottler technical service layers.
Within the integrated agricultural tier, Cargill Incorporated exemplifies feedstock-secured production models. DDW The Color House and Sethness Products Company occupy positions as specialized formulation houses with century-old technical service relationships. Sensient Technologies Corporation represents the diversified ingredient platform archetype with cross-category colorant capabilities. These three anchors illustrate how competitive positioning stratifies between supply security and application expertise.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill Incorporated |
| DDW The Color House |
| Nigay SAS |
| Döhler Group |
| Sethness Products Company |
| BASF SE |
| Aipu Food Industry Co. Ltd. |
| Sensient Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
Maharashtra's concentrated liquid caramel production capacity in the Mumbai-Pune corridor shapes downstream pricing power across India's processed food sector, with modern trade procurement centralization compressing distributor margins and elevating direct-to-bottler premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the caramel colorant market. Natural and organic certification grades command substantial premiums over conventional Class III and IV variants as clean-label procurement policies harden at multinational beverage and dairy processors. Price differentiation centers on feedstock provenance and EFSA compliance certification, with ammonia-processed variants facing cost compression from tightened 4-methylimidazole purity specifications. Quick-service restaurant chains exhibit the highest price sensitivity due to volume scale and specification standardization, while craft spirits bottlers absorb premium positioning for double-concentrated liquid expertise.
Supply Chain Analysis
Export-control restrictions on advanced pyrolysis monitoring technology limit equipment flows to emerging production zones, concentrating precision manufacturing capability in established hubs. Supply draws from integrated agricultural conglomerates in the United States, Germany, and India, with merchant processors in Brazil and China absorbing feedstock volatility. Molasses and corn syrup dependencies expose margin predictability to commodity price swings, while single-source vulnerability in spectrophotometric inline monitoring systems creates bottleneck risk. Distribution runs through technical service-embedded direct relationships rather than traditional ingredient distributor networks, with large beverage bottlers bypassing intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation disruption is accelerating competitive consolidation as EFSA purity specifications and FDA 4-methylimidazole monitoring reshape viable supplier archetypes.
For Market Incumbents: Harden feedstock security through backward integration into molasses and corn syrup supply chains, particularly in India's expanding dairy corridor where localized production advantages are intensifying. Invest in dedicated analytical laboratory infrastructure to maintain EU export access under tightened Class III and IV caramel specifications, locking out smaller toll processors unable to absorb purification capex burdens. For New Entrants and Emerging Players: Build out specialized technical service capabilities for India's underpenetrated regional dairy and confectionery markets, where centralized procurement desks at modern trade chains seek embedded formulation support. Target spray-dried powder production for seasoning blend applications in China's Yangtze River Delta export hub, leveraging lower regulatory compliance thresholds for non-EU destinations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated agricultural-colorant conglomerates with captive feedstock control and spectrophotometric process digitization capabilities. The five-to-ten year viability window rewards platforms combining supply security with direct bottler relationships. Monitor FSSAI-Codex alignment implementation as the signal for India's regulatory clarity inflection and early compliance investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill's captive molasses sourcing secures margin predictability against agricultural commodity volatility. |
| Technical Service Embedding at Bottler Facilities | DDW's dosing calibration teams in Wisconsin and Colorado lock in multi-year dark beer supply agreements. |
| Analytical Laboratory Certification Investment | Munich-based testing networks enable European processors to maintain EFSA-compliant export batch release. |
| Localized Production in India's Food Corridor | Mumbai-Pune capacity addresses Maharashtra dairy processors' natural-grade liquid caramel procurement expansion. |
| Spectrophotometric Inline Monitoring Deployment | Real-time tinctorial power feedback digitizes quality assurance and compresses batch-to-batch variation penalties. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with caramel colorant plant managers, beverage procurement leads at multinational bottlers, FSSAI regulatory affairs specialists, and technical R&D directors at specialized colorant houses; and secondary validation through customs and trade flow databases, EFSA re-evaluation documentation, SEC 10-K filings from listed ingredient suppliers, and FSSAI-Codex alignment notifications. Bottom-up volume modeling triangulated against top-down value estimates derived from procurement desk specifications and distributor channel checks.
Forecast inputs incorporated grade tier segmentation across natural, organic, synthetic, and non-GMO certifications; application intensity across beverage, bakery, dairy, and snack processing; and regional regulatory cluster differentiation between EU EFSA enforcement, US FDA GRAS oversight, and India's FSSAI harmonization trajectory. CAGRs were derived from trend extrapolation of clean-label procurement policy adoption rates and displacement patterns for synthetic alternatives, with cross-reference to molasses and corn syrup feedstock price elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by agricultural conglomerates or rapid regulatory tightening beyond EFSA's current trajectory would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Europe Food Enzymes Market