
 South America Food Additives Market | 2026-2036
South America Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Additives Market Analytics
Buyer concentration among Brazil's multinational food processors is decoupling from traditional mid-sized dairy cooperatives, fragmenting procurement volumes across new snack and beverage entrants. Cargill Incorporated leverages its grain-derived additive supply chain to dominate regional sourcing networks. Kerry Group Plc sustains formulation partnerships with pan-South American beverage manufacturers. Givaudan anchors premium flavor positioning through specialized taste modulation technologies.
Food additives encompass chemical substances and natural extracts incorporated into food matrices at controlled concentrations to enhance shelf stability, sensory properties, or nutritional profiles, with inclusion rates typically ranging from parts-per-million to several percent by weight depending on functional category and regulatory maximum limits. Their primary commercial purpose centers on enabling standardized product quality across variable raw material inputs and extended distribution chains. Preservatives command the largest current revenue share due to tropical climate-driven spoilage risks, while sweeteners represent the fastest structural expansion as sugar-reduction mandates intensify across Andean and Southern Cone markets. Flavor enhancers concentrate margin pools in savory applications, particularly within Brazil's processed meat sector.
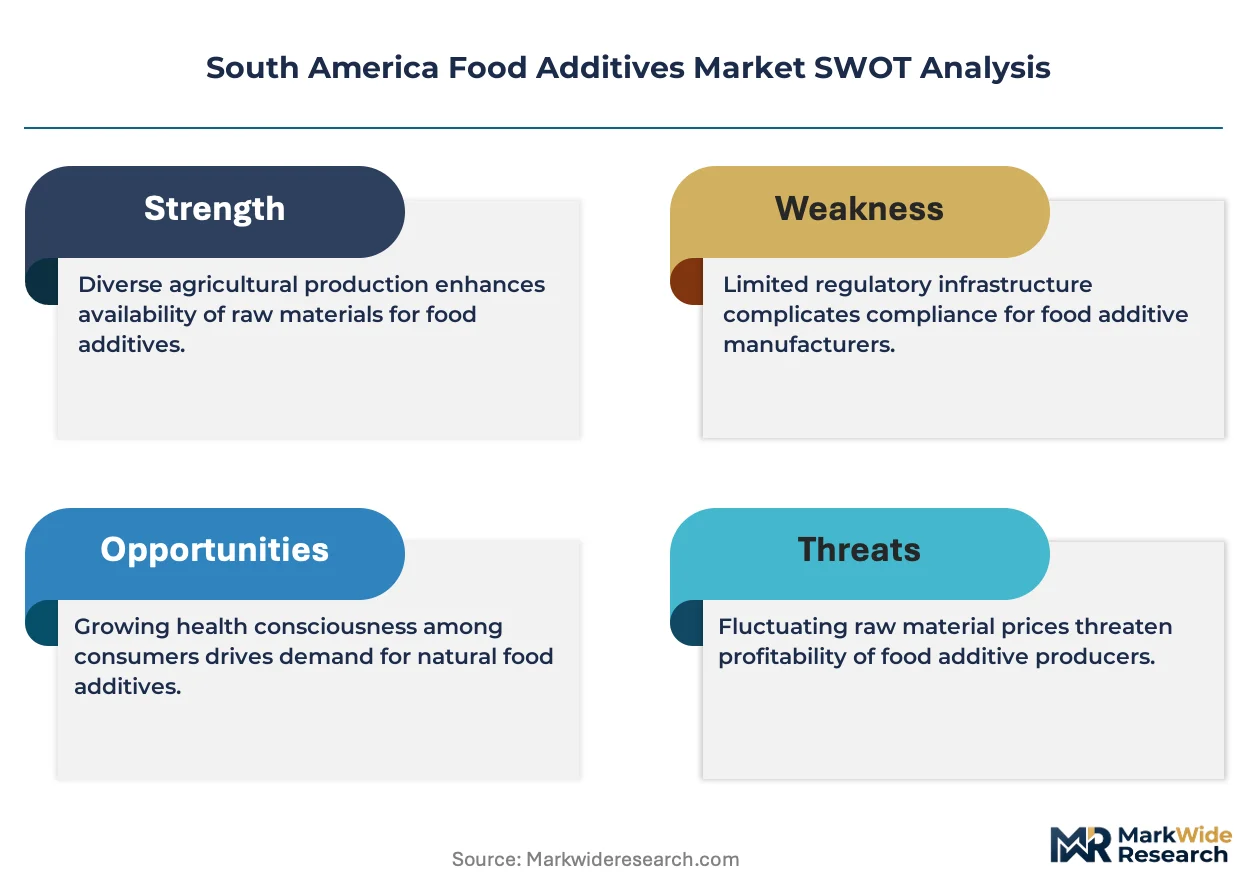
ANVISA governs additive safety assessments and positive-list approvals across Brazil, Argentina's national food safety authority enforces Mercosur-aligned additive standards, and Chile's Ministry of Health maintains stricter maximum level thresholds for certain colorant categories. These frameworks collectively determine which functional ingredients achieve commercial scale, with approval reciprocity gaps between Mercosur members creating formulation complexity for cross-border product lines. Stakeholders must monitor regulatory harmonization negotiations while building flexible formulation capabilities that adapt to divergent national maximum limits.
Market Dynamics
ANVISA's compressed approval timelines for novel additives are redistributing competitive advantage toward formulation-flexible suppliers capable of rapid Mercosur compliance adaptation. This regulatory acceleration is compressing product development cycles while fragmenting procurement relationships across Brazil's Southeast industrial corridor.
Growth Catalysts
- Sugar-Reduction Mandates:Andean and Southern Cone governments are enforcing beverage reformulation requirements. Sweetener suppliers capture expanded procurement volumes from carbonated drink manufacturers.
- ANVISA Pathway Modernization:Brazil's streamlined safety assessment protocols reduce novel ingredient time-to-market. Food processors accelerate clean-label product launches.
- Tropical Climate Spoilage Risks:Extended distribution chains across Amazonian logistics networks drive preservative demand. Processed meat and dairy manufacturers prioritize shelf-stability additives.
Market Restraints
- Mercosur Approval Reciprocity Gaps:Divergent national maximum limits between Brazil and Argentina create cross-border formulation complexity. Manufacturers maintain parallel product specifications.
- Grain-Derived Input Volatility:Corn and soybean price fluctuations transmit directly to additive production costs. Cargill's supply chain dominance concentrates pricing power.
- Natural Extract Yield Limitations:Botanical sourcing constraints restrict clean-label preservative scalability. Suppliers face procurement bottlenecks during harvest cycles.
Strategic Opportunities
- Chilean Premium Colorant Thresholds:Stricter Ministry of Health limits create specialized demand for high-purity formulations. Premium positioning opportunities open for compliant suppliers.
- Snack and Beverage Entrant Fragmentation:New processing ventures across São Paulo's industrial belt distribute procurement volumes beyond incumbent dairy cooperatives.
- Taste Modulation Technology Convergence:Flavor enhancers combining yeast extracts with peptide systems enable sodium reduction without sensory compromise. Processed meat manufacturers pilot integrated solutions.
Industry Challenges
- Cross-Border Compliance Talent Scarcity:Formulation chemists with simultaneous ANVISA and Argentina national food safety authority expertise command premium compensation. Manufacturers face recruitment bottlenecks.
- Legacy Dairy Cooperative Integration:Mid-sized processors struggle to adapt procurement systems to multinational additive specifications. Technical retrofitting demands capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Additives Market |
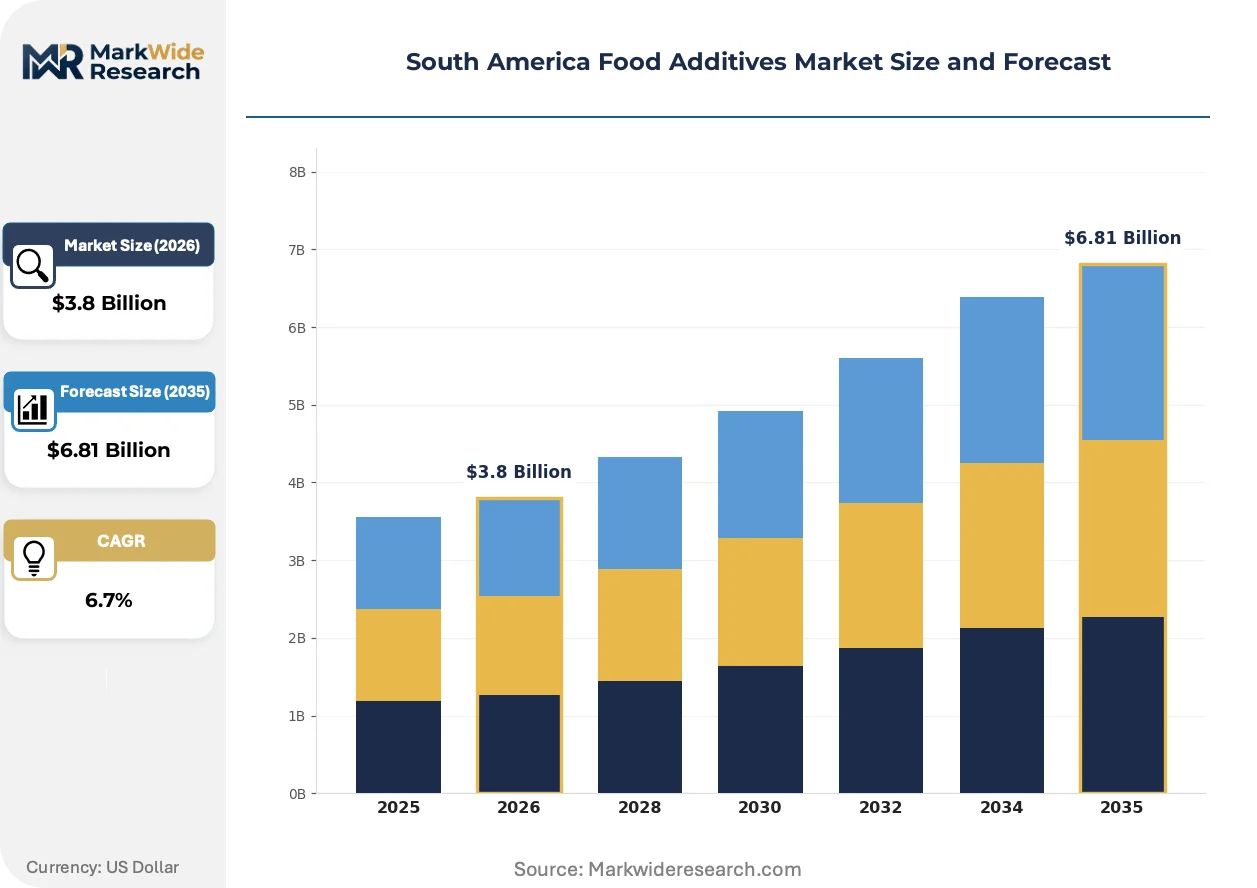
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Colorants, Sweeteners Application: Beverages, Dairy Products, Bakery Items, Snacks Form: Liquid, Powder, Granular, Paste Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Cargill Incorporated, Givaudan, Firmenich SA, Archer Daniels Midland Company, BASF SE, Kerry Group Plc, Ajinomoto Co Inc, Corbion NV, International Flavors & Fragrances, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Additives Market Evolving Landscape
Clean-label formulation requirements are compressing synthetic additive demand while expanding natural extract and fermentation-derived alternatives across South American processing operations.
Encapsulation technologies are integrating controlled-release preservative systems into meat matrices. Brazilian processors adopt these systems to maintain clean-label claims while achieving tropical shelf-life targets. The technology is integrating thermal stability and moisture-activated release mechanisms that reduce inclusion rates without compromising safety margins.
ANVISA's positive-list expansion for plant-derived antimicrobials is enabling rosemary extract and cultured sugar applications previously restricted to synthetic benzoates. Argentina's national food safety authority maintains tighter restrictions, forcing manufacturers to maintain dual formulation portfolios. Chile's Ministry of Health is accelerating parallel assessments, narrowing the regulatory fragmentation window.
Direct-procurement relationships between São Paulo-based food processors and specialty additive suppliers are displacing traditional distributor intermediaries. Snack manufacturers negotiate volume commitments with taste-modulation technology providers. This channel compression concentrates in Brazil's Southeast corridor where purchasing power aggregates around multinational headquarters.
South America Food Additives Market Segmentation
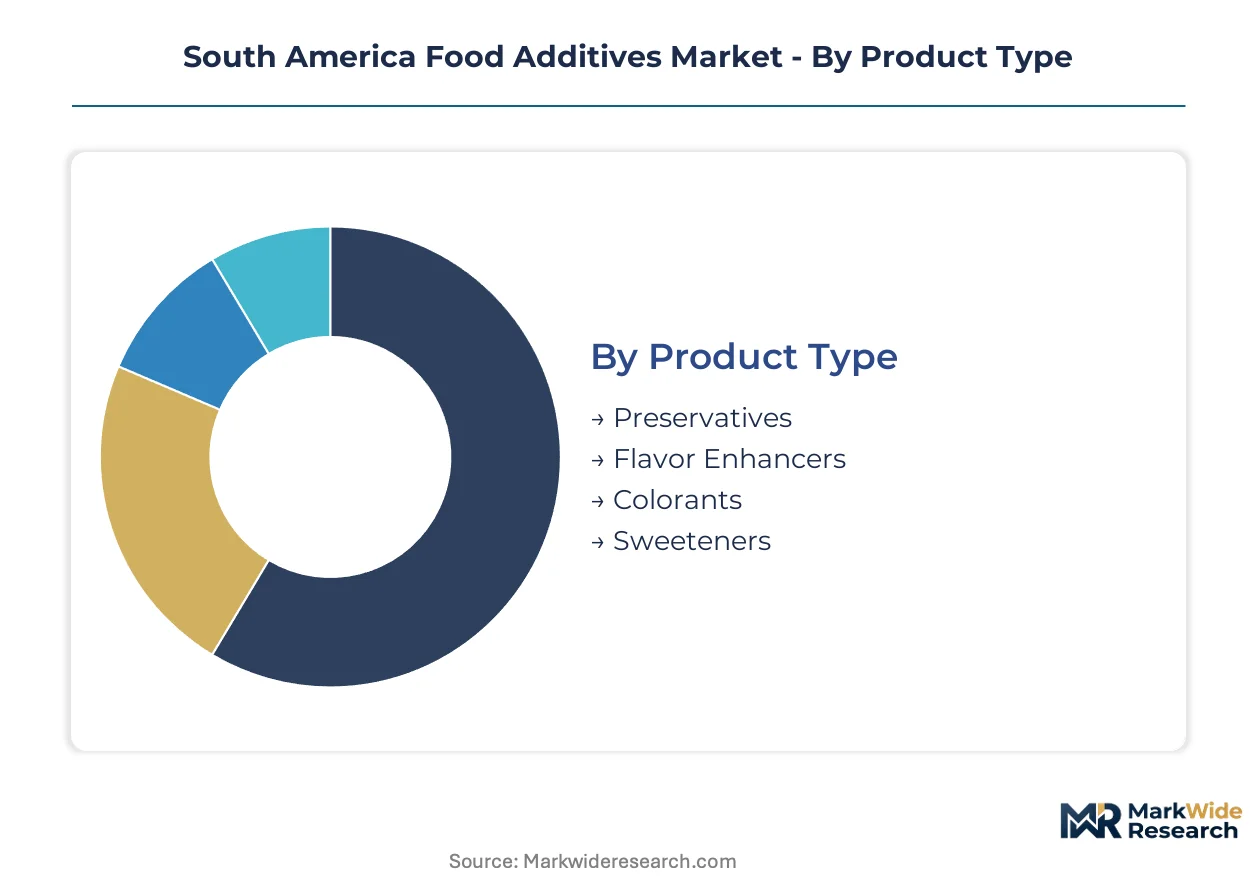
Food additive procurement patterns across South America diverge sharply by functional category and end-use application. ANVISA's positive-list architecture and Mercosur's fragmented compliance requirements force manufacturers to maintain parallel formulation specifications across segment boundaries.
Product Type:
Supply concentration among Brazilian grain processors and multinational ingredient houses determines competitive dynamics within each functional category.
- Preservatives:Sorbates, benzoates, and natural antimicrobials inhibit microbial proliferation in high-moisture food matrices. Demand concentrates within Brazil's processed meat sector, where São Paulo-based manufacturers combat tropical spoilage risks across extended Amazonian distribution chains.
- Sweeteners:High-intensity compounds and bulk sugar substitutes enable beverage reformulation under Andean sugar-reduction mandates. Argentine carbonated drink manufacturers are expanding procurement volumes as provincial governments enforce stricter nutritional labeling thresholds.
- Flavor Enhancers:Yeast extracts, nucleotides, and peptide systems amplify savory perception without sodium loading. Chilean processed food exporters prioritize these additives for clean-label positioning in premium export markets.
- Colorants:Synthetic dyes and natural extracts from annatto, turmeric, and beetroot standardize visual appeal across variable raw material inputs. Chile's Ministry of Health maintains stricter maximum level thresholds than ANVISA, forcing dual-specification production lines.
Preservatives absorb the bulk of installed capacity; sweeteners are expanding most quickly.
Application:
End-use demand patterns track Brazil's Southeast industrial corridor concentration and Argentina's Pampas dairy belt geography.
- Beverages:Carbonated soft drinks, juices, and functional waters require acidulants, sweeteners, and stabilizers for shelf-life extension. Brazilian multinational bottlers command regional purchasing power through consolidated procurement desks in São Paulo.
- Dairy Products:Emulsifiers, stabilizers, and preservatives maintain texture and safety across refrigerated distribution. Argentine dairy cooperatives in Santa Fe and Córdoba provinces represent fragmented mid-volume demand distinct from multinational scale.
- Bakery Items:Antioxidants, emulsifiers, and enzymes control staling and improve dough handling. Brazilian industrial bakeries along the São Paulo-Rio de Janeiro axis drive volume concentration for shelf-life extension additives.
- Snacks:Seasoning blends, acidulants, and colorants deliver consistent sensory profiles for extruded and fried products. New entrant manufacturers in Brazil's Southeast industrial belt are fragmenting procurement relationships beyond traditional distributor networks.
Beverages capture the dominant share of high-volume additive consumption; snacks are climbing the fastest as new processing ventures proliferate.
Form:
Physical state selection hinges on manufacturing equipment compatibility, dissolution kinetics, and stability requirements during tropical storage and transport.
- Liquid:Ready-to-pump solutions integrate directly into continuous processing lines without hydration steps. Brazilian beverage manufacturers prefer liquid acidulants and colorants for streamlined batch consistency.
- Powder:Spray-dried and agglomerated formats offer extended stability and reduced transportation costs. Argentine dairy processors utilize powdered stabilizers for recombined milk applications.
- Granular:Free-flowing particles minimize dusting and improve metering accuracy in automated systems. Chilean bakery manufacturers specify granular emulsifiers for precise dough conditioning.
- Paste:High-concentration semi-solids suit small-batch artisanal production and specialized flavor delivery. Brazilian processed meat specialists employ paste-form curing accelerators for uniform distribution in coarse-ground formulations.
Powder forms dominate bulk commodity movements; liquid formats are gaining share fastest among high-throughput beverage operations.
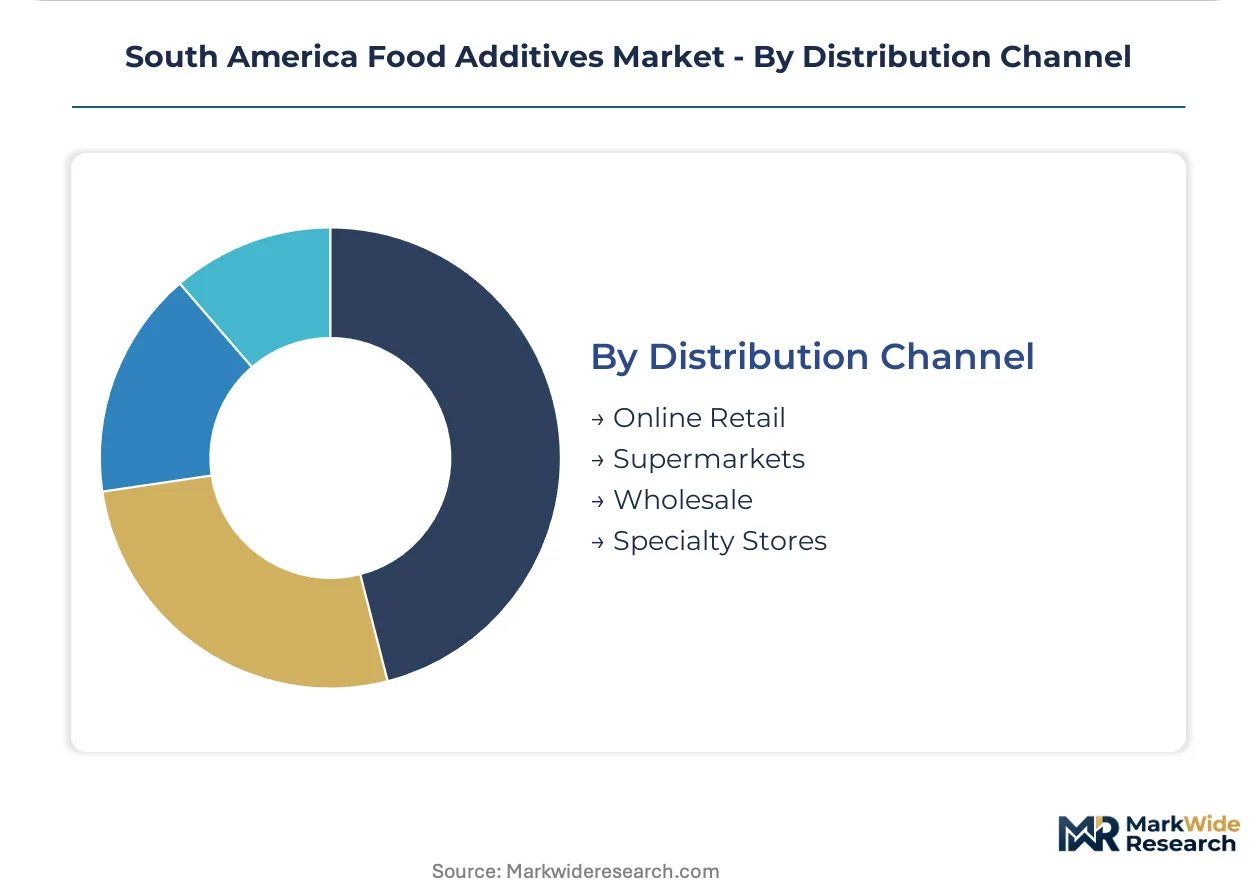
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and ANVISA documentation complexity for imported specialty ingredients.
- Online Retail:Digital platforms serve small-scale food artisans and regional processors seeking fragmented additive assortments without minimum order constraints. Brazilian e-commerce penetration in industrial chemicals remains limited by hazardous material shipping regulations.
- Supermarkets:Mass-market retailers stock consumer-packaged baking aids and colorants for home use. Argentine supermarket chains maintain limited professional-grade additive selections compared to Brazilian counterparts.
- Wholesale:Distributor networks aggregate volumes across mid-sized processors lacking direct supplier relationships. São Paulo-based wholesalers dominate regional flow control for commodity preservatives and sweeteners.
- Specialty Stores:Technical ingredient suppliers provide formulation support, regulatory documentation, and custom blending services. Chilean specialty stores concentrate in Santiago's food technology district, serving export-oriented manufacturers with premium clean-label requirements.
Wholesale channels handle the majority of industrial volume; specialty stores are expanding most quickly as clean-label technical demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Southeast industrial corridor commands dominant additive procurement volumes, with São Paulo-based food processors aggregating regional purchasing power across beverage and processed meat applications.
Brazil
ANVISA's streamlined approval pathways for novel ingredients compress product development cycles for clean-label formulations. São Paulo's multinational headquarters drive consolidated procurement desks, while Minas Gerais dairy processors expand natural preservative adoption. The Southeast corridor concentrates demand for encapsulation technologies targeting tropical shelf-life extension.
Argentina
Provincial sugar-reduction mandates accelerate high-intensity sweetener procurement from carbonated drink manufacturers. The national food safety authority enforces Mercosur-aligned additive standards tighter than ANVISA on botanical extracts. Santa Fe and Córdoba dairy cooperatives represent fragmented mid-volume demand distinct from multinational scale.
Chile
The Ministry of Health maintains stricter maximum level thresholds for synthetic colorants than regional counterparts, forcing dual-specification production lines for export-oriented manufacturers. Santiago's food technology district anchors specialty store concentration serving premium clean-label requirements. Northern mining corridor logistics networks drive preservative demand for extended distribution.
Colombia
Andean beverage reformulation requirements intensify acidulant and sweetener procurement from Bogotá-based bottlers. The national food safety authority harmonizes additive standards with Mercosur frameworks while maintaining distinct maximum limits for certain emulsifier categories. Antioquia's processed food cluster expands natural extract sourcing for clean-label positioning.
Peru
Lima's coastal food processing belt concentrates demand for stabilizers and colorants in canned fish and native grain applications. The national health authority implements phased additive maximum limit reductions aligned with Pacific Alliance trade bloc standards. Arequipa's dairy and bakery manufacturers pilot yeast extract-based flavor enhancers for sodium reduction.
South America Food Additives Market Competitive Landscape
Brazilian grain processors anchor one tier; European and Asian specialists hold formulation technology positions. The market structure concentrates around multinational ingredient houses with integrated supply chains and regional distribution networks. Three archetypes dominate: grain-derivative suppliers leveraging captive raw material access, fermentation technology specialists, and taste modulation platform providers. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Within the grain-derivative tier, Cargill Incorporated occupies a position exemplifying backward integration into corn and soybean supply chains. Kerry Group Plc and Givaudan represent the formulation partnership and taste modulation archetypes respectively, with the former anchoring pan-regional beverage relationships and the latter specializing in sensory technology platforms. These three entities collectively illustrate the competitive structure spanning raw material control, technical service capabilities, and premium positioning segments.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Givaudan |
| Firmenich SA |
| Archer Daniels Midland Company |
| BASF SE |
| Kerry Group Plc |
| Ajinomoto Co Inc |
| Corbion NV |
| International Flavors & Fragrances |
| Others |
Value Network & Pricing Analysis
Encapsulation technology adoption across Brazilian meat processors is simultaneously compressing per-unit additive costs and concentrating procurement leverage among formulation-flexible suppliers capable of rapid ANVISA compliance adaptation. This production-method transition redistributes margin pools from commodity preservative suppliers toward integrated technology providers while fragmenting traditional distributor intermediaries in São Paulo's Southeast corridor.
Pricing Analysis
Volume-mass sweeteners and commodity preservatives trade on thin margins, while specialty taste-modulation systems and high-purity natural extracts capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates clean-label fermentation-derived additives from synthetic benzoates and bulk corn-derived sweeteners. Pricing pressure stems from grain-derived input volatility transmitting directly through Cargill's supply chain dominance. Mid-sized Argentine dairy cooperatives exhibit highest price sensitivity due to capital constraints on technical retrofitting, whereas Chilean export-oriented manufacturers prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Regional distribution centers in São Paulo and Buenos Aires anchor hub-and-spoke patterns serving Brazil's Southeast industrial belt and Argentina's Pampas dairy cluster. Supply concentrates among Brazilian grain processors, Argentine soybean derivative facilities, and European fermentation technology specialists. Raw material dependencies include corn and soybean feedstocks, botanical extracts from Andean cultivation zones, and peptide systems from Asian fermentation houses. Single-source vulnerability concentrates in Cargill's backward-integrated corn syrup networks. Distribution runs through São Paulo-based wholesalers for commodity volumes and specialty stores in Santiago's food technology district for premium clean-label requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around formulation-flexible suppliers as ANVISA's compressed approval timelines and Mercosur compliance fragmentation force capital-constrained mid-tier players toward acquisition or exit.
For Market Incumbents: To counter procurement fragmentation among São Paulo snack and beverage entrants, deepen direct-procurement relationships with taste-modulation technology providers and acquire regional specialty distributors to lock channel control. Prioritize backward integration into botanical extract sourcing to mitigate harvest-cycle yield limitations threatening clean-label preservative scalability. For New Entrants and Emerging Players: Capture white-space in Chile's premium colorant segment where stricter Ministry of Health maximum limits create specialized demand for high-purity formulations. Target Argentine provincial carbonated drink manufacturers facing sugar-reduction mandates with rapid-customization sweetener portfolios. Lead with technical service capabilities that bridge ANVISA and Argentina national food safety authority compliance gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational ingredient houses seeking Mercosur formulation expertise. Long-term viability favors suppliers with simultaneous ANVISA approval navigation and encapsulation technology platforms. Watch ANVISA-Argentina reciprocity negotiation progress as inflection indicator for cross-border formulation complexity reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Brazilian meat processors achieve tropical shelf-life targets without synthetic additive inclusion. |
| Botanical Extract Backward Integration | Suppliers secure Andean cultivation zone access to stabilize clean-label preservative yields. |
| Direct-Procurement Channel Expansion | São Paulo-based processors displace distributor intermediaries for taste-modulation systems. |
| Dual-Regulatory Compliance Certification | Formulation houses capture cross-border product line contracts spanning ANVISA and Argentine standards. |
| Fermentation Capacity Scale-Up | Yeast extract and peptide system producers meet sodium-reduction demand from processed meat manufacturers. |
Research Methodology
Independent corroboration across ANVISA filing databases, Argentine national food safety authority approval registries, and Chilean Ministry of Health maximum limit determinations underwrites the qualitative findings. Primary interviews with formulation chemists at São Paulo-based multinational processors, procurement leads at Santa Fe dairy cooperatives, and technical directors at Santiago specialty additive suppliers combined with secondary validation from customs trade flows, SEC filings of listed ingredient houses, and Mercosur regulatory harmonization documents. Bottom-up segment sizing and top-down market triangulation cross-validate volume estimates.
Comparable-period anchoring to historical preservative and sweetener procurement patterns across Brazil's Southeast corridor established baseline growth trajectories. The analytical framework models demand across functional category, end-use application, physical form, and distribution channel dimensions throughout the forecast period. CAGRs derive from additive inclusion rate trends, beverage reformulation mandate enforcement intensity, and encapsulation technology adoption curves in processed meat operations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA-Argentina reciprocity negotiations, grain price volatility transmission, and natural extract yield fluctuations. Outputs reflect documented assumptions regarding regulatory approval timelines and clean-label formulation penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Egypt Food Enzymes Market