
 Canada Food Additives Market | 2026-2036
Canada Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Additives Market Outlook
Clean-label specification tiers is reorganizing competitive dynamics across Canadian food additive procurement. Cargill Incorporated leverages its North American grain processing infrastructure to dominate sweetener supply contracts with major beverage bottlers. Tate & Lyle PLC sustains technology leadership in specialty starch modification for clean-label texture solutions. Archer Daniels Midland Company anchors its position through backward integration into Canadian canola and pulse protein extraction.
Food additives encompass substances intentionally incorporated into food matrices to achieve technical effects including preservation, sweetening, flavor modulation, color enhancement, or texture modification, typically at concentrations below one percent by weight. These compounds function through mechanisms such as pH reduction, antioxidant electron donation, or Maillard reaction acceleration to extend shelf stability, standardize sensory profiles, or enable novel product formats. Preservatives and sweeteners represent the most structurally consequential product type segments, with preservatives commanding established margin pools in dairy and bakery applications while natural sweeteners capture accelerated investment from reformulating manufacturers. The application dimension shows beverages and dairy products concentrating volume, whereas sauces present underdeveloped penetration for enzyme-based texture modifiers.
Health Canada, the Canadian Food Inspection Agency, and the Food and Drug Regulations collectively govern additive safety assessments, maximum usage levels, and novel ingredient approvals through pre-market notification requirements and post-market surveillance protocols. The Safe Food for Canadians Regulations impose additional traceability and preventive control obligations that elevate compliance costs for imported additive formulations. Stakeholders must monitor evolving novel food determinations for precision fermentation-derived ingredients and prepare for potential alignment between Canadian and U.S. FDA Generally Recognized As Safe notification pathways.
Market Dynamics
Clean-label ingredient mandates from major Canadian retailers are compressing formulation cycles and forcing additive suppliers to accelerate natural alternative development timelines.
Growth Catalysts
- Health Canada novel food pathways:Streamlined pre-market assessments for precision fermentation-derived proteins are accelerating commercialization timelines for alternative sweeteners and texture modifiers.
- Greater Toronto Area beverage concentration:Ontario's processing corridor generates concentrated demand for clean-label stabilizers and natural colorants from reformulating manufacturers.
- Pulse protein extraction scale-up:Prairie canola and pea processing infrastructure expansion is creating captive supply chains for plant-derived emulsifiers and binding agents.
Market Restraints
- Canola oil price volatility:Input cost swings for lecithin and lipid-based emulsifiers compress margin pools for mid-tier additive blenders.
- Single-source fermentation capacity:Concentrated North American production of natural high-intensity sweeteners creates supply vulnerability for Canadian formulators.
- Shelf-life performance gaps:Clean-label preservatives demonstrate inferior mold inhibition in high-moisture bakery applications versus synthetic alternatives.
Strategic Opportunities
- Quebec dairy processing expansion:Underpenetrated enzyme-based texture modification in artisanal cheese production presents white space for specialty lipase suppliers.
- Western Canada plant protein convergence:Integration of extrusion technology with fermentation-derived flavor masking creates novel savory additive platforms.
- Direct-to-manufacturer digital channels:E-procurement platforms are disintermediating traditional distributor networks for mid-volume bakery and confectionery buyers.
Industry Challenges
- Food safety certification backlog:Safe Food for Canadians Regulations preventive control plan approvals face extended timelines at the Canadian Food Inspection Agency.
- Legacy formulation integration:Retrofitting clean-label alternatives into established industrial processes requires capital-intensive line revalidation at Ontario and Alberta processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Additives Market |
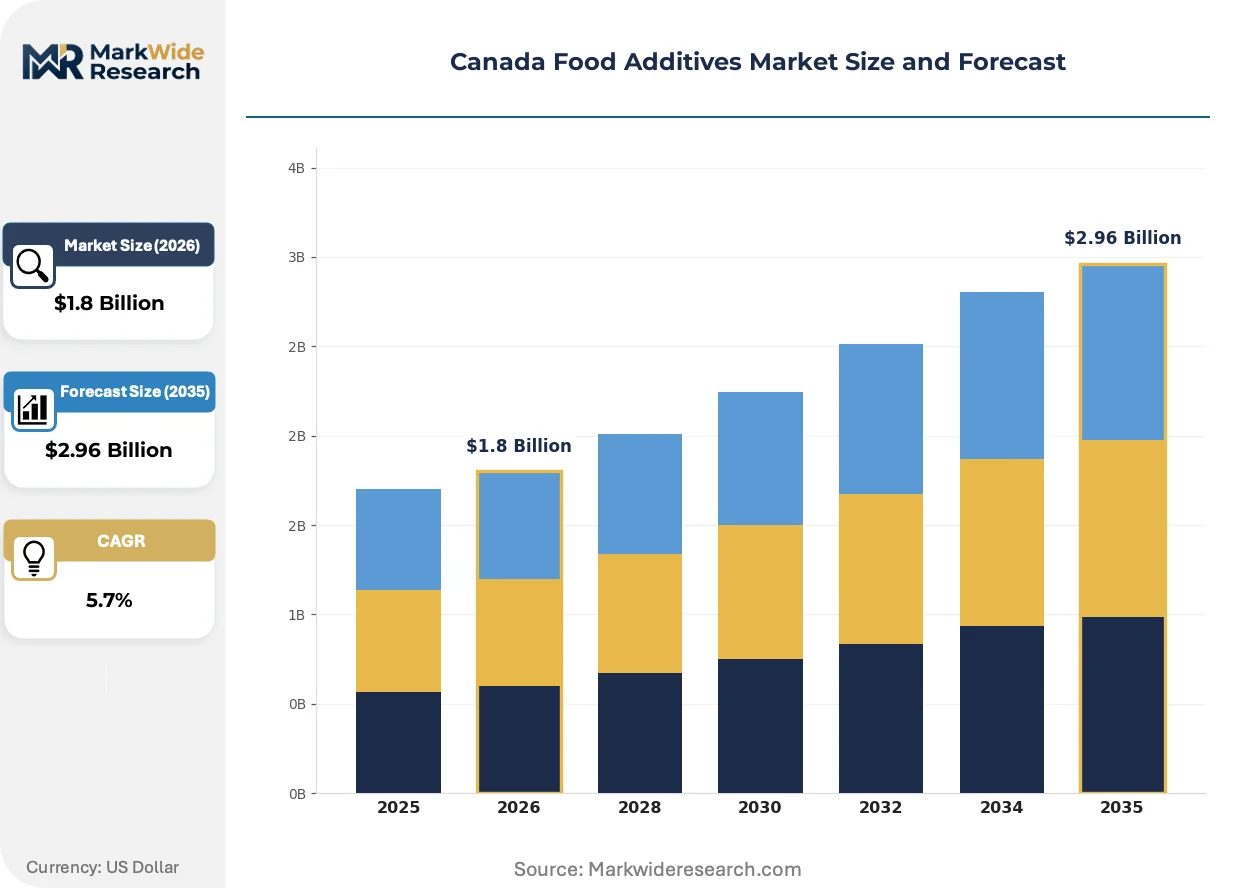
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
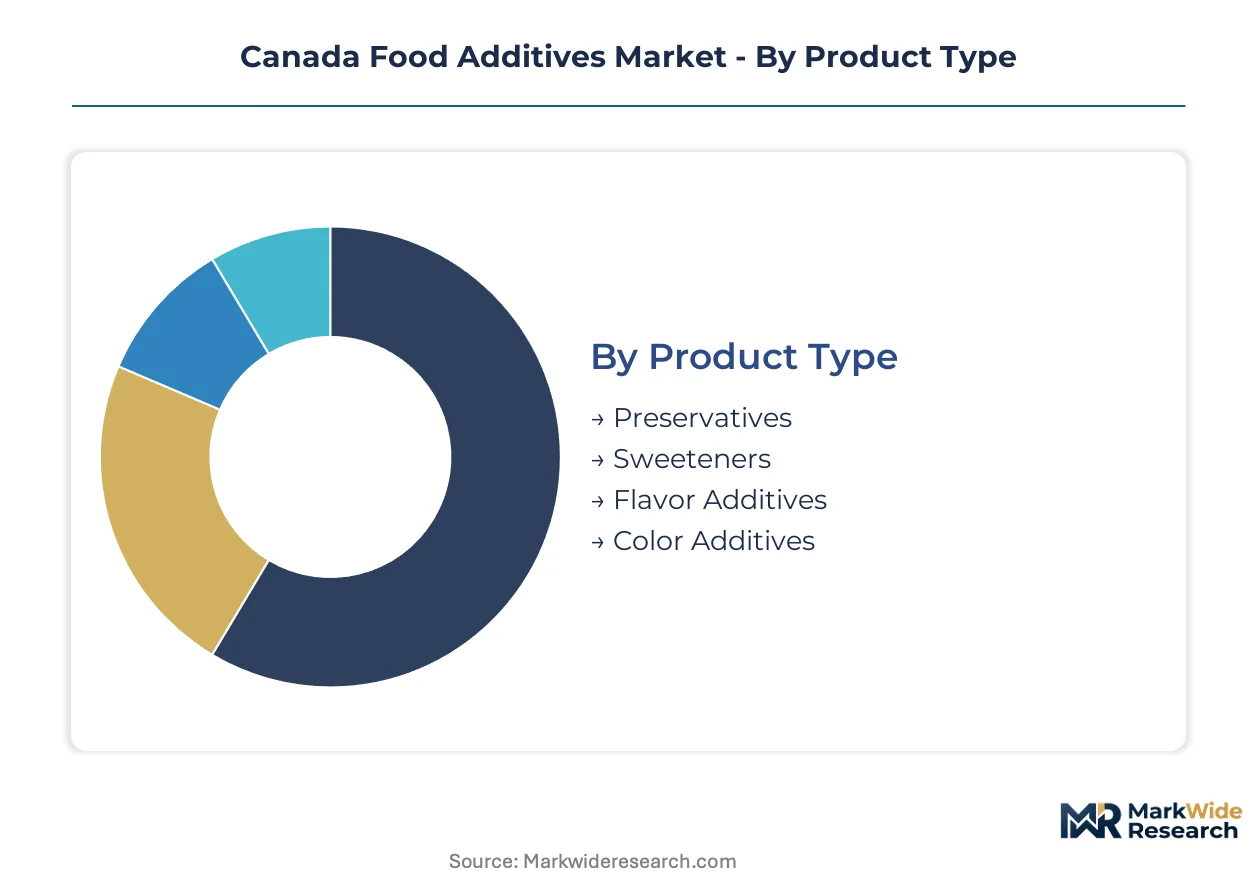
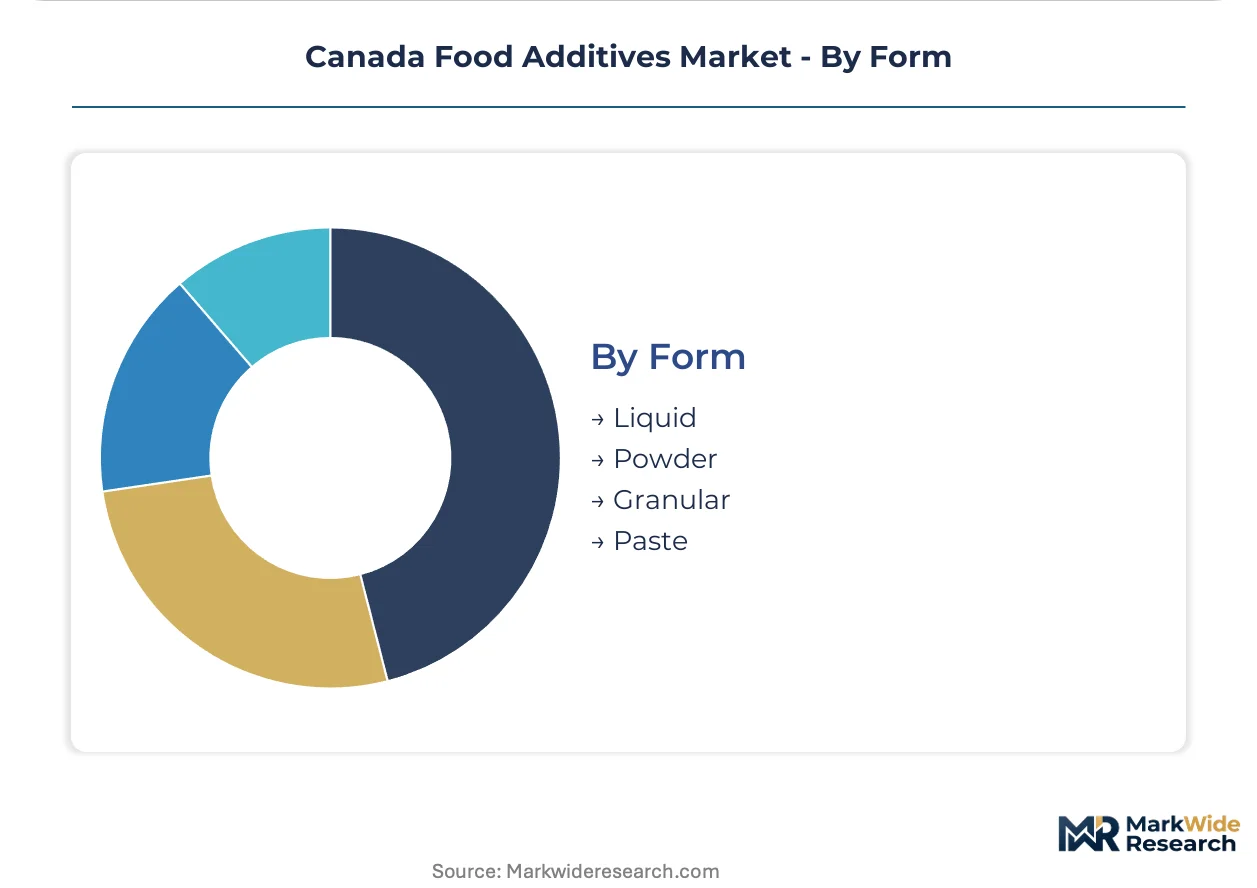
| Segmentation | Product Type: Preservatives, Sweeteners, Flavor Additives, Color Additives Application: Beverages, Dairy Products, Bakery, Sauces End User: Manufacturers, Retailers, Wholesalers, Food Service Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Ingredion Incorporated, JG Group Stevia Canada, Jungbunzlauer Suisse AG, Cargill Incorporated, DuPont de Nemours Inc., Brenntag Canada Inc., NOW Health Group Inc., Archer Daniels Midland Company, Tate & Lyle PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Additives Market Strategic Shifts
Bioprocessing advances and regulatory alignment pressures are compressing development cycles while fragmenting procurement authority across Canadian food manufacturing.
Precision fermentation-derived high-intensity sweeteners are achieving parity with steviol glycosides in taste profile stability. Major Canadian beverage bottlers in the Greater Toronto Area are piloting these ingredients for zero-sugar carbonated launches. This biotechnology platform is miniaturizing production footprints and enabling distributed manufacturing models that bypass traditional bulk import dependencies.
Health Canada's updated Food and Drug Regulations for novel food ingredients are mandating expanded toxicological datasets for enzyme-modified starches. The Canadian Food Inspection Agency has intensified post-market surveillance sampling for undeclared allergen cross-contamination in imported additive formulations. Dairy and infant nutrition manufacturers are responding by internalizing supplier audit protocols and demanding batch-level certificates of analysis.
Consolidated retail procurement is concentrating additive specification authority at headquarters level rather than plant-level discretion. Loblaws and Sobeys are imposing unified clean-label scorecards that disqualify synthetic colorants and azo dyes across their private-label portfolios. This centralization is most visible in Ontario and British Columbia, where national account managers now negotiate multi-year additive supply agreements directly with tier-one ingredient houses.
Canada Food Additives Market Segmentation
Canadian food additive procurement channels fragment across direct manufacturer relationships, distributor networks, and digital platforms. Understanding how each segment flows through these channels reveals margin concentration points and supplier negotiation leverage. The analysis below maps technical specifications to purchasing behaviors across four critical dimensions.
Product Type:
Channel mix varies sharply by product chemistry: preservatives and sweeteners move through bulk commodity distributors serving Ontario's beverage corridor, while specialty colorants and flavor systems route through technical ingredient houses with formulation support capabilities.
- Preservatives:Benzoates, sorbates, and natural alternatives like cultured dextrose inhibit microbial proliferation through pH modulation or competitive exclusion. Demand concentrates in Greater Toronto Area dairy processors facing Health Canada shelf-life compliance pressures for clean-label reformulations.
- Sweeteners:High-intensity variants including steviol glycosides and precision fermentation-derived platforms deliver sweetness without caloric load. Beverage manufacturers in Ontario drive procurement volume as retailers mandate sugar reduction across private-label portfolios.
- Flavor Additives:Natural extracts, reaction flavors, and encapsulated systems standardize sensory profiles across production batches. Artisanal sauce producers in Quebec represent an emerging customer segment for clean-label flavor masking solutions.
- Color Additives:Anthocyanins, carotenoids, and caramel formulations replace synthetic azo dyes in response to retailer scorecard exclusions. Bakery applications in British Columbia show accelerating adoption of stable natural red alternatives.
By volume, preservatives lead. By growth pace, sweeteners are ahead.
Application:
Cost tier stratification separates commodity-grade additives for high-volume beverage production from premium-priced enzyme systems for artisanal dairy applications. Margin pools concentrate where technical service requirements elevate supplier switching costs.
- Beverages:Carbonated soft drinks, functional waters, and ready-to-drink teas require stabilizers, acidulants, and natural colorants with thermal stability. The Greater Toronto Area processing corridor generates concentrated procurement volume for clean-label reformulation projects.
- Dairy Products:Yogurt, cheese, and ice cream applications demand texture modifiers, cultures, and enzyme-based flavor development. Quebec's expanding artisanal cheese sector presents white space for specialty lipase suppliers.
- Bakery:Bread, pastry, and cake formulations utilize emulsifiers, enzymes, and mold inhibitors. Western Canada plant protein convergence is creating novel binding agent requirements for gluten-free product lines.
- Sauces:Dressings, condiments, and cooking sauces employ thickeners, acidulants, and flavor enhancers. Enzyme-based texture modification remains underpenetrated relative to starch-based alternatives.
By revenue contribution, beverages dominate. By margin expansion potential, dairy products show the steepest trajectory.
End User:
Customer type determines contract structure: manufacturers negotiate multi-year supply agreements with technical specifications, while food service operators purchase through distributor catalogs with limited formulation support.
- Manufacturers:Large-scale food and beverage producers in Ontario and Quebec specify additives at headquarters level, consolidating procurement authority. Direct supplier relationships predominate for volume categories.
- Retailers:Loblaws and Sobeys impose unified clean-label scorecards across private-label portfolios, disqualifying synthetic colorants and driving additive specification changes upstream.
- Wholesalers:Traditional distribution networks serve mid-tier bakery and confectionery buyers, though e-procurement platforms are disintermediating these channels for standard products.
- Food Service:Restaurant chains and institutional caterers purchase through broadline distributors with limited technical service, creating price-sensitive demand for commodity-grade additives.
By contract value, manufacturers anchor procurement. By specification influence, retailers are gaining share fastest.
Form:
Supply concentration in Prairie canola processing and Ontario fermentation capacity shapes physical form availability, with liquid and powder formats dominating import-dependent categories.
- Liquid:Emulsions, syrups, and concentrated solutions enable precise dosing in continuous beverage production lines. High-volume Ontario bottlers favor liquid sweeteners and colorants for processing efficiency.
- Powder:Spray-dried and agglomerated formats offer extended shelf stability and reduced shipping costs. Prairie-based pulse protein processors supply powdered emulsifiers with captive supply chain advantages.
- Granular:Free-flowing crystals and prills facilitate automated handling in bakery and dairy applications. Granular acidulants serve Quebec cheese production with consistent dissolution properties.
- Paste:High-viscosity concentrates and purees deliver intense flavor and color in sauce applications. Artisanal producers in British Columbia represent a niche demand segment for paste-format natural extracts.
By shipment volume, powder leads. By processing convenience premium, liquid formats command expanding share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's food additive trade flows reflect a net importer position, with domestic production concentrated in Prairie grain processing and Ontario fermentation capacity while specialty ingredients enter through Vancouver and Montreal ports.
Ontario
The Greater Toronto Area beverage corridor drives concentrated demand for clean-label stabilizers and natural colorants. Health Canada's Food and Drug Regulations govern pre-market approval for novel ingredients entering through this hub. Toronto and Mississauga host headquarters-level procurement for national retailers imposing unified additive specifications.
Quebec
Expanding artisanal cheese production creates demand for specialty lipase and enzyme-based texture modifiers. The Canadian Food Inspection Agency enforces Safe Food for Canadians Regulations traceability requirements across provincial dairy processors. Montreal serves as the eastern import gateway for European natural extract formulations.
Alberta
Canola crushing and pulse protein extraction infrastructure anchors captive supply chains for plant-derived emulsifiers. Prairie processing capacity buffers input cost volatility for lecithin and lipid-based additives. Calgary and Edmonton distribution nodes serve bakery manufacturers reformulating for clean-label mandates.
British Columbia
Vancouver's port facilities handle Pacific Rim imports of high-intensity natural sweeteners and specialty starches. Provincial food manufacturers face accelerated retailer scorecard exclusions for synthetic colorants. The Lower Mainland clusters natural product formulators targeting premium-positioned clean-label launches.
Canada Food Additives Market Competitive Environment
Concentration sits with diversified agricultural processors controlling upstream raw material flows. Three to five integrated ingredient houses dominate volume contracts through backward integration into Canadian canola and North American grain processing. Mid-tier blenders compete on formulation technical service for regional dairy and bakery accounts. Competitive moves center on Prairie protein extraction capacity expansion and direct-to-manufacturer digital channel development.
Among North American agricultural conglomerates, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven archetypes with captive supply chain control. Tate & Lyle PLC occupies a position representing technology-led specialty modification expertise. These three anchors illustrate how competitive positioning fragments between commodity volume leadership and premium technical service provision.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| JG Group Stevia Canada |
| Jungbunzlauer Suisse AG |
| Cargill Incorporated |
| DuPont de Nemours Inc. |
| Brenntag Canada Inc. |
| NOW Health Group Inc. |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
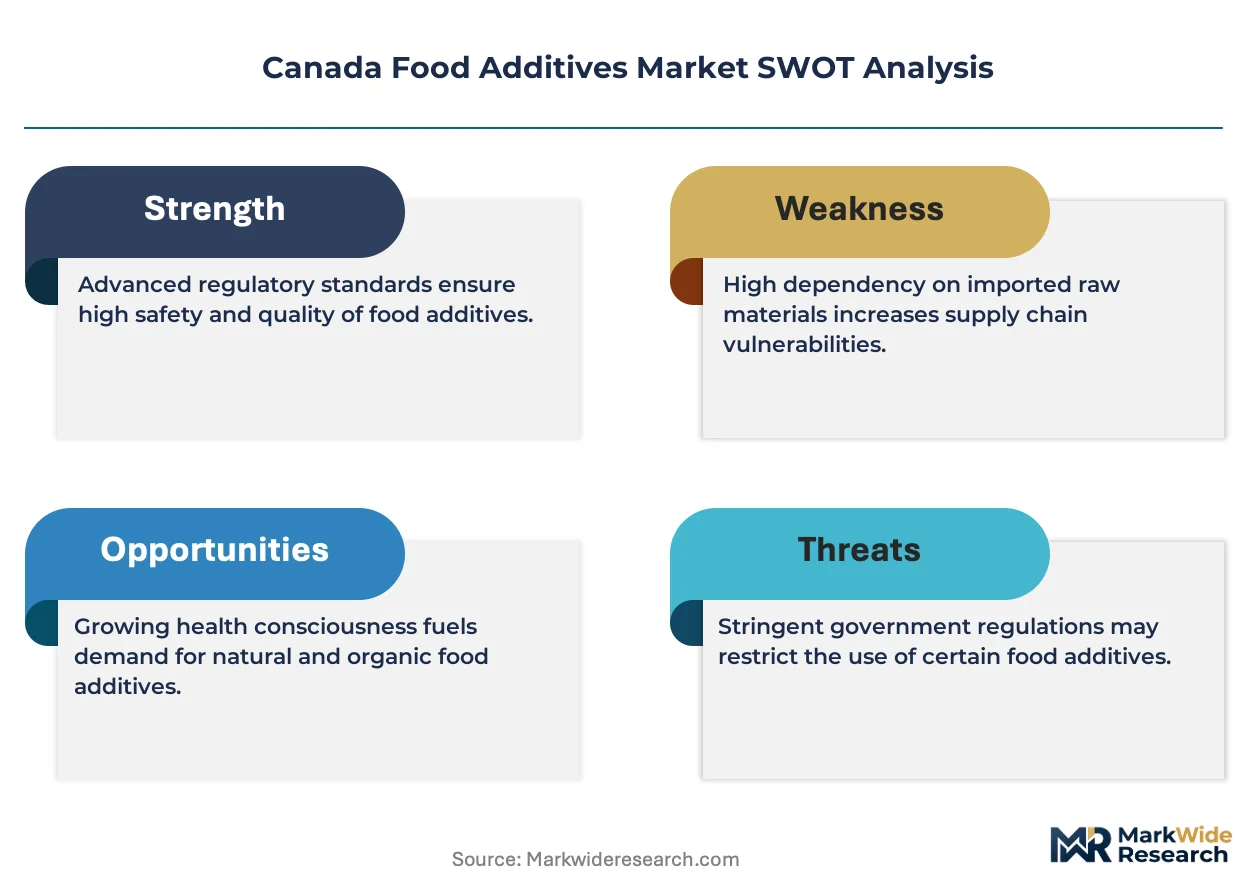
Safe Food for Canadians Regulations preventive control plan approvals gate both supplier qualification and price differentiation simultaneously, forcing mid-tier additive blenders to absorb compliance audit costs while tier-one ingredient houses capture certification premiums. Health Canada's novel food determination pathways concentrate pricing power with established players holding validated toxicological datasets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Ontario's beverage corridor. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived high-intensity sweeteners from commodity steviol glycosides and synthetic alternatives. Pricing pressure stems from canola oil price volatility compressing lecithin margin pools. Food service operators purchasing through broadline distributors exhibit highest price sensitivity; headquarters-level manufacturers negotiating multi-year agreements show lowest.
Supply Chain Analysis
Single-source fermentation capacity in the United States creates supply vulnerability for Canadian formulators dependent on imported natural high-intensity sweeteners. Prairie canola crushing and North American grain processing feed lipid-based emulsifier production. Tariff exposure on precision fermentation inputs from U.S. facilities elevates landed cost uncertainty. Distribution runs through Toronto and Montreal hub-and-spoke networks serving regional dairy and bakery processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical formulation service contracts are expanding faster than commodity additive sales, creating recurring-revenue attach opportunities for suppliers embedding application laboratories at customer sites.
For Market Incumbents: Compound Prairie protein extraction capacity through captive pea and canola processing infrastructure to defend against precision fermentation substitution threats. Deepen backward integration into Ontario fermentation facilities to secure novel sweetener supply chains. Prioritize Health Canada pre-market notification dossier investments to accelerate clean-label preservative approvals ahead of reformulation deadlines. For New Entrants and Emerging Players: Canadian Food Inspection Agency fast-track certifications for enzyme-modified starch applications unlock Quebec artisanal cheese sector penetration. Target underdeveloped enzyme-based texture modification in sauce applications where starch alternatives dominate. Enter through direct-to-manufacturer digital channels disintermediating traditional distributor networks for mid-volume bakery accounts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation-derived ingredient platforms. Five-to-ten year viability favors acquisition targets holding validated novel food determinations and captive Prairie protein supply. Watch Health Canada alignment with U.S. FDA GRAS notification pathways as regulatory harmonization inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Prairie Protein Extraction Scale-Up | Captive supply of canola lecithin and pea emulsifiers buffers input cost volatility for Ontario processors. |
| Novel Food Dossier Investment | Accelerated Health Canada approvals unlock precision fermentation sweetener commercialization ahead of competitors. |
| Direct-to-Manufacturer Digital Platform | E-procurement disintermediation captures margin from mid-tier bakery and confectionery buyers. |
| Application Laboratory Embedding | Technical service contracts create switching costs and recurring revenue attachment at dairy facilities. |
| Quebec Dairy Processing Partnership | Specialty lipase supply agreements penetrate artisanal cheese expansion with enzyme-based texture solutions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage formulation chemists, dairy processing engineers, procurement directors at Ontario retailers, Health Canada regulatory affairs specialists, and Prairie grain elevator operators. Secondary validation drew from CFIA enforcement reports, Health Canada novel food determinations, Canadian Grain Commission trade statistics, and SEC filings of North American agricultural processors. Bottom-up volume estimates triangulated against top-down industry value assessments.
Across the analysis window, projections integrate product type, application, end user, and physical form segmentation with regional production hub clustering. CAGRs derive from historical volume trajectories adjusted for clean-label reformulation acceleration and precision fermentation commercialization timelines. Forecast inputs incorporate Prairie protein processing capacity expansion schedules and Health Canada regulatory pathway velocity assumptions.
Underlying assumptions cover sustained retailer clean-label scorecard enforcement and stable canola input supply, with deviation risk concentrated in novel food approval timeline delays and U.S.-Canada trade policy shifts. Practitioners should keep alternative scenarios live as Health Canada-FDA regulatory alignment negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Argentina Food Additives Market