
 Cook-Up Starch Market | 2026-2036
Cook-Up Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Cook-Up Starch Market Outlook
The capital-intensity divergence between integrated wet-milling operators and specialty-modification houses is collapsing as mid-scale players adopt continuous processing platforms. Cargill Incorporated leverages its global grain origination network to secure feedstock cost advantages across multiple hemispheres. Ingredion Incorporated anchors its position through deep R&D pipelines in clean-label texturizers. Tate & Lyle PLC differentiates via precision-modified starch portfolios targeting high-viscosity sauce systems.
Cook-up starch denotes granular starch requiring thermal hydration above gelatinization temperature to develop viscosity, typically comprising amylose and amylopectin ratios between 15:85 and 28:72 depending on botanical source, with peak viscosity achieved at 85–95°C in standard Brabender amylograph testing. Native starch occupies the volume base in cost-sensitive applications, while modified starch captures margin pools where freeze-thaw stability and shear resistance command formulation premiums. The snack segment sustains above-average growth as extruded and coated products proliferate across retail channels.
FDA food-additive regulations under 21 CFR 172.892 govern chemical modification permissibility, while EU REACH and EFSA purity standards constrain residual reagent thresholds for imports into European food manufacturing. The EU Green Deal's farm-to-fork sustainability targets are pressing starch processors to document carbon intensity across cultivation and wet-milling stages. Stakeholders must monitor evolving clean-label certification schemes and decide whether to invest in physical modification technologies that bypass chemical derivatization entirely.
Market Dynamics
Clean-label certification requirements are forcing starch processors to abandon chemical modification routes and rebuild production lines around physical modification technologies that satisfy EU REACH and FDA 21 CFR 172.892 purity thresholds without synthetic reagent residues.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Carbon intensity documentation mandates are pulling modified starch demand toward processors with verified wet-milling sustainability credentials across Germany, France, and the Netherlands.
- Extruded snack proliferation:Retail channel expansion for coated and puffed products is accelerating cook-up starch consumption in high-shear extrusion applications where peak viscosity stability determines product quality.
- Thermal hydration precision:Advanced Brabender amylograph testing protocols are enabling formulators to match specific amylose-amylopectin ratios to sauce and bakery applications with tighter viscosity windows.
Market Restraints
- Maize and wheat price volatility:Feedstock cost swings for cereal-based starches compress margins for non-integrated processors lacking captive grain origination networks.
- Residual reagent thresholds:EFSA purity standards under EU REACH constrain import flexibility for Asian suppliers using higher-reagent modification chemistries.
- Clean-label substitution:Native starch and minimally processed alternatives are capturing formulation share in cost-sensitive bakery segments where functional performance gaps have narrowed.
Strategic Opportunities
- Physical modification white space:Thermal and mechanical modification technologies bypass chemical derivatization entirely, opening premium positioning for processors investing in shear-induced or hydrothermal platforms.
- Freeze-thaw stability premiums:Modified starch grades with enhanced retrogradation resistance command formulation premiums in frozen ready-meal applications where texture recovery determines repeat purchase rates.
- Sustainability-linked procurement:Major food manufacturers are implementing supplier scorecards tied to documented carbon intensity across cultivation, milling, and modification stages.
Industry Challenges
- Continuous processing retrofit costs:Mid-scale players face capital intensity barriers when transitioning from batch to continuous modification platforms that match integrated operator efficiency.
- Cross-border certification timelines:Dual FDA and EU REACH compliance documentation creates extended approval cycles for new modification chemistries and process changes.
- Specialized formulation talent scarcity:Deep expertise in amylograph interpretation and starch-protein interaction modeling concentrates among legacy European and North American technical service teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cook-Up Starch Market |
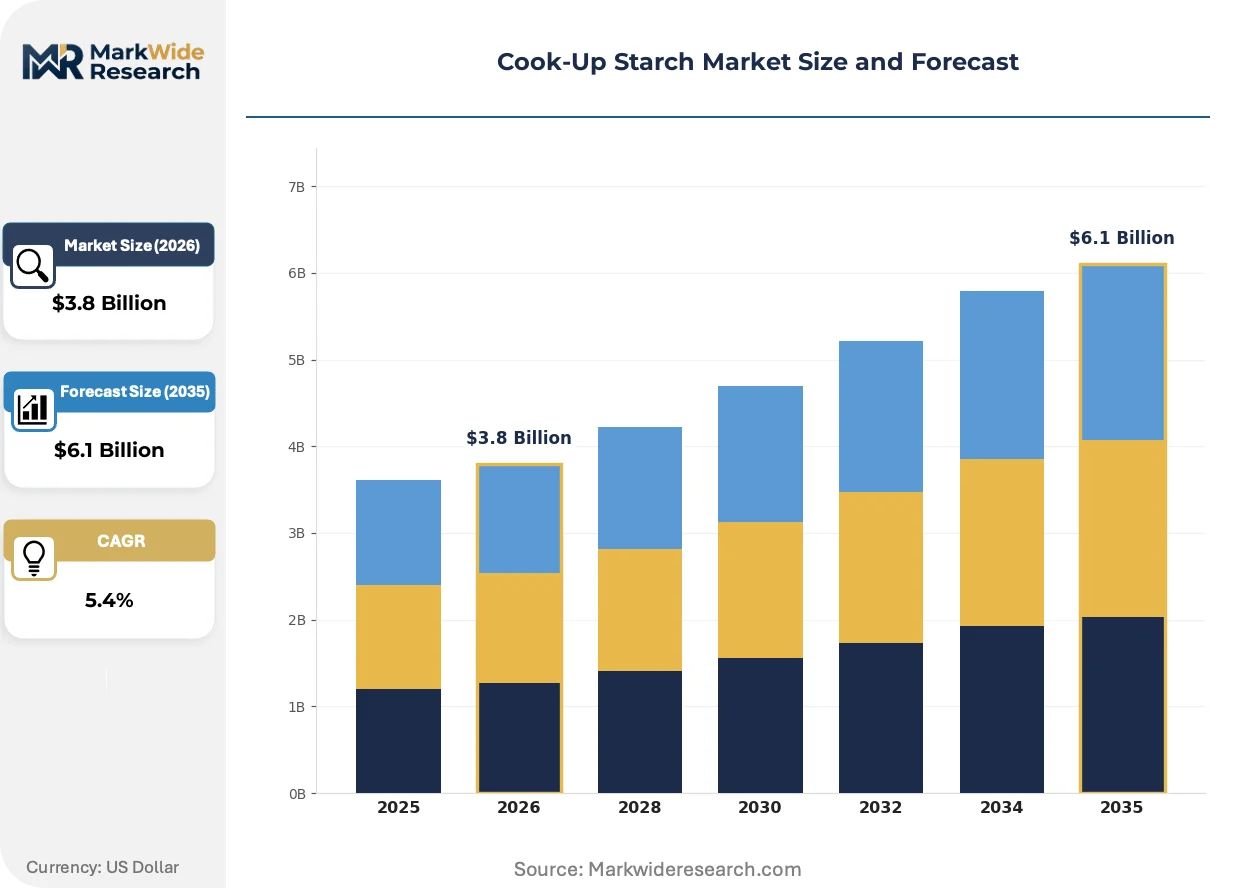
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Products, Bakery Items, Sauces, Snacks Product Type: Modified Starch, Native Starch, Instant Starch, Pre-gelatinized Starch Distribution Channel: Online Retailers, Supermarkets, Wholesale Distributors, Specialty Stores End User: Food Manufacturers, Restaurants, Catering Services, Home Cooks |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Avebe U.A., Emsland Group, AGRANA Beteiligungs-AG, Grain Processing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cook-Up Starch Market Strategic Shifts
Physical modification technologies are displacing chemical derivatization as the dominant innovation pathway, driven by clean-label certification demands and tightening residual reagent regulations across multiple jurisdictions.
Shear-induced modification is fragmenting the traditional chemical modification value pool. This thermal-mechanical process disrupts granular structure without reagent introduction, enabling clean-label viscosity development. Premium sauce and ready-meal formulators in Germany and the Netherlands are adopting shear-modified starches at accelerating rates. The technology is compressing margins for legacy chemical modification houses while creating entry points for equipment specialists with extrusion expertise.
EU REACH Annex XVII updates are tightening residual epichlorohydrin and propylene oxide thresholds for chemically modified food starches. Industrial consequence includes forced process redesign for cross-border suppliers serving European manufacturing customers. High-viscosity sauce systems and frozen bakery applications are most affected, with formulators accelerating qualification of physically modified alternatives to maintain import compliance.
Buyer concentration among multinational food manufacturers is compressing supplier negotiation leverage and accelerating qualification timeline demands. Procurement teams at major bakery and sauce producers are consolidating starch supplier panels from six-to-eight vendors to three-to-four preferred partners with dual-continent supply security. This pattern is most visible in Germany and surrounding Central European manufacturing clusters where Emsland Group and Roquette Frères anchor regional processing infrastructure.
Cook-Up Starch Market Segmentation
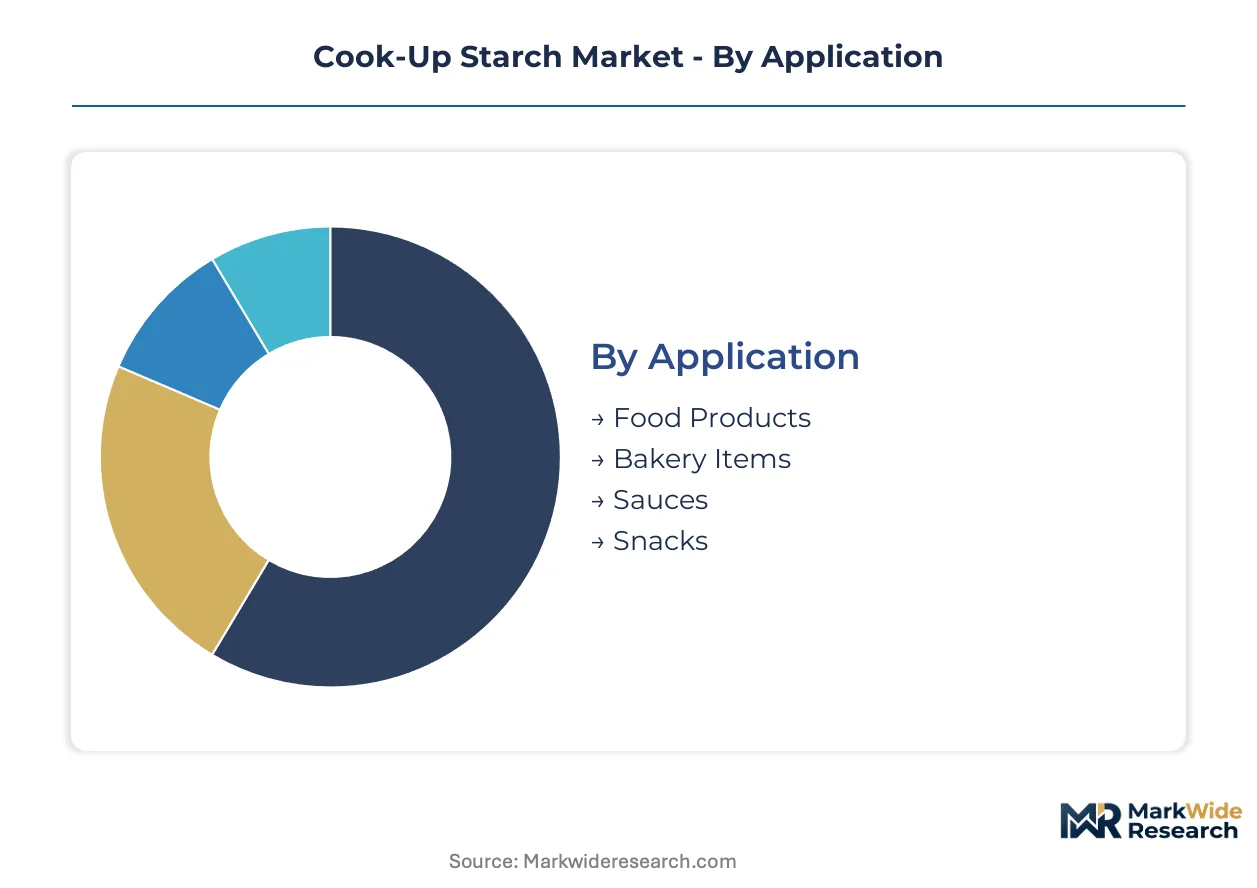
Cook-up starch procurement patterns diverge sharply between bulk industrial buyers negotiating long-term supply contracts and fragmented foodservice operators purchasing through distribution intermediaries. Channel economics dictate formulation requirements, with food manufacturers prioritizing functional consistency at scale while restaurants trade performance precision for packaging flexibility and minimum order efficiency.
Application:
Food manufacturers route high-volume sauce and bakery applications through wholesale distributors, whereas snack producers increasingly source directly from modification houses to secure extrusion-grade specifications.
- Food Products:Encompasses ready-meals, processed meats, and dairy analogues where freeze-thaw stability and shear resistance determine supplier selection. Concentrated demand among German and Dutch frozen food manufacturers facing EU Green Deal carbon documentation mandates.
- Bakery Items:Bread, cakes, and pastry applications requiring specific amylose-amylopectin ratios for crumb structure and shelf-life extension. Clean-label pressures are accelerating native starch substitution in cost-sensitive European retail bakery channels.
- Sauces:High-viscosity systems demanding peak stability at 85–95°C gelatinization temperatures. Brabender amylograph testing protocols dominate procurement specifications for premium sauce formulators.
- Snacks:Extruded and coated products where high-shear processing resistance determines quality outcomes. Retail channel proliferation across Central European markets is pulling modified starch demand from integrated processors.
Food Products dominates installed base. Snacks is where expansion concentrates.
Product Type:
Margin stratification separates commodity native grades from premium modified variants, with physical modification technologies capturing price premiums previously reserved for chemical derivatization.
- Modified Starch:Chemically or physically altered to enhance freeze-thaw stability, acid resistance, and shear tolerance. EFSA residual reagent thresholds under EU REACH are forcing process redesign for cross-border suppliers serving European manufacturing customers.
- Native Starch:Unmodified granular starch extracted through standard wet-milling without derivatization. Cost-sensitive bakery segments in France and Italy are shifting volume toward native grades as functional performance gaps narrow.
- Instant Starch:Cold-water dispersible variants eliminating thermal hydration requirements. Catering services and quick-service restaurants prioritize instant grades for operational speed despite viscosity limitations.
- Pre-gelatinized Starch:Thermally pre-treated starch offering partial hydration convenience. Home cook segments through specialty stores and online channels drive fragmented demand for pre-gelatinized convenience formats.
Native Starch commands volume leadership. Modified Starch is climbing the fastest on value expansion.
Distribution Channel:
Procurement scale determines channel selection, with multinational food manufacturers bypassing intermediaries while regional players depend on distributor technical service capabilities.
- Online Retailers:E-commerce platforms serving fragmented home cook and small restaurant demand with packaged specialty grades. German and French digital grocery expansion is creating new access points for pre-gelatinized and instant formats.
- Supermarkets:Retail shelf presence for consumer-packaged starch products targeting home cooking applications. Limited penetration outside specialty and ethnic food aisles in mainstream European grocery.
- Wholesale Distributors:Bulk supply intermediaries providing technical service and inventory management for mid-scale food manufacturers. Central European distribution clusters around Emsland and Roquette processing infrastructure anchor regional supply security.
- Specialty Stores:Niche channels serving ethnic food manufacturers and artisanal producers requiring specific botanical sources or certification grades. Concentrated in urban manufacturing corridors with diverse food processing bases.
Wholesale Distributors dominate industrial procurement. Online Retailers is gaining share fastest among fragmented end users.
End User:
Formulation sophistication varies dramatically across user types, from food manufacturer laboratories conducting amylograph validation to home cooks relying on package instructions.
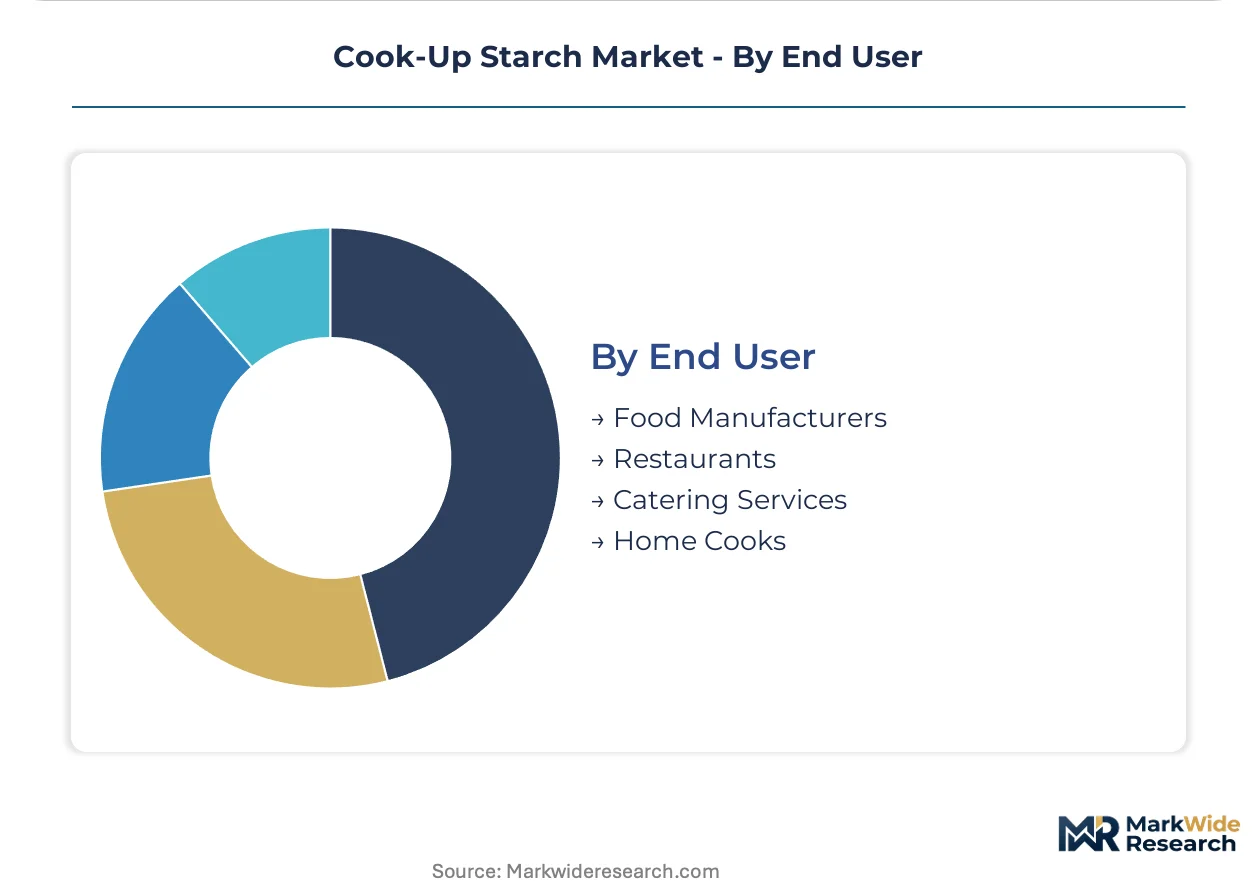
- Food Manufacturers:Industrial-scale buyers implementing supplier scorecards tied to carbon intensity documentation and dual-continent supply security. German frozen ready-meal producers are consolidating vendor panels from six-to-eight suppliers to three-to-four preferred partners.
- Restaurants:Foodservice operators prioritizing operational consistency and packaging flexibility over peak viscosity precision. Quick-service chains in the Netherlands favor instant starch for sauce preparation speed.
- Catering Services:Large-volume event and institutional food providers requiring cold-water dispersible solutions for field preparation. Bulk procurement through wholesale distributors dominates channel economics.
- Home Cooks:Fragmented consumer demand for convenience formats with clear preparation instructions. Limited price tolerance constrains penetration of premium modified grades outside specialty retail.
Food Manufacturers anchor demand volume. Restaurants is where application diversification is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food manufacturers consume cook-up starch primarily for frozen ready-meal viscosity stability, whereas United States buyers concentrate procurement in extruded snack applications where high-shear resistance commands formulation premiums.
Germany
Frozen ready-meal producers in Lower Saxony drive modified starch demand for texture recovery after freeze-thaw cycles. EU REACH Annex XVII compliance documentation anchors supplier qualification protocols for cross-border procurement teams. Emsland Group's processing complex in Emlichheim anchors regional supply security for multinational food manufacturers consolidating vendor panels.
United States
Extruded snack manufacturers prioritize high-shear stability in cook-up starch specifications for coated and puffed product lines. FDA 21 CFR 172.892 governs chemical modification permissibility for domestic and imported grades. Cargill Incorporated leverages its Minneapolis headquarters and grain origination network to secure feedstock cost advantages across multiple hemispheres.
France
Retail bakery channels accelerate native starch substitution as clean-label pressures narrow functional performance gaps against modified alternatives. EU Green Deal farm-to-fork carbon intensity documentation mandates pull procurement toward processors with verified wet-milling sustainability credentials. Roquette Frères' Lestrem facility anchors starch processing infrastructure serving northern French manufacturing clusters.
Netherlands
Sauce formulators in Dutch manufacturing corridors adopt shear-modified starches at accelerating rates to bypass residual reagent compliance constraints. EFSA purity standards under EU REACH constrain import flexibility for Asian suppliers using higher-reagent modification chemistries. Avebe U.A.'s potato starch expertise concentrates in Groningen province, serving premium viscosity applications.
China
Domestic snack producers expand extrusion capacity, pulling modified starch demand toward local wet-milling operators with cost-positioning advantages. SAMR food additive standards and GB quality benchmarks govern import substitution strategies for multinational manufacturers. Processing clusters in Shandong province concentrate native and modified starch production for cost-sensitive Asian food manufacturing.
Cook-Up Starch Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding feedstock origination advantages and the lower tier competing on modification technology differentiation. The market structure reflects consolidation pressure from buyer panel reduction at major food manufacturers. Three archetypes dominate: grain-origination majors with captive supply networks, European potato-starch specialists with regional clustering advantages, and mid-scale modification houses retrofitting continuous processing platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure dual-continent supply security credentials.
Within the integrated grain-origination tier, Cargill Incorporated and Archer Daniels Midland Company exemplify the feedstock-cost positioning that underpins volume leadership. Ingredion Incorporated occupies a position among the R&D-intensive modification specialists, while Tate & Lyle PLC sits within the precision-formulation tier targeting high-viscosity sauce systems. European potato-starch concentration is represented by Roquette Frères and Avebe U.A., both anchoring regional supply infrastructure in France and the Netherlands respectively. Emsland Group exemplifies the mid-scale continuous-processing retrofit strategy, consolidating position in German manufacturing corridors through technical service depth.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Avebe U.A. |
| Emsland Group |
| AGRANA Beteiligungs-AG |
| Grain Processing Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at integrated wet-milling complexes in Germany and the Netherlands sets price floors across the cook-up starch value chain, compressing margin headroom for non-integrated modification houses lacking captive grain origination. Scale advantages at Emsland Group and Roquette Frères processing clusters translate into procurement leverage that mid-scale competitors cannot match without continuous processing retrofits.
Pricing Analysis
After-sales technical service contracts and formulation support agreements drive lifetime value for modification houses serving multinational food manufacturers. Three-tier pricing structure across premium modified, standard native, and economy unmodified grades reflects certification tier and amylograph performance specifications. Cost compression in standard native grades is intensifying because clean-label substitution narrows functional performance gaps against modified alternatives. Food manufacturers implementing supplier consolidation programs exhibit lowest price sensitivity, while fragmented foodservice operators purchasing through wholesale distributors remain most exposed to spot-price volatility.
Supply Chain Analysis
Germany, the Netherlands, and France anchor wet-milling and modification infrastructure for European cook-up starch supply. Maize and wheat feedstock draws from Black Sea and North American origination networks, while potato starch sources concentrate in Dutch and northern French growing regions. Single-source vulnerability at specialized modification houses lacking dual-continent supply security creates procurement risk for multinational food manufacturers. Distribution runs through wholesale distributor clusters around Emsland and Roquette processing facilities, with direct sourcing gaining share among extruded snack producers seeking extrusion-grade specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label certification platforms are creating interoperability standards that reshape supplier qualification economics, with EU REACH and FDA dual-compliance documentation becoming the dominant ecosystem gatekeeper for cross-border procurement.
For Market Incumbents: Fortify position by deepening backward integration into specialty potato and waxy maize cultivars with tailored amylose-amylopectin ratios, and accelerate physical modification platform deployment to preempt regulatory tightening on residual reagent thresholds. Shear-induced modification technology from equipment specialists threatens legacy chemical modification margins. Certification investment in EU Green Deal carbon intensity documentation anchors preferred supplier status with consolidating buyer panels. For New Entrants and Emerging Players: Anchor in physical modification white space where thermal and hydrothermal platforms bypass chemical derivatization entirely, targeting German and Dutch sauce formulators facing EFSA purity compliance constraints. Shear-modified starch adoption among premium ready-meal producers represents the most penetrable segment. Technical service partnerships with Brabender amylograph testing laboratories accelerate qualification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated wet-milling operators with long-term supply contracts to multinational food manufacturers and captive technical service relationships. Five-to-ten year viability favors processors with verified sustainability credentials across cultivation and modification stages. Acquisition target archetype: mid-scale modification houses with continuous processing retrofits underway and established European manufacturing corridor presence. Signal to watch: buyer panel consolidation velocity at German frozen ready-meal producers.| Strategic Initiative | Industry Significance |
|---|---|
| Physical Modification Platform Deployment | Shear-induced and hydrothermal technologies bypass EU REACH residual reagent constraints entirely. |
| Backward Integration into Specialty Cultivars | Captive waxy maize and potato supply secures amylose-amylopectin ratio control for premium grades. |
| Dual-Continent Supply Security Certification | FDA and EU REACH compliance documentation opens procurement access to consolidating multinational panels. |
| Carbon Intensity Documentation Investment | EU Green Deal farm-to-fork verification anchors preferred supplier scorecards at major food manufacturers. |
| Continuous Processing Retrofit | Batch-to-continuous conversion matches integrated operator efficiency and compresses unit modification costs. |
Study Parameters
A standing panel of starch modification plant managers, procurement leads at downstream food manufacturers, distribution channel partners, and technical R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from EU REACH Annex XVII filings, EFSA purity standard updates, FDA 21 CFR 172.892 regulatory registers, and customs trade data on maize and wheat feedstock flows. Bottom-up volume modeling across application segments triangulated against top-down value estimates from processor revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, application, distribution channel, and end user, with additional dimensioning by modification technology platform and certification tier. CAGRs were derived from trend extrapolation of clean-label substitution rates and physical modification adoption curves, with inputs from Brabender amylograph performance specifications and extrusion-grade demand growth in snack applications.
Material uncertainties — feedstock price volatility, regulatory threshold revisions, and buyer panel consolidation velocity — sit outside the modeled envelope. Forecasts reflect assumptions on clean-label certification permanence and physical modification technology maturation. Recalibration cycles align with material shifts in EU REACH enforcement patterns and multinational procurement policy changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Japan Food Enzymes Market