
 South America Feed Yeast Market | 2026-2036
South America Feed Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Yeast Market Analytics
Distributor networks across Brazil and Argentina is reconfiguring as multinational feed compounders consolidate procurement around fewer, larger yeast suppliers. Lesaffre et Compagnie S.A. anchors its South American position through captive fermentation capacity near São Paulo. Lallemand Inc. competes by specializing in live yeast cultures tailored to tropical ruminant stress conditions. ICC Brazil leverages local manufacturing to sustain cost advantages in dried yeast for domestic poultry integrators.
Feed yeast comprises Saccharomyces cerevisiae and related species cultivated through aerobic fermentation, then processed into live, dried, autolyzed, or derivative forms containing proteins, nucleotides, and beta-glucans that modulate gut microbiota and enhance nutrient absorption in monogastric and ruminant animals. Its primary commercial purpose is to improve feed conversion ratios and replace or reduce antibiotic growth promoters in intensive livestock systems. Dried yeast occupies the largest volume share due to shelf stability and blending compatibility with standard feed mills, while live yeast commands premium positioning among ruminant nutritionists seeking real-time rumen pH modulation. Yeast derivatives represent the fastest-expanding margin pool as aquaculture and premium poultry premixes absorb nucleotide-rich fractions for immune priming.
Brazil's MAPA enforces veterinary product registration and residue thresholds that elevate compliance costs for imported yeast additives, while Argentina's SENASA mandates GMP certification for all feed-grade microbial products entering its domestic supply chain. These frameworks advantage producers with established local quality dossiers and on-ground technical service teams. Stakeholders must monitor pending regulatory harmonization talks between Mercosur members, as unified standards would reshape cross-border manufacturing and distribution strategies.
Market Dynamics
Brazil's MAPA residue mandates are forcing feed compounders to abandon antibiotic growth promoters and rebuild formulations around verified yeast derivatives, restructuring procurement relationships across the continent's largest feed manufacturing corridor.
Growth Catalysts
- Regulatory displacement:MAPA's stricter veterinary residue thresholds in Brazil eliminate legacy antibiotic options and redirect formulation budgets toward Saccharomyces cerevisiae-based alternatives with established compliance dossiers.
- Poultry integration density:São Paulo and Minas Gerais states concentrate integrated broiler operations that absorb dried yeast at scale for feed conversion optimization in antibiotic-free systems.
- Rumen acidosis mitigation:Argentine feedlot operators facing heat-stress losses are adopting live yeast cultures for real-time rumen pH modulation in high-grain finishing diets.
Market Restraints
- Molasses supply volatility:Brazilian ethanol sector competition for cane-derived feedstock creates input cost instability for domestic fermentation capacity.
- Import dependency for derivatives:Nucleotide-rich yeast fractions for aquaculture premixes rely on European processing infrastructure, exposing margins to currency fluctuation.
- SENASA GMP certification friction:Argentina's mandatory good manufacturing practice requirements for feed-grade microbial products extend approval timelines for new market entrants.
Strategic Opportunities
- Colombian aquaculture penetration:Tilapia and shrimp producers along the Magdalena River basin remain undersupplied with beta-glucan immune primers for hatchery applications.
- Autolyzed yeast fractionation:Separation of mannan-oligosaccharide and nucleotide streams enables premium positioning in breeder hen and early-stage piglet premixes.
- Mercosur harmonization tailwind:Pending unified standards across member states would eliminate redundant registration costs and enable centralized manufacturing for cross-border distribution.
Industry Challenges
- Fermentation technologist scarcity:Brazil's universities produce insufficient aerobic process engineers to staff expanding captive production facilities near Campinas.
- MAPA dossier compilation timelines:Veterinary product registration requirements demand 18-24 month technical documentation cycles that delay revenue recognition for novel yeast strains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Yeast Market |
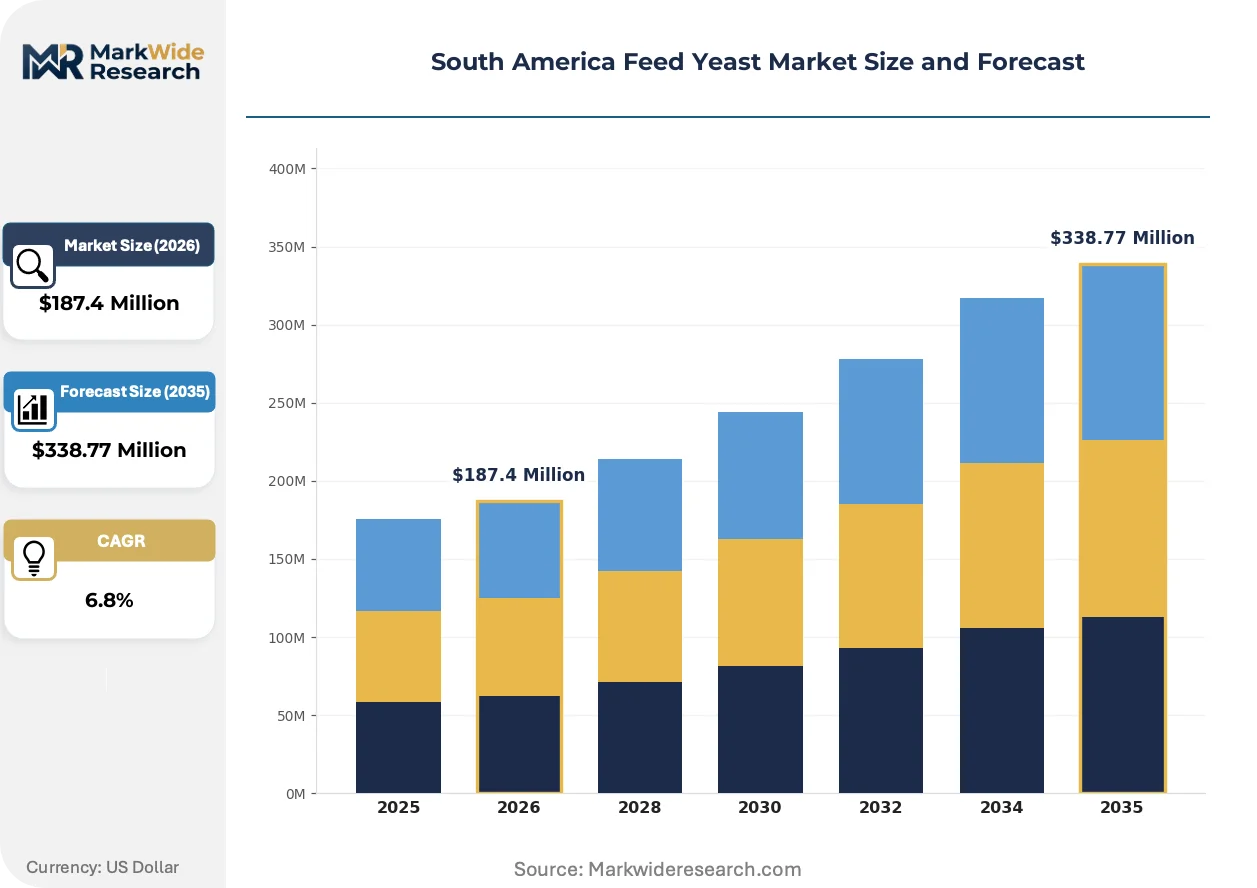
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Yeast, Dried Yeast, Autolyzed Yeast, Yeast Derivatives End User: Poultry, Ruminants, Swine, Aquaculture Application: Animal Feed, Nutritional Supplements, Premixes, Functional Ingredients Distribution Channel: Online Retail, Distributors, Supermarkets, Specialty Stores |
| Companies Covered | dsm-firmenich AG, Lesaffre et Compagnie S.A., Lallemand Inc., Kemin Industries, Inc., Alltech, Inc., Archer Daniels Midland Company, Nutreco N.V., ICC Brazil, Cargill, Incorporated, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Yeast Market Evolving Landscape
Feed yeast technology is fragmenting into specialized functional streams as tropical livestock stress physiology and residue-free mandates reshape product development priorities across South American operations.
Yeast cell wall extraction technology is hybridizing conventional autolysis with enzymatic hydrolysis to isolate beta-glucan fractions with enhanced immune-modulating potency. Argentine dairy nutritionists are adopting these refined derivatives for transition cow diets at accelerating rates. The technology is hybridizing dried yeast commodity margins toward pharmaceutical-grade fractionation economics that favor integrated processors with in-house laboratory capabilities.
MAPA's veterinary product registration framework now mandates batch-level residue documentation and third-party laboratory verification for all imported microbial feed additives. This regulatory architecture elevates compliance costs for traders lacking Brazilian technical service infrastructure. Domestic poultry integrators are responding by consolidating procurement around suppliers with established São Paulo-state quality dossiers and on-ground laboratory partnerships.
Compound feed manufacturers are unbundling yeast specification from volume-based procurement contracts and adopting performance-guaranteed ingredient purchasing. Large integrators in Brazil's southeastern corridor now negotiate live yeast inclusion rates tied to measured rumen pH or feed conversion outcomes rather than standard dry matter percentages. This behavioral shift concentrates most visibly among vertically integrated broiler operations with in-house nutrition teams and real-time barn monitoring systems.
South America Feed Yeast Market Segmentation
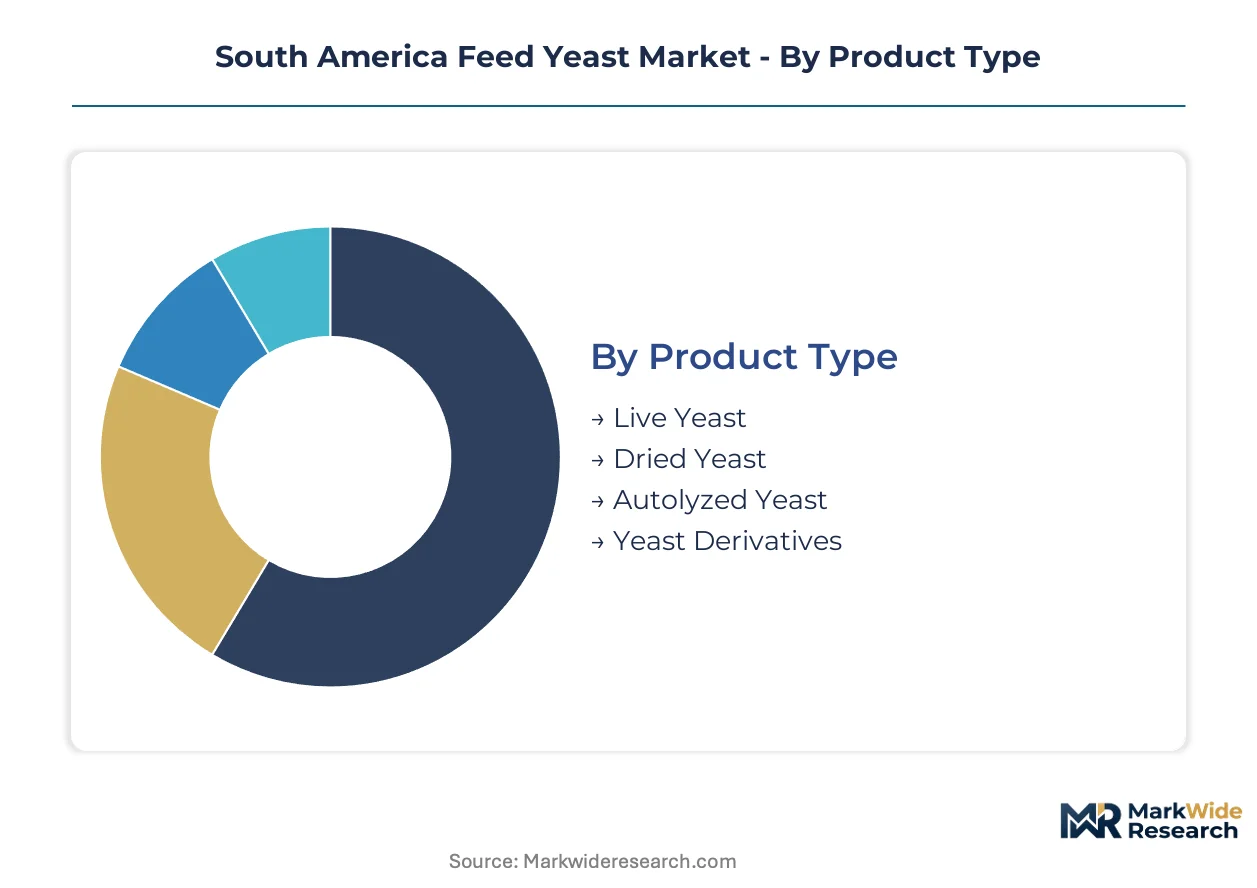
Feed yeast segmentation in South America reflects divergent production economics and regulatory compliance burdens across product forms. Understanding these divisions clarifies where formulation budgets concentrate versus where margin expansion is occurring.
Product Type:
Inventory velocity varies dramatically across product types, with dried yeast turning fastest through standard feed mills while live yeast cultures require cold-chain logistics that extend order cycles.
- Dried Yeast:Saccharomyces cerevisiae biomass dehydrated to 8-10% moisture content, processed into inactive whole cells or cell fragments. São Paulo-state poultry integrators absorb this form at scale for antibiotic-free broiler formulations, driven by MAPA residue documentation requirements that favor established shelf-stable products with complete compliance dossiers.
- Yeast Derivatives:Fractionated outputs including beta-glucans, mannan-oligosaccharides, and nucleotides extracted through enzymatic or autolytic processing. Aquaculture hatcheries along Brazil's northeastern coast and Colombian Magdalena River basin are absorbing nucleotide-rich fractions for immune priming in tilapia and shrimp larval stages, climbing the fastest as premium premix margins outpace commodity dried yeast economics.
- Live Yeast:Viable Saccharomyces cerevisiae cultures maintained in active metabolic state, requiring temperature-controlled distribution infrastructure. Argentine feedlot operators facing heat-stress mortality are adopting these cultures for real-time rumen pH modulation in high-grain finishing diets.
- Autolyzed Yeast:Self-digested yeast biomass where endogenous enzymes rupture cell walls to release intracellular proteins and nucleotides. Brazilian breeder hen operations use this intermediate grade for early-stage immune development protocols.
Dried yeast dominates installed base across southeastern Brazil's feed manufacturing corridor. Yeast derivatives is where expansion concentrates as aquaculture and premium poultry premixes absorb fractionated outputs.
End User:
Customer scale and technical sophistication determine procurement patterns, with integrated operations driving volume while specialized segments command premium positioning.
- Poultry:Vertically integrated broiler operations across São Paulo and Minas Gerais states constitute the largest volume sink, with in-house nutrition teams specifying yeast inclusion rates tied to feed conversion outcomes rather than standard dry matter percentages.
- Ruminants:Argentine feedlot operators and Brazilian dairy cooperatives are adopting live yeast cultures for rumen acidosis mitigation, particularly where heat stress compounds metabolic disorders in high-grain finishing systems.
- Swine:Sow farms and nursery operations in southern Brazil incorporate autolyzed yeast for gut microbiota modulation in post-weaning piglets, though penetration lags poultry integration density.
- Aquaculture:Tilapia and shrimp producers in Colombia's Magdalena River basin and Brazil's northeastern coastal zones remain undersupplied with beta-glucan immune primers, creating expansion headroom as hatchery biosecurity standards tighten.
Poultry commands the largest share of current procurement volume. Aquaculture represents the steepest expansion trajectory as hatchery applications for nucleotide fractions gain technical validation.
Application:
Specification intensity escalates from bulk feed inclusion through to pharmaceutical-grade functional ingredients, with documentation requirements multiplying at each tier.
- Animal Feed:Direct inclusion into complete feeds at 0.1-2.0% inclusion rates, predominantly dried yeast forms blended at standard feed mills across Brazil's southeastern manufacturing corridor.
- Premixes:Concentrated formulations containing 5-20% yeast derivatives, produced by specialized compounders for distribution to mid-scale operations lacking in-house formulation capability.
- Functional Ingredients:Isolated beta-glucan and nucleotide fractions positioned for immune modulation claims, requiring MAPA veterinary product registration and third-party laboratory verification that elevates compliance costs.
- Nutritional Supplements:Direct-fed microbials and yeast-based additives sold through veterinary channels for targeted therapeutic or transition-period interventions.
Animal Feed anchors current volume throughput. Functional Ingredients is where margin expansion concentrates as fractionation technology enables pharmaceutical-grade positioning.
Distribution Channel:
Channel selection correlates with customer scale and technical service requirements, with large integrators bypassing traditional intermediaries.
- Distributors:Regional feed additive distributors with technical service teams dominate mid-scale poultry and swine operation supply, particularly in Brazil's interior states beyond São Paulo's manufacturing corridor.
- Online Retail:Emerging channel serving smallholder operations and specialty livestock producers, constrained by cold-chain requirements for live yeast products and MAPA documentation needs for derivative forms.
- Specialty Stores:Veterinary and agricultural supply retailers catering to hobby farmers and niche species producers with smaller lot sizes and higher service expectations.
- Supermarkets:Minimal penetration limited to consumer-facing pet supplement formats, negligible for production livestock applications.
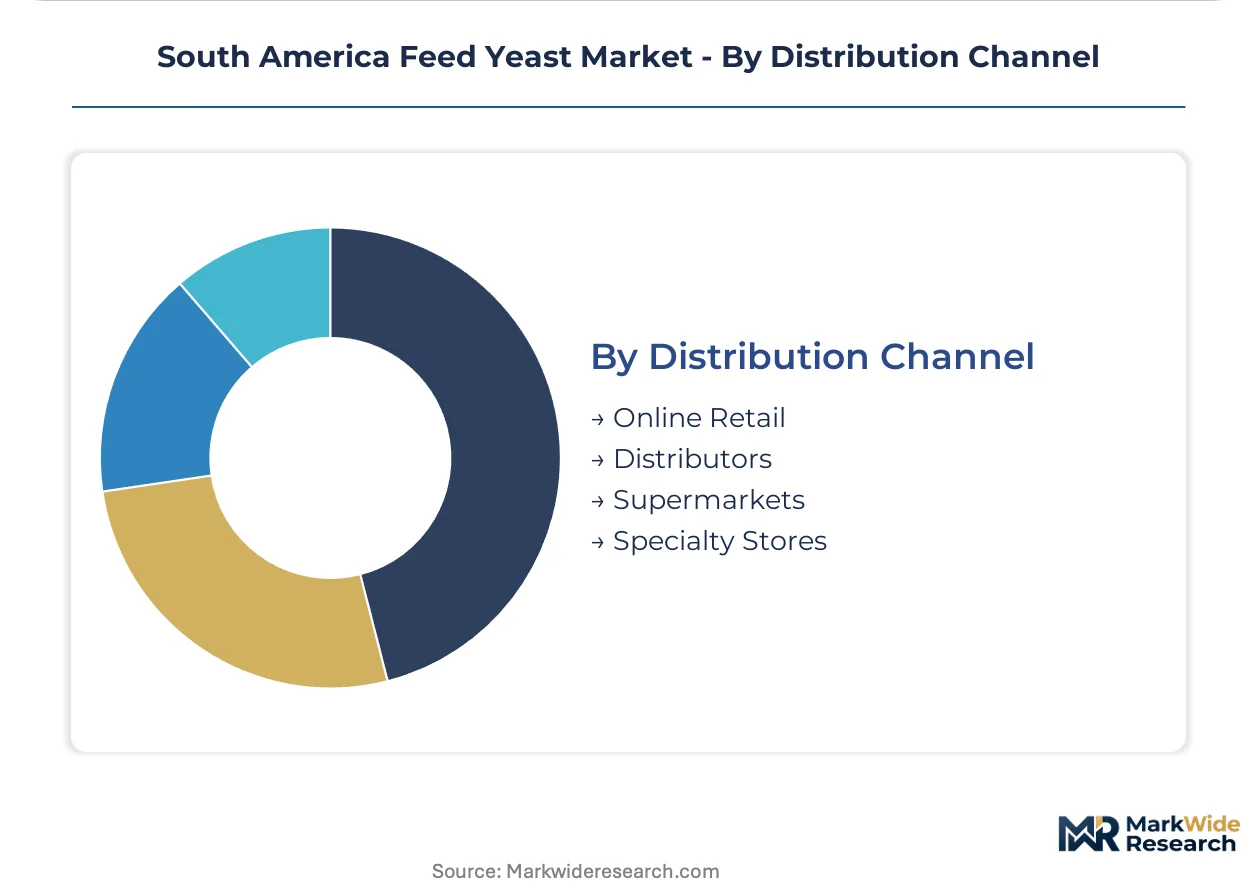
Distributors maintain the deepest installed base across commercial livestock operations. Online Retail is where channel experimentation concentrates as digital procurement platforms target underserved smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paranaguá Container Terminal anchors Brazil's feed yeast import infrastructure, handling bulk fermentation inputs that supply São Paulo's manufacturing corridor. This port capacity underwrites South America's largest feed additive distribution network.
Brazil
Poultry integrators in São Paulo and Minas Gerais states absorb dried yeast at scale for antibiotic-free broiler systems. MAPA's veterinary residue mandates eliminate legacy growth promoters and redirect procurement toward verified Saccharomyces cerevisiae products. Campinas anchors captive fermentation expansion as universities struggle to supply sufficient aerobic process engineers.
Argentina
Feedlot operators adopt live yeast cultures for rumen pH modulation amid heat-stress mortality in high-grain finishing diets. SENASA mandates GMP certification for all feed-grade microbial products, extending approval timelines for new entrants. The Pampas grain belt concentrates technical service teams serving integrated cattle operations.
Colombia
Tilapia and shrimp producers along the Magdalena River basin remain undersupplied with beta-glucan immune primers for hatchery applications. The national aquaculture regulator tightens biosecurity standards for larval-stage nutrition. Barranquilla's port infrastructure supports emerging import channels for nucleotide-rich yeast fractions.
Chile
Salmon aquaculture operations drive demand for autolyzed yeast derivatives in smolt immunization protocols. The country's national fisheries service enforces residue documentation for all imported feed additives. Puerto Montt anchors processing capacity serving southern marine hatchery clusters.
Peru
Marine fishmeal processors diversify into yeast-based protein alternatives amid volatile anchovy harvests. The national agricultural health service monitors microbial feed additive registrations with heightened scrutiny. Lima's feed manufacturing district concentrates blending operations for Andean poultry integrators.
South America Feed Yeast Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with fractionation technology and fermentation capacity. The market structures around three tiers: multinational nutrition platforms with veterinary registration infrastructure, regional fermentation operators with molasses supply security, and derivative specialists with enzymatic extraction capabilities. Dominant competitive moves include backward integration into captive fermentation capacity and strategic partnerships with university laboratories for novel strain development.
Among European-anchored nutrition platforms, dsm-firmenich AG and Lesaffre et Compagnie S.A. exemplify the integrated archetype with established MAPA dossiers and São Paulo-state technical presence. Lallemand Inc. represents the specialized live yeast tier, occupying a position tied to tropical ruminant stress applications. ICC Brazil anchors the domestic manufacturing vector, sitting within the cost-advantaged dried yeast segment serving poultry integrators. These three archetypes—multinational platform, live yeast specialist, and local fermenter—define competitive positioning across the continent's feed manufacturing corridor.
| Leading Market Players |
|---|
| dsm-firmenich AG |
| Lesaffre et Compagnie S.A. |
| Lallemand Inc. |
| Kemin Industries, Inc. |
| Alltech, Inc. |
| Archer Daniels Midland Company |
| Nutreco N.V. |
| ICC Brazil |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
The Paranaguá-Santos logistics corridor shapes cost dynamics across Brazil's feed yeast market, concentrating supply power among São Paulo-state fermenters while forcing price differentiation between cold-chain live yeast and shelf-stable dried forms.
Pricing Analysis
Volume-discount tiering structures separate MAPA-registered functional ingredients from commodity dried yeast, with certification-grade beta-glucan fractions commanding premium positioning against standard autolyzed forms. Price differentiation hinges on veterinary dossier completeness and cold-chain logistics requirements, with Argentine feedlot operators absorbing live yeast premiums for rumen pH modulation. Pricing pressure stems from molasses feedstock competition with Brazil's ethanol sector, compressing margins for domestic fermentation capacity. Smallholder aquaculture producers in Colombia's Magdalena basin exhibit highest price sensitivity, while vertically integrated Brazilian poultry operations prioritize performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between European nucleotide processors and Brazilian aquaculture premixers dominates supply chain risk architecture, exposing margin pools to currency fluctuation. Geographic supply concentration centers on Brazil, Argentina, and European derivative processors, with nucleotide-rich fractions drawing from enzymatic extraction infrastructure outside the continent. Raw material dependencies include cane molasses, fermentation nutrients, and specialized cold-chain packaging. Single-source vulnerability characterizes nucleotide supply, where hatchery applications hinge on limited European fractionation capacity. Distribution runs through São Paulo-state technical service teams serving integrated poultry operations, with regional distributors covering mid-scale swine and ruminant producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MAPA's antibiotic displacement mandate creates a high-growth disruption window, redirecting formulation budgets toward Saccharomyces cerevisiae alternatives with established residue compliance dossiers.
For Market Incumbents: Entrench position through captive fermentation capacity expansion near Campinas and MAPA dossier deepening for novel strain variants. Consolidate procurement relationships with São Paulo-state poultry integrators before harmonized Mercosur standards enable cross-border competitor entry. Threat vectors include European nucleotide processors establishing Brazilian fractionation joint ventures. For New Entrants and Emerging Players: Colombian aquaculture hatcheries along the Magdalena River basin represent the most penetrable entry point, with tilapia and shrimp producers undersupplied for beta-glucan immune primers. Argentine dairy cooperatives seeking transition cow derivatives offer secondary white-space. Go-to-market execution should anchor in Barranquilla port partnerships for nucleotide-rich import channels. For Investors and Strategic Acquirers: Regional fermentation operators with molasses supply security and established SENASA or MAPA quality dossiers present the optimal acquisition target archetype for medium-term consolidation plays. Long-term viability hinges on fractionation technology integration and Mercosur harmonization timing. The signal to watch is pending regulatory unification talks between member states.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Expansion | Backward integration into molasses-fed aerobic production near São Paulo insulates margin pools from ethanol sector competition. |
| MAPA Veterinary Product Registration | Established dossiers with batch-level residue documentation create procurement stickiness among antibiotic-free poultry integrators. |
| Enzymatic Fractionation Partnership | Joint ventures with European nucleotide processors localize immune-primer supply for Colombian aquaculture hatcheries. |
| Cold-Chain Distribution Buildout | Temperature-controlled logistics networks capture live yeast premiums from Argentine feedlot heat-stress mitigation demand. |
| Mercosur Harmonization Positioning | Centralized manufacturing readiness eliminates redundant registration costs when unified standards activate cross-border distribution. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MAPA veterinary product registrations, SENASA GMP certification databases, and customs trade flows for fermentation inputs. Primary interviews engaged feed compounder procurement directors, poultry integrator nutritionists, Argentine feedlot operators, and yeast manufacturer technical service teams. Secondary sources included ANVISA feed additive filings, Brazilian ethanol sector molasses utilization reports, and aquaculture hatchery biosecurity standards from Colombia's national regulator. Bottom-up volume estimates from state-level feed production statistics were triangulated against top-down manufacturer capacity disclosures.
Forecast inputs incorporate product form segmentation, end-user concentration patterns, and regulatory compliance burden trajectories across the projection horizon. The analytical framework models dried yeast, live yeast, yeast derivatives, and autolyzed yeast as distinct margin pools with divergent growth elasticities. CAGRs were derived from regression analysis against feed production forecasts and antibiotic displacement penetration curves. Industry-specific inputs include MAPA registration timeline assumptions and Mercosur harmonization probability weighting.
Stress conditions across molasses price volatility, currency fluctuation for nucleotide imports, and MAPA approval timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and fractionation technology transfer rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Protein Market
Ingredients
Cocoa Derivatives Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Edible Oils and Fats Market
Ingredients
Mung Bean Protein Market
Ingredients
Global Malt Ingredients Market
Ingredients
Carotenoids Market
Ingredients
Plant Based Ingredients Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Cheese Ingredients Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Apple Extract Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Campesterol Market
Ingredients
Canola Protein Market
Ingredients
Multi-Grain Premixes Market