
 Paclobutrazol Market | 2026-2036
Paclobutrazol Market Size, Share, and Industry Trends Forecast 2026-2036
Paclobutrazol Market Analysis
Ornamental plant cultivation is consolidating as a priority end-use vertical for paclobutrazol consumption, while traditional field-crop applications face margin compression. BASF SE leverages its formulation expertise across European horticulture markets. Jiangsu Luye Agrochemicals anchors supply from China's Jiangsu province. UPL competes through its extensive distributor network in South Asia and Latin America.
Paclobutrazol is a triazole plant growth regulator that inhibits gibberellin biosynthesis, typically applied at concentrations between 250 to 2000 ppm depending on crop species and desired growth suppression. Manufacturers synthesize the active ingredient through multi-step organic reactions involving chlorination and cyclization processes, yielding a white crystalline solid with melting point around 165 degrees Celsius. Emulsifiable concentrate formulations dominate commercial volumes due to superior shelf stability and ease of tank-mixing with fungicides. Soluble powder formats are gaining traction among research institutions and precision agriculture operators seeking calibrated dosing. The granular segment occupies a mature position in turf management applications where slow-release characteristics match maintenance schedules.
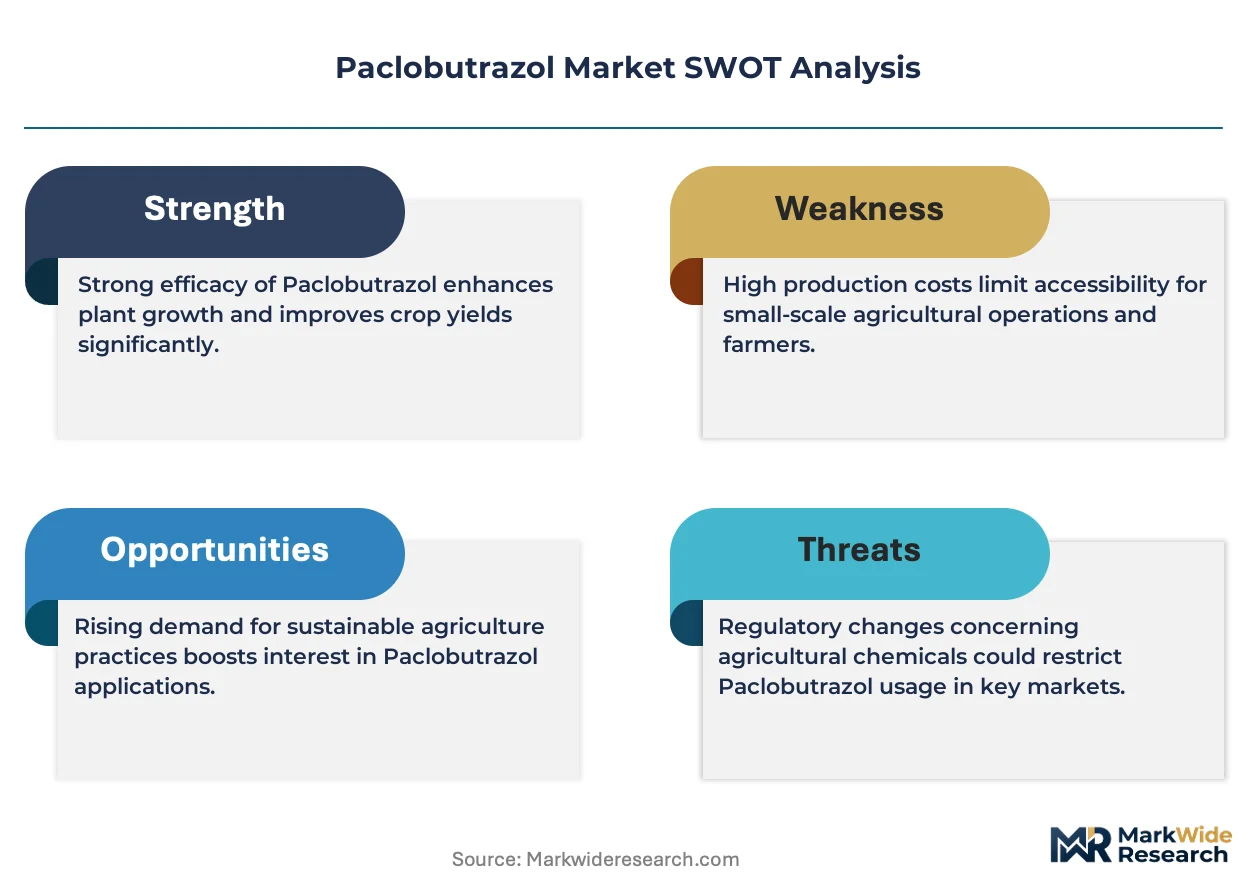
The EPA governs paclobutrazol tolerances and registration requirements under FIFRA in the United States, while REACH compliance governs substance authorization across EU member states. India's Central Insecticides Board mandates registration under the Insecticides Act for all imported and domestically manufactured formulations. China's Ministry of Agriculture and Rural Affairs enforces residue limits through GB standards that affect export-oriented producers. Stakeholders must monitor regulatory divergence between jurisdictions as maximum residue limits tighten in key export destinations and biopesticide alternatives advance through parallel approval pathways.
Market Dynamics
Ornamental horticulture's pivot toward precision growth management is compressing traditional field-crop margins while elevating formulation complexity requirements across the value chain.
Growth Catalysts
- Protected Cultivation Expansion:India's Maharashtra and Gujarat states are scaling greenhouse infrastructure for fruits and vegetables, creating concentrated demand nodes for growth regulators with precise dose-response profiles.
- REACH Authorization Pathways:The EU's substance evaluation framework is accelerating registration of low-dose triazole formulations, reducing time-to-market for compliant suppliers targeting European ornamental growers.
- Emulsifiable Concentrate Shelf Stability:Superior tank-mix compatibility with fungicide programs is pulling adoption among commercial greenhouse operators managing integrated pest and growth protocols.
Market Restraints
- Chlorinated Intermediate Volatility:Multi-step organic synthesis involving chlorination and cyclization exposes manufacturers to petrochemical feedstock price swings and energy-intensive process costs.
- Jiangsu Province Supply Concentration:China's Jiangsu province anchors a disproportionate share of active ingredient production, creating geographic vulnerability to regional environmental enforcement actions.
- Biopesticide Substitution Trajectory:Gibberellin biosynthesis inhibitors derived from microbial fermentation are advancing through parallel regulatory pathways, threatening triazole market position in organic-certified operations.
Strategic Opportunities
- Precision Agriculture Integration:Soluble powder formats calibrated for drone and robotic application systems are opening white space among research institutions and technology-forward growers.
- Latin American Distributor Networks:Underpenetrated protected cultivation markets in Brazil and Colombia offer expansion vectors for established South Asian supply chains.
- EPA Re-Registration Tailwinds:The agency's plant growth regulator review process is streamlining label expansions for turf management applications, enabling granular formulation growth in golf course and municipal maintenance segments.
Industry Challenges
- Residue Limit Harmonization:Divergent GB standards in China, EPA tolerances in the United States, and EU MRLs are forcing manufacturers to maintain multiple analytical certification workflows for export-oriented production.
- Formulation R&D Talent Scarcity:Expertise in slow-release granular engineering and emulsion stability chemistry is concentrating among aging specialist cohorts, constraining new product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paclobutrazol Market |
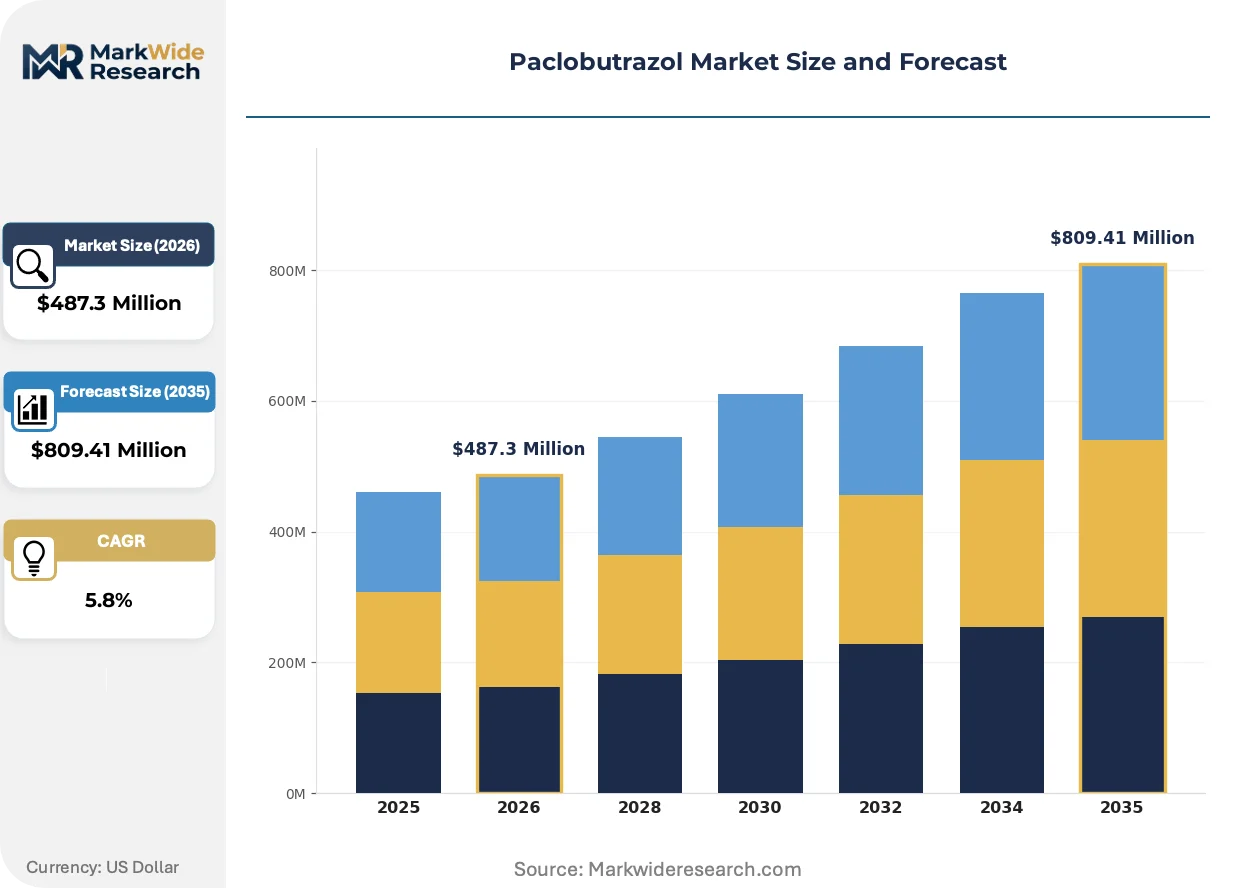
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid Concentrate, Soluble Powder, Emulsifiable Concentrate Application: Agriculture, Horticulture, Turf Management, Ornamental Plants End User: Farmers, Commercial Growers, Landscape Professionals, Research Institutions Distribution Channel: Online Stores, Distributors, Retail Outlets, Agricultural Cooperatives |
| Companies Covered | Bailing Agrochemical, Canary Agrochemicals Pvt. Ltd., India Pesticides Limited, Jiangsu Sevencontinent Green Chemical, Jiangsu Luye Agrochemicals, R.V. Agri Corporation, Yancheng Limin Chemical, UPL, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paclobutrazol Market Emerging Trajectories
Digital dosing platforms and bio-based formulation science are fragmenting established application protocols while regulatory pressure on residue chemistry intensifies reformulation investment cycles.
Micro-encapsulation technology for controlled-release paclobutrazol delivery is decentralizing application timing decisions away from calendar-based schedules toward plant-response triggers. Commercial greenhouse operators in the Netherlands and Spain are piloting sensor-integrated dosing systems that match growth suppression to real-time canopy development metrics. This shift is decentralizing agronomic authority from extension services to on-site precision agriculture technicians.
REACH's evolving substance authorization criteria are tightening hazard classification thresholds for triazole compounds across EU member states. Formulators are responding by investing in metabolite profiling and environmental fate studies to defend existing registrations. The ornamental cultivation segment faces the steepest compliance cost escalation, as smaller growers lack in-house regulatory affairs capacity.
Buyers are unbundling after-sales technical support from product supply contracts, demanding standalone agronomic consulting for dose optimization. This pattern is most pronounced among India's emerging protected cultivation clusters, where first-time greenhouse operators require intensive calibration guidance. Distributors are responding by building specialized horticulture service teams, compressing margins on pure product transactions while capturing value through advisory retainers.
Paclobutrazol Market Segmentation
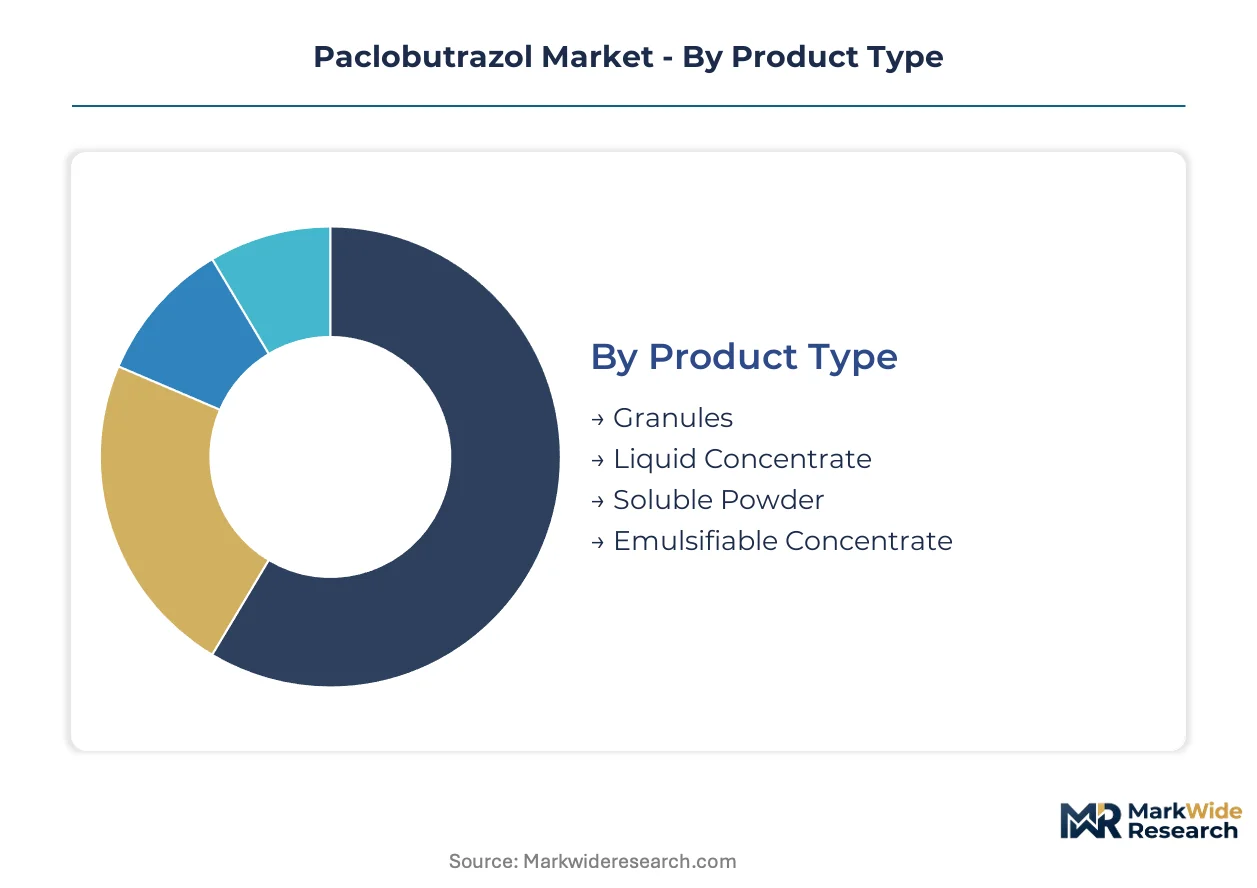
Paclobutrazol's formulation diversity and application specificity create distinct value tiers across the supply chain. Buyers segment by technical performance requirements, regulatory compliance burdens, and integration complexity with existing crop management protocols.
Product Type:
Cost tier differentiation separates commodity bulk buyers from precision agriculture operators seeking calibrated dosing flexibility.
- Emulsifiable Concentrate:Oil-in-water formulations deliver superior shelf stability and seamless tank-mix compatibility with fungicide programs. Commercial greenhouse operators in the Netherlands and Spain favor this format for integrated pest and growth management protocols where application timing flexibility reduces labor costs.
- Soluble Powder:Dry crystalline formulations enable precise weight-based dosing for research institutions and drone application systems. India's Maharashtra protected cultivation clusters are adopting this format as first-time greenhouse operators seek granular control over growth suppression rates.
- Granules:Slow-release matrices match turf maintenance schedules across golf course and municipal landscaping segments.
- Liquid Concentrate:Ready-to-dilute solutions serve high-volume field-crop applications where mixing efficiency outweighs precision requirements.
Emulsifiable concentrate leads volumes today; soluble powder is gaining share fastest.
Application:
Margin structure varies sharply between high-value horticulture and price-pressured broadacre agriculture.
- Ornamental Plants:Precision growth management for flowering species and container stock commands formulation premiums. European ornamental growers under REACH compliance pressure are consolidating purchases toward registered low-dose triazole suppliers with documented metabolite profiles.
- Horticulture:Protected cultivation of fruits and vegetables in India's Gujarat state is concentrating demand for growth regulators with established dose-response curves in high-humidity greenhouse environments.
- Turf Management:Granular slow-release applications dominate golf course maintenance schedules across the United States.
- Agriculture:Field-crop applications face margin compression as generic suppliers compete on price in commodity grain markets.
Ornamental plants leads volumes today; horticulture is expanding most quickly.
End User:
Technical sophistication and regulatory compliance capacity fragment procurement behavior across buyer types.
- Commercial Growers:Large-scale greenhouse operations with in-house agronomic staff purchase directly from manufacturers, unbundling technical support from product supply. Spain's Almeria cluster exemplifies this pattern, with operators maintaining proprietary dosing protocols calibrated to cultivar-specific responses.
- Farmers:Smallholder and broadacre operators rely on distributor networks for application guidance, particularly in India's emerging protected cultivation regions where first-time adopters require intensive calibration support.
- Research Institutions:Universities and breeding centers source soluble powder formats for controlled-environment studies with replicable dosing precision.
- Landscape Professionals:Municipal and commercial maintenance contractors prioritize granular formulations with predictable release characteristics for scheduled application windows.
Commercial growers lead volumes today; research institutions are climbing the fastest.
Distribution Channel:
Supply chain configuration determines service intensity and margin capture for manufacturers.
- Distributors:Specialized horticulture distributors with technical service teams dominate high-value ornamental and protected cultivation segments. UPL's extensive South Asian network exemplifies this model, capturing value through advisory retainers rather than pure product margins.
- Agricultural Cooperatives:Farmer-owned purchasing bodies aggregate volume for field-crop applications, compressing prices through collective bargaining power in commodity markets.
- Online Stores:E-commerce platforms serve research institutions and small-scale operators seeking transparent pricing on standardized formulations.
- Retail Outlets:Brick-and-mortar agricultural supply stores maintain relevance in regions with limited digital infrastructure or where immediate product availability outweighs cost considerations.
Distributors lead volumes today; agricultural cooperatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting formulation investments toward jurisdictions with streamlined plant growth regulator approval pathways, compressing time-to-market for compliant suppliers while elevating compliance costs in mature markets.
United States
Turf management and ornamental cultivation drive steady demand across Florida and California greenhouse clusters. The EPA's FIFRA-governed re-registration review for plant growth regulators shapes product compliance timelines and label expansion opportunities. Golf course maintenance contractors in Arizona and Texas metropolitan areas favor granular slow-release formats for scheduled application windows.
China
Jiangsu province anchors active ingredient synthesis through chlorination and cyclization process capacity serving export-oriented formulators. The Ministry of Agriculture and Rural Affairs enforces residue limits through GB standards that constrain export batch certification workflows. Yancheng and surrounding chemical processing zones concentrate multi-step organic synthesis infrastructure for triazole compounds.
India
Maharashtra and Gujarat states are scaling protected cultivation infrastructure for greenhouse fruits and vegetables, creating concentrated demand nodes for precise dose-response growth regulators. The Central Insecticides Board mandates registration under the Insecticides Act for all imported and domestically manufactured formulations. Pune and Ahmedabad industrial corridors are attracting distributor network investments to serve first-time greenhouse operators requiring intensive calibration support.
Netherlands
Commercial ornamental growers in Westland and Aalsmeer clusters are piloting sensor-integrated dosing systems that match growth suppression to real-time canopy development metrics. REACH authorization pathways are accelerating registration of low-dose triazole formulations for compliant suppliers. Almeria-adjacent Dutch greenhouse technology exporters are transferring precision agriculture protocols to Spanish protected cultivation operations.
Brazil
Underpenetrated protected cultivation markets in São Paulo and Minas Gerais states offer expansion vectors for established South Asian supply chains. ANVISA governs plant protection product registration through consolidated agrochemical legislation aligned with OECD standards. Campinas and Ribeirão Preto agricultural research centers are evaluating soluble powder formats for drone application systems in precision horticulture trials.
Paclobutrazol Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise concentrating among European and Chinese incumbents while distributor networks capture value in emerging markets. The supply side exhibits moderate consolidation at the active ingredient level, with Jiangsu province anchoring disproportionate synthesis capacity, and fragmentation at the formulated product tier where regional blending operations proliferate. Three archetypes dominate: integrated agrochemical majors with REACH-registered portfolios, mid-scale Asian manufacturers supplying technical grade material, and distributor-led service organizations bundling agronomic consulting with product supply. Competitive moves center on backward integration into chlorinated intermediate production and geographic expansion through horticulture-specialized distributor acquisitions.
Within the integrated major tier, BASF SE and UPL occupy positions reflecting contrasting geographic emphases—BASF SE exemplifies European formulation expertise deployed across horticulture markets, while UPL anchors distributor network density in South Asia and Latin America. Among Chinese technical-grade suppliers, Jiangsu Luye Agrochemicals and Jiangsu Sevencontinent Green Chemical represent the Jiangsu province production cluster that feeds global formulators. These three companies illustrate how regulatory compliance capacity and supply chain proximity to protected cultivation growth zones determine competitive positioning in plant growth regulator markets.
| Leading Market Players |
|---|
| Bailing Agrochemical |
| Canary Agrochemicals Pvt. Ltd. |
| India Pesticides Limited |
| Jiangsu Sevencontinent Green Chemical |
| Jiangsu Luye Agrochemicals |
| R.V. Agri Corporation |
| Yancheng Limin Chemical |
| UPL |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Backward integration into chlorinated intermediate production anchors pricing power for paclobutrazol manufacturers, as captive supply of cyclization feedstocks insulates formulators from petrochemical volatility while compressing procurement costs for REACH-registered European suppliers.
Pricing Analysis
Distributor margin layers dominate paclobutrazol value capture, with specialized horticulture distributors in South Asia and Latin America commanding advisory retainers that separate premium service bundles from commodity product transactions. Three-tier pricing structure across premium REACH-registered formulations, standard technical-grade supplies, and economy generic alternatives reflects certification burden and metabolite documentation depth. Pricing pressure stems from biopesticide substitution trajectories in organic-certified operations, compressing triazole margins among non-differentiated suppliers. Commercial growers with in-house agronomic staff exhibit lowest price sensitivity, while India's first-time greenhouse operators show highest elasticity due to intensive calibration support requirements.
Supply Chain Analysis
India's PLI scheme for agrochemical manufacturing and domestic-content preferences in government-procured agricultural inputs are reshaping sourcing patterns toward localized formulation capacity. Active ingredient synthesis concentrates in China's Jiangsu province, with technical-grade production feeding global formulators in India and Brazil. Chlorinated intermediates and cyclization catalysts constitute critical input dependencies, alongside emulsion stabilizers for concentrate formulations. Single-source vulnerability runs through Jiangsu's environmental enforcement exposure, where regional regulatory actions disrupt multi-step organic synthesis. Distribution runs through specialized horticulture distributors with technical service teams, particularly UPL's South Asian network and BASF SE's European horticulture channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paclobutrazol functions as a regulatory compounder, with the EPA's FIFRA-governed re-registration review for plant growth regulators accelerating label expansions and consolidating compliant supplier positions in turf management applications.
For Market Incumbents: Hedge against biopesticide substitution by accelerating micro-encapsulation R&D for controlled-release delivery systems that match plant-response triggers rather than calendar schedules. Deepen backward integration into chlorinated intermediate production to insulate margins from petrochemical feedstock volatility. Prioritize distributor acquisitions in Brazil's underpenetrated protected cultivation corridors to preempt South Asian supply chain expansion. For New Entrants and Emerging Players: Capture white space in soluble powder formats calibrated for drone application systems, where India's Maharashtra protected cultivation clusters and Brazil's Campinas research centers are piloting precision agriculture protocols. Target research institutions and breeding centers seeking replicable dosing precision for controlled-environment studies. Deploy agronomic consulting-led go-to-market models that unbundle technical support from product supply, mirroring UPL's advisory retainer structure. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation R&D talent scarcity constrains new product pipeline velocity among aging specialist cohorts. The five-to-ten year viability window favors acquisition of mid-scale Asian manufacturers with technical-grade production capacity and dormant REACH registration pathways. Monitor biopesticide regulatory approval trajectories as the critical inflection signal for triazole demand displacement in organic-certified segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorinated Intermediates | Captive supply of cyclization feedstocks insulates Jiangsu-based manufacturers from petrochemical volatility. |
| Micro-Encapsulation Technology Deployment | Controlled-release delivery matches Dutch sensor-integrated dosing systems for real-time canopy response. |
| Distributor Network Acquisition in Latin America | Campinas and São Paulo corridors offer underpenetrated protected cultivation expansion vectors. |
| REACH Metabolite Profiling Investment | Environmental fate studies defend existing registrations against tightening EU hazard classification thresholds. |
| Soluble Powder Format Development | Drone-calibrated dosing opens precision agriculture adoption among Maharashtra greenhouse operators. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant growth regulator formulators, horticulture distributors, greenhouse operations managers, and regulatory affairs specialists with secondary validation from EPA FIFRA filings, REACH authorization databases, Central Insecticides Board registration records, and customs trade data. Bottom-up formulation volume estimates triangulated against top-down agrichemical market sizing.
Segment-weighting approaches modeled formulation type, application vertical, and end-user sophistication across the projection horizon, with emulsifiable concentrate, soluble powder, and granular matrices each assigned distinct growth trajectories based on precision agriculture adoption curves and turf management maintenance schedules. CAGRs derived from historical volume elasticities against protected cultivation infrastructure investment data, with regulatory approval timelines and residue limit harmonization progress serving as industry-specific forecast modifiers.
EPA re-registration delays, REACH substance authorization rejections, and Jiangsu environmental enforcement actions are the dominant revision risks that could compress forecast growth. Forecasts reflect assumptions on biopesticide substitution rates and protected cultivation expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Feed Antioxidants Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
China Feed Amino Acids Market