
 Global Fans and Blowers Market | 2026-2036
Global Fans and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fans and Blowers Market Analysis
Modular fan array configurations is pivoting buyer choice away from single large units toward scalable, redundant systems. Greenheck Fan Corporation leverages its vertical integration in sheet metal fabrication to control lead times on custom housings. Systemair AB anchors its position through standardized modular platforms that reduce installation complexity across European infrastructure projects.
Fans and blowers are electromechanical devices engineered to move air or gases through ductwork, process equipment, or ambient spaces, with performance measured in cubic feet per minute and static pressure in inches of water gauge. Centrifugal blowers dominate heavy industrial applications where high-pressure airflow is required against system resistance. Axial fans capture the fastest expansion in data center cooling, while variable speed technology concentrates margin pools through energy savings and demand-responsive operation.
The U.S. Department of Energy enforces minimum efficiency standards under the Energy Policy and Conservation Act, compelling manufacturers to redesign motor-fan combinations. The EU Ecodesign Directive and F-Gas Regulation restrict refrigerant-based cooling alternatives, indirectly expanding demand for advanced air-moving equipment. China's GB standards on motor efficiency and the MIIT's green manufacturing certification create divergent compliance pathways. Stakeholders must monitor regulatory divergence between efficiency frameworks to optimize product portfolio allocation across jurisdictions.
Market Dynamics
Modular fan array architectures are compressing procurement cycles across hyperscale data centers, while efficiency mandates from the U.S. Department of Energy and the EU F-Gas Regulation force synchronous motor-fan redesigns across all major export markets.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on refrigerant-based cooling systems are redirecting capital toward advanced air-moving equipment in European industrial facilities.
- Hyperscale data center construction:Cloud infrastructure operators in Northern Virginia, Frankfurt, and Singapore are specifying redundant fan arrays for thermal management.
- Permanent magnet synchronous motors:Adoption of rare-earth magnet motor technology is cutting energy consumption in heavy industrial ventilation systems.
Market Restraints
- Copper and electrical steel volatility:Input cost swings for laminated steel cores and winding copper constrain margin predictability for motor-fan integrators.
- Rare-earth supply concentration:Dependence on Chinese processing capacity for neodymium magnets creates geopolitical exposure for high-efficiency motor production.
- Aeroacoustic performance ceilings:Blade tip speed limitations impose hard constraints on noise reduction without diameter expansion.
Strategic Opportunities
- India industrial corridor expansion:Greenfield manufacturing zones in Gujarat and Tamil Nadu are generating first-time demand for process ventilation systems.
- Retrofit aftermarket services:Aging installed bases in German automotive plants are creating demand for drop-in impeller upgrades and control system integration.
- AI-optimized predictive maintenance:Convergence of vibration sensors and machine learning algorithms is enabling service contract models that capture lifetime value.
Industry Challenges
- Computational fluid dynamics expertise:Shortage of simulation engineers capable of optimizing blade geometry for custom duty points extends development timelines.
- Multi-jurisdiction certification lag:Sequential testing for UL, CE, and GB standards delays product launches by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fans and Blowers Market |
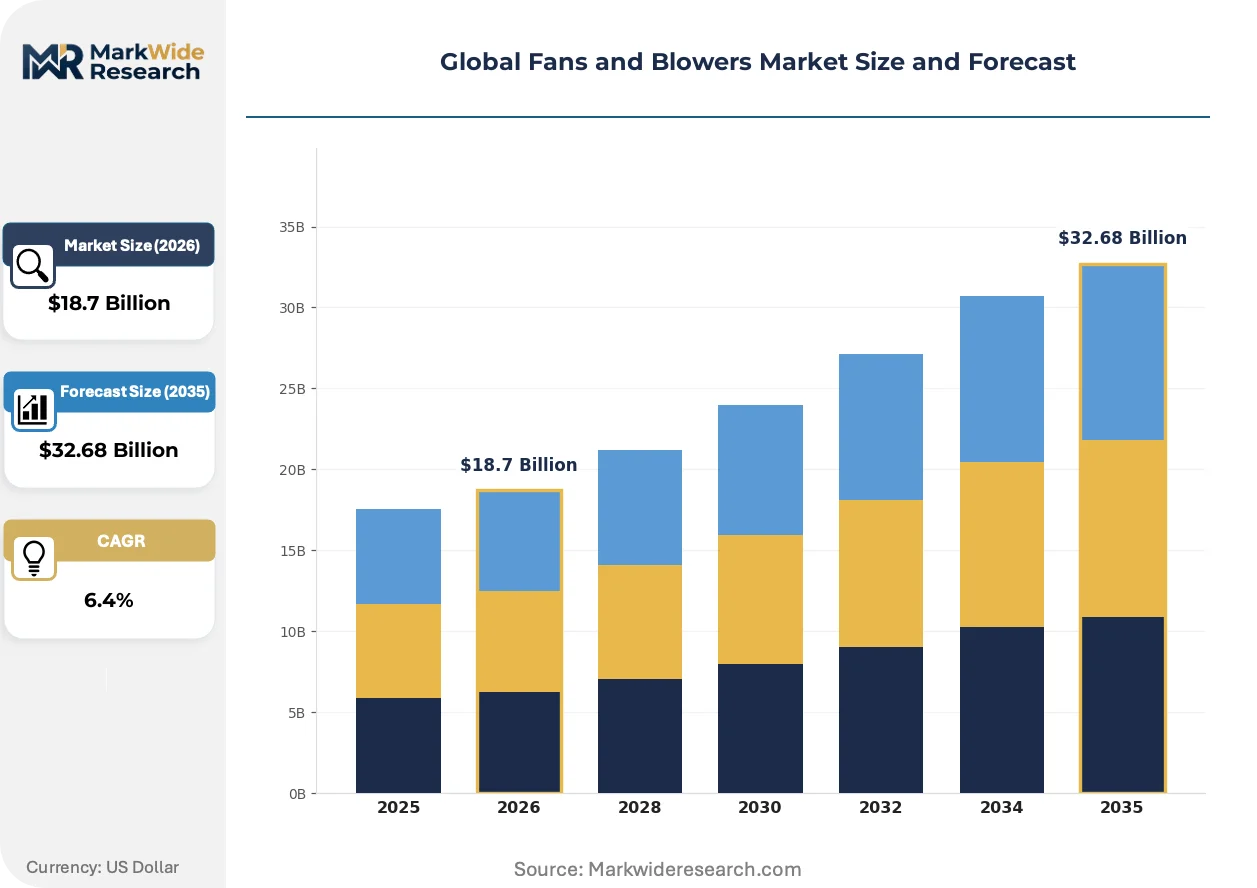
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Blowers, Mixed Flow Fans, Paddle Fans Application: HVAC Systems, Industrial Ventilation, Exhaust Systems, Process Cooling Industry Vertical: Manufacturing, Residential, Commercial, Automotive Technology: Electric, Solar-Powered, High-Efficiency, Variable Speed |
| Companies Covered | Greenheck Fan Corporation, Twin City Fan Companies Ltd., Howden Group Ltd, Systemair AB, Soler & Palau Sistemas de Ventilación S.L.U., Johnson Controls International plc, ABB Ltd., Nidec Corporation, Loren Cook Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fans and Blowers Market Emerging Trajectories
Electrification of thermal management and tightening efficiency frameworks are compressing product lifecycles. Manufacturers must synchronize hardware redesigns with control software updates while serving divergent regional certification pathways.
Direct-drive permanent magnet motors are consolidating position in mid-to-large centrifugal applications. Data center operators in Ashburn, Dublin, and Amsterdam are specifying these configurations to eliminate belt maintenance and reduce bearing failure rates. The technology is consolidating supplier tiers by bundling motor and impeller design under single-source accountability.
China's MIIT green manufacturing certification and updated GB motor efficiency standards are forcing export-oriented producers to maintain parallel product lines. Domestic manufacturers serving the local construction and steel sectors are retooling foundry and winding operations to meet the new tiers. This bifurcation is compressing margins for multinational suppliers without localized production.
Life-cycle cost contracting is displacing upfront capital purchase in Nordic district heating and North American wastewater treatment sectors. Equipment financiers and energy service companies are capturing decision authority from traditional MEP contractors. Germany and Denmark show the deepest penetration of this model, with payback guarantees tied to measured kilowatt-hour reductions.
Global Fans and Blowers Market Segmentation
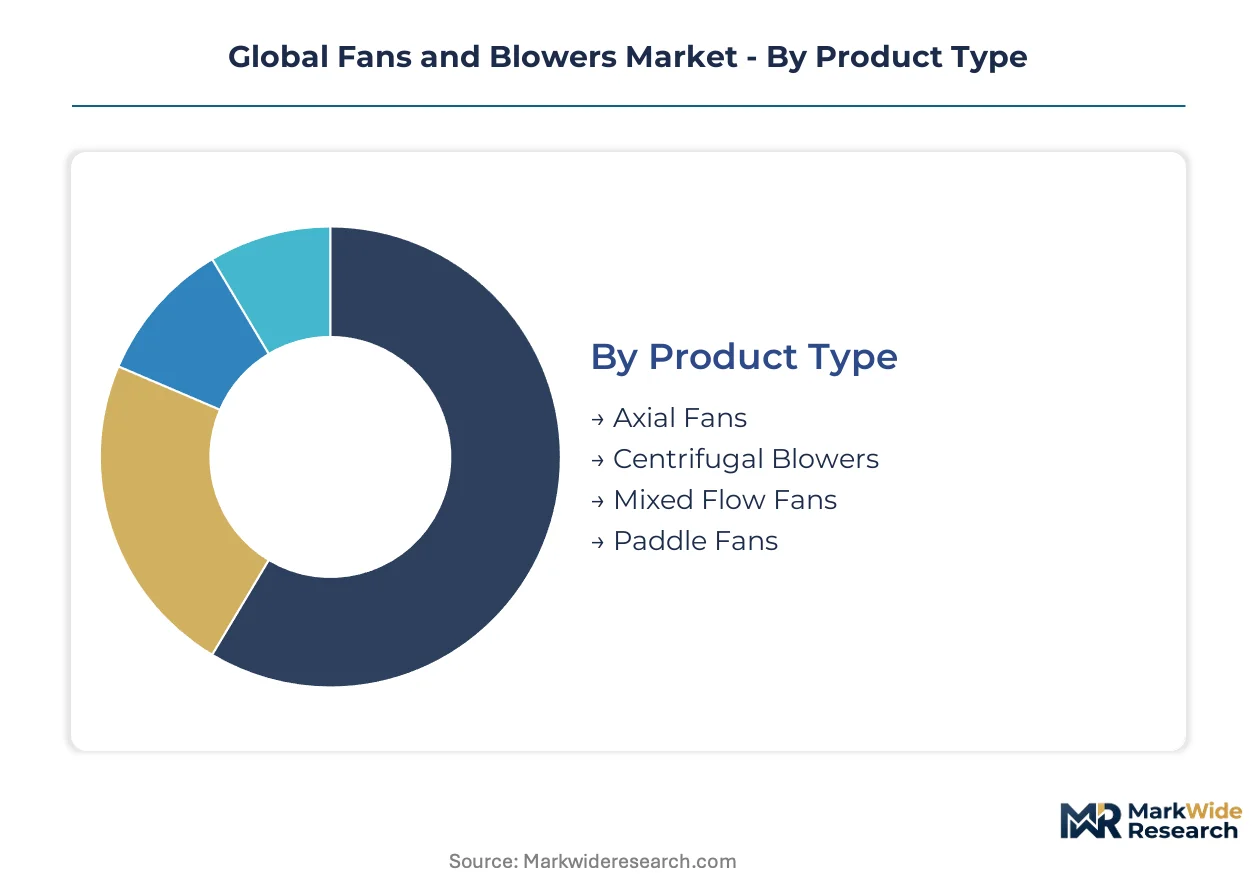
Segmentation in the fans and blowers market reveals divergent compliance burdens across product architectures. Certification requirements from the U.S. Department of Energy, EU Ecodesign Directive, and China's GB standards fragment product development roadmaps. Manufacturers must maintain parallel qualification tracks to serve regulated end-uses in data centers, automotive plants, and district heating networks.
Product Type:
UL listing for electrical safety applies universally, while AMCA certification for air performance separates commercial-grade from industrial-specified units. EU F-Gas Regulation compliance becomes mandatory for any blower deployed in refrigerant-adjacent cooling systems.
- Axial Fans:Propeller-style impellers generate high-volume, low-pressure airflow through minimal duct resistance. Hyperscale data centers in Northern Virginia and Singapore specify redundant axial arrays for aisle containment cooling, driven by cloud infrastructure expansion and thermal density limits per rack. Blade tip speed constraints from aeroacoustic limits force diameter scaling rather than RPM increases.
- Centrifugal Blowers:Radial impellers accelerate air perpendicular to the intake axis, delivering elevated static pressure against system losses. Heavy industrial ventilation in German automotive stamping plants and Chinese steel mills depends on these configurations for fume extraction and process air delivery, with efficiency mandates from the EU Ecodesign Directive and China's GB motor standards forcing synchronous redesigns.
- Mixed Flow Fans:Diagonal impeller geometry blends axial throughput with centrifugal pressure capability for medium-duty HVAC applications.
- Paddle Fans:Flat-blade designs handle high-particulate airstreams in agricultural drying and material conveying where efficiency is secondary to durability.
Centrifugal blowers sit at the top of the volume ranking, with axial fans climbing the fastest on data center deployment curves.
Application:
Cost tiering separates commodity HVAC replacements from engineered process systems. Specification authority concentrates with MEP contractors at the low end and directly with owner-operators for critical cooling.
- HVAC Systems:Commercial building climate control depends on standardized fan coils and rooftop units with quick-swap motor modules. Retrofit demand in aging U.S. office stock and European district heating networks is accelerating, though copper and electrical steel volatility constrains margin predictability for replacement contractors.
- Industrial Ventilation:Process air handling for manufacturing environments requires custom-duty point engineering and CFD-optimized blade geometry. Greenfield industrial corridors in Gujarat and Tamil Nadu are generating first-time demand for heavy-duty ventilation infrastructure, while German automotive plants drive aftermarket impeller upgrade cycles.
- Exhaust Systems:Fume and contaminant removal applications prioritize corrosion-resistant coatings and spark-resistant construction for hazardous environments.
- Process Cooling:Direct-contact and closed-loop cooling for industrial machinery demands precise temperature control and redundancy.
HVAC systems dominate installed base volume, while process cooling gains share fastest on semiconductor and battery manufacturing expansion.
Industry Vertical:
Customer type determines procurement modality. Owner-operators with in-house engineering favor life-cycle cost contracting; general contractors prioritize first-cost minimization.
- Manufacturing:Steel, cement, and chemical plants specify heavy-duty centrifugal configurations with permanent magnet synchronous motors for energy recovery. China's MIIT green manufacturing certification and updated GB motor efficiency standards are forcing export-oriented producers to maintain parallel product lines for domestic versus international deployment.
- Residential:Single-family and multi-family construction drives demand for compact, low-noise axial units with standardized housings. The U.S. Department of Energy minimum efficiency standards under the Energy Policy and Conservation Act compel motor-fan redesigns for split-system air handlers and heat pump outdoor units.
- Commercial:Office, retail, and institutional buildings specify mid-size mixed-flow and axial configurations for rooftop and built-up systems.
- Automotive:Paint booths, welding stations, and foundry ventilation require explosion-rated and high-temperature construction with rapid deployment capabilities.
Manufacturing anchors volume demand, with residential climbing fastest on heat pump electrification mandates.
Technology:
Margin concentration follows energy performance tiering. Variable speed and permanent magnet configurations command premium positioning against fixed-speed commodity alternatives.
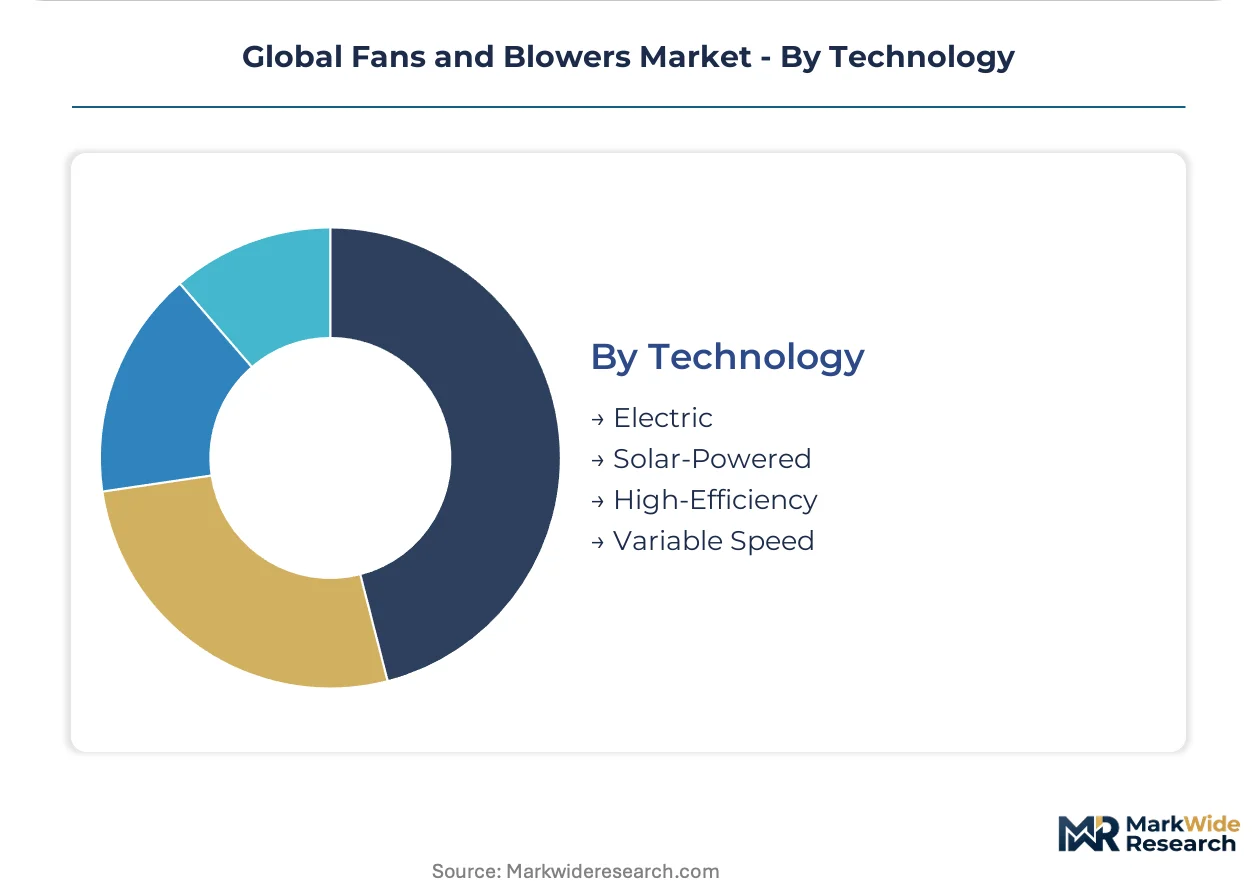
- Electric:Grid-connected AC and DC motor drives serve as the baseline technology across all voltage classes and duty ratings. The installed base spans from fractional-horsepower residential units to multi-hundred-kilowatt industrial process blowers, with efficiency regulations from the U.S. Department of Energy and EU Ecodesign Directive forcing continuous motor redesign cycles.
- Variable Speed:Inverter-driven permanent magnet and advanced induction motors enable demand-responsive airflow modulation. Data center operators in Ashburn, Dublin, and Amsterdam are specifying these configurations to eliminate belt maintenance and reduce bearing failure rates, consolidating supplier tiers under single-source motor-impeller accountability.
- High-Efficiency:Premium motor and aerodynamic designs exceed minimum regulatory tiers for utility rebate eligibility and green building certification.
- Solar-Powered:Off-grid and grid-tied photovoltaic drives serve remote agricultural and developing-world applications with limited infrastructure.
Electric technology holds dominant volume position, with variable speed configurations expanding most quickly on energy service contracting penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fans and blowers manufacturing traces its industrial-scale origins to the foundries and machine shops of 19th-century Germany and the United States, where centrifugal impeller designs first served steelmaking and mine ventilation. Today's production networks span captive fabrication facilities in high-wage economies and export-oriented assembly clusters in industrializing markets.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives specification of redundant axial fan arrays for thermal containment. The U.S. Department of Energy enforces minimum efficiency standards under the Energy Policy and Conservation Act, compelling synchronous motor-fan redesigns. Cloud infrastructure operators in Ashburn directly procure advanced air-moving equipment, bypassing traditional MEP contractors.
Germany
Automotive stamping plants in Bavaria and North Rhine-Westphalia generate aftermarket demand for impeller upgrades and control system integration. The EU Ecodesign Directive and F-Gas Regulation restrict refrigerant-based cooling alternatives, indirectly expanding specification authority for advanced ventilation. District heating networks in Hamburg and Berlin show deepest penetration of life-cycle cost contracting models.
China
Steel mills and cement plants in Hebei and Shandong provinces specify heavy-duty centrifugal configurations with permanent magnet synchronous motors. The MIIT's green manufacturing certification and updated GB motor efficiency standards force export-oriented producers to maintain parallel product lines. Domestic manufacturers serving local construction sectors retool foundry operations to meet new efficiency tiers.
India
Greenfield manufacturing zones in Gujarat and Tamil Nadu generate first-time demand for process ventilation infrastructure. The Bureau of Indian Standards and CEA efficiency mandates create compliance pathways distinct from Western regulatory frameworks. Industrial corridor expansion near Ahmedabad and Chennai concentrates procurement of heavy-duty fume extraction systems.
Netherlands
Data center operators in Amsterdam specify direct-drive permanent magnet configurations to eliminate belt maintenance and reduce bearing failure rates. The EU F-Gas Regulation redirects capital toward air-moving equipment in refrigerant-restricted cooling architectures. Randstad logistics hubs concentrate distribution of standardized modular fan platforms for European infrastructure deployment.
Global Fans and Blowers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across efficiency certification tiers and application complexity. The vendor base organizes into three distinct strata: integrated manufacturers with captive metal fabrication, modular platform specialists serving standardized infrastructure, and regional fabricators competing on lead time for custom duty points. Consolidation pressure intensifies as direct-drive permanent magnet technology bundles motor and impeller design under single-source accountability. Strategic moves concentrate on backward integration into sheet metal supply and geographic expansion through localized certification capacity.
Among integrated manufacturers with captive fabrication, Greenheck Fan Corporation and Twin City Fan Companies Ltd. occupy positions where vertical control over custom housings compresses lead times for engineered process systems. Systemair AB anchors the modular platform tier through standardized configurations that reduce installation complexity across European infrastructure projects. These three represent divergent competitive vectors: fabrication depth, platform standardization, and regional certification density.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| Twin City Fan Companies Ltd. |
| Howden Group Ltd |
| Systemair AB |
| Soler & Palau Sistemas de Ventilación S.L.U. |
| Johnson Controls International plc |
| ABB Ltd. |
| Nidec Corporation |
| Loren Cook Company |
| Others |
Supply Flow & Price Mechanics
CFD simulation engineers concentrated in Southern Germany and Detroit command wage premiums that compress margins on custom-engineered centrifugal blowers, widening spreads between premium CFD-optimized tiers and standard catalog offerings.
Pricing Analysis
Life-cycle cost contracting dominates capital equipment procurement across Nordic district heating and North American wastewater treatment sectors. Price differentiation rests on AMCA certification grade and permanent magnet motor efficiency tier, with utility rebate eligibility separating premium from standard positioning. Cost compression in economy-grade HVAC replacements intensifies as copper and electrical steel volatility constrains contractor margins. Data center operators show lowest price sensitivity, prioritizing bearing failure reduction over first-cost minimization.
Supply Chain Analysis
China's MIIT green manufacturing certification and updated GB motor efficiency standards are forcing export-oriented producers to localize winding and foundry operations. Manufacturing gravity centers on China, Germany, and the United States for impeller casting and motor assembly. Laminated electrical steel cores and rare-earth neodymium magnets feed from concentrated Chinese processing capacity. Single-source vulnerability in magnet supply creates geopolitical exposure. Distribution runs through Randstad logistics hubs for European infrastructure deployment and direct procurement by hyperscale cloud operators in Northern Virginia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation compounds demand for advanced air-moving equipment by restricting refrigerant-based cooling alternatives, redirecting capital toward ventilation infrastructure across European industrial facilities.
For Market Incumbents:Cement fabrication depth through backward integration into sheet metal supply and captive custom housing production. Control lead times on engineered process systems to defend against modular platform specialists. Invest in parallel certification capacity for UL, CE, and GB standards to compress product launch cycles threatened by sequential testing delays.
For New Entrants and Emerging Players:E-commerce aftermarket channels offer lowest-friction entry into replacement impeller and control system upgrades for aging German automotive plants. Target retrofit services in Bavarian stamping facilities where owner-operators seek drop-in efficiency improvements. Penetrate through AI-optimized predictive maintenance service contracts that capture lifetime value from vibration sensor deployments.
For Investors and Strategic Acquirers:Energy service companies and equipment financiers are the most active acquirers in this space, capturing decision authority from traditional MEP contractors through performance-guaranteed contracting models. Five-to-ten year viability favors suppliers with localized certification density across efficiency jurisdictions. Monitor permanent magnet motor adoption curves as inflection indicator for supplier tier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sheet Metal Supply | Greenheck Fan Corporation compresses lead times on custom housings through captive fabrication. |
| Modular Platform Standardization | Systemair AB reduces installation complexity across European infrastructure projects. |
| Direct-Drive Permanent Magnet Motor Adoption | Data center operators in Amsterdam eliminate belt maintenance and reduce bearing failure rates. |
| Parallel Certification Capacity Investment | Multinational suppliers avoid six-to-nine month launch delays from sequential UL, CE, and GB testing. |
| AI-Optimized Predictive Maintenance Launch | Vibration sensor and machine learning convergence enables service contract models capturing lifetime value. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from plant engineers at German automotive stamping facilities, procurement teams at hyperscale data center operators in Northern Virginia and Amsterdam, aftermarket service heads at Nordic district heating utilities, and OEM motor-fan integrators. Secondary validation drew from U.S. Department of Energy efficiency standard filings, EU Ecodesign Directive compliance databases, China's MIIT green manufacturing certification registries, and AMCA air performance test data. Bottom-up segment sizing and top-down macro constraint checks were triangulated to anchor projections.
Segment-weighting approaches distributed value and volume across product type, application, industry vertical, and technology dimensions. Centrifugal blower, axial fan, mixed flow, and paddle configurations were modeled against HVAC, industrial ventilation, exhaust, and process cooling end-uses. Permanent magnet synchronous motor adoption curves and variable speed drive penetration rates fed energy performance tier projections. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion patterns across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for direct-drive permanent magnet motor consolidation would alter the outlook. Forecasts reflect assumptions about rare-earth magnet supply stability and efficiency mandate enforcement continuity. Copper price volatility and multi-jurisdiction certification lag present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
North America Rental Chillers Market