
 Industrial Marking Equipment Market | 2026-2036
Industrial Marking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Marking Equipment Market Foresight
REACH compliance is broadening the cost-of-entry calculus for equipment vendors serving European automotive and pharmaceutical clients. Trumpf leverages its vertical integration in fiber laser sources to sustain pricing power across industrial marking lines. Videojet Technologies Inc. anchors its position through extensive channel control in continuous inkjet installations. Gravotech specializes in rotary and laser engraving systems for compliance-heavy aerospace applications.
Industrial marking equipment encompasses systems that permanently or semi-permanently apply alphanumeric codes, barcodes, logos, or machine-readable identifiers onto metal, plastic, glass, or composite substrates using laser ablation, inkjet deposition, mechanical indentation, or thermal transfer processes. These systems operate at marking speeds ranging from hundreds to thousands of units per minute, with laser systems achieving permanent marks at depths of 0.01 mm to 0.5 mm depending on substrate and power settings. Laser marking dominates premium installations where permanence and zero-consumable operation justify higher capital outlay, while continuous inkjet retains volume leadership in food, beverage, and pharmaceutical packaging lines where speed and substrate flexibility outweigh durability requirements. Dot peen marking occupies a stable niche in heavy metal fabrication and aerospace part identification, where deep mechanical marks survive extreme thermal and abrasive environments.
The EPA enforces emissions and hazardous substance rules that affect ink formulation and solvent recovery in marking operations across US manufacturing facilities. EMA and CE marking requirements under the EU Machinery Directive shape product safety standards and market access protocols for equipment sold into European pharmaceutical and medical device supply chains. China's SAMR and GB standards govern laser safety classifications and electromagnetic compatibility for domestically produced and imported marking systems. Stakeholders must monitor evolving traceability mandates from FDA and EMA as serialization requirements expand beyond pharmaceuticals into medical devices and select food categories.
Market Dynamics
Traceability mandates from automotive OEMs and pharmaceutical regulators are compressing installation timelines for laser and inkjet marking systems across tier-1 supplier facilities. Equipment vendors face simultaneous pressure to deliver zero-defect serialization at line speeds exceeding 1,000 units per minute while absorbing compliance documentation burdens that previously sat with end-users.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon-based cooling in industrial lasers is accelerating fiber laser adoption in German and French automotive stamping plants.
- Pharmaceutical serialization:FDA DSCSA enforcement and EMA Falsified Medicines Directive extensions are mandating unit-level traceability across US and European packaging lines.
- Electric vehicle battery marking:Cell-to-pack architectures require permanent DMC codes on aluminum housings and copper busbars for warranty tracking and recycling compliance.
Market Restraints
- Rare earth magnet dependency:Chinese export licensing for neodymium and dysprosium concentrates supply risk for galvo motor assemblies in high-speed laser markers.
- Capital intensity threshold:UV laser systems for medical device polymer marking require 40-60% higher upfront investment than CO2 alternatives, freezing mid-tier contract manufacturers.
- REACH substance restrictions:ECHA candidate list expansions for solvent-based inks are forcing reformulation cycles that extend qualification timelines by 8-14 months.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing and medical devices are pulling marking equipment investment into Gujarat and Tamil Nadu industrial corridors.
- AI-integrated vision verification:Convergence of deep learning-based OCR and inline laser marking is opening premium pricing for closed-loop quality systems in aerospace forging.
- Remanufacturing traceability:EU Circular Economy Action Plan requirements for component-level lifecycle tracking are creating installed-base upgrade demand in German machine tool rebuild shops.
Industry Challenges
- Laser safety officer scarcity:IEC 60825-1 compliance certification for Class 4 fiber laser installations faces 6-9 month personnel training backlogs in US and European facilities.
- Legacy MES integration:Proprietary communication protocols from 1990s-era manufacturing execution systems are forcing custom middleware development for serialization data handoff.
- Multi-site standardization:Global automotive Tier-1 suppliers struggle to harmonize marking formats across mixed-vendor fleets accumulated through regional plant acquisitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Marking Equipment Market |
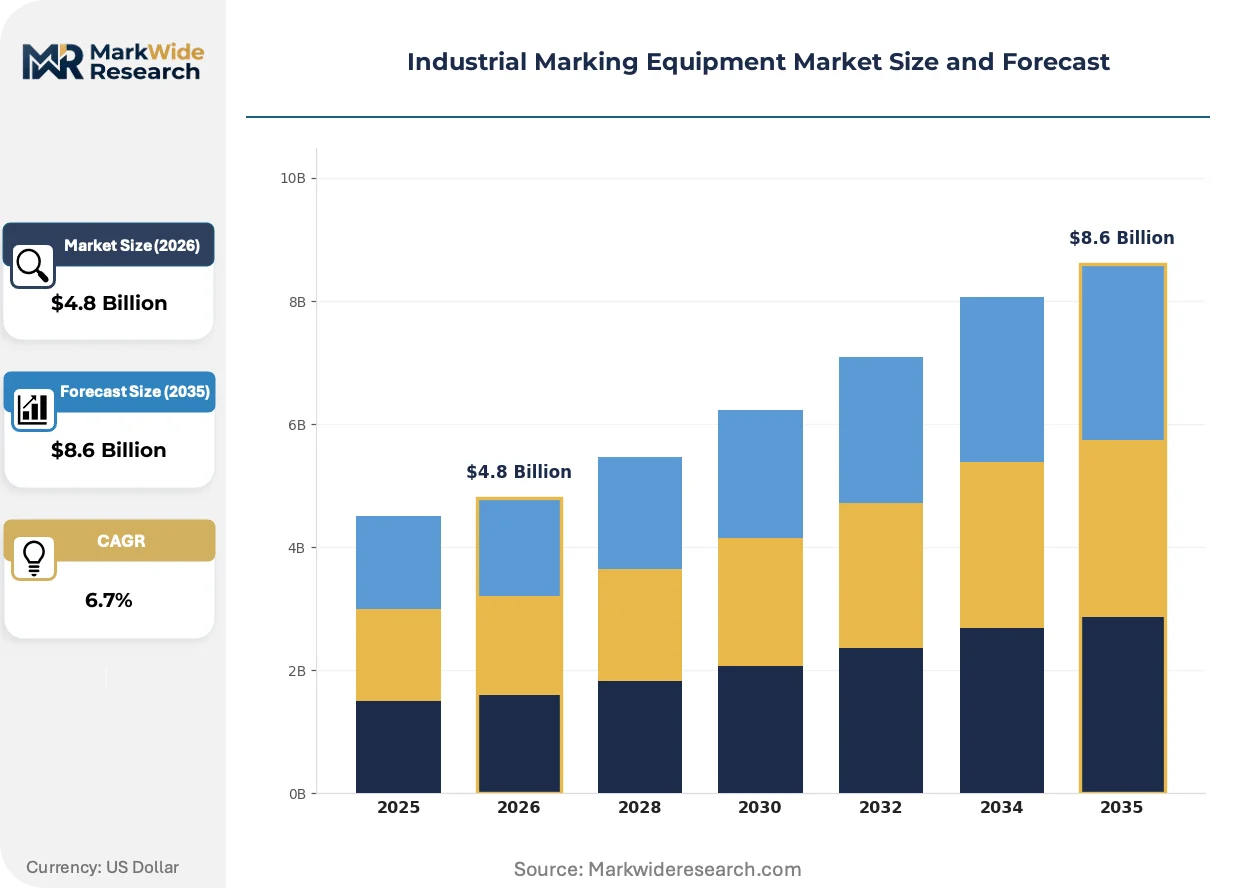
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Marking, Dot Peen Marking, Inkjet Marking, Thermal Transfer Technology: Continuous Inkjet, High-Resolution Inkjet, Laser, Micro-Percussive End User: Automotive Manufacturers, Electronics Producers, Aerospace Developers, Pharmaceutical Firms Delivery Mode: On-premises, Cloud-based, Hybrid, Mobile |
| Companies Covered | Trotec Laser GmbH, Trumpf, Videojet Technologies Inc., Gravotech, Keyence, Markem-Imaje, Han's Laser, Hitachi Industrial Equipment & Solutions Ltd., Domino Printing Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Marking Equipment Market Shifts & Advancements
Ultrafast picosecond and femtosecond laser sources are rewriting the thermal damage threshold for heat-sensitive substrates. Equipment architecture is consolidating around modular platforms that swap marking heads without line revalidation.
Picosecond IR lasers are overtaking nanosecond fiber sources in medical device polymer marking where heat-affected zone control determines FDA biocompatibility clearance. Boston Scientific and Medtronic procurement teams are specifying sub-10 picosecond pulse widths for PEEK and PPSU implant housings. This specification compression is freezing out vendors lacking in-house ultrafast source development.
EU Machinery Directive 2006/42/EC amendments effective 2027 will mandate embedded cybersecurity for networked marking systems. Equipment OEMs must redesign controller architectures to satisfy CE marking under the expanded Essential Health and Safety Requirements. German packaging machinery builders are front-loading certification costs to avoid 2026-2027 installation bottlenecks.
Automotive battery manufacturers are unbundling after-sales service contracts from initial equipment purchases. CATL and BYD procurement teams now separate spare parts, field service, and software maintenance into competitive rebid cycles every 36 months. This unbundling is most advanced in Chinese and Hungarian gigafactory deployments where equipment utilization rates exceed 85%.
Industrial Marking Equipment Market Segmentation
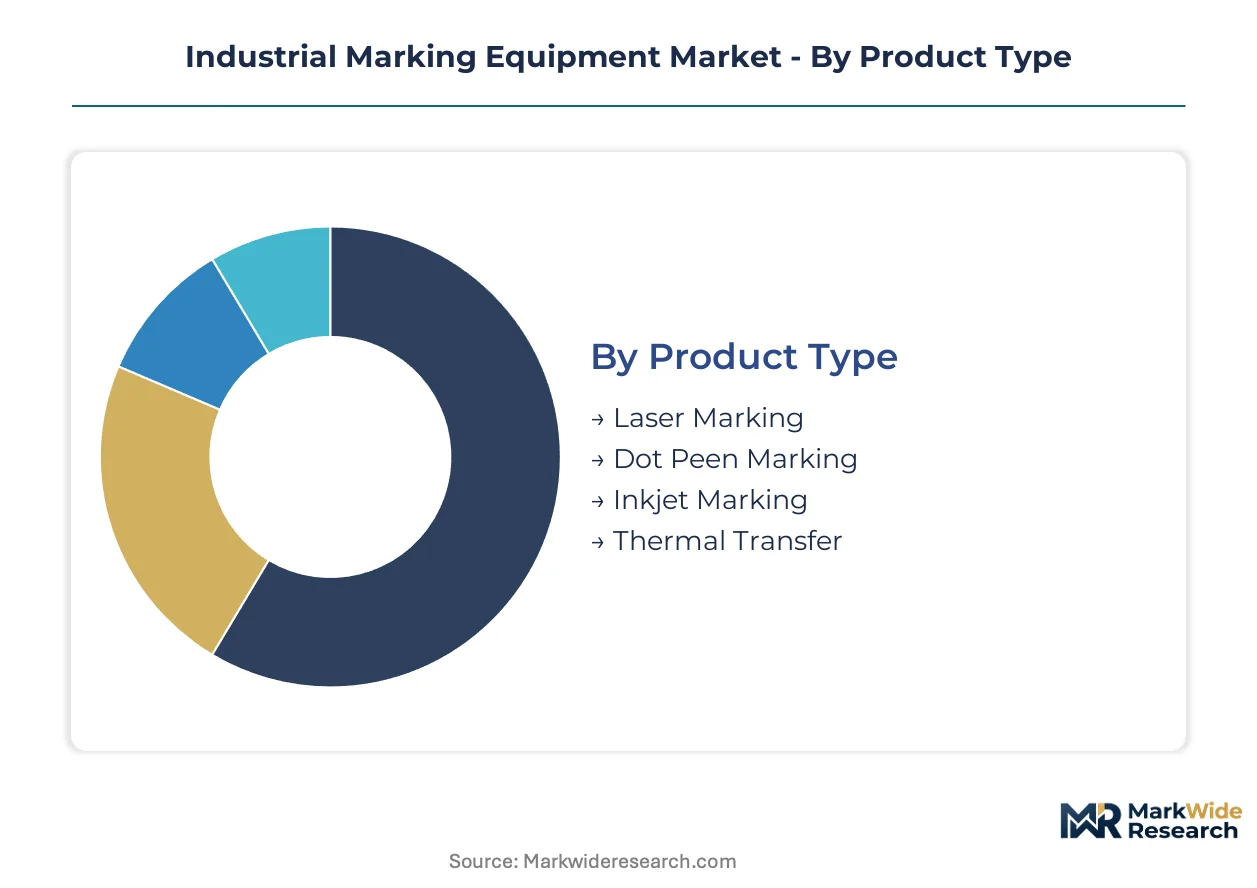
Marking equipment selection hinges on substrate permanence requirements, line speed thresholds, and total cost of ownership across consumables and maintenance. Segmentation reveals where capital-intensive laser systems displace mechanical or ink-based alternatives, and which compliance environments favor specific technology investments.
Product Type:
Laser systems command premium positioning through zero-consumable operation, while inkjet and mechanical alternatives dominate high-volume, cost-sensitive installations.
- Laser Marking:Fiber, CO2, and UV laser sources ablate or anneal substrates without contact, achieving permanent marks at depths from 0.01 mm to 0.5 mm. German automotive stamping plants and Chinese battery gigafactories are specifying fiber lasers to satisfy EU F-Gas phasedown mandates and cell-level traceability requirements.
- Dot Peen Marking:Carbide-tipped pins mechanically indent alphanumeric codes into metal surfaces through controlled percussion. Aerospace forging suppliers in France and the United States deploy these systems where deep mechanical marks must survive thermal cycling and abrasive cleaning protocols.
- Inkjet Marking:Solvent-based and UV-curable inks deposit codes through piezoelectric or thermal drop-on-demand heads.
- Thermal Transfer:Ribbon-based wax-resin systems transfer ink through heated printheads onto flexible packaging substrates.
Today's leader: Laser Marking. Tomorrow's challenger: Dot Peen Marking.
Technology:
Resolution specifications and substrate compatibility determine technology selection across pharmaceutical serialization and electronics micro-marking applications.
- Continuous Inkjet:Pressurized ink streams break into charged droplets steered by electrostatic deflection plates, enabling marking at line speeds exceeding 1,000 units per minute. Food and beverage packagers in the United States favor these systems for substrate flexibility on curved glass and metal cans.
- High-Resolution Inkjet:Piezoelectric printheads deposit smaller droplet volumes for barcode readability at 600 dpi equivalent. Medical device contract manufacturers in Ireland and Switzerland specify these systems for FDA-compliant label-grade coding on polymer trays.
- Laser:Solid-state and gas laser sources deliver permanent, non-contact marking across metals, ceramics, and select organics.
- Micro-Percussive:Electromagnetically actuated pins create shallow indentations for light-gauge metal and plastic identification.
Continuous Inkjet retains volume leadership. High-Resolution Inkjet gains share fastest in medical device and pharmaceutical packaging.
End User:
Compliance intensity varies sharply across end-use verticals, with pharmaceutical and aerospace procurement teams imposing the most stringent validation documentation requirements.
- Automotive Manufacturers:OEMs and tier-1 suppliers mark powertrain components, electronics housings, and battery cells for warranty tracking and recall management. German and Chinese producers are expanding DMC code requirements to copper busbars and aluminum cell housings under emerging recycling mandates.
- Electronics Producers:PCB fabricators and semiconductor packagers apply 2D codes for component traceability through SMT assembly and final test. South Korean and Taiwanese manufacturers are driving demand for ultrafast laser sources that mark silicon and ceramic substrates without thermal damage.
- Aerospace Developers:Airframe and engine manufacturers specify deep mechanical or laser marks that survive extreme operating environments.
- Pharmaceutical Firms:Serialization mandates from FDA and EMA require unit-level traceability across blister packs, bottles, and cartons.
Automotive Manufacturers anchor current demand. Pharmaceutical Firms present the steepest compliance-driven expansion trajectory.
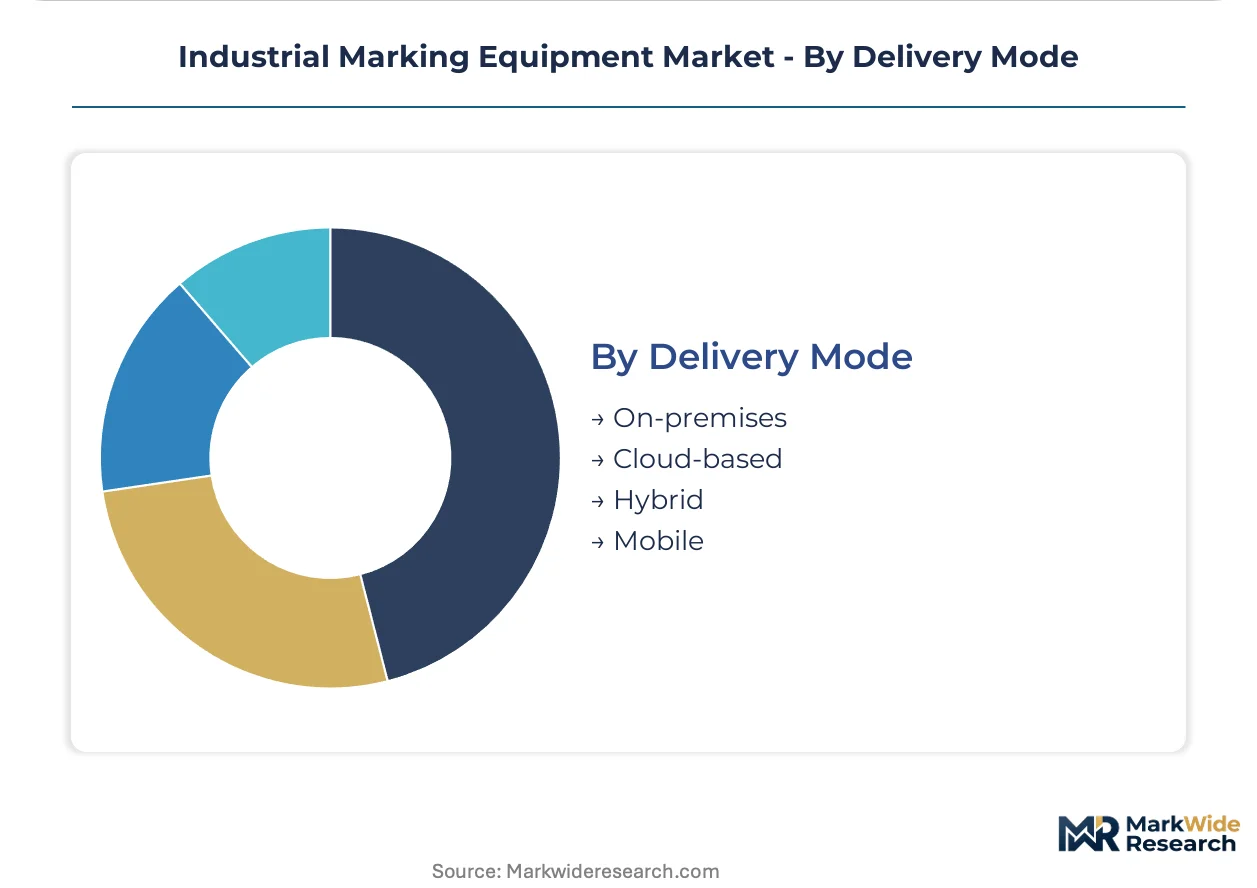
Delivery Mode:
Architecture choices reflect IT infrastructure maturity, cybersecurity posture, and multi-site standardization requirements across global manufacturing footprints.
- On-premises:Local controller hardware and proprietary software installations dominate high-security environments with air-gapped production networks. Defense contractors in the United States and nuclear component suppliers in France mandate these configurations to satisfy ITAR and RCC-E security protocols.
- Cloud-based:Browser-accessible marking management platforms enable remote job programming and fleet monitoring. Contract packaging organizations in India and Brazil are adopting these systems to coordinate multi-client serialization across distributed facilities.
- Hybrid:Edge controllers with intermittent cloud synchronization balance local latency requirements with centralized data aggregation.
- Mobile:Battery-powered handheld units serve field service, construction equipment, and remote asset marking applications.
On-premises retains share in regulated industries. Cloud-based architectures are expanding most quickly among multi-site contract manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial marking equipment industry traces its modern scale to German machine tool builders and Japanese electronics manufacturers who pioneered automated traceability systems in the 1980s. These foundations established technical standards that persist across automotive and aerospace supply chains. Today, demand concentrates in manufacturing corridors where regulatory compliance and export-oriented production intersect.
United States
FDA DSCSA enforcement and EPA emissions rules drive pharmaceutical and packaging line investments. The agency mandates unit-level serialization for drug distribution security. Chicago-area contract packagers and Boston medical device clusters are expanding laser marking capacity to meet 2025 compliance deadlines.
Germany
Automotive OEM traceability mandates and machinery safety directives shape procurement specifications. The EU F-Gas Regulation accelerates fiber laser adoption in Stuttgart and Munich stamping plants. Bavarian battery equipment builders are integrating marking systems for cell-to-pack architectures serving CATL and Northvolt supply chains.
China
Electric vehicle battery marking and electronics traceability dominate domestic demand. SAMR laser safety classifications and GB standards govern domestic production and import protocols. Shenzhen and Suzhou industrial corridors host the densest concentration of fiber laser installations for consumer electronics and automotive component marking.
Japan
Semiconductor packaging and precision electronics sustain high-resolution marking requirements. METI industrial standards and PMDA pharmaceutical regulations enforce serialization protocols. Kyushu and Nagoya manufacturing belts are specifying ultrafast laser sources for silicon wafer and ceramic substrate marking without thermal damage.
India
Electronics manufacturing incentives and medical device production subsidies attract marking equipment investment. The PLI scheme for smartphones and pharmaceuticals pulls capacity into Gujarat and Tamil Nadu corridors. CDSCO serialization requirements for exported pharmaceuticals are accelerating continuous inkjet and laser system installations in Mumbai-Pune industrial zones.
Industrial Marking Equipment Market Competitive Landscape
The competitive structure tilts toward technology-integrated specialists with captive source development. German and Japanese players anchor premium positioning through in-house laser source production, while US and European inkjet specialists maintain volume leadership via extensive channel control. Three archetypes dominate: vertically integrated laser source developers, consumables-dependent inkjet platform operators, and compliance-focused engraving specialists. Consolidation pressure is mounting through strategic technology licensing and regional distribution partnerships.
Among German-integrated specialists, Trumpf GmbH + Co. KG exemplifies the laser source developer archetype through its captive fiber laser production. Videojet Technologies Inc. occupies a position within the consumables-driven inkjet tier, reflecting US-based platform scale. Gravotech S.A. represents the compliance-specialist vector with its French-rooted engraving systems focus. These three anchors illustrate how geographic origin and structural positioning shape competitive differentiation across permanent versus semi-permanent marking technologies.
| Leading Market Players |
|---|
| Trotec Laser GmbH |
| Trumpf |
| Videojet Technologies Inc. |
| Gravotech |
| Keyence |
| Markem-Imaje |
| Han's Laser |
| Hitachi Industrial Equipment & Solutions Ltd. |
| Domino Printing Sciences |
| Others |
Supply & Pricing Matrix
Pharmaceutical serialization mandates from FDA and EMA are compressing procurement timelines for zero-defect marking systems, forcing equipment vendors to absorb qualification documentation costs that previously sat with end-users and compressing margin structures across premium laser installations.
Pricing Analysis
The bundled-vs-unbundled service split now dominates contract structures, with automotive battery manufacturers separating spare parts, field service, and software maintenance into competitive rebid cycles every 36 months. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-validated laser systems commanding 40-60% premiums over non-validated alternatives. Price differentiation hinges on ISO 13485 medical device certification and geographic delivery cost differentials. Pricing pressure stems from Chinese equipment makers entering mid-tier fiber laser segments. Contract packaging organizations in India and Brazil exhibit highest price sensitivity; aerospace forging suppliers in France and the United States show lowest.
Supply Chain Analysis
India's PLI scheme local-content rules and China's SAMR domestic certification requirements are reshaping sourcing patterns for galvo motor assemblies and fiber laser sources. Supply concentration centers on China, Germany, and Japan for high-speed laser marking systems. Raw material dependencies include neodymium and dysprosium rare earth concentrates for precision motors, fiber laser gain modules, and UV-curable ink formulations. Single-source vulnerability runs through Chinese export licensing for rare earth magnet supply. Distribution runs through authorized regional service partners with captive spare parts inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU F-Gas Regulation compliance costs in German automotive stamping plants run 25-35% above equivalent Chinese battery gigafactory installations, creating margin expansion opportunities for vendors with dual certification pathways.
For Market Incumbents: Anticipate margin compression from Chinese fiber laser entrants by deepening backward integration into ultrafast picosecond source development and front-loading EU Machinery Directive 2027 cybersecurity certification costs to avoid installation bottlenecks. Prioritize channel control in pharmaceutical serialization to defend against consumables-independent laser displacement. For New Entrants and Emerging Players: Enter via AI-integrated vision verification systems for aerospace forging applications, where deep learning-based OCR convergence with inline marking commands premium pricing. Target India's PLI-funded electronics manufacturing corridors in Gujarat and Tamil Nadu. Pursue remanufacturing traceability upgrades in German machine tool rebuild shops as the most penetrable white-space segment. For Investors and Strategic Acquirers: Asymmetric upside sits with compliance-focused engraving specialists possessing captive aerospace certification relationships and modular platform architectures that swap marking heads without line revalidation. Long-term viability favors vendors with in-house ultrafast laser source development over consumables-dependent inkjet operators. Monitor Chinese rare earth export licensing decisions as the critical inflection signal for galvo motor supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ultrafast Laser Sources | Captive picosecond development locks out competitors from FDA biocompatibility-sensitive medical device marking. |
| EU Machinery Directive Cybersecurity Certification | Front-loaded CE marking investment avoids 2026-2027 installation bottlenecks in German packaging machinery. |
| Regional Service Partner Network Expansion | Authorized spare parts inventory in India and Brazil reduces pharmaceutical contract packager downtime exposure. |
| AI-Vision Verification Platform Integration | Deep learning OCR convergence commands premium pricing in aerospace forging closed-loop quality systems. |
| Remanufacturing Traceability Upgrade Programs | EU Circular Economy Action Plan compliance creates installed-base demand in German machine tool rebuild shops. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each combining interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory affairs leads at pharmaceutical and automotive manufacturers with secondary validation through FDA DSCSA guidance documents, EMA Falsified Medicines Directive extensions, SAMR GB standards filings, and SEC 10-K equipment vendor disclosures. Bottom-up and top-down triangulation cross-validates installation unit counts against capital expenditure disclosures.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include product type, technology, end user, and delivery mode, with industry-specific layering of regulatory compliance tier and certification status. CAGRs derive from weighted average of historical trajectory and policy-driven inflection assumptions. Forecast inputs incorporate EU F-Gas Regulation phasedown timelines and pharmaceutical serialization enforcement deadlines.
The model holds under stable trade policy conditions; deviation in Chinese rare earth export licensing or EU Machinery Directive implementation timing would shift equipment vendor margin assumptions. Forecasts reflect documented base-case assumptions regarding regulatory enforcement intensity and technology substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
Europe Vacuum Pump Market