
 Ultrasonic Cleaning Equipment Market | 2026-2036
Ultrasonic Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Cleaning Equipment Market Intelligence
The ISO 13485 quality management standard for medical devices is reorganizing the competitive field for ultrasonic cleaning equipment. This requirement for validated cleaning processes favors established suppliers with extensive documentation. Emerson Electric Co. leverages its broad industrial automation portfolio to serve multinational clients. Elma Schmidbauer GmbH specializes in high-precision units for European medical and laboratory sectors, while Crest Ultrasonics competes with large-scale industrial systems.
Ultrasonic cleaning equipment employs high-frequency sound waves, typically between 20 and 40 kHz, to generate cavitation in a liquid medium. This process dislodges contaminants from complex surfaces without abrasion, making it essential for precision cleaning. Industrial units represent a significant portion of the market, driven by demand from automotive components manufacturing. Conversely, benchtop cleaners designed for electronics assembly and laboratory instruments command higher price points due to stringent performance and control specifications.
Regulatory frameworks, including the US FDA's device guidelines and Europe's CE marking under the Medical Device Regulation (MDR), dictate equipment validation protocols. In China, GB standards for industrial machinery influence safety and performance requirements, shaping market access for manufacturers. Equipment vendors must now focus on developing systems compatible with emerging biocompatible materials and environmentally friendly aqueous cleaning agents.
Market Dynamics
The convergence of stringent regulatory mandates, particularly ISO 13485 for medical devices, and the technical demands of electronics miniaturization represents the central force shaping the ultrasonic cleaning equipment market. This dual pressure compels vendors to deliver validated, high-precision systems capable of meeting microscopic cleanliness standards.
Growth Catalysts
- Electronics Miniaturization:The continuous reduction in the size of semiconductor components and printed circuit boards, especially within East Asian fabrication facilities, requires advanced non-contact cleaning to prevent damage to delicate structures.
- Medical Device Sterilization:Strict protocols from regulators like the US FDA and adherence to CE marking under Europe's MDR necessitate validated cleaning processes, making ultrasonic systems essential for manufacturers of complex surgical instruments and implants.
- Precision Manufacturing:Germany's automotive and industrial manufacturing sectors rely on ultrasonic cleaning to remove contaminants from intricate parts like fuel injectors and hydraulic components without causing surface abrasion, ensuring performance and longevity.
Market Restraints
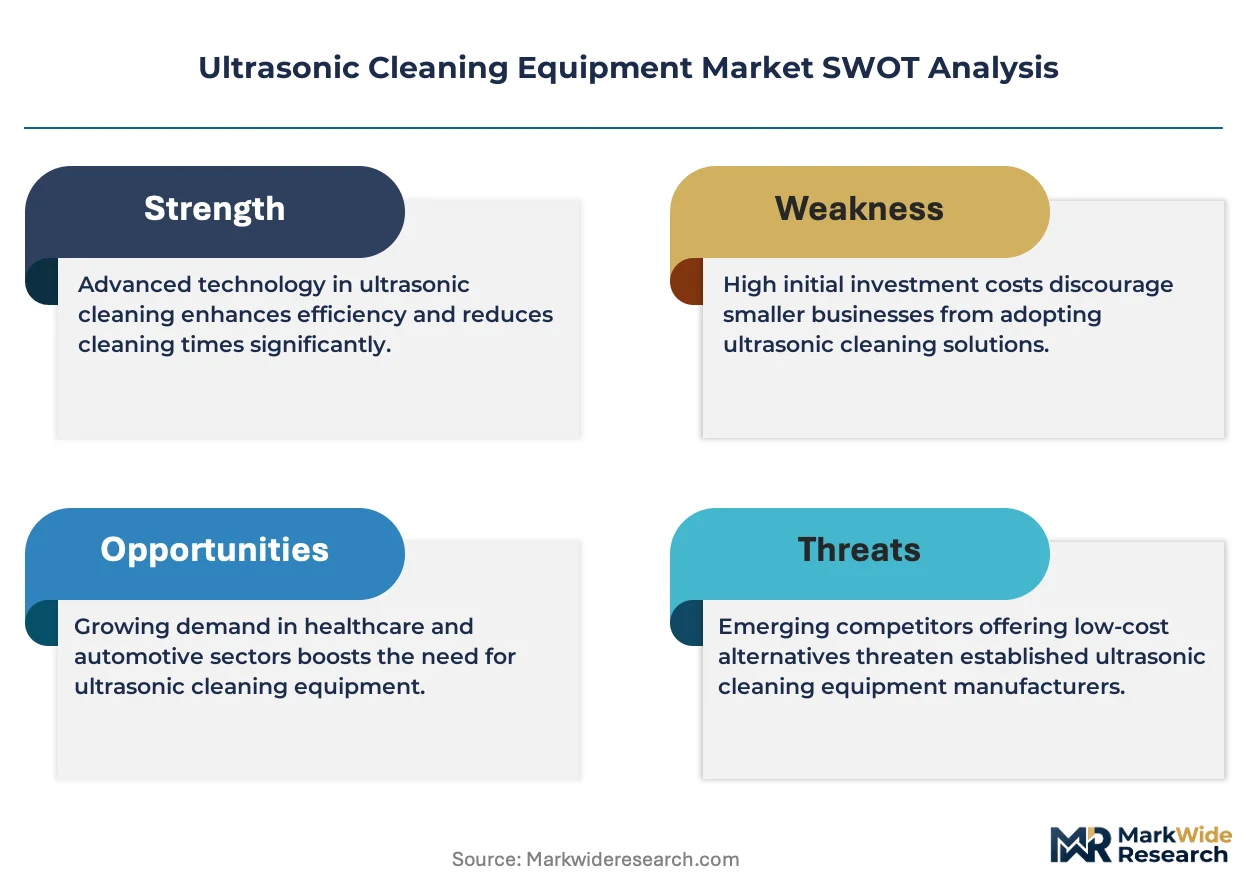
- High Capital Cost:The significant initial investment required for large-scale, industrial-grade ultrasonic cleaning systems acts as a barrier for small and medium-sized enterprises in the manufacturing and automotive repair sectors.
- Material Compatibility Issues:Certain sensitive materials, including soft polymers and specific metal alloys, can be susceptible to surface pitting or damage from the intense cavitation forces, limiting applications.
- Alternative Technology Emergence:For specific high-value applications, such as cleaning optics or sensitive electronics, alternative methods like plasma cleaning, supercritical CO2, and laser ablation present a substitution threat.
Strategic Opportunities
- EV Battery Components:The manufacturing of electric vehicle batteries and their associated power electronics creates a new application for precision cleaning of electrodes, busbars, and housing components to ensure safety and performance.
- Process Automation and AI:Integrating machine learning algorithms for real-time monitoring and automatic adjustment of frequency, power, and temperature can create smart, self-validating systems for the pharmaceutical and aerospace industries.
- Biocompatible Material Cleaning:Developing specialized ultrasonic systems and processes optimized for cleaning new biocompatible materials and 3D-printed medical implants offers a significant growth avenue.
Industry Challenges
- Complex Validation Cycles:Equipment vendors and end-users in the medical device sector face long and expensive validation and documentation cycles to comply with FDA and MDR requirements for cleaning processes.
- Transducer Supply Chain:The supply of high-performance piezoelectric transducers, a critical component, is concentrated among a limited number of specialized manufacturers, creating potential bottlenecks and price volatility.
- Aqueous Chemistry Optimization:Formulating and qualifying effective, environmentally friendly aqueous cleaning agents that work synergistically with ultrasonic energy for specific contaminants and substrates remains a complex technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Cleaning Equipment Market |
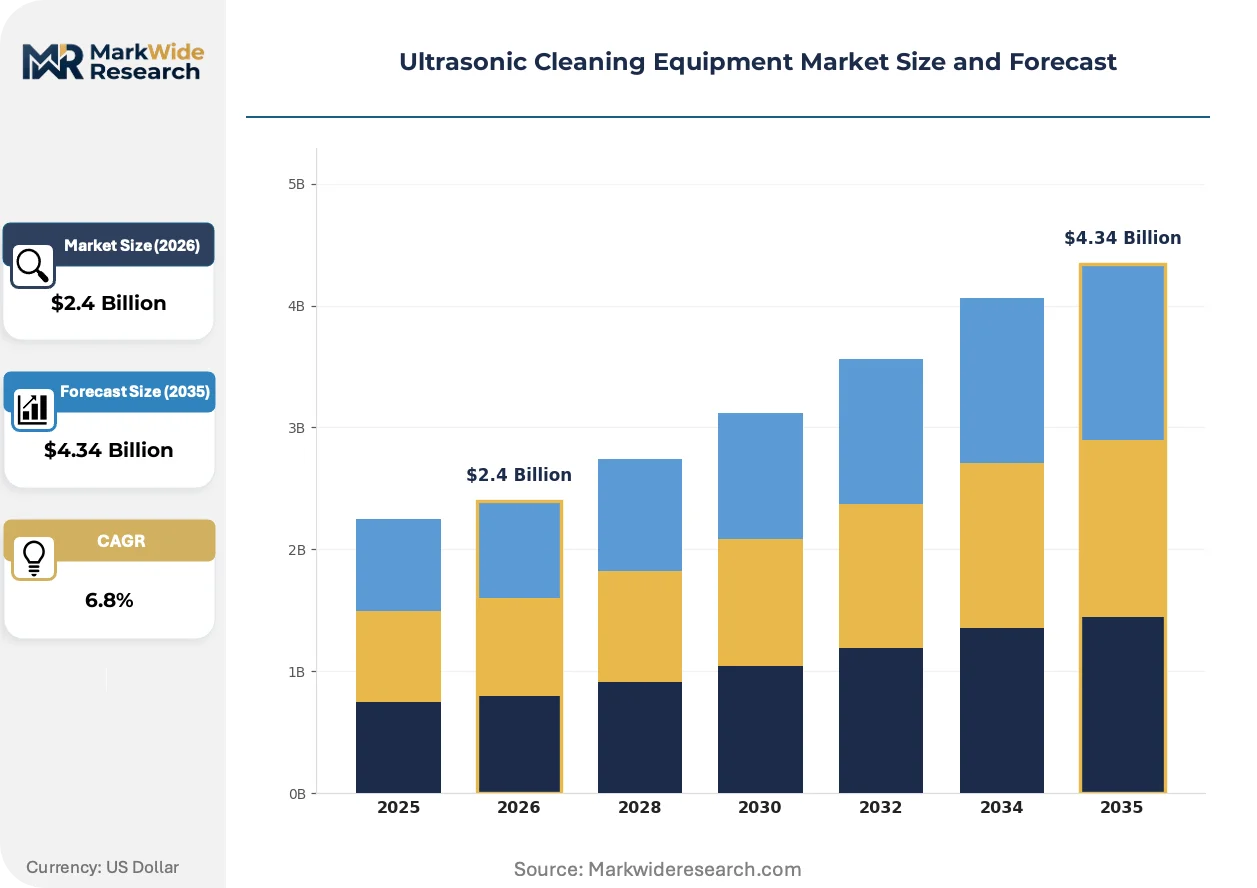
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Cleaners, Industrial Units, Ultrasonic Baths, Portable Devices, Inline Systems Technology: Piezoelectric, Magnetostrictive, Digital Frequency, Pulse Technology, Microprocessor Controlled Application: Jewelry Cleaning, Electronics Assembly, Laboratory Instruments, Automotive Components, Optical Instruments End User: Manufacturing Plants, Research Facilities, Repair Workshops, Educational Institutions, Medical Device Makers |
| Companies Covered | Emerson Electric Co., Omegasonics, Crest Ultrasonics, GTSONIC, Ultrasonic Power Corporation, Elma Schmidbauer GmbH, SharperTek, Branson Ultrasonics, L&R Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Cleaning Equipment Market Strategic Shifts & Innovations
A fundamental shift toward intelligent, data-driven cleaning processes is redefining equipment design and market expectations. This evolution prioritizes verifiable performance, process control, and compatibility with sustainable chemistry, moving beyond simple contaminant removal to validated, repeatable outcomes.
Technology and Product Evolution
Adaptive ultrasonic technology utilizes integrated sensors to dynamically adjust power and frequency based on the cleaning load and liquid conditions. Medical device and semiconductor manufacturers are adopting these systems to achieve uniform cleaning. This intelligent control is displacing older, fixed-frequency units that risk damaging delicate components or delivering inconsistent results across complex geometries.
Regulatory and Policy Shifts
Europe's Medical Device Regulation (MDR) imposes rigorous validation requirements on all manufacturing processes, including cleaning. This mandate accelerates the phase-out of certain harsh solvents in favor of safer, aqueous-based cleaning agents. The medical device segment is most affected, compelling equipment manufacturers to engineer systems optimized for the physical properties of these environmentally friendly chemistries.
Demand-Side and Behavioral Shifts
A preference for operational expenditure over capital expenditure is driving interest in equipment leasing and service-based models. This approach allows smaller contract manufacturers in the electronics and medical sectors to access advanced cleaning technology without a large upfront investment. The trend is most pronounced in highly competitive manufacturing regions like Mexico and Poland, where cost control and technology access are critical differentiators.
Ultrasonic Cleaning Equipment Market Segmentation
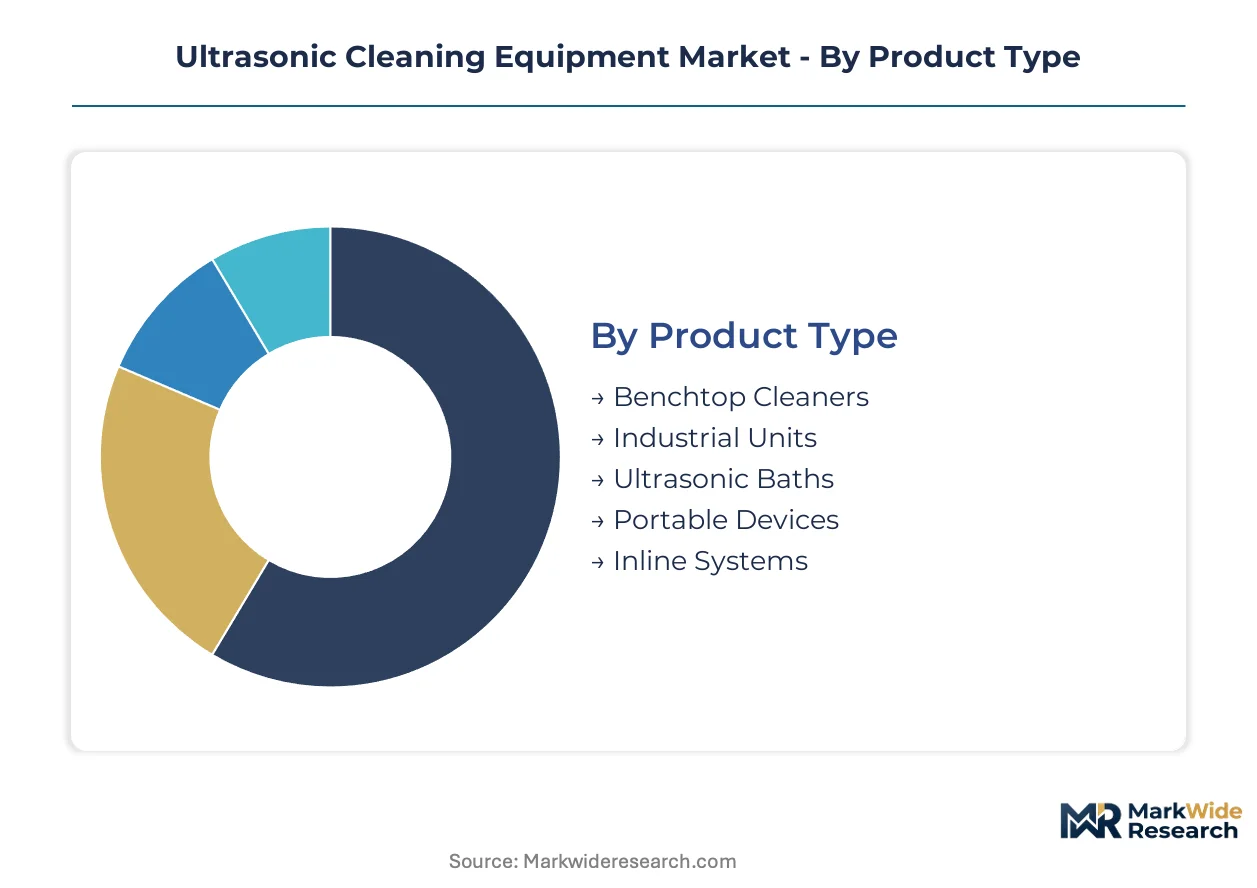
The ultrasonic cleaning equipment market differentiates across various dimensions, reflecting the diverse industrial requirements and regulatory landscapes it serves. Understanding these segments is crucial for manufacturers to tailor solutions that meet specific performance, compliance, and cost criteria across global end-user industries.
Product Type:
Regulatory frameworks differentiate ultrasonic cleaning equipment based on design and intended use, influencing market access and required certifications.
- Industrial Units:These large-scale systems are engineered for high-volume, continuous operation in manufacturing environments, handling components for automotive, aerospace, and general industrial applications. Demand concentrates in Germany's precision manufacturing sector, where complex parts require non-abrasive cleaning.
- Benchtop Cleaners:Compact, self-contained units typically found in laboratories, dental offices, and electronics assembly facilities, offering precise control over cleaning parameters for delicate items. These command higher price points due to stringent performance and control specifications for electronics assembly.
- Ultrasonic Baths:Versatile standalone tanks used for general cleaning purposes in various settings, from educational institutions to small workshops.
- Portable Devices:Handheld or compact units designed for on-site or mobile cleaning tasks, prioritizing ease of transport and quick deployment.
- Inline Systems:Integrated into automated production lines, these systems provide continuous, high-throughput cleaning, essential for semiconductor fabrication and high-volume medical device manufacturing.
Industrial Units handle the majority of throughput; Inline Systems are the fastest mover on share.
Technology:
The underlying technological architecture of ultrasonic systems dictates performance capabilities and associated production costs.
- Piezoelectric:This technology utilizes ceramic transducers that convert electrical energy into high-frequency sound waves, generating cavitation efficiently. Piezoelectric transducers form the core of most modern ultrasonic cleaning equipment due to their reliability and broad frequency range.
- Microprocessor Controlled:These advanced systems integrate digital control units for precise regulation of frequency, power, temperature, and cycle times, ensuring repeatable and validated cleaning processes. Medical device makers and semiconductor facilities in East Asia increasingly adopt these systems for critical applications.
- Magnetostrictive:Employing ferromagnetic materials, these transducers convert magnetic energy into mechanical vibrations, often used for heavy-duty industrial applications requiring robust power.
- Digital Frequency:Allows for fine-tuning and sweeping of ultrasonic frequencies to optimize cleaning for specific geometries and contaminant types, enhancing versatility.
- Pulse Technology:Delivers ultrasonic energy in short, high-intensity bursts, effective for dislodging stubborn contaminants without damaging sensitive substrates.
Advanced microprocessor control systems are gaining traction for their precision, while piezoelectric transducers remain fundamental to most designs.
Application:
Diverse end-use applications for ultrasonic cleaning equipment reflect varying requirements for precision, scale, and material compatibility.
- Electronics Assembly:Critical for removing microscopic contaminants from printed circuit boards, semiconductor components, and delicate electronic parts to prevent short circuits and ensure performance. Miniaturization trends in East Asian fabrication facilities drive demand for non-contact cleaning.
- Automotive Components:Utilized for cleaning intricate engine parts, fuel injectors, hydraulic components, and transmission parts to remove oils, grease, and carbon deposits without abrasion. Germany's automotive industry heavily relies on this application for quality assurance.
- Jewelry Cleaning:A common application for removing dirt, oils, and residues from precious metals and gemstones, enhancing aesthetic appeal.
- Laboratory Instruments:Essential for sterilizing and cleaning glassware, surgical tools, and analytical equipment in research and medical settings, maintaining hygiene and experimental integrity.
- Optical Instruments:Requires highly specialized ultrasonic cleaning to remove dust and smudges from lenses, mirrors, and precision optics without causing surface damage.
Precision cleaning for electronics and automotive parts drives substantial volume, while specialized optical cleaning requires highly controlled processes.
End User:
Different end-user segments demand tailored ultrasonic cleaning solutions, driven by operational scale, regulatory compliance, and budget considerations.
- Manufacturing Plants:Large-scale industrial facilities across automotive, aerospace, and general manufacturing sectors use ultrasonic systems for cleaning production parts, molds, and machinery. These facilities prioritize throughput and robust system design.
- Medical Device Makers:Adherence to stringent standards like ISO 13485 and US FDA guidelines necessitates validated ultrasonic cleaning processes for surgical instruments, implants, and diagnostic devices. This segment demands systems optimized for biocompatible materials and aqueous cleaning agents.
- Research Facilities:Academic and commercial laboratories utilize ultrasonic cleaners for glassware, scientific instruments, and sample preparation, ensuring cleanliness for experimental accuracy.
- Repair Workshops:Automotive, electronics, and general repair shops employ ultrasonic cleaning for reconditioning components, extending equipment lifespan and improving performance.
- Educational Institutions:Schools and universities use basic ultrasonic cleaners for laboratory demonstrations, equipment maintenance, and student projects.
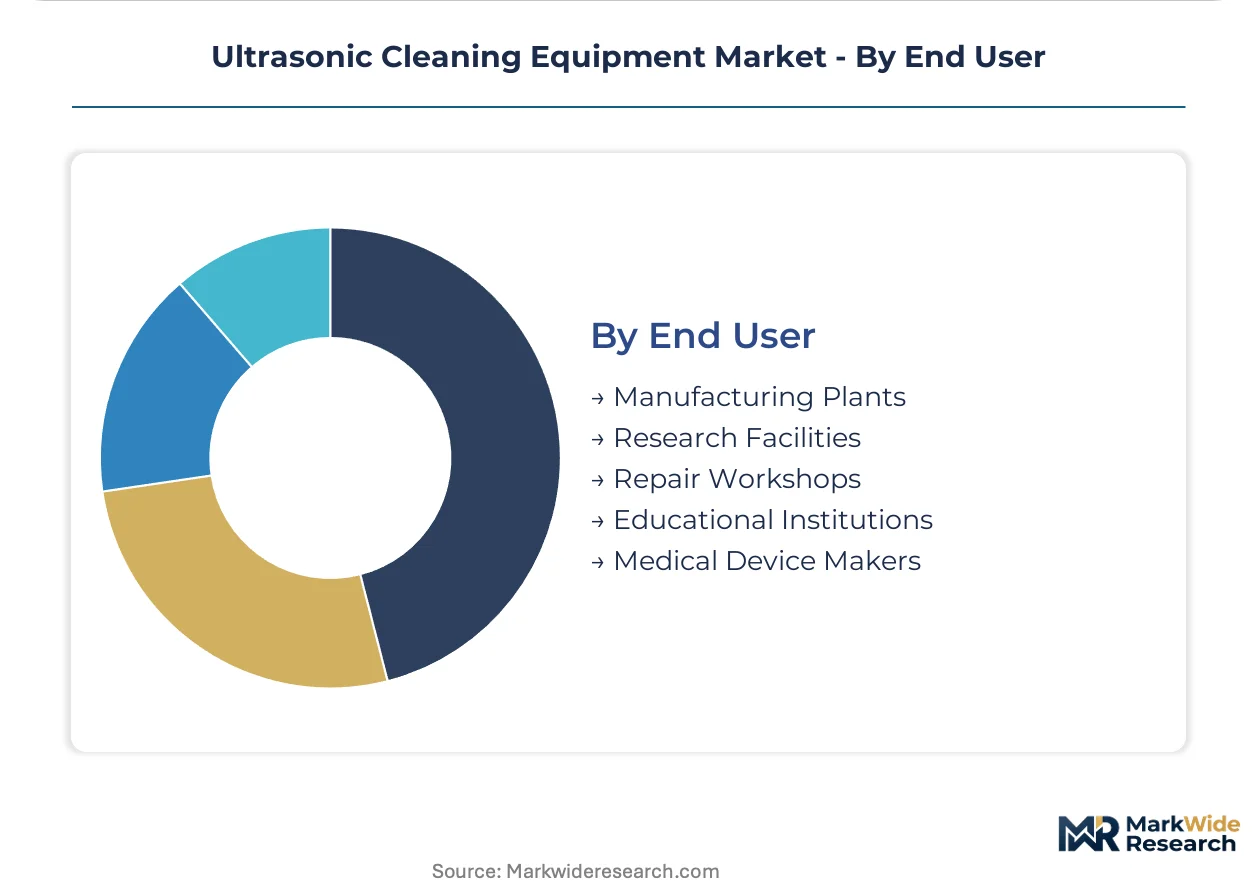
Medical device manufacturers face the most stringent validation requirements, contrasting with the broader operational needs of manufacturing plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory mandates and technological advancements drive ultrasonic cleaning equipment demand across key global manufacturing hubs. Stringent cleanliness requirements for medical devices and the push for electronics miniaturization compel industries to adopt advanced cleaning solutions. This market expansion is particularly evident in regions with high-precision manufacturing and advanced technological sectors.
Germany
Germany's high-precision manufacturing sector demands advanced ultrasonic cleaning for automotive components and industrial machinery. European CE marking under the Medical Device Regulation (MDR) requires validated cleaning processes for medical device manufacturers. Automotive clusters in Bavaria and Baden-Württemberg utilize ultrasonic systems to ensure the cleanliness of intricate parts.
United States
The US FDA's device guidelines necessitate validated cleaning protocols for medical device manufacturers, creating significant demand for ultrasonic equipment. Aerospace and defense industries also require precision cleaning for critical components. Manufacturing facilities in the Northeast Corridor and California rely on these systems for high-reliability applications.
China
China's rapid expansion in semiconductor fabrication and electronics assembly fuels demand for advanced non-contact cleaning solutions. GB standards for industrial machinery influence safety and performance requirements for ultrasonic equipment. Major electronics manufacturing hubs in the Yangtze River Delta and Pearl River Delta drive significant market volume.
South Korea
Electronics miniaturization in South Korea's robust semiconductor and display manufacturing industries necessitates highly precise ultrasonic cleaning. The country's strong export focus on high-tech products demands adherence to global quality standards. Fabrication facilities in the Seoul Capital Area and Gyeonggi Province integrate advanced inline cleaning systems.
Japan
Japan's advanced automotive and optical instrument manufacturing sectors require superior cleaning performance for delicate components. Rigorous quality control standards across various industries enforce the use of high-precision cleaning technologies. Industrial clusters in the Kanto region and Chubu region consistently invest in innovative ultrasonic solutions.
Ultrasonic Cleaning Equipment Market Key Industry Players
Listed leaders compete with private specialists across the ultrasonic cleaning equipment market, which exhibits a tiered structure favoring providers of validated, high-precision systems. The market segments into large industrial solution providers, niche high-precision specialists, and general-purpose equipment manufacturers. Strategic partnerships and portfolio diversification are common competitive moves among established players.
Within the premium industrial segment, Emerson Electric Co. occupies a position leveraging its broad industrial automation portfolio to serve multinational clients. Elma Schmidbauer GmbH exemplifies a high-precision specialist, providing advanced units for European medical and laboratory sectors. Crest Ultrasonics anchors the large-scale industrial systems category, competing with robust solutions for heavy-duty applications.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Omegasonics |
| Crest Ultrasonics |
| GTSONIC |
| Ultrasonic Power Corporation |
| Elma Schmidbauer GmbH |
| SharperTek |
| Branson Ultrasonics |
| L&R Manufacturing |
| Others |
Cost & Logistics Intelligence
Typical lead times for custom industrial ultrasonic systems, extending to 12-16 weeks, reflect specialized component sourcing and complex assembly processes. This extended lead time directly influences pricing power for established vendors, particularly for highly configured units.
Pricing Analysis
Certification level, specifically ISO 13485 and US FDA compliance, creates the primary spread in ultrasonic cleaning equipment pricing. The dominant pricing model is a hybrid, combining project-based quotations for large industrial systems with transactional sales for benchtop units. Customization and after-sales service bundles also drive price differentiation, reflecting specialized engineering and ongoing support. Pricing softness affects general-purpose equipment due to increased competition from new entrants, while medical device manufacturers exhibit the least price sensitivity given stringent validation requirements.
Supply Chain Analysis
Rising inbound logistics costs, particularly for specialized components shipped across East Asian trade lanes, impact the overall cost structure of ultrasonic cleaning equipment. Geographic supply concentration for critical piezoelectric transducers and advanced microprocessors centers on China, South Korea, and Japan. This creates single-source vulnerability for high-performance transducers, posing a structural risk to equipment manufacturers. Distribution runs through direct sales channels for complex industrial systems, while benchtop and portable units often leverage broader distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic cleaning equipment market presents a significant service-attach opportunity, with validated process optimization and preventative maintenance contracts expanding faster than hardware sales.
For Market Incumbents:
Secure long-term contracts with medical device manufacturers by investing in ISO 13485-compliant validation services and advanced process documentation. This counters the threat from specialized software providers offering process control solutions and reinforces market share against emerging entrants. Expand capacity in Germany and the US to meet localized demand for high-precision industrial units, leveraging channel control for aftermarket parts and consumables.
For New Entrants and Emerging Players:
Anchor in the electronics assembly segment, particularly for specialized cleaning of 3D-printed components and flexible circuits, which represents an underpenetrated white space. Target contract manufacturers in Mexico and Poland with leasing models and modular benchtop systems to lower upfront investment barriers. Develop application-specific aqueous cleaning chemistries that work synergistically with new ultrasonic frequencies.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large industrial conglomerates seeking to divest non-core precision cleaning divisions, offering established technology and client bases. Long-term viability across the next decade hinges on acquiring specialists in AI-driven process automation and biocompatible material cleaning technologies. The signal to watch is the increasing patent activity in adaptive ultrasonic frequency control, indicating future performance differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered adaptive cleaning systems | Enhances cleaning uniformity for complex geometries in medical devices. |
| Invest in biocompatible material cleaning R&D | Addresses the growing market for 3D-printed implants and specialized medical tools. |
| Expand service-based equipment leasing models | Lowers capital expenditure for small and medium-sized contract manufacturers. |
| Secure supply agreements for advanced transducers | Mitigates single-source vulnerability and ensures component availability. |
| Pursue CE marking and FDA validation for new systems | Unlocks access to regulated medical device manufacturing markets in Europe and the US. |
Research Approach
The analysis maps industrial, medical, and electronics sub-sectors, each validated through primary interviews with medical device engineers and automotive plant managers. This involved combining insights from semiconductor fab operators and industrial equipment procurement leads with secondary data from ISO 13485 audit reports and GB standards. FDA device guidelines and patent databases further informed a robust bottom-up and top-down triangulation process.
Forecast outputs were consistently validated against industry benchmarks for precision cleaning equipment, ensuring alignment with historical market trajectories. The analytical framework models segmentation across product type, technology, application, and end-user, incorporating regional regulatory clusters throughout the forecast period. Compound Annual Growth Rates were derived from an iterative process factoring in semiconductor miniaturization rates and medical device production volumes.
Underlying assumptions cover stable regulatory environments and sustained industrial investment, with deviation risk concentrated in geopolitical shifts impacting transducer supply. Forecasts reflect these baseline conditions, acknowledging that rapid emergence of disruptive alternative cleaning technologies could alter market dynamics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Glass Engraving Machines Market
Industrial Equipment
Contour Measuring Machines Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Vertical Centrifugal Separator Market