
 Global Thick Film Heater Market | 2026-2036
Global Thick Film Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thick Film Heater Market Outlook
Direct OEM supply agreements is reconfiguring how thick film heater manufacturers reach end-equipment builders. Watlow Electric Manufacturing Company leverages its vertical manufacturing footprint to control substrate-to-assembly lead times. Ferro Techniek anchors European medical device supply chains through specialized ceramic heater production. Chromalox competes on thermal engineering services bundled with heater systems, differentiating beyond commodity hardware.
Thick film heaters integrate resistive conductive pastes fired onto ceramic or metal substrates, achieving watt densities between 50 and 200 W/cm² with response times under 10 seconds for precision thermal management. These devices serve critical heating functions in semiconductor processing, medical diagnostics, automotive battery thermal conditioning, and industrial fluid systems. Polyimide heaters lead flexible substrate applications where space constraints and rapid thermal cycling dominate design requirements, while silicone heaters sustain broader industrial equipment penetration due to lower unit costs and easier custom shaping. Screen printing remains the dominant manufacturing technology, though laser etching gains share in aerospace and medical devices where trace pattern precision directly impacts heater uniformity and safety margins.
FDA medical device regulations and EPA material restrictions in the United States, alongside REACH substance controls and CE marking requirements under the EU MDR in Europe, shape substrate material selection and biocompatibility testing protocols. Japan's METI energy efficiency standards and China's GB standards for electrical heating appliances add compliance layers for suppliers serving Asian OEMs. Stakeholders must monitor evolving RoHS exemptions for high-temperature solder alloys and track polymer substrate flame-retardant classifications, as these material rules increasingly determine market access across major demand clusters.
Market Dynamics
Automotive electrification programs and medical device biocompatibility mandates are compressing substrate qualification timelines while concentrating procurement power among tier-one OEMs with captive thermal engineering capabilities.
Growth Catalysts
- Automotive Battery Thermal Conditioning:Electric vehicle manufacturers in Germany and Japan are integrating thick film heaters into battery management systems to maintain optimal operating temperatures across climate zones.
- REACH Substance Controls:European ECHA restrictions on legacy heating element materials are accelerating substrate innovation toward ceramic-polymer composites with enhanced thermal cycling durability.
- Screen Printing Automation:Precision manufacturing clusters in the United States are deploying closed-loop paste deposition systems that reduce resistance variance below 2% for diagnostic equipment applications.
Market Restraints
- Palladium Price Volatility:Resistive paste formulations depend on palladium alloys whose spot market fluctuations compress gross margins for heater manufacturers without forward hedging programs.
- Japanese Substrate Concentration:High-purity alumina ceramic supply for medical-grade heaters concentrates among three Japanese producers, creating single-source vulnerability for European and North American assemblers.
- Silicone Heater Substitution:Industrial fluid heating applications below 150°C increasingly specify silicone rubber heaters due to 40% lower unit costs and simpler geometric customization.
Strategic Opportunities
- Indian Diagnostic Equipment:CDSCO streamlined medical device registration is opening procurement channels for flexible polyimide heaters in point-of-care diagnostic platforms manufactured in Bangalore and Hyderabad.
- Laser Etching Convergence:Aerospace-grade trace pattern precision from fiber laser systems is enabling heater designs with 50-micron feature resolution for satellite thermal control applications.
- US IRA Clean Energy Credits:Domestic content bonuses for battery thermal management components are incentivizing thick film heater production reshoring to Michigan and Ohio manufacturing corridors.
Industry Challenges
- Polymer Flame-Retardant Certification:UL 94 V-0 testing timelines for new substrate formulations extend 14-18 months, delaying product launches for medical device OEMs with compressed development cycles.
- Multi-Physics Simulation Talent:Thermal-electrical-mechanical co-design capabilities remain scarce among heater engineering teams, forcing reliance on external consultancy for complex substrate-stack optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thick Film Heater Market |
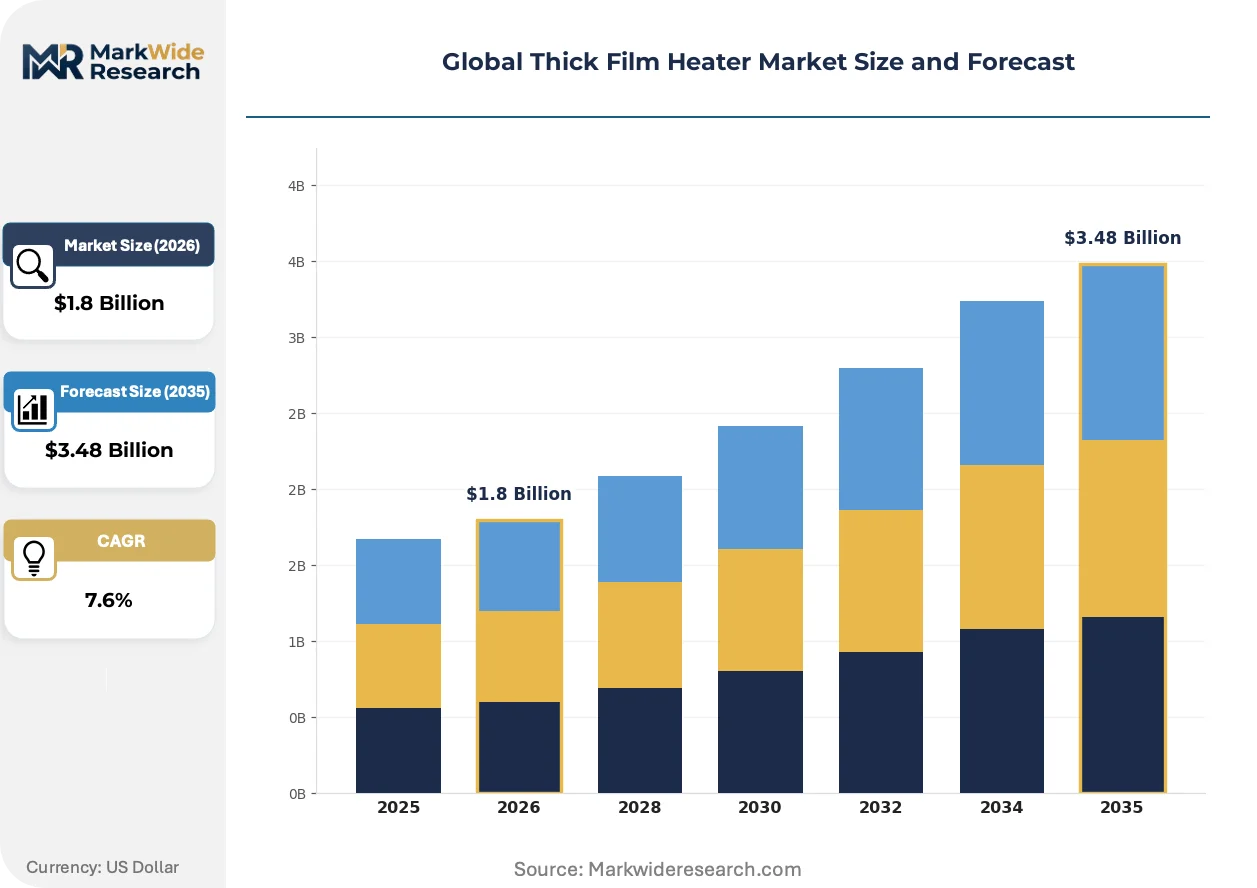
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Heaters, ETFE Heaters, Polyimide Heaters, Silicone Heaters Application: Aerospace, Medical Devices, Automotive Components, Industrial Equipment End User: OEMs, Aftermarket Providers, Research Institutions, Construction Companies Technology: Screen Printing, Laser Etching, Inkjet Printing, Thermoforming |
| Companies Covered | BriskHeat Corporation, Ferro Techniek, Watlow Electric Manufacturing Company, NIBE Industrier AB, Backer Marathon Group, Chromalox, Tempco Electric Heater Corporation, Noritake, Omega Engineering Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thick Film Heater Market Strategic Shifts
Thick film heater technology is bifurcating between ultra-precision medical applications demanding sub-second thermal response and industrial scales prioritizing substrate cost reduction through material substitution.
Laser-etched trace patterns on alumina nitride substrates are rendering obsolete conventional screen-printed designs in aerospace attitude control systems. Satellite manufacturers in the United States and France specify these heaters for reaction wheel thermal management where watt density uniformity directly impacts pointing accuracy. The technology is compressing supplier qualification lists to three certified vendors with in-house laser machining capability.
EU MDR biocompatibility testing expansion is mandating ISO 10993 cytotoxicity validation for all heater substrates contacting patient fluids or diagnostic reagents. German medical device OEMs now require batch-level material certificates extending back to raw ceramic powder sources. Polyimide heater suppliers without established biocompatibility documentation are exiting the European diagnostic equipment supply chain.
Direct thermal engineering service contracts are displacing component-only procurement for semiconductor processing equipment. OEMs in Japan and the United States now contract heater performance outcomes—temperature uniformity specifications and failure rate thresholds—rather than purchasing discrete hardware. This model concentrates procurement among integrated thermal solution providers with simulation-backed design capabilities and captive substrate production.
Global Thick Film Heater Market Segmentation
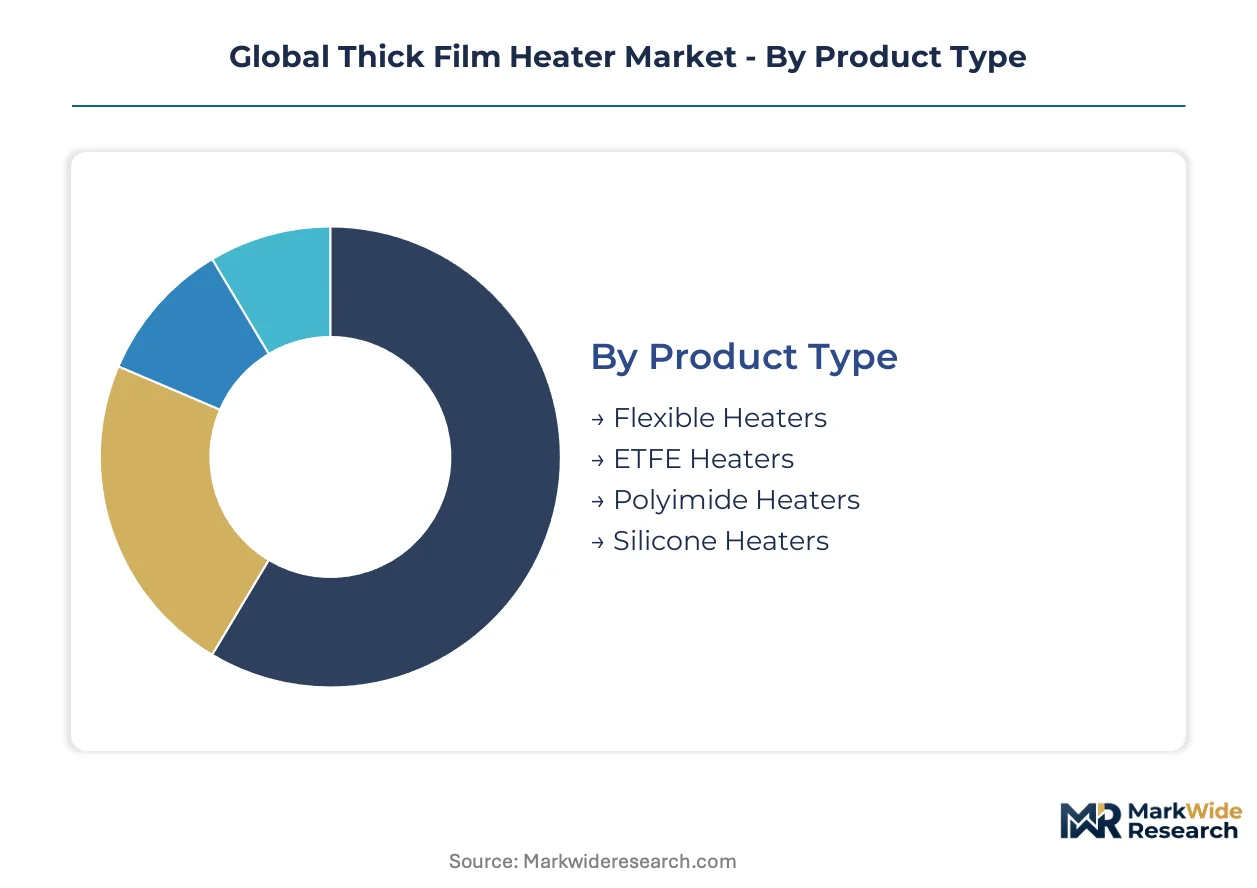
Thick film heater procurement patterns diverge sharply across substrate technologies and end-use specifications. Medical device OEMs prioritize biocompatibility certification paths, while automotive buyers emphasize thermal cycling durability under extreme climate exposure.
Product Type:
Cost tier positioning separates commodity industrial applications from precision medical and aerospace specifications where substrate purity commands premium pricing.
- Flexible Heaters:Polyimide and silicone-based substrates enable conformal mounting on curved surfaces with bending radii below 5mm. Diagnostic equipment manufacturers in Germany and the United States specify these for point-of-care devices requiring rapid thermal cycling between 25°C and 85°C.
- Polyimide Heaters:Kapton-based substrates achieve watt densities exceeding 150 W/cm² with dielectric strength above 5000 VAC. Japan's METI energy efficiency standards are accelerating substitution of rigid ceramic heaters in consumer appliance control modules.
- ETFE Heaters:Ethylene tetrafluoroethylene substrates deliver chemical resistance for semiconductor wet processing equipment.
- Silicone Heaters:Wire-wound or etched foil designs on fiberglass-reinforced silicone rubber serve industrial fluid systems below 200°C operating temperatures.
Silicone heaters command the established base. The steepest expansion runs through polyimide substrates.
Application:
Application mix reflects divergent certification burdens, with FDA device regulations and EU MDR biocompatibility mandates creating distinct qualification timelines across end-use verticals.
- Medical Devices:ISO 10993 cytotoxicity validation and FDA 21 CFR Part 820 quality system compliance govern substrate selection for diagnostic reagent warmers and therapeutic heating pads. German OEMs now mandate batch-level material certificates tracing ceramic powders to specific mine sources.
- Automotive Components:Battery thermal management systems in electric vehicles specify thick film heaters for cell conditioning across ambient temperatures from -40°C to 60°C. NHTSA safety standards and EPA material restrictions constrain polymer flame-retardant selections for cabin heating applications.
- Aerospace:Laser-etched alumina nitride substrates serve satellite reaction wheel thermal control with 50-micron trace precision.
- Industrial Equipment:Process fluid heating and packaging machinery dominate volume consumption with less stringent material certification requirements.
Industrial equipment absorbs the highest unit volumes. Medical devices are climbing the fastest as diagnostic platform miniaturization accelerates.
End User:
Customer type determines contract structure, with OEMs consolidating procurement through direct thermal engineering service agreements while aftermarket channels remain fragmented.
- OEMs:Tier-one automotive and semiconductor equipment manufacturers now contract performance outcomes—temperature uniformity specifications and mean-time-between-failure thresholds—rather than purchasing discrete heater hardware. This model favors suppliers with captive substrate production and multi-physics simulation capabilities.
- Research Institutions:National laboratories and university engineering departments specify custom heater geometries for experimental thermal management systems with low volume but high technical support requirements.
- Aftermarket Providers:Industrial maintenance distributors stock standardized silicone and polyimide heaters for equipment repair and retrofit applications.
- Construction Companies:Building integrated heating systems for concrete curing and temporary climate control represent emerging demand with severe cost sensitivity.
OEMs concentrate procurement power through outcome-based contracting. Research institutions represent the most fragmented demand channel.
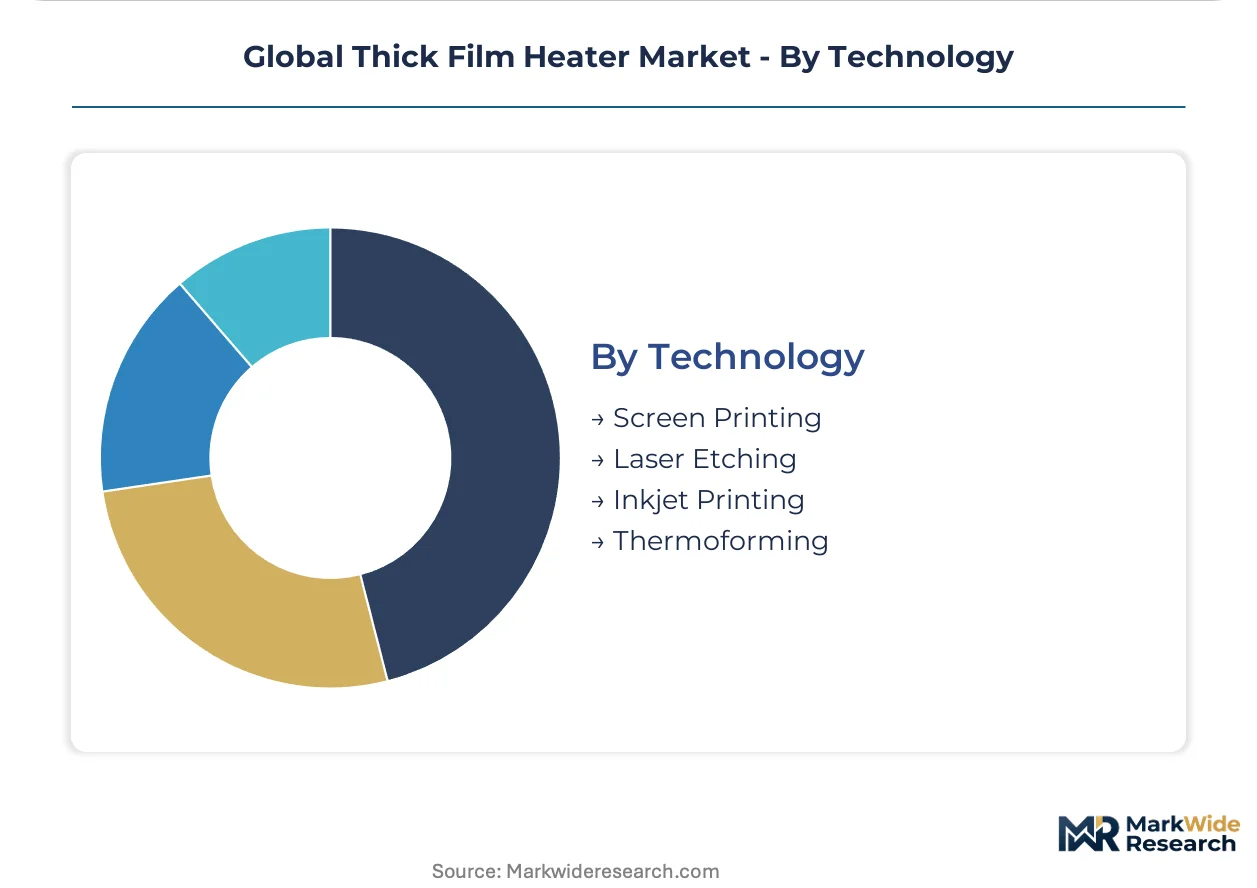
Technology:
Manufacturing process selection hinges on trace pattern precision requirements, with aerospace and medical applications tolerating higher unit costs for improved thermal uniformity.
- Screen Printing:Thick film paste deposition through stainless steel mesh screens remains dominant for ceramic substrate heaters, achieving resistance tolerances of ±5% in production volumes. Automation of paste viscosity control and squeegee pressure is compressing variance below 2% for diagnostic equipment applications in the United States.
- Laser Etching:Fiber laser systems ablate resistive metal films with 50-micron feature resolution, enabling heater designs for satellite thermal control where watt density uniformity directly impacts pointing accuracy. The technology has compressed aerospace supplier qualification lists to three certified vendors.
- Inkjet Printing:Piezoelectric deposition of nanoparticle conductive inks enables rapid prototyping and low-volume customization without screen tooling costs.
- Thermoforming:Vacuum and pressure forming of heated polymer substrates shapes three-dimensional heater geometries for automotive interior applications.
Screen printing retains the production volume base. Laser etching is gaining share fastest in precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in German precision manufacturing clusters while cost-sensitive procurement in Indian diagnostic equipment markets compresses margins for standard-grade flexible heaters.
Germany
Automotive electrification programs and medical device miniaturization drive thick film heater procurement from domestic OEMs. EU MDR biocompatibility mandates and REACH substance controls through ECHA accelerate substrate qualification timelines. Stuttgart and Munich manufacturing corridors host precision ceramics producers supplying ceramic-polymer composite heaters for battery thermal management systems.
United States
Semiconductor processing equipment and aerospace satellite manufacturers specify laser-etched alumina nitride heaters with 50-micron trace precision. FDA device regulations and EPA material restrictions constrain polymer flame-retardant selections for medical diagnostic applications. Michigan and Ohio manufacturing corridors attract IRA clean energy credit-driven reshoring of battery thermal management component production.
Japan
High-purity alumina ceramic supply for medical-grade heaters concentrates among three domestic producers serving global diagnostic equipment assemblers. METI energy efficiency standards accelerate substitution of rigid ceramic heaters with polyimide substrates in consumer appliance control modules. Nagoya and Osaka industrial clusters integrate thick film heaters into electric vehicle battery management systems for climate-zone cell conditioning.
India
Point-of-care diagnostic platform manufacturers in Bangalore and Hyderabad expand procurement of flexible polyimide heaters as CDSCO streamlines medical device registration pathways. Domestic content requirements and PLI scheme incentives for electronics manufacturing attract substrate assembly investments. Chennai and Pune industrial zones develop silicone heater production for industrial fluid systems serving regional process industries.
China
GB standards for electrical heating appliances and dual carbon goals shape substrate material selection for domestic appliance and automotive OEMs. MIIT industrial upgrading programs accelerate screen printing automation in precision manufacturing clusters. Yangtze River Delta electronics manufacturing hubs integrate thick film heaters into semiconductor processing equipment for domestic foundry expansion.
Global Thick Film Heater Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling substrate production and thermal engineering capabilities. Market structure concentrates procurement power among tier-one OEMs contracting performance outcomes rather than discrete hardware, compressing supplier lists to integrated thermal solution providers. Three archetypes dominate: captive substrate producers with in-house ceramic firing, thermal engineering consultancies bundling simulation services, and flexible substrate assemblers serving medical device OEMs. Dominant competitive moves include backward integration into alumina ceramic powder sourcing and geographic expansion through direct OEM supply agreements in electrification corridors.
Among established Western manufacturers, Watlow Electric Manufacturing Company and Chromalox exemplify the integrated thermal solution archetype, while Ferro Techniek occupies a position within the European medical device supply chain specialization. These entities represent the competitive response to outcome-based contracting models where temperature uniformity specifications and failure rate thresholds replace component-only procurement. Japanese producers including Noritake anchor the high-purity ceramic substrate tier, reflecting the geographic concentration of medical-grade alumina supply. The competitive dynamic favors entities with captive substrate production, multi-physics simulation capabilities, and established biocompatibility documentation paths under EU MDR and FDA frameworks.
| Leading Market Players |
|---|
| BriskHeat Corporation |
| Ferro Techniek |
| Watlow Electric Manufacturing Company |
| NIBE Industrier AB |
| Backer Marathon Group |
| Chromalox |
| Tempco Electric Heater Corporation |
| Noritake |
| Omega Engineering Inc |
| Others |
Value Chain & Pricing Dynamics
Japanese high-purity alumina ceramic production concentrates among three domestic suppliers, anchoring margin pools in medical-grade heater substrates where batch-level material certificates command substantial premiums over standard industrial grades.
Pricing Analysis
Configured-to-order pricing for laser-etched alumina nitride heaters with 50-micron trace precision carries 40-60% premiums over screen-printed standard designs. Three-tier pricing structure across medical-certified, automotive-qualified, and industrial-grade levels segments buyers by certification burden and thermal cycling requirements. Cost compression in silicone rubber heaters is intensifying because Indian and Chinese assemblers are scaling standardized production for fluid heating applications below 150°C. Construction companies and aftermarket distributors exhibit highest price sensitivity, while German medical device OEMs prioritize biocompatibility documentation over unit cost.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and supply-chain finance facilities from Japanese trading houses are restructuring working capital requirements for substrate assemblers. Raw material dependencies center on palladium alloys for resistive pastes, high-purity alumina powders from Japanese producers, and polyimide films from US and South Korean chemical suppliers. Single-source vulnerability in medical-grade ceramic substrates creates structural risk for European and North American heater manufacturers. Distribution runs through direct OEM supply agreements for tier-one automotive and semiconductor equipment builders, with fragmented industrial aftermarket channels serving maintenance and repair demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-physics simulation capabilities for thermal-electrical-mechanical co-design remain scarce across the supplier base, constraining complex substrate-stack optimization and concentrating procurement power among integrated thermal solution providers with captive engineering talent.
For Market Incumbents: Harden supply security through backward integration into alumina ceramic powder sourcing or binding long-term offtake agreements with Japanese producers. Expand captive laser machining capability to defend position against aerospace qualification list compression. Prioritize EU MDR and FDA biocompatibility documentation investments to maintain access to German and US medical device supply chains as regulatory timelines extend. For New Entrants and Emerging Players: Establish a beachhead in Indian point-of-care diagnostic equipment through CDSCO-registered polyimide heater supply to Bangalore and Hyderabad manufacturers. Target construction sector concrete curing applications with cost-optimized silicone heater designs. Pursue direct thermal engineering service contracts rather than component-only sales to differentiate from commoditized industrial suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated thermal solution providers with captive substrate production and established biocompatibility documentation paths. Long-term viability hinges on simulation-backed design capabilities and outcome-based contracting relationships with tier-one OEMs. Monitor palladium price hedging programs and laser etching certification status as inflection indicators for margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Ceramic Powder | Secures medical-grade substrate supply against Japanese producer concentration risk. |
| Laser Etching Capability Certification | Enables access to aerospace satellite thermal control specifications from US and French manufacturers. |
| EU MDR Biocompatibility Documentation Investment | Maintains market access as German OEMs mandate ISO 10993 cytotoxicity validation. |
| Direct Thermal Engineering Service Contracts | Shifts revenue model from hardware sales to performance-based outcomes with Japanese semiconductor equipment OEMs. |
| Geographic Expansion to Indian Diagnostic Corridors | Captures CDSCO-streamlined procurement growth in Bangalore and Hyderabad manufacturing zones. |
Study Parameters
Desk research of ECHA REACH substance restriction filings, FDA 510(k) device registrations, METI energy efficiency standard updates, and customs trade data preceded structured interviews with thermal engineering directors at semiconductor equipment OEMs, procurement leads at German automotive tier-one suppliers, biomedical engineers at US diagnostic device manufacturers, and plant managers at Japanese ceramic substrate producers. Primary fieldwork combined with secondary validation from SEC 10-K filings, industry association technical publications, and hospital procurement database extracts. Bottom-up unit demand estimates triangulated against top-down market value reconstruction.
Forecast assumptions held regulatory compliance timelines and palladium price volatility bands fixed while varying electric vehicle production ramp rates and medical device miniaturization trajectories across the projection horizon. Segmentation modeling incorporated substrate technology, end-use application, manufacturing process, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to normalized baseline values. Industry-specific inputs included NHTSA battery safety standard evolution and IRA domestic content bonus qualification thresholds.
Sensitivities concentrate around REACH substance restriction expansion, Japanese alumina supply disruption, and laser etching technology diffusion rates. Forecasts reflect documented assumptions regarding OEM consolidation patterns and thermal engineering service contract adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Global Flat Glass Tempering Machines Market