
 South America Electric Vehicle Charging Equipment Market | 2026-2036
South America Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle Charging Equipment Market Insights
Aftermarket service revenue is rewriting value capture in South America as hardware commoditization pushes margin pools toward maintenance contracts and software subscriptions. ABB Ltd leverages its regional service network to anchor long-term fleet agreements across Brazilian sugar-ethanol logistics corridors. Siemens AG competes through integrated energy management platforms that extend beyond pure charging into grid-balancing services for commercial operators.
South America Electric Vehicle Charging Equipment comprises conductive power transfer systems rated between 3.7 kW and 350 kW, employing either alternating-current rectification onboard the vehicle or direct-current conversion within the station enclosure, designed primarily to replenish battery electric vehicle energy stores for passenger transport, freight logistics, and shared mobility services. DC Fast Chargers command disproportionate capital allocation from charging station providers due to utilization premiums on highway corridors, while Wall Mounted Chargers sustain volume leadership in residential deployments across gated condominium complexes. Ultra-Fast Charging technology attracts concentrated R&D investment as Brazilian utilities test 350 kW liquid-cooled cable systems for heavy-duty fleet terminals.
Brazil's ANP biofuel-electric regulatory framework and Argentina's CNEA energy transition standards shape product certification requirements, with both agencies mandating grid-interoperability testing for imported charging hardware. ANVISA in Brazil and local municipal regulators in Santiago, Chile enforce electromagnetic compatibility and safety protocols that filter non-compliant suppliers from public procurement channels. Stakeholders must monitor how MERCOSUR harmonization negotiations reshape cross-border equipment certification before committing to single-country manufacturing footprints.
Market Dynamics
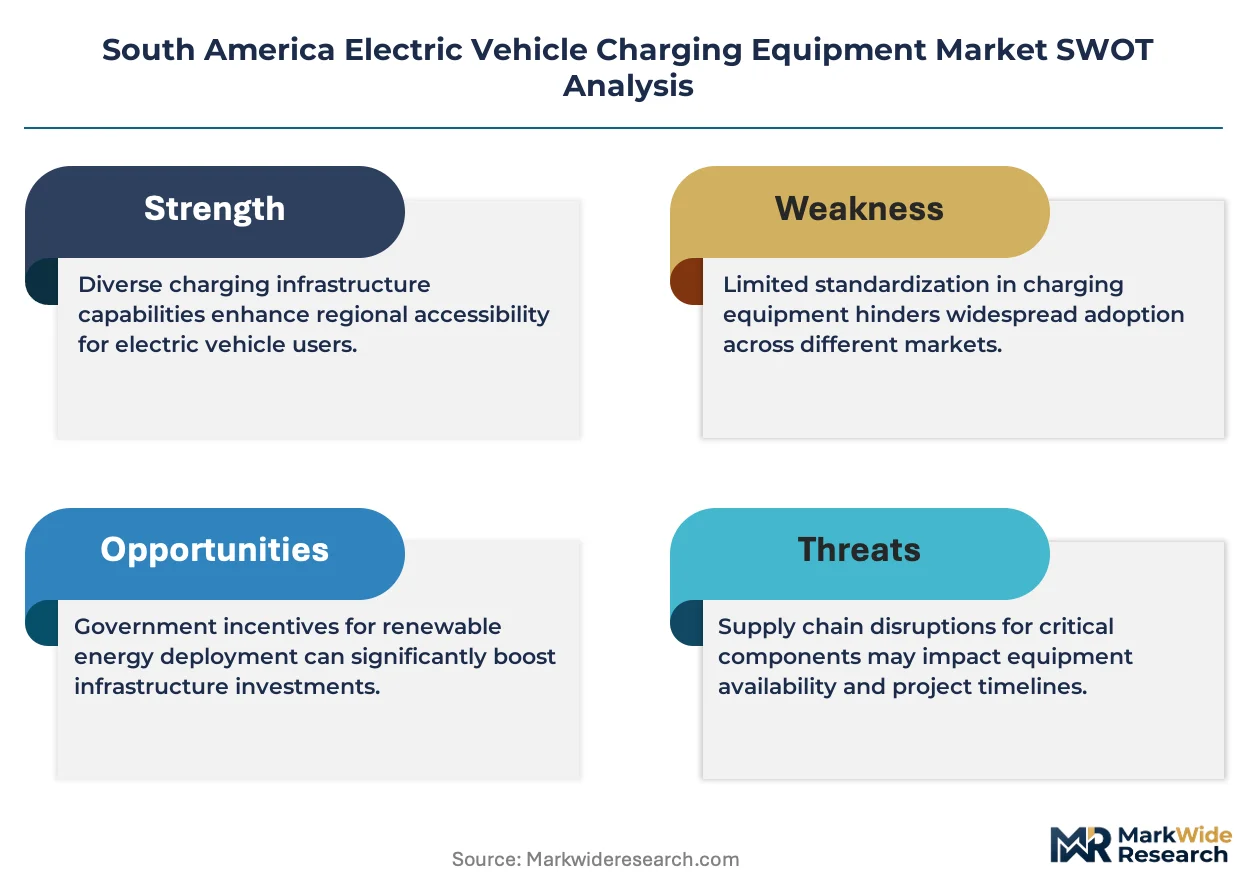
Brazil's ANP biofuel-electric hybrid mandate is forcing fleet operators to accelerate depot charging commitments, creating a structural pull toward high-capacity DC infrastructure that reshapes capital allocation across the value chain.
Growth Catalysts
- ANP Regulatory Framework:Brazil's national biofuel-electric hybrid policies create direct procurement incentives for fleet electrification, channeling public and private capital toward charging infrastructure deployment along sugar-ethanol logistics corridors.
- Ultra-Fast Charging R&D:Brazilian utilities are testing 350 kW liquid-cooled cable systems for heavy-duty fleet terminals, validating next-generation hardware specifications before commercial scale-up.
- CABA Metropolitan Concentration:Buenos Aires port logistics corridors in Argentina generate concentrated early demand for ultra-fast charging, creating anchor utilization for highway corridor investments.
Market Restraints
- Import Hardware Certification:ANP and CNEA mandates for grid-interoperability testing create extended validation timelines for foreign equipment suppliers, filtering non-compliant manufacturers from public procurement channels.
- Copper and Semiconductor Input Volatility:Power electronics and cable assemblies depend on commodity inputs with price instability that compresses hardware margins and complicates long-term fleet contract pricing.
- Grid Capacity Constraints:Distribution network limitations in secondary Brazilian cities restrict site selection for high-power charging depots, forcing expensive upstream electrical infrastructure upgrades.
Strategic Opportunities
- MERCOSUR Harmonization:Cross-border equipment certification negotiations create pathway for single manufacturing footprint serving multiple national markets, reducing compliance duplication for regional suppliers.
- Software-Subscription Revenue:Hardware commoditization pushes margin pools toward maintenance contracts and energy management platforms that extend beyond pure charging into grid-balancing services.
- Chilean Municipal Procurement:Santiago's electromagnetic compatibility and safety protocols for public charging tenders reward early-certified suppliers with preferential channel access in a underpenetrated Andean market.
Industry Challenges
- Electrical Engineering Talent Scarcity:High-voltage power systems integration and liquid-cooled thermal management require specialized skills in short supply across Brazilian and Argentine technical labor markets.
- Legacy Fleet Integration Complexity:Sugar-ethanol logistics operators face operational friction retrofitting depot workflows around charging schedules, requiring change management investment that delays contract execution.
- Multi-Agency Certification Coordination:ANVISA electromagnetic compatibility reviews, ANP grid-interoperability testing, and municipal safety inspections create overlapping approval timelines that extend project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle Charging Equipment Market |
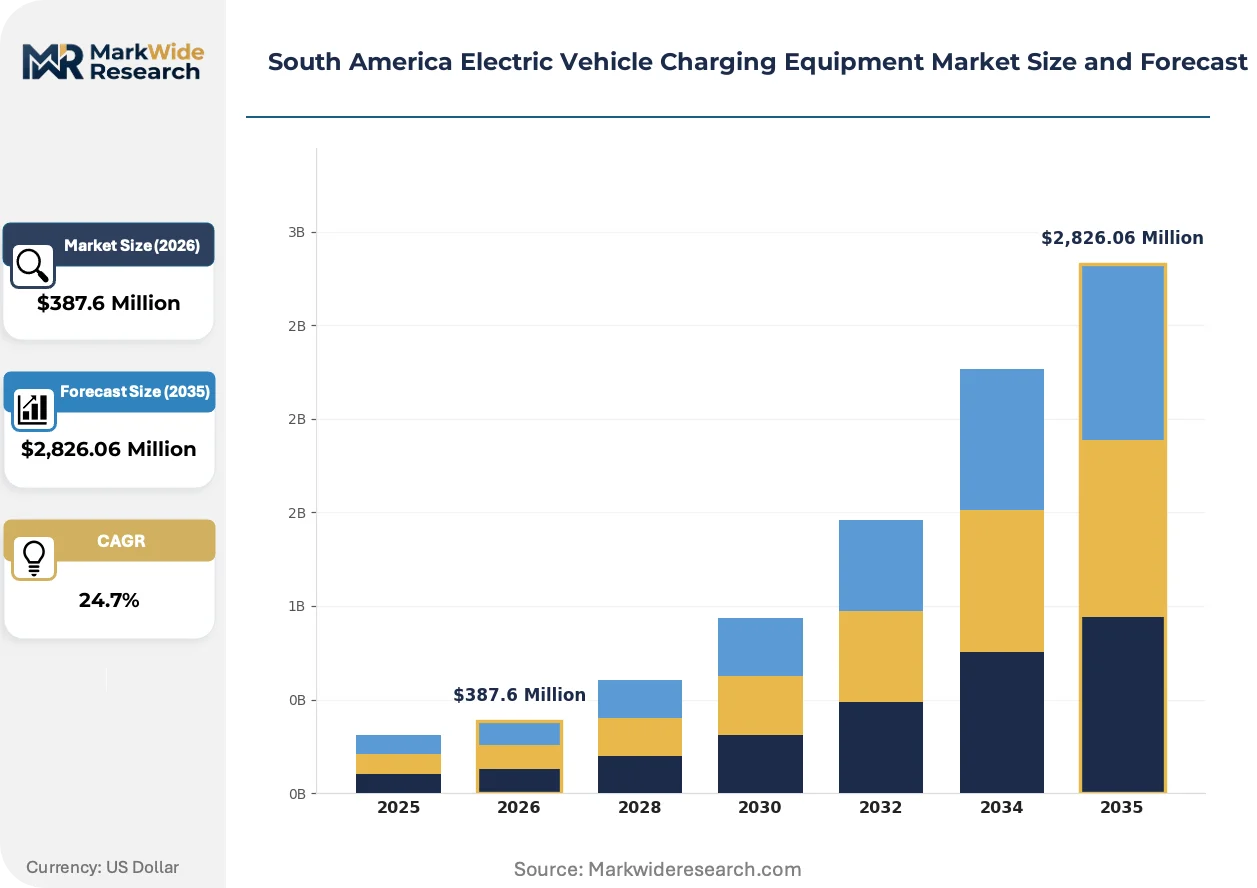
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $2,826.06 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wall Mounted Chargers, Portable Chargers End User: Residential, Commercial, Fleet Operators, Charging Station Providers Technology: Level 1 Charging, Level 2 Charging, Ultra-Fast Charging, Wireless Charging Installation Type: On-Street, Off-Street, Fleet Terminals, Public Charging Stations |
| Companies Covered | ABB Ltd, Schneider Electric, Siemens AG, ChargePoint Holdings Inc, Blink Charging Co, Delta Electronics Inc, Webasto Group, Leviton Manufacturing, Eaton Corp PLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle Charging Equipment Market Trends and Innovations
Charging infrastructure is bifurcating into two development tracks: residential and light commercial hardware racing toward cost minimization, while fleet and highway segments pursue performance maximization through advanced thermal and power management systems.
Dynamic load balancing software is virtualizing the traditional relationship between charging station capacity and grid connection size. Fleet operators in Brazilian sugar-ethanol corridors are adopting these platforms to minimize demand charges and defer transformer upgrades. The technology is virtualizing capital allocation by allowing more vehicles to charge on constrained electrical infrastructure than physical nameplate ratings would permit.
Argentina's CNEA energy transition standards are mandating bidirectional power flow capability in new public charging installations. This industrial consequence forces hardware redesigns toward vehicle-to-grid readiness. Heavy-duty fleet terminals around Buenos Aires port logistics corridors are most affected, with operators selecting certified equipment earlier than technical necessity to secure incentive eligibility.
Fleet procurement committees are consolidating vendor relationships around integrated energy service providers rather than discrete equipment transactions. Brazilian sugar-ethanol logistics groups now require charging hardware vendors to bundle installation, maintenance, and software subscriptions. This pattern is most visible in São Paulo state, where three large cooperatives have shifted to single-source agreements covering ten-year operational lifecycles.
South America Electric Vehicle Charging Equipment Market Segmentation
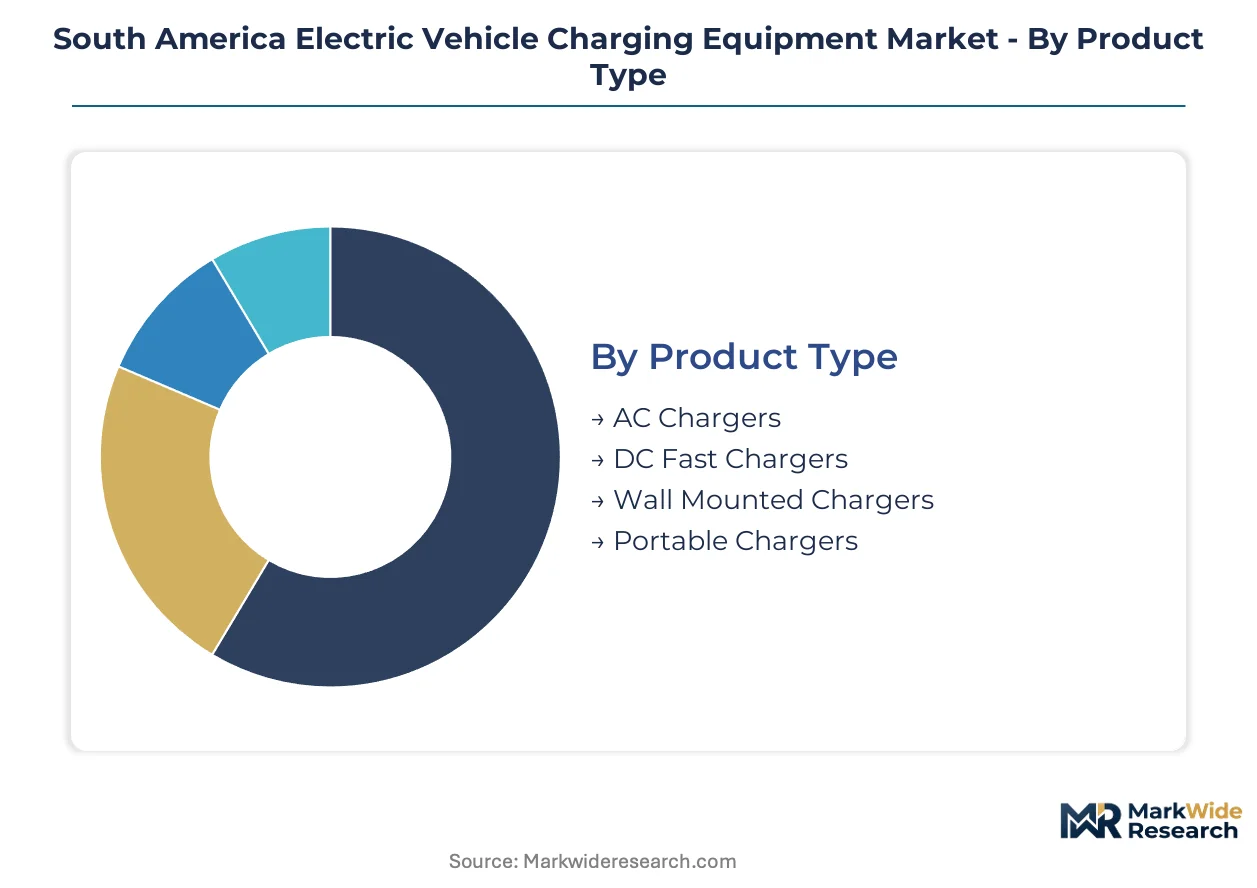
Segmentation in South America Electric Vehicle Charging Equipment reveals divergent capital intensity and replacement cycles across hardware categories. Fleet electrification timelines and regulatory certification requirements create distinct procurement rhythms that suppliers must align against.
Product Type:
Cycle times vary sharply: portable units turn over every 3-4 years as consumer electronics refresh, while DC fast charging hardware operates on 10-15 year depreciation schedules tied to utility interconnection agreements.
- AC Chargers:These units rely on onboard vehicle rectification, limiting station complexity to connector and control systems. Brazilian gated condominium complexes in São Paulo and Rio de Janeiro drive volume as resident associations negotiate bulk procurement for parking structure retrofits. ANVISA electromagnetic compatibility certification creates a 6-9 month validation window that filters smaller importers.
- DC Fast Chargers:External rectification enables 50-350 kW delivery, demanding liquid-cooled cable assemblies and sophisticated thermal management. Highway corridor deployments between São Paulo and Campinas anchor early utilization, though grid capacity constraints in secondary cities restrict site selection and extend commissioning timelines.
- Wall Mounted Chargers:Compact form factors suit residential garages and small commercial lots with limited electrical service upgrades. Santiago municipal tenders favor pre-certified units to accelerate public procurement cycles.
- Portable Chargers:Mobile emergency units serve ride-hail drivers and informal fleet operators lacking depot access. Argentine CABA logistics corridors see concentrated demand from last-mile delivery contractors.
Wall Mounted Chargers anchors the volume base while DC Fast Chargers gains share at the steepest rate.
End User:
Customer procurement sophistication spans from individual residential buyers to institutional fleet committees with decade-long vendor evaluation frameworks.
- Residential:Individual consumers purchasing through retail channels or condominium association bulk programs. São Paulo state tax incentives for home charging installation drive seasonal demand spikes aligned with automotive release cycles.
- Commercial:Property developers and retail operators installing customer-facing charging as amenity infrastructure. Shopping center operators in Buenos Aires prioritize visible curb-side placement to capture dwell-time revenue.
- Fleet Operators:Sugar-ethanol logistics groups and urban delivery networks with centralized depot charging requirements. Brazilian cooperatives now mandate 10-year service bundling including maintenance and software subscriptions.
- Charging Station Providers:Specialized infrastructure developers operating highway corridor and urban fast-charging networks. These entities concentrate capital allocation on utilization-optimized sites with grid-balancing revenue potential.
Fleet Operators command the highest per-site capital deployment while Charging Station Providers expand most quickly through network density strategies.
Technology:
Performance tiers map directly to dwell-time economics: longer parking durations tolerate slower charging, while commercial vehicle operations demand power delivery compression.
- Level 1 Charging:Standard 120V residential delivery at 1.4-1.9 kW suits overnight residential replenishment. Argentine energy subsidies for low-power residential connections sustain this tier despite slow delivery speeds.
- Level 2 Charging:240V systems delivering 3.7-22 kW dominate workplace and commercial parking deployments. Brazilian office park developers favor this tier for employee amenity programs with 6-8 hour dwell periods.
- Ultra-Fast Charging:150-350 kW systems with liquid-cooled cables enable sub-30 minute heavy-duty fleet turnaround. Brazilian utilities test these specifications at sugar-ethanol terminal sites before commercial highway deployment.
- Wireless Charging:Inductive pad systems eliminate connector wear but suffer efficiency losses and high capital costs. Santiago pilot programs for autonomous shuttle routes represent the region's primary deployment channel.
Level 2 Charging sustains installed base leadership while Ultra-Fast Charging climbs the fastest on fleet electrification timelines.
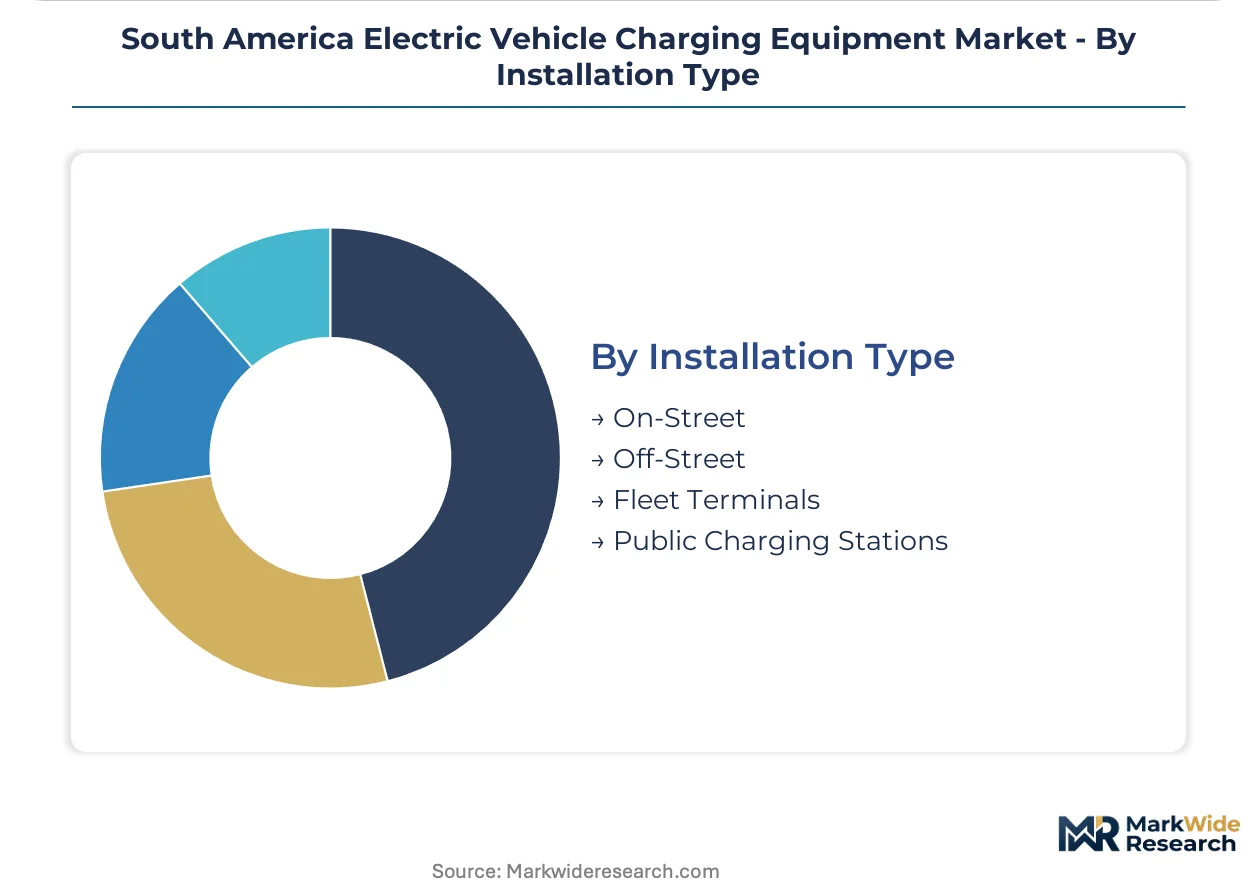
Installation Type:
Site control and electrical access determine deployment feasibility more than charging technology selection in many South American municipalities.
- On-Street:Curb-side installations on public rights-of-way requiring municipal concession agreements. Buenos Aires port logistics corridors concentrate early deployments where freight operators lack private depot access.
- Off-Street:Parking structure and surface lot installations on private property with simpler permitting. Brazilian shopping center operators leverage existing electrical service to minimize upstream infrastructure costs.
- Fleet Terminals:Dedicated heavy-duty charging depots with 350 kW+ capacity and dynamic load balancing. ANP biofuel-electric hybrid mandates accelerate sugar-ethanol cooperative investment in these centralized facilities.
- Public Charging Stations:Mixed-use highway and urban sites serving retail charging demand. Chilean electromagnetic compatibility protocols filter supplier participation in Santiago municipal tenders.
Off-Street deployments anchor current volume while Fleet Terminals gain share at the steepest rate on regulatory-driven procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across South America: fleet operators in Brazil absorb premium hardware costs under ANP mandate pressure, while Argentine commercial buyers delay procurement awaiting currency stabilization, and Chilean municipal tenders filter suppliers on electromagnetic compatibility certification costs.
Brazil
Sugar-ethanol logistics cooperatives drive depot charging demand across São Paulo state as ANP biofuel-electric hybrid policies force fleet electrification timelines. ANVISA electromagnetic compatibility reviews and ANP grid-interoperability testing create 6-9 month validation windows for imported hardware. São Paulo-Campinas highway corridors anchor early ultra-fast charging utilization, with Brazilian utilities testing 350 kW liquid-cooled systems at heavy-duty fleet terminals.
Argentina
Buenos Aires port logistics corridors concentrate early ultra-fast charging demand from freight operators lacking private depot infrastructure. CNEA energy transition standards mandate bidirectional power flow capability in new public installations, forcing hardware redesigns toward vehicle-to-grid readiness. The CABA metropolitan cluster generates anchor utilization for highway corridor investments, with heavy-duty fleet terminals selecting certified equipment earlier than technical necessity to secure incentive eligibility.
Chile
Santiago municipal procurement channels reward early-certified suppliers with preferential access in an underpenetrated Andean market. Local electromagnetic compatibility and safety protocols filter non-compliant suppliers from public tenders, creating certification barriers that favor established regional players. Pilot programs for autonomous shuttle routes in Santiago represent the primary deployment channel for wireless inductive charging systems.
Colombia
Urban delivery networks in Bogotá generate concentrated demand for portable charging units among last-mile contractors lacking depot access. National energy transition frameworks are aligning with regional MERCOSUR harmonization negotiations, creating potential pathways for cross-border equipment certification. Andean corridor logistics operators are evaluating fleet electrification timelines against secondary city grid capacity constraints.
South America Electric Vehicle Charging Equipment Market Competitive Landscape
Integrated energy service providers and discrete hardware manufacturers split the market along bundling-versus-unbundling lines. European industrial conglomerates with regional service networks anchor long-term fleet agreements, while North American charging specialists compete through software platforms and network density strategies. Two dominant competitive moves are reshaping positioning: backward integration into power electronics manufacturing to control semiconductor and copper input costs, and consolidation of vendor relationships around decade-long operational lifecycle contracts.
Among European-based industrial groups, ABB Ltd and Siemens AG exemplify the integrated service archetype, leveraging established regional maintenance networks to anchor fleet agreements. ChargePoint Holdings Inc represents the network-density specialist model, competing through software subscriptions and charging platform scale. These three companies illustrate the strategic bifurcation between hardware-plus-service bundling and pure-play infrastructure development.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric |
| Siemens AG |
| ChargePoint Holdings Inc |
| Blink Charging Co |
| Delta Electronics Inc |
| Webasto Group |
| Leviton Manufacturing |
| Eaton Corp PLC |
| Others |
Pricing and Supply Chain Analysis
São Paulo state's concentration of power electronics assembly capacity shapes downstream pricing power for charging station providers serving Brazilian sugar-ethanol logistics corridors. ANP biofuel-electric hybrid mandates create procurement urgency that absorbs premium hardware costs, while secondary city grid constraints force expensive electrical upgrades that filter price-sensitive buyers from fleet terminal deployments.
Pricing Analysis
Aftermarket service contracts and software subscriptions now drive lifetime value capture as hardware margins compress under commodity input volatility. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates fleet operators with decade-long vendor frameworks from residential condominium bulk buyers. Pricing pressure stems from copper and semiconductor cost swings that complicate long-term contract pricing for charging station providers. Fleet procurement committees show lowest price sensitivity due to ANP regulatory deadlines, while individual residential buyers in gated complexes negotiate aggressively on installation bundling.
Supply Chain Analysis
Export control restrictions on wide-bandgap semiconductors and high-voltage power modules limit component flows from US and EU sources into South American assembly operations. Manufacturing concentration centers on China for power electronics, South Korea for battery management systems, and domestic Brazilian facilities for final enclosure assembly. Raw material dependencies span copper cable assemblies, liquid-cooled thermal management components, and silicon carbide switching devices. Single-source vulnerability in semiconductor supply creates qualification delays for ANP grid-interoperability testing. Distribution runs through authorized service networks anchored by European industrial conglomerates with regional maintenance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock fleet operators into decade-long vendor relationships. ANP and CNEA validation timelines filter non-compliant suppliers, embedding incumbents with approved hardware platforms.
For Market Incumbents: Insulate market position by deepening captive production of power electronics to offset semiconductor input volatility, and extend software subscription attach rates through dynamic load balancing platforms that virtualize grid connection constraints. Emerging North American charging specialists threaten network density advantages in highway corridors, making channel control through exclusive fleet terminal agreements the critical defensive lever.
For New Entrants and Emerging Players: Chilean municipal procurement channels in Santiago offer the most penetrable entry point, where electromagnetic compatibility certification barriers have filtered participation and created whitespace for pre-certified suppliers. Target autonomous shuttle pilot programs as the primary deployment channel for wireless inductive charging systems, leveraging underpenetrated Andean market status to establish reference installations before competitive density builds.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated energy service providers with backward integration into power electronics manufacturing and established regional maintenance networks. Five-to-ten year viability hinges on software-subscription revenue scaling that offsets hardware commoditization. The signal to monitor is MERCOSUR harmonization progress on cross-border equipment certification, which would trigger manufacturing footprint consolidation and reshape acquisition target valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive semiconductor sourcing insulates margins from commodity volatility affecting ANP-compliant hardware. |
| Dynamic Load Balancing Platform Launch | Software subscriptions virtualize grid constraints for Brazilian fleet operators facing transformer upgrade delays. |
| ANVISA Electromagnetic Compatibility Pre-Certification | Early validation accelerates Santiago municipal tender participation in underpenetrated Chilean markets. |
| Fleet Terminal Single-Source Agreements | Ten-year service bundling locks sugar-ethanol cooperatives into integrated maintenance and software ecosystems. |
| 350 kW Liquid-Cooled System Deployment | Ultra-fast charging validation at Brazilian heavy-duty terminals enables highway corridor scale-up. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors at Brazilian sugar-ethanol cooperatives, charging station network developers, ANP regulatory affairs specialists, and power electronics procurement leads at hardware manufacturers. Secondary validation drew from ANP grid-interoperability filings, ANVISA electromagnetic compatibility registries, CNEA energy transition standards documentation, and MERCOSUR technical harmonization protocols. Bottom-up equipment shipment tracking and top-down infrastructure investment forecasts were triangulated against utility interconnection disclosures and fleet operator capex announcements.
Calibration approaches anchored volume and value outputs across the analysis window against observed procurement cycles for AC residential hardware, DC fast charging highway deployments, and fleet terminal ultra-fast systems. Segmentation dimensions modeled include product type, end user archetype, power delivery tier, and installation site control. CAGRs were derived from logistic diffusion curves fitted to regulatory mandate timelines and fleet electrification commitments. Key forecast inputs incorporated ANP biofuel-electric hybrid policy implementation rates and Santiago municipal tender award patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by North American network-density specialists or Chinese power electronics manufacturers would shift outcomes. Material shifts in MERCOSUR harmonization negotiations, semiconductor export control regimes, or Brazilian grid capacity upgrade schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market