
 Multi-Brand Universal Home Charging Pile Market | 2026-2036
Multi-Brand Universal Home Charging Pile Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Brand Universal Home Charging Pile Market Insights
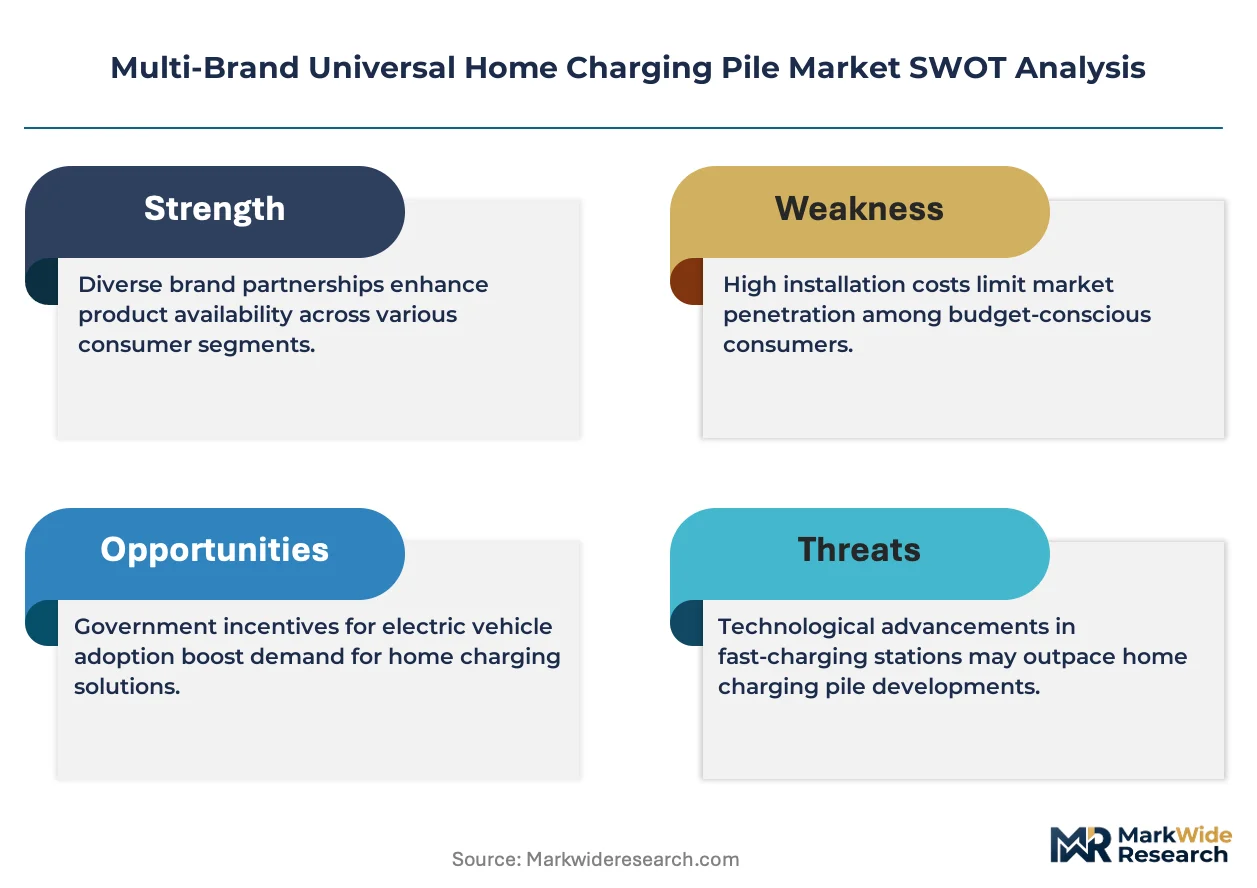
Buyer concentration among multi-family dwelling developers and residential community managers is hardening as EV ownership spreads beyond single-family homeowners. Tesla leverages its proprietary connector ecosystem to sustain brand lock-in among premium buyers, while ChargePoint anchors its position through broad OEM partnerships and open-network compatibility. ABB competes on industrial-grade reliability and bidirectional charging readiness for European markets.
A multi-brand universal home charging pile is an electric vehicle supply equipment unit designed to deliver alternating current power across multiple connector standards, typically rated between 7 kW and 22 kW for residential applications with integrated load management and network connectivity. Its primary purpose is to enable seamless charging for diverse EV brands within shared residential environments without proprietary restrictions. Wall-mounted installations dominate unit economics due to lower trenching and foundation costs, while smart chargers with OCPP protocol support capture the fastest-growing margin pool through software subscriptions and grid services. Level 2 charger hardware remains the volume backbone, though bidirectional charging technology is emerging as the critical differentiation vector for product roadmaps.
NHTSA's Federal Motor Vehicle Safety Standards and California's Title 24 building code together shape product certification requirements and installation mandates across the US residential sector. Germany's KBA type-approval framework and the EU's F-Gas Regulation constrain refrigerant-cooled high-power designs, steering manufacturers toward passive thermal management. China's GB standards and MIIT certification govern connector interoperability and electromagnetic compatibility for units entering its domestic market. Stakeholders must monitor how utility rate structures and distributed energy resource aggregation rules reshape the business case for bidirectional-capable hardware before committing to platform architectures.
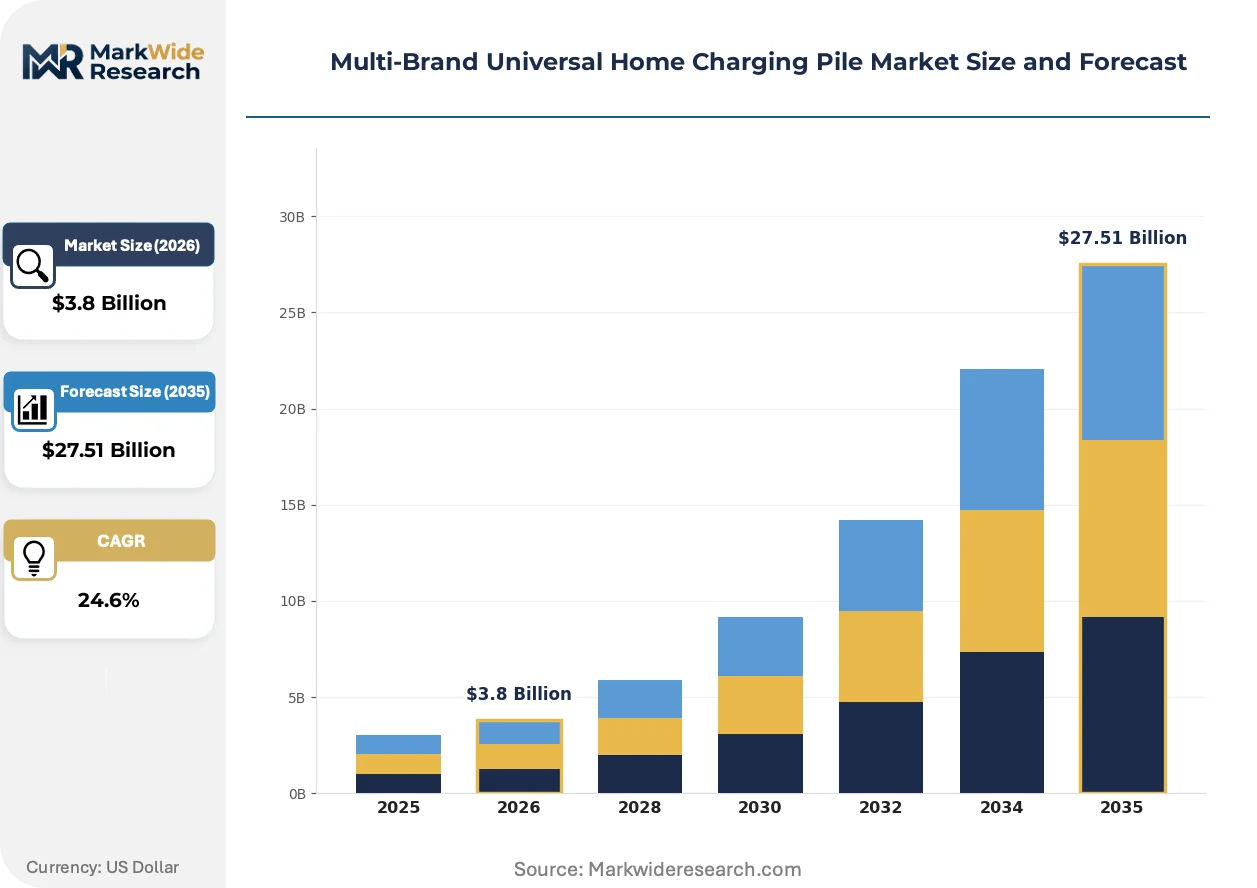
Market Dynamics
Bidirectional charging capability is modularizing product roadmaps as residential developers prioritize grid-interactive infrastructure over basic Level 2 hardware. Load management software subscriptions now command margin pools that hardware vendors cannot access through unit sales alone.
Growth Catalysts
- California's Title 24 mandate:New residential construction must include EV-ready electrical capacity, creating baseline demand for universal charging infrastructure across multi-family developments.
- Apartment penetration acceleration:Suburban multi-family dwelling adoption is hardening as EV ownership broadens beyond single-family homeowners into middle-income renters.
- China's GB standard harmonization:MIIT certification requirements for connector interoperability eliminate proprietary lock-in, enabling multi-brand hardware deployment in tier-one cities.
Market Restraints
- Copper and semiconductor input volatility:Power electronics and cabling constitute 35-40% of bill-of-materials costs, exposing manufacturers to commodity price swings without pass-through mechanisms in fixed municipal contracts.
- German KBA type-approval bottlenecks:Refrigerant-cooled high-power designs face extended certification timelines under F-Gas Regulation constraints, steering manufacturers toward passive thermal management with lower output ceilings.
- Proprietary connector ecosystem persistence:Tesla's North American Charging Standard maintains installed-base lock-in among premium single-family segments, fragmenting addressable market for truly universal hardware.
Strategic Opportunities
- India's PLI scheme for EV infrastructure:Domestic manufacturing incentives create white space for cost-optimized 7-11 kW units targeting emerging apartment markets in Bangalore and Pune.
- Vehicle-to-grid aggregation services:Convergence of bidirectional charging hardware with utility demand-response programs enables recurring revenue streams beyond equipment sales.
- Retrofit channel expansion:Electrical contractor networks are displacing traditional distributor relationships for existing building installations, capturing margin through turnkey service bundling.
Industry Challenges
- OCPP protocol certification complexity:Multi-version software compliance across utility territories extends product launch timelines and fragments firmware development resources.
- Grid interconnection standardization gaps:Utility-specific communication requirements force hardware customization for each metropolitan service territory, compressing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Brand Universal Home Charging Pile Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Charger, Level 2 Charger, Smart Charger, Portable Charger Technology: AC Charging, DC Fast Charging, Wireless Charging, Bidirectional Charging Installation: Wall-Mounted, Freestanding, Indoor, Outdoor End User: Individual Homeowners, Multi-Family Dwellings, Residential Communities, Fleet Operators |
| Companies Covered | Tesla, ChargePoint, ABB, Shell Recharge, Siemens, EVB, Wallbox, Enphase, Blink Charging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Brand Universal Home Charging Pile Market Trends and Innovations
Smart charging software is capturing value pools that hardware commoditization has relinquished. Vendors now compete on grid services integration and energy management algorithms rather than power output specifications alone.
Power electronics architecture is modularizing as silicon carbide MOSFETs replace IGBT-based designs in residential-rated inverters. Tier-one suppliers in Shenzhen and Munich are adopting these wide-bandgap semiconductors for 22 kW peak output with passive cooling. This thermal efficiency breakthrough is modularizing enclosure designs, enabling wall-mounted form factors that trenching-intensive pedestal installations cannot match.
Germany's F-Gas Regulation is constraining refrigerant-based thermal management in high-power residential units. Manufacturers must now certify passive cooling architectures under KBA type-approval frameworks that prioritize electromagnetic compatibility over raw output density. European product roadmaps are responding with split-phase power distribution and derated continuous operation modes.
Community association procurement is consolidating vendor selection across multi-family portfolios. Property managers in China's tier-one cities and Germany's Rhine-Ruhr corridor now specify OCPP-compliant hardware with centralized billing integration, displacing individual unit purchases by residents. This buyer concentration is compressing sales cycles but demanding white-label software customization and multi-year service commitments.
Multi-Brand Universal Home Charging Pile Market Segmentation
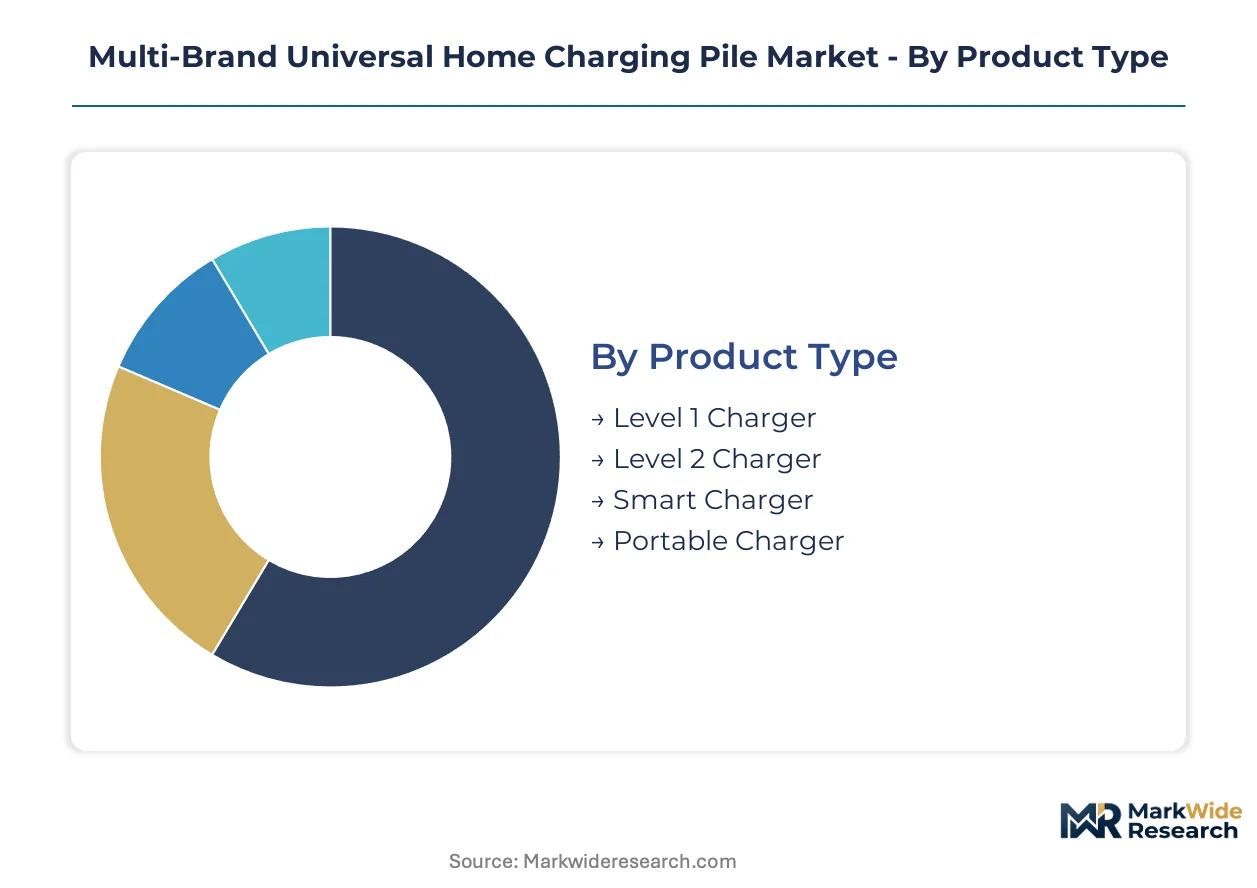
Segmentation in the multi-brand universal home charging pile market reveals how hardware specifications, installation constraints, and user environments shape procurement decisions. Developers and property managers prioritize interoperability and load management capabilities over raw power output, while individual buyers balance upfront costs against future-proofing for bidirectional functionality.
Product Type:
Volume concentrates in standardized Level 2 hardware, while premium margins accrue to software-integrated smart chargers with grid-service subscriptions.
- Level 1 Charger:120-volt residential units deliver 1.4-1.9 kW through standard household outlets, limiting deployment to legacy electrical infrastructure in older apartment buildings where panel upgrades are cost-prohibitive. Demand clusters in US suburban retrofits where NHTSA safety compliance can be met without dedicated circuit installation.
- Level 2 Charger:240-volt AC units rated 7-22 kW constitute the residential backbone, with silicon carbide MOSFET architectures enabling passive cooling at 22 kW peak output. China's tier-one cities and Germany's Rhine-Ruhr corridor specify these for multi-family new construction under MIIT and KBA certification frameworks.
- Smart Charger:OCPP-protocol units with cloud connectivity and dynamic load balancing command recurring software revenue streams.
- Portable Charger:Detachable cord sets with interchangeable connector heads address renter mobility and travel use cases.
Mature deployment sits with Level 2 hardware. Newer deployment is concentrated in smart chargers with vehicle-to-grid integration.
Technology:
AC charging dominates unit economics through established power electronics, while bidirectional capability is reshaping product roadmaps for grid-interactive residential developments.
- AC Charging:Alternating current delivery at 7-22 kW leverages existing residential distribution infrastructure, minimizing trenching and transformer upgrade costs. California's Title 24 mandate drives specification in suburban multi-family developments where electrical capacity must serve multiple parking spaces.
- Bidirectional Charging:Vehicle-to-grid and vehicle-to-home power flow enables residential energy arbitrage and emergency backup, with hardware premiums justified by utility demand-response revenue streams. Germany's F-Gas Regulation steers manufacturers toward passive thermal management for these higher-complexity inverters.
- DC Fast Charging:Residential-rated 50+ kW units remain niche due to three-phase power requirements.
- Wireless Charging:Inductive pad systems eliminate connector wear but carry efficiency penalties and higher BOM costs.
AC charging anchors current procurement volumes. Bidirectional systems are expanding most quickly in European markets with aggregated grid services frameworks.
Installation:
Wall-mounted configurations minimize civil works expenditure, while freestanding pedestals command trenching premiums that alter project financing structures.
- Wall-Mounted:Bracket-attached enclosures reduce foundation and conduit costs by 60-70% versus pedestal alternatives, with Shenzhen and Munich suppliers modularizing silicon carbide inverter designs for this form factor. China's high-rise residential towers specify these for basement parking integration.
- Outdoor:NEMA 3R/IP54-rated enclosures with conformal-coated electronics withstand temperature cycling and moisture ingress. Germany's KBA type-approval mandates electromagnetic compatibility testing for outdoor electromagnetic environments.
- Freestanding:Pedestal installations serve surface parking lots without structural wall proximity.
- Indoor:Garage-integrated units prioritize compact footprints and reduced noise signatures.
Wall-mounted hardware captures the standard deployment model. Outdoor-rated systems are gaining share fastest in climates with extreme temperature variation.
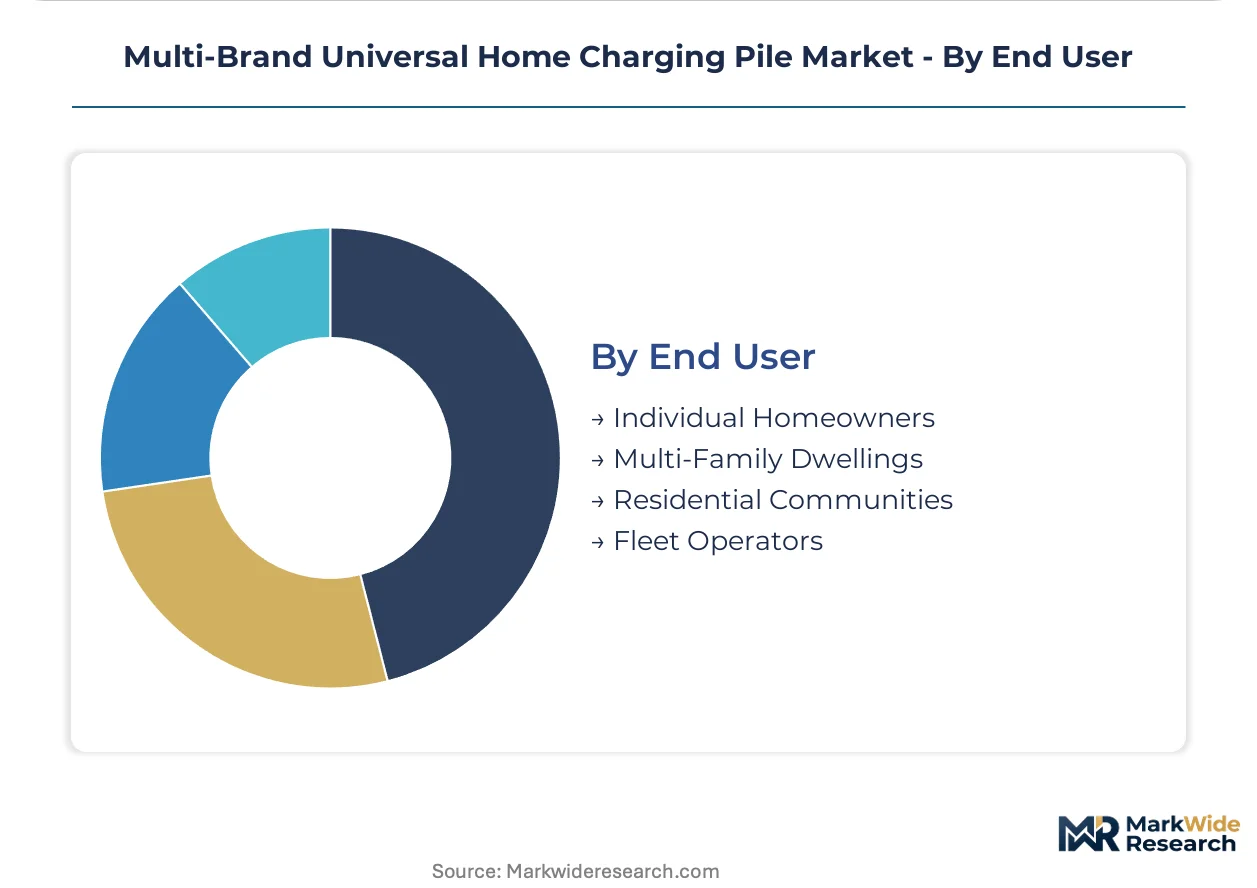
End User:
Multi-family dwelling procurement is consolidating vendor relationships, while individual homeowners retain fragmented purchasing patterns through retail channels.
- Multi-Family Dwellings:Property managers across China's tier-one cities and Germany's Rhine-Ruhr metropolitan corridor specify OCPP-compliant hardware with centralized billing platforms, displacing resident-purchased units. California's Title 24 mandate creates baseline demand for EV-ready electrical capacity in new suburban construction.
- Residential Communities:Homeowner associations negotiate portfolio-level service contracts with white-label software customization and multi-year maintenance commitments.
- Individual Homeowners:Single-family detached purchases favor plug-and-play simplicity over grid-interactive features.
- Fleet Operators:Residential fleet depots require high-availability scheduling and priority charging algorithms.
Individual homeowners represent established demand. Multi-family dwellings are climbing the fastest as EV ownership broadens beyond early adopter demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-family dwelling developers in China's tier-one cities and Germany's Rhine-Ruhr corridor are consolidating procurement volumes faster than single-family markets. California's Title 24 mandate and the EU's building performance directives are hardening regulatory baselines for EV-ready infrastructure.
United States
California's Title 24 building code mandates EV-capable electrical infrastructure in all new residential construction, creating baseline demand across suburban multi-family developments. NHTSA's Federal Motor Vehicle Safety Standards govern connector safety certification for units entering interstate commerce. The San Francisco Bay Area and Los Angeles metropolitan clusters anchor deployment volumes where apartment penetration rates outpace national averages.
Germany
The Rhine-Ruhr metropolitan corridor concentrates multi-family dwelling adoption as EV ownership broadens beyond early adopter demographics into middle-income rental segments. Germany's KBA type-approval framework and the EU's F-Gas Regulation constrain refrigerant-cooled high-power designs, steering manufacturers toward passive thermal management. Munich and Stuttgart industrial clusters host silicon carbide inverter development for 22 kW wall-mounted units.
China
MIIT certification requirements for GB standard connector interoperability eliminate proprietary lock-in, enabling multi-brand hardware deployment in Shanghai, Beijing, and Shenzhen. The country's dual carbon goals accelerate EV-ready mandates in new high-rise residential construction. Shenzhen suppliers are modularizing wide-bandgap semiconductor architectures for basement parking integration in tier-one city towers.
India
The PLI scheme for EV infrastructure creates white space for cost-optimized 7-11 kW units targeting emerging apartment markets in Bangalore and Pune. State-level building code amendments in Maharashtra and Karnataka are beginning to mirror California's EV-ready mandates. Domestic manufacturing incentives are drawing component suppliers to the Chennai and Pune industrial corridors.
Multi-Brand Universal Home Charging Pile Market Competitive Landscape
Chinese producers anchor one tier through Shenzhen and Shanghai manufacturing clusters; European specialists hold certification advantages under KBA and CE frameworks. The vendor base organizes around three strategic archetypes: automotive OEMs with proprietary connector ecosystems, industrial electrical incumbents with grid-interactive capabilities, and pure-play charging network operators with software subscription models. Dominant competitive moves include bidirectional charging technology licensing and vertical integration into load management software platforms.
Within the automotive-anchored tier, Tesla represents proprietary ecosystem lock-in through its North American Charging Standard. ChargePoint and ABB exemplify contrasting positioning strategies—ChargePoint sits within the open-network operator archetype, while ABB occupies the industrial-grade reliability segment. These three companies collectively illustrate how competitive positioning fragments across connector philosophy, thermal management approach, and grid services integration depth.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| Shell Recharge |
| Siemens |
| EVB |
| Wallbox |
| Enphase |
| Blink Charging |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration across power electronics and software platforms anchors supply position and pricing power for multi-brand universal home charging pile vendors. Shenzhen and Munich manufacturing clusters feed wall-mounted hardware with silicon carbide MOSFET architectures, while OCPP-compliant load management software creates recurring revenue streams that hardware margins cannot match.
Pricing Analysis
Volume concentrates in standardized Level 2 hardware while premium margins accrue to smart chargers with grid-service subscriptions. Three-tier pricing structure across premium bidirectional units, standard OCPP-compliant hardware, and economy Level 2 chargers reflects certification grade and after-sales bundling differentiation. Cost compression in economy tiers intensifies because copper and semiconductor input volatility lacks pass-through mechanisms in fixed municipal contracts. Multi-family dwelling developers exhibit highest price sensitivity due to portfolio-scale procurement, while individual homeowners in premium segments show lowest sensitivity for bidirectional-capable units.
Supply Chain Analysis
Dual-sourcing requirements from German KBA and Chinese MIIT certification frameworks mandate multi-supplier qualification for power electronics and thermal management components. Manufacturing gravity centers on China, Germany, and the United States, with Shenzhen suppliers dominating silicon carbide inverter production and Munich clusters specializing in passive cooling architectures. Bill-of-materials rests on copper cabling, semiconductor power modules, and conformal-coated circuit boards. Single-source vulnerability concentrates in wide-bandgap semiconductor foundries. Distribution runs through electrical contractor networks displacing traditional distributor relationships for retrofit channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into load management software platforms and silicon carbide inverter production represents the critical upstream lever shaping competitive durability. Incumbents and challengers alike must secure captive supply of power electronics or SaaS revenue streams to defend margin position.
For Market Incumbents: Acquire OCPP software development teams and bidirectional charging IP portfolios to consolidate grid-services revenue streams. Defend against pure-play charging network operators by embedding load management algorithms directly into hardware firmware, neutralizing their SaaS-tiered pricing advantage. Secure KBA and MIIT certification pipelines in Munich and Shenzhen manufacturing clusters to maintain regulatory moats against emerging Asian challengers. For New Entrants and Emerging Players: Launch via electrical contractor networks in India's Bangalore and Pune apartment markets, bypassing established distributor relationships that incumbent vendors control. White-label OCPP-compliant hardware for property management platforms in China's tier-one cities, capturing multi-family dwelling procurement consolidation before branded vendors lock in long-term service contracts. Target cost-optimized 7-11 kW units under India's PLI scheme manufacturing incentives. For Investors and Strategic Acquirers: Exit pathways concentrate in industrial electrical incumbents seeking grid-interactive capabilities and automotive OEMs pursuing charging infrastructure vertical integration. Long-term viability hinges on software subscription attach rates rather than hardware shipment volumes. Monitor utility demand-response program rollouts as the inflection signal for bidirectional charging hardware adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Bidirectional Charging Technology Licensing | Enables vehicle-to-grid revenue streams under Germany's F-Gas Regulation constraints. |
| Silicon Carbide Inverter Manufacturing Scale-Up | Reduces thermal management costs for 22 kW wall-mounted units in Shenzhen clusters. |
| OCPP Software Platform Integration | Captures recurring margins from multi-family dwelling load management subscriptions. |
| Electrical Contractor Network Partnership | Displaces distributor relationships for existing building retrofit channel expansion. |
| MIIT and KBA Certification Investment | Secures type-approval access for China's tier-one cities and Germany's Rhine-Ruhr corridor. |
Research Methodology
SEC filings from charging infrastructure vendors, NHTSA safety certification databases, and MIIT GB standard documentation formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with property managers at multi-family developments, electrical contractors specializing in EV-ready retrofits, and procurement leads at OEM charging divisions validated demand assumptions and pricing dynamics. Bottom-up unit shipment estimates across Level 2, smart charger, and bidirectional hardware categories triangulated against top-down addressable parking space calculations in California, Germany, and China regulatory zones.
Historical trendline analysis of EV-ready building code adoption curves and silicon carbide MOSFET cost reduction trajectories informed the projection framework. Segmentation modeling incorporated product type, installation configuration, end-user archetype, and regional regulatory cluster dimensions. CAGRs derived from S-curve technology diffusion parameters applied to multi-family dwelling penetration rates and fleet operator deployment schedules. Bidirectional charging hardware premiums and software subscription attach rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for vehicle-to-grid aggregation services would alter the outlook if utility rate structures fail to remunerate distributed energy resource participation. Forecasts reflect assumptions about copper price stabilization and semiconductor supply chain normalization. Deviation in California Title 24 enforcement intensity or China's dual carbon goal acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market