
 EV Solar Charging Wallbox Market | 2026-2036
EV Solar Charging Wallbox Market Size, Share, and Industry Trends Forecast 2026-2036
EV Solar Charging Wallbox Market Insights
The EU Green Deal is pivoting the cost-of-entry calculus for wallbox manufacturers by embedding carbon-accounting requirements into product certification. Tesla leverages its Supercharger ecosystem to anchor proprietary wallbox sales in North American markets. Wallbox competes through aggressive channel control across European retail networks. SolarEdge Technologies specializes in hybrid inverter-integrated charging units that merge photovoltaic conversion with vehicle power delivery.
An EV solar charging wallbox is a grid-connected or off-grid electrical interface that converts direct current from photovoltaic arrays into alternating current compatible with electric vehicle battery management systems, typically operating at 7–22 kW residential and 50–350 kW commercial power levels. Its primary commercial purpose is to enable behind-the-meter charging that minimizes grid dependency and reduces time-of-use electricity exposure. Home chargers dominate installed base volume while fast chargers capture disproportionate margin pools due to hardware complexity and installation service bundling. Smart charging technology is displacing basic timer-based units as utilities introduce dynamic rate structures and vehicle-to-grid protocols.
FCC certification governs wireless connectivity modules in US wallbox units while CE marking mandates electromagnetic compatibility across European deployments. California's Title 24 building standards and Germany's KBA type-approval framework are accelerating product standardization by requiring bidirectional-capable hardware in new construction. Stakeholders must monitor how utility interconnection rules evolve around vehicle-to-grid export permissions, as this regulatory boundary will determine which technology architectures achieve scalable deployment.
Market Dynamics
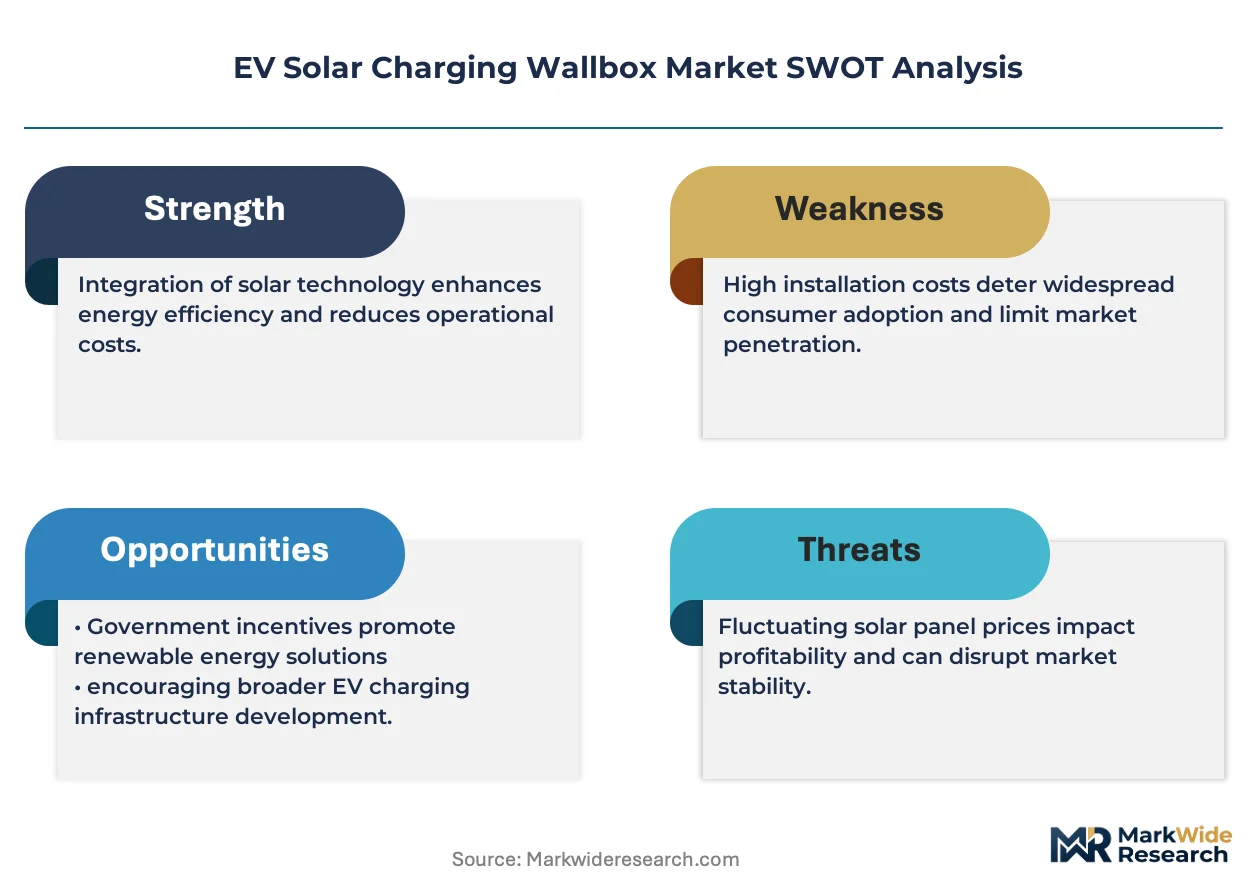
California's Title 24 mandate for solar-ready EV infrastructure in new residential construction is compressing product development cycles and forcing hardware standardization across the supplier base.
Growth Catalysts
- Building Energy Code Mandates:Germany's KBA type-approval framework and California's Title 24 standards now require bidirectional-capable wallbox hardware in new construction, pulling demand forward.
- Vehicle-to-Grid Protocol Maturation:Utility interconnection rule evolution around export permissions is enabling behind-the-meter energy arbitrage for residential solar owners.
- Distributed Generation Convergence:Suburban districts in Shanghai, Munich, and San Diego exhibit concentrated demand where rooftop photovoltaic adoption overlaps with electric vehicle penetration.
Market Restraints
- Semiconductor Input Volatility:Power electronics and wireless connectivity modules face supply concentration risk from limited foundry capacity.
- Installation Service Bottlenecks:Certified electrician shortages in Germany and California extend deployment timelines and inflate project costs.
- Grid Interconnection Friction:Utility approval processes for bidirectional export remain inconsistent across US states and EU member countries.
Strategic Opportunities
- Hybrid Inverter Integration:Convergence of photovoltaic DC-AC conversion with vehicle power delivery eliminates redundant hardware and reduces balance-of-system costs.
- Commercial Fleet Electrification:Workplace and depot charging installations at 50-350 kW power levels capture disproportionate margin pools through service bundling.
- Dynamic Rate Structure Alignment:Utility time-of-use tariffs create arbitrage value for smart charging systems with vehicle-to-home capability.
Industry Challenges
- FCC and CE Certification Timelines:Electromagnetic compatibility testing for wireless modules creates 4-6 month product launch delays.
- Legacy Electrical Infrastructure Retrofit:Residential panel upgrades and service entrance modifications add unpredictable soft costs to installation projects.
- Cross-Standard Interoperability:Multiple vehicle communication protocols complicate firmware development and testing matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Solar Charging Wallbox Market |
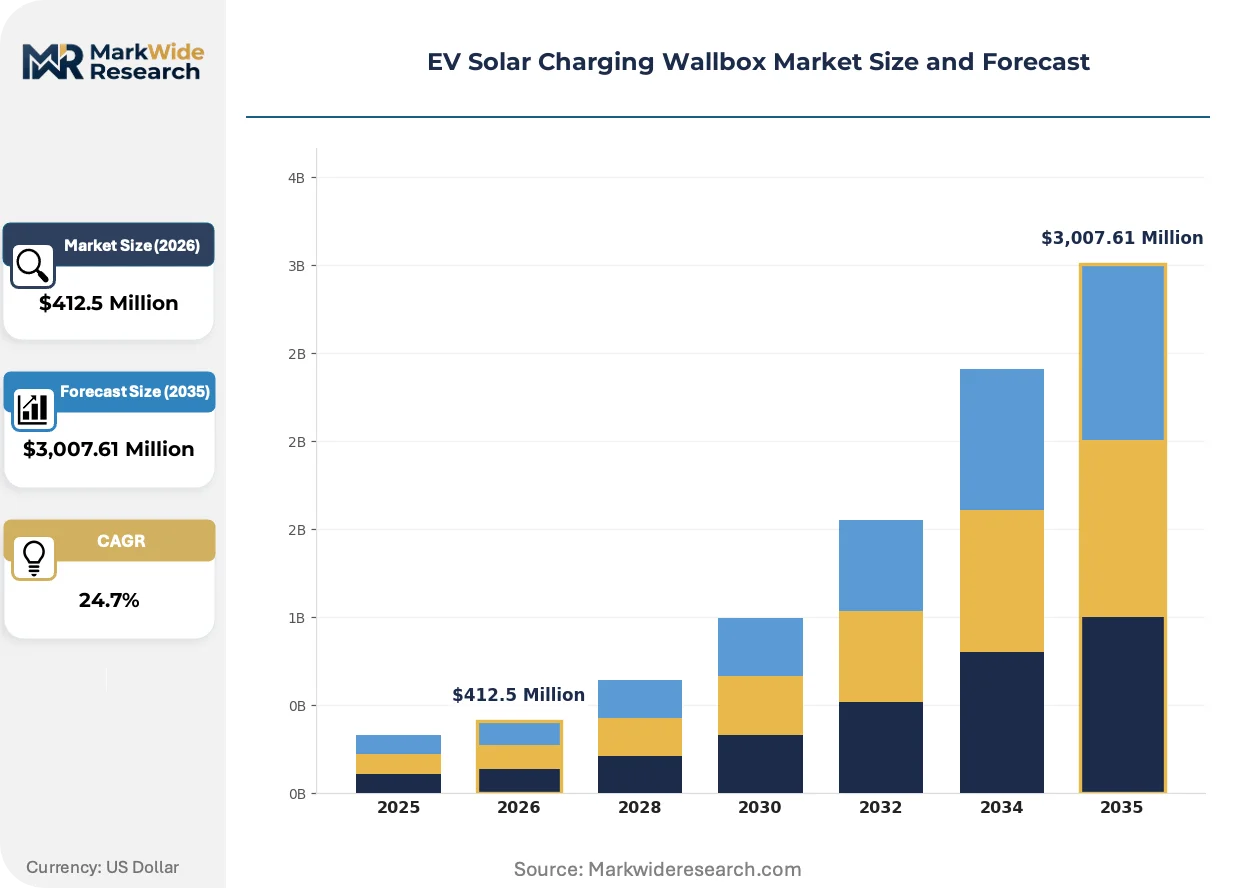
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,007.61 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Chargers, Commercial Chargers, Fast Chargers, Portable Chargers Technology: Solar Photovoltaic, Hybrid Systems, Smart Charging, DC Fast Charging Installation: Wall-Mounted, Free Standing, Embedded, Outdoor Solutions End User: Residential Users, Fleet Operators, Businesses, Charging Networks |
| Companies Covered | Tesla, ChargePoint, Wallbox, EVBox, Envision Solar, SolarEdge Technologies, SunPower, KEBA, go-e Charger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Solar Charging Wallbox Market Trends and Innovations
Smart charging technology is compressing the installed base of basic timer-based units as dynamic rate structures and grid-interactive protocols become standard utility offerings.
Hybrid inverter-integrated wallbox units are consolidating photovoltaic conversion and vehicle power delivery into single hardware platforms. Residential homeowners with rooftop arrays are adopting these systems to eliminate redundant AC-DC conversion losses. This consolidation is compressing supplier margins for standalone charger manufacturers while rewarding electrical equipment conglomerates with captive inverter technology.
The EU Green Deal is embedding carbon-accounting requirements into product certification frameworks for wallbox manufacturers. CE marking mandates now extend to lifecycle emissions disclosure, altering procurement criteria for public infrastructure tenders. European retail networks are responding by prioritizing suppliers with verified supply chain transparency.
Buyer preference is rotating toward bundled installation and maintenance contracts rather than hardware-only transactions. Channel partners in suburban US and German markets are unbundling after-sales service from equipment margins to capture recurring revenue streams. This shift is most visible in California and Bavaria where contractor certification requirements create service provider scarcity.
EV Solar Charging Wallbox Market Segmentation
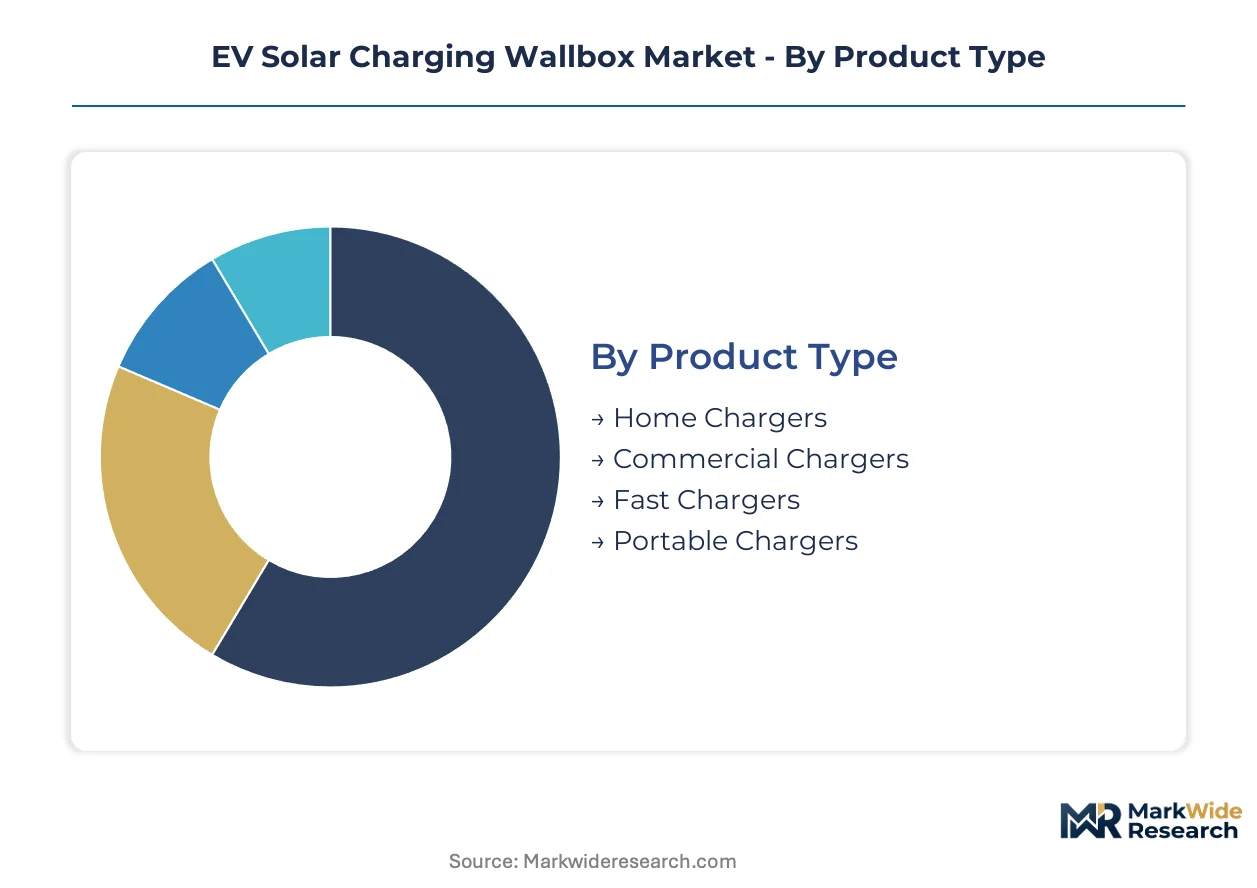
Segmentation in the EV solar charging wallbox market reveals divergent margin structures across power classes and installation contexts. Hardware suppliers calibrate R&D allocation differently for residential volume plays versus commercial service bundles.
Product Type:
Home chargers dominate unit volume while fast chargers command premium pricing through complexity and installation bundling.
- Home Chargers:These units operate at 7–22 kW power levels for residential garages and driveways. Demand concentrates in suburban districts of Shanghai, Munich, and San Diego where rooftop photovoltaic arrays overlap with electric vehicle ownership. California's Title 24 mandate for solar-ready infrastructure in new construction is pulling demand forward for bidirectional-capable residential hardware.
- Commercial Chargers:Workplace and depot installations at 50–350 kW serve fleet electrification and employee charging programs. Fleet operators in Germany's industrial corridors negotiate bundled installation and maintenance contracts rather than hardware-only transactions, capturing recurring revenue streams through service provider scarcity.
- Fast Chargers:High-power DC units eliminate AC-DC conversion losses through direct battery coupling. Highway corridor deployments and urban charging hubs require utility interconnection approvals that remain inconsistent across jurisdictions.
- Portable Chargers:Mobile units with photovoltaic-integrated storage target off-grid and emergency applications. Recreational vehicle owners and remote workforce segments represent niche adoption.
Today's leader: Home Chargers. Tomorrow's challenger: Fast Chargers.
Technology:
Smart charging protocols are displacing basic timer-based units as utilities introduce dynamic rate structures and vehicle-to-grid export permissions.
- Solar Photovoltaic:Direct DC coupling from rooftop arrays eliminates grid dependency for daytime charging. Residential homeowners in distributed generation clusters prioritize these systems to minimize time-of-use electricity exposure.
- Hybrid Systems:Convergence of photovoltaic DC-AC conversion with vehicle power delivery consolidates redundant hardware. SolarEdge Technologies and electrical equipment conglomerates with captive inverter technology capture margin from this consolidation while standalone charger manufacturers face compression.
- Smart Charging:Grid-interactive protocols enable demand response and energy arbitrage. Utility rate structure evolution around vehicle-to-home capability creates value pools for bidirectional hardware.
- DC Fast Charging:Direct current delivery bypasses onboard vehicle converters for rapid replenishment. Commercial fleet operators and highway charging networks drive specification requirements for 350 kW peak output.
Smart Charging is climbing the fastest as regulatory frameworks mature around export permissions and dynamic pricing.
Installation:
Certified electrician shortages in Germany and California extend deployment timelines and inflate soft costs across mounting configurations.
- Wall-Mounted:Bracket-attached units maximize space efficiency in residential garages and commercial parking structures. This configuration dominates retrofits where existing electrical infrastructure requires minimal modification.
- Free Standing:Pedestal and bollard designs serve outdoor parking lots and curbside deployment. Municipal charging networks in European retail corridors favor this format for public accessibility.
- Embedded:Flush-mounted integration with building architecture targets premium residential and commercial developments. New construction mandates in California and Germany accelerate specification for solar-ready embedded infrastructure.
- Outdoor Solutions:Weather-hardened enclosures with IP65+ ratings withstand coastal and extreme climate exposure. San Diego's coastal districts and Shanghai's humid subtropical conditions drive material specification requirements.
Wall-Mounted retains the largest installed base. Embedded is gaining share fastest through building code mandates.
End User:
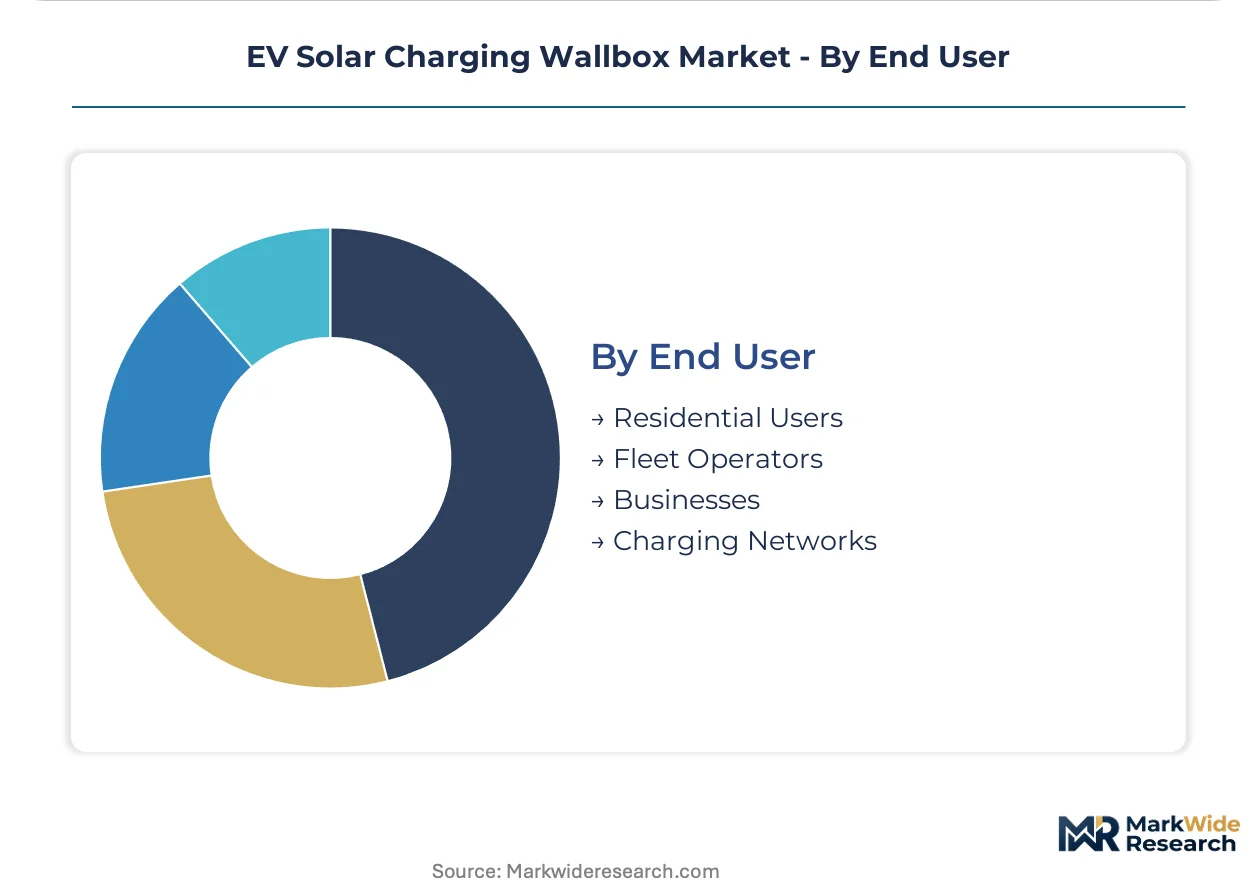
Residential homeowners with rooftop solar arrays represent the volume foundation while fleet operators capture disproportionate margin through service bundling.
- Residential Users:Single-family homeowners with distributed generation assets seek behind-the-meter charging independence. Suburban districts where photovoltaic adoption overlaps with electric vehicle penetration exhibit concentrated demand.
- Fleet Operators:Commercial vehicle depots and workplace charging programs require 50–350 kW infrastructure with predictable uptime guarantees. Service provider scarcity in Germany and California creates pricing power for certified installation contractors.
- Businesses:Corporate campuses and retail locations deploy charging as employee benefit and customer amenity. Workplace installations in Munich's industrial suburbs anchor recurring maintenance contract revenue.
- Charging Networks:Multi-site operators aggregate demand across highway corridors and urban hubs. Utility interconnection friction for bidirectional export complicates network-scale deployment planning.
Residential Users anchor current volume. Fleet Operators present the steepest expansion trajectory as commercial electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified electricians and solar installation technicians concentrate in suburban districts where distributed generation and electric vehicle ownership overlap. Workforce scarcity in these clusters extends deployment timelines and inflates soft costs. Regional demand patterns track building code mandates and utility interconnection rule evolution.
United States
Residential homeowners with rooftop arrays in San Diego and California's coastal suburbs drive hardware demand for bidirectional-capable units. California's Title 24 building standards mandate solar-ready EV infrastructure in new construction, pulling demand forward. Certified electrician shortages in the state extend installation timelines and create pricing power for contractors.
Germany
Munich's industrial suburbs and Bavarian residential districts exhibit concentrated demand where photovoltaic adoption overlaps with electric vehicle penetration. Germany's KBA type-approval framework requires bidirectional-capable wallbox hardware in new construction, accelerating product standardization. Fleet operators in industrial corridors negotiate bundled installation contracts due to service provider scarcity.
China
Suburban districts of Shanghai demonstrate demand concentration where distributed generation and electric mobility converge. The country's national energy regulator advances vehicle-to-grid protocol standards for behind-the-meter energy arbitrage. Yangtze River Delta manufacturing clusters supply power electronics components to domestic and export markets.
Japan
Residential solar owners in Kanto and Kansai regions seek charging independence through behind-the-meter systems. METI promotes smart charging interoperability standards for grid-interactive protocols. Osaka-area industrial suburbs anchor early adoption of hybrid inverter-integrated units.
Australia
Sydney and Melbourne metropolitan solar households drive residential charger volume in distributed generation clusters. State-level building efficiency codes in New South Wales and Victoria accelerate solar-ready infrastructure specifications. Coastal climate exposure drives material specification requirements for weather-hardened enclosures.
EV Solar Charging Wallbox Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware and software layers. The supplier base organizes into three strategic archetypes: electrical equipment conglomerates with captive inverter technology, standalone charging hardware manufacturers, and integrated energy platform operators. Dominant competitive moves include hybrid inverter convergence to eliminate redundant hardware and channel control strategies to capture recurring service revenue.
Within the integrated platform tier, Tesla and ChargePoint occupy positions that exemplify ecosystem anchoring through proprietary charging networks. Wallbox represents the focused European specialist archetype with retail channel concentration. SolarEdge Technologies sits within the electrical equipment conglomerate category, leveraging captive inverter technology for hybrid system integration.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| Wallbox |
| EVBox |
| Envision Solar |
| SolarEdge Technologies |
| SunPower |
| KEBA |
| go-e Charger |
| Others |
Pricing and Supply Chain Analysis
Backward integration into power electronics manufacturing anchors supplier pricing power for electrical equipment conglomerates while compressing margins for standalone charger vendors dependent on merchant semiconductor sourcing. California's Title 24 mandate and Germany's KBA framework accelerate demand for bidirectional-capable hardware, shifting procurement criteria toward certified installation bundling.
Pricing Analysis
The bundled-versus-unbundled service split separates premium hardware suppliers from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service scope. Price differentiation reflects CE marking complexity and FCC wireless module testing timelines. Cost compression in residential segments intensifies because certified electrician shortages inflate installation soft costs. Fleet operators exhibit lowest price sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Direct-to-installer channels handle residential demand while fleet operators negotiate direct OEM relationships for 50-350 kW systems. Power electronics concentrate in China, Taiwan, and South Korea. Silicon carbide MOSFETs, wireless connectivity modules, and weather-hardened enclosure materials feed from concentrated foundry capacity. Single-source vulnerability in semiconductor inputs threatens production continuity. Distribution runs through certified electrical contractors in California and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hybrid inverter convergence and recurring service revenue capture as hardware commoditization pressures standalone manufacturers. Bidirectional capability certification and installation bundling shift value toward integrated platform operators.
For Market Incumbents: Cement channel control across certified installer networks in California and Germany to defend against emerging hybrid inverter specialists. Deepen captive supply of power electronics through foundry partnerships in Taiwan and South Korea. Prioritize KBA and FCC pre-certification investment to compress product launch timelines against regulatory acceleration. For New Entrants and Emerging Players: California's Title 24 mandate opens a window for solar-ready embedded infrastructure targeting new residential construction. White-space concentrates in commercial fleet depot charging at 50-350 kW power levels where service provider scarcity creates pricing power. Pursue direct utility partnership models for vehicle-to-grid protocol early adoption. For Investors and Strategic Acquirers: Roll-up economics work for electrical equipment conglomerates with captive inverter technology because hybrid system integration eliminates redundant hardware and captures margin compression from standalone charger manufacturers. Target mid-scale installers with certified contractor networks in suburban Munich and San Diego districts. Monitor utility interconnection rule evolution around export permissions as inflection indicator for bidirectional hardware scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Inverter Integration | Consolidates photovoltaic conversion with vehicle power delivery, eliminating redundant AC-DC conversion losses. |
| Certified Installer Network Acquisition | Captures recurring service revenue streams where electrician shortages create provider scarcity. |
| Bidirectional Hardware Certification | Positions suppliers for California Title 24 and Germany KBA mandate compliance in new construction. |
| Utility Partnership for V2G Protocols | Enables behind-the-meter energy arbitrage as interconnection rules mature around export permissions. |
| Power Electronics Foundry Investment | Secures silicon carbide MOSFET supply against semiconductor input volatility and single-source risk. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster combined with secondary validation. Interviews with wallbox product managers, certified electrical contractors, utility interconnection officers, and fleet procurement directors anchor qualitative assessment. Secondary sources include EIA capacity data, IEA electric vehicle outlooks, FERC interconnection filings, and building code regulatory databases. Bottom-up unit economics triangulate against top-down market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from value-per-unit shifts across power class segments. Modeled dimensions include product type, technology protocol, installation configuration, and end-user archetype. CAGRs derive from segment-level growth trajectory blending. Forecast inputs incorporate utility rate structure evolution and vehicle-to-grid protocol maturation timelines without year-specific anchoring.
Revisions become necessary when semiconductor supply disruptions, building code acceleration, or utility interconnection rule reversals materialize. Forecasts reflect assumptions about bidirectional hardware adoption curves and certified workforce expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Car Charging Pile Market
Electric Vehicle Charging
Charging As a Service Market