
 Electric Vehicle (EV) Charging Station Operation Market | 2026-2036
Electric Vehicle (EV) Charging Station Operation Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Charging Station Operation Market Insights
Project finance tied to long-term power purchase agreements is fragmenting capital requirements across smaller regional operators and infrastructure funds. ChargePoint leverages its software-agnostic platform to sustain deployment velocity without owning underlying grid assets. Tesla anchors the supercharging segment through proprietary connector standards and captive vehicle demand. Shell Recharge competes by integrating forecourt conversions with renewable energy certificates across European markets.
Electric Vehicle Charging Station Operation encompasses the ownership, management, and monetization of energy dispensing infrastructure for battery electric vehicles, typically involving power electronics rated from 7 kW AC residential units to 350 kW DC fast chargers with liquid-cooled cables. The primary commercial purpose is to deliver measurable, billable energy transfer while optimizing asset utilization through dynamic pricing and grid integration protocols. DC Fast Charging occupies the highest margin pool due to premium pricing and fleet dependency, while Destination Charging extends utilization through hospitality and retail tie-ins. Public Charging dominates transaction volume but faces utilization rate pressures that Private Charging avoids through subscription models.
The EU Green Deal and national building codes mandating EV-ready parking in France, Germany, and Spain are reshaping installation obligations for developers and landlords. NHTSA corridor designations and EPA emissions credit frameworks in the United States steer federal funding toward interstate highway networks rather than urban saturation. Stakeholders must monitor how ISO 15118 plug-and-charge standards alter payment friction and customer retention economics as interoperability mandates expand.
Market Dynamics
ISO 15118 plug-and-charge protocols are eliminating payment friction and recalibrating customer retention economics across European charging networks. This standardization force is compressing operator margins while accelerating infrastructure interoperability mandates from Germany to the Netherlands.
Growth Catalysts
- EU Green Deal infrastructure obligations:France, Germany, and Spain now mandate EV-ready parking in new construction, forcing developers to pre-wire commercial and residential assets for future charging demand.
- Last-mile fleet electrification:Logistics operators across urban corridors are converting delivery van pools to electric, creating captive demand for high-utilization DC fast charging hubs.
- Autobahn corridor deployment:German federal-state partnerships are funding 350 kW charging stations along highway networks to eliminate range anxiety for long-haul passenger and freight traffic.
Market Restraints
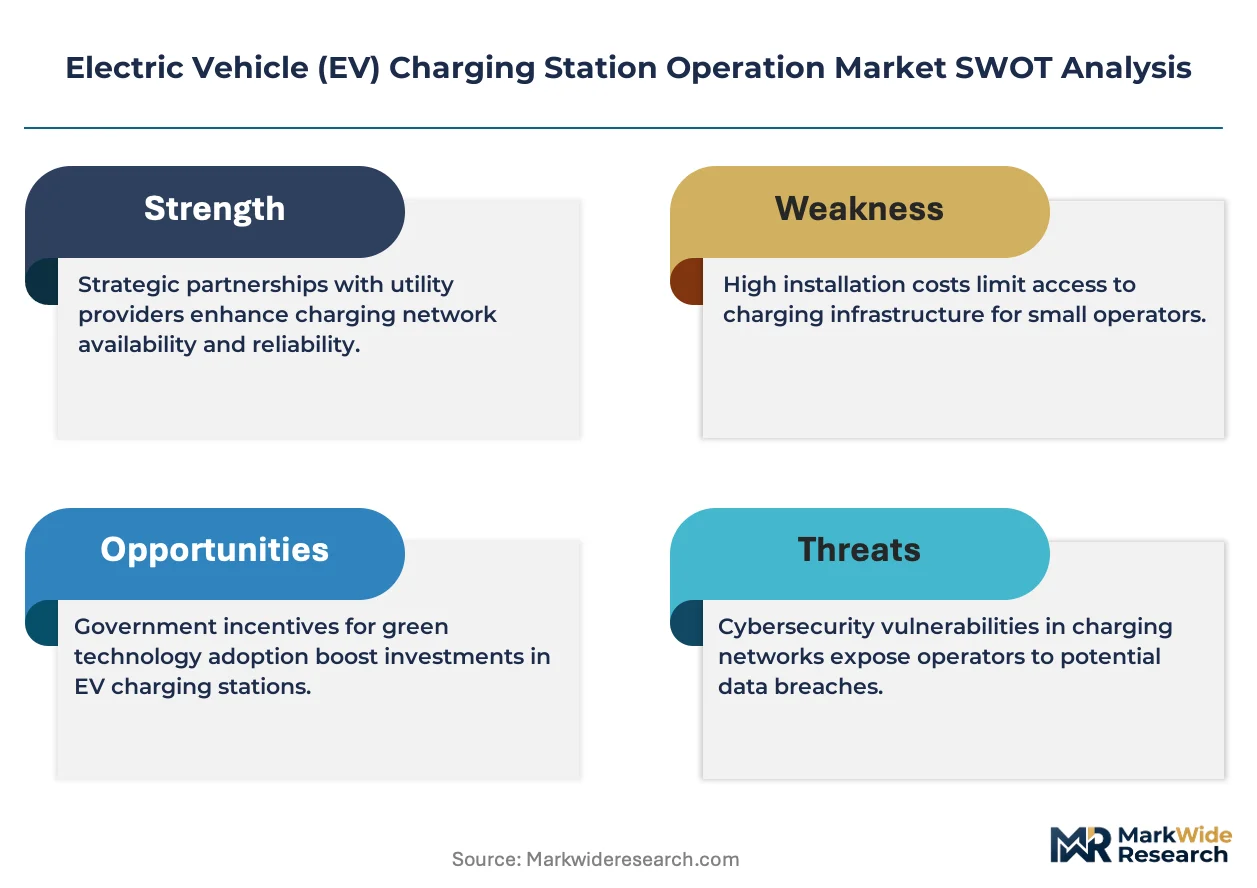
- Grid connection queuing delays:Distribution network operators in the Netherlands and Belgium face 18-24 month backlogs for new high-capacity connections, freezing site development timelines.
- Copper and silicon carbide supply concentration:Power electronics manufacturing depends on Chinese-processed rare earth refining and German wafer fabrication, exposing operators to input volatility.
- Proprietary connector fragmentation:Tesla's NACS standard competes with CCS2 across European markets, forcing multi-cable hardware investments that inflate capex per stall.
Strategic Opportunities
- Polish and Romanian highway corridors:These member states lag Germany and France in charging density, creating first-mover positioning for operators securing TEN-T network funding.
- Vehicle-to-grid integration:Bidirectional charging hardware converging with home energy management systems opens revenue stacking through frequency regulation services.
- Building code retrofit mandates:Germany's KfW subsidy program and France's RE2020 regulations are forcing existing commercial parking structures to install charging infrastructure during renovation cycles.
Industry Challenges
- Power electronics technician scarcity:Specialized maintenance skills for liquid-cooled 350 kW cable systems and inverter diagnostics outpace vocational training output in France and Germany.
- CE certification timelines:New charger models face 8-14 month approval windows under the EU Machinery Directive and EMC harmonized standards, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Charging Station Operation Market |
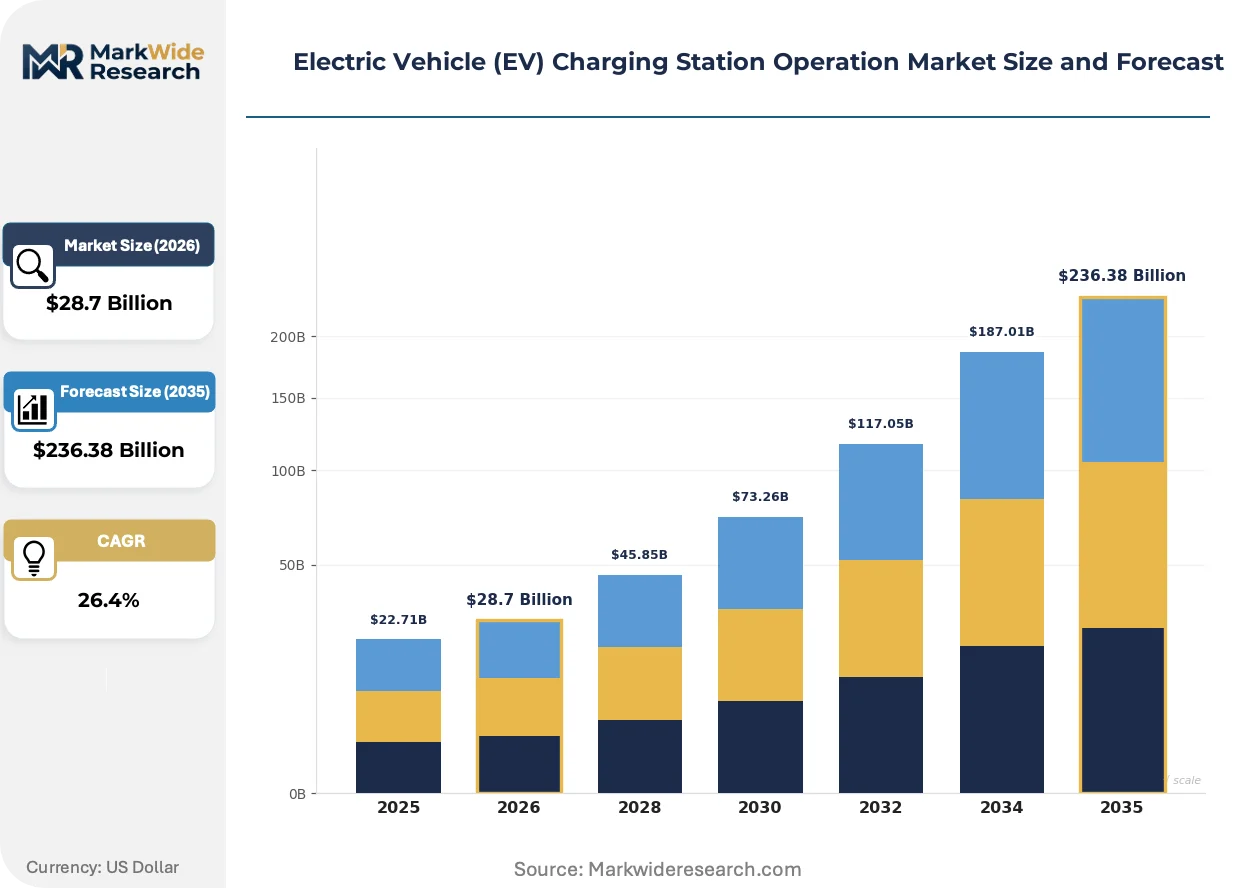
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $236.38 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: AC Charging, DC Fast Charging, Wireless Charging, Supercharging Service Type: Public Charging, Private Charging, Fleet Charging, Destination Charging Installation Type: On-Street Charging, Off-Street Charging, Home Charging, Commercial Charging Customer Type: Individual Consumers, Businesses, Government Agencies, Utility Providers |
| Companies Covered | ChargePoint, Tesla, ABB, EVBox, Shell Recharge, BP Pulse, EVgo, Blink Charging, Enel X, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Charging Station Operation Market Trends and Innovations
Software-defined charging architectures are decoupling hardware from monetization logic, enabling operators to reconfigure tariff structures without physical equipment swaps. This virtualization layer is attracting venture investment into charging-as-a-service platforms.
Dynamic load management software is virtualizing grid connection capacity by algorithmically distributing available power across multiple charging sessions. Fleet operators with predictable dwell times are adopting these systems first, squeezing 40% more throughput from fixed transformer ratings. The structural compression of per-stall infrastructure costs is enabling hub deployments in grid-constrained urban locations.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on automated pricing systems used by charging networks. Operators must now document how machine learning models set real-time tariffs, creating compliance overhead. German regulators are scrutinizing these systems most intensively, forcing disclosure of training data sources and decision logic.
Fleet procurement teams are consolidating charging contracts under multi-year service agreements that bundle hardware, software, and energy costs into per-kilometer rates. This unbundles traditional equipment ownership from operational responsibility. Logistics operators in the Netherlands and Belgium are driving this shift fastest, pressuring charging providers to absorb utilization risk.
Electric Vehicle (EV) Charging Station Operation Market Segmentation
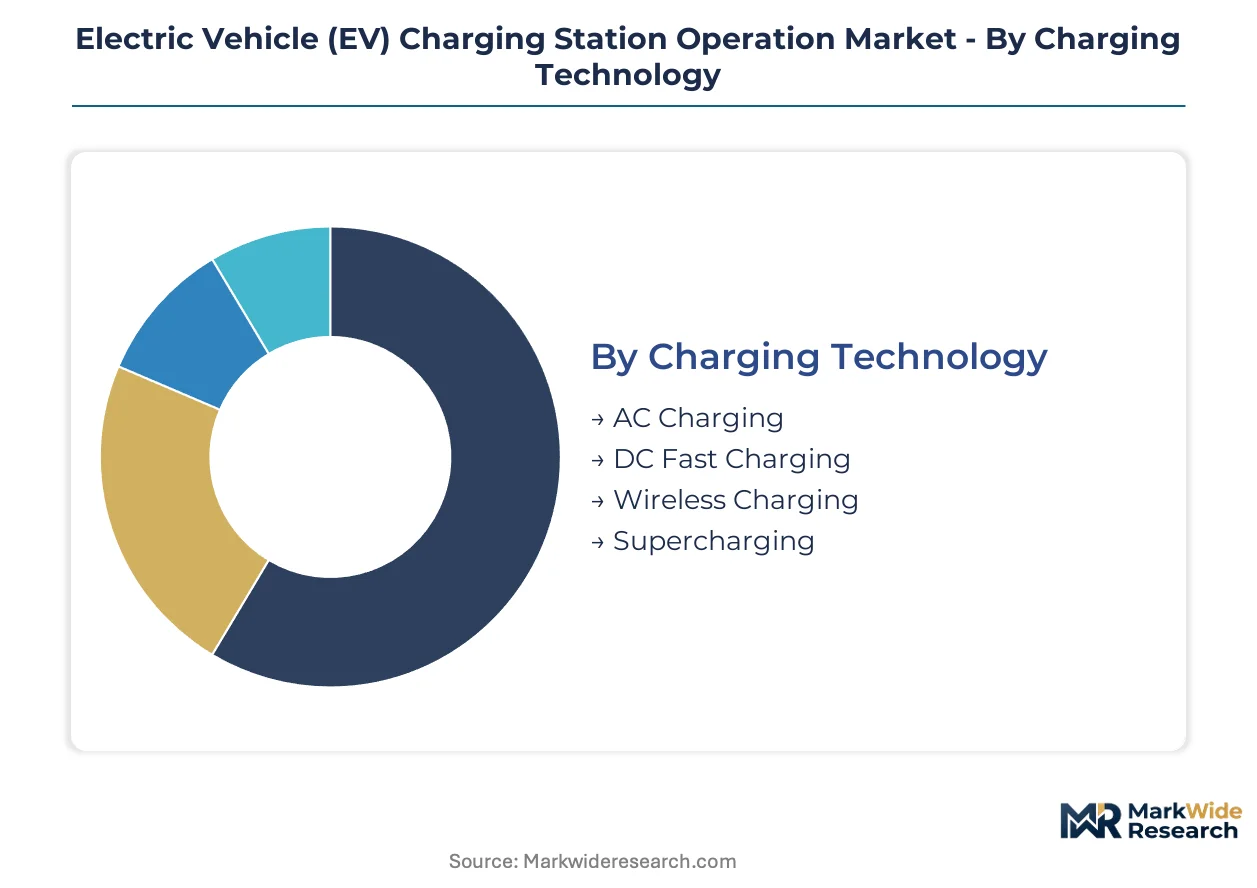
Segmentation in EV charging station operation reveals how capital intensity, utilization patterns, and regulatory exposure vary across deployment models. Operators configure asset portfolios differently depending on which technology-service-customer intersections they target.
Charging Technology:
Mature AC infrastructure dominates installed base volume while emerging supercharging and wireless systems recalibrate competitive positioning.
- AC Charging:Power electronics deliver 7-22 kW through onboard vehicle inverters, making hardware capex the lowest per stall. German residential retrofits and workplace parking installations in France concentrate demand here as building codes mandate EV-ready pre-wiring.
- DC Fast Charging:External rectifiers feed 50-350 kW directly to battery packs, requiring liquid-cooled cables and dedicated transformer capacity. Autobahn corridor deployments in Germany and fleet hubs across Dutch logistics zones absorb the majority of new connections despite grid queuing delays.
- Wireless Charging:Inductive pad systems eliminate connector wear but suffer efficiency losses and foreign object detection complexity. Pilot deployments at German taxi ranks and Norwegian ferry terminals test operational viability.
- Supercharging:Proprietary 250-350 kW networks with captive connector standards lock in vehicle-brand customer bases. Tesla's NACS deployment across European markets forces multi-standard hardware investments from competing operators.
DC Fast Charging handles the majority of throughput; Supercharging is the fastest mover on share as proprietary networks expand coverage.
Service Type:
Customer access models split between open-network transaction volume and closed-system utilization guarantees.
- Public Charging:Open-access stations serve sporadic demand from mixed vehicle fleets, creating utilization rate pressures that compress per-kWh margins. Dutch and Belgian highway networks depend on this model for TEN-T compliance.
- Private Charging:Subscription or membership-based access locks in recurring revenue through workplace and residential clusters. German corporate fleet parks and French condominium installations favor this structure for predictable load profiles.
- Fleet Charging:Captive depot infrastructure serves logistics operators with scheduled dwell times, enabling dynamic load management that squeezes 40% more throughput from fixed transformer ratings. Last-mile delivery electrification in the Netherlands drives fastest expansion here.
- Destination Charging:Retail and hospitality tie-ins extend charging sessions into dwell periods, monetizing parking rather than energy velocity. Spanish hotel chains and French supermarket forecourts anchor deployment.
Fleet Charging captures the steepest expansion trajectory as logistics electrification tightens; Public Charging remains the volume baseline despite margin compression.
Installation Type:
Site classification determines grid connection complexity, permitting timelines, and land tenure structures.
- On-Street Charging:Curb-side units in urban cores face trenching costs and utility coordination with municipal street departments. Paris and Amsterdam deployment programs concentrate here.
- Off-Street Charging:Dedicated parking structures eliminate right-of-way negotiations but require landlord agreements and building code compliance. German commercial retrofits under KfW subsidies dominate activity.
- Home Charging:Residential garage and driveway installations represent lowest per-session infrastructure cost but fragment customer acquisition across millions of individual decision points.
- Commercial Charging:Workplace and retail locations bundle charging with parking services, creating B2B sales cycles with facility managers rather than end drivers.
Off-Street Charging handles the majority of throughput; On-Street Charging is expanding most quickly as urban curbside mandates tighten.
Customer Type:
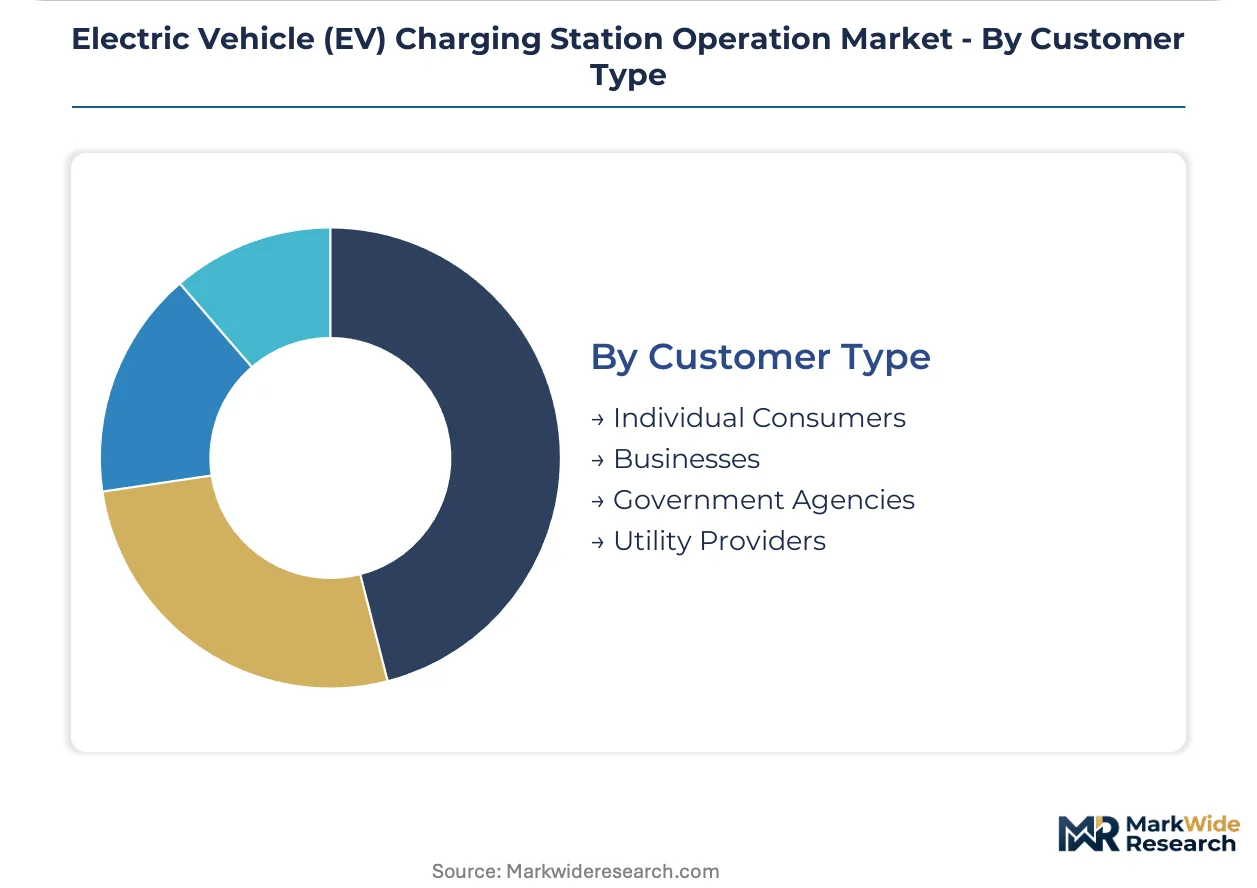
Purchasing authority separates fragmented individual decision-making from consolidated enterprise procurement.
- Individual Consumers:Sporadic charging needs and price sensitivity drive app-based network hopping rather than loyalty, forcing operators to compete on real-time availability data.
- Businesses:Corporate fleet managers consolidate charging contracts under multi-year service agreements that bundle hardware, software, and energy into per-kilometer rates, transferring utilization risk to providers.
- Government Agencies:Municipal and national procurement vehicles channel public funding toward highway corridor coverage and underserved region backfill, with TEN-T network obligations in Poland and Romania creating first-mover positioning.
- Utility Providers:Grid operators view charging infrastructure as demand management and frequency regulation assets, particularly where vehicle-to-grid integration enables bidirectional revenue stacking.
Businesses handle the majority of throughput; Government Agencies are climbing the fastest on share as infrastructure obligations harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal infrastructure obligations and national ICE phase-out laws are concentrating deployment capital in specific corridors and urban clusters. France, Germany, and the Netherlands anchor European expansion through mandated building codes and public-private funding mechanisms.
Germany
Fleet operators across logistics and last-mile delivery are converting van pools to electric, creating captive demand for high-utilization DC fast charging hubs. The KfW subsidy program forces existing commercial parking structures to install infrastructure during renovation cycles. Autobahn corridor charging and urban fleet hubs in North Rhine-Westphalia and Bavaria receive combined federal-state investment.
France
RE2020 regulations and EV-ready parking mandates in new construction are forcing developers to pre-wire commercial and residential assets. ANSM and national building code enforcement accelerate installation obligations for landlords and facility managers. Paris on-street deployment programs and supermarket forecourt conversions in Île-de-France concentrate activity.
Netherlands
TEN-T network compliance requirements and urban curbside mandates are tightening deployment timelines for highway and municipal operators. Distribution network operators face 18-24 month backlogs for new high-capacity connections, freezing site development. Amsterdam and Rotterdam deployment programs lead density expansion despite grid queuing delays.
United States
NHTSA corridor designations and EPA emissions credit frameworks steer federal funding toward interstate highway networks rather than urban saturation. Logistics electrification across California and Texas freight corridors drives fleet hub demand. The Pacific Northwest and Southeast states absorb infrastructure investment through state-level zero-emission vehicle mandates.
China
Dual carbon goals and MIIT charging infrastructure targets accelerate deployment across Yangtze River Delta and Pearl River Delta megacity clusters. State Grid Corporation and private operators co-invest in high-power charging corridors connecting Beijing-Tianjin-Hebei to Sichuan-Chongqing manufacturing zones. Shenzhen and Shanghai lead supercharging network density.
Electric Vehicle (EV) Charging Station Operation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented ownership structures. The vendor base splits between integrated energy majors, pure-play charging network operators, and automotive-captive infrastructure arms. Three strategic archetypes dominate: forecourt converters leveraging retail footprints, software-agnostic platform operators, and proprietary connector standard holders. M&A activity concentrates on regional operator consolidation and technology licensing partnerships.
Within the integrated energy tier, Shell Recharge and BP Pulse occupy positions linking forecourt conversions to renewable energy certificate frameworks. ChargePoint exemplifies the software-agnostic archetype through platform-based deployment velocity without underlying grid asset ownership. Tesla anchors the supercharging segment through proprietary connector standards and captive vehicle demand.
| Leading Market Players |
|---|
| ChargePoint |
| Tesla |
| ABB |
| EVBox |
| Shell Recharge |
| BP Pulse |
| EVgo |
| Blink Charging |
| Enel X |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp freight corridor's energy logistics costs cascade through EV charging hardware procurement, amplifying price spreads between CE-certified premium units and uncertified economy imports while concentrating supply leverage with German power electronics fabricators.
Pricing Analysis
Certification level under EU Machinery Directive and EMC harmonized standards creates the primary spread between hardware tiers. Three-tier pricing structure across premium liquid-cooled 350 kW systems, standard 150 kW air-cooled units, and economy 50 kW imports dominates procurement. Cost compression in the economy tier is intensifying because Chinese-processed silicon carbide wafers face longer CE approval timelines. Fleet operators consolidating multi-year service agreements exhibit lowest price sensitivity; individual consumers hopping between charging apps drive margin erosion through real-time tariff comparison.
Supply Chain Analysis
Foxconn, Delta Electronics, and ABB's Power Grids division hold contract manufacturing capacity for power electronics assembly. Geographic supply concentrates in China for rare earth refining and magnet processing, Germany for silicon carbide wafer fabrication, and Taiwan for semiconductor controller production. Raw material dependencies span copper for cabling, silicon carbide for high-efficiency inverters, and neodymium for cooling system motors. Single-source vulnerability in Chinese-processed rare earths exposes operators to export restriction risk. Distribution runs through Tier 1 charging network operators who bundle hardware with software subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV charging station operation is entering a cyclical recovery phase as fleet electrification mandates tighten and grid connection backlogs begin clearing. Capital deployment timing hinges on monitoring ISO 15118 interoperability rollout and TEN-T funding disbursement velocity.
For Market Incumbents: Entrench market position through backward integration into power electronics assembly and captive silicon carbide sourcing partnerships. Shell Recharge and BP Pulse face margin compression from software-agnostic platform competitors; defend by locking fleet operators into 5-7 year energy-as-a-service contracts with guaranteed uptime SLAs. Prioritize CE certification pre-approval investments to compress 8-14 month hardware launch timelines. For New Entrants and Emerging Players: Build out Polish and Romanian highway corridor positions before TEN-T network funding saturates German and French markets. The most penetrable white-space sits in bidirectional charging hardware for vehicle-to-grid integration, where technical standards remain unsettled. Pursue municipal on-street deployment partnerships in Amsterdam and Paris to secure curbside real estate ahead of building code mandates. For Investors and Strategic Acquirers: Regional operators with secured grid connection queue positions in the Netherlands and Belgium present acquisition targets with embedded scarcity value. Long-term viability across the analysis window rests on software-defined charging architectures decoupling hardware from monetization logic. Monitor German regulator scrutiny of AI-driven dynamic pricing algorithms as an inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15118 Plug-and-Charge Certification | Eliminates payment friction and locks in customer retention across European networks. |
| Silicon Carbide Backward Integration | Secures supply of high-efficiency wafers from German foundries against Chinese export volatility. |
| Vehicle-to-Grid Hardware Development | Opens frequency regulation revenue stacking through bidirectional charging with home energy systems. |
| TEN-T Corridor Positioning | Captures first-mover advantage in Polish and Romanian highway networks before funding saturation. |
| Dynamic Load Management Software | Squeezes 40% more throughput from fixed transformer ratings in grid-constrained urban hubs. |
Research Methodology
The analysis maps AC residential, DC fast charging, wireless, and supercharging sub-sectors, each validated through interviews with charging network operators, fleet procurement managers, distribution network engineers, and power electronics procurement leads. Primary fieldwork combined with secondary validation against SEC filings of listed charging operators, EIA infrastructure deployment data, EU TEN-T progress reports, and national building code regulatory filings. Bottom-up site-level deployment tracking triangulates against top-down market size estimates from automotive OEM electrification roadmaps.
Assumption sets held grid connection approval timelines and copper pricing volatility fixed at baseline levels while varying fleet electrification mandate enforcement intensity and ISO 15118 adoption curves across the projection horizon. Segmentation dimensions modeled include charging technology tier, service type access model, installation site classification, and customer purchasing authority. CAGRs were derived from deployment run-rate analysis and power electronics cost curve trajectories. Industry-specific forecast inputs span KfW subsidy disbursement velocity and RE2020 enforcement timelines.
Stress conditions across grid queuing delay extensions, silicon carbide supply disruptions, and NACS versus CCS2 standard fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement and technology cost curves. Quarterly review of German KBA type-approval timelines and Dutch distribution network operator connection queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market