
 United States Electric Vehicle (EV) Charging Equipment Market | 2026-2036
United States Electric Vehicle (EV) Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle (EV) Charging Equipment Market Analytics
Texas is rewriting the competitive map for EV charging equipment manufacturing with multiple gigafactory-adjacent supply clusters emerging along the I-35 corridor. ChargePoint leverages its software-integrated hardware stack to dominate commercial installations across suburban retail corridors. Tesla Superchargers anchors the DC fast charging segment through its proprietary connector standard and captive network density.
United States Electric Vehicle (EV) Charging Equipment comprises conductive power transfer systems rated from 1.4 kW residential Level 1 units through 350 kW DC fast chargers, employing liquid-cooled cables and CCS1/NACS connector protocols to replenish battery electric vehicle packs. The primary purpose spans residential overnight charging, workplace opportunistic charging, and highway corridor rapid replenishment for commercial and consumer mobility. DC Fast Chargers capture the fastest growth trajectory as fleet electrification and long-distance travel demand strain existing infrastructure capacity. Smart Charging technology segments are pulling margin pools toward grid-integrated bidirectional systems that monetize peak-shaving services.
FAA, NHTSA, and FERC collectively shape the regulatory perimeter through vehicle safety standards, grid interconnection rules, and interstate corridor electrification mandates under the Bipartisan Infrastructure Law. NHTSA's Federal Motor Vehicle Safety Standards govern charging system electrical integrity, while FERC Order 2222 enables distributed energy resource aggregation that rewards smart charging participation. Stakeholders must monitor NEVI program compliance deadlines and state utility commission rate-case proceedings that determine charger economics.
Market Dynamics
The NEVI formula program is compressing deployment timelines for highway corridor charging networks while state-level zero-emission mandates force fleet operators into accelerated electrification schedules.
Growth Catalysts
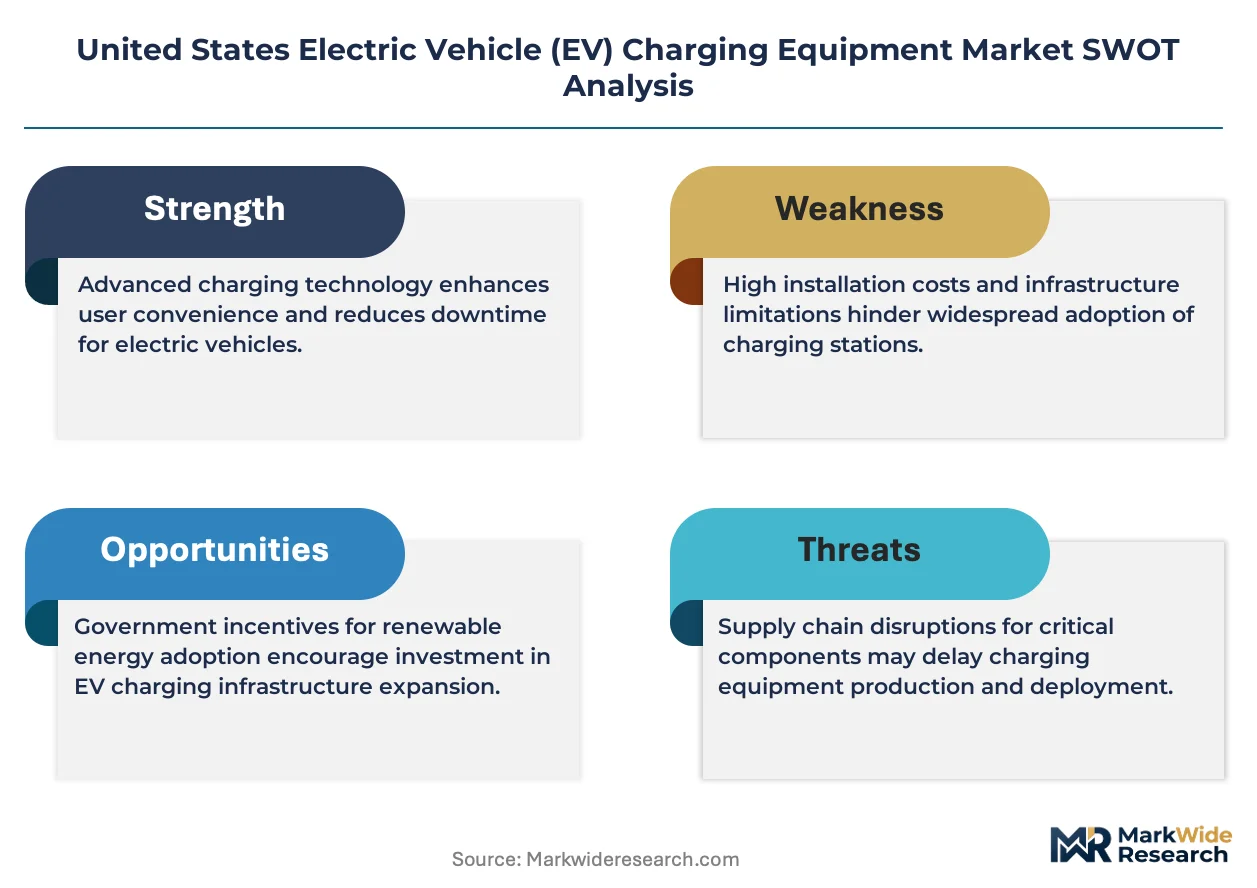
- NEVI Funding Streams:Federal highway corridor electrification dollars are de-risking capital deployment for DC fast charging infrastructure across interstate networks.
- Fleet Electrification Mandates:California's Advanced Clean Trucks regulation is pulling demand for heavy-duty charging hardware into logistics depots and municipal transport yards.
- Bidirectional Power Hardware:Vehicle-to-grid capable charging systems are opening revenue streams through FERC Order 2222-enabled distributed energy resource aggregation.
Market Restraints
- Transformer Lead Times:Utility-scale electrical equipment procurement cycles now stretch 18-24 months, gating site energization for high-capacity charging hubs.
- Domestic Content Requirements:Buy America provisions under the Bipartisan Infrastructure Law are constraining supply flexibility for steel enclosures and cable assemblies.
- Copper Price Volatility:Liquid-cooled cable assemblies and busbar systems face margin pressure from commodity swings in conductor metals.
Strategic Opportunities
- Multi-Unit Dwelling Retrofits:Unwired parking structures in Texas and Florida apartment complexes represent untapped installation volume for Level 2 load-managed systems.
- Workplace Charging as Benefit:Employer-subsidized charging is emerging as a recruitment tool in suburban office parks across the Sun Belt.
- NACS Standardization:The J3400 connector protocol is converging hardware designs and reducing SKU complexity for equipment manufacturers.
Industry Challenges
- Licensed Electrician Scarcity:High-voltage installation capacity is bottlenecking deployment velocity in markets with aggressive utility rebate deadlines.
- Interconnection Queue Backlogs:Utility study and construction timelines for commercial site upgrades are extending project completion windows beyond fleet operator requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle (EV) Charging Equipment Market |
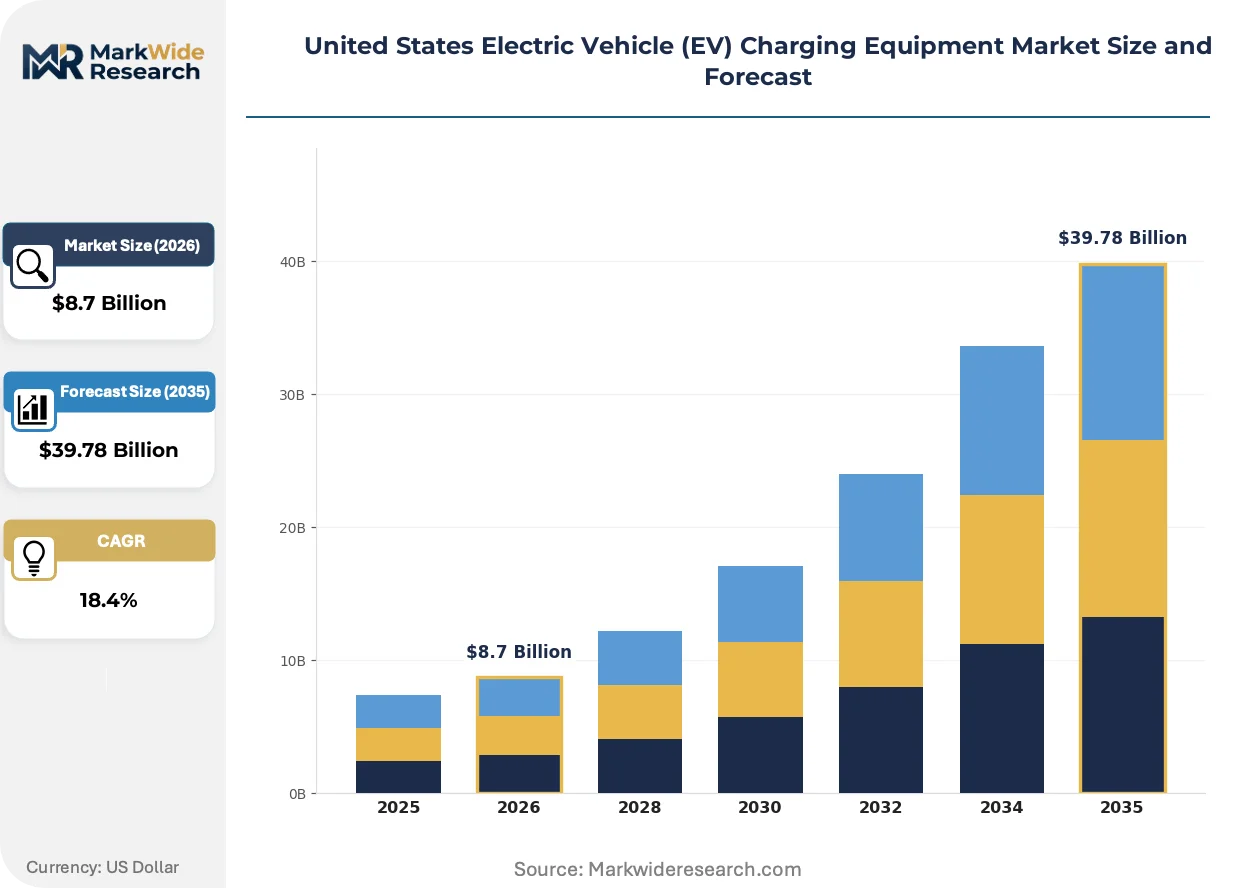
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers Technology: Plug-in Technology, Smart Charging, Vehicle-to-Grid, Solar-Integrated Installation: Residential Installations, Commercial Installations, Public Charging Stations, Fleet Charging Solutions End User: Individuals, Businesses, Government Entities, Fleets |
| Companies Covered | ChargePoint, EV Connect, Tesla Superchargers, Ford Charge, Red E Charge, Electrify America, Blink, Rivian Adventure Network, EVgo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle (EV) Charging Equipment Market Evolving Landscape
Hardware-software integration is redefining competitive differentiation as charging systems evolve from passive electrical equipment into grid-interactive assets.
Dynamic load management software is collapsing the capital intensity of multi-port charging installations by enabling power sharing across connector heads without transformer upgrades. Fleet operators with depot charging needs are adopting these systems to maximize vehicle throughput on constrained electrical service. The technology is compressing infrastructure costs for logistics electrification programs.
FERC Order 2222 is enabling distributed energy resource aggregation that compensates smart charging participation in wholesale electricity markets. This regulatory framework is creating new revenue streams for bidirectional-capable hardware deployments. Commercial and industrial sites with vehicle fleets are the primary beneficiaries, with early adoption concentrated in Texas and California ISO territories.
Buyers are consolidating vendor relationships around full-stack providers capable of delivering hardware, installation, and ongoing network management under unified service agreements. This pattern is displacing the fragmented procurement model where fleet operators separately sourced equipment, electrical contractors, and software subscriptions. The shift is most pronounced among municipal transit agencies and national logistics carriers with standardized rollout requirements.
United States Electric Vehicle (EV) Charging Equipment Market Segmentation
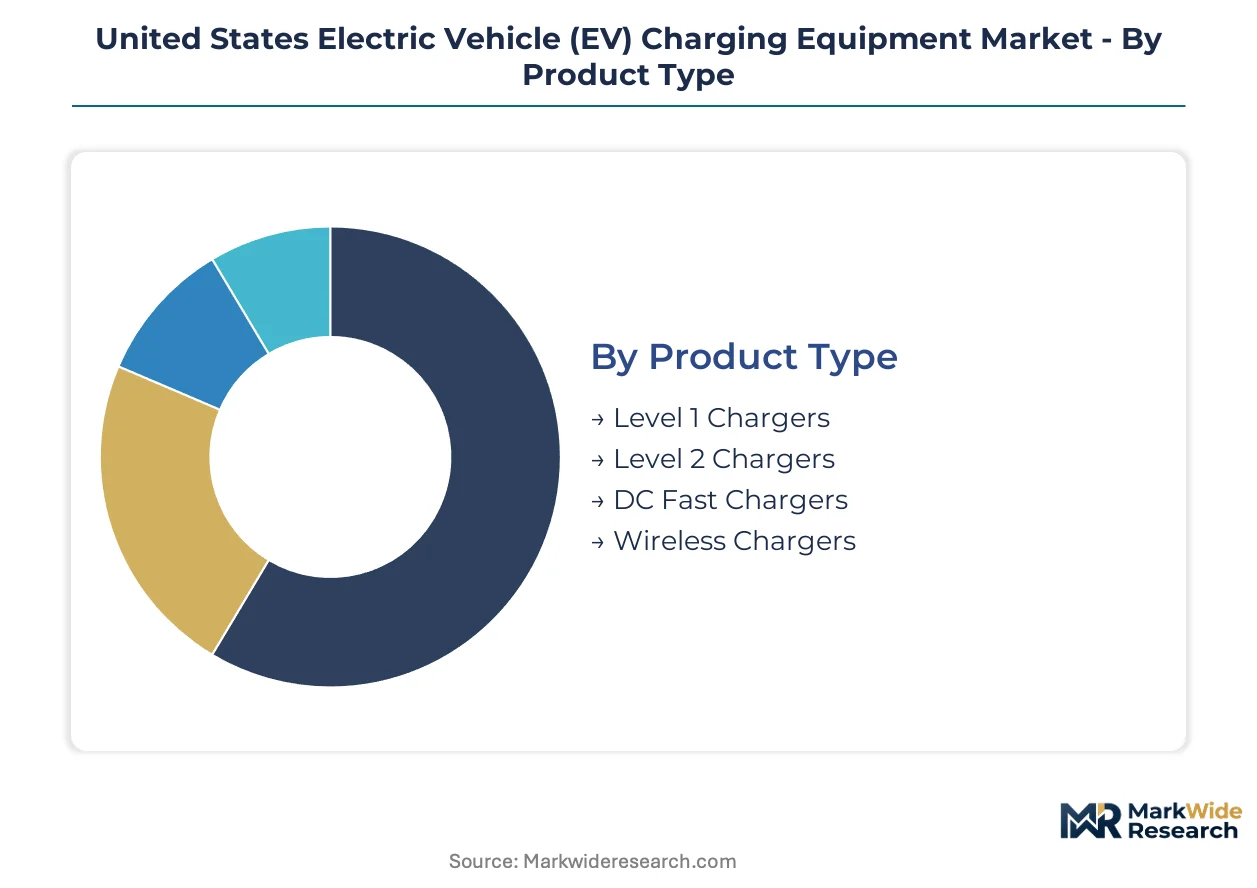
Segmentation reveals how hardware specifications, grid integration capabilities, and installation environments create distinct margin profiles and service intensity requirements across the United States EV charging equipment landscape. Equipment manufacturers configure product portfolios differently for each segment, with warranty terms and software subscription models varying substantially by use case and power rating.
Product Type:
After-sales service intensity escalates dramatically with power output, as liquid-cooled cable assemblies and high-voltage power electronics in DC systems demand specialized technician networks that Level 1 and Level 2 hardware avoids entirely.
- Level 1 Chargers:These 1.4 kW residential units operate on standard 120V outlets without dedicated electrical infrastructure. Demand concentrates in legacy housing stock across Texas and Florida apartment complexes where panel upgrades are economically prohibitive. The segment carries minimal service burden due to passive thermal management and absence of installation complexity.
- DC Fast Chargers:High-power units from 50 kW to 350 kW employ liquid-cooled CCS1/NACS connectors and active thermal management for highway corridor deployment. Fleet electrification mandates in California logistics depots are pulling demand for 150+ kW configurations with 24/7 uptime requirements. These systems generate recurring revenue through network management subscriptions and preventive maintenance contracts.
- Level 2 Chargers:7-19 kW AC units dominate workplace and multi-unit dwelling retrofits with moderate installation complexity.
- Wireless Chargers:Inductive pad systems remain nascent, with pilot deployments concentrated in premium residential and autonomous shuttle applications.
By volume, Level 2 Chargers leads. By growth pace, DC Fast Chargers is ahead.
Technology:
Technology selection determines whether charging equipment functions as passive electrical hardware or as a grid-interactive asset capable of generating ancillary revenue streams through wholesale market participation.
- Smart Charging:Load management algorithms optimize power distribution across multiple connector heads without transformer upgrades. Fleet operators in Texas ISO territories deploy these systems to maximize vehicle throughput on constrained electrical service while capturing demand response payments. The technology collapses infrastructure capital intensity for depot charging programs.
- Vehicle-to-Grid:Bidirectional power electronics enable battery discharge back to grid or building loads under FERC Order 2222 aggregation frameworks. California municipal transit agencies and Texas commercial fleets with predictable parking schedules represent early adoption clusters. Hardware margins expand through software-enabled revenue sharing arrangements.
- Plug-in Technology:Conventional unidirectional AC and DC charging without communication-layer optimization dominates residential and basic commercial installations.
- Solar-Integrated:DC-coupled photovoltaic integration reduces grid dependency for off-grid and peak-shaving applications in sun-belt states.
Smart Charging commands the largest installed base. Vehicle-to-Grid is climbing the fastest.
Installation:
Installation environment dictates electrical infrastructure requirements, with public highway corridors facing 18-24 month transformer lead times that residential retrofits typically bypass.
- Public Charging Stations:Highway corridor and urban curbside deployments require utility-scale interconnection studies and often dedicated substations. NEVI formula program funding is compressing deployment timelines across interstate networks in California, Texas, and Florida. These sites generate the highest service revenue per unit through network management fees and uptime guarantee contracts.
- Fleet Charging Solutions:Depot configurations for logistics and municipal transport aggregate multiple high-power dispensers with dynamic load management. California's Advanced Clean Trucks regulation is accelerating procurement for heavy-duty charging hardware in distribution centers and transit yards. Procurement patterns favor full-stack vendors capable of unified hardware, installation, and software service agreements.
- Residential Installations:Single-family home deployments favor Level 2 hardwired or plug-in units with minimal grid interaction.
- Commercial Installations:Workplace and retail parking configurations prioritize load management across multiple ports with employer-subsidized access models.
Commercial Installations represents the largest addressable base. Fleet Charging Solutions is expanding most quickly.
End User:
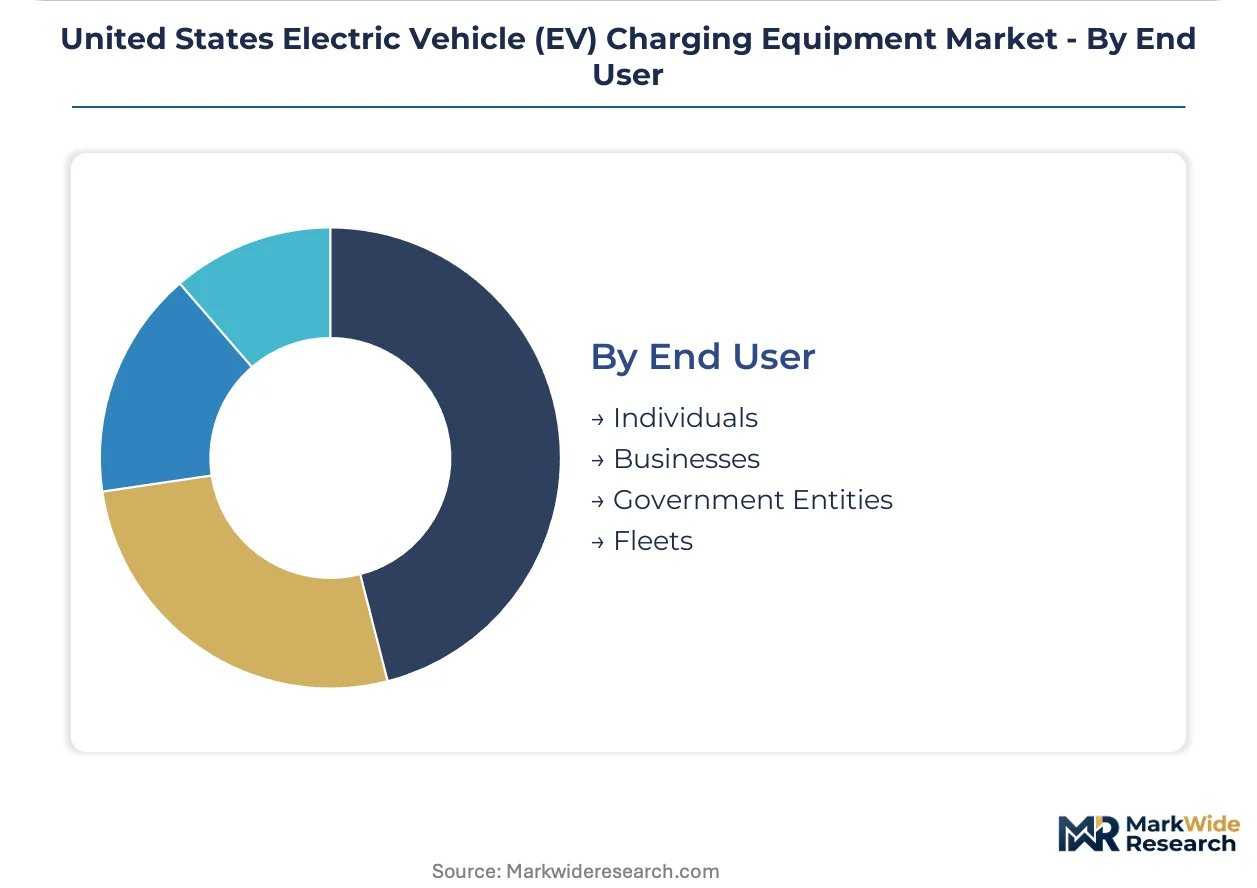
End user type determines procurement sophistication, with fleet operators and government entities consolidating vendor relationships while individual consumers remain fragmented.
- Fleets:National logistics carriers and municipal transit agencies standardize on unified procurement frameworks with multi-site rollout requirements. These buyers demand 99%+ uptime guarantees and integrated telematics compatibility. The segment is displacing fragmented equipment-plus-contractor procurement models.
- Government Entities:Municipal and state agencies navigate NEVI compliance deadlines and Buy America domestic content requirements for federal funding eligibility. Procurement cycles extend 12-18 months with extensive technical specification development.
- Individuals:Single-point residential purchases favor retail distribution through electrical supply houses and big-box channels.
- Businesses:Workplace charging programs treat equipment as employee benefit infrastructure with HR budget ownership rather than facilities capital.
Fleets account for the highest revenue concentration. Government Entities is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2222 anchors demand aggregation in Texas ISO territories, while NHTSA safety standards govern equipment deployment across state lines. State-level zero-emission mandates and NEVI formula funding create divergent deployment velocities across sub-regional markets.
California
California's Advanced Clean Trucks regulation pulls heavy-duty charging hardware into Central Valley logistics depots and Los Angeles Basin transit yards. CARB compliance deadlines compress procurement timelines for fleet operators. The Bay Area anchors software-integrated charging development with utility rebate programs accelerating multi-unit dwelling retrofits.
Texas
Texas ISO demand response markets reward FERC Order 2222-enabled smart charging participation across Dallas-Fort Worth and Houston metroplexes. ERCOT grid volatility creates price arbitrage opportunities for bidirectional-capable depot systems. I-35 corridor gigafactory-adjacent clusters concentrate supply chain infrastructure between Austin and San Antonio.
Florida
Florida Power & Light utility rebate programs accelerate Level 2 deployment in Tampa and Orlando suburban office corridors. Hurricane resilience requirements shape hardware specifications for public charging networks. Miami-Dade municipal electrification mandates drive transit yard charging procurement.
New York Metro
NYISO grid interconnection queues extend commercial site upgrade timelines for fleet charging in New Jersey distribution centers. Con Edison demand response programs compensate workplace charging load management across Long Island and Westchester. NYC curbside charging pilot programs test urban infrastructure models.
Pacific Northwest
Bonneville Power Administration wholesale rate structures influence charging economics for Seattle and Portland fleet operators. Washington state zero-emission vehicle mandates accelerate municipal transit electrification. Hydroelectric grid stability supports high-power charging hub development along I-5 corridor.
United States Electric Vehicle (EV) Charging Equipment Market Competitive Landscape
Capability concentration sits with full-stack providers integrating hardware, software, and network management; scale advantage sits with captive network operators deploying proprietary connector standards. The market structures around three archetypes: vertically integrated automaker networks, independent charging network operators, and utility-aligned infrastructure providers. Consolidation pressures favor unified service agreements over fragmented procurement. Competitive moves center on NACS standardization adoption and dynamic load management software integration.
Within the independent network operator tier, ChargePoint and EVgo represent the full-stack archetype with software-integrated hardware deployment. Tesla Superchargers anchors the captive network model through proprietary infrastructure density. Among utility-aligned providers, Electrify America occupies a position exemplifying highway corridor electrification under federal funding programs.
| Leading Market Players |
|---|
| ChargePoint |
| EV Connect |
| Tesla Superchargers |
| Ford Charge |
| Red E Charge |
| Electrify America |
| Blink |
| Rivian Adventure Network |
| EVgo |
| Others |
Value Network & Pricing Analysis
I-35 corridor gigafactory-adjacent clusters between Austin and San Antonio concentrate domestic manufacturing capacity for power electronics and cable assemblies, compressing delivery timelines for Texas fleet operators while California buyers absorb premium logistics costs from Asian component flows.
Pricing Analysis
Coastal-to-interior price spreads of 15-25% separate California corridor deployments from Texas depot installations, reflecting divergent electrical infrastructure upgrade burdens and permitting timelines. Three-tier pricing structure across premium, standard, and economy levels tracks NEVI compliance certification, liquid-cooled cable specifications, and software integration depth. Cost compression in standard-tier hardware is intensifying because Buy America domestic content requirements constrain low-cost import sourcing. Municipal transit agencies exhibit highest price sensitivity due to extended procurement cycles, while national logistics carriers with uptime guarantees accept premium positioning.
Supply Chain Analysis
Copper cathode and silicon carbide MOSFETs draw from Chilean mining operations and Taiwanese foundry capacity respectively, tethering margin stability to commodity exchange volatility and semiconductor fabrication allocation. China, South Korea, and Japan concentrate liquid-cooled connector manufacturing and high-voltage power module assembly. Single-source vulnerability in silicon carbide substrates presents structural risk as automotive powertrain demand competes for limited wafer starts. Distribution runs through electrical supply houses and direct OEM procurement channels, with full-stack vendors displacing fragmented contractor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NACS standardization across J3400 protocol implementations signals platform-economics inflection, collapsing connector SKU proliferation and enabling interoperability arbitrage for software-integrated hardware providers.
For Market Incumbents: Build network density moats through captive installation capacity in ERCOT and CAISO territories before electrician scarcity hardens into structural constraint. Consolidate around full-stack service agreements that bundle hardware, software, and maintenance under unified uptime guarantees. Defensive positioning requires backward integration into power electronics assembly to offset transformer lead time bottlenecks gating site energization. For New Entrants and Emerging Players: Pursue multi-unit dwelling retrofit white space across Florida and Texas apartment complexes where load-managed Level 2 systems face minimal incumbent saturation. Target workplace charging benefit programs in Sun Belt suburban office parks as recruitment infrastructure with HR budget ownership. Anchor go-to-market through utility rebate program partnerships that compress customer acquisition costs. For Investors and Strategic Acquirers: Long-term, this sits as a grid-interactive infrastructure play because FERC Order 2222 aggregation frameworks monetize bidirectional power flows beyond commodity hardware margins. Acquisition targets cluster around dynamic load management software specialists with fleet operator reference accounts. Signal to watch is NEVI program compliance deadline acceleration forcing distressed asset consolidation among undercapitalized highway corridor developers.| Strategic Initiative | Industry Significance |
|---|---|
| NACS Connector Standardization | J3400 protocol convergence collapses SKU complexity and enables cross-network roaming for Tesla Superchargers and independent operators. |
| Dynamic Load Management Deployment | Power-sharing algorithms maximize vehicle throughput on constrained electrical service without utility transformer upgrades. |
| Vehicle-to-Grid Hardware Integration | Bidirectional power electronics capture FERC Order 2222-enabled revenue streams through wholesale market participation. |
| Full-Stack Service Consolidation | Unified hardware-installation-software agreements displace fragmented procurement for municipal transit agencies. |
| NEVI Corridor Network Buildout | Federal highway electrification funding de-risks capital deployment across interstate networks in California, Texas, and Florida. |
Research Methodology
Desk research of FERC interconnection filings, NHTSA Federal Motor Vehicle Safety Standards, and state utility commission rate-case proceedings preceded structured interviews with fleet electrification directors, utility demand response program managers, charging network deployment engineers, and electrical contractor operations leads. Secondary validation drew from NEVI program disbursement reports, ERCOT wholesale market data, and SEC 10-K equipment manufacturer disclosures. Bottom-up installation volume estimates triangulated against top-down federal funding allocation trajectories.
Assumptions held NEVI formula program funding continuity and state zero-emission mandate enforcement trajectories fixed, while copper price volatility and transformer procurement timelines were modeled as sensitivity variables across the projection horizon. Segmentation dimensions spanned power output tier, grid integration technology, installation environment, and end-user procurement sophistication. CAGRs were derived from installation run-rate analysis and fleet operator electrification schedule commitments, with hardware replacement cycles and software subscription renewal rates as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and construction labor availability would shift infrastructure deployment velocity. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and commodity price stabilization. Cross-checking against utility interconnection queue backlogs and licensed electrician training program graduation rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Airport Charging Stations Market