
 Denmark Electric Vehicle Charging Equipment Market | 2026-2036
Denmark Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Electric Vehicle Charging Equipment Market Insights
Subscription-based load management software is rebalancing what Danish charging vendors monetize beyond hardware sales. Zaptec leverages its cloud platform to sustain recurring revenue from residential and commercial installations. Schneider Electric anchors its position through integrated energy management systems that bundle EV charging with building automation. ABB competes on DC fast charging specialization for highway corridor deployments across the Danish road network.
Electric vehicle charging equipment comprises electrical infrastructure that converts grid alternating current to direct current at specified voltage and power levels for battery replenishment, with AC chargers typically delivering 3.7–22 kW and DC fast chargers exceeding 50 kW through onboard or external rectification. The primary purpose is enabling safe, standardized energy transfer to electric drivetrains across stationary parking contexts. AC chargers occupy the largest installed base in Denmark due to lower capital requirements and compatibility with overnight residential cycles, while DC fast chargers represent the fastest-expanding segment driven by fleet electrification and intercity mobility needs. Workplace charging applications command premium positioning as employers bundle infrastructure with employee benefit programs and sustainability reporting obligations.
Danish building regulations administered by the Danish Transport, Construction and Housing Authority mandate EV-ready infrastructure in new construction, while the Danish Energy Agency coordinates grid integration standards for high-capacity charging clusters. CE marking requirements under EU harmonized standards govern product safety and electromagnetic compatibility for all equipment deployed. Stakeholders must monitor forthcoming revisions to Denmark's Building Regulations and grid tariff structures as these will determine site economics for ultra-fast charging investments.
Market Dynamics
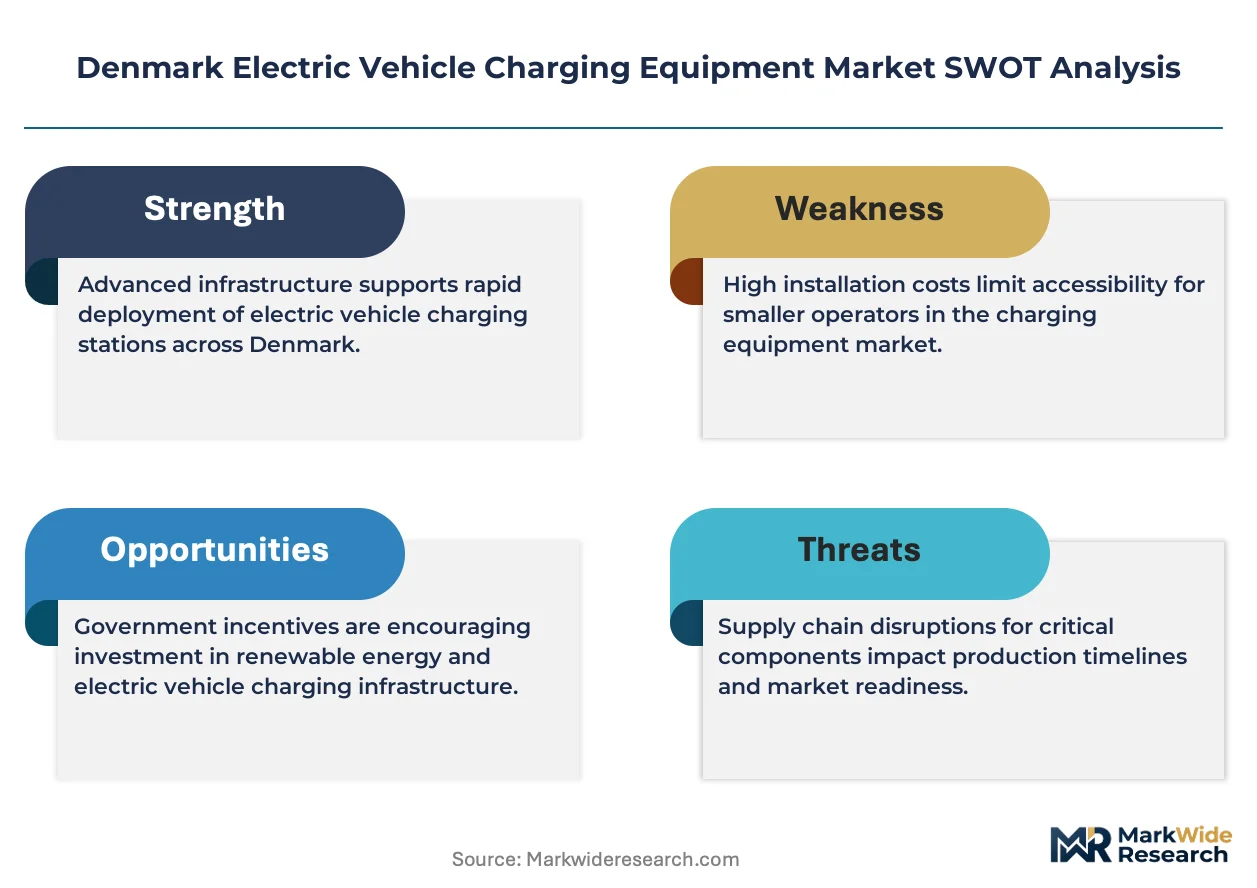
Denmark's Building Regulations mandate pre-installation conduit in new parking structures, forcing developers to internalize EV-ready infrastructure costs and reshaping site economics for charging equipment deployment across Jutland and Zealand.
Growth Catalysts
- Fleet Electrification Mandates:Danish logistics operators accelerate DC fast charger procurement to electrify heavy-duty corridors serving Copenhagen and Aarhus distribution hubs.
- CE Marking Harmonization:EU electromagnetic compatibility standards reduce certification friction for equipment suppliers entering the Danish market through simplified conformity assessment.
- Subscription Load Management:Cloud-based software platforms enable recurring revenue streams from residential and commercial installations, decoupling vendor economics from hardware-only sales.
Market Restraints
- Grid Connection Queues:Energinet's interconnection approval timelines delay high-capacity cluster deployments, compressing investor returns for ultra-fast charging stations.
- Copper Price Volatility:Raw material swings in power electronics and cabling components destabilize equipment manufacturer margins and project financing certainty.
- Residential AC Saturation:Overnight charging penetration among single-family housing stock limits addressable market expansion for basic Level 2 units.
Strategic Opportunities
- Workplace Benefit Bundling:Employer sustainability reporting obligations under EU CSRD create procurement pull for integrated charging-as-amenity installations.
- Highway Corridor Gaps:Sparse DC fast coverage along E45 and E20 routes between Odense and Esbjerg offers first-mover positioning for mobility service providers.
- Building Automation Convergence:Integration of EV charging with HVAC and lighting control systems opens bundled energy management contracts for facility managers.
Industry Challenges
- Power Electronics Talent Scarcity:Shortage of grid integration specialists delays commissioning for 150kW+ installations requiring harmonic filtering expertise.
- Legacy Parking Retrofit Complexity:Existing multi-unit residential structures lack electrical capacity for distributed charging, forcing expensive transformer upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Electric Vehicle Charging Equipment Market |
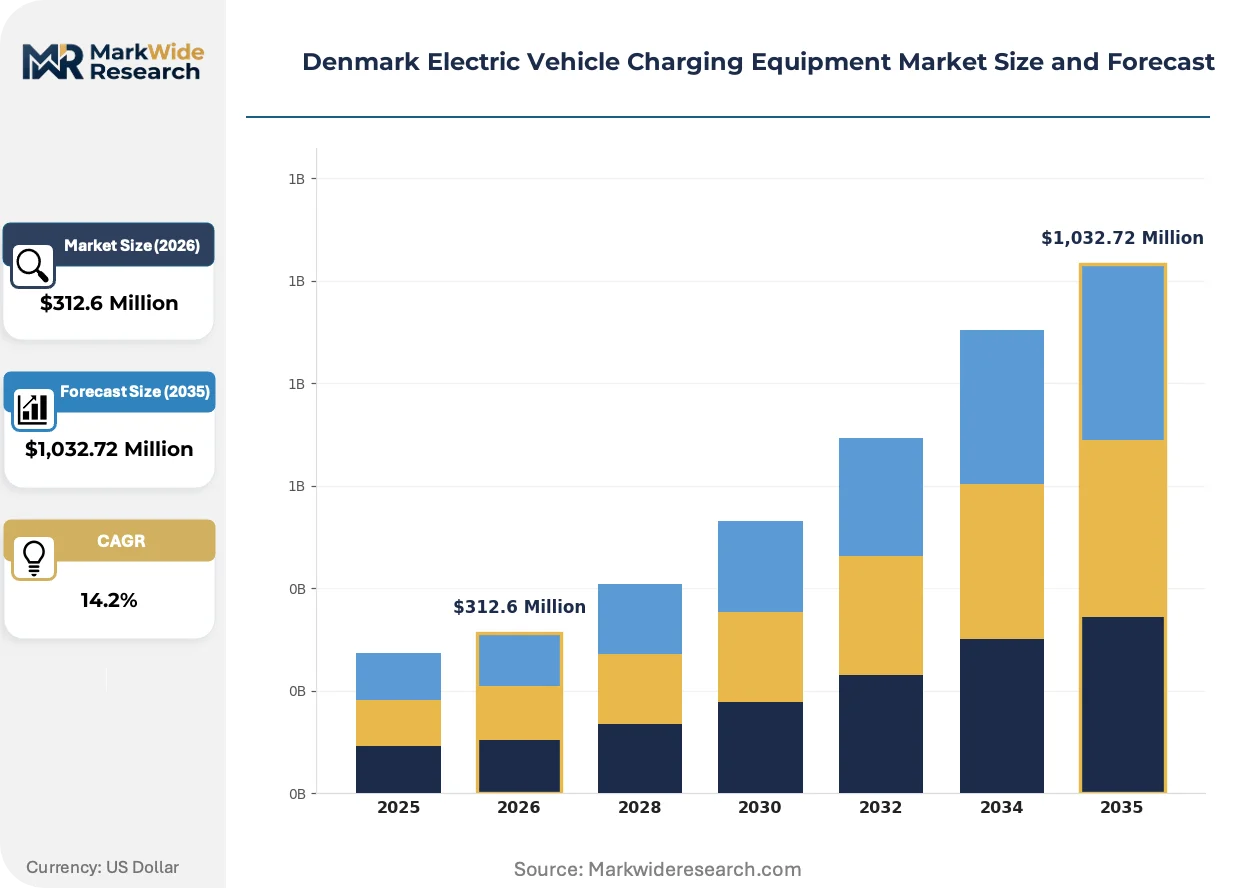
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,032.72 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Ultra-Fast Chargers Application: Residential Charging, Workplace Charging, Public Charging Stations, Fleet Charging, Commercial Parking Installation Type: Wall-Mounted, Pedestal, Socket Outlet, Integrated Charging Systems, Mobile Charging Units Customer Type: Private Vehicle Owners, Commercial Fleet Operators, Retail Businesses, Municipal Authorities, Energy Service Providers |
| Companies Covered | Zaptec, Schneider Electric, Siemens, ABB, EVBox, Wallbox, Tesla, Clever, E.ON, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Electric Vehicle Charging Equipment Market Trends and Innovations
Danish charging infrastructure is pivoting from hardware-centric deployment toward software-defined energy management, with vendors competing on platform interoperability and dynamic load balancing rather than unit specifications alone.
Modular power electronics is consolidating charger architecture across the Danish market. Silicon carbide inverter designs enable 350kW peak output from compact footprints. Fleet operators in Zealand prioritize these units for depot charging. The technology is consolidating supplier tiers by collapsing discrete component supply chains into integrated subsystems.
Denmark's Building Regulations administered by the Danish Transport, Construction and Housing Authority now require EV-ready conduit in all new parking structures above ten spaces. This mandate shifts capital allocation from retrofit markets toward new construction partnerships. Residential developers in Greater Copenhagen respond by pre-wiring entire underground garages during concrete pours.
Buyers now favor subscription-based load management over perpetual software licenses. Commercial landlords and housing associations seek operational expenditure models that bundle firmware updates with remote diagnostics. This preference shift concentrates vendor selection criteria on platform uptime guarantees rather than hardware durability alone. Municipal fleet managers in Aalborg and Aarhus lead this transition.
Denmark Electric Vehicle Charging Equipment Market Segmentation
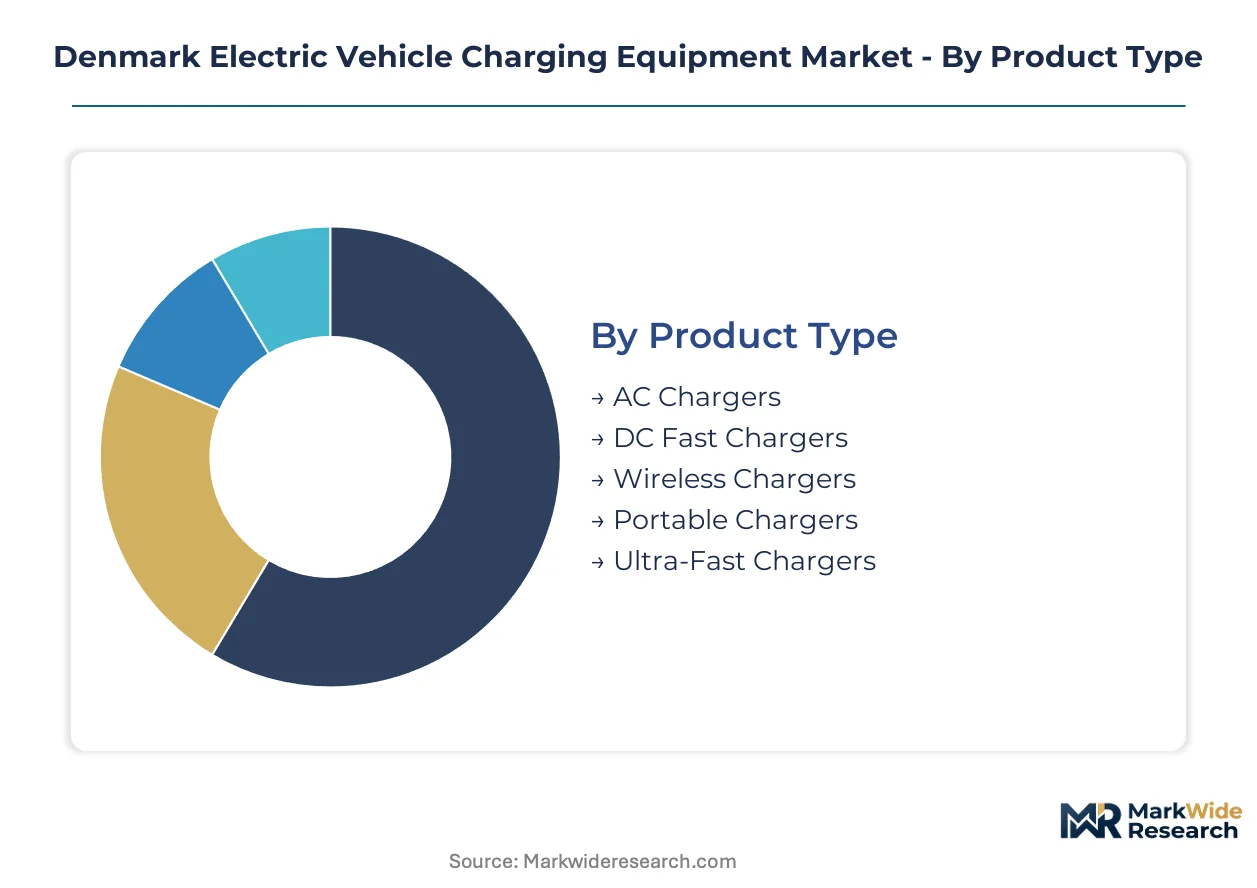
Segmentation in Denmark's EV charging equipment market reveals distinct procurement patterns across power levels, installation contexts, and customer economics. Equipment specifications diverge sharply between overnight residential cycles and high-throughput fleet depots. Understanding these divides enables vendors to align product portfolios with the country's regulatory mandates and regional infrastructure gaps.
Product Type:
Upgrade cycles in Danish charging infrastructure are shortening as silicon carbide power electronics displace legacy silicon designs, forcing replacement decisions across installed bases.
- AC Chargers:These units convert grid alternating current to vehicle-compatible direct current at 3.7–22 kW through onboard rectification, requiring minimal external infrastructure. Danish single-family housing stock in Jutland and Zealand drives steady demand, though residential saturation limits expansion for basic Level 2 units.
- DC Fast Chargers:External rectification systems deliver 50–350 kW directly to battery packs, bypassing onboard limitations. Fleet operators across Copenhagen and Aarhus distribution hubs are accelerating procurement to electrify heavy-duty corridors, making this the most contested vendor battleground.
- Wireless Chargers:Inductive power transfer systems eliminate cable connections through magnetic resonance coupling. Danish municipal trials in Copenhagen focus on autonomous shuttle applications.
- Portable Chargers:Compact mobile units provide emergency or travel charging through standard household outlets. Limited penetration due to Denmark's dense fixed infrastructure network.
- Ultra-Fast Chargers:350 kW+ peak output systems enable sub-20-minute replenishment for long-distance mobility. Sparse highway coverage along E45 and E20 routes creates first-mover positioning opportunities.
AC Chargers sits at the top of the volume ranking, with DC Fast Chargers climbing the fastest.
Application:
Cost tier differentiation separates premium integrated workplace installations from basic residential socket solutions, with mid-market public charging occupying contested middle ground.
- Residential Charging:Overnight replenishment systems dominate Danish EV ownership patterns, leveraging the country's high single-family housing penetration. Building Regulations now mandate EV-ready conduit in new parking structures, reshaping developer procurement toward pre-wired installations.
- Workplace Charging:Employer-subsidized infrastructure bundles charging access with sustainability reporting obligations under EU CSRD. Copenhagen metropolitan employers command premium positioning for integrated amenity installations.
- Public Charging Stations:Municipal and commercial open-access infrastructure serves intercity mobility and apartment dwellers. Energinet's grid connection queues delay high-capacity cluster deployments in Aalborg and Esbjerg.
- Fleet Charging:Centralized depot systems for logistics and public transport operators require coordinated load management. Zealand fleet operators prioritize modular 350 kW units for overnight heavy-duty replenishment.
- Commercial Parking:Retail and hospitality venues deploy charging as customer retention tools. Housing associations across Greater Copenhagen favor subscription-based operational expenditure models.
Residential Charging maintains installed base dominance, while Fleet Charging gains share fastest on electrification mandates.
Installation Type:
Customer type concentration among municipal authorities and housing associations favors standardized pedestal and wall-mounted form factors over specialized mobile configurations.
- Wall-Mounted:Compact bracket-attached units optimize space-constrained residential garages and workplace parking structures. Danish developers in new Copenhagen construction specify these during concrete pours to comply with Building Regulations.
- Pedestal:Freestanding posts serve outdoor public and commercial parking environments with dual-cable configurations. Municipal procurement in Aarhus prioritizes vandal-resistant designs for streetscape integration.
- Socket Outlet:Basic connector-only infrastructure without integrated electronics. Minimal deployment due to incompatibility with smart charging requirements.
- Integrated Charging Systems:Building automation convergence bundles EV charging with HVAC and lighting control. Facility managers in Odense commercial developments seek bundled energy management contracts.
- Mobile Charging Units:Temporary trailer-mounted systems for event or emergency deployment. Niche applications limited by Denmark's high fixed infrastructure density.
Wall-Mounted leads deployment counts, with Integrated Charging Systems expanding most quickly on building automation convergence.
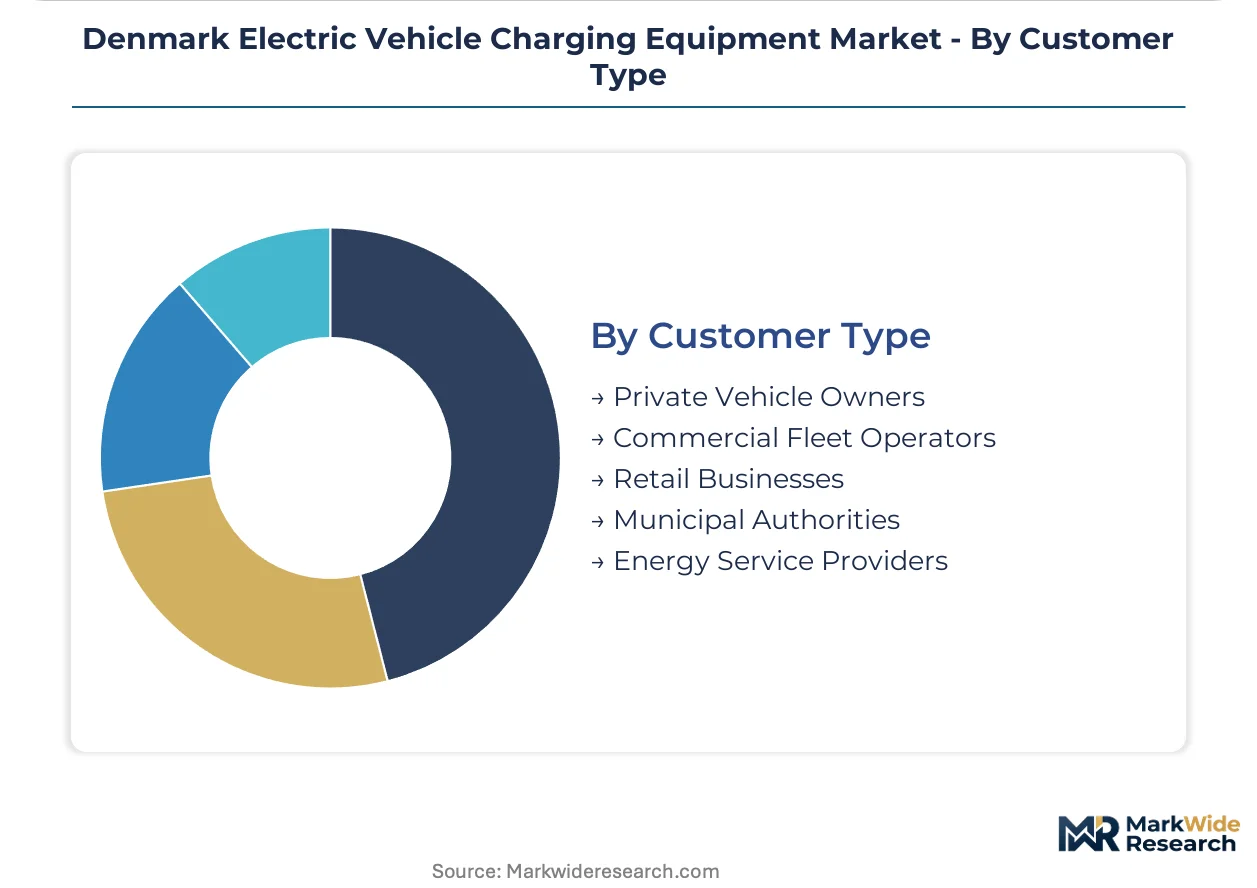
Customer Type:
Margin structures vary sharply across customer types, with Energy Service Providers capturing recurring software revenue while Retail Businesses treat charging as loss-leading amenity spend.
- Private Vehicle Owners:Individual purchasers of residential and portable charging equipment. Overnight charging penetration among single-family housing stock limits addressable market expansion for basic units.
- Commercial Fleet Operators:Logistics and transport companies deploying centralized DC fast charging for electrified vehicle pools. Danish operators accelerate procurement to serve Copenhagen and Aarhus distribution hubs.
- Retail Businesses:Supermarkets, malls, and hospitality venues installing customer-facing charging points. Bundled sustainability reporting drives procurement alongside foot traffic objectives.
- Municipal Authorities:City and regional governments deploying public infrastructure and fleet electrification. Copenhagen's municipal charging density targets concentrate demand in the capital region.
- Energy Service Providers:Utilities and independent operators offering charging-as-a-service with bundled energy management. Cloud-based load management platforms enable recurring revenue decoupled from hardware sales.
Private Vehicle Owners holds the largest customer base, with Energy Service Providers showing the steepest expansion trajectory on platform monetization models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's DC fast charging corridor density exceeds Denmark's by roughly threefold, yet Danish fleet electrification mandates are compressing deployment timelines faster than any Nordic neighbor.
Zealand
Copenhagen metropolitan employers drive workplace charging procurement under EU CSRD sustainability reporting obligations. The Danish Transport, Construction and Housing Authority enforces Building Regulations mandating EV-ready conduit in new parking structures. Greater Copenhagen developers pre-wire entire underground garages during concrete pours.
Jutland
Logistics operators accelerate DC fast charger procurement to electrify heavy-duty corridors serving Aarhus distribution hubs. CE marking requirements under EU harmonized standards govern electromagnetic compatibility for all equipment deployed. Aalborg municipal fleet managers lead transitions toward subscription-based load management platforms.
Funen
Odense commercial developments seek bundled energy management contracts integrating EV charging with HVAC and lighting control systems. The Danish Energy Agency coordinates grid integration standards for high-capacity charging clusters. Sparse highway coverage along E20 routes between Odense and Esbjerg creates first-mover positioning opportunities.
North Denmark Region
Energinet's interconnection approval timelines delay high-capacity cluster deployments, compressing investor returns for ultra-fast charging stations. Grid tariff structure revisions will determine site economics for 150kW+ installations requiring harmonic filtering expertise. Residential overnight charging penetration among single-family housing stock limits addressable market expansion for basic Level 2 units.
Denmark Electric Vehicle Charging Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hardware vendors competing on silicon carbide power electronics while software platforms capture recurring revenue through cloud-based load management. The vendor base concentrates around integrated energy management systems and DC fast charging specialization. Two strategic archetypes dominate: building automation convergers bundling EV charging with facility controls, and highway corridor specialists deploying modular 350kW units. M&A activity targets software-defined energy management capabilities, while capacity expansion focuses on compact silicon carbide inverter designs.
Among Nordic-origin specialists, Zaptec occupies a position exemplifying cloud-platform monetization models, while Clever anchors the mobility service provider archetype. ABB sits within the industrial electrification tier, representing DC fast charging specialization for infrastructure-scale deployments. These three entities collectively illustrate the market's pivot from hardware-centric competition toward software-defined service architectures.
| Leading Market Players |
|---|
| Zaptec |
| Schneider Electric |
| Siemens |
| ABB |
| EVBox |
| Wallbox |
| Tesla |
| Clever |
| E.ON |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up charging infrastructure specialists have consolidated component sourcing across Nordic supply bases, compressing procurement leverage into fewer vendor relationships while enforcing price discipline through volume commitments to silicon carbide foundries.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for power electronics modules, forcing Danish equipment vendors toward subscription-SaaS tiered pricing models that decouple revenue from hardware margins. Price differentiation hinges on CE certification tier and after-sales service bundling, with municipal fleet operators showing lowest price sensitivity due to EU CSRD compliance mandates, while housing associations drive hardest bargain on basic AC units.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs has elevated inventory carrying costs for Danish distributors, concentrating procurement around China, Germany, and South Korea for silicon carbide wafers, copper cabling, and power electronics assemblies. The supply chain rests on single-source vulnerability for 350kW inverter modules, with distribution running through Energinet-certified integrators serving Jutland and Zealand deployment clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's Building Regulations create a regulatory arbitrage window against German and Swedish markets where retrofit economics dominate, rewarding early positioning in new construction partnerships across Greater Copenhagen.
For Market Incumbents: To counter silicon carbide power electronics commoditization, ABB and Schneider Electric should deepen backward integration into inverter module design while securing exclusive distribution agreements with Zealand housing associations before subscription platforms lock in switching costs. For New Entrants and Emerging Players: Direct-to-installer digital channels offer the lowest-friction entry path, targeting Odense and Esbjerg corridor gaps with modular 150kW units positioned between incumbent premium tiers and basic fleet offerings. For Investors and Strategic Acquirers: Energy service providers are the most active acquirer in this space, consolidating cloud-platform capabilities ahead of grid tariff restructuring; target asset-light software vendors with Energinet integration certifications and municipal contract backlogs as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures inverter module priority allocation from Taiwanese foundries amid capacity constraints. |
| Cloud Platform Integration | Enables recurring revenue capture from Aalborg municipal fleet load management contracts. |
| Building Automation Partnership | Positions charging hardware within Odense commercial HVAC-lighting bundled contracts. |
| Highway Corridor Deployment | Captures first-mover positioning along E20 gaps between Odense and Esbjerg. |
| Energinet Certification Investment | Accelerates grid interconnection approval timelines for 350kW cluster deployments. |
Research Methodology
Direct dialogue with charging infrastructure procurement managers, municipal fleet operators, electrical contractors, and Energinet grid integration engineers informed primary intelligence, cross-referenced against Danish Building Regulations filings, CE marking databases, Energinet interconnection queues, and EU CSRD implementation guidance, with bottom-up installation forecasts triangulated against top-down vehicle electrification targets.
Bottom-up modeling of unit shipments across power tiers, installation contexts, and customer archetypes was reconciled with top-down expenditure projections from municipal capital budgets and fleet operator procurement disclosures over the analysis window. Segmentation dimensions included charger power class, deployment setting, and regional regulatory cluster, with CAGRs derived from installed base replacement cycles and electrification mandate compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for wireless inductive charging would alter the outlook for conductive infrastructure investments. Forecasts reflect assumptions around grid tariff stability and copper price normalization. A model refresh is warranted upon material change in Denmark's Building Regulations or Energinet interconnection fee structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Global EV Charging Piles Market