
 Neighbourhood Electric Vehicle Market | 2026-2036
Neighbourhood Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Neighbourhood Electric Vehicle Market Insights
Retirement community transport is shifting from gasoline-powered golf carts to street-legal low-speed electric vehicles. Polaris sustains dominant brand recognition across resort and private-community channels. Club Car leverages vertical manufacturing integration to control chassis and battery pack costs. Kandi Technologies Group anchors its position through aggressive pricing in North American dealership networks.
Neighbourhood electric vehicles are battery-powered road vehicles engineered for operation on public roads with posted speed limits of 35 mph or less, typically featuring enclosed cabs, three- or four-wheel configurations, and lithium-ion or lead-acid propulsion systems designed for short-distance passenger and light-cargo transport. Low-Speed Vehicles dominate unit volume owing to regulatory permissiveness in US states, while Battery Electric technology leads absolute sales as municipalities phase out internal-combustion fleet purchases. Corporate Fleets represent the fastest-growing end-user category as campus logistics operators replace aging utility vehicles with zero-emission alternatives.
The US NHTSA Federal Motor Vehicle Safety Standards for low-speed vehicles and EPA emissions regulations jointly define product eligibility and market access for manufacturers selling into American jurisdictions. State-level departments of motor vehicles administer registration, insurance, and road-use permissions that vary considerably between Florida, California, and Arizona. Stakeholders must monitor evolving municipal procurement specifications and battery recycling mandates that will reshape supplier qualification requirements.
Market Dynamics
Municipal fleet electrification mandates are compressing procurement cycles across North American cities, forcing manufacturers to accelerate NHTSA certification timelines and expand lithium-ion pack production capacity ahead of traditional automotive development schedules.
Growth Catalysts
- US EPA tailpipe standards:Federal emissions thresholds are eliminating internal-combustion utility vehicles from municipal bid pools, redirecting capital toward zero-emission alternatives.
- Retirement community transport:Master-planned developments in Florida and Arizona are replacing gasoline golf carts with street-legal enclosed cabs for resident mobility.
- Lithium-ion chemistry:Energy density improvements are extending single-charge range beyond 50 miles, satisfying daily-use requirements for campus logistics operators.
Market Restraints
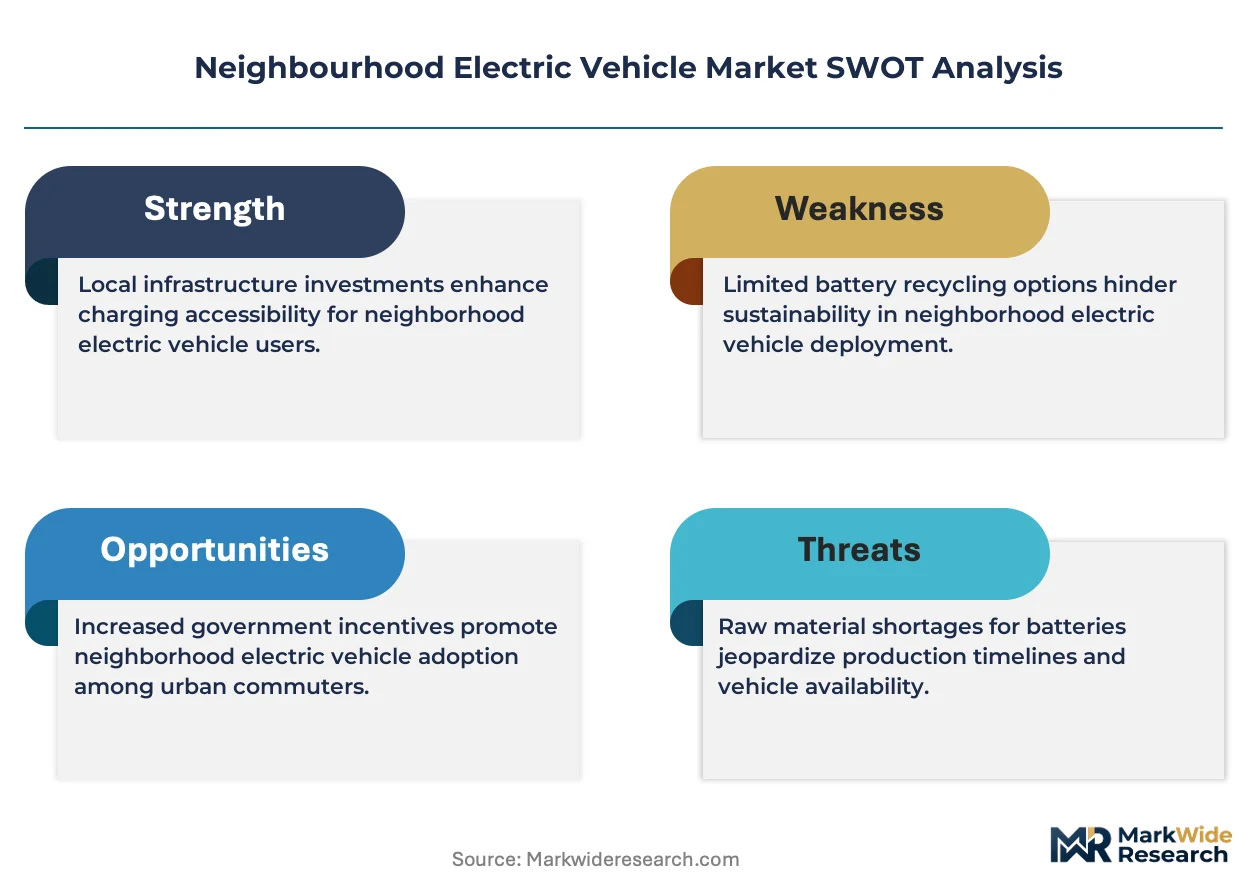
- Battery raw material concentration:Cathode active material supply chains cluster in Chinese processing facilities, exposing North American assemblers to export control volatility.
- NHTSA low-speed vehicle standards:Federal crashworthiness requirements mandate automotive-grade braking and lighting systems that inflate base chassis costs relative to off-road alternatives.
- Golf cart substitution:Unregulated off-highway vehicles priced 40-60% below street-legal equivalents capture price-sensitive buyers in private communities without road-access requirements.
Strategic Opportunities
- Corporate campus logistics:Technology and healthcare campuses in California and Texas are piloting autonomous low-speed shuttles for employee transport between parking structures and core facilities.
- Battery second-life applications:Retired automotive packs are entering refurbishment channels for NEV propulsion, creating circular supply economics for cost-sensitive fleet operators.
- State ZEV mandates:California Air Resources Board requirements are cascading into procurement specifications for municipal service vehicles in adjacent western states.
Industry Challenges
- Automotive electronics integration:NHTSA-compliant control modules require software validation protocols that extend development timelines by 8-12 months for traditional golf cart manufacturers.
- Technician certification gaps:High-voltage safety training for lithium-ion systems remains scarce in dealership networks outside major metropolitan markets, constraining service coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neighbourhood Electric Vehicle Market |
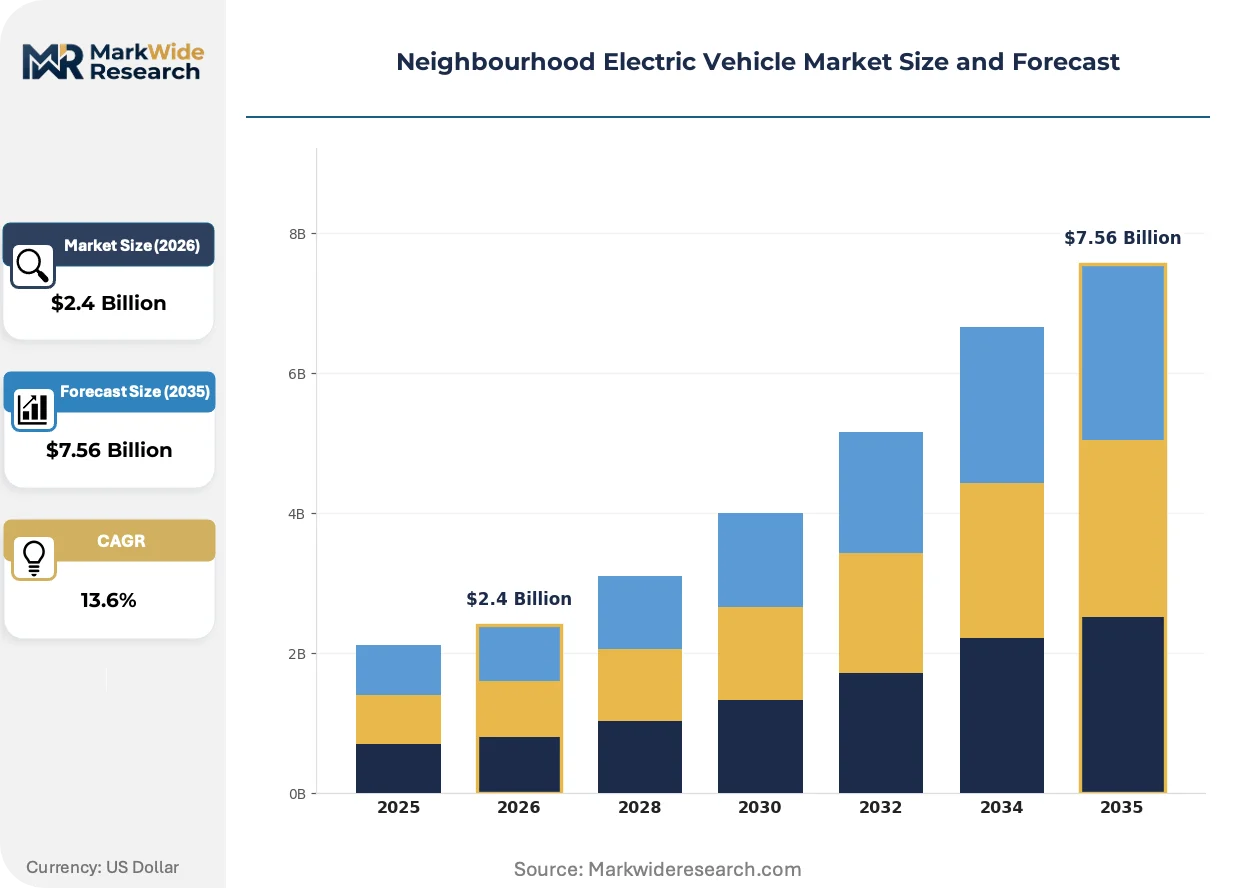
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.56 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Speed Vehicles, Electric Scooters, Electric Bicycles, Golf Carts End User: Retail Customers, Municipalities, Corporate Fleets, Educational Institutions Technology: Battery Electric, Plug-in Hybrid, Hydrogen Fuel Cell, Regenerative Braking Distribution Channel: Online Retail, Dealerships, Direct Sales, Leasing Companies |
| Companies Covered | Textron Specialized Vehicles, Polaris, Club Car, Yamaha Golf-Car, Shifeng Group, Yogomo, Kandi Technologies Group, Garia, Columbia Vehicle Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neighbourhood Electric Vehicle Market Trends and Innovations
Electrification is penetrating vehicle categories previously dominated by small internal-combustion engines, with connectivity and autonomous operation emerging as secondary differentiators beyond powertrain technology.
Lithium iron phosphate battery architecture is consolidating across the low-speed vehicle segment due to thermal stability advantages in enclosed-cab configurations. Fleet operators in Arizona and Nevada are specifying this chemistry for summer temperature exposure. The technology is consolidating supplier relationships around three dominant cell producers with automotive validation credentials.
US NHTSA Federal Motor Vehicle Safety Standard 500 compliance requirements are expanding to cover autonomous operation capabilities. Manufacturers must now submit validation data for electronic stability control and automated emergency braking systems. Low-speed shuttle pilots in California master-planned communities are driving this regulatory expansion.
Direct fleet procurement from manufacturers is displacing traditional dealership intermediaries for municipal and corporate buyers with volume commitments above 50 units. Arizona retirement community operators are negotiating multi-year service agreements inclusive of battery replacement schedules. This pattern is most visible in Sun Belt states with concentrated master-planned development activity.
Neighbourhood Electric Vehicle Market Segmentation
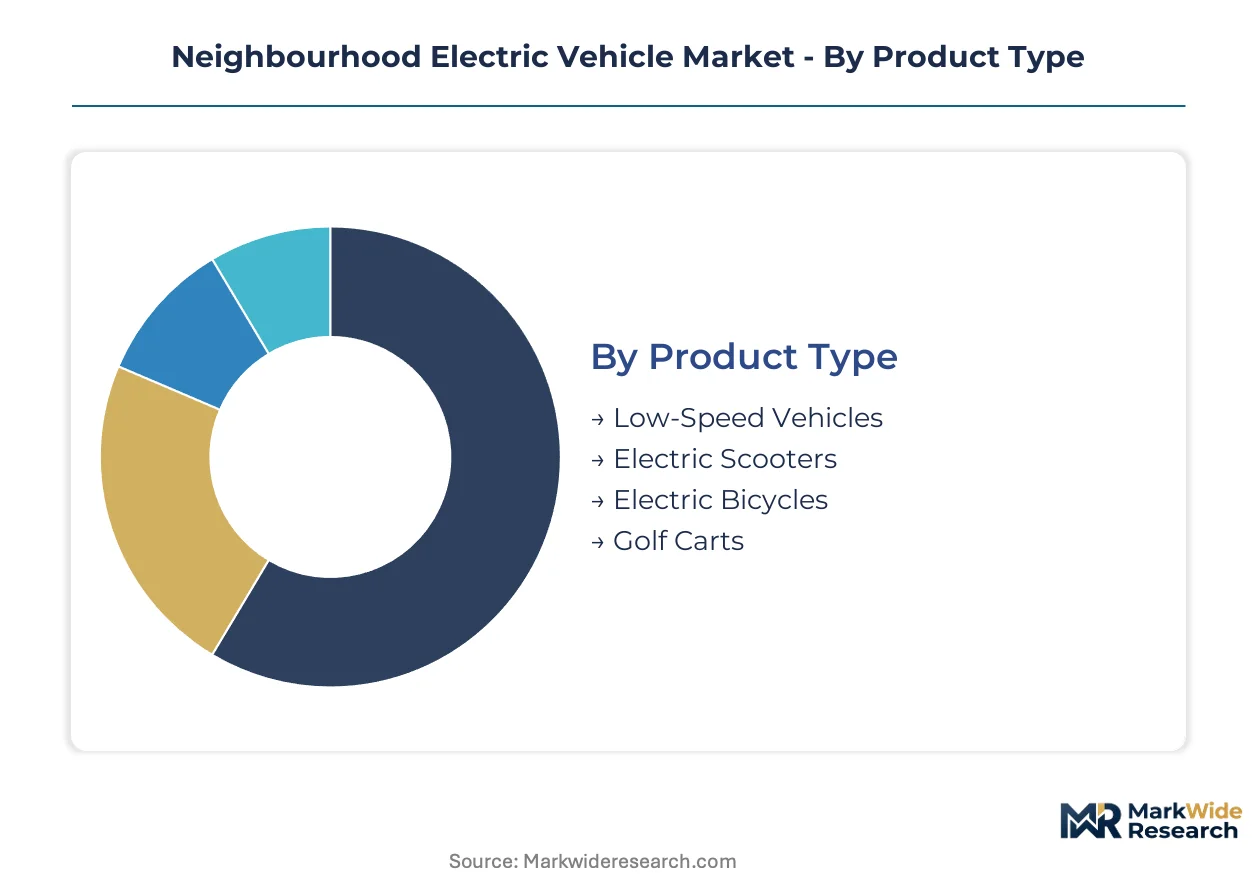
Segmentation reveals how regulatory boundaries and use-case requirements split demand across fundamentally different vehicle architectures. Manufacturers must align certification investments with the specific compliance pathways governing each product category.
Product Type:
Volume concentrates in street-legal platforms, while premium pricing attaches to recreational and utility variants lacking highway access.
- Low-Speed Vehicles:Enclosed-cab four-wheelers engineered to NHTSA Federal Motor Vehicle Safety Standard 500, featuring automotive-grade braking, lighting, and crashworthiness. Demand clusters in Florida and Arizona master-planned communities where posted speed limits of 35 mph or less enable legal road access. Municipal fleet procurement mandates in California and Texas are compressing delivery timelines for certified chassis.
- Golf Carts:Open-air or partially enclosed utility platforms historically powered by lead-acid batteries, now transitioning to lithium-ion propulsion. Retirement communities in Sun Belt states are replacing gasoline models with street-legal electric conversions, though unregulated off-highway variants capture price-sensitive buyers in private developments without road-access requirements.
- Electric Scooters:Two-wheel standing or seated platforms designed for individual mobility over distances under 10 miles. Campus logistics operators in California are piloting shared fleets for employee transport between parking structures and core facilities.
- Electric Bicycles:Pedal-assist or throttle-controlled two-wheelers occupying regulatory gray zones between bicycles and motor vehicles. Last-mile delivery contractors in Texas metropolitan markets are adopting cargo-configured variants for urban package distribution.
Today's leader: Low-Speed Vehicles. Tomorrow's challenger: Golf Carts.
End User:
Procurement authority separates fragmented individual buyers from concentrated institutional purchasers with multi-unit deployment authority.
- Corporate Fleets:Technology and healthcare campuses in California and Texas are replacing aging internal-combustion utility vehicles with zero-emission alternatives for grounds maintenance and internal logistics. Direct manufacturer procurement is displacing dealership intermediaries for volume commitments above 50 units.
- Municipalities:Cities across the US are accelerating electrification timelines under EPA tailpipe standards and state-level zero-emission vehicle mandates. Fleet managers must navigate NHTSA certification requirements while compressing traditional automotive development schedules.
- Retail Customers:Individual purchasers in Sun Belt retirement communities seek enclosed-cab alternatives to gasoline golf carts for resident mobility. Price sensitivity drives substitution toward unregulated off-highway vehicles where road access is not required.
- Educational Institutions:University campuses in Arizona and Nevada are specifying lithium iron phosphate battery architecture for summer temperature exposure in enclosed-cab configurations.
Corporate Fleets are expanding most quickly as campus logistics operators execute sustainability commitments.
Technology:
Battery chemistry choices trade energy density against thermal stability and supply chain concentration.
- Battery Electric:Lithium-ion or lead-acid propulsion systems dominating absolute sales as municipalities phase out internal-combustion fleet purchases. Lithium iron phosphate architecture is consolidating across the segment due to thermal stability advantages in enclosed-cab configurations.
- Plug-in Hybrid:Range-extended architectures retaining small internal-combustion generators for applications exceeding single-charge range requirements. Limited penetration in low-speed applications where daily use patterns fall within battery-electric capabilities.
- Hydrogen Fuel Cell:Proton-exchange membrane systems offering rapid refueling for continuous-duty fleet applications. Pilot deployments are constrained by hydrogen infrastructure availability in North American markets.
- Regenerative Braking:Kinetic energy recovery systems extending single-charge range in stop-and-go campus and community environments. Integration with NHTSA-compliant electronic stability control modules is extending development timelines.
Battery Electric commands current deployment. Hydrogen Fuel Cell holds speculative positioning for heavy-duty cycle applications.
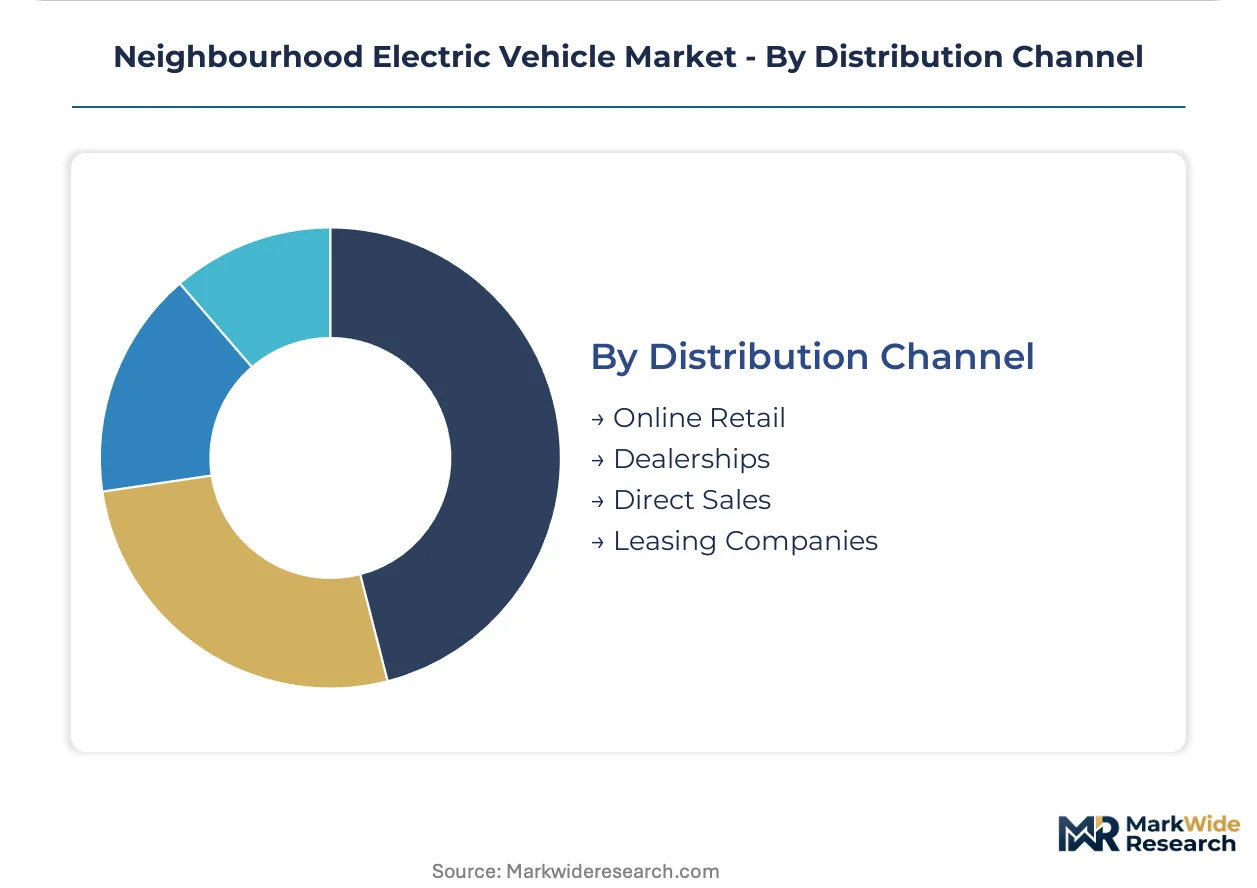
Distribution Channel:
Channel selection reflects purchase scale, service requirements, and financing preferences across buyer categories.
- Direct Sales:Manufacturer-to-fleet relationships capturing municipal and corporate buyers with volume commitments and multi-year service agreements. Arizona retirement community operators are negotiating battery replacement schedules inclusive of refurbishment timelines.
- Dealerships:Traditional retail networks serving individual purchasers and small commercial accounts. High-voltage safety training for lithium-ion systems remains scarce outside major metropolitan markets, constraining service coverage.
- Online Retail:Digital platforms capturing price-sensitive buyers for electric bicycles and entry-level electric scooters. Regulatory compliance verification falls to purchasers navigating state-level registration requirements.
- Leasing Companies:Fleet management providers offering operational lease structures for corporate and municipal accounts seeking to transfer residual value risk. Battery second-life economics are entering refurbishment channels for cost-sensitive operators.
Direct Sales is gaining share fastest among institutional purchasers. Dealerships retain fragmentation across individual buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly capacity to jurisdictions where NHTSA certification costs and state-level compliance burdens create arbitrage opportunities against European regulatory regimes. The United States retains production density for street-legal platforms, while Chinese suppliers penetrate cost-sensitive segments through pricing advantages in battery pack sourcing.
United States
Florida and Arizona master-planned communities generate concentrated demand for enclosed-cab low-speed vehicles with lithium iron phosphate battery architecture. The EPA tailpipe standards and California Air Resources Board zero-emission mandates are accelerating municipal fleet procurement timelines. Corporate campus operators in Texas and California are negotiating direct manufacturer relationships for volume commitments exceeding fifty units.
China
Domestic manufacturers supply cathode active material processing capacity that underpins North American assembler cost structures. The MIIT new energy vehicle catalog and GB standards for low-speed electric vehicles define export eligibility for suppliers targeting American jurisdictions. Zhejiang and Shandong province production clusters concentrate golf cart and low-speed vehicle chassis assembly for North American dealership networks.
Germany
Automotive-grade braking and lighting system suppliers validate components for NHTSA Federal Motor Vehicle Safety Standard 500 compliance. The KBA type approval framework and EU Green Deal electrification targets are diverting domestic manufacturer attention toward passenger car segments. Bavaria-based engineering consultancies are supporting US market entry strategies for European low-speed vehicle specialists.
Japan
METI energy density research programs and JIS standards for lithium-ion cells influence battery pack specifications in premium low-speed vehicle configurations. Domestic manufacturers are prioritizing domestic kei car and mini-vehicle segments over North American export development. Tokyo-based trading houses are facilitating cathode material supply chain relationships between Chinese processors and North American assemblers.
Canada
Health Canada environmental protection guidelines and provincial zero-emission vehicle incentives in British Columbia and Quebec are stimulating municipal pilot programs. The federal government procurement specifications for low-speed utility vehicles are aligning with US EPA tailpipe standards. Ontario manufacturing facilities are assembling NHTSA-compliant chassis for cross-border distribution to American fleet operators.
Neighbourhood Electric Vehicle Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration determining margin capture in battery pack and chassis production. The vendor base concentrates around three strategic tiers: diversified powersports conglomerates with resort channel dominance, dedicated low-speed vehicle specialists with NHTSA certification expertise, and Chinese contract assemblers with cost-positioned offerings. Competitive positioning hinges on automotive electronics integration capabilities and direct fleet procurement relationship management. Manufacturers are executing capacity expansion in lithium-ion pack assembly and strategic partnerships with cathode material suppliers to secure qualification for municipal bid pools.
Within the diversified conglomerate tier, Polaris and Textron Specialized Vehicles exemplify brand equity accumulation across resort and private-community distribution channels. Among dedicated specialists, Club Car occupies a position representing vertical manufacturing integration for chassis and battery pack cost control. Kandi Technologies Group anchors the contract assembler archetype through aggressive pricing strategies in North American dealership networks. These three players collectively illustrate how certification investment, manufacturing scope, and channel strategy differentiate competitive positioning in procurement cycles compressed by municipal electrification mandates.
| Leading Market Players |
|---|
| Textron Specialized Vehicles |
| Polaris |
| Club Car |
| Yamaha Golf-Car |
| Shifeng Group |
| Yogomo |
| Kandi Technologies Group |
| Garia |
| Columbia Vehicle Group |
| Others |
Pricing and Supply Chain Analysis
Lithium iron phosphate battery chemistry consolidation is compressing pack costs while concentrating supplier relationships around three dominant cell producers with automotive validation credentials, simultaneously lowering chassis price floors and tightening procurement leverage for North American assemblers.
Pricing Analysis
Distributor margin layers vary sharply between direct fleet procurement and dealership retail channels. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-certified chassis from off-highway conversions and refurbished battery configurations. Cost compression in economy tiers is intensifying because Chinese contract assemblers are undercutting certified competitors in private-community bids. Retail customers in Sun Belt retirement communities exhibit highest price sensitivity, while municipal fleet buyers prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Domestic-content mandates under the US Inflation Reduction Act are reshaping sourcing requirements for battery pack assembly and cathode active material procurement. Cathode processing capacity concentrates in China, South Korea, and Japan, while chassis fabrication clusters in Zhejiang and Shandong province production facilities. North American assemblers draw from Chinese cathode supply chains that face export control volatility and tariff exposure. Distribution runs through direct manufacturer relationships for fleet volumes above fifty units and traditional dealership networks for fragmented individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Neighbourhood Electric Vehicle Market functions as a regulatory compounder where EPA tailpipe standards and state-level zero-emission vehicle mandates are compressing procurement cycles and redirecting municipal capital toward certified zero-emission alternatives.
For Market Incumbents: Cement NHTSA certification expertise as a defensible moat against emerging golf cart converters seeking street-legal status. Deepen in-house production of lithium iron phosphate battery packs to capture margin erosion from Chinese cell suppliers. Expand direct fleet procurement relationships in Texas and California corporate campuses before dealership networks recover service coverage for high-voltage systems.
For New Entrants and Emerging Players: Capture white-space opportunity in autonomous low-speed shuttle pilots across California master-planned communities where NHTSA Federal Motor Vehicle Safety Standard 500 compliance requirements are expanding to cover automated operation. Target Arizona and Nevada educational institutions specifying thermal-stable battery architecture for summer temperature exposure. Lead with battery second-life refurbishment economics as a service-inclusive pricing model.
For Investors and Strategic Acquirers: Valuations sit cheapest among dedicated low-speed vehicle specialists with NHTSA certification expertise but limited lithium-ion pack assembly scale. Long-term viability hinges on automotive electronics integration capabilities and direct fleet relationship management rather than resort channel brand equity. Watch California Air Resources Board mandate cascading into adjacent western state procurement specifications as the inflection indicator for municipal demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NHTSA Certification Investment | Automotive-grade braking and lighting validation opens municipal bid pools under EPA tailpipe standards. |
| Lithium Iron Phosphate Pack Assembly | Thermal stability advantages satisfy Arizona and Nevada fleet specifications for enclosed-cab configurations. |
| Direct Fleet Procurement Relationships | Manufacturer-to-fleet contracts displace dealership intermediaries for volume commitments exceeding fifty units. |
| Battery Second-Life Refurbishment | Retired automotive packs create circular supply economics for cost-sensitive campus logistics operators. |
| Autonomous Operation Validation | Electronic stability control and automated emergency braking data submission addresses expanding FMVSS 500 requirements. |
Research Methodology
Multiple input streams — OEM platform engineering directors, municipal fleet procurement managers, lithium-ion cell supplier account executives, and dealership service operations heads — were reconciled against NHTSA certification databases, EPA emissions compliance filings, and state-level zero-emission vehicle mandate documentation. Secondary validation drew from vehicle production registries, municipal bid award records, and cathode material trade flow data. Bottom-up unit deployment estimates and top-down market sizing were triangulated across the analysis window.
Cross-reference between historical procurement velocity and expert panel input shaped the analytical framework across product type, end user, battery chemistry, and distribution channel segmentation dimensions. CAGRs were derived from modeled deployment trajectories incorporating NHTSA certification timeline compression and lithium-ion pack cost curves. Forecast inputs included municipal electrification mandate adoption rates and retirement community master-planned development pipeline data.
Regulatory timeline acceleration, cathode material export control actions, and autonomous operation standard finalization are the dominant revision risks that could shift deployment trajectories. Forecasts reflect documented assumptions about NEV eligibility definitions and fleet replacement cycle timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Moped Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market