
 Electric Vehicle Electronic Expansion Valve (EXV) Market | 2026-2036
Electric Vehicle Electronic Expansion Valve (EXV) Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Electronic Expansion Valve (EXV) Market Insights
Buyer concentration among OEMs is decoupling from traditional tiered supply structures as vehicle assemblers bring thermal system specification in-house. Danfoss A/S leverages its refrigerant controls heritage to anchor European premium EV programs. Fujikoki Corporation competes through precision machining capabilities that sustain Japanese OEM relationships. Denso Corporation dominates integrated thermal module supply, extending its position from combustion-era climate systems into battery cooling architectures.
An electric vehicle electronic expansion valve modulates refrigerant flow through superheat control via stepper motor or pulse-width modulation, maintaining evaporator outlet temperatures within ±0.5°C to protect lithium-ion cells from thermal runaway. Modulating valve configurations command attention as OEMs replace simpler on-off designs for multi-zone battery pack cooling. Electronic technology leads the technology dimension, displacing thermal and pneumatic alternatives as 800V architectures demand faster response loops. OEM end users concentrate procurement decisions at the platform level, compressing tier-1 supplier margins while vehicle assemblers internalize EXV specification authority.
China's MIIT enforces GB/T energy consumption standards that mandate precise thermal management efficiency verification for NEV homologation. The EPA and NHTSA in the United States coordinate refrigerant leakage and safety testing protocols that shape EXV sealing and materials requirements. Europe's ECHA REACH restrictions on perfluorinated compounds are forcing refrigerant transitions that demand redesigned valve compatibility. Stakeholders must monitor how regulatory divergence between refrigerant chemistries and voltage platform standards fragments supplier qualification burdens across regional production footprints.
Market Dynamics
Platform-level thermal system specification authority is migrating from tier-1 suppliers to OEM engineering centers, compressing supplier margins while accelerating modulating EXV adoption for 800V battery architectures.
Growth Catalysts
- MIIT Efficiency Mandates:China's GB/T energy consumption verification requirements for NEV homologation force precise refrigerant control system upgrades across domestic production lines.
- 800V Electrification:High-voltage battery platforms demand faster thermal response loops that only electronic superheat control can deliver, eliminating thermal and pneumatic alternatives.
- Stuttgart-Munich Manufacturing Corridor:German OEM concentration around premium EV programs creates concentrated procurement pull for precision-machined modulating valves.
Market Restraints
- Copper and Rare Earth Input Volatility:Stepper motor windings and permanent magnet materials expose valve producers to commodity price swings that resist pass-through pricing.
- Japanese Precision Machining Concentration:Critical sealing surface capabilities cluster among specialized suppliers in Aichi and Shizuoka prefectures, creating single-source vulnerability.
- ECHA REACH Transition Costs:Perfluorinated compound restrictions force refrigerant chemistry pivots that require complete valve material qualification cycles.
Strategic Opportunities
- Indian NEV Manufacturing Scale-Up:PLI scheme incentives for domestic battery and thermal component production open qualification pathways for localized EXV supply.
- Multi-Zone Battery Cooling Architectures:Cell-to-pack designs with zonal thermal management expand addressable valve counts per vehicle beyond single-evaporator configurations.
- Service Channel Integration:Predictive thermal management diagnostics create aftermarket valve replacement revenue streams tied to battery health monitoring platforms.
Industry Challenges
- Embedded Software Validation:EXV control algorithms require ASIL-D functional safety certification timelines that extend development cycles by 18-24 months.
- Thermal System Integration Complexity:Battery pack engineers must coordinate valve response with heat pump mode switching, creating cross-functional coordination burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Electronic Expansion Valve (EXV) Market |
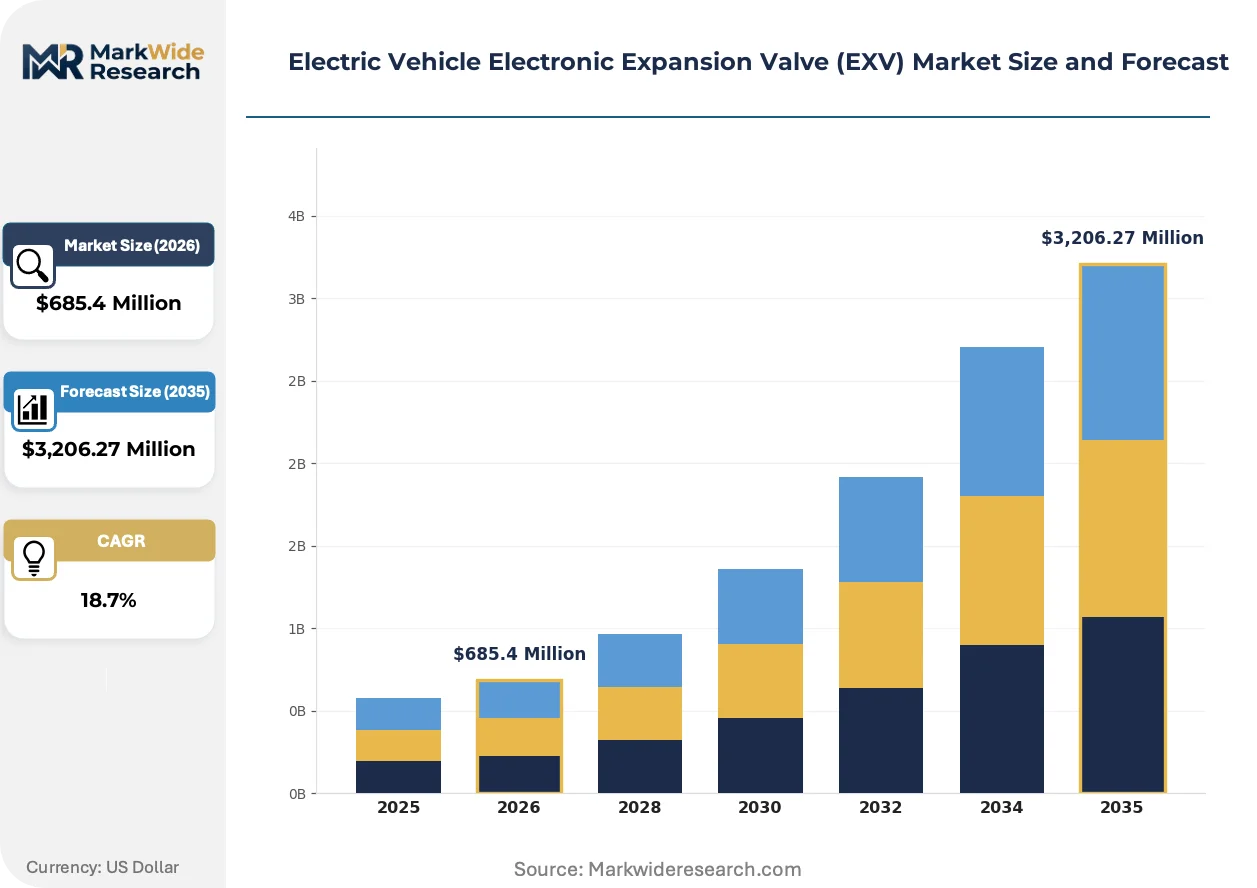
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Off Valve, Modulating Valve, Safety Valve, Control Valve Technology: Thermal, Electronic, Pneumatic, Mechanical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Chilling Systems, HVAC Systems, Refrigeration, Temperature Control |
| Companies Covered | Danfoss A/S, Fujikoki Corporation, Denso Corporation, MAHLE GmbH, Mitsubishi Electric Corporation, Sanhua Automotive, Parker Hannifin Corporation, Emerson Electric Co., Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Electronic Expansion Valve (EXV) Market Trends and Innovations
Pulse-width modulation control architectures are displacing legacy stepper motor designs as OEMs prioritize response speed over absolute positioning accuracy in dynamic thermal loads.
Silicon carbide power electronics is absorbing valve driver circuit functions into integrated thermal management controllers, consolidating PCB real estate and reducing wiring harness complexity. Tier-1 thermal module suppliers are adopting SiC-based drivers for 800V platforms within 24-month design cycles. This convergence is absorbing discrete valve controller suppliers into larger power electronics portfolios.
ECHA F-Gas Regulation phase-down schedules are forcing refrigerant transitions from R-134a toward R-1234yf and CO2 systems with divergent pressure-temperature envelopes. Valve sealing materials and orifice geometries require complete redesigns for each chemistry pathway. European OEMs are responding with parallel qualification tracks that fragment supplier engineering resources across incompatible refrigerant architectures.
Specification authority consolidation at OEM platform engineering centers is collapsing traditional tiered supply relationships for thermal components. Vehicle assemblers now issue valve performance specifications directly, relegating tier-1 suppliers to assembly and logistics roles. This pattern concentrates most visibly in German and Chinese OEM organizations where battery thermal strategy sits within central engineering functions rather than delegated climate system divisions.
Electric Vehicle Electronic Expansion Valve (EXV) Market Segmentation
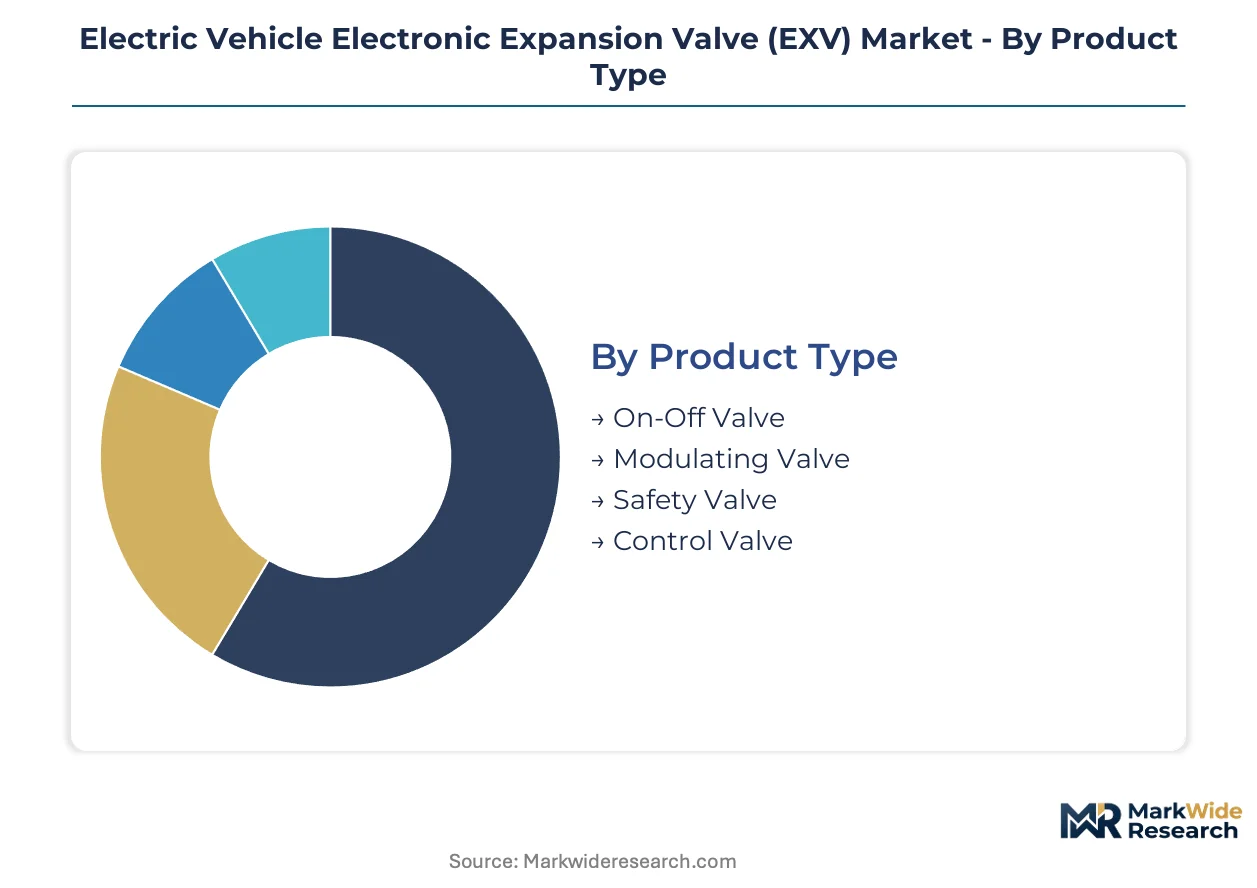
Segmentation in the Electric Vehicle Electronic Expansion Valve market reveals how thermal management complexity fragments across valve architectures, control technologies, and supply chain positions. Each dimension exposes different margin structures and qualification barriers that shape supplier strategy.
Product Type:
Integration depth varies sharply—modulating valves embed directly into battery thermal modules, while safety and control valves often operate as standalone circuit protection elements.
- Modulating Valve:These valves deliver continuous refrigerant flow adjustment through stepper motor or pulse-width modulation, maintaining evaporator outlet temperatures within ±0.5°C. Demand concentrates in Stuttgart and Munich manufacturing corridors where German OEMs specify precision-machined units for 800V battery architectures. MIIT efficiency mandates in China accelerate replacement of simpler designs.
- On-Off Valve:Binary open-close operation suits basic HVAC compressor cycling in entry-level EVs. Procurement volume clusters among cost-optimized Chinese NEV platforms where thermal management prioritizes component count reduction over zone-level precision.
- Safety Valve:Pressure-relief mechanisms protect refrigerant circuits from overpressure events during thermal runaway scenarios. Integration into battery pack enclosures is rising with cell-to-pack designs.
- Control Valve:Multi-port configurations coordinate refrigerant distribution across heat pump modes and battery cooling loops. Japanese OEM programs in Aichi Prefecture favor these for integrated thermal module architectures.
Modulating valves lead volumes today; safety valves are gaining share fastest as 800V platforms demand redundant circuit protection.
Technology:
Cost tiers separate mature thermal/pneumatic solutions from electronic architectures commanding premium positioning in high-voltage platforms.
- Electronic:Microprocessor-driven superheat control enables sub-second response loops essential for dynamic battery loads. Dominates 800V programs where pulse-width modulation displaces stepper motor designs for speed optimization.
- Thermal:Bulb-and-capillary sensing provides passive refrigerant modulation without electrical inputs. Survives only in legacy vehicle conversions and auxiliary cooling loops where response latency is acceptable.
- Pneumatic:Pressure-differential actuation persists in commercial vehicle applications with stable thermal loads. European ECHA F-Gas transitions are forcing material redesigns for compatibility with R-1234yf and CO2 pressure envelopes.
- Mechanical:Fixed-orifice restrictors serve cost-constrained auxiliary circuits. Indian PLI scheme domestic production targets these for localization before advancing to electronic designs.
Electronic technology leads volumes today; pulse-width modulation variants are climbing the fastest as OEMs prioritize response speed.
End User:
Customer type determines specification authority—OEMs increasingly internalize valve performance requirements while compressing tier-1 supplier margins.
- OEMs:Vehicle assemblers now issue direct valve specifications from platform engineering centers, bypassing traditional tier-1 climate system divisions. Battery thermal strategy sits within central engineering functions in German and Chinese organizations.
- Tier-1 Suppliers:Thermal module integrators retain assembly and logistics roles but lose specification influence. Danfoss and Denso defend positions through refrigerant controls heritage and integrated module supply respectively.
- Vehicle Assemblers:Contract manufacturers without full R&D capabilities rely on tier-1 thermal system packages. Volumes concentrate in emerging NEV production hubs seeking rapid qualification pathways.
- Aftermarket Providers:Service channel valve replacement ties to predictive battery health monitoring platforms. Revenue potential expands as first-generation EVs exit warranty periods.
OEMs lead volumes today; aftermarket providers are expanding most quickly as installed base ages.
Application:
Application maturity separates established HVAC architectures from emerging battery-specific thermal management configurations.
- Temperature Control:Zonal battery cell management demands multiple EXVs per pack, expanding valve counts beyond single-evaporator legacy designs. Cell-to-pack architectures with multi-zone cooling are the steepest expansion trajectory.
- HVAC Systems:Cabin climate control retains volume leadership but faces pressure from heat pump integration that merges battery and occupant thermal loops. German premium programs specify separate precision valves for each zone.
- Chilling Systems:Fast-charging thermal management requires dedicated refrigerant circuits to cool inlet coolant. Chinese GB/T homologation standards mandate efficiency verification for these subsystems.
- Refrigeration:Auxiliary cooling for power electronics and onboard chargers employs compact valve configurations. Japanese precision machining capabilities in Shizuoka Prefecture supply critical sealing surfaces.
HVAC systems lead volumes today; temperature control is gaining share fastest as battery architectures proliferate zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium EV thermal system engineering while China scales NEV production volume through MIIT-mandated efficiency standards, creating divergent procurement patterns across the two largest demand centers.
China
NEV production lines in Shanghai and Guangzhou absorb modulating EXV volumes as MIIT enforces GB/T energy consumption verification for homologation. The dual carbon goals accelerate refrigerant control precision requirements. Yangtze River Delta manufacturing clusters around Suzhou and Ningbo host tier-1 thermal module assembly operations serving BYD and Tesla Shanghai.
Germany
Stuttgart and Munich anchor European precision valve demand as BMW, Mercedes-Benz, and Porsche specify 800V battery architectures requiring ±0.5°C evaporator control. KBA type-approval processes coordinate with ECHA F-Gas Regulation phase-down schedules. Baden-Württemberg suppliers cluster around Denso and MAHLE production facilities in Ludwigsburg and Stuttgart.
United States
EPA refrigerant leakage protocols and NHTSA safety testing shape EXV sealing material specifications for Detroit Three EV programs. IRA production tax credits incentivize domestic battery thermal component sourcing. Michigan's automotive corridor around Detroit and Lansing concentrates engineering specification authority for North American platforms.
Japan
Aichi and Shizuoka prefectures retain critical precision machining capabilities for valve sealing surfaces serving Toyota and Honda integrated thermal modules. METI technology roadmaps prioritize heat pump efficiency targets. Nagoya-area suppliers coordinate with Denso and Fujikoki manufacturing networks for domestic OEM programs.
India
PLI scheme incentives for domestic NEV component production open qualification pathways for localized EXV supply as Tata Motors and Mahindra scale electric platforms. BIS standards adoption lags European and Chinese regulatory stringency. Tamil Nadu and Gujarat manufacturing hubs attract tier-1 thermal system investments from global suppliers.
Electric Vehicle Electronic Expansion Valve (EXV) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Tier-1 thermal module integrators retain assembly scale but surrender specification authority to OEM platform engineering centers. Component specialists defend margin through precision machining capabilities and refrigerant controls heritage. Strategic moves concentrate on backward integration into valve controller electronics and geographic expansion into Indian PLI scheme jurisdictions.
Within the diversified industrial tier, Danfoss A/S and Parker Hannifin Corporation occupy positions anchored by refrigerant and fluid controls heritage spanning multiple thermal system categories. Denso Corporation exemplifies the integrated module supplier archetype, extending combustion-era climate system relationships into battery cooling architectures. Fujikoki Corporation represents precision machining specialists concentrated in Japanese supply relationships.
| Leading Market Players |
|---|
| Danfoss A/S |
| Fujikoki Corporation |
| Denso Corporation |
| MAHLE GmbH |
| Mitsubishi Electric Corporation |
| Sanhua Automotive |
| Parker Hannifin Corporation |
| Emerson Electric Co. |
| Valeo SA |
| Others |
Pricing and Supply Chain Analysis
800V architecture adoption across European and Chinese OEM programs is compressing valve response time requirements while concentrating precision machining demand in specialized supplier clusters. This technical transition simultaneously elevates electronic control premiums and exposes buyers to single-source dependencies in Japanese sealing surface capabilities.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electronic modulating valves as domestic tier-1 suppliers scale assembly operations. Three-tier pricing structure across precision-machined premium, mid-grade electronic, and cost-optimized mechanical tiers separates German OEM specifications from Chinese NEV platform procurement. Cost compression in the economy tier is intensifying because MIIT efficiency mandates force rapid design cycle turnover. Tier-1 thermal module integrators exhibit highest price sensitivity as OEMs internalize specification authority; precision machining specialists command lowest sensitivity due to irreplaceable sealing surface capabilities.
Supply Chain Analysis
ASIL-D functional safety certification gates entry into 800V platform supply, forcing valve controller suppliers through 18-24 month qualification timelines. Manufacturing concentrates in Germany, China, and Japan, with Aichi and Shizuoka prefectures anchoring critical sealing surface production. Copper winding and rare earth magnet inputs draw from concentrated mining jurisdictions, exposing producers to commodity volatility that resists contractual pass-through. Single-source vulnerability in Japanese precision machining creates structural risk for European and North American OEM programs. Distribution runs through tier-1 thermal module integrators who retain assembly and logistics roles while surrendering specification influence to OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority migration toward OEM platform engineering centers has transformed this market into a late-cycle quality story where precision-machined modulating valves for 800V architectures command sustainable premiums over commodity alternatives.
For Market Incumbents: Deepen backward integration into silicon carbide valve driver electronics before power electronics consolidation absorbs discrete controller functions. Defend margin position through captive precision machining investments in Aichi Prefecture supplier networks to offset Japanese single-source vulnerability. Prioritize ASIL-D certification maintenance as emerging Chinese competitors accelerate electronic control development cycles. For New Entrants and Emerging Players: Indian contract vehicle assemblers lack full R&D capabilities and present the most penetrable buyer archetype for localized EXV supply under PLI scheme incentives. Target Tamil Nadu and Gujarat manufacturing hubs seeking rapid thermal component qualification pathways. Pursue joint development agreements with tier-1 thermal module integrators relegated to assembly roles by OEM specification authority consolidation. For Investors and Strategic Acquirers: Valuations sit cheapest among precision machining specialists with irreplaceable sealing surface capabilities and established Japanese OEM relationships. Long-term viability over the mid-cycle horizon rests on refrigerant chemistry transition readiness as ECHA F-Gas regulations force R-1234yf and CO2 system redesigns. Monitor ECHA REACH restriction announcements as the critical signal for valve material qualification cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Driver Integration | Absorbs discrete valve controller functions into consolidated thermal management electronics for 800V platforms. |
| Precision Machining Capability Acquisition | Secures irreplaceable sealing surface production concentrated in Aichi and Shizuoka prefectures. |
| ASIL-D Certification Investment | Enables supply qualification for battery thermal management systems requiring functional safety compliance. |
| Indian PLI Scheme Localization | Opens qualification pathways for domestic EXV supply as Tata Motors and Mahindra scale electric platforms. |
| Multi-Zone Battery Cooling Development | Expands valve counts per vehicle beyond single-evaporator configurations in cell-to-pack architectures. |
Research Methodology
Bottom-up OEM platform modeling reconciled against top-down tier-1 supplier production tracking forms the analytical core of this study. Primary interviews with thermal system procurement directors, OEM platform engineers, valve controller R&D leads, and aftermarket service channel managers combined with secondary validation from MIIT GB/T filings, KBA type-approval databases, EPA refrigerant leakage protocols, and ECHA F-Gas regulation schedules. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of modulating valve adoption rates across 800V platform introductions established baseline penetration curves. The forecast framework segments by valve architecture, control technology, end-user authority position, and application thermal load complexity across the projection horizon. CAGRs derive from vehicle production forecasts weighted by battery thermal management content per platform. Key inputs include OEM platform electrification roadmaps, MIIT NEV efficiency mandate enforcement timelines, and ECHA refrigerant phase-down schedules.
Underlying measurement precision varies by segment; electronic modulating valves for 800V platforms carry tighter precision than mechanical auxiliary circuit configurations. Forecasts reflect assumptions regarding OEM specification authority migration rates, refrigerant chemistry transition timing, and rare earth supply stability. A model refresh is warranted upon material change in ECHA F-Gas regulation enforcement or MIIT GB/T standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Solar Electric Car Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market