
 Isoleucine Market | 2026-2036
Isoleucine Market Size, Share, and Industry Trends Forecast 2026-2036
Isoleucine Market Outlook
Modular dosing formats are restructuring buyer choice across the isoleucine value chain. Single-serve sachets and stackable capsule systems now compete with bulk powder for shelf space. Ajinomoto Co., Inc. leverages its fermentation heritage to dominate pharmaceutical-grade supply. Evonik Industries AG specializes in precision nutrition applications with high-purity isolates. Xintai Jiahe Biotech Co., Ltd. anchors cost-sensitive segments through integrated fermentation infrastructure.
Isoleucine is a branched-chain amino acid (BCAA) with the molecular formula C6H13NO2, produced industrially via microbial fermentation of carbohydrate feedstocks or enzymatic synthesis from precursors. It serves as an essential building block for muscle protein synthesis, energy metabolism regulation, and therapeutic formulations addressing metabolic disorders. Crystalline grades command premium positioning in pharmaceutical applications where purity thresholds exceed 99 percent. Powder formats sustain volume leadership across nutritional supplements and food fortification due to blending flexibility and lower unit economics. Animal feed applications represent a maturing channel with stable offtake but compressed margins relative to human nutrition segments.
Food and Drug Administration oversight of dietary supplement labeling shapes product claims and channel access in the United States. The European Food Safety Authority evaluates novel food applications and health claim substantiation for isoleucine-fortified products. China's National Medical Products Administration and Ministry of Ecology and Environment jointly govern fermentation facility licensing and environmental compliance for amino acid manufacturers. Stakeholders must monitor evolving purity standards and regional certification divergence to protect market access and margin structures.
Market Dynamics
Fermentation technology advances from Chinese biotech clusters are compressing production costs and redrawing competitive boundaries across pharmaceutical and nutritional grade supply tiers.
Growth Catalysts
- BCAA supplementation protocols:Sports nutrition formulators are expanding isoleucine inclusion in pre-workout and recovery matrices. Athlete demand for leucine-isoleucine-valine stacking drives volume.
- GB standards harmonization:China's updated fermentation facility codes under NMPA-MEE joint oversight are streamlining licensing for amino acid producers. Domestic scale advantages accelerate export capacity buildup.
- Precision nutrition platforms:Metabolic health applications targeting glucose regulation and muscle preservation in aging populations are opening clinical-grade channels beyond traditional sports use.
Market Restraints
- Corn dextrose feedstock volatility:Carbohydrate substrate costs fluctuate with agricultural commodity cycles. Fermentation economics remain tethered to grain futures.
- Jiangsu-Zhejiang supply concentration:Over half of global fermentation capacity sits within a 300-kilometer radius. Geographic clustering creates disruption vulnerability.
- Enzymatic synthesis substitution:Cell-free biocatalytic routes from precursors threaten microbial fermentation's cost edge in pharmaceutical-grade segments.
Strategic Opportunities
- India nutraceutical import substitution:CDSCO's streamlined novel food pathways and FSSAI fortification allowances are creating domestic manufacturing incentives. Local fermentation infrastructure remains underdeveloped.
- Personalized amino acid profiling:At-home metabolic testing kits are enabling individualized BCAA dosing. Direct-to-consumer subscription models bypass traditional retail.
- South Korea functional food mandates:MFDS guidelines encouraging protein fortification in senior nutrition products are expanding food-grade isoleucine absorption.
Industry Challenges
- Pharmaceutical-grade validation timelines:FDA and EMA purity certification cycles extend 18-24 months. Working capital intensity strains mid-scale producers.
- Cross-border environmental compliance:MEE wastewater discharge standards and REACH chemical registration requirements impose dual-track facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoleucine Market |
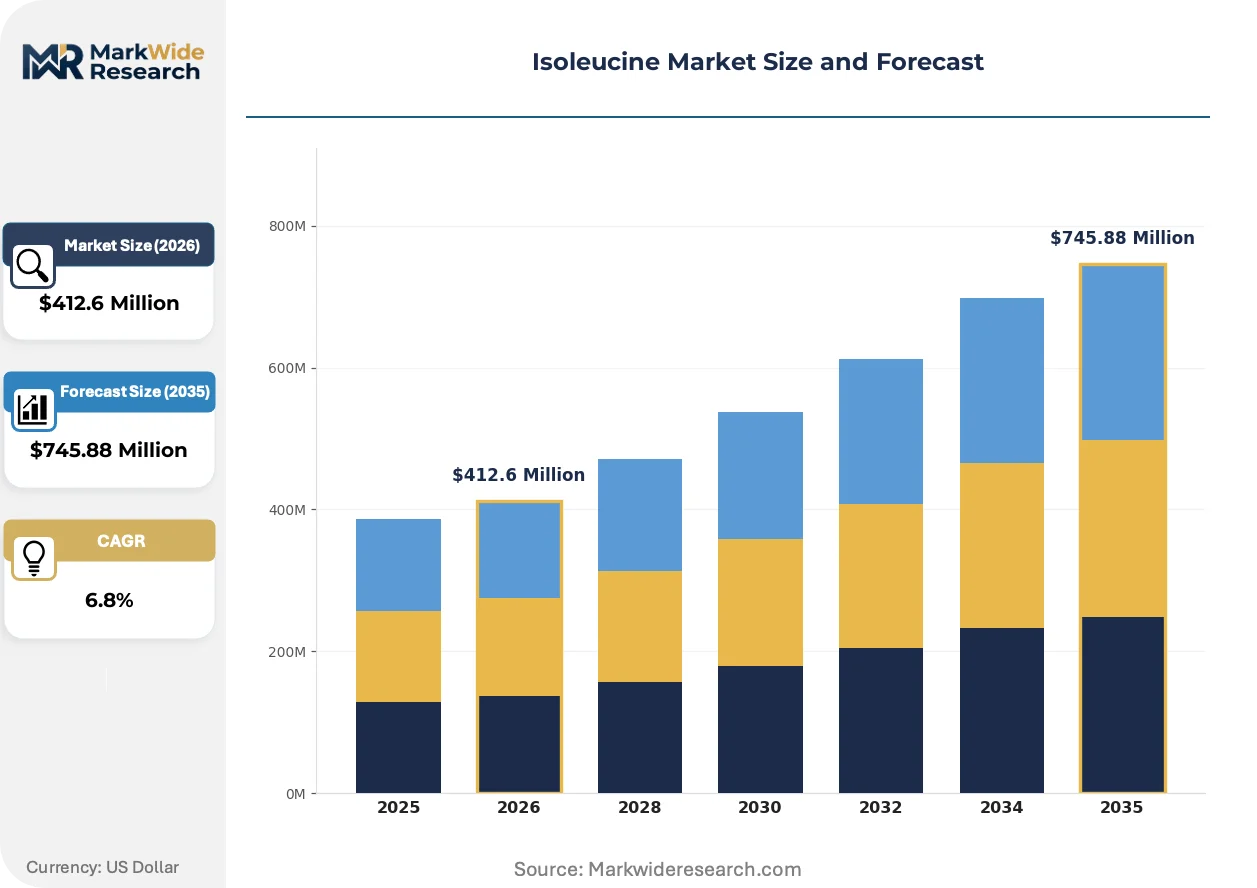
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline, Powder, Granules, Liquid Application: Nutritional Supplements, Food & Beverages, Pharmaceuticals, Animal Feed End User: Athletes, Health Enthusiasts, Hospitals, Research Institutions Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Xintai Jiahe Biotech Co., Ltd., Meihua Holdings Group Co., Ltd., Fufeng Group, CJ CheilJedang Corp, Showa Denko, Kyowa Hakko Bio Co., Ltd., Wuxi Jinghai Amino Acid Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoleucine Market Strategic Shifts
Continuous fermentation systems and single-use bioreactor designs are displacing batch processes. These hardware shifts enable real-time quality monitoring and reduce contamination risk.
Cell-free enzymatic synthesis using engineered dehydrogenases is rewriting cost structures for high-purity pharmaceutical grades. Contract manufacturers in Basel and Boston are piloting these platforms. The technology is compressing fermentation's historical moat in sub-100-kilogram batches.
EFSA's 2023 guidance on branched-chain amino acid health claim substantiation is tightening evidentiary requirements for muscle maintenance claims. European sports nutrition brands are reformulating label language. The policy shift is diverting marketing investment toward clinical trial sponsorship.
Buyers in performance nutrition are consolidating supplier relationships around integrated amino acid portfolios. Single-source contracts covering leucine, isoleucine, and valine are displacing spot purchasing. This concentration is most visible among North American private-label contract manufacturers.
Isoleucine Market Segmentation
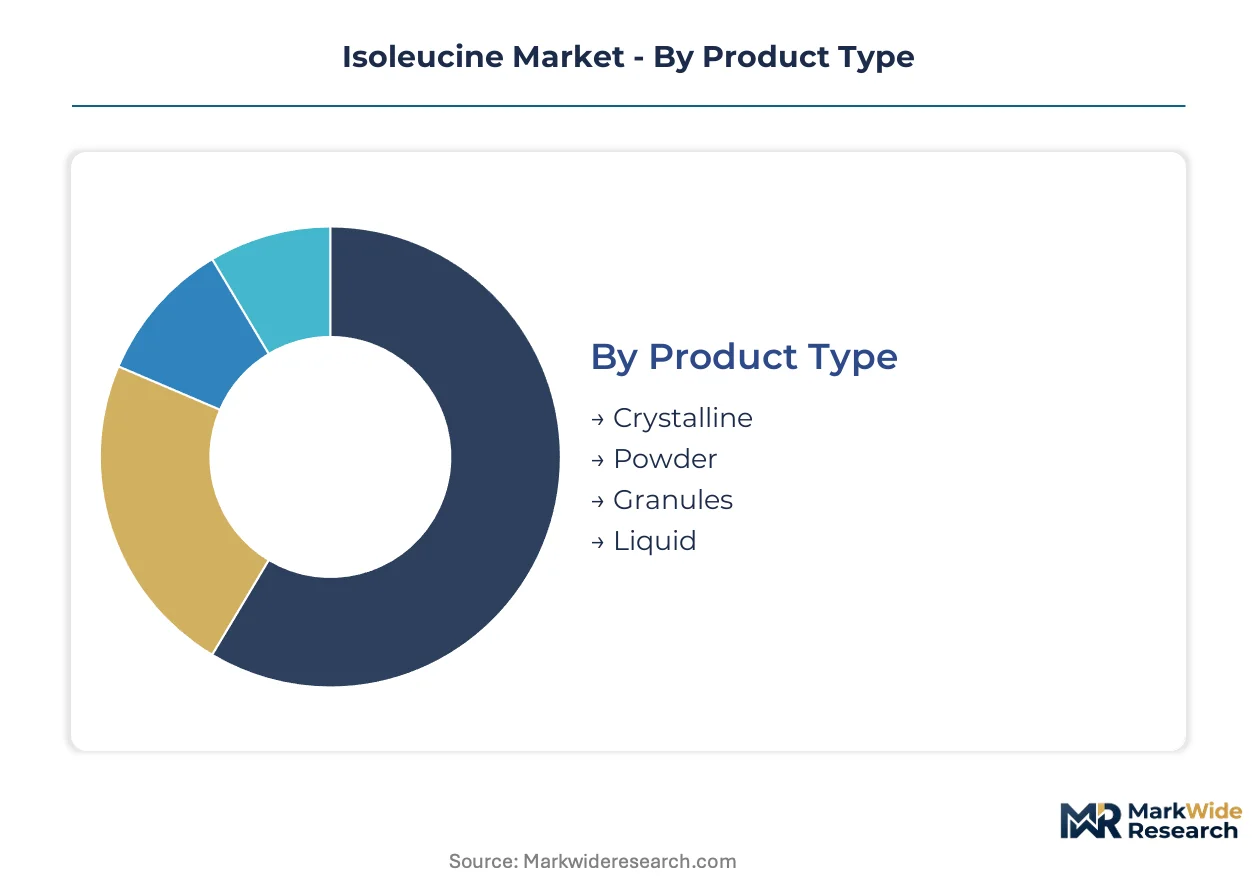
Isoleucine procurement patterns diverge sharply across purity grades and channel structures. Pharmaceutical buyers enforce certificate-of-analysis protocols that nutritional supplement brands rarely match. Understanding these segment boundaries protects margin positioning and regulatory compliance.
Product Type:
Buyers in this category separate by purity threshold and handling requirements rather than price alone.
- Crystalline:Achieves purity thresholds exceeding 99 percent through repeated recrystallization and chromatographic finishing. FDA and EMA validation timelines of 18-24 months lock in supplier relationships for parenteral nutrition and metabolic disorder therapeutics. Crystalline leads volumes today; liquid is gaining share fastest.
- Powder:Maintains 95-98 percent purity with lower processing intensity. Blending flexibility drives absorption across sports nutrition premixes and food fortification matrices in China and India. Powder sustains the broadest geographic footprint.
- Granules:Offers improved flowability for high-speed tableting operations. Pharmaceutical contract manufacturers in Germany and Switzerland specify granule morphology for direct-compression formulations.
- Liquid:Delivers ready-to-dose convenience for clinical enteral nutrition and ready-to-drink sports beverages. MFDS fortification guidelines in South Korea are accelerating food-grade liquid adoption.
Granule morphology commands premium positioning in European pharmaceutical manufacturing; liquid formats are expanding most quickly in Asian functional beverages.
Application:
Margin structures in this category invert between high-volume commodity offtake and low-volume clinical validation.
- Nutritional Supplements:Encompasses pre-workout stacks, recovery matrices, and standalone BCAA capsules. Leucine-isoleucine-valine stacking protocols among competitive athletes sustain volume leadership in North American private-label manufacturing. Nutritional Supplements leads volumes today; Pharmaceuticals is gaining share fastest.
- Food & Beverages:Covers protein fortification in senior nutrition, meal replacements, and functional beverages. EFSA health claim substantiation requirements are tightening label language and diverting marketing investment toward clinical trial sponsorship.
- Pharmaceuticals:Addresses parenteral nutrition, hepatic encephalopathy therapeutics, and metabolic disorder management. Purity certification cycles and pharmacopeial compliance create substantial barriers to entry.
- Animal Feed:Represents maturing demand for swine and poultry ration optimization. Stable offtake persists but margins compress relative to human nutrition segments due to commodity pricing dynamics.
Feed applications anchor volume in agricultural processing regions; pharmaceutical-grade supply commands the steepest expansion trajectory in metabolic health.
End User:
Specification intensity separates institutional procurement from consumer-directed purchasing.
- Athletes:Drives demand for modular dosing formats including single-serve sachets and stackable capsule systems. Sports nutrition brands compete for sponsorship relationships with competitive weightlifting and endurance communities.
- Health Enthusiasts:Absorbs mass-market BCAA supplementation through direct-to-consumer subscription models and at-home metabolic testing integration.
- Hospitals:Enforces parenteral nutrition compounding standards and batch-level traceability. Group purchasing organizations consolidate supplier relationships around integrated amino acid portfolios.
- Research Institutions:Procures small-batch reference standards and isotope-labeled isoleucine for metabolic pathway studies. Academic pricing structures differ substantially from commercial supply tiers.
Hospital procurement concentrates purchasing power through GPO structures; health enthusiast direct-to-consumer channels are climbing the fastest.
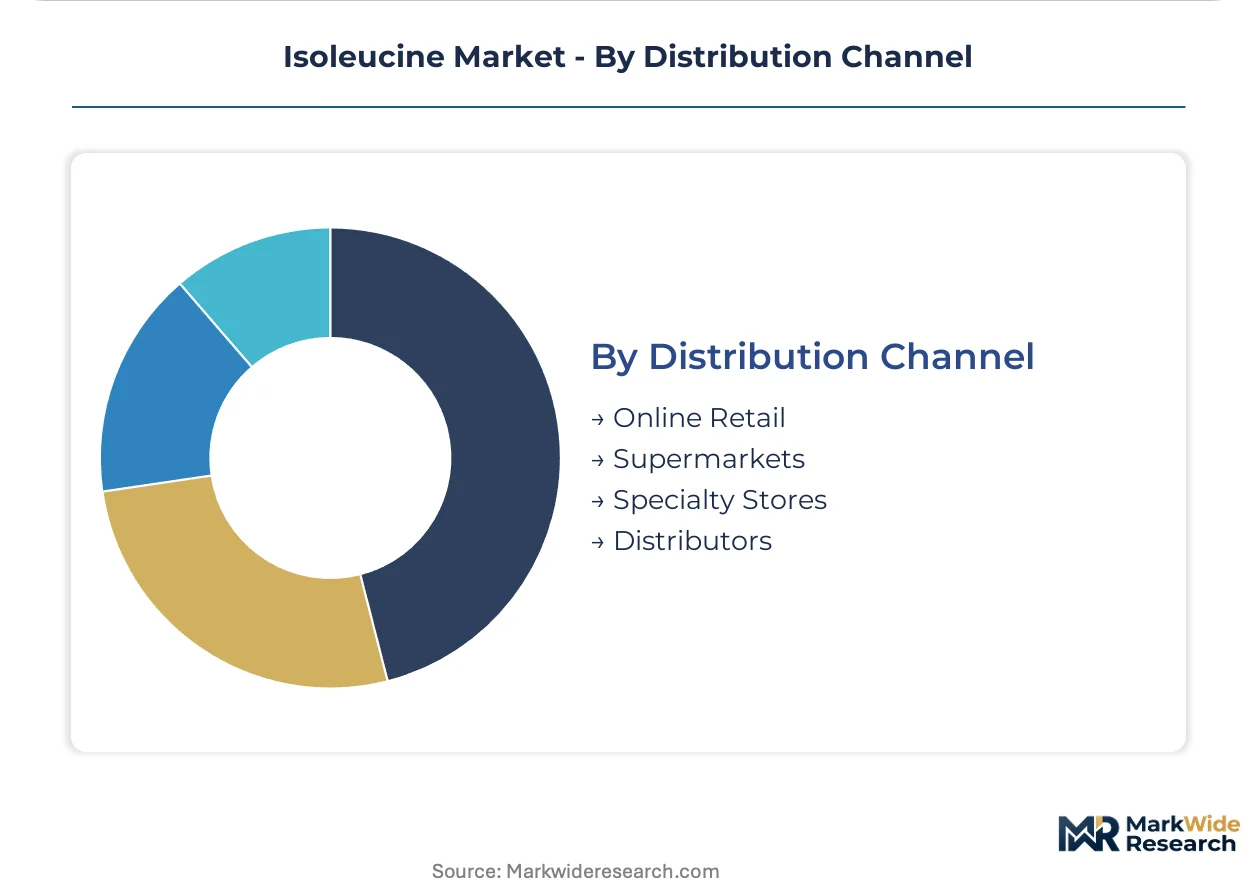
Distribution Channel:
Channel selection in this category reflects buyer sophistication and replenishment urgency.
- Online Retail:Captures subscription-based replenishment and personalized amino acid profiling services. Amazon and specialized sports nutrition platforms dominate North American and European consumer access.
- Supermarkets:Distributes mass-market BCAA products through health and wellness aisle placement. Retailer private-label programs are compressing branded shelf space.
- Specialty Stores:Serves dedicated bodybuilding and performance nutrition communities with staff-curated product education. Store-brand stacking recommendations influence brand selection.
- Distributors:Manages bulk pharmaceutical and food-grade procurement with certificate-of-analysis documentation and lot tracking. Regional distributors in Jiangsu and Zhejiang provinces anchor Chinese domestic supply.
Distributor relationships dominate pharmaceutical and food-manufacturing procurement; online retail is expanding most quickly in consumer-directed segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based amino acid production traces its industrial lineage to post-war Japanese biotechnology development, with subsequent scaling across Chinese coastal provinces during the 1990s. This historical trajectory continues to shape where capacity concentrates and how regulatory frameworks evolve.
China
Domestic amino acid manufacturing scale and export capacity anchor demand concentration, with fermentation facilities clustering in Jiangsu and Zhejiang provinces. NMPA-MEE joint oversight of GB standards harmonization streamlines licensing for producers. Xintai Jiahe Biotech Co., Ltd. exemplifies integrated fermentation infrastructure serving cost-sensitive segments.
United States
Sports nutrition brands drive BCAA supplementation adoption among competitive athletes, with private-label contract manufacturers consolidating supplier relationships. FDA oversight of dietary supplement labeling shapes product claims and channel access. Greater Boston and San Diego biotech corridors host precision nutrition platform development.
Germany
Pharmaceutical-grade isoleucine demand concentrates in parenteral nutrition and metabolic disorder therapeutics, with EMA purity certification cycles extending 18-24 months. REACH chemical registration requirements impose facility investment obligations. Basel-adjacent contract manufacturers pilot cell-free enzymatic synthesis platforms.
South Korea
MFDS fortification guidelines encouraging protein fortification in senior nutrition products expand food-grade isoleucine absorption. Functional beverage manufacturers accelerate liquid format adoption. Seoul Capital Area anchors domestic distribution infrastructure for nutritional supplements.
India
CDSCO streamlined novel food pathways and FSSAI fortification allowances create domestic manufacturing incentives, though local fermentation infrastructure remains underdeveloped. Nutraceutical import substitution pressures build across Maharashtra and Gujarat pharmaceutical corridors. Mumbai-Pune industrial belt attracts contract manufacturing investment.
Isoleucine Market Competitive Environment
Premium-margin players sit above commodity-margin players across purity-grade stratification, with pharmaceutical-grade certification commanding 18-24 month validation timelines that lock in supplier relationships. The vendor base organizes around three strategic archetypes: integrated fermentation specialists with backward feedstock control, precision nutrition platform developers, and regional cost-optimized suppliers. Dominant competitive moves include capacity expansion in Chinese biotech clusters and strategic partnerships for enzymatic synthesis technology licensing.
Within the integrated fermentation tier, Ajinomoto Co., Inc. and Xintai Jiahe Biotech Co., Ltd. represent contrasting geographic anchors—Japanese heritage fermentation expertise versus Chinese coastal province scale economics. Evonik Industries AG occupies a position exemplifying precision nutrition specialization. These three entities illustrate how competitive positioning fragments across certification intensity rather than consolidating around volume leadership.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Xintai Jiahe Biotech Co., Ltd. |
| Meihua Holdings Group Co., Ltd. |
| Fufeng Group |
| CJ CheilJedang Corp |
| Showa Denko |
| Kyowa Hakko Bio Co., Ltd. |
| Wuxi Jinghai Amino Acid Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Corn dextrose futures volatility cascades through fermentation economics into three distinct pricing tiers for crystalline, powder, and feed-grade isoleucine. Pharmaceutical buyers absorb premium positioning for FDA-validated supply, while animal nutrition procurement teams negotiate spot contracts tethered to agricultural commodity cycles.
Pricing Analysis
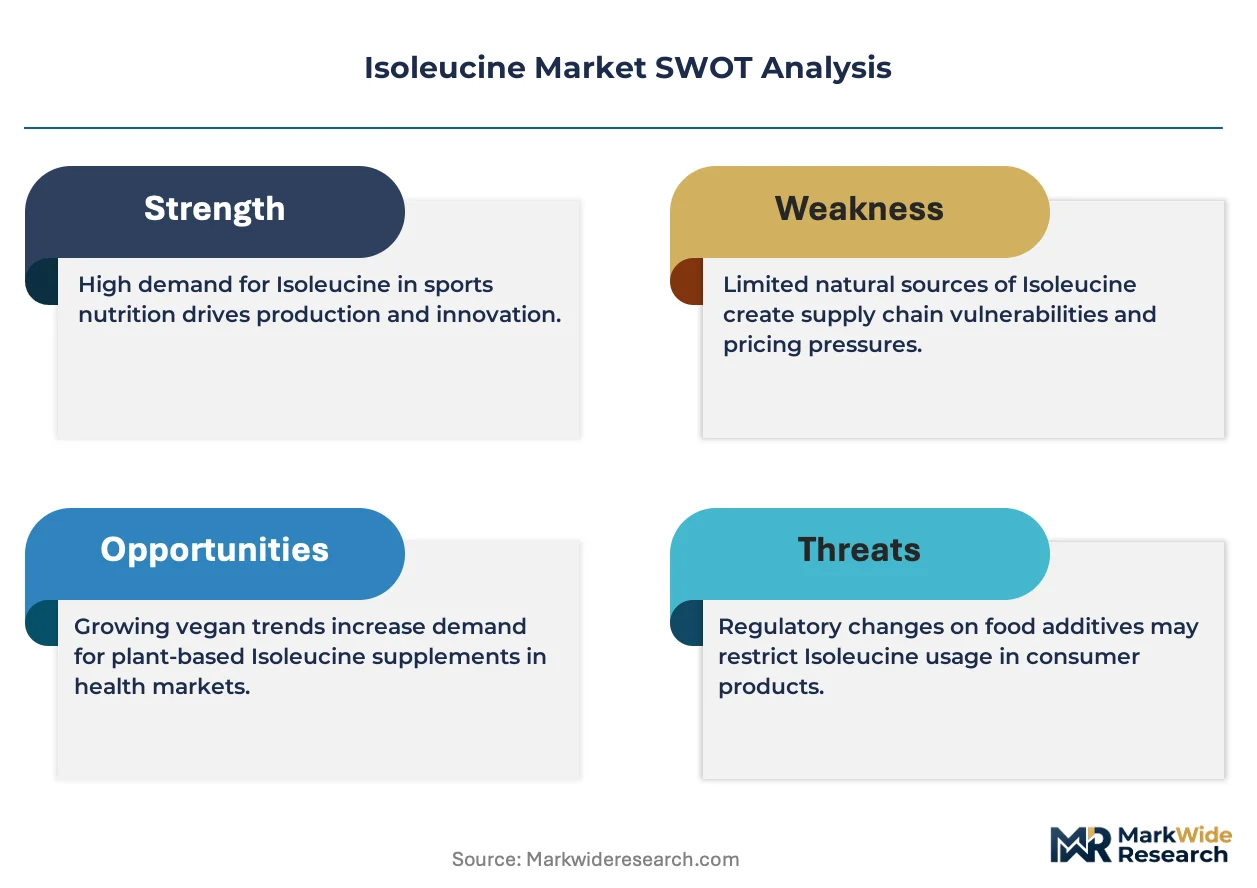
Three-tier pricing structure across pharmaceutical, nutritional, and feed grades dominates contract negotiations. Certification intensity and purity thresholds separate crystalline premiums from commodity powder, while volume scale compresses unit economics for feed-grade offtake. Pricing pressure stems from Chinese fermentation capacity expansion in Jiangsu-Zhejiang clusters. Contract manufacturers exhibit highest price sensitivity; parenteral nutrition formulators show lowest.
Supply Chain Analysis
Return flows of expired pharmaceutical inventory and off-spec fermentation batches feed into animal feed reprocessing streams. Manufacturing gravity centers on China, Japan, and South Korea for fermentation infrastructure. Carbohydrate feedstocks, engineered microbial strains, and chromatographic resins anchor input dependencies. Single-source vulnerability concentrates in Jiangsu province fermentation corridors. Distribution runs through regional distributors for pharmaceutical and food-manufacturing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isoleucine market functions as a stable compounder, with BCAA supplementation protocols in sports nutrition and metabolic health applications driving steady volume expansion.
For Market Incumbents: Cement supplier relationships through integrated amino acid portfolios covering leucine, isoleucine, and valine to counter enzymatic synthesis substitution threats. Invest in NMPA-MEE joint licensing compliance to defend Jiangsu-Zhejiang capacity positions against environmental regulatory tightening. Backward integration into corn dextrose procurement secures margin buffers against agricultural commodity volatility. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for personalized amino acid profiling services targeting health enthusiasts. Target India nutraceutical import substitution through CDSCO novel food pathway navigation and Maharashtra-Gujarat contract manufacturing partnerships. White-space sits in at-home metabolic testing kit integration for individualized BCAA dosing protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with precision nutrition platform developers possessing cell-free enzymatic synthesis capabilities. Long-term viability favors acquisition targets with pharmaceutical-grade certification infrastructure and EMA-FDA dual-track validation experience. Watch MFDS fortification guideline expansion in South Korea as signal for food-grade absorption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Chinese biotech clusters in Jiangsu-Zhejiang provinces compress production costs through scale economics. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA validation cycles lock in supplier relationships for parenteral nutrition applications. |
| Enzymatic Synthesis Technology Licensing | Cell-free biocatalytic platforms from Basel and Boston contract manufacturers rewrite cost structures. |
| Backward Integration into Feedstock Supply | Corn dextrose procurement control buffers margin compression from agricultural commodity cycles. |
| Direct-to-Consumer Channel Development | Subscription models for personalized amino acid profiling bypass traditional retail concentration. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered fermentation plant managers, sports nutrition brand formulators, pharmaceutical procurement leads, and CDSCO regulatory affairs specialists. Secondary validation drew from NMPA facility licensing records, EFSA health claim guidance documents, customs trade data for amino acid imports, and SEC filings of publicly traded fermentation specialists. Bottom-up volume modeling and top-down market sizing triangulated segment outputs.
Segment-weighting across product type, application, end user, and distribution channel dimensions anchored the analytical framework. CAGRs were derived from historical trajectory analysis and forward-looking capacity buildout assumptions. Forecast inputs incorporated BCAA stacking protocol adoption curves, NMPA-MEE regulatory harmonization timelines, and enzymatic synthesis technology diffusion rates across pharmaceutical-grade supply tiers.
Feedstock price volatility, regulatory certification delays, and substitution technology maturation are the dominant revision risks. Forecasts reflect assumptions around fermentation yield improvements and regional licensing efficiency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Middle East and Africa Omega-3 Products Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Cognition Supplements Market