
 South America Mate Market | 2026-2036
South America Mate Market Size, Share, and Industry Trends Forecast 2026-2036
South America Mate Market Analytics
The ready-to-drink beverage category is pivoting toward mate-infused functional drinks as health-conscious consumers in Brazil and Argentina seek natural caffeine alternatives. Establecimiento Las Marías leverages its vertically integrated yerba mate estates to secure raw material consistency across harvest cycles. Cooperativa Agrícola de la Colonia Liebig Ltda anchors its position through cooperative sourcing networks spanning northeastern Argentina. Companhia de Bebidas das Américas (Ambev) competes by extending its beverage distribution infrastructure into premium mate-based product lines.
Mate denotes dried leaves of Ilex paraguariensis, a holly species native to the Paraná River basin, typically containing 1-2% caffeine by dry weight and processed through fire-drying or air-drying methods before aging for 6-24 months to develop characteristic bitterness and aroma. The product serves as a traditional stimulant beverage and increasingly as a functional ingredient in energy and wellness formulations. Loose Leaf mate commands the deepest consumer loyalty in Argentina and Uruguay, while Ready-to-Drink formulations capture the fastest growth trajectory as urban Brazilian consumers prioritize convenience. Specialty Stores distribution channels sustain higher margin pools through curated origin stories and organic certifications, whereas Supermarkets dominate absolute volume throughput across the region.
ANVISA in Brazil enforces stringent food additive and labeling standards that constrain flavoring formulations and health claims on mate products. Argentina's national food code and provincial agricultural quality boards govern harvest timing, processing hygiene, and geographic indication protections for traditional producers. Stakeholders must monitor how evolving Mercosur harmonization talks reshape cross-border certification reciprocity and whether Argentine drought cycles alter harvest quality benchmarks ahead of planting decisions.
Market Dynamics
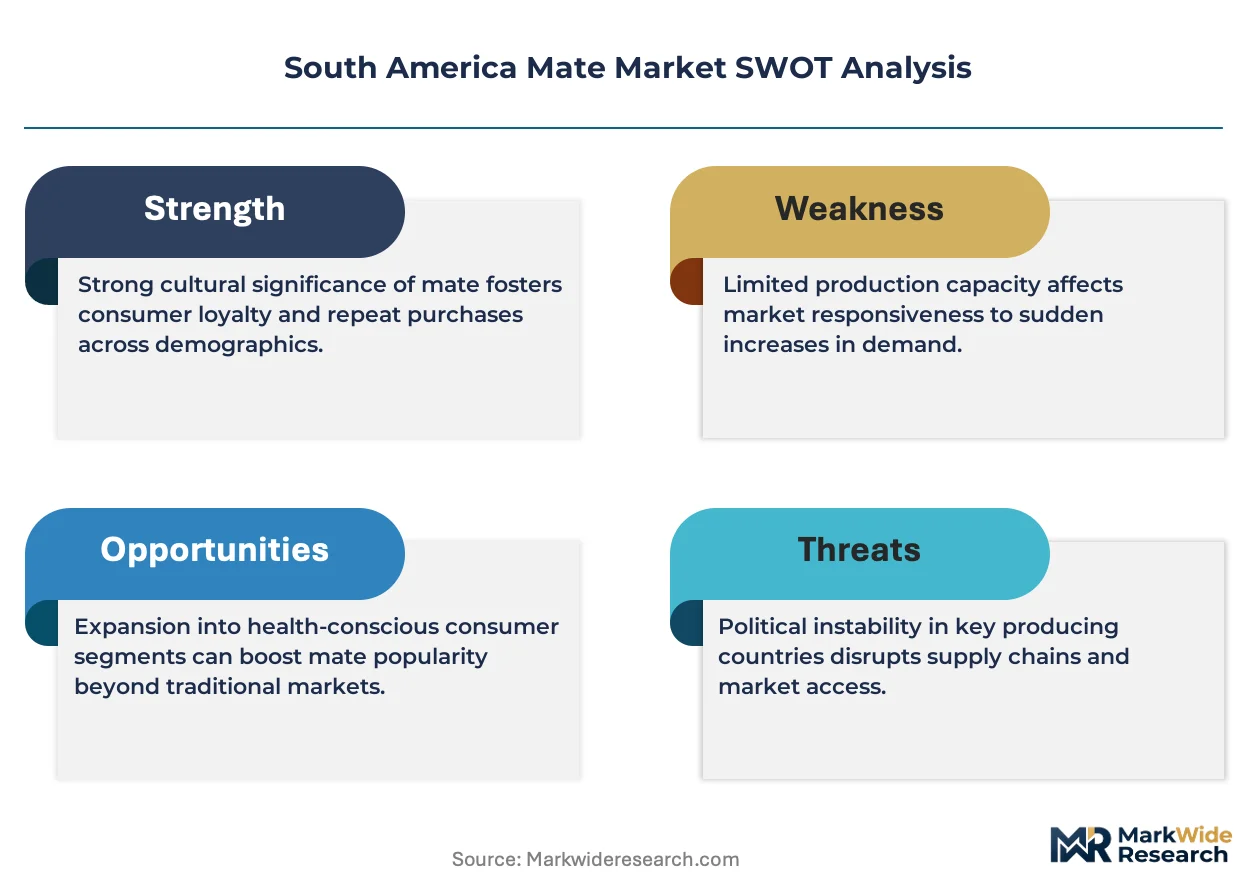
ANVISA's tightening food and beverage labeling standards in Brazil are forcing reformulation across ready-to-drink mate portfolios, while Argentine drought cycles compress harvest quality predictability and reshape planting decisions across the Paraná River basin.
Growth Catalysts
- Urban Convenience Demand:Brazilian metropolitan consumers in São Paulo and Rio de Janeiro are pivoting toward canned and bottled mate formats that fit commuter consumption patterns.
- ANVISA Labeling Clarity:Brazil's national health surveillance agency is mandating cleaner ingredient panels that reward natural caffeine positioning over synthetic alternatives.
- Cooperative Processing Networks:Argentine agricultural cooperatives in Misiones and Corrientes provinces are pooling drying and aging infrastructure to reduce per-unit processing costs.
Market Restraints
- Input Cost Volatility:Firewood and natural gas prices for drying operations fluctuate with Argentine energy policy shifts, squeezing processor margins.
- Geographic Supply Concentration:Over 70% of premium yerba mate leaf originates from a 200-kilometer radius in northeastern Argentina, exposing buyers to localized weather shocks.
- Substitution Pressure:Guaraná-based and green tea beverages capture similar functional positioning in Brazilian retail channels at lower price points.
Strategic Opportunities
- Uruguay Underpenetration:Montevideo's café culture remains dominated by traditional loose-leaf consumption, leaving ready-to-drink shelf space uncontested.
- Mercosur Harmonization Tailwind:Pending cross-border certification reciprocity agreements would streamline Argentine mate exports into Brazilian retail chains.
- Specialty Store Channel Expansion:Curated organic and single-origin mate lines command 40-60% price premiums through dedicated beverage boutiques in Buenos Aires and Porto Alegre.
Industry Challenges
- Certification Timeline Compression:Organic and fair-trade audits for Argentine estates now require 18-24 month validation cycles, delaying premium product launches.
- Legacy Drying Infrastructure:Conversion from traditional smoke-drying to air-drying systems demands capital outlays that cooperative structures struggle to aggregate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Mate Market |
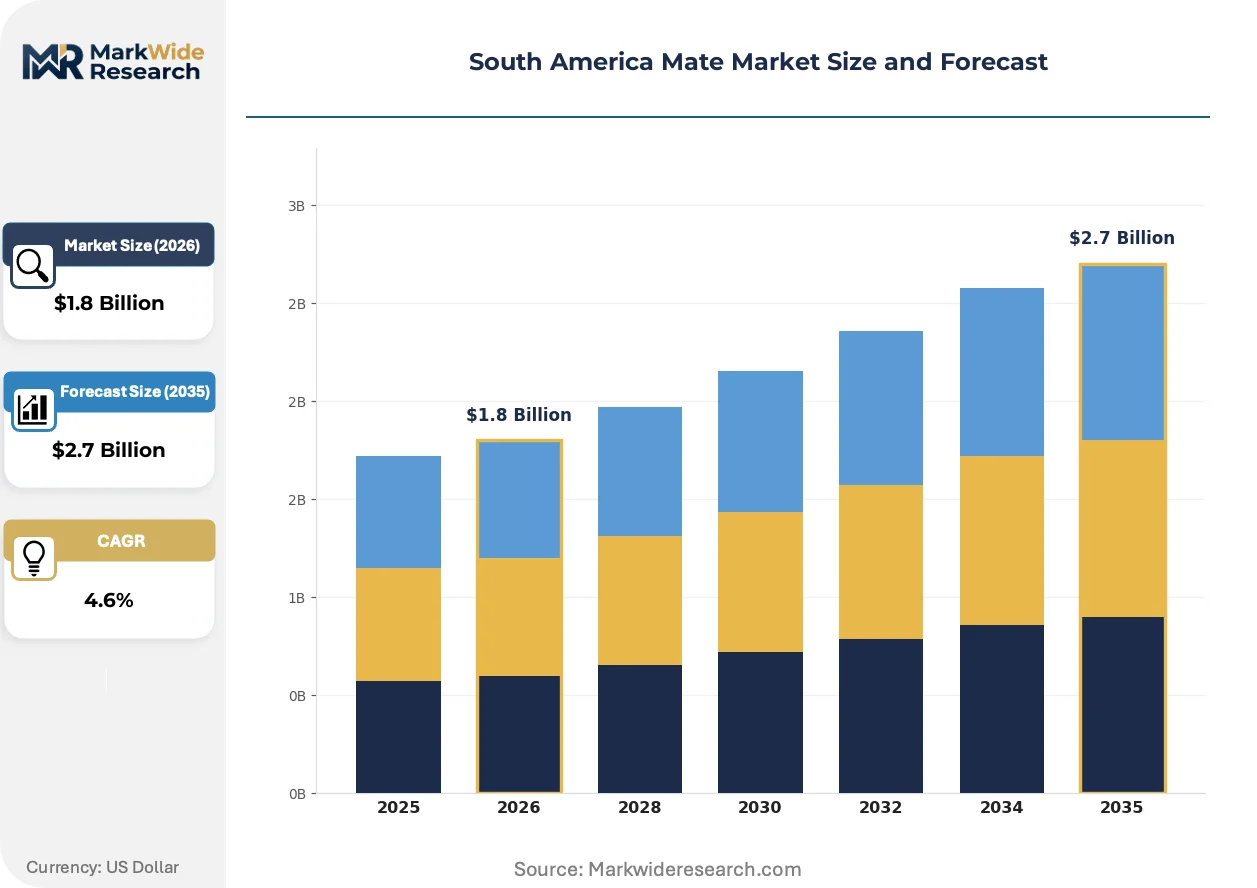
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Instant, Flavored Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores End User: Households, Restaurants, Cafes, Hotels Form: Traditional, Ready-to-Drink, Powdered, Extract |
| Companies Covered | Establecimiento Las Marías, Cooperativa Agrícola de la Colonia Liebig Ltda, Molinos Río de la Plata, La Cachuera, Establecimiento Diez Hermanos, Establecimiento Santa Ana, Companhia de Bebidas das Américas (Ambev), The Coca-Cola Company, Grupo Mate Verde, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Mate Market Evolving Landscape
Processing technology and regulatory frameworks are converging to redefine how mate moves from harvest to consumption, with implications for every node in the value chain from drying yards to retail shelves.
Cold-brew extraction technology is integrating into industrial-scale mate processing facilities, replacing heat-intensive traditional methods that degrade volatile aromatic compounds. Brazilian ready-to-drink manufacturers in Curitiba and São Paulo are adopting these systems to capture the "fresh-steeped" taste profile previously limited to loose-leaf preparation. This technology is integrating quality consistency across batch volumes while compressing the time-to-market for new flavor variants.
ANVISA's updated food additive regulations are prohibiting certain synthetic flavor carriers and mandating explicit caffeine content disclosure on all mate beverages. The industrial consequence is a wholesale reformulation of flavored mate SKUs toward natural extract-based systems. Ready-to-drink lines targeting Brazilian supermarkets are most affected, with several portfolios undergoing 12-18 month label redesign cycles.
Direct-to-consumer subscription models are displacing traditional wholesale relationships for premium organic mate brands. Specialty roasters and beverage curators in Buenos Aires and Montevideo are building recurring revenue through origin-specific monthly deliveries. This pattern is most visible among Argentine millennials aged 25-40 who prioritize traceability and harvest-date freshness over supermarket availability.
South America Mate Market Segmentation
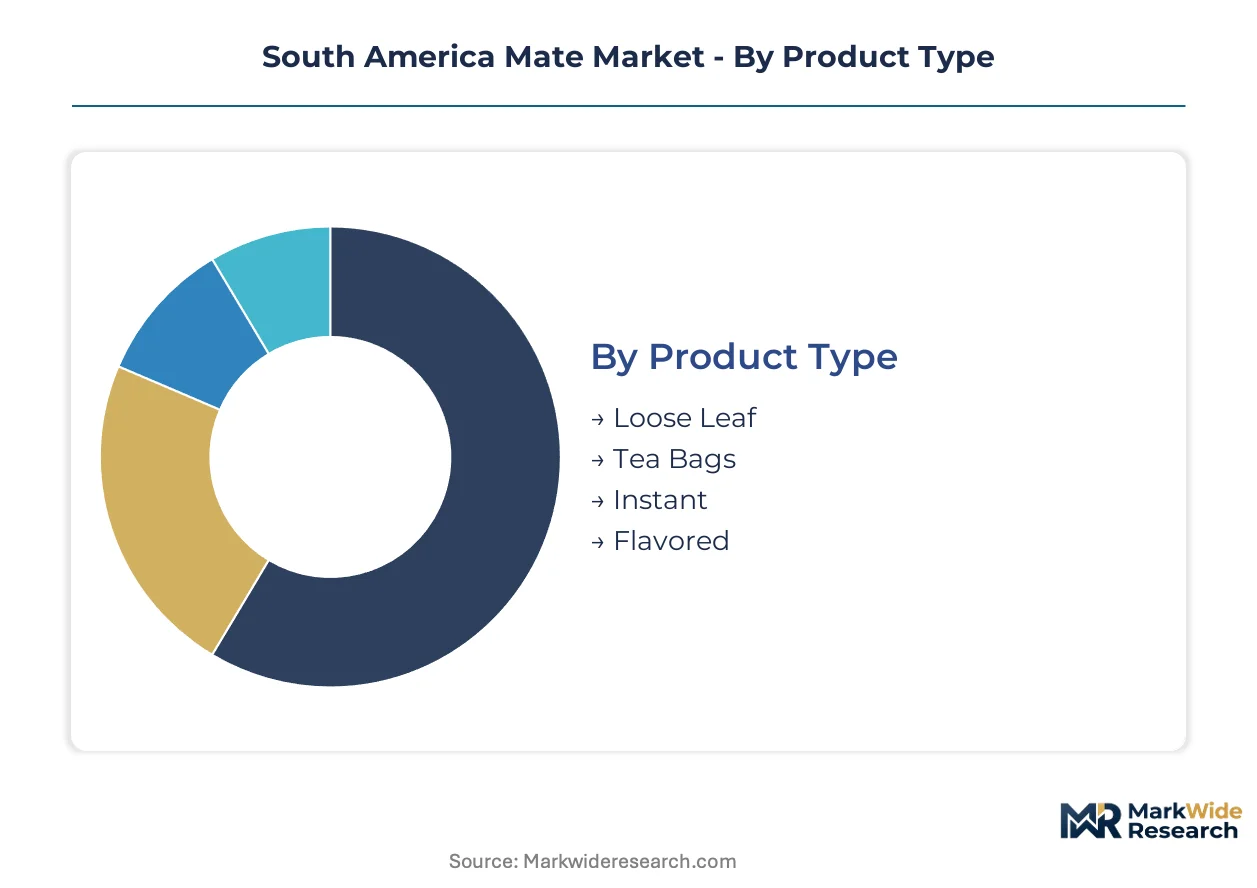
Segmentation in the South America mate market exposes how supply chain configuration and consumption rituals diverge across product formats and channel structures. Understanding these divides reveals where processors capture margin premiums versus where volume throughput dominates.
Product Type:
Supply concentration in northeastern Argentina's drying estates directly shapes which product formats processors prioritize based on leaf grade consistency and aging infrastructure capacity.
- Loose Leaf:Unprocessed or minimally fragmented dried leaves requiring traditional gourd-and-bombilla preparation. Argentina's traditional consumption belt and Uruguayan households sustain deepest loyalty here, though aging warehouse constraints limit export scalability.
- Tea Bags:Finely cut leaf enclosed in filter paper for single-serve steeping. Brazilian urban centers and São Paulo office environments drive demand as commuters seek portable formats without gourd rituals.
- Instant:Spray-dried or freeze-dried soluble granules. Argentine processors in Misiones province leverage surplus leaf grades for industrial-scale extraction.
- Flavored:Leaf or extract blended with citrus, mint, or botanical additives. ANVISA's tightening additive regulations in Brazil are forcing reformulation toward natural extract carriers.
Loose Leaf absorbs the bulk of installed capacity; Flavored is expanding most quickly as Brazilian ready-to-drink manufacturers diversify portfolios.
Distribution Channel:
Margin capture potential varies sharply across channels, with curated origin stories commanding price premiums while high-volume retail drives absolute throughput.
- Supermarkets:Mass retail chains across Brazil and Argentina handling standardized SKUs in bulk packaging. São Paulo and Rio de Janeiro metropolitan areas concentrate volume throughput, though slotting fees compress processor margins.
- Specialty Stores:Curated beverage boutiques emphasizing organic certifications and single-origin provenance. Buenos Aires and Porto Alegre clusters sustain 40-60% price premiums through harvest-date freshness and direct trade relationships.
- Online Retail:Direct-to-consumer subscription models displacing traditional wholesale relationships. Argentine millennials aged 25-40 prioritize traceability and recurring deliveries over supermarket availability.
- Convenience Stores:Small-format urban retail targeting impulse purchases and commuter patterns. Brazilian metropolitan transit corridors show strongest growth for canned and bottled mate formats.
Supermarkets absorb the bulk of installed capacity; Online Retail is climbing the fastest as subscription models bypass traditional distribution markups.
End User:
Consumption rituals and preparation infrastructure requirements segment demand by institutional scale and service format complexity.
- Households:Individual and family consumption units purchasing retail formats for home preparation. Argentina's traditional belt and southern Brazil maintain gourd-based rituals, while urban Brazilian households pivot toward convenience formats.
- Restaurants:Foodservice establishments integrating mate into beverage menus or table service. Montevideo's café culture remains dominated by loose-leaf service, leaving ready-to-drink penetration minimal.
- Cafes:Specialty beverage shops expanding mate-based menu offerings. Buenos Aires and São Paulo clusters experiment with cold-brew extraction and flavored latte formulations.
- Hotels:Hospitality properties offering mate as amenity or minibar inclusion. Brazilian business hotels in Curitiba and Porto Alegre test branded single-serve formats for guest convenience.
Households absorb the bulk of installed capacity; Cafes are gaining share fastest as specialty beverage culture spreads across Argentine and Brazilian urban centers.
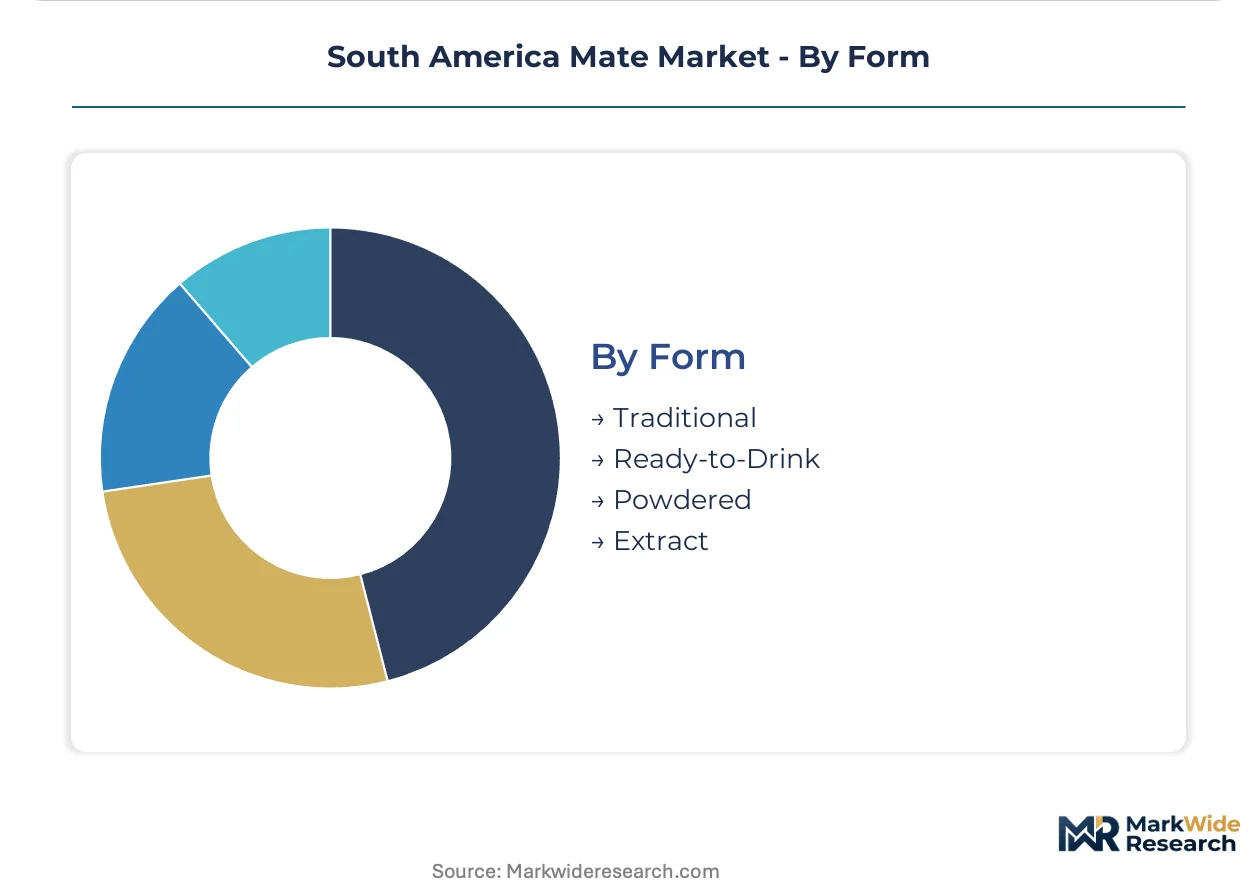
Form:
Processing technology intensity and capital requirements stratify competitive positioning across preparation-ready versus value-added formats.
- Traditional:Raw or aged loose leaf requiring consumer-side preparation with hot water and gourd. Argentina's Corrientes and Misiones provinces anchor production, with cooperative drying networks pooling infrastructure.
- Ready-to-Drink:Pre-brewed and packaged beverages in canned or bottled formats. Cold-brew extraction technology adoption in Curitiba and São Paulo facilities is capturing fresh-steeped taste profiles previously limited to loose-leaf.
- Powdered:Finely milled leaf for blending into smoothies or baking applications. Brazilian wellness and functional food manufacturers explore mate as natural caffeine alternative to guaraná.
- Extract:Concentrated liquid or standardized powder for industrial formulation. ANVISA's caffeine disclosure mandates affect labeling complexity for extract-based SKUs entering Brazilian retail.
Traditional absorbs the bulk of installed capacity; Ready-to-Drink represents the fastest-growing trajectory as urban Brazilian consumers prioritize convenience without ritual preparation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mercosur special economic zone drives mate production concentration across the Paraná River basin, with tariff coordination shaping cross-border trade flows between Argentina and Brazil. Provincial tax incentives in Misiones and Corrientes anchor primary processing infrastructure, while Brazilian import protocols determine finished goods penetration into metropolitan retail channels.
Argentina
Traditional gourd-based consumption rituals sustain household demand in the Corrientes-Misiones corridor, where cooperative drying networks pool aging infrastructure. ANMAT, Argentina's national food regulator, enforces geographic indication protections for traditional producers under the national food code. The Posadas-Apóstoles industrial cluster concentrates fire-drying and air-drying facilities that supply both domestic loose-leaf markets and export-oriented extract production.
Brazil
Urban commuters in São Paulo and Rio de Janeiro pivot toward ready-to-drink canned formats that bypass gourd preparation requirements. ANVISA mandates explicit caffeine disclosure and restricts synthetic flavor carriers, forcing 12-18 month reformulation cycles across flavored mate portfolios. Curitiba's beverage manufacturing corridor adopts cold-brew extraction systems to capture fresh-steeped taste profiles for supermarket distribution.
Uruguay
Montevideo's café culture maintains deep loyalty to loose-leaf service rituals, leaving ready-to-drink shelf space largely uncontested by industrial processors. The country's consumer protection code aligns with Mercosur harmonization talks that could streamline Argentine import certification. Coastal Montevideo and Paysandú clusters sustain traditional consumption patterns with minimal penetration of convenience-oriented formats.
Paraguay
Domestic consumption centers on tereré, the cold-brewed mate variant distinct from hot-steeped traditions across the southern cone. The national plant health service, SENAVE, regulates Ilex paraguariensis harvest timing and phytosanitary export certification for leaf crossing into Argentine processing facilities. The Alto Paraná region supplies raw leaf to northeastern Argentine cooperatives under informal cross-border sourcing arrangements.
Chile
Santiago's specialty beverage shops introduce mate-based menu offerings to urban consumers unfamiliar with traditional preparation methods. The Ministry of Health's food labeling regulations require Spanish-language nutritional panels that complicate Argentine import packaging. Providencia and Ñuñoa district cafés experiment with cold-brew lattes and flavored formulations targeting wellness-oriented millennials.
South America Mate Market Competitive Landscape
Top-tier vendors anchor estate-scale production, while cooperative structures and multinational beverage conglomerates occupy distinct competitive tiers. The market structure stratifies across three archetypes: vertically integrated yerba mate estates controlling harvest-to-package workflows, agricultural cooperatives pooling member-grown leaf through shared processing infrastructure, and diversified beverage corporations extending distribution reach into premium mate categories. Dominant competitive moves include backward integration into drying and aging assets, plus strategic partnerships with specialty retail channels that command organic certification premiums.
Within the estate-integrated tier, Establecimiento Las Marías exemplifies captive supply control over multi-harvest raw material consistency. Among cooperative structures, Cooperativa Agrícola de la Colonia Liebig Ltda occupies a position anchored through member sourcing networks across northeastern Argentina. At the diversified beverage end, Companhia de Bebidas das Américas (Ambev) represents distribution infrastructure leverage into ready-to-drink mate lines.
| Leading Market Players |
|---|
| Establecimiento Las Marías |
| Cooperativa Agrícola de la Colonia Liebig Ltda |
| Molinos Río de la Plata |
| La Cachuera |
| Establecimiento Diez Hermanos |
| Establecimiento Santa Ana |
| Companhia de Bebidas das Américas (Ambev) |
| The Coca-Cola Company |
| Grupo Mate Verde |
| Others |
Value Network & Pricing Analysis
Cold-brew extraction technology adoption in Curitiba and São Paulo processing facilities is compressing production cycles while concentrating capital requirements among larger processors capable of financing stainless steel fermentation infrastructure. This equipment transition simultaneously elevates quality consistency thresholds and widens the gap between estate-scale operators and cooperative drying networks dependent on traditional fire-drying methods.
Pricing Analysis
Short lead-time premiums for harvest-fresh organic lots command 40-60% markups over aged commodity grades in Buenos Aires specialty boutiques. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification stringency and traceability depth. Cost compression in standard-grade loose leaf is intensifying because Argentine energy policy shifts inflate natural gas and firewood drying expenses. Brazilian supermarkets exhibit highest price sensitivity, while Montevideo café operators absorb premiums for single-origin provenance.
Supply Chain Analysis
Organic and fair-trade certification gating now requires 18-24 month validation cycles, delaying premium product launches and freezing out smaller cooperatives lacking audit resources. Supply concentrates in Argentina's Misiones-Corrientes corridor, Brazil's Paraná basin, and Paraguay's Alto Paraná region. Processing draws from Ilex paraguariensis leaf, natural gas or firewood fuel stocks, and stainless steel aging infrastructure. Single-source vulnerability runs through the 200-kilometer premium leaf radius in northeastern Argentina exposed to drought shocks. Distribution runs through cooperative pooling arrangements feeding branded estate packagers and multinational beverage distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around processors capable of financing certification compliance and cold-brew capital expenditure. ANVISA's reformulation mandates are forcing weaker ready-to-drink players into distressed exits or acquisition.
For Market Incumbents: Deploy cooperative processing network consolidation to aggregate drying infrastructure and split certification audit costs across member estates. Lock in long-term supply agreements with Alto Paraná leaf brokers before Mercosur harmonization streamlines cross-border sourcing. Guaraná-based beverage substitution in Brazilian retail channels threatens volume share; counter with cold-brew freshness positioning that synthetic caffeine alternatives cannot replicate. For New Entrants and Emerging Players: ANVISA's updated caffeine disclosure and natural flavor mandates in Brazil opens a window for clean-label ready-to-drink formulations that incumbent portfolios require 12-18 months to reformulate. Target Montevideo's uncontested convenience store channel where traditional loose-leaf café culture has blocked industrial penetration. Lead with direct-to-consumer subscription models bypassing supermarket slotting fee barriers that crush margin for unknown brands. For Investors and Strategic Acquirers: Exit pathways concentrate in estate-scale acquisitions by multinational beverage conglomerates seeking captive supply for functional drink line extensions. Five-to-ten year viability hinges on water security in the Paraná River basin and the pace of air-drying infrastructure conversion. Watch Argentine drought cycle frequency as the inflection signal for harvest quality volatility and premium grade scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aging Infrastructure | Captive warehouse capacity insulates against cooperative bottlenecks during harvest compression periods. |
| Cold-Brew Extraction Scale-Up | São Paulo and Curitiba facilities capture fresh-steeped taste profiles previously limited to loose-leaf preparation. |
| Organic Certification Fast-Track | Early audit completion secures 18-24 month validation advantage over competitors launching premium lines. |
| Direct-to-Consumer Subscription Launch | Buenos Aires and Montevideo millennials aged 25-40 prioritize traceability over supermarket availability. |
| Mercosur Harmonization Pre-Positioning | Cross-border certification reciprocity would streamline Argentine mate exports into Brazilian retail chains. |
Research Methodology
Independent corroboration across cooperative board members, ANVISA regulatory affairs specialists, and specialty retail buyers underwrites the qualitative findings in this study. Primary fieldwork engaged estate operations directors at vertically integrated yerba mate producers, procurement leads at Brazilian ready-to-drink manufacturers, and category managers at São Paulo supermarket chains. Secondary validation drew from ANVISA additive regulation filings, Argentine provincial agricultural quality board harvest reports, and Mercosur trade harmonization documentation. Bottom-up volume builds from drying facility capacity and aging warehouse throughput triangulate against top-down consumption surveys across Argentine households and Brazilian urban commuters.
Comparable-period anchoring to historical harvest quality cycles and regulatory implementation timelines shaped the projection horizon. The analytical framework segments by product format, distribution channel, and end-user preparation ritual complexity across the modeling period. CAGRs derive from installed capacity utilization trajectories and channel shift elasticity parameters. Forecast inputs incorporate ANVISA reformulation cycle duration and cold-brew equipment adoption curves in Brazilian processing corridors.
The model assumes a particular technology adoption path; alternative pathways for air-drying infrastructure conversion would alter the outlook if Argentine energy subsidies unexpectedly restore fire-drying cost competitiveness. Forecasts reflect assumptions about drought cycle severity and Mercosur certification reciprocity timing. A model refresh is warranted upon material change in Paraná River basin hydrological conditions or ANVISA flavor additive prohibitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
India Sports Drinks Market
Beverages
Japan Energy Drink Market
Beverages
United States Smoothie Market
Beverages
Hot Cocoa Mix Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
CBD-Infused Beverages Market
Beverages
China Soy Beverages Market
Beverages
Oat Based Beverages Market
Beverages
Sparkling Water Market
Beverages
Nitro-Infused Cola Market
Beverages
Beverage Premix Market
Beverages
Milk Tea Powder Market
Beverages
Packaged Milkshake Market
Beverages
South America Bottled Water Market
Beverages
Global Soda Maker Market