
 Canada Whey Protein Market | 2026-2036
Canada Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Whey Protein Market Outlook
Canadian dairy processing infrastructure is shifting toward higher-value protein fractionation. Groupe Lactalis leverages its St. Hubert plant network to sustain whey isolate output for North American export channels. Agropur Dairy Cooperative anchors its ingredient business through backward integration into cheese-making byproducts. Saputo competes on manufacturing scale, operating multiple fractionation lines that supply both domestic brands and international commodity buyers.
Whey protein comprises the globular proteins isolated from liquid whey, a cheese-making byproduct containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins at concentrations ranging from 0.7% to 0.8% in raw whey. Manufacturers concentrate these proteins through ultrafiltration and diafiltration, yielding ingredients with protein content from 34% in concentrates to 90%+ in isolates for sports nutrition, clinical nutrition, and functional food applications. Isolate commands premium positioning due to lower lactose and fat content, while ready-to-drink formats capture faster velocity through convenience channels. Powder maintains volume dominance across institutional and direct-to-consumer segments, though bars show accelerated placement in gym and health store distribution.
Health Canada's Natural and Non-prescription Health Products Directorate enforces Good Manufacturing Practices and label claims verification, while the Canadian Food Inspection Agency monitors dairy ingredient safety under Safe Food for Canadians Regulations. The Canadian Dairy Commission's pricing framework shapes milk input costs and thereby whey protein economics for domestic processors. Stakeholders must monitor potential reform to supply management rules and their cascading effects on whey stream availability and processor margin structures.
Market Dynamics
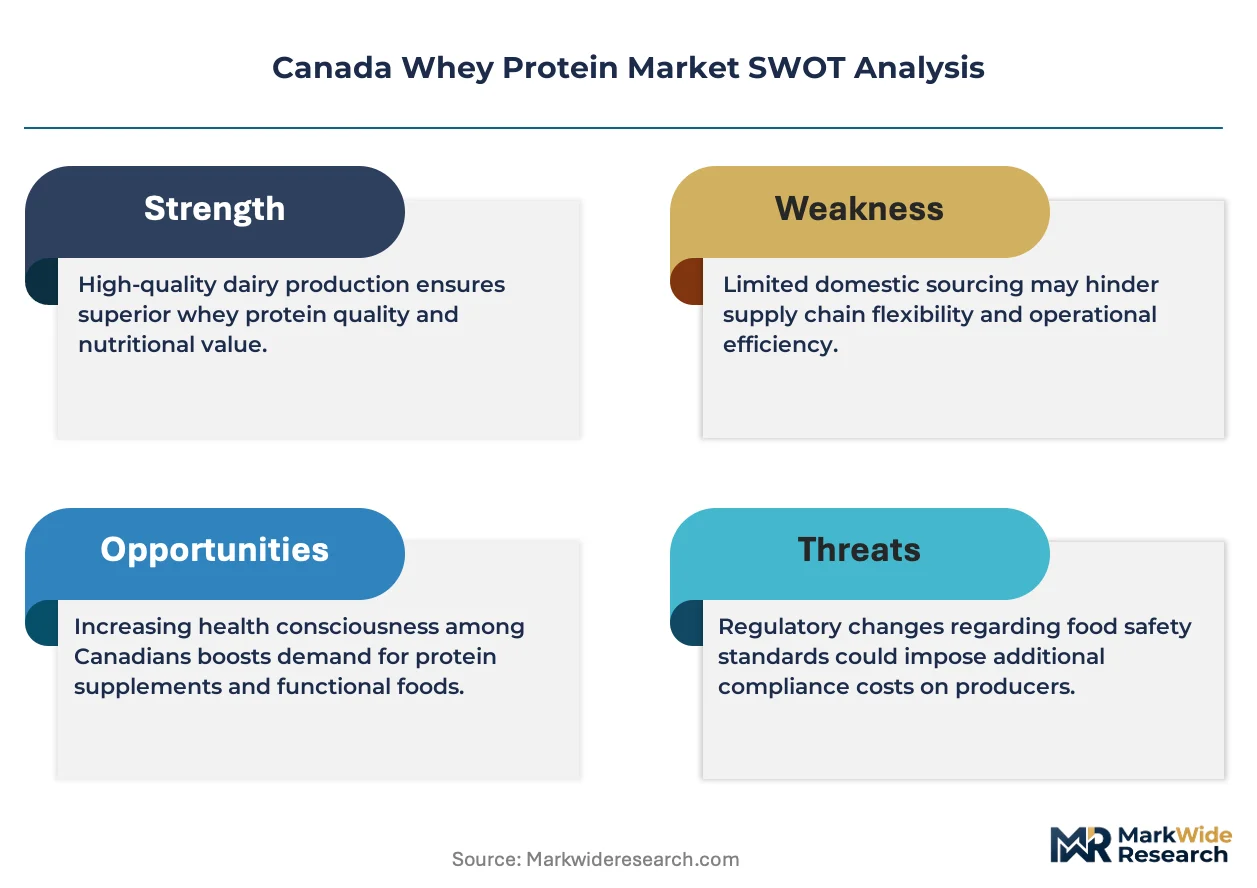
Canada's whey protein sector operates under the gravitational pull of supply management economics, where the Canadian Dairy Commission's pricing framework constrains milk input costs while simultaneously limiting whey stream availability for fractionation. This structural tension between controlled dairy supply and expanding protein demand shapes processor investment decisions, margin structures, and competitive positioning across Ontario and Quebec processing clusters.
Growth Catalysts
- Sports Nutrition Category Expansion:Athletes and recreational fitness consumers in Toronto, Montreal, and Vancouver are driving volume for isolate and hydrolysate formats through specialty retail and direct-to-consumer channels.
- Health Canada's NNHPD Framework:Clear labeling standards and Good Manufacturing Practice requirements reduce regulatory ambiguity for compliant manufacturers, accelerating product registration timelines versus jurisdictions with fragmented oversight.
- Clinical Nutrition Integration:Hospital formulary committees and long-term care procurement bodies are incorporating whey protein into sarcopenia prevention protocols and post-surgical recovery regimens.
Market Restraints
- Supply Management Price Floors:The Canadian Dairy Commission's milk pricing mechanism elevates whey input costs relative to New Zealand and US spot markets, compressing processor margins on commodity-grade concentrate exports.
- Quebec-Ontario Processing Concentration:Over 80% of fractionation capacity sits within 300 kilometers of Montreal and Toronto, creating geographic vulnerability to regional logistics disruptions and labor actions.
- Plant Protein Substitution:Pea and fava protein isolates from Prairie processing facilities are capturing share in vegan-positioned applications where functional performance gaps have narrowed.
Strategic Opportunities
- Western Canada Distribution Infrastructure:Calgary and Edmonton represent underserviced demand nodes where cold-chain logistics investments could capture institutional and retail volume currently supplied from Ontario.
- Medical Foods Regulatory Pathway:Health Canada's evolving framework for foods for special dietary purposes offers premium positioning potential for whey-based clinical nutrition products with substantiated health claims.
- Microfiltration-Reverse Osmosis Convergence:Adoption of ceramic membrane systems combined with advanced diafiltration is enabling native whey protein recovery with superior functional properties for beverage applications.
Industry Challenges
- Protein Fractionation Talent Scarcity:Dairy processing engineers with ultrafiltration and spray-drying expertise are concentrated among retiring cohorts at legacy cooperatives, constraining operational scaling for emerging processors.
- NNHPD Compliance Timelines:Natural Product Number acquisition for novel delivery formats averages 18-24 months, delaying revenue recognition for innovation pipelines targeting health-conscious consumers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Whey Protein Market |
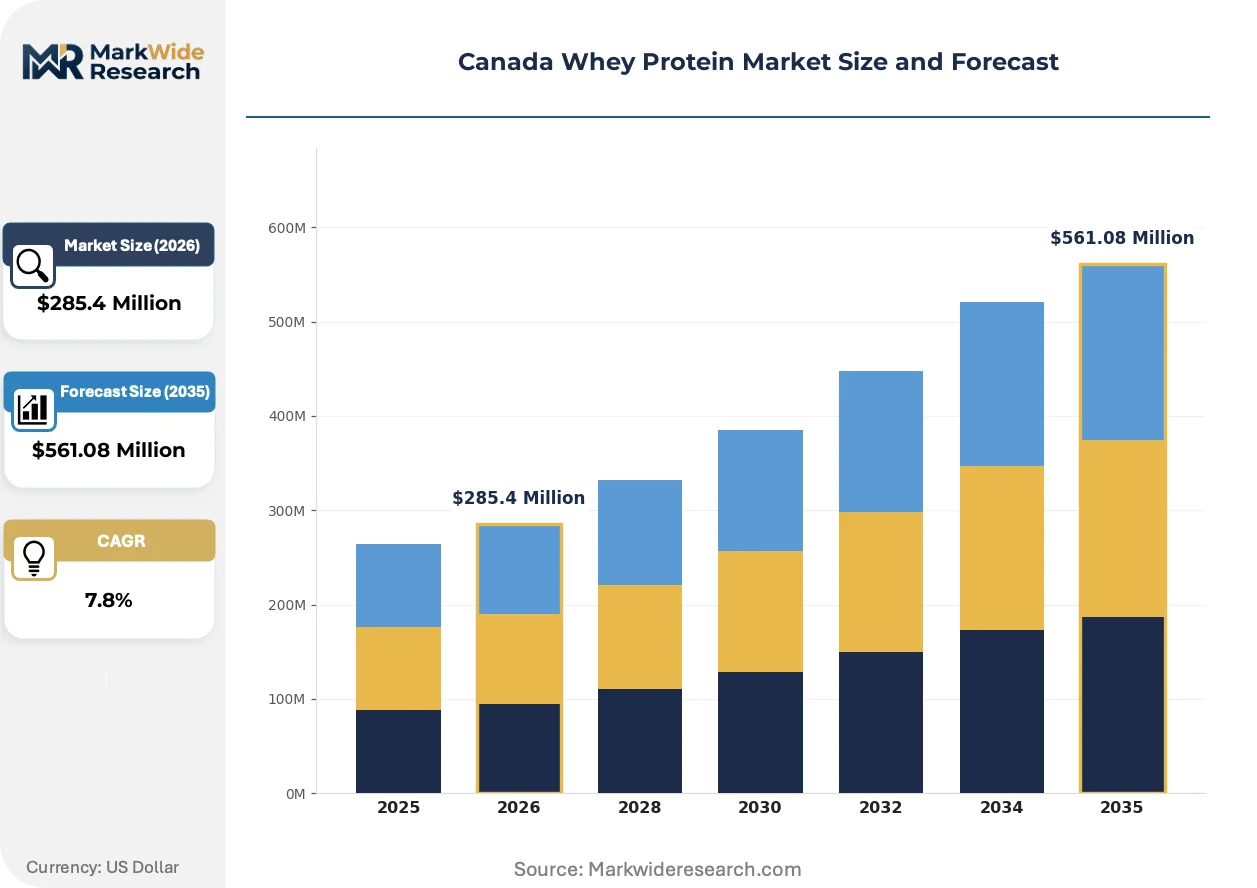
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends Form: Powder, Ready-to-Drink, Bars, Capsules End User: Athletes, Fitness Enthusiasts, General Consumers, Medical Patients Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms |
| Companies Covered | Groupe Lactalis, Saputo, Agropur Dairy Cooperative, Davisco Foods International, Royal FrieslandCampina, Arla Foods, Glanbia, Hilmar Ingredients, Fonterra Co-operative Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Whey Protein Market Strategic Shifts
Membrane technology advancement and shifting procurement patterns are reconfiguring how whey protein moves from dairy cooperative to end-consumer. These forces are compressing traditional value chain steps while elevating the importance of functional differentiation and regulatory agility.
Cross-flow microfiltration systems are integrating ceramic membrane technology with automated clean-in-place protocols to recover native whey protein structures that resist denaturation during thermal processing. Sports nutrition manufacturers in British Columbia and Alberta are adopting these systems to secure isolate with superior emulsification properties for ready-to-drink applications. This equipment transition is integrating quality differentiation into capital allocation decisions, favoring processors with balance sheet capacity for multi-million dollar filtration line upgrades.
Health Canada's evolving approach to protein content claims under the Natural and Non-prescription Health Products Directorate is tightening analytical method requirements for label substantiation. Manufacturers must now demonstrate amino acid profile compliance through third-party testing against reference standards, elevating quality assurance costs across the supply base. Small and mid-size brands lacking in-house analytical capabilities are outsourcing verification to accredited laboratories in Toronto and Montreal, creating dependency relationships with testing service providers.
Direct-to-consumer subscription models are displacing traditional wholesale distribution for premium isolate and hydrolysate products. Fitness enthusiasts in Vancouver, Calgary, and Ottawa are purchasing through brand-operated digital channels that offer flavor customization and auto-replenishment scheduling. This channel migration is most visible among consumers aged 25-40, where convenience positioning and loyalty program structures are overcoming price sensitivity that previously favored mass retail procurement.
Canada Whey Protein Market Segmentation
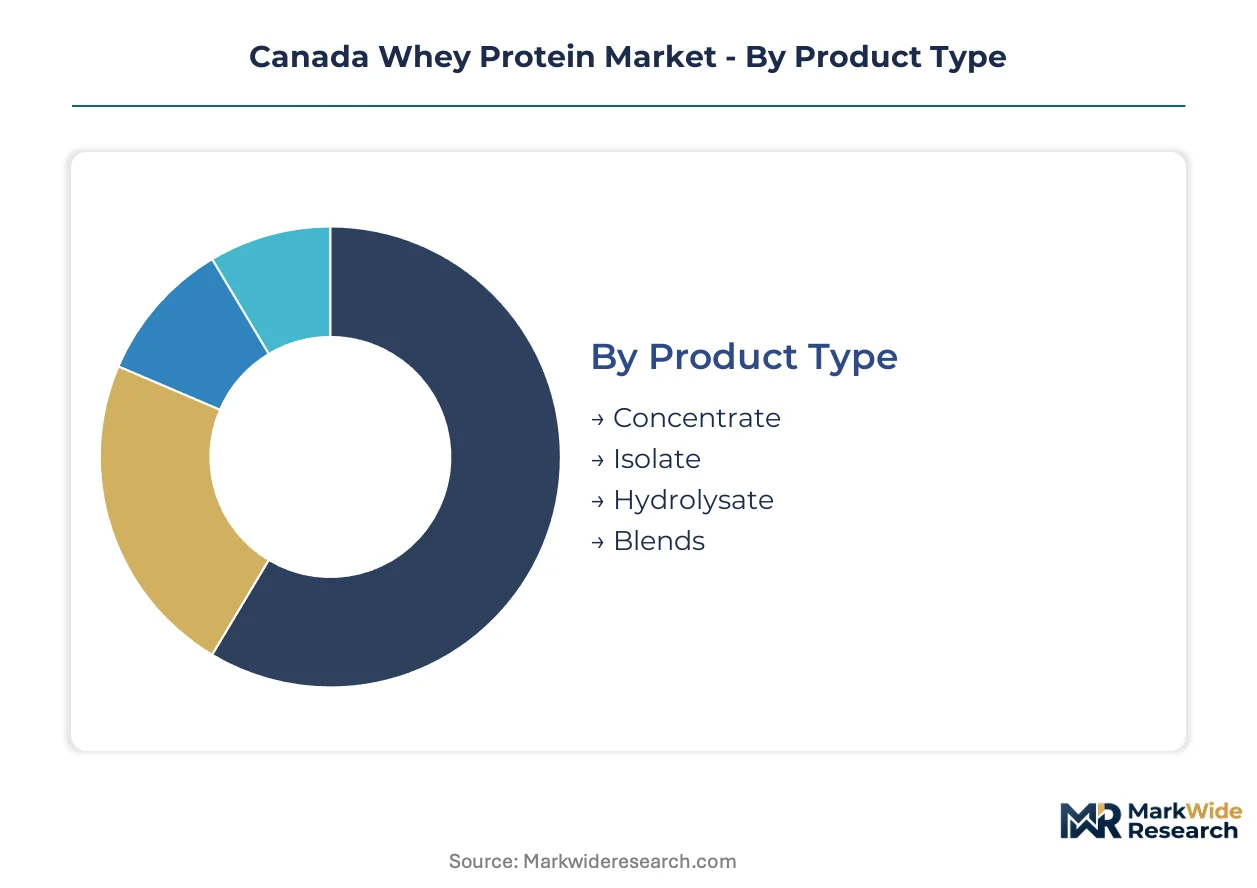
Whey protein segmentation in Canada reflects divergent buyer priorities across performance tiers, convenience requirements, and clinical credibility standards. Manufacturers configure product portfolios around these fault lines to capture margin concentration in isolate while defending volume positions in concentrate.
Product Type:
Buyers in this category differentiate by protein purity tolerance, lactose sensitivity, and price elasticity for performance gains.
- Concentrate:Protein content ranges from 34% to 80% with retained lactose and lipids from raw whey. Demand concentrates in Ontario institutional procurement for food manufacturing applications where cost efficiency outweighs purity requirements.
- Isolate:Ultrafiltration and diafiltration yield 90%+ protein content with minimal lactose. Toronto and Vancouver specialty retail channels drive premium positioning among competitive bodybuilders and physique athletes seeking rapid absorption without digestive compromise.
- Hydrolysate:Enzymatic pre-digestion creates peptide-bond cleavage for accelerated amino acid availability. Sports nutrition formulators in Quebec leverage this grade for post-workout recovery positioning.
- Blends:Multi-protein combinations balance cost and absorption kinetics. General consumer segments in Calgary and Edmonton favor these for everyday supplementation versatility.
Volume sits with Concentrate; growth tilts toward Isolate.
Form:
Consumption context and portability requirements shape purchasing decisions across this dimension.
- Powder:Bulk packaging dominates institutional and direct-to-consumer segments with dosing flexibility and extended shelf stability. Quebec dairy cooperatives anchor supply for this format through established spray-drying infrastructure.
- Ready-to-Drink:Pre-mixed beverages capture convenience-driven demand from urban professionals in Vancouver and Montreal seeking post-gym consumption without preparation. Cold-chain distribution requirements constrain margin structures for smaller brands.
- Bars:Co-extruded and cold-pressed formats integrate whey with carbohydrate matrices for meal replacement positioning. Alberta health food retailers report accelerated placement velocity among hiking and outdoor recreation consumers.
- Capsules:Encapsulated delivery addresses clinical nutrition protocols and consumers averse to dairy taste profiles. Long-term care procurement in Ontario incorporates these for sarcopenia management compliance.
Revenue concentration favors Powder; Ready-to-Drink expands most quickly through convenience channel penetration.
End User:
Performance expectations and health claim substantiation requirements create distinct buyer archetypes.
- Athletes:Competitive and recreational competitors prioritize leucine content and absorption kinetics for muscle protein synthesis optimization. Sports nutrition brands target this segment through sponsorship relationships with Canadian collegiate athletic programs.
- Fitness Enthusiasts:Regular gym attendees seek protein supplementation for body composition management without competitive performance demands. This cohort drives flavor innovation and subscription model adoption in British Columbia.
- General Consumers:Health-conscious individuals incorporate whey as a dietary protein source independent of exercise regimens. Mass retail distribution in Ontario and Quebec supermarkets captures this price-sensitive volume.
- Medical Patients:Hospital formulary committees and clinical dietitians prescribe whey for post-surgical recovery and malnutrition intervention. Health Canada's NNHPD framework governs label claims for this indication.
Athletes command premium pricing; Medical Patients represent the steepest expansion trajectory through clinical nutrition integration.
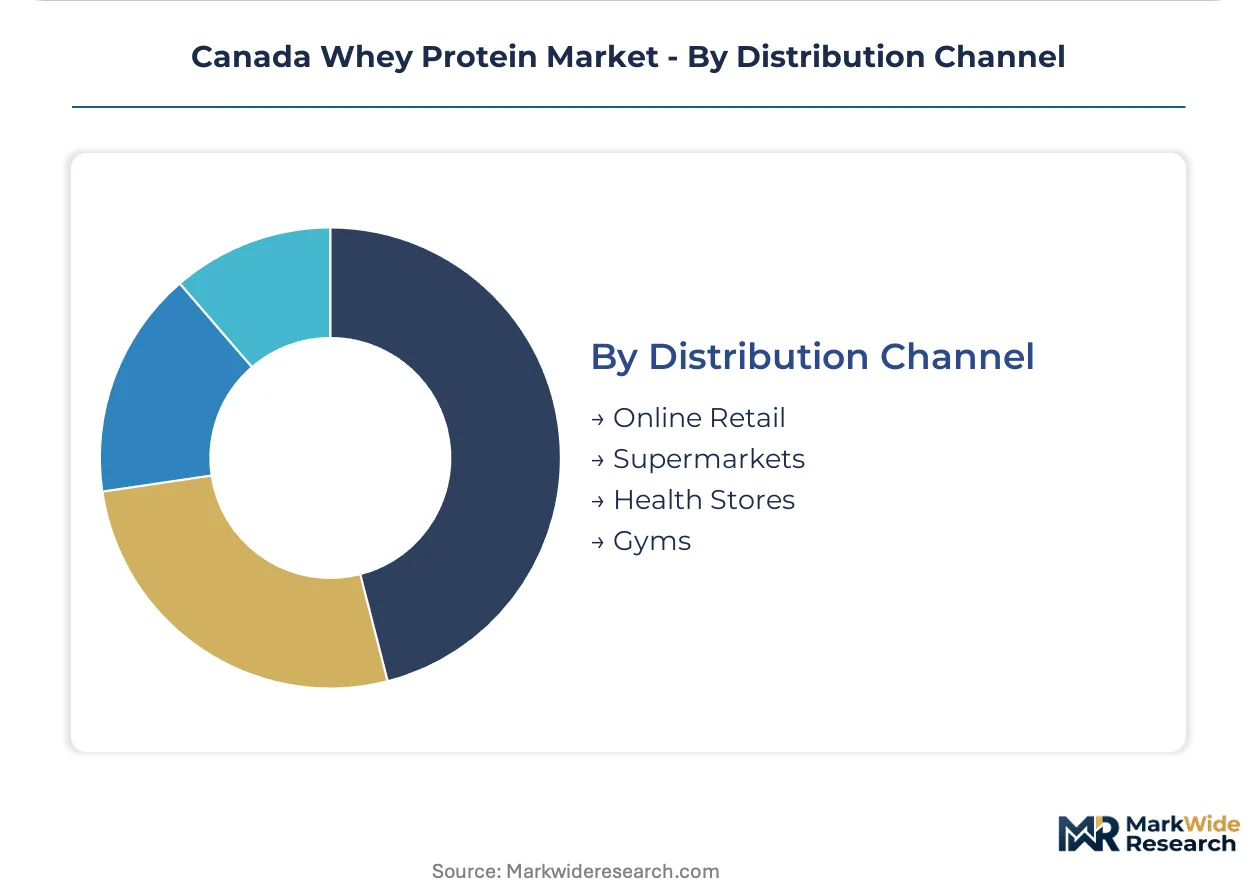
Distribution Channel:
Channel selection reflects purchase urgency, product education requirements, and replenishment frequency.
- Online Retail:Direct-to-consumer platforms enable flavor customization and subscription scheduling. Vancouver and Calgary consumers aged 25-40 favor this channel for isolate and hydrolysate procurement.
- Supermarkets:Mass retail placement captures impulse purchases and routine pantry replenishment. Loblaws and Sobeys networks dominate this channel in Ontario and Quebec urban centers.
- Health Stores:Specialty retailers provide product education and premium positioning for organic and grass-fed certified offerings. Independent operators in Toronto and Montreal sustain this channel's relevance.
- Gyms:Point-of-sale placement at fitness facilities captures immediate post-workout consumption demand. GoodLife Fitness and independent box gyms in Alberta and British Columbia operate this channel.
Supermarkets retain volume leadership; Online Retail gains share fastest through subscription model scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processing infrastructure concentrates in Ontario and Quebec, where cheese-making byproduct streams feed fractionation capacity. These provinces anchor whey protein supply chains through established cooperative networks and urban demand density.
Ontario
Toronto's metropolitan fitness culture drives isolate demand through specialty retail and direct-to-consumer channels. Health Canada's Natural and Non-prescription Health Products Directorate enforces Good Manufacturing Practices for supplement registration in this province. The St. Hubert plant network in southwestern Ontario sustains whey isolate output for North American export markets.
Quebec
Montreal anchors clinical nutrition procurement with hospital formulary committees incorporating whey into sarcopenia protocols. The Canadian Dairy Commission's pricing framework shapes milk input costs for Quebec processors. Agropur Dairy Cooperative leverages backward integration into cheese-making byproducts to anchor its ingredient business from Montreal-area facilities.
Alberta
Calgary and Edmonton represent underserviced demand nodes for institutional and retail volume currently supplied from Ontario. The Canadian Food Inspection Agency monitors dairy ingredient safety under Safe Food for Canadians Regulations across Prairie processing facilities. Cold-chain logistics investments in Edmonton could capture western distribution share currently dependent on eastern supply chains.
British Columbia
Vancouver's health-conscious consumers aged 25-40 favor online subscription models for isolate and hydrolysate procurement. Health Canada's NNHPD framework governs label claims verification for products entering this market. Sports nutrition manufacturers in the Lower Mainland adopt ceramic membrane systems for native whey protein recovery with superior emulsification properties.
Canada Whey Protein Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue clinical nutrition and functional food positioning. The market structures around dairy cooperative networks with captive whey streams and multinational ingredient suppliers with global fractionation footprints. Three archetypes dominate: backward-integrated cooperatives controlling milk supply, specialist ingredient divisions of diversified dairy corporations, and commodity traders sourcing from multiple jurisdictions. Competitive moves concentrate on membrane technology upgrades and geographic expansion into underserviced western provinces.
Within the cooperative archetype, Agropur Dairy Cooperative and Fonterra Co-operative Group represent member-owned structures with integrated cheese-making and protein fractionation operations. Among diversified dairy corporations, Groupe Lactalis and Saputo occupy positions spanning consumer brands and ingredient supply, leveraging manufacturing scale across multiple fractionation lines. These entities exemplify how control over milk input streams and spray-drying infrastructure anchors competitive positioning in a supply-managed environment.
| Leading Market Players |
|---|
| Groupe Lactalis |
| Saputo |
| Agropur Dairy Cooperative |
| Davisco Foods International |
| Royal FrieslandCampina |
| Arla Foods |
| Glanbia |
| Hilmar Ingredients |
| Fonterra Co-operative Group |
| Others |
Value Chain & Pricing Dynamics
Health Canada's NNHPD certification requirements gate qualified supply and premium-tier pricing access, as manufacturers must demonstrate amino acid profile compliance through third-party testing against reference standards before commanding isolate premiums.
Pricing Analysis
Third-party analytical verification bundling separates certified NNHPD-registered isolate from unverified concentrate offerings. Pricing stratifies across premium, standard, and economy tiers based on protein purity grade and lactose content threshold. Cost compression in concentrate exports is intensifying because New Zealand and US spot markets undercut Canadian Dairy Commission price floors. Institutional food manufacturers in Ontario exhibit highest price sensitivity, while competitive bodybuilders in Toronto and Vancouver absorb premiums for rapid-absorption hydrolysate formats.
Supply Chain Analysis
Cheese-making byproduct streams from Ontario and Quebec dairy cooperatives anchor domestic whey protein supply. Raw whey draws from Groupe Lactalis St. Hubert facilities, Agropur Montreal-area cheese plants, and Saputo fractionation lines. Single-source vulnerability concentrates in the Montreal-Toronto corridor, where over 80 percent of fractionation capacity sits within 300 kilometers. Distribution runs through dairy cooperative networks for institutional volume, with direct-to-consumer channels capturing premium isolate and hydrolysate demand in Vancouver and Calgary.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over cheese-making byproduct streams determines processor margin sustainability and isolate output capacity.
For Market Incumbents: Cement supply security through captive whey stream agreements with Quebec and Ontario dairy cooperatives, insulating against plant protein substitution from Prairie pea and fava processing facilities. Expand ceramic membrane filtration capacity at St. Hubert and Montreal-area plants to defend premium isolate positioning against commodity concentrate price erosion. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to entry for Alberta and British Columbia fitness enthusiasts aged 25-40, where eastern supply chains currently underservice demand. Target clinical nutrition procurement committees in Montreal hospitals with NNHPD-registered hydrolysate formulations for sarcopenia protocols, leveraging 18-24 month compliance timelines as competitive moats against established sports nutrition brands. For Investors and Strategic Acquirers: Membrane technology upgrade announcements at legacy cooperatives are the leading indicator that operational scaling constraints are easing, signaling viable acquisition windows for engineering-starved processing assets. Prioritize western Canada distribution infrastructure plays in Calgary and Edmonton, where cold-chain logistics investments could capture institutional volume currently supplied from Ontario.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Filtration Deployment | Native whey protein recovery with superior emulsification properties enables ready-to-drink beverage expansion in British Columbia. |
| Backward Integration into Cheese-Making Byproducts | Agropur and cooperative processors secure captive whey streams under Canadian Dairy Commission pricing frameworks. |
| Direct-to-Consumer Subscription Launch | Flavor customization and auto-replenishment scheduling capture Vancouver and Calgary fitness enthusiasts aged 25-40. |
| Clinical Nutrition NNHPD Registration | Hospital formulary committee approval for sarcopenia protocols opens premium positioning in Montreal and Toronto. |
| Western Distribution Infrastructure Buildout | Cold-chain logistics investments in Edmonton reduce dependency on eastern supply chains for Prairie demand. |
Study Parameters
Document review covered Canadian Dairy Commission pricing bulletins, Health Canada NNHPD product registration databases, and Safe Food for Canadians Regulations enforcement records, complemented by interviews with dairy processing engineers, sports nutrition brand formulation directors, hospital procurement committee members, and clinical dietitians specializing in sarcopenia management. Secondary validation drew from Canadian Food Inspection Agency inspection reports, provincial dairy cooperative annual disclosures, and retail audit data from Nielsen and Circana. Bottom-up volume estimates from fractionation capacity utilization triangulated against top-down demand projections from fitness participation rates and clinical nutrition protocol adoption.
Historical capacity expansion patterns cross-referenced against panel input from membrane technology suppliers and spray-dryer equipment manufacturers informed the analytical framework across the projection horizon. Segmentation modeling incorporated product type, form, end user archetype, and distribution channel dimensions. CAGRs were derived from protein fractionation output trends and sports nutrition category velocity data. Forecast inputs included Canadian Dairy Commission milk pricing reform scenarios and plant protein substitution elasticity coefficients from Prairie processing facility output.
The model holds under stable supply management rules and NNHPD compliance timelines; deviation in Canadian Dairy Commission pricing reform or membrane technology talent availability would shift processor margin structures. Forecasts reflect documented assumptions about whey stream availability and clinical nutrition procurement integration. Supply management rule changes, plant protein functional performance advances, and NNHPD analytical method updates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Global Egg Protein Market