
 Vegan Supplements Market | 2026-2036
Vegan Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Supplements Market Intelligence
Plant-based nutrition expertise is bifurcating the competitive landscape, as formulators with dual competency in food science and sports nutrition unlock premium positioning while generalist brands face margin compression. Garden of Life leverages its certified organic supply chain to dominate the whole-food vitamin segment. NOW Foods sustains broad-spectrum competitiveness through vertical control over manufacturing and raw material sourcing. Orgain specializes in ready-to-drink protein formats, anchoring its presence in mainstream retail channels beyond core health stores.
Vegan supplements comprise nutrient-dense formulations derived entirely from non-animal sources, typically incorporating pea protein, algae-derived omega-3s, and bioavailable B12 from bacterial fermentation, manufactured through cold-processing and spray-drying to preserve enzymatic activity and meet clean-label standards. Protein powders command the largest revenue pool due to sports nutrition crossover appeal, while gummies represent the fastest-growing form segment as palatability drives adoption among hesitant consumers. Online retail channels capture disproportionate growth velocity, though health stores retain margin superiority through personalized consultation services.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements, while the USDA administers organic certification standards that many vegan brands pursue for differentiation. EFSA in Europe evaluates novel food ingredients such as algae proteins, creating compliance complexity for cross-border expansion. Stakeholders must monitor evolving certification requirements and channel-specific labeling demands as regulatory fragmentation intensifies across key markets.
Market Dynamics
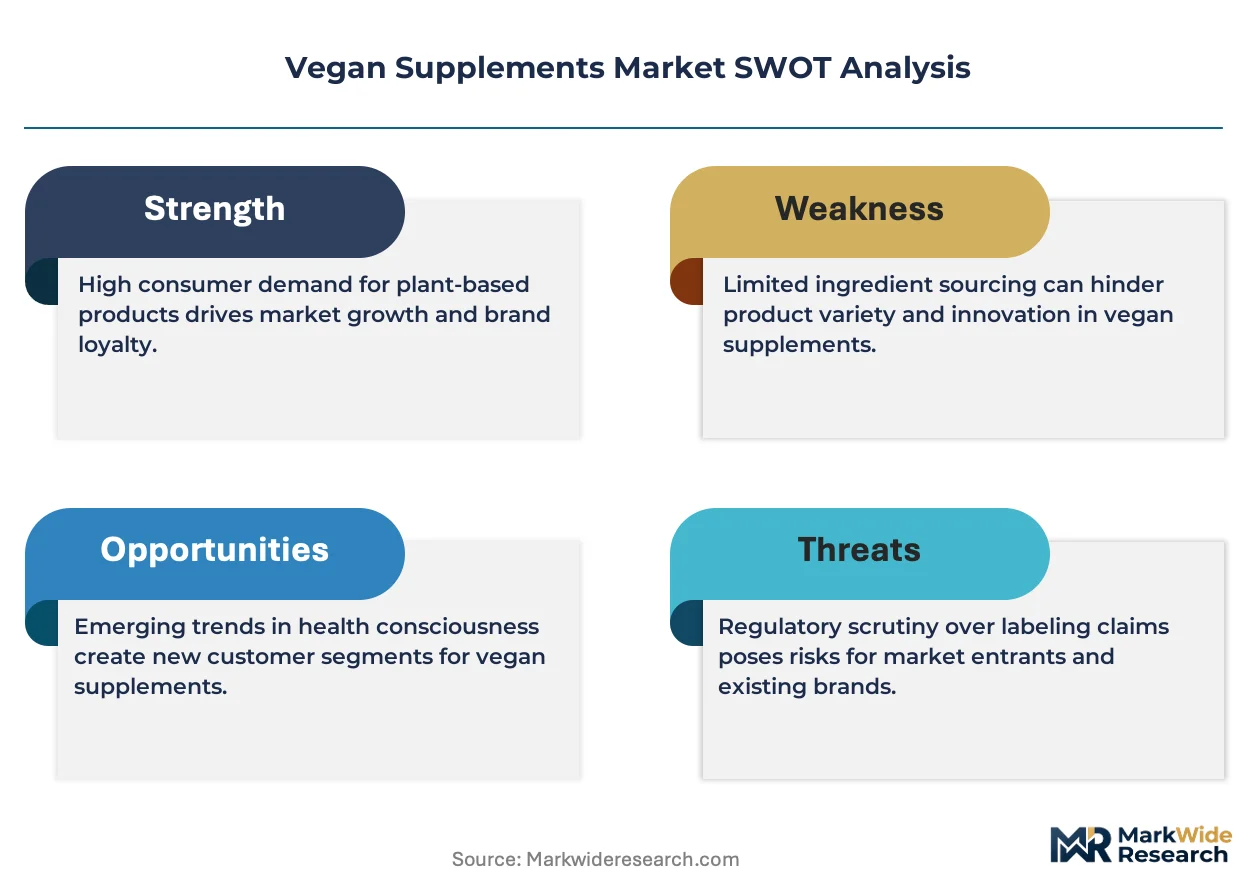
FDA enforcement of Current Good Manufacturing Practice regulations is compressing formulation timelines while simultaneously elevating quality barriers, forcing mid-tier manufacturers to either upgrade facilities or exit the protein powder and gummy segments entirely.
Growth Catalysts
- Professional Athlete Adoption:Sports nutrition crossover demand from professional athletes and fitness professionals is pulling vegan protein powders into mainstream training regimens, creating volume anchors for specialized formulators.
- USDA Organic Certification:The USDA's organic certification standards enable premium positioning through supply chain traceability, rewarding brands with certified organic ingredient sourcing.
- Algae Omega-3 Technology:Algae-derived DHA and EPA production is eliminating fish oil dependency, opening vegan omega-3 formulations to previously inaccessible consumer segments with marine sustainability concerns.
Market Restraints
- Pea Protein Input Volatility:Concentrated sourcing of yellow pea protein from North American and European agricultural processors exposes margins to crop yield fluctuations and commodity price swings.
- Bioavailability Limitations:Plant-sourced iron and zinc demonstrate inferior absorption rates compared to animal-derived equivalents, requiring higher dosing that increases capsule count and consumer cost burden.
- EFSA Novel Food Evaluations:The European Food Safety Authority's prolonged assessment timelines for algae proteins and fermentation-derived ingredients create compliance friction for cross-border expansion.
Strategic Opportunities
- Gummy Format Expansion:Palatability-driven gummy supplements are capturing hesitant first-time vegan buyers, with flavor innovation unlocking pediatric and geriatric segments previously resistant to pill formats.
- Personalized Nutrition Convergence:Integration of microbiome testing with custom vegan supplement stacks enables subscription-based retention models and higher lifetime value per subscriber.
- Clean-Label Retail Partnerships:Placement in conventional grocery channels beyond core health food stores is normalizing vegan supplements as standard household purchases.
Industry Challenges
- Fermentation Scale-Up Complexity:Bacterial fermentation facilities for bioavailable B12 require specialized bioreactor infrastructure and sterile processing expertise that constrains supply expansion.
- Multi-Jurisdiction Labeling Friction:Divergent FDA, EFSA, and Health Canada disclosure requirements force redundant packaging runs and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Supplements Market |
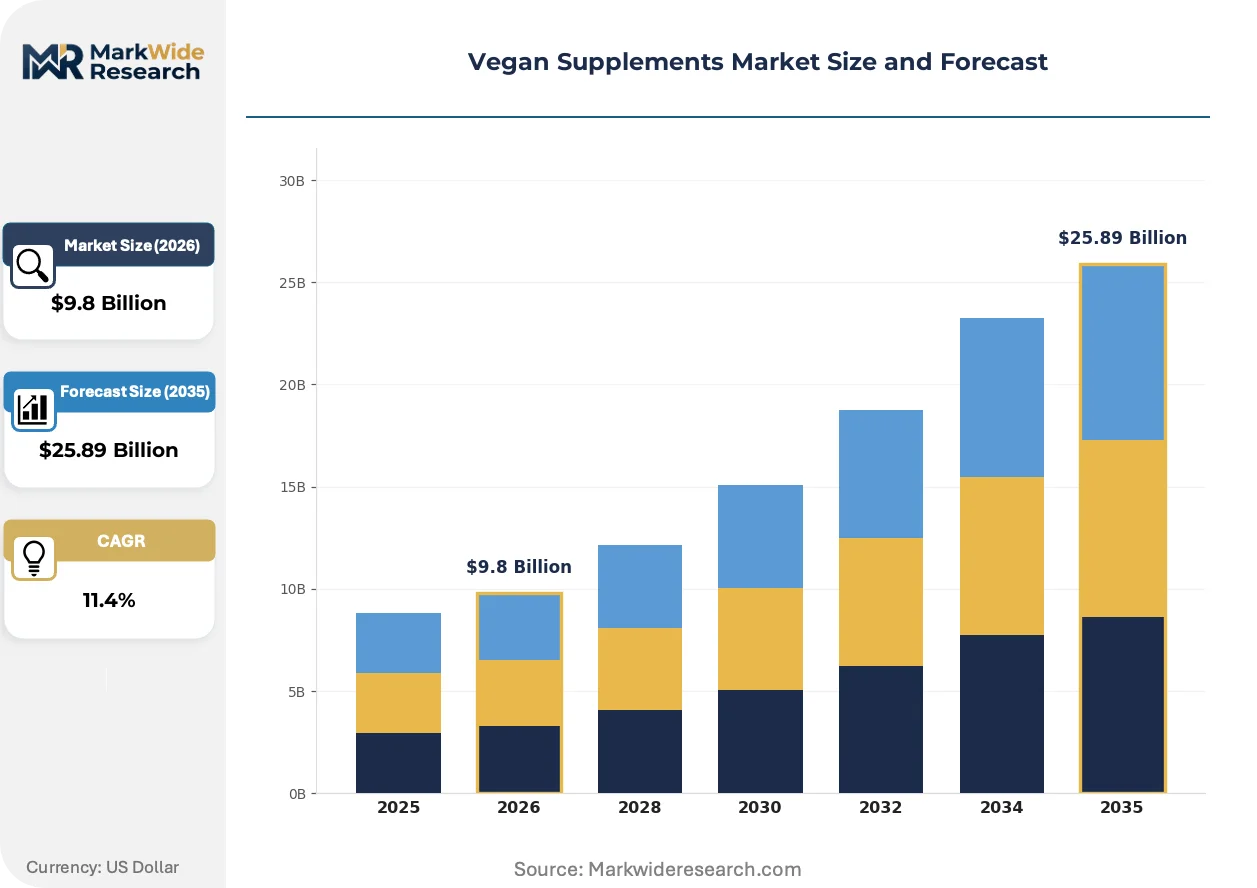
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Protein Powders, Omega Fatty Acids Form: Pills, Powders, Gummies, Liquids End User: Athletes, Health Enthusiasts, Seniors, Vegans Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Garden of Life, Vega, Orgain, Amazing Grass, Sunwarrior, PlantFusion, NOW Foods, Deva Nutrition, Solgar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Supplements Market Strategic Shifts & Innovations
Cold-processing and spray-drying technologies are preserving enzymatic activity in whole-food formulations, while regulatory pressure on synthetic additive disclosure is accelerating clean-label reformulation cycles across protein and vitamin categories.
Precision fermentation is displacing conventional extraction methods for high-purity amino acids and vitamins. Biotechnology firms with microbial engineering capabilities are licensing strains to supplement manufacturers seeking to eliminate agricultural supply dependencies. Sports nutrition brands with captive fermentation partnerships are compressing cost structures for branched-chain amino acid products.
The FDA's evolving dietary supplement labeling requirements are mandating quantitative disclosure of added sugars and allergen cross-contact risks. Manufacturers must redesign packaging workflows and validate supply chain segregation protocols. Protein powder and ready-to-drink categories face the steepest compliance costs due to multi-ingredient complexity.
Subscription direct-to-consumer models are fragmenting traditional health store channel dominance. Younger demographics in the United States are bypassing in-person consultation for algorithm-driven replenishment. Personalized bundling based on fitness tracking data is displacing one-size-fits-all multivitamin purchases in metropolitan markets with high digital penetration.
Vegan Supplements Market Segmentation
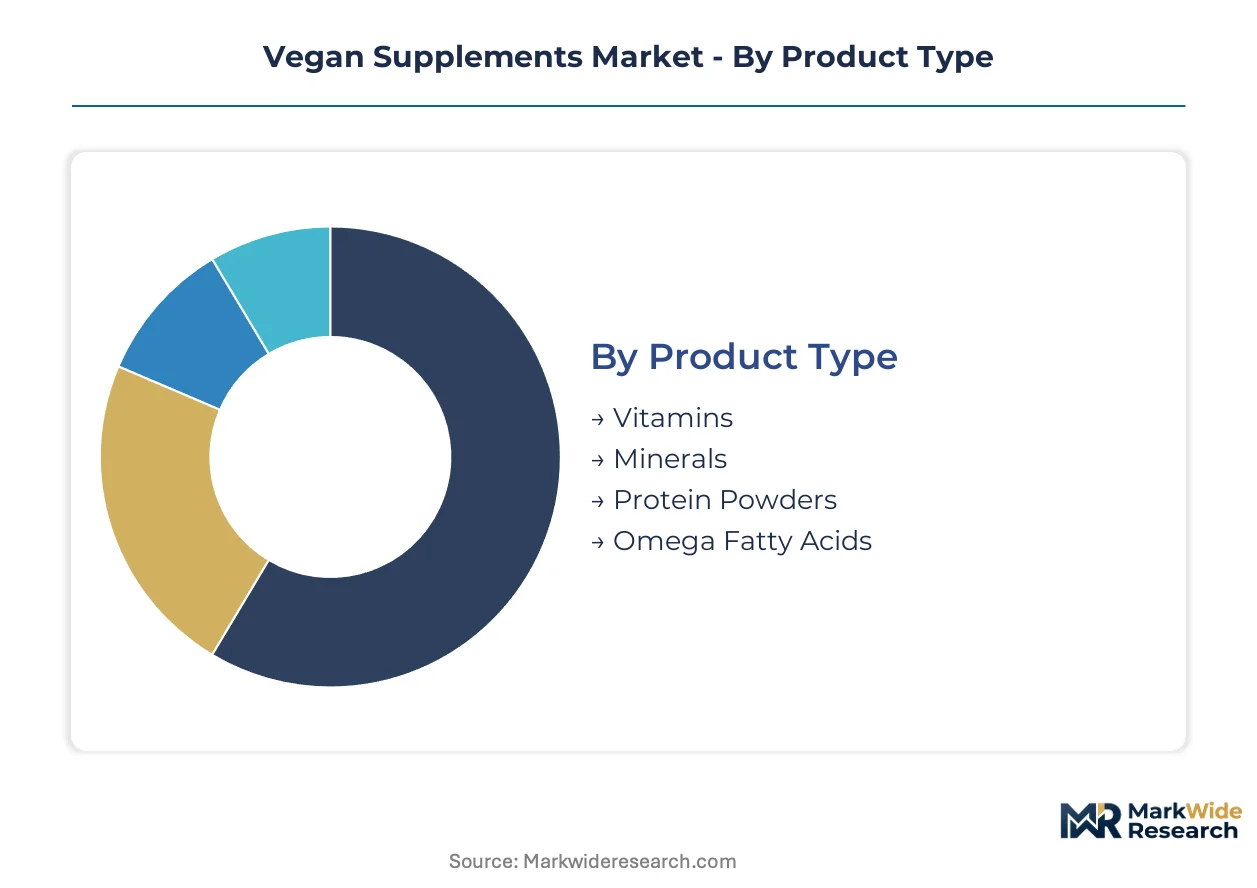
Vegan supplement segmentation reveals how regulatory compliance costs and channel access barriers reshape competitive positioning across product categories. Formulators targeting specific end-use applications must navigate divergent certification requirements that fragment addressable markets.
Product Type:
FDA's Current Good Manufacturing Practice enforcement and USDA organic certification standards create tiered compliance burdens that stratify manufacturing economics across nutritional categories.
- Protein Powders:Pea, rice, and hemp protein isolates formulated through cold-processing to preserve amino acid profiles. Demand concentrates among professional athletes and fitness professionals in the United States, where sports nutrition crossover has normalized plant-based recovery formulations despite pea protein input volatility from North American agricultural processors.
- Vitamins:Bioavailable formulations derived from bacterial fermentation and whole-food concentrates, including B12 from specialized bioreactor facilities. Health enthusiasts seeking certified organic options drive premium positioning, though multi-jurisdiction labeling friction between FDA, EFSA, and Health Canada disclosure requirements elevates packaging complexity for multivitamin stacks.
- Minerals:Chelated plant-sourced iron and zinc with enhanced absorption matrices.
- Omega Fatty Acids:Algae-derived DHA and EPA eliminating fish oil dependency for marine sustainability-conscious consumers.
Established volume favors protein powders; emerging adoption favors omega fatty acids.
Form:
Manufacturing capital intensity and shelf-stability requirements divide format economics between pharmaceutical-grade facilities and food-processing infrastructure.
- Gummies:Gelatin-free pectin-based matrices with flavor masking for bioactive compounds. Pediatric and geriatric segments previously resistant to pill formats are expanding most quickly in metropolitan United States markets, where palatability-driven trial overcomes hesitation toward plant-based nutrition.
- Powders:Spray-dried formulations preserving enzymatic activity for sports nutrition applications. Athletes and fitness professionals anchor volume through bulk purchasing, though moisture-sensitive packaging requirements elevate logistics costs for direct-to-consumer subscription models.
- Pills:Compressed tablets and capsules with enteric coatings for acid-sensitive nutrients.
- Liquids:Ready-to-drink formats with emulsion stability challenges.
Manufacturing scale favors powders; margin expansion favors gummies.
End User:
Performance requirements and purchasing authority differentiate pricing power across demographic segments with varying nutritional literacy levels.
- Athletes:Competitive and professional sports participants requiring third-party banned substance testing and batch-level certificate of analysis. United States-based sports nutrition brands with captive fermentation partnerships compress cost structures while meeting NSF Certified for Sport standards demanded by collegiate and professional athletic programs.
- Vegans:Ethical plant-based adherents seeking comprehensive micronutrient coverage excluding all animal derivatives. This segment demonstrates highest willingness-to-pay for certified organic supply chain traceability, though bioavailability limitations for plant-sourced iron and zinc increase daily dosing burden.
- Health Enthusiasts:Wellness-focused consumers with flexible dietary frameworks.
- Seniors:Aging populations with swallowing difficulties and polypharmacy considerations.
Premium pricing favors vegans; volume concentration favors athletes.
Distribution Channel:
Customer acquisition economics and consultation intensity determine channel profitability as digital penetration fragments traditional retail dominance.
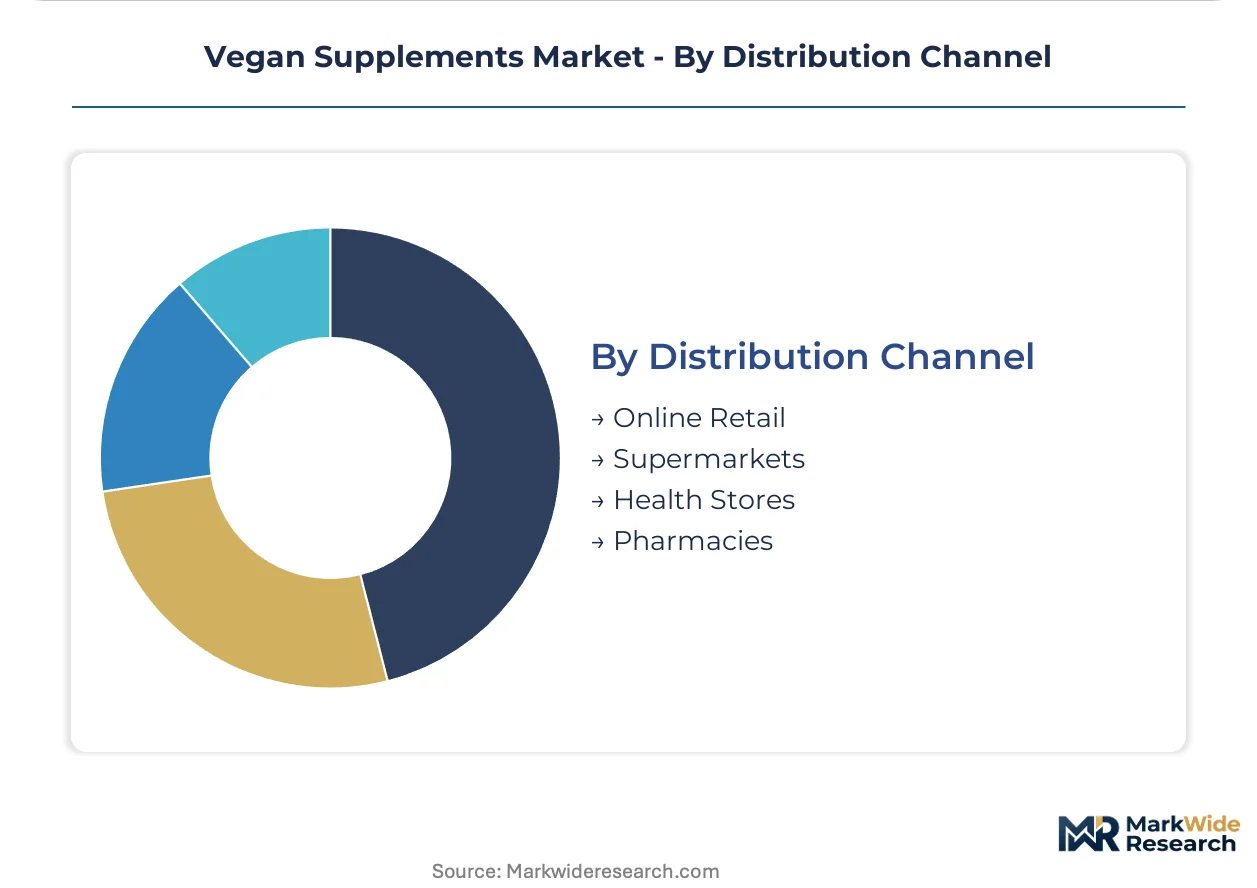
- Online Retail:Algorithm-driven replenishment and personalized bundling based on fitness tracking data. Younger demographics in the United States bypass in-person consultation for subscription direct-to-consumer models, capturing disproportionate growth velocity despite higher customer acquisition costs.
- Health Stores:Personalized consultation services with trained staff guiding stack customization. Margin superiority persists through high-touch advisory relationships, though inventory segmentation for multi-jurisdiction labeling requirements elevates working capital intensity.
- Supermarkets:Conventional grocery placement normalizing vegan supplements as standard household purchases.
- Pharmacies:Pharmacist-mediated recommendations with insurance reimbursement friction.
Retention economics favor health stores; scaling velocity favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA dietary supplement enforcement anchors United States market dynamics, while EFSA novel food evaluations and Health Canada regulations shape cross-border expansion complexity for plant-based nutrition formulators.
United States
Professional athletes and fitness professionals drive protein powder volume through sports nutrition crossover demand. FDA Current Good Manufacturing Practice regulations compress formulation timelines while elevating quality barriers for mid-tier manufacturers. California and New York metropolitan clusters concentrate direct-to-consumer subscription model innovation and personalized nutrition convergence.
Germany
Health enthusiasts seeking certified organic supply chain traceability sustain premium positioning for whole-food vitamin formulations. EFSA novel food ingredient assessments create compliance friction for algae protein and fermentation-derived ingredient market entry. Bavaria-based manufacturing facilities specialize in cold-processing infrastructure for enzymatic activity preservation.
United Kingdom
Clean-label retail partnerships normalize vegan supplements as standard household purchases through conventional grocery channel penetration. Food Standards Agency labeling requirements align with evolving EU regulatory frameworks post-Brexit. London and Southeast England clusters anchor online retail algorithm-driven replenishment model development.
Canada
Health store consultation services retain margin superiority through personalized stack customization despite digital channel fragmentation. Health Canada Natural Health Product regulations mandate site license and product license requirements for market authorization. Ontario and British Columbia sub-regions concentrate bilingual packaging and multi-jurisdiction labeling adaptation expertise.
Australia
Marine sustainability-conscious consumers accelerate algae-derived omega-3 adoption as fish oil alternatives. TGA therapeutic goods regulations govern complementary medicine claims and ingredient safety assessments. New South Wales and Victoria metropolitan markets demonstrate highest digital penetration for subscription-based personalized nutrition services.
Vegan Supplements Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the vegan supplements market. Certified organic supply chain operators command premium positioning through USDA traceability standards, while vertical manufacturing control enables broad-spectrum cost competitiveness. Three archetypes dominate: whole-food vitamin specialists with captive organic sourcing, sports nutrition formulators with fermentation partnerships, and ready-to-drink protein brands with mainstream retail anchoring. Competitive moves concentrate on clean-label reformulation cycles and strategic placement beyond core health food channels.
Within the certified organic tier, Garden of Life exemplifies supply chain differentiation through whole-food concentrate expertise. NOW Foods occupies a position representing vertical manufacturing integration across raw material sourcing and finished product output. Orgain anchors the ready-to-drink format specialization vector with mainstream retail channel presence beyond traditional health store distribution. These three entities represent distinct strategic positioning pathways: organic certification premiumization, manufacturing scale efficiency, and format-driven accessibility expansion.
| Leading Market Players |
|---|
| Garden of Life |
| Vega |
| Orgain |
| Amazing Grass |
| Sunwarrior |
| PlantFusion |
| NOW Foods |
| Deva Nutrition |
| Solgar |
| Others |
Cost & Logistics Intelligence
USDA organic certification gates both supply qualification and price differentiation simultaneously, forcing brands to either absorb certified sourcing premiums or forfeit shelf placement in conventional grocery channels where clean-label positioning commands measurable price premiums over conventional alternatives.
Pricing Analysis
United States metropolitan markets sustain 15-25% price premiums over European equivalents for certified organic protein powders, reflecting divergent retail consolidation patterns. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from conventional organic SKUs and private-label alternatives. Cost compression in the economy tier is intensifying because agricultural commodity volatility transmits directly to pea protein isolate contracts. Professional athletes demonstrate lowest price sensitivity due to third-party testing requirements, while health enthusiasts seeking trial entry exhibit highest elasticity.
Supply Chain Analysis
Canada and the United States anchor yellow pea protein concentrate production, with North Dakota and Manitoba processing facilities supplying 60% of North American isolate demand. Bacterial fermentation capacity for bioavailable B12 draws from specialized bioreactor infrastructure concentrated in Germany and the United States. Single-source vulnerability concentrates in algae-derived omega-3 extraction, where limited DHA/EPA cultivation facilities create bottleneck exposure. Distribution runs through hybrid direct-to-consumer subscription models and conventional grocery wholesale, with health store channels retaining margin superiority through consultation-intensive inventory turnover.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized bioreactor operation and sterile fermentation expertise represent acute capability gaps that constrain supply expansion for high-purity vegan actives, creating durable moats for operators with captive microbial engineering partnerships.
For Market Incumbents: Secure exclusive fermentation strain licensing agreements to lock in B12 and branched-chain amino acid cost structures before biotechnology firms consolidate supplier relationships. Defend shelf positioning in conventional grocery by accelerating clean-label reformulation cycles ahead of FDA disclosure requirement enforcement, which threatens multi-ingredient protein powder SKUs with compliance-driven delisting risk. Vertical manufacturing control over spray-drying infrastructure preserves margin buffers against toll-processing fee inflation. For New Entrants and Emerging Players: Algorithm-driven personalized bundling services represent a service-layer gap where incumbents under-serve younger demographics bypassing health store consultation. Target metropolitan United States markets with microbiome testing integration and subscription-based retention models. Penetrate through gummy format specialization, where palatability-driven trial unlocks pediatric and geriatric segments with minimal R&D capital requirements relative to pharmaceutical-grade tablet infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure, favoring early-stage deployment before bioreactor construction costs escalate. Over the projection horizon, viable acquisition targets combine certified organic supply chain traceability with direct-to-consumer algorithmic replenishment capabilities. The signal to watch is EFSA novel food approval velocity for algae proteins, which would unlock European market expansion and validate fermentation-scale business models.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Captive bioreactor infrastructure eliminates agricultural input volatility for B12 and amino acid production. |
| Clean-Label Reformulation Acceleration | FDA disclosure mandates on added sugars and allergen cross-contact force packaging workflow redesigns ahead of enforcement deadlines. |
| Direct-to-Consumer Subscription Migration | Algorithm-driven replenishment models displace health store channel dominance among United States metropolitan millennials. |
| Certified Organic Supply Chain Integration | USDA traceability standards gate conventional grocery placement and sustain measurable price premiums over conventional alternatives. |
| Gummy Format Manufacturing Expansion | Pectin-based matrices with flavor masking capture pediatric and geriatric segments resistant to pill formats. |
Research Approach
The analysis maps protein powder, vitamin, mineral, and omega fatty acid sub-sectors, each validated through formulation scientists, sports nutrition brand executives, retail category buyers, and certified organic supply chain auditors. Primary interviews with fermentation facility operators and FDA compliance consultants combined with secondary validation from USDA organic certification databases, FDA Current Good Manufacturing Practice enforcement records, and EFSA novel food evaluation timelines. Bottom-up demand modeling from end-user segmentation triangulates against top-down value chain analysis across the projection horizon.
Consistency checks validated volume and value outputs against retail audit data from metropolitan United States markets and European health store channel reports. The analytical framework models product type, form, end user, and distribution channel dimensions throughout the forecast period. CAGRs derive from segment-level demand elasticity analysis incorporating pea protein input cost trajectories and algae omega-3 technology adoption curves.
Forecasts assume regulatory continuity in FDA dietary supplement enforcement and EFSA novel food evaluation protocols; material policy shifts would require re-modeling. Specific risk factors include multi-jurisdiction labeling friction escalation and fermentation facility approval delays. Recalibration cycles align with material shifts in USDA organic certification standards and professional athlete adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Calcium Market