
 North America Prenatal Supplements Market | 2026-2036
North America Prenatal Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Prenatal Supplements Market Analytics
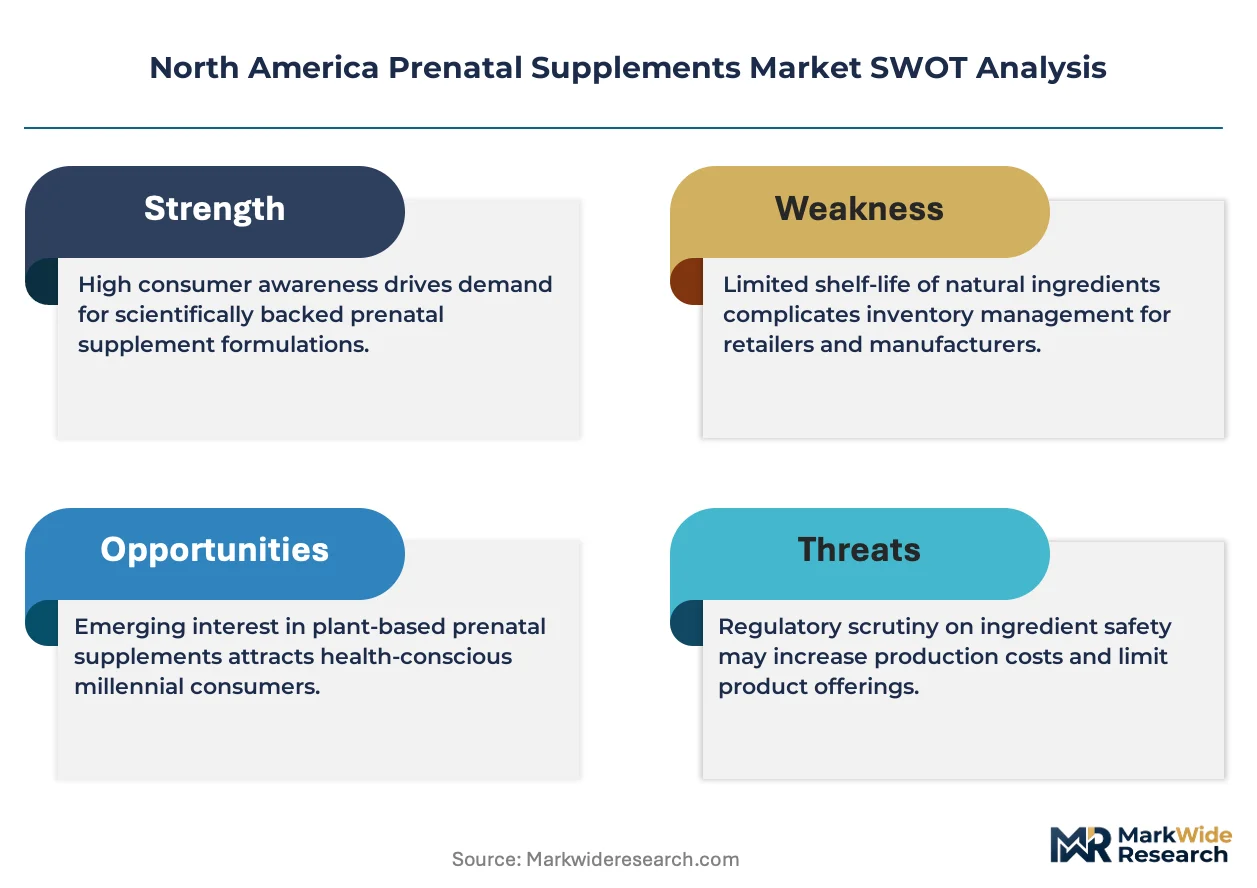
Single-source ingredient procurement is rebalancing toward multi-supplier arrangements as manufacturers seek supply security for methylfolate and algae-derived DHA. Bayer AG leverages its pharmaceutical heritage to sustain credibility with obstetrician networks, while Garden of Life differentiates through USDA Organic and Non-GMO Project certifications. Thorne HealthTech Inc. anchors its position via practitioner-exclusive distribution and third-party NSF testing protocols.
North America prenatal supplements encompass formulated nutritional products containing folic acid, iron, calcium, iodine, and DHA, manufactured through tablet compression, softgel encapsulation, or spray-drying processes, designed to support fetal neural tube development and maternal hematologic health during gestation. The vitamins segment dominates volume, with methylated B12 and activated folate variants commanding premium positioning, while gummies represent the fastest-expanding form factor as pill-fatigue drives format innovation among first-trimester users. Online retail channels capture disproportionate growth, though pharmacies retain margin concentration through clinician endorsement and insurance-adjacent purchasing programs.
FDA's Current Good Manufacturing Practice regulations and the FTC's substantiation standards for health claims jointly elevate compliance costs for new entrants, while Health Canada Natural and Non-prescription Health Products Directorate requirements create additional cross-border formulation complexity. Stakeholders must monitor evolving state-level Medicaid reimbursement for prescription prenatal vitamins and the trajectory of personalized nutrition platforms integrating biomarker testing into supplement regimens.
Market Dynamics
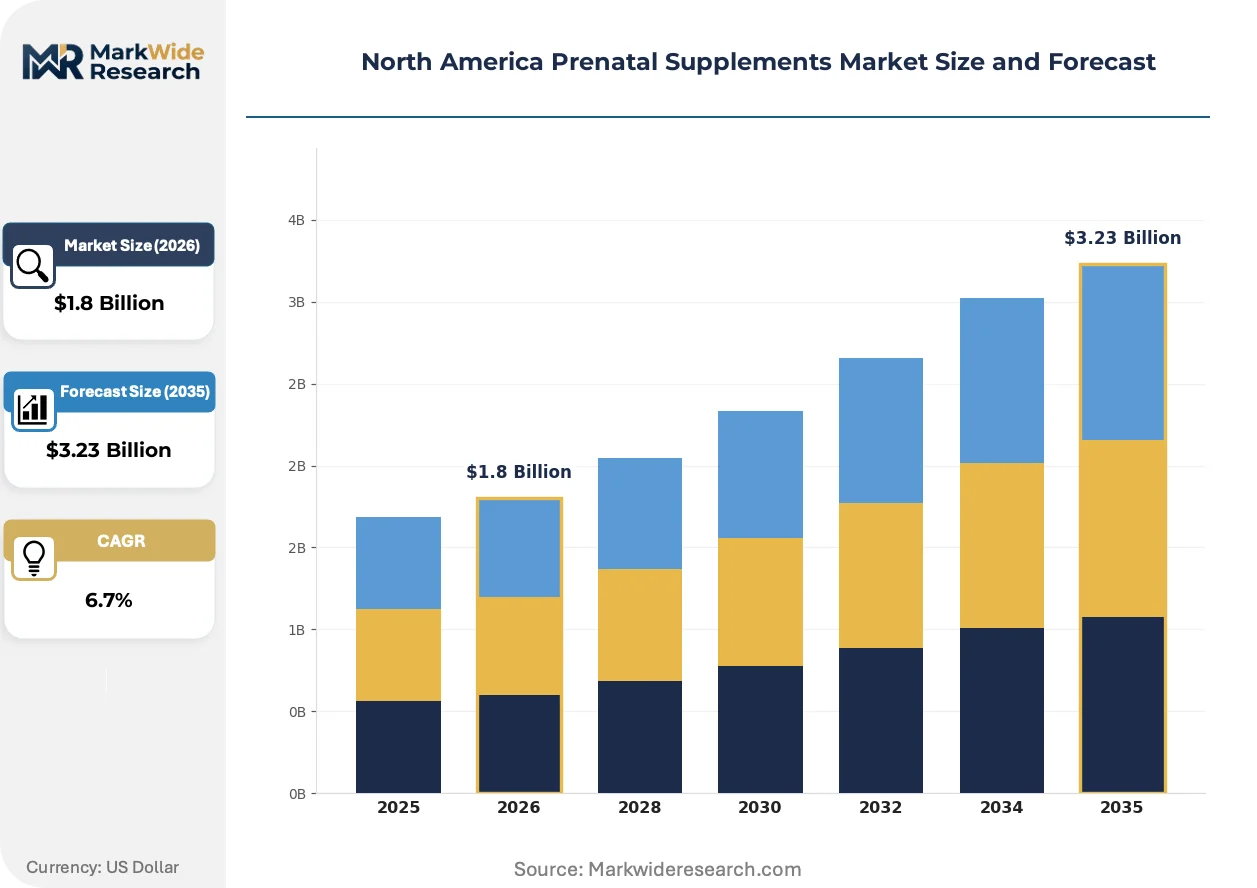
Millennial and Gen Z expectant mothers are reconfiguring prenatal supplement demand toward methylated folate and algae-derived DHA formulations, pressuring legacy manufacturers to reformulate portfolios while absorbing FDA compliance cost escalations.
Growth Catalysts
- DSHEA enforcement priorities:Heightened FDA scrutiny of health claims substantiation is filtering out marginal competitors, consolidating shelf space for established brands with compliant labeling infrastructure.
- Direct-to-consumer subscription models:Pharmacy-based counseling services in California and Texas are converting one-time buyers into recurring revenue streams through insurance-adjacent purchasing programs.
- Pill-fatigue among first-trimester users:Format innovation toward gummy and liquid delivery systems is expanding addressable market share among nausea-affected consumers who cannot tolerate traditional tablets.
Market Restraints
- Algae-derived DHA supply concentration:Single-source dependency on marine biotechnology suppliers creates input volatility when harvest conditions fluctuate.
- Health Canada cross-border complexity:Natural and Non-prescription Health Products Directorate requirements force dual formulation tracks, elevating working capital requirements for North American manufacturers.
- Iron bisglycinate cost premium:Gentler absorption forms command 3-4x raw material cost versus ferrous sulfate, compressing margin on price-sensitive pharmacy contract bids.
Strategic Opportunities
- Medicaid reimbursement expansion:State-level prescription prenatal vitamin coverage in Texas and New York is creating pharmacy channel pull-through for clinically endorsed brands.
- Biomarker-integrated personalization:MTHFR genetic testing platforms are converging with supplement regimens to enable folate metabolism-customized dosing protocols.
- Practitioner-exclusive distribution:Clinician counseling networks represent underexploited channels where professional endorsement drives premium price realization.
Industry Challenges
- NSF/USP certification timelines:Third-party testing protocol completion stretches 8-14 months, delaying new formulation launches past critical gestational marketing windows.
- Methylfolate synthesis expertise scarcity:Qualified analytical chemists capable of validating 6S-5-methyltetrahydrofolate stability command compensation premiums that strain mid-tier R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Prenatal Supplements Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Omega-3 Fatty Acids, Probiotics Form: Tablets, Capsules, Powders, Gummies Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores End User: Pregnant Women, Healthcare Providers, Nutritionists, Gynecologists |
| Companies Covered | Church & Dwight Co., Inc., Nestle S.A., Procter & Gamble Company, Bayer AG, Abbott Laboratories, Country Life, Garden of Life, Rainbow Light Nutritional Systems, Thorne HealthTech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Prenatal Supplements Market Evolving Landscape
Format diversification and supply chain digitization are converging to compress product development cycles while elevating traceability expectations among ingredient-conscious buyers.
Near-infrared spectroscopy is automating raw material identity verification at receiving docks, enabling real-time release decisions that compress quality hold times from weeks to hours. Contract manufacturers serving subscription-focused brands are adopting this technology fastest, eliminating bottlenecks that previously constrained just-in-time production models.
FDA's updated dietary supplement labeling requirements are mandating clearer pregnancy-specific warnings and nutrient disclosure formats, forcing reformulation of legacy SKUs to maintain shelf placement. Manufacturers with centralized regulatory affairs functions are absorbing these transitions more efficiently than decentralized competitors, widening compliance capability gaps.
Expectant mothers are consolidating purchases through pharmacy-integrated telehealth platforms that bundle prenatal counseling with automated refill scheduling. This channel is displacing traditional retail impulse purchases in California and New York metropolitan corridors, where insurance pre-authorization workflows increasingly originate through digital health portals rather than in-clinic dispensing.
North America Prenatal Supplements Market Segmentation
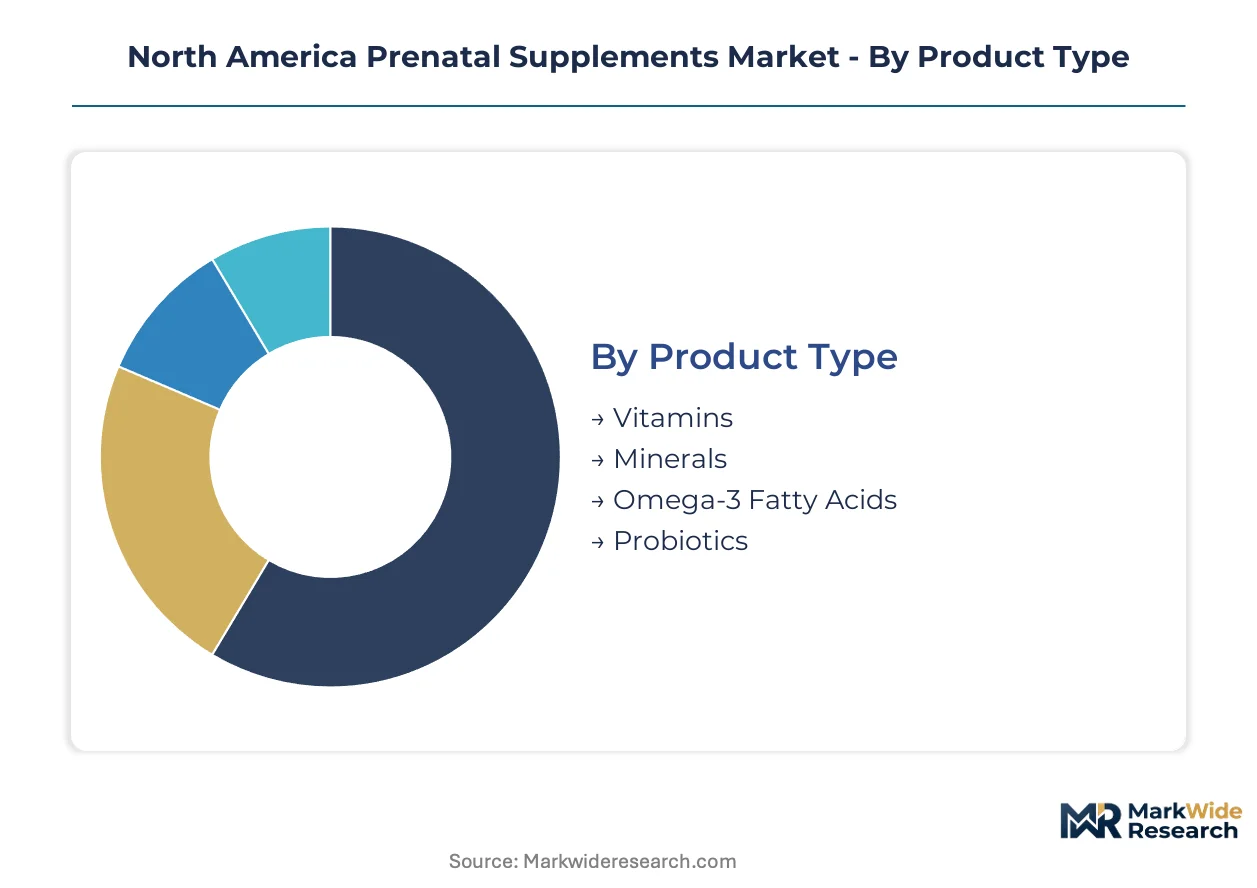
Prenatal supplement manufacturers configure production lines around four intersecting dimensions that determine margin structure and channel access. Supply concentration in methylfolate synthesis and algae-derived DHA shapes which product categories absorb capital investment priority.
Product Type:
Raw material sourcing concentration tilts formulation economics toward vitamin and mineral categories with established supplier networks.
- Vitamins:Methylated B12 and activated folate variants require qualified analytical chemists for 6S-5-methyltetrahydrofolate stability validation. Demand clusters in California, Texas, and New York where direct-to-consumer subscription models convert one-time buyers into recurring revenue.
- Minerals:Iron bisglycinate commands three-to-four times the raw material cost of ferrous sulfate, compressing margins on pharmacy contract bids. Texas and New York Medicaid reimbursement programs are creating pharmacy channel pull-through for clinically endorsed mineral formulations.
- Omega-3 Fatty Acids:Algae-derived DHA supply dependency on marine biotechnology suppliers creates input volatility when harvest conditions fluctuate.
- Probiotics:Strain-specific stability requirements elevate cold-chain logistics costs for direct-to-consumer fulfillment.
Today's leader: Vitamins. Tomorrow's challenger: Omega-3 Fatty Acids.
Form:
Manufacturing equipment specialization and compression tooling investments segment production capacity between solid and alternative delivery formats.
- Tablets:Tablet compression lines dominate contract manufacturing capacity in North America, offering lowest unit cost at scale. Pill-fatigue among first-trimester users with nausea is eroding addressable share in this legacy format.
- Gummies:Format innovation toward gummy delivery systems is expanding market share among nausea-affected consumers who cannot tolerate traditional tablets. California metropolitan corridors show disproportionate gummy adoption through pharmacy-integrated telehealth platforms.
- Capsules:Softgel encapsulation accommodates lipid-soluble nutrients including DHA with superior oxidative stability versus chewable alternatives.
- Powders:Spray-dried formulations serve the smallest addressable segment, concentrated among consumers seeking dose customization.
Tablets retain volume leadership. Gummies are climbing the fastest.
Distribution Channel:
Channel economics diverge sharply between clinician-endorsed pharmacy networks and algorithm-driven digital acquisition.
- Pharmacies:Pharmacy-based counseling services in California and Texas convert one-time buyers into recurring revenue through insurance-adjacent purchasing programs. Clinician endorsement drives premium price realization in this channel.
- Online Retail:Direct-to-consumer subscription models capture disproportionate growth, though customer acquisition costs escalate as digital advertising competition intensifies.
- Supermarkets:Impulse purchase dependency and limited shelf space constrain premium positioning for methylated formulations.
- Health Stores:USDA Organic and Non-GMO Project certification requirements limit supplier base for this channel.
Pharmacies anchor margin concentration. Online retail is gaining share fastest.
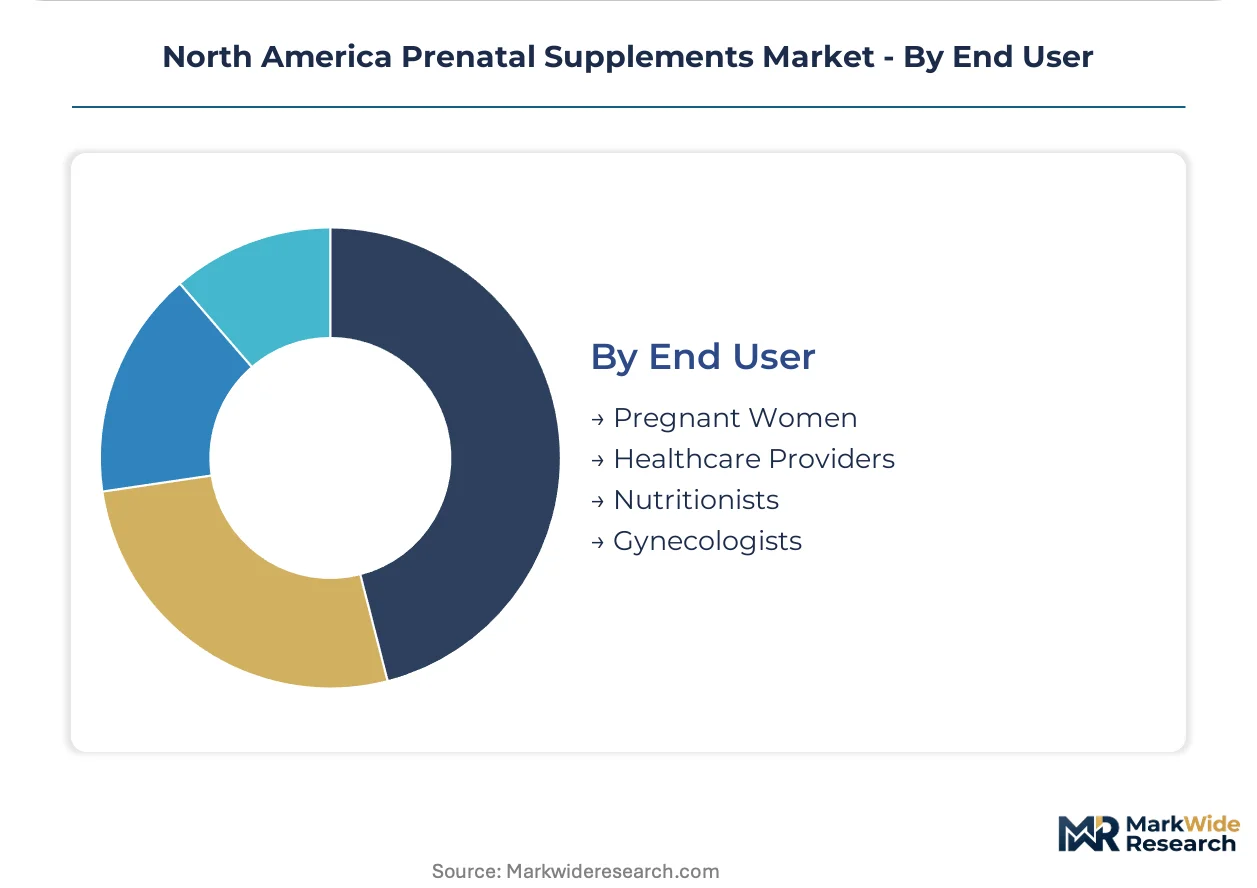
End User:
Purchasing authority and reimbursement access separate consumer-directed from professionally mediated demand.
- Pregnant Women:Millennial and Gen Z expectant mothers are reconfiguring demand toward methylated folate and algae-derived DHA formulations. This segment absorbs format innovation costs most readily.
- Healthcare Providers:Practitioner-exclusive distribution networks represent underexploited channels where professional endorsement drives premium price realization and protocol adherence.
- Nutritionists:Biomarker-integrated personalization platforms are converging with supplement regimens to enable folate metabolism-customized dosing protocols through this advisor channel.
- Gynecologists:Obstetrician network credibility sustains brand preference for manufacturers with pharmaceutical heritage and NSF testing protocols.
Pregnant Women dominate volume. Healthcare Providers offer the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA and Health Canada compliance regimes is concentrating methylfolate synthesis capacity in jurisdictions where dual-certification pathways minimize redundant testing costs. Manufacturers locate blending operations near state-level Medicaid reimbursement hubs to capture pharmacy channel pull-through.
United States
California, Texas, and New York absorb the majority of direct-to-consumer subscription volume, with pharmacy-integrated telehealth platforms displacing traditional retail. FDA Current Good Manufacturing Practice regulations and FTC substantiation standards elevate compliance costs for new entrants. The Los Angeles-San Diego corridor hosts contract manufacturers adopting near-infrared spectroscopy for raw material verification.
Canada
Health Canada Natural and Non-prescription Health Products Directorate requirements force dual formulation tracks for cross-border suppliers. Toronto and Vancouver metropolitan areas concentrate distribution infrastructure serving both domestic demand and re-export to US markets. Quebec's pharmaceutical manufacturing heritage sustains analytical chemistry talent pools for methylfolate stability validation.
Mexico
Pharmacy-based counseling services in Mexico City and Monterrey are expanding insurance-adjacent purchasing programs for prenatal formulations. COFEPRIS regulatory alignment with FDA standards is accelerating contract manufacturing investment in Baja California and Querétaro. Guadalajara's pharmaceutical cluster is developing softgel encapsulation capacity for DHA-fortified products.
North America Prenatal Supplements Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue practitioner-exclusive distribution and biomarker-integrated personalization. The market structures around three tiers: pharmaceutical heritage manufacturers with obstetrician network credibility, certified-organic specialists commanding premium positioning, and subscription-native brands optimizing direct-to-consumer acquisition. Strategic moves concentrate on NSF/USP certification acquisition and algae-derived DHA supply partnerships.
Within the pharmaceutical heritage tier, Bayer AG and Abbott Laboratories anchor positions through clinician endorsement networks and compliance infrastructure. Garden of Life exemplifies the certified-organic specialist archetype, while Thorne HealthTech Inc. occupies the practitioner-exclusive distribution vector with third-party testing protocols. These three entities represent distinct competitive positions rather than overlapping market presence.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Nestle S.A. |
| Procter & Gamble Company |
| Bayer AG |
| Abbott Laboratories |
| Country Life |
| Garden of Life |
| Rainbow Light Nutritional Systems |
| Thorne HealthTech Inc. |
| Others |
Value Network & Pricing Analysis
Millennial and Gen Z expectant mothers concentrated in California, Texas, and New York are driving subscription-based pricing models that reward recurring revenue over transactional pharmacy purchases. This buyer archetype's preference for direct-to-consumer channels is compressing traditional retail markups while elevating premium-tier acceptance for methylated formulations.
Pricing Analysis
Pharmacy channel margins absorb the steepest compression as insurance-adjacent purchasing programs in Texas and New York Medicaid networks limit price flexibility. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified practitioner brands from mass-market tablets and private-label economy tiers. Cost compression in the standard tier intensifies because iron bisglycinate and algae-derived DHA input costs are escalating. First-trimester users seeking gummy formats show least price sensitivity, while supermarket impulse buyers exhibit highest elasticity.
Supply Chain Analysis
Methylfolate synthesis expertise rests on a narrow base of qualified analytical chemists capable of validating 6S-5-methyltetrahydrofolate stability, creating qualified-laboratory dependency in the United States, Canada, and Switzerland. Algae-derived DHA feedstock draws from marine biotechnology suppliers concentrated in coastal regions with harvest condition volatility. Single-source vulnerability for activated folate precursors elevates risk when synthesis batch failures occur. Distribution runs through pharmacy-integrated telehealth platforms in metropolitan corridors alongside traditional wholesale-to-retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in prenatal supplements hinges on methylated formulation premiums offsetting FDA compliance cost escalations. Manufacturers capturing practitioner-channel price realization while automating quality verification will widen profitability gaps.
For Market Incumbents: Cement obstetrician network credibility through NSF certification maintenance and methylfolate stability data packages that subscription-native entrants cannot replicate. Absorb FDA labeling reformulation costs centrally to outpace decentralized competitors. Prioritize backward integration into algae-derived DHA supply partnerships to reduce harvest-volatility exposure. For New Entrants and Emerging Players: Direct-to-consumer telehealth platforms represent the most penetrable route for bypassing pharmacy channel gatekeepers. Target nutritionist-advisor networks in California and New York where biomarker-integrated personalization commands premium positioning. Launch with gummy format SKUs to capture nausea-affected first-trimester users abandoned by legacy tablet manufacturers. For Investors and Strategic Acquirers: Pharmaceutical heritage manufacturers with obstetrician endorsement infrastructure are the most active acquirer in this space, seeking methylfolate synthesis capabilities and practitioner-channel access. Acquisition target archetype: mid-tier contract manufacturers with near-infrared spectroscopy quality systems and California pharmacy network relationships. Watch state-level Medicaid reimbursement expansion in Texas and New York as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner-Exclusive Distribution | Clinician endorsement through Thorne HealthTech's NSF protocols commands premium price realization. |
| Algae-DHA Supply Partnership | Marine biotechnology supplier agreements insulate against harvest-condition volatility in DHA feedstock. |
| Near-Infrared Spectroscopy Deployment | Los Angeles-San Diego contract manufacturers compress quality hold times from weeks to hours. |
| Methylfolate Synthesis Investment | Quebec analytical chemistry talent pools validate 6S-5-methyltetrahydrofolate stability for premium tiers. |
| Pharmacy Telehealth Integration | California and New York digital health portals displace in-clinic dispensing for subscription conversion. |
Research Methodology
Bottom-up expectant mother demand modeling reconciled against top-down methylfolate and algae-DHA supply tracking forms the analytical core of this study. Primary interviews with obstetrician network managers, pharmacy benefit directors, contract manufacturing quality heads, and subscription-brand supply chain officers combined with secondary validation from FDA labeling guidance documents, Health Canada Natural and Non-prescription Health Products Directorate filings, and state Medicaid formulary databases. Triangulation across these sources ensures demand-side survey data aligns with production capacity and raw material procurement patterns.
Historical trendline analysis of vitamin and mineral formulation volumes, gummy format adoption curves, and channel-shift patterns informs the projection framework. Segmentation modeling spans product type, delivery form, distribution channel, and end-user purchasing authority across the analysis window. CAGRs derive from fitted growth curves adjusted for methylfolate synthesis capacity constraints and state-level reimbursement trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for biomarker-integrated personalization platforms would alter the outlook if MTHFR genetic testing penetration accelerates beyond current clinical integration rates. Forecasts reflect assumptions about FDA enforcement consistency and Health Canada cross-border harmonization progress. A small set of triggers—algae harvest failures, methylfolate batch contamination events, and state Medicaid coverage reversals—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Soy Isoflavones Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Propolis Market