
 DC Switchgear Market | 2026-2036
DC Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
DC Switchgear Market Intelligence
The replacement of sulfur hexafluoride (SF6) gas with environmentally friendly alternatives in high-voltage circuit breakers is consolidating product designs around vacuum and air-insulated technologies. Siemens leverages its extensive R&D in vacuum interrupter technology to capture this shift. Schneider Electric specializes in medium-voltage DC solutions for applications like data centers and telecommunication facilities. ABB dominates the high-voltage segment, particularly in traction power and utility-scale renewable projects.
DC switchgear comprises circuit breakers, fuses, and disconnectors designed to control and protect electrical equipment in direct current circuits. It operates by interrupting fault currents, preventing damage to assets like batteries, inverters, and motors. Demand from renewable power plants and data centers is driving the application segment. Within product types, solid-state solutions like Insulated Gate Bipolar Transistor (IGBT) switchgear are gaining share over traditional electromechanical designs due to faster switching speeds.
Compliance with International Electrotechnical Commission (IEC) standards, such as IEC 62271 for high-voltage switchgear, is mandatory for market access. In addition, regulations like the EU's F-Gas Regulation, which restricts SF6 use, and grid codes from entities like the US Federal Energy Regulatory Commission (FERC) influence component selection. Vendor selection will increasingly hinge on the ability to provide SF6-free solutions and digitally controlled switchgear for automated grid management.
Market Dynamics
The fundamental market dynamic is the concurrent push from decarbonization policies and the rapid expansion of DC-native infrastructure. Mandates like the EU Green Deal and China's dual carbon goals are accelerating renewable energy projects, while data center proliferation creates concentrated pockets of DC power demand.
Growth Catalysts
- Renewable Energy Targets:National commitments to decarbonization, such as Germany's Energiewende and India's renewable energy goals, necessitate the construction of utility-scale solar and wind farms, which rely on DC switchgear for efficient power collection and transmission.
- Data Center Expansion:The build-out of hyperscale data centers and telecommunication facilities to support cloud computing and 5G services creates substantial demand for medium-voltage DC switchgear to ensure power reliability and protect critical server equipment.
- Solid-State Technology:Advances in semiconductor-based devices like IGBTs are enabling faster, more reliable solid-state circuit breakers, improving performance over older electromechanical designs and encouraging adoption in sensitive applications like battery storage systems.
Market Restraints
- High Capital Cost:The initial investment for high-voltage DC (HVDC) and advanced solid-state switchgear is significantly higher than for conventional AC equipment, posing a barrier for projects with constrained budgets or in price-sensitive developing markets.
- Technical Complexity:Interrupting DC fault currents, which lack a natural zero-crossing point, presents a persistent engineering challenge, particularly at high voltages. This complexity can increase design costs and limit the reliability of certain switchgear types.
- Interoperability Standards:The absence of universally adopted standards for multi-vendor DC microgrids and charging infrastructures creates integration challenges, slowing deployment and increasing project risk for system integrators and asset owners.
Strategic Opportunities
- EV Charging Infrastructure:The global build-out of DC fast-charging stations for electric vehicles presents a significant greenfield opportunity for specialized, compact DC switchgear designed for public and commercial charging applications.
- SF6-Free Alternatives:Developing and marketing environmentally friendly switchgear that uses vacuum technology or alternative gas mixtures provides a clear path to differentiation, especially in markets with stringent environmental laws like the EU's F-Gas Regulation.
- Rural Electrification:Underpenetrated markets in regions like Sub-Saharan Africa and Southeast Asia offer long-term growth potential for medium-voltage DC switchgear as part of off-grid and microgrid projects designed to improve energy access.
Industry Challenges
- Specialized Skills Shortage:A deficit of engineers and technicians with deep expertise in high-voltage DC power systems and digital protection relay programming hinders the timely execution of complex projects and limits maintenance capabilities.
- Legacy System Integration:Integrating modern, digitally controlled DC switchgear into aging AC grid infrastructure is a complex and costly process, often requiring extensive retrofitting and custom engineering solutions that can cause project delays.
- Grid Code Compliance:Adherence to a fragmented landscape of national and regional grid codes, such as those issued by FERC in the US or various TSOs in Europe, complicates product design and certification, adding to development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC Switchgear Market |
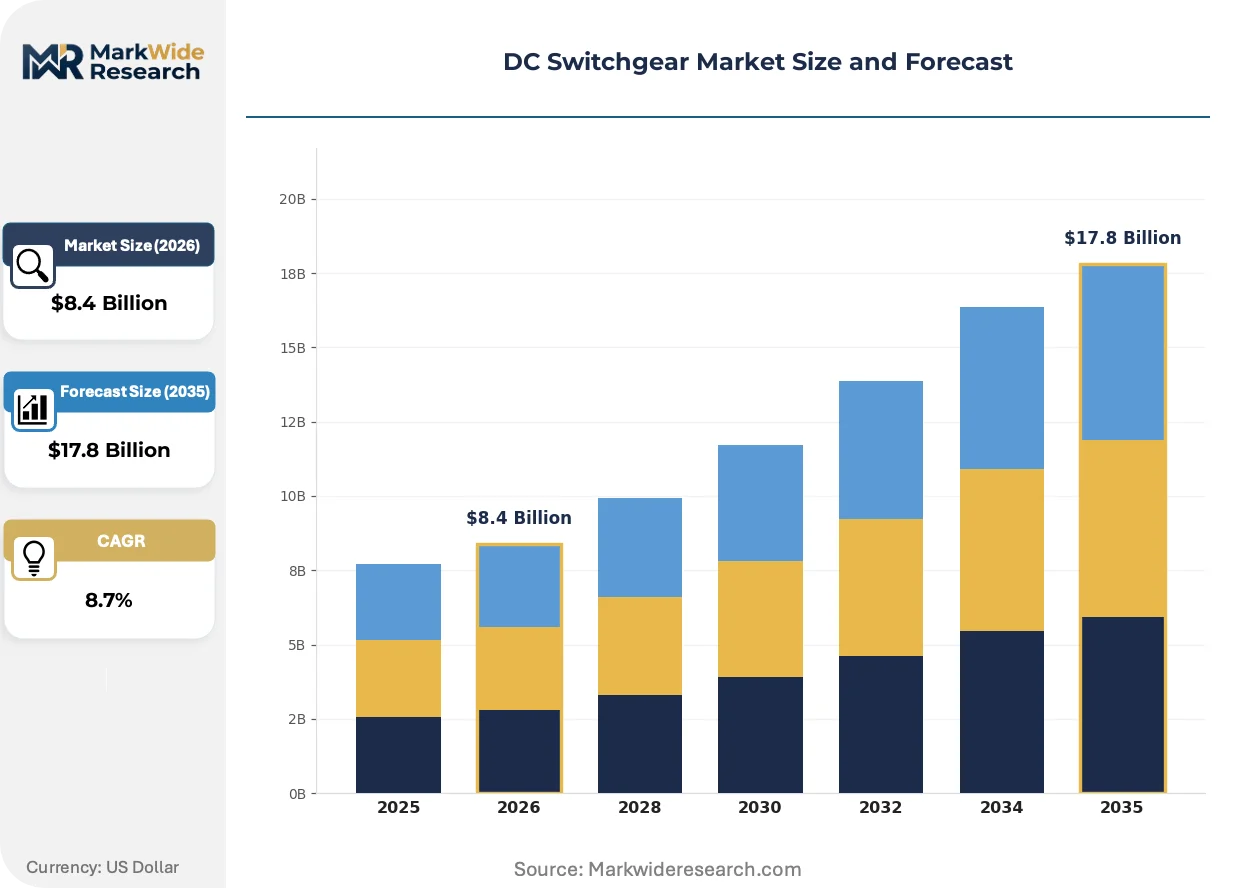
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Circuit Breaker, Vacuum Circuit Breaker, SF6 Circuit Breaker, Insulated Gate Bipolar Transistor, Hybrid Switchgear Technology: Electromechanical, Solid State, Magnetic, Hybrid, Digital Control Application: Renewable Power Plants, Data Centers, Traction Power, Telecommunication Facilities, Server Farms End User: Utility Providers, Telecommunication Operators, Rail Network Providers, Data Hosting Companies, Industrial Manufacturers |
| Companies Covered | ABB, Siemens, Eaton Corporation, Schneider Electric, General Electric, Hitachi Energy, Mitsubishi Electric Corporation, Sécheron, LS ELECTRIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC Switchgear Market Strategic Shifts & Innovations
Digitalization and environmental sustainability are the primary forces shaping product evolution. The shift away from SF6 gas is compelling a redesign of high-voltage circuit breakers, while the integration of digital controls is transforming switchgear from a simple protective device into an intelligent grid management asset.
Solid-state circuit breakers, which use Insulated Gate Bipolar Transistors (IGBTs), provide ultra-fast fault interruption without mechanical parts. Data centers and battery energy storage systems are adopting these devices to protect sensitive power electronics from damaging current surges. This technology is modularizing protection schemes, enabling scalable and reconfigurable DC microgrid designs that were impractical with slower electromechanical equipment.
The European Union's F-Gas Regulation imposes strict controls on the use of sulfur hexafluoride (SF6), a potent greenhouse gas common in high-voltage switchgear. This directive is compelling a market-wide pivot to alternative technologies, including vacuum interrupters and eco-friendly gas mixtures. Switchgear manufacturers targeting the European market must now demonstrate compliance and invest in SF6-free R&D to maintain market access.
End-users are increasingly specifying switchgear based on lifecycle performance and digital features, not just upfront capital cost. This behavioral shift favors vendors offering integrated solutions with predictive maintenance analytics and remote asset management capabilities. The trend is most pronounced in the procurement for utility-scale renewable power plants, where maximizing uptime is critical to financial performance.
DC Switchgear Market Segmentation
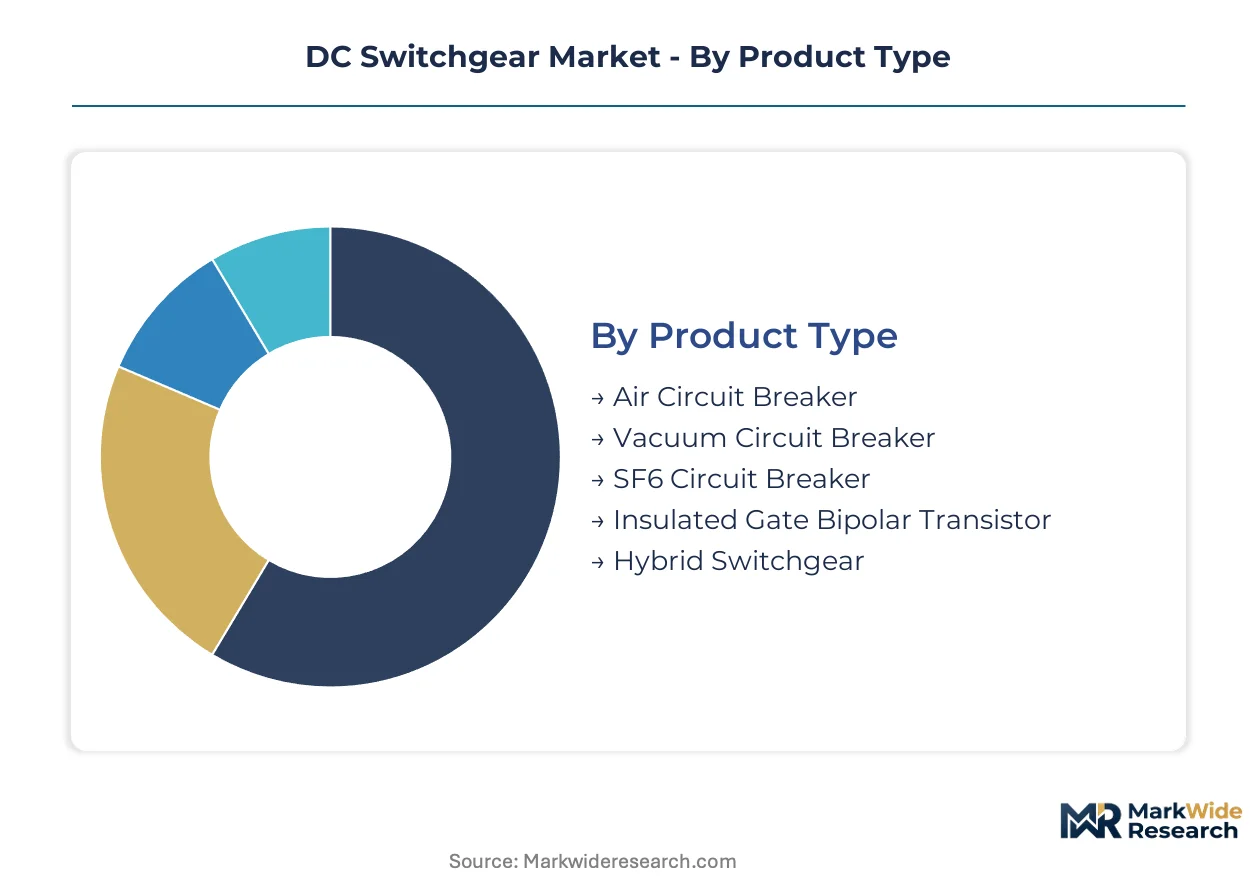
The DC switchgear market exhibits diverse segmentation, reflecting the varied technological requirements and application landscapes. Understanding these divisions is crucial for identifying areas of concentrated demand and emerging growth trajectories within the direct current power infrastructure.
Product Type:
The product type segmentation differentiates between high-volume, traditional solutions and premium, technologically advanced offerings.
- Insulated Gate Bipolar Transistor:These solid-state devices offer ultra-fast switching speeds by leveraging semiconductor technology. Demand is concentrating in data centers and battery energy storage systems, where sensitive power electronics require rapid fault interruption.
- Vacuum Circuit Breaker:These devices interrupt current in a sealed vacuum chamber, eliminating the need for SF6 gas. European markets are increasingly specifying vacuum technology due to stringent environmental regulations like the EU's F-Gas Regulation.
- Air Circuit Breaker:These traditional circuit breakers use air as the arc quenching medium, commonly found in low and medium-voltage applications.
- SF6 Circuit Breaker:These high-voltage devices use sulfur hexafluoride gas for insulation and arc quenching, but face replacement pressure due to environmental concerns.
- Hybrid Switchgear:This category combines features of different switchgear types, often integrating mechanical and solid-state components for optimized performance.
Today's leader: Vacuum Circuit Breaker. Tomorrow's challenger: Insulated Gate Bipolar Transistor.
Technology:
Technology segmentation highlights the varying cost tiers and performance capabilities available in the market.
- Solid State:This technology utilizes semiconductor components like IGBTs for rapid and precise current interruption without mechanical moving parts. Its adoption is accelerating in sensitive applications such as battery energy storage systems and data center power distribution.
- Digital Control:This involves integrating intelligent electronic devices and communication protocols for remote monitoring, diagnostics, and automated grid management. Utility providers and large-scale renewable power plants are increasingly specifying these features for enhanced operational efficiency.
- Electromechanical:These traditional designs rely on mechanical contacts and springs for current interruption, representing a mature but slower technology.
- Magnetic:This technology uses magnetic fields to extinguish arcs, offering an alternative to traditional mechanical or gas-insulated systems.
- Hybrid:This segment combines elements of both electromechanical and solid-state technologies to balance performance and cost.
Solid State technology represents the fastest-growing trajectory, while Digital Control is quickly gaining market share.
Application:
Application segmentation reveals where demand concentrates and how specific industries drive market expansion.
- Renewable Power Plants:This segment includes utility-scale solar and wind farms that require DC switchgear for efficient power collection, conversion, and transmission to the grid. National decarbonization policies, like Germany's Energiewende, drive significant investment in this area.
- Data Centers:These facilities demand reliable DC switchgear to manage power distribution, protect critical server equipment, and ensure continuous operation for cloud computing services. The build-out of hyperscale data centers creates substantial demand.
- Traction Power:This application covers railway electrification systems, where high-voltage DC switchgear is essential for powering trains and ensuring network reliability.
- Telecommunication Facilities:These sites use medium-voltage DC solutions to maintain power for critical infrastructure supporting 5G and other communication networks.
- Server Farms:These specialized data storage facilities utilize DC switchgear for efficient power delivery and protection of extensive computing hardware.
Renewable Power Plants and Data Centers collectively account for the largest share of market revenue.
End User:
End-user segmentation categorizes demand by distinct customer types, each with unique operational requirements.
- Utility Providers:These entities manage national and regional power grids, deploying DC switchgear for integrating renewable energy sources and upgrading transmission infrastructure. Grid modernization initiatives globally are driving their procurement decisions.
- Data Hosting Companies:These firms operate hyperscale data centers and cloud platforms, requiring advanced DC switchgear for power reliability and protection of high-density server racks. Their expansion directly fuels demand for specialized solutions.
- Telecommunication Operators:These companies invest in DC switchgear to power their extensive network infrastructure, including base stations and central offices.
- Rail Network Providers:These organizations deploy DC switchgear for traction substations and overhead lines to ensure safe and continuous operation of electric trains.
- Industrial Manufacturers:This sector uses DC switchgear for various industrial processes, motor control, and specialized equipment requiring direct current power.
Utility Providers represent a mature segment, while Data Hosting Companies exhibit rapid market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive high-voltage transmission infrastructure development anchors significant demand for DC switchgear. The expansion of renewable energy projects and data centers across key global economies drives regional market dynamics. Decarbonization policies and grid modernization initiatives further stimulate procurement.
China
China's extensive investments in high-voltage transmission infrastructure and telecommunication facilities generate substantial DC switchgear demand. The nation's dual carbon goals mandate increased renewable energy integration, requiring robust DC protection. Industrial hubs in the Yangtze River Delta are rapidly deploying advanced DC power solutions for grid modernization.
Germany
Germany's ambitious Energiewende initiative drives significant demand for DC switchgear in utility-scale solar and wind farms. The EU's F-Gas Regulation compels a market-wide shift to SF6-free vacuum interrupters for high-voltage applications. Bavaria's advanced manufacturing sector actively integrates DC switchgear for industrial processes and energy storage.
United States
United States hyperscale data centers and utility-scale renewable energy projects require reliable DC switchgear for power distribution. Federal Energy Regulatory Commission (FERC) grid codes influence component selection for grid integration and stability. Silicon Valley's tech giants lead in deploying advanced DC solutions for their expansive data center campuses.
India
India's ambitious renewable energy goals necessitate significant investment in DC switchgear for solar and wind power evacuation. The government's push for rural electrification and telecom expansion further stimulates demand for medium-voltage DC solutions. Karnataka's burgeoning IT sector and industrial parks adopt DC switchgear for reliable power infrastructure.
DC Switchgear Market Key Industry Players
Global majors compete with regional champions across technology innovation and market access. The DC switchgear market exhibits a tiered structure, with established players dominating high-voltage segments and specialized firms focusing on niche applications. Strategic archetypes include integrated power solution providers and component-focused manufacturers. Portfolio diversification and geographic expansion represent dominant competitive moves among market participants.
Integrated power solution providers like ABB and Siemens exemplify comprehensive offerings across high-voltage and medium-voltage segments. These European-based entities leverage extensive R&D in vacuum interrupter technology and advanced digital controls. Schneider Electric, another European firm, occupies a position specializing in medium-voltage DC solutions for data centers and telecommunication facilities. These companies anchor market development through their broad product portfolios and global presence, addressing diverse application requirements from utility-scale projects to critical infrastructure.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Eaton Corporation |
| Schneider Electric |
| General Electric |
| Hitachi Energy |
| Mitsubishi Electric Corporation |
| Sécheron |
| LS ELECTRIC |
| Others |
Cost & Logistics Intelligence
Semiconductor component costs, driven by global chip demand, directly influence the pricing of advanced solid-state DC switchgear, impacting premium solution tiers for data centers and renewable energy projects.
Pricing Analysis
Input-cost pass-through is evident in the DC switchgear market, particularly for specialized components like IGBTs and vacuum interrupters. The dominant pricing model combines project-based contracts for large installations with per-unit transactional sales for standard components. Price differentiation stems from compliance with SF6-free regulations and the integration of advanced digital control features. Pricing softness runs through traditional electromechanical designs due to increased competition, while utility providers and data hosting companies exhibit lower price sensitivity for mission-critical applications than rural electrification projects.
Supply Chain Analysis
Logistics and freight costs significantly influence the global distribution of DC switchgear components and finished products, with supply concentration centering on China for high-volume manufacturing, Germany for advanced SF6-free technologies, and Japan for specialized semiconductor components. The market draws from critical raw materials like copper and rare earth elements, alongside advanced semiconductor wafers. A structural risk exists in single-source vulnerability for specialized IGBTs, impacting lead times for solid-state solutions. Distribution runs through direct sales channels for utility providers and hyperscale data centers, complemented by a network of specialized channel partners for smaller industrial and telecommunication projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DC switchgear market functions as a regulatory compounder, with demand significantly amplified by mandates like the EU's F-Gas Regulation. This directive compels a market-wide pivot towards environmentally friendly SF6-free solutions, reshaping product development and procurement.
For Market Incumbents: Acquire specialized solid-state technology firms to counter the threat of faster, more efficient solid-state solutions displacing traditional electromechanical designs. Incumbents like ABB and Siemens should also deepen vertical integration into advanced vacuum interrupter manufacturing to secure supply chains for SF6-free products. This strategic lever mitigates margin pressure from rising component costs and ensures compliance with evolving environmental regulations like the EU Green Deal. Consolidate market share in high-voltage segments through strategic partnerships.
For New Entrants and Emerging Players: The EU's F-Gas Regulation in Europe opens a window for new entrants specializing in SF6-free medium-voltage DC switchgear. Target the rapidly expanding EV charging infrastructure segment, particularly compact solutions for fast-charging stations, which represents a penetrable application. Develop modular, digitally controlled microgrid solutions for rural electrification projects in Sub-Saharan Africa, offering a clear go-to-market angle through partnerships with local energy developers. Focus on interoperability standards for multi-vendor environments.
For Investors and Strategic Acquirers: Consolidation pressure builds where technical complexity and high capital costs create barriers to entry for specialized DC switchgear. The long-term viability of this market, over the next 5-10 years, favors firms with robust R&D in solid-state and SF6-free technologies. Target mid-cap specialists with strong intellectual property in digital control and predictive maintenance analytics. A signal to watch is the acceleration of grid code harmonization across major economies, indicating reduced integration risks and broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand SF6-Free Product Portfolio | Addresses stringent environmental regulations like the EU F-Gas Regulation and growing sustainability demands. |
| Invest in Solid-State Technology R&D | Captures demand from data centers and battery storage systems for ultra-fast fault interruption capabilities. |
| Develop Advanced Digital Control Modules | Enables utility providers to implement automated grid management and predictive maintenance analytics. |
| Target EV Charging Infrastructure Solutions | Capitalizes on the significant greenfield opportunity presented by the global build-out of fast-charging stations. |
| Form Strategic Microgrid Integration Partnerships | Addresses interoperability challenges and expands market reach into underserved rural electrification projects. |
Research Approach
Coverage spans China, Germany, and the United States, with primary inputs from each region informing this analysis. This includes combining insights from interviews with utility planning officers, data center architects, and R&D directors at switchgear manufacturers, validated by secondary sources. These secondary sources comprise IEC standards documents, FERC filings, and national energy agency reports. Bottom-up market sizing and top-down validation ensure robust data triangulation across all segments.
Rate-of-change decomposition analyzes historical trends and projects future market dynamics across the analysis window. The analytical framework models segmentation by product type (e.g., IGBT, vacuum circuit breaker), application (e.g., renewable power plants, data centers), and voltage class. Compound Annual Growth Rates were derived from an assessment of technological adoption curves and regulatory impact. Forecast inputs include projected renewable energy capacity additions and data center infrastructure investment.
Revisions become necessary when significant shifts in energy policy or technological breakthroughs in DC protection materialize. Forecasts reflect underlying assumptions regarding regulatory stability and infrastructure development. Geopolitical tensions impacting raw material supply chains present a specific risk factor. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Molded Case Circuit Breaker Market
Switches
Global High Voltage Switchgear Market
Switches
North America Low Voltage Switchgear Market
Switches
Smart Pole-Mounted Switch Market
Switches
ASEAN Switchgear Market
Switches
Pressure Switch Market
Switches
India Switchgear Market
Switches
Hazardous Location Limit Switches Market
Switches
Rocker Switch Market
Switches
Residual Current Circuit Breaker Market
Switches
Smart Dimmer Switch Market
Switches
North America Switchgear Market
Switches
Low Voltage Disconnect Switch Market
Switches
Proximity Switches Market
Switches
Oil Level Switches Market
Switches
Canada Switch Gear Market