
 Beet Pulp Market | 2026-2036
Beet Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Beet Pulp Market Outlook
Pet food producers is unwinding the traditional livestock farmer dominance in beet pulp procurement as premium pet diets incorporate dried fiber sources. Südzucker AG leverages its integrated sugar-to-pulp infrastructure across Central Europe to sustain supply continuity for animal nutrition customers. Tereos Group anchors its competitive stance through molassed beet pulp specialization, while Ontario Dehy Inc. competes on geographic proximity to North American dairy corridors.
Beet pulp consists of the fibrous residue remaining after sugar extraction from sugar beets, typically containing 8-10% residual sugar and 18-22% crude fiber on a dry matter basis, and serves primarily as a digestible fiber source in ruminant and equine rations. Dried beet pulp dominates volume flows due to its extended shelf stability and ease of bulk transport, though pelleted beet pulp commands margin premiums by reducing dust and improving handling efficiency. Molassed beet pulp occupies a distinct value tier where palatability enhancement justifies price spreads in performance livestock and pet food formulations.
The EU Green Deal and F-Gas Regulation shape beet pulp trajectory by incentivizing biomass valorization pathways that compete with traditional feed disposal, while the USDA's biomass crop assistance framework influences North American processor investment decisions. REACH compliance requirements in Europe and FDA feed ingredient standards in the United States create divergent compliance burdens that fragment market access protocols. Stakeholders must track regulatory arbitrage opportunities between jurisdictions where carbon accounting rules differentially reward agricultural residue utilization.
Market Dynamics
The EU Green Deal's biomass valorization mandates are redirecting sugar industry residue streams away from low-margin disposal routes toward higher-value feed and industrial applications, compressing traditional supply availability for livestock customers.
Growth Catalysts
- EU Green Deal biomass targets:Mandatory agricultural residue utilization quotas are pulling beet pulp into certified circular economy pathways, creating structured demand from bioplastics compounders.
- Dairy cattle nutrition science:Fiber digestibility research from German and Dutch universities is embedding beet pulp in high-performance rations for lactating herds.
- Pet food premiumization:North American and European pet food formulators are specifying dried beet pulp for digestive health positioning in super-premium dry diets.
Market Restraints
- Sugar beet harvest volatility:Weather-driven yield fluctuations in France and Poland create raw material uncertainty that propagates through pulp supply contracts.
- Competing biomass valorization:Anaerobic digestion subsidies under Germany's EEG framework divert beet pulp toward biogas production, constraining feed-grade availability.
- Protein meal substitution:Soy hulls and dried distillers grains from US ethanol plants offer comparable fiber profiles at freight-advantaged prices to coastal European buyers.
Strategic Opportunities
- Bioplastics feedstock certification:REACH-compliant traceability systems enable beet pulp entry into polyhydroxyalkanoate supply chains for food-contact applications.
- Equine nutrition expansion:Professional horse training facilities in Kentucky and Newmarket are adopting molassed beet pulp for controlled-release energy formulations.
- Direct-to-farm digital channels:Platform-based procurement systems are disintermediating traditional agricultural merchant networks for mid-sized dairy operations.
Industry Challenges
- Moisture calibration expertise:Drying operation optimization requires specialized process engineers scarce in regional sugar processing facilities.
- Multi-jurisdiction feed registration:FDA feed ingredient notifications, EFSA additive authorizations, and national veterinary registrations create overlapping compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beet Pulp Market |
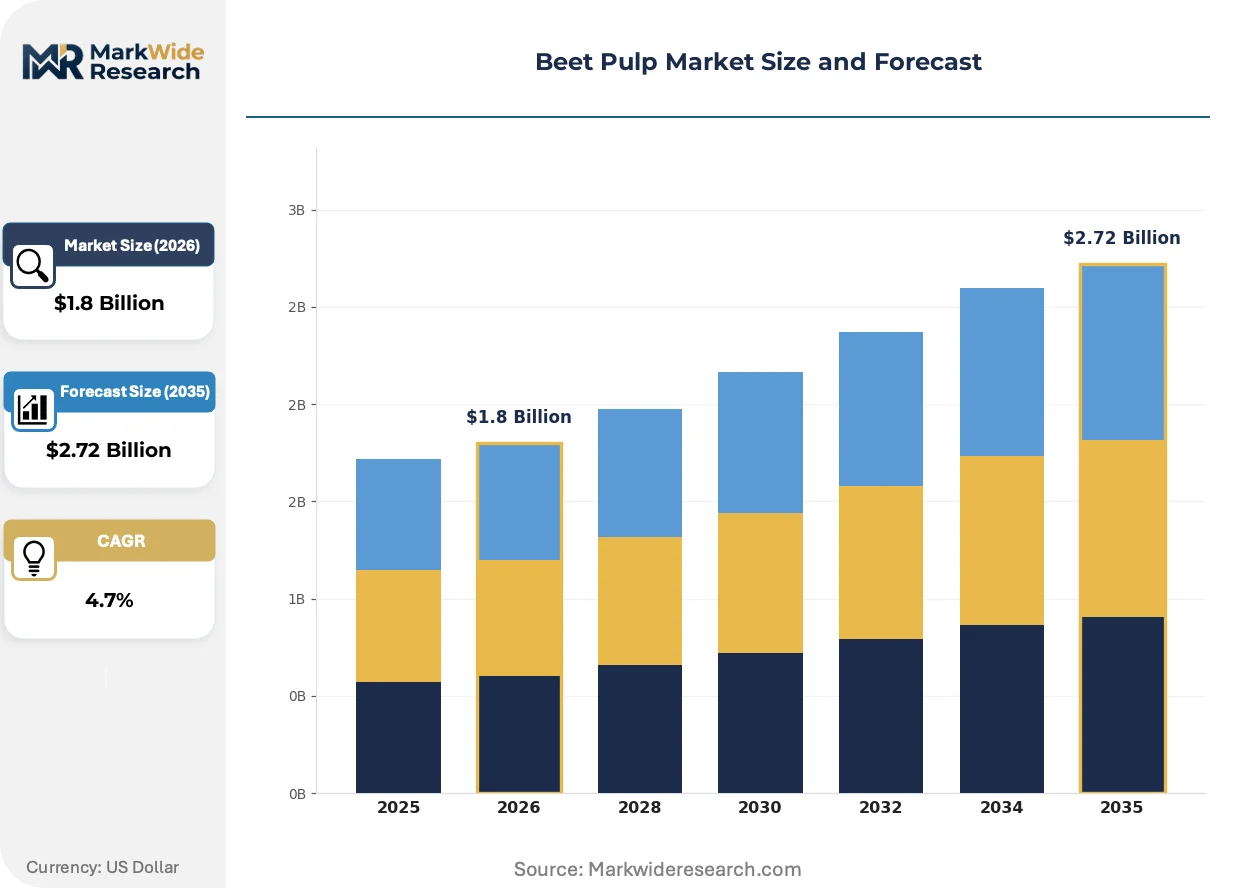
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Beet Pulp, Dried Beet Pulp, Pelleted Beet Pulp, Molassed Beet Pulp Application: Animal Feed, Food Industry, Nutraceuticals, Bioplastics End User: Livestock Farmers, Food Manufacturers, Pet Food Producers, Nutraceutical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Supermarkets |
| Companies Covered | Amalgamated Sugar, Tereos Group, Südzucker AG, British Sugar, American Crystal Sugar, Nordzucker, Michigan Sugar, Cosun Beet Company, Ontario Dehy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beet Pulp Market Strategic Shifts
Processing technology maturation and regulatory carbon-accounting precision are bifurcating beet pulp value chains into commodity feed streams and specialty biomaterial precursors.
Near-infrared spectroscopy for real-time moisture and residual sugar measurement is fragmenting quality assurance protocols across the industry. Large-scale processors in Germany and France are deploying inline NIR systems to replace batch laboratory testing. This capability compression is enabling spot-market trading of certified specification lots that previously required bilateral supply agreements.
The EU F-Gas Regulation's phase-down schedules are accelerating refrigeration plant retrofits that indirectly affect beet pulp economics. Sugar factories replacing hydrofluorocarbon cooling systems face capital allocation tradeoffs that delay pulp drying capacity expansions. Eastern European processors with older thermal infrastructure are most exposed to this compliance-driven investment sequencing.
Consolidation among North American dairy cooperatives is compressing supplier negotiation cycles from annual to quarterly terms. Large procurement consortia in Wisconsin and California are unbundling ingredient sourcing from nutrition advisory services, forcing beet pulp merchants to compete on specification transparency rather than technical support relationships. This pattern is most pronounced in regions where cooperative processing capacity exceeds 500,000 head equivalents.
Beet Pulp Market Segmentation
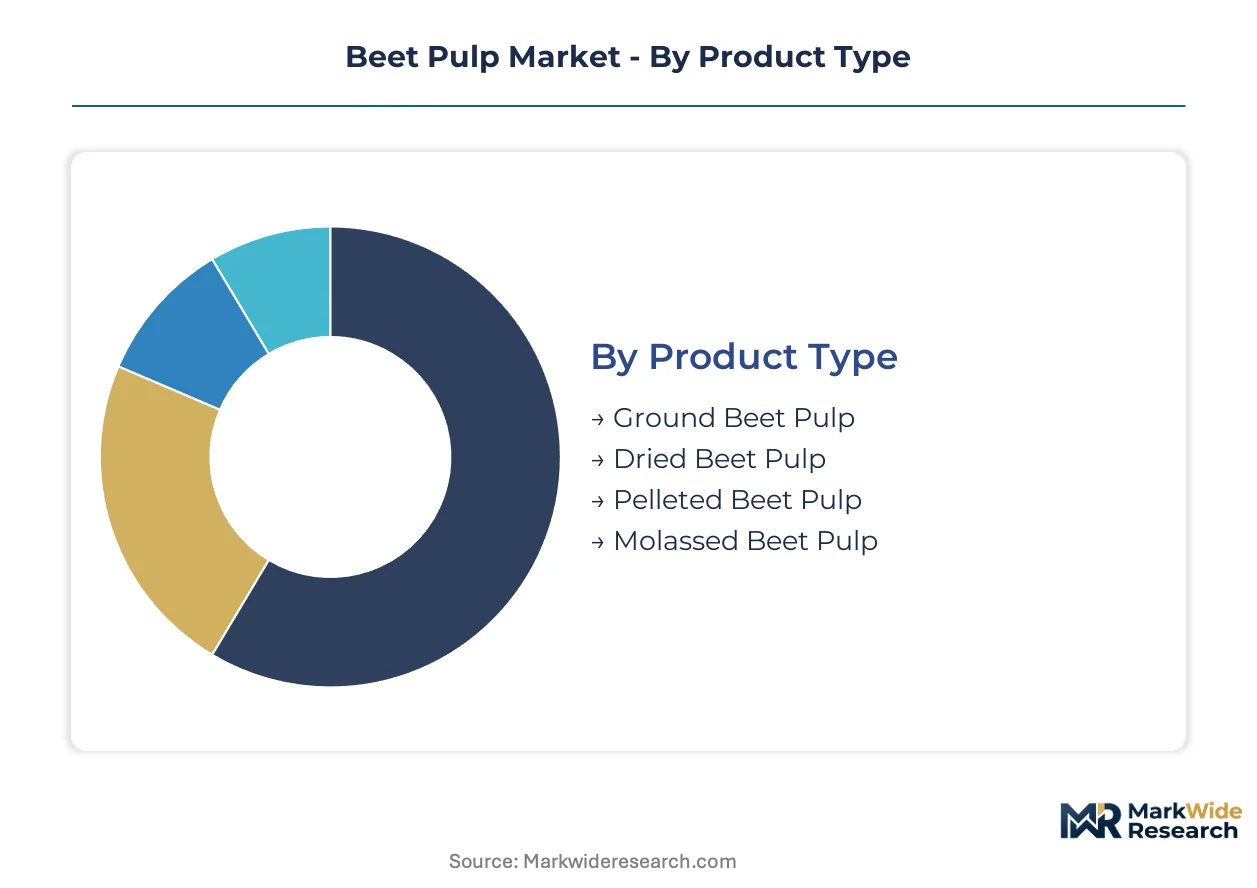
Beet pulp flows through distinct value tiers shaped by processing intensity and moisture content, with channel economics determining where each product form captures margin. Understanding these segment boundaries reveals where supply constraints and demand premiums concentrate across the value chain.
Product Type:
Channel mix varies sharply by physical form: dried and pelleted grades move through agricultural distributors and direct sales to livestock operations, while molassed variants reach pet food formulators through specialized feed ingredient merchants.
- Dried Beet Pulp:Contains 8-10% residual sugar and 18-22% crude fiber on a dry matter basis, produced through rotary drum or flash drying systems. Demand concentrates in German and Dutch dairy corridors where nutritionists specify digestible fiber for high-producing lactating herds constrained by rumen acidosis risk.
- Molassed Beet Pulp:Palatability-enhanced through surface application of cane or beet molasses, commanding margin premiums in performance livestock and premium pet food formulations. Kentucky and Newmarket equine training facilities are adopting this grade for controlled-release energy in competition horse rations.
- Pelleted Beet Pulp:Densified through mechanical compression to reduce dust and improve handling efficiency; flows through bulk handling infrastructure serving large dairy cooperatives.
- Ground Beet Pulp:Coarse-milled for on-farm mixing flexibility; preferred by smaller livestock operations with limited storage capacity.
By volume, dried beet pulp leads. By growth pace, molassed beet pulp is expanding most quickly.
Application:
Cost tier stratification separates commodity feed applications from certified biomaterial pathways, with bioplastics commanding specification premiums that justify traceability investments.
- Animal Feed:Dominant value capture channel serving ruminant and equine nutrition; fiber digestibility research from German universities is embedding beet pulp in high-performance dairy rations.
- Bioplastics:Emerging high-margin pathway where REACH-compliant traceability enables entry into polyhydroxyalkanoate supply chains for food-contact applications; EU Green Deal biomass targets are pulling material into certified circular economy streams.
- Food Industry:Limited current penetration; fiber enrichment applications in processed foods face formulation compatibility constraints.
- Nutraceuticals:Niche segment exploring prebiotic fiber positioning; regulatory authorization timelines under EFSA additive frameworks delay commercial scale-up.
Animal feed commands current volume. Bioplastics demonstrates the steepest expansion trajectory.
End User:
Customer type determines procurement rhythm: livestock farmers negotiate annual supply agreements, while pet food producers operate on quarterly specification cycles with unbundled ingredient sourcing.
- Livestock Farmers:Traditional demand anchor in dairy cattle operations; Wisconsin and California cooperative procurement consortia are compressing supplier negotiation cycles from annual to quarterly terms.
- Pet Food Producers:North American and European formulators specifying dried beet pulp for digestive health positioning in super-premium dry diets; unwinding traditional livestock farmer dominance in procurement.
- Food Manufacturers:Minimal current offtake; fiber enrichment applications require additional processing to meet food-grade specifications.
- Nutraceutical Companies:Early-stage demand exploring prebiotic claims; FDA feed ingredient notifications and EFSA additive authorizations create overlapping compliance timelines.
Livestock farmers retain volume leadership. Pet food producers are gaining share fastest.
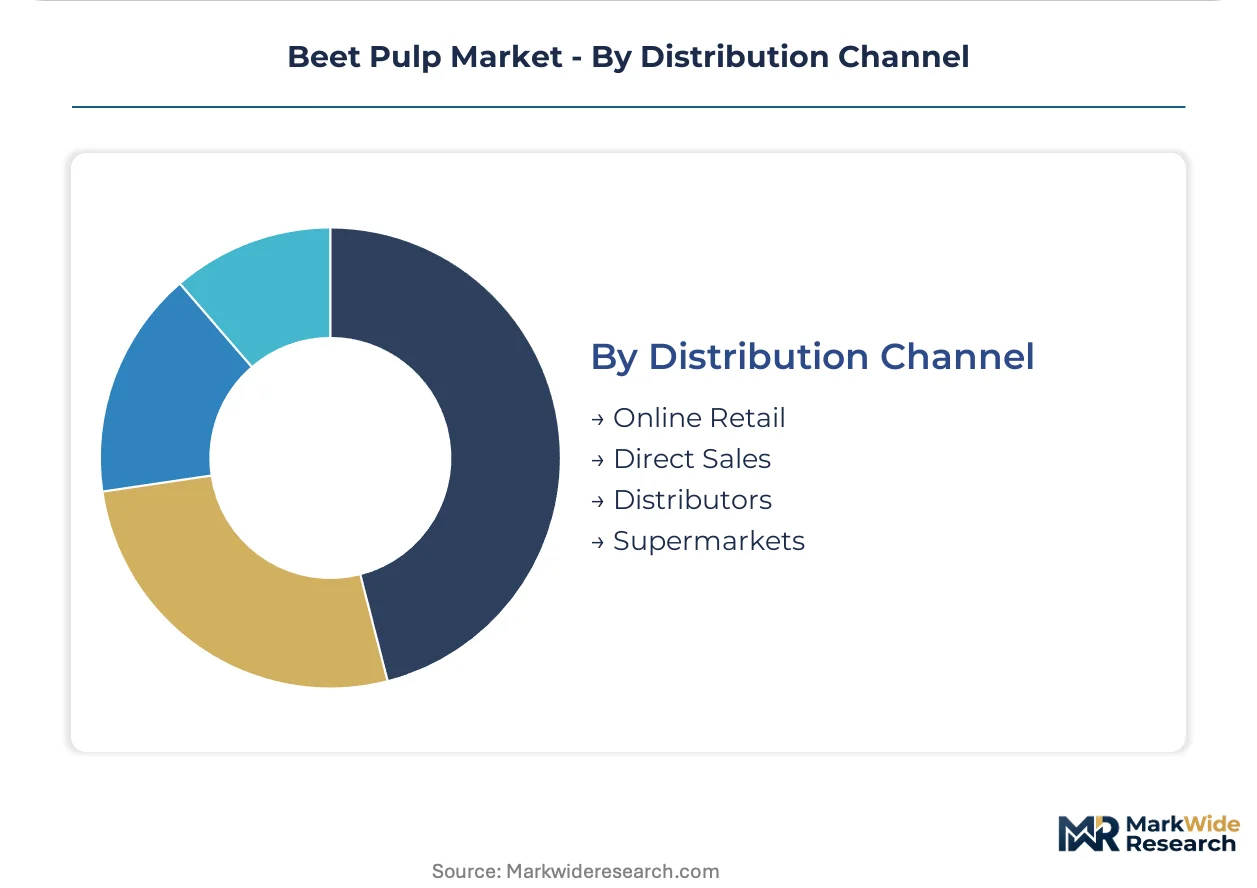
Distribution Channel:
Supply concentration in integrated sugar processing networks favors direct sales and distributor relationships, with platform-based procurement emerging for mid-sized dairy operations.
- Distributors:Agricultural merchant networks handling bulk dried and pelleted grades; Südzucker AG and Nordzucker leverage integrated sugar-to-pulp infrastructure to sustain supply continuity.
- Direct Sales:Large dairy cooperatives and bioplastics compounders sourcing certified specification lots; near-infrared spectroscopy deployment is enabling spot-market trading previously requiring bilateral agreements.
- Online Retail:Limited penetration; small-scale equine and hobby farm customers purchasing bagged molassed products.
- Supermarkets:Negligible current presence; consumer packaged goods positioning remains underdeveloped.
Distributors handle greatest volume. Direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sugar processors dominate export flows, shipping dried beet pulp through Rotterdam to North American dairy corridors and molassed grades to UK equine markets.
Germany
EU Green Deal biomass quotas pull beet pulp into certified circular economy pathways for bioplastics compounders. The EEG framework subsidizes anaerobic digestion, diverting some feed-grade material toward biogas production. Lower Saxony and Bavaria host integrated sugar-to-pulp processing networks serving livestock and industrial customers.
United States
Wisconsin and California dairy cooperatives compress supplier negotiation cycles from annual to quarterly terms. USDA biomass crop assistance frameworks influence processor investment decisions in beet belt states. Michigan and Minnesota sugar beet regions supply dried pulp to Midwest dairy corridors through direct sales channels.
France
Weather-driven yield fluctuations in sugar beet harvests create raw material uncertainty propagating through pulp supply contracts. REACH compliance requirements shape traceability investments for biomaterial pathways. The Champagne-Ardenne and Picardy clusters anchor processing capacity for domestic dairy and export markets.
United Kingdom
Newmarket equine training facilities adopt molassed beet pulp for controlled-release energy formulations in competition horse rations. British Sugar operates integrated processing serving domestic livestock and pet food customers. East Anglia concentrates beet growing and pulp drying infrastructure.
Netherlands
Rotterdam bulk handling infrastructure facilitates transshipment of German and French dried pulp to Atlantic buyers. Dutch universities generate fiber digestibility research embedding beet pulp in high-performance dairy rations. The Port of Rotterdam serves as the primary logistics hub for EU beet pulp export flows.
Beet Pulp Market Competitive Environment
Player mix skews toward integrated sugar processors with captive pulp streams. Three to five vertically integrated European cooperatives control majority volume. Strategic archetypes separate at integrated sugar-to-pulp processors, standalone drying specialists, and regional agricultural merchants. Dominant competitive moves include backward integration into sugar beet sourcing and geographic proximity plays to dairy corridors.
Among integrated European processors, Südzucker AG, Tereos Group, and Nordzucker occupy positions defined by captive supply infrastructure and multi-country processing footprints. Südzucker AG exemplifies the integrated archetype through Central European sugar-to-pulp networks. Tereos Group represents molassed beet pulp specialization. Nordzucker anchors northern European supply continuity. North American presence concentrates in Amalgamated Sugar and American Crystal Sugar, which sit within regional beet belt processing clusters.
| Leading Market Players |
|---|
| Amalgamated Sugar |
| Tereos Group |
| Südzucker AG |
| British Sugar |
| American Crystal Sugar |
| Nordzucker |
| Michigan Sugar |
| Cosun Beet Company |
| Ontario Dehy Inc. |
| Others |
Value Chain & Pricing Dynamics
Rotary drum drying capacity utilization in Lower Saxony and Bavaria processing clusters shapes both supply concentration and price floors for German beet pulp exports. Südzucker AG and Nordzucker leverage scale economies to compress unit drying costs below Eastern European competitors, establishing floor prices that marginal operators cannot match without EU Green Deal biomass subsidy offsets.
Pricing Analysis
Prior-generation flash drying systems command discount tiers against rotary drum installations with inline near-infrared spectroscopy, while next-generation pelletized and molassed variants capture premium spreads. Contract-based long-term offtake dominates, with price differentiation resting on residual sugar certification and REACH-compliant traceability for bioplastics pathways. Cost compression in standard dried grades is intensifying because anaerobic digestion subsidies under Germany's EEG framework divert feedstock toward biogas. Livestock farmers exhibit highest price sensitivity, while pet food producers accept specification premiums for palatability-enhanced molassed grades.
Supply Chain Analysis
Strategic stockpile preferences dominate livestock procurement, with Wisconsin and California dairy cooperatives maintaining 60-90 day dried pulp inventories against harvest volatility. Supply concentrates in Germany, France, and the United States, with raw material dependencies on sugar beet harvests, natural gas for thermal drying, and molasses surface coatings. Single-source vulnerability runs through integrated sugar-to-pulp processors controlling 70% of European capacity. Distribution runs through agricultural merchant networks for bulk dried grades and direct sales channels for certified biomaterial lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beet pulp sits in early-cycle expansion as EU Green Deal biomass quotas redirect sugar industry residue streams from disposal routes toward certified circular economy pathways. Penetration into bioplastics feedstock and premium pet nutrition remains underdeveloped relative to addressable demand.
For Market Incumbents: Consolidate backward integration into sugar beet sourcing contracts in Poland and France to hedge weather-driven yield volatility threatening pulp supply continuity. Capture channel control through platform-based procurement systems disintermediating traditional agricultural merchants serving mid-sized dairy operations.
For New Entrants and Emerging Players: Lead with equine nutrition specialization targeting Kentucky and Newmarket training facilities adopting molassed beet pulp for controlled-release energy formulations. The most penetrable white-space sits in direct-to-farm digital channels for North American hobby farms and small-scale livestock operations bypassing cooperative procurement consortia.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with captive sugar-to-pulp infrastructure and multi-country processing footprints serving both feed and industrial customers. Long-term viability favors integrated operators with REACH-compliant traceability systems enabling bioplastics pathway entry. The signal to watch is anaerobic digestion subsidy rate adjustments under Germany's EEG framework diverting feed-grade material availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugar Beet Sourcing | Captive raw material supply from Champagne-Ardenne growing regions insulates against harvest volatility. |
| Molassed Product Line Expansion | Palatability-enhanced grades command margin premiums in Kentucky equine nutrition markets. |
| REACH-Compliant Traceability Investment | Certification enables entry into polyhydroxyalkanoate supply chains for food-contact bioplastics. |
| Direct-to-Farm Digital Platform Launch | Disintermediation of agricultural merchant networks captures mid-sized dairy procurement volume. |
| Inline NIR Spectroscopy Deployment | Real-time moisture measurement enables spot-market trading previously requiring bilateral agreements. |
Study Parameters
Initial hypotheses were tested against primary input from sugar processing plant managers, dairy nutritionists at Wisconsin cooperative consortia, pet food formulation scientists, and bioplastics compounders, then refined through secondary validation. Sources included EU customs trade data, EFSA additive authorization filings, USDA biomass crop assistance program disclosures, and SEC 10-K filings from integrated processors. Bottom-up volume estimates from regional sugar beet processing capacity were triangulated against top-down demand projections from livestock and pet food consumption trends.
Variance decomposition across the projection horizon isolates drivers by product form, application pathway, and end-user procurement rhythm. Segmentation dimensions modeled include physical processing intensity, certification grade tier, and geographic production cluster. CAGRs were derived from installed drying capacity expansion schedules and substitution elasticity estimates for soy hulls and dried distillers grains. Forecast inputs incorporated EEG subsidy rate trajectories and F-Gas Regulation compliance investment sequencing affecting capital allocation tradeoffs.
Forecasts assume regulatory continuity in EU Green Deal biomass quotas and Germany's EEG framework; material policy shifts would require re-modeling supply availability for feed-grade versus biogas diversion. Revision becomes warranted when anaerobic digestion subsidy rates cross thresholds that structurally redirect beet pulp flows from livestock nutrition toward energy recovery pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Boswellia Market