
 Organic Soymeal Market | 2026-2036
Organic Soymeal Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Soymeal Market Outlook
Capital-intensity divergence between integrated crushers and toll processors is redrawing competitive boundaries in organic soymeal. Vantage Organic Foods leverages backward integration into certified organic soybean origination across North American growing regions. Nordic Soya anchors its position through proximity to Baltic Sea port infrastructure serving Scandinavian dairy cooperatives. South Dakota Soybean Processors sustains volume leadership via dedicated organic crush lines that minimize commingling risk.
Organic soymeal is the protein-rich coproduct of mechanical or solvent extraction from certified organic soybeans, typically containing 44-48% crude protein and residual oil below 2% for de-hulled grades; it serves as the primary vegetable protein input in formulated feeds and meat alternatives requiring non-GMO, pesticide-free traceability. De-hulled soymeal dominates value capture due to premium pricing in aquaculture and layer hen diets, while texturized variants represent the fastest-growing format as European meat substitute manufacturers scale extrusion capacity. Human nutrition applications command margin pools above commodity feed channels, though volume remains concentrated in specialized retail and direct-procurement contracts.
USDA National Organic Program standards govern crop certification and handling continuity, while EU Organic Regulation 2018/848 enforces third-country equivalency for import access. Brazil's MAPA organic seal and India's APEDA organic certification create parallel compliance tracks for export-oriented crushers. Stakeholders must monitor evolving deforestation due diligence rules in the EU and emerging state-level organic feed mandates in the United States.
Market Dynamics
EU Organic Regulation 2018/848 third-country equivalency requirements are forcing North American crushers to restructure origination and handling protocols, compressing supply timelines and elevating compliance costs for cross-Atlantic trade.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:Binding reduction targets for synthetic pesticide residues in feed chains are redirecting poultry integrator procurement toward certified organic protein sources. German layer operations now specify organic soymeal in contracted volumes.
- Scandinavian dairy cooperatives:Baltic Sea port infrastructure enables just-in-time delivery of deforestation-free certified meal to ruminant feed formulators. Danish and Swedish processors report binding multi-year supply agreements.
- Mechanical pressing technology:Cold-press extraction preserves amino acid profiles for aquaculture diets, commanding premium placement in salmonid feed formulations. Norwegian farmers specify pressed meal over solvent-extracted alternatives.
Market Restraints
- Organic soybean input volatility:Premium spreads over conventional beans fluctuate with weather-driven yield variance in North American growing regions, compressing crusher margins unpredictably.
- Certification timeline friction:USDA National Organic Program transition periods require 36 months for land qualification, throttling supply elasticity when demand spikes.
- Textured wheat gluten substitution:European meat substitute manufacturers increasingly blend alternative plant proteins, capping soymeal share in extruded analog formulations.
Strategic Opportunities
- Indian APEDA organic certification track:Export-oriented crushers can access EU equivalency through India's parallel compliance framework, diversifying origination beyond North and South American supply bases.
- Human nutrition channel expansion:Specialized retail and direct-procurement contracts for organic protein isolates command margin pools above commodity feed channels, though volumes remain constrained.
- State-level organic feed mandates:Emerging US state regulations for organic livestock operations create captive demand pools requiring certified deforestation-free protein sourcing.
Industry Challenges
- Commingling risk mitigation:Dedicated organic crush lines require substantial capital deployment for equipment segregation and cleaning protocols, elevating break-even thresholds for toll processors.
- Traceability system integration:Blockchain and mass-balance documentation platforms must interface with legacy ERP systems at cooperative elevators, creating implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Soymeal Market |
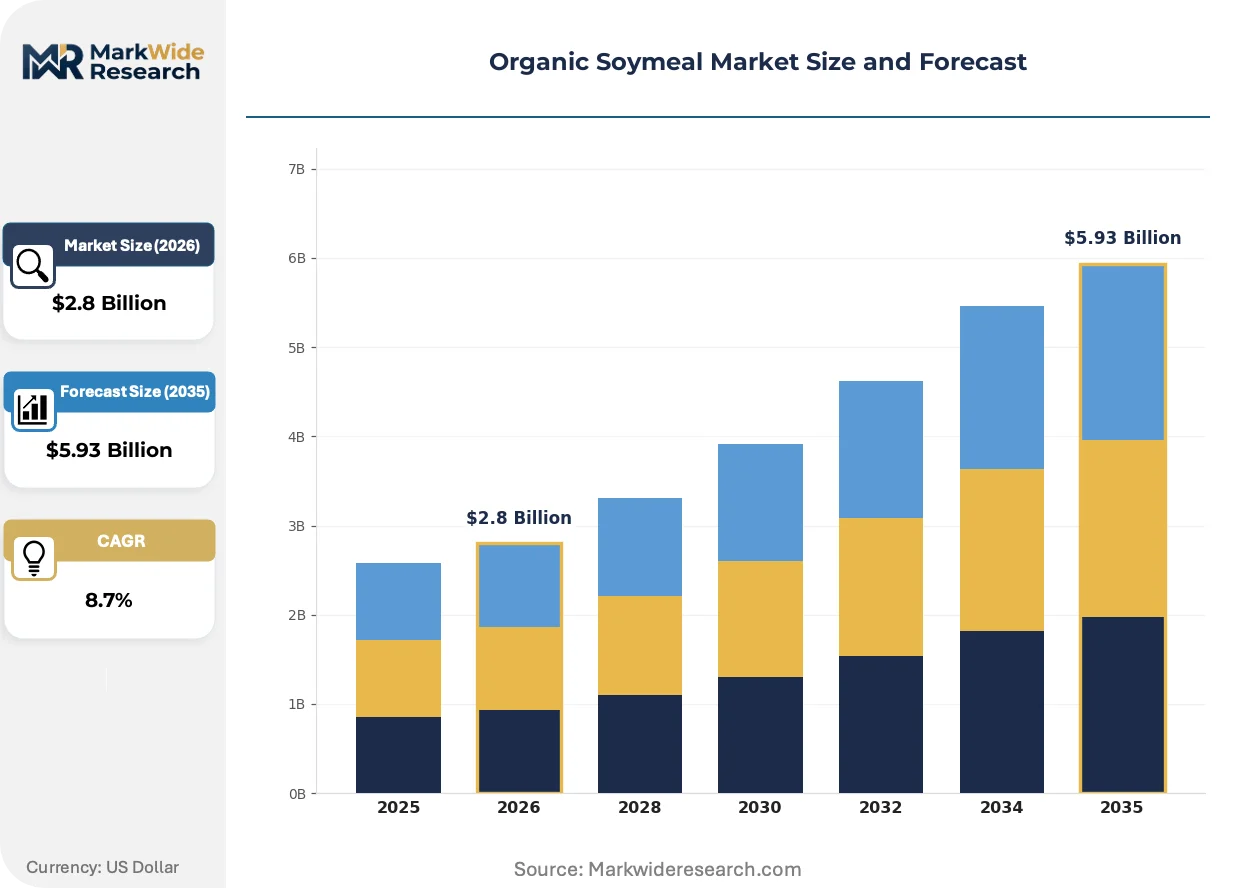
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: De-hulled, Whole, Texturized, Flour End Use: Animal Feed, Human Nutrition, Food Products, Bakery Distribution Channel: Online, Supermarkets, Specialized Retailers, Wholesale Packaging Type: Bags, Bulk Containers, Totes, Pouches |
| Companies Covered | Vantage Organic Foods, Nordic Soya, South Dakota Soybean Processors, Manat Group, Satavie, Sapthsathi Organic Agriculture Project, SVF Soya, Patanjali Foods Ltd., AFG Brasil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Soymeal Market Strategic Shifts
Processing technology convergence with digital traceability platforms is restructuring how organic soymeal moves from field to formulation, compressing verification cycles and enabling premium capture.
Near-infrared spectroscopy coupled with blockchain verification is decomposing traditional paper-based organic chain-of-custody documentation. Layer hen feed formulators in the Netherlands and Denmark now require real-time compositional data and origin verification. This technology compression is collapsing audit timelines from weeks to hours while enabling dynamic premium pricing based on verified protein content and deforestation-free status.
EU deforestation due diligence rules scheduled for full enforcement are mandating geolocation-linked supply mapping for all imported organic feed materials. Crushers must document plot-level coordinates for every soybean entering certified streams. Baltic Sea port terminals serving Scandinavian markets are investing in satellite verification infrastructure to maintain access to EU dairy cooperative contracts.
Direct-procurement contracting between organic poultry integrators and certified crushers is displacing spot market purchases. German and French layer operations now negotiate multi-year volume agreements with fixed organic premiums, transferring price risk upstream while securing supply continuity. This relationship compression is most visible in northern European markets where farm-to-fork traceability commands retail shelf placement.
Organic Soymeal Market Segmentation
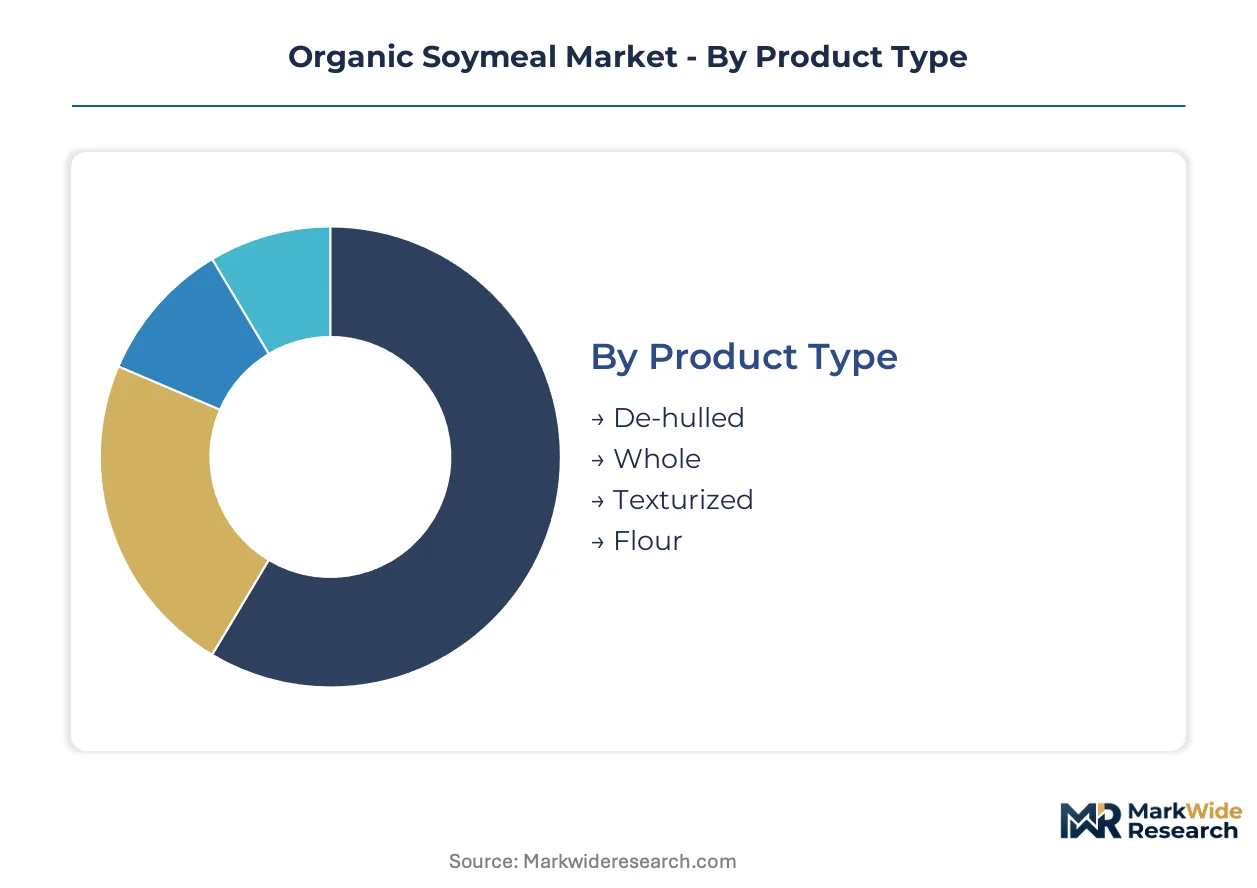
Organic soymeal segmentation reflects divergent supply chain requirements across feed and food channels. Certification standards, handling protocols, and customer specifications create distinct commercial corridors that processors must navigate simultaneously.
Product Type:
Geographic concentration varies sharply by processing format, with de-hulled grades dominating EU import flows while texturized variants serve domestic European extrusion capacity.
- De-hulled:Mechanical removal of hulls yields 47-49% protein content with residual oil below 1.5%, meeting aquaculture and layer hen specifications. German and Dutch feed formulators specify de-hulled for salmonid and organic poultry diets, paying premiums for verified deforestation-free origination. Cold-press extraction variants command additional margin in Norwegian aquaculture contracts.
- Texturized:Extrusion processing creates fibrous structure for meat analog applications. European meat substitute manufacturers in Germany and France scale dedicated extrusion lines, sourcing texturized soymeal for hybrid protein formulations. This segment gains share fastest as plant-based retail shelf space expands.
- Whole:Unprocessed meal retains hull fractions with 44% protein and higher fiber content. Ruminant feed operations in Denmark and Sweden accept whole grades for cost-sensitive dairy rations.
- Flour:Finely milled meal serves human nutrition applications including protein fortification and gluten-free baking. Specialized retail channels in Germany and Austria source organic soymeal flour for direct consumer sales.
De-hulled holds the largest share; momentum sits with texturized.
End Use:
Margin structures diverge dramatically between commodity feed channels and specialized food applications, with certification depth determining pricing power.
- Animal Feed:Poultry integrators and aquaculture operations absorb the majority of organic soymeal volume. EU Green Deal mandates bind German layer operations to certified organic protein sourcing, creating structural demand growth. Dairy cooperatives in Scandinavia specify Baltic Sea port delivery for just-in-time ruminant formulation.
- Human Nutrition:Protein isolates and specialized retail products command margin pools above commodity channels. Direct-procurement contracts with health food distributors in Germany and Austria constrain volume but sustain premium capture.
- Food Products:Meat analog manufacturers blend texturized soymeal with alternative proteins. French and German extrusion facilities report binding multi-year supply agreements.
- Bakery:Organic soymeal flour fortifies gluten-free and high-protein baked goods. Austrian and German artisan bakeries represent a niche but stable demand pool.
Animal Feed generates dominant volume; Human Nutrition captures superior margins.
Distribution Channel:
Channel selection tracks customer scale and certification verification requirements, with large integrators bypassing traditional wholesale structures.
- Wholesale:Bulk shipments to feed mills and food manufacturers concentrate through Baltic Sea and North Sea port terminals. Danish and Swedish dairy cooperatives procure via cooperative wholesale structures with embedded traceability.
- Specialized Retailers:Health food stores and organic cooperatives in Germany and Austria serve small-scale human nutrition buyers. These channels require packaged formats with full organic chain-of-custody documentation.
- Online:Direct-to-processor platforms emerge for mid-scale poultry operations seeking transparent pricing. German layer farms increasingly source through digital procurement channels.
- Supermarkets:Limited penetration for bulk soymeal; retail presence concentrates in consumer-packaged flour and protein products. Austrian supermarket chains stock organic soymeal flour for home baking segments.
Wholesale channels move the greatest tonnage; specialized retailers sustain premium realization.
Packaging Type:
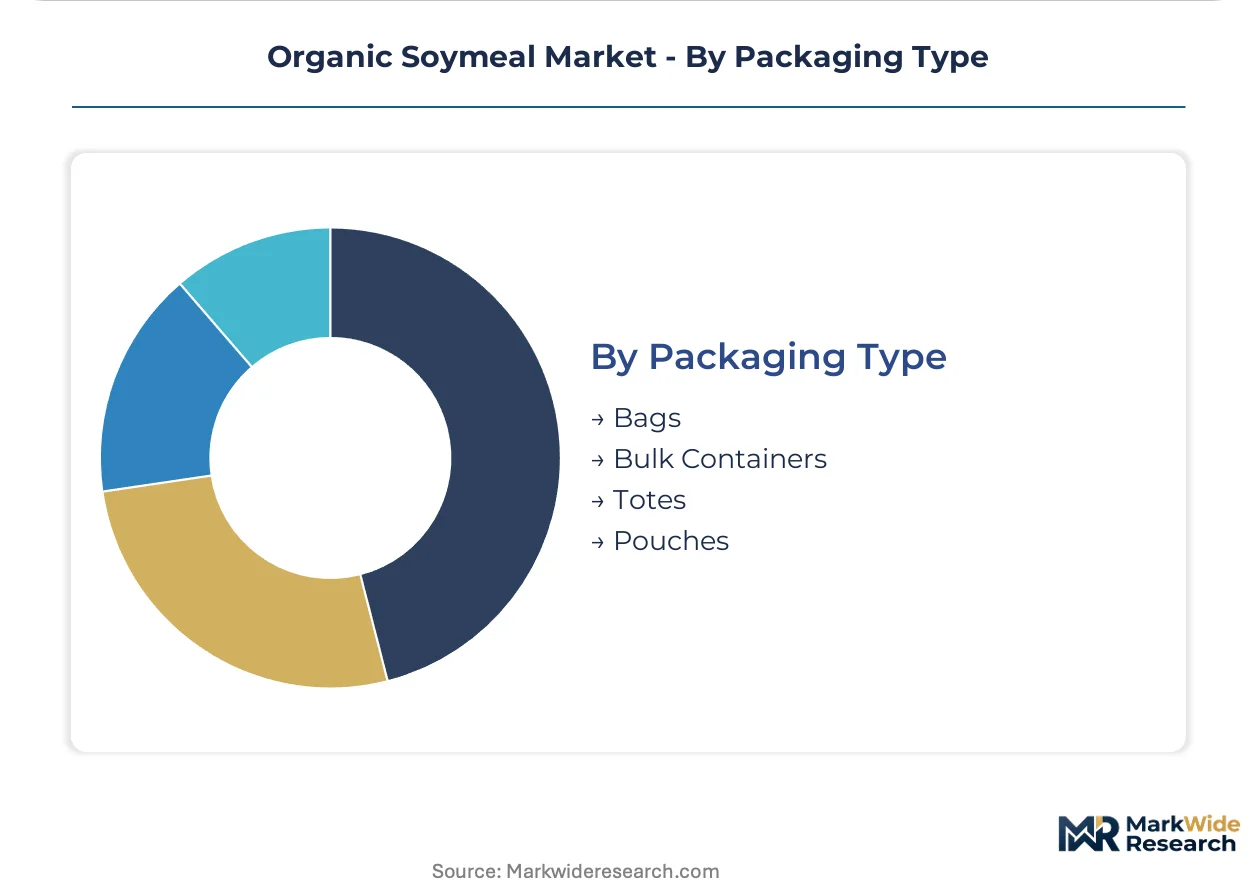
Packaging selection reflects handling infrastructure at destination and contamination risk protocols for organic certification maintenance.
- Bulk Containers:Ocean freight and rail movements to major crush facilities and feed mills utilize bulk handling. Port terminals at Hamburg and Rotterdam maintain dedicated organic bulk infrastructure.
- Bags:25-50kg woven polypropylene sacks serve mid-scale feed formulators and food manufacturers. German and Dutch layer operations specify bagged delivery for on-farm storage.
- Totes:Intermediate bulk containers bridge bulk and bagged formats for specialty processors. Scandinavian dairy cooperatives favor totes for flexible ruminant feed blending.
- Pouches:Consumer retail formats dominate human nutrition and bakery channels. Austrian and German health food retailers stock pouch-packaged organic soymeal flour.
Bulk containers handle peak volume; pouches deliver highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German feed formulators command premium pricing power over Baltic Sea suppliers, while North American crushers absorb compliance cost compression from EU third-country equivalency mandates.
Germany
Layer hen operations in Lower Saxony and North Rhine-Westphalia specify certified organic soymeal under EU Green Deal farm-to-fork procurement rules. The Federal Office for Agriculture and Food enforces deforestation-free documentation for all imported feed proteins. Hamburg port terminals maintain dedicated organic bulk infrastructure serving Dutch and Danish cross-border demand.
United States
South Dakota and Minnesota crush facilities supply poultry integrators scaling organic livestock operations under emerging state-level feed mandates. USDA National Organic Program standards govern 36-month land transition protocols that throttle supply elasticity. Pacific Northwest exporters face compressed timelines meeting EU Organic Regulation 2018/848 equivalency requirements.
Denmark
Danish dairy cooperatives procure Baltic Sea deliveries for just-in-time ruminant feed formulation. The Danish Veterinary and Food Administration enforces pesticide residue thresholds that redirect sourcing toward certified organic channels. Aarhus and Copenhagen processing clusters report binding multi-year supply agreements with Swedish cross-border buyers.
Brazil
MAPA organic seal holders in Rio Grande do Sul and Paraná position for EU market access through equivalency negotiations. The Ministry of Agriculture mandates geolocation documentation for deforestation compliance. Santos port operators invest in satellite verification infrastructure to maintain European dairy cooperative contracts.
India
APEDA-certified crushers in Maharashtra and Gujarat diversify origination options for EU-bound organic protein. The Agricultural and Processed Food Products Export Development Authority operates a parallel compliance track for third-country equivalency. Mumbai and Kandla port facilities serve as alternative supply nodes reducing North American concentration risk.
Organic Soymeal Market Competitive Environment
Concentration sits with backward-integrated crushers controlling certified organic origination networks. North American and European processors dominate volume leadership through dedicated segregation infrastructure that mitigates commingling risk. Two strategic archetypes define competitive positioning: integrated originator-crushers with captive supply chains, and toll processors dependent on third-party bean procurement. Dominant competitive moves include capacity expansion in Baltic Sea port zones and strategic partnerships with poultry integrators for multi-year offtake agreements.
Within the integrated crusher tier, Vantage Organic Foods exemplifies backward integration into certified organic soybean origination across North American growing regions. Nordic Soya anchors Scandinavian supply through proximity to Baltic Sea port infrastructure. South Dakota Soybean Processors occupies a position as a volume leader via dedicated organic crush lines that minimize cross-contamination exposure.
| Leading Market Players |
|---|
| Vantage Organic Foods |
| Nordic Soya |
| South Dakota Soybean Processors |
| Manat Group |
| Satavie |
| Sapthsathi Organic Agriculture Project |
| SVF Soya |
| Patanjali Foods Ltd. |
| AFG Brasil |
| Others |
Value Chain & Pricing Dynamics
Ninety-day EU third-country equivalency verification timelines compress procurement windows for Baltic Sea deliveries, concentrating pricing power with Hamburg and Rotterdam terminal operators who control certified organic bulk infrastructure. This lead-time rigidity amplifies premium capture for de-hulled grades serving German layer operations while squeezing toll processors dependent on spot organic bean markets.
Pricing Analysis
The customization-premium spread between cold-pressed aquaculture grades and standard solvent-extracted feed tiers widens with certification depth. Contract-based long-term offtake agreements dominate, with de-hulled variants commanding placement above whole grades due to protein content verification and deforestation-free documentation. Price differentiation hinges on EU Organic Regulation 2018/848 equivalency status and mechanical pressing technology. Margins are tightening for toll processors facing organic soybean input volatility. Small-scale Scandinavian dairy cooperatives exhibit highest price sensitivity; Norwegian salmonid feed formulators show least.
Supply Chain Analysis
Baltic Sea port congestion and container availability constraints on the North Atlantic trade lane elevate inbound logistics costs for EU-bound organic soymeal. Supply concentrates in the United States, Brazil, and India, with origination drawing from certified organic soybean cultivation in the Upper Midwest, Rio Grande do Sul, and Maharashtra. Inputs hinge on organic seed stock, mechanical crush equipment, and mass-balance documentation systems. Single-source vulnerability persists where crushers lack diversified origination. Distribution runs through cooperative wholesale structures serving Danish and Swedish dairy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic soymeal markets track cyclical recovery patterns tied to EU Green Deal implementation phases, with farm-to-fork mandate enforcement creating predictable demand pulses for certified protein sourcing.
For Market Incumbents: Fortify dedicated organic crush line capacity in Baltic Sea port zones to capture Scandinavian dairy cooperative volume. Deepen backward integration into certified organic soybean origination across North American growing regions to mitigate input volatility. Invest in blockchain-mass-balance traceability platforms before EU deforestation due diligence full enforcement. For New Entrants and Emerging Players: Mid-scale poultry integrator under-service in emerging US state-level organic feed mandate jurisdictions offers white-space entry. Target direct-procurement contracting gaps where German layer operations seek transparent pricing outside incumbent cooperative structures. Pursue APEDA certification track access for EU equivalency diversification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural conglomerates with underutilized organic crush assets and dormant certification infrastructure. Long-term viability centers on processors controlling both origination networks and port-adjacent processing capacity. Monitor EU deforestation regulation enforcement timing as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Origination | Vantage Organic Foods secures captive organic soybean supply across Upper Midwest growing regions. |
| Baltic Sea Port Capacity Expansion | Nordic Soya anchors Scandinavian dairy cooperative contracts through Rotterdam-adjacent infrastructure. |
| Blockchain Traceability Platform Deployment | Danish layer operations now require real-time compositional data for premium tier placement. |
| APADA Certification Track Diversification | Indian crushers access EU equivalency parallel compliance reducing North American concentration. |
| Direct-Procurement Contracting Shift | German poultry integrators displace spot purchases with multi-year volume agreements. |
Study Parameters
The analysis maps organic soymeal processing formats, certification compliance tracks, and end-use channels, each validated through primary interviews with crush facility operators, organic certification auditors, feed formulation executives, and Baltic Sea port terminal managers. Secondary sources include USDA National Organic Program filings, EU Organic Regulation 2018/848 equivalency documentation, APEDA export records, and customs trade data. Bottom-up volume modeling triangulates against top-down protein demand estimates.
Consistency checks validated volume and value outputs against organic livestock operation scaling data and EU Green Deal procurement mandate implementation timelines. The analytical framework segments by processing technology, protein grade tier, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from organic poultry integrator contract growth trajectories and aquaculture feed formulation substitution rates for certified deforestation-free protein.
Forecasts assume regulatory continuity in EU Organic Regulation 2018/848 enforcement and USDA National Organic Program standards; material policy shifts in deforestation due diligence or state-level organic feed mandates would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Consumer Floriculture Market