
 China Compound Feed Market | 2026-2036
China Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
China Compound Feed Market Outlook
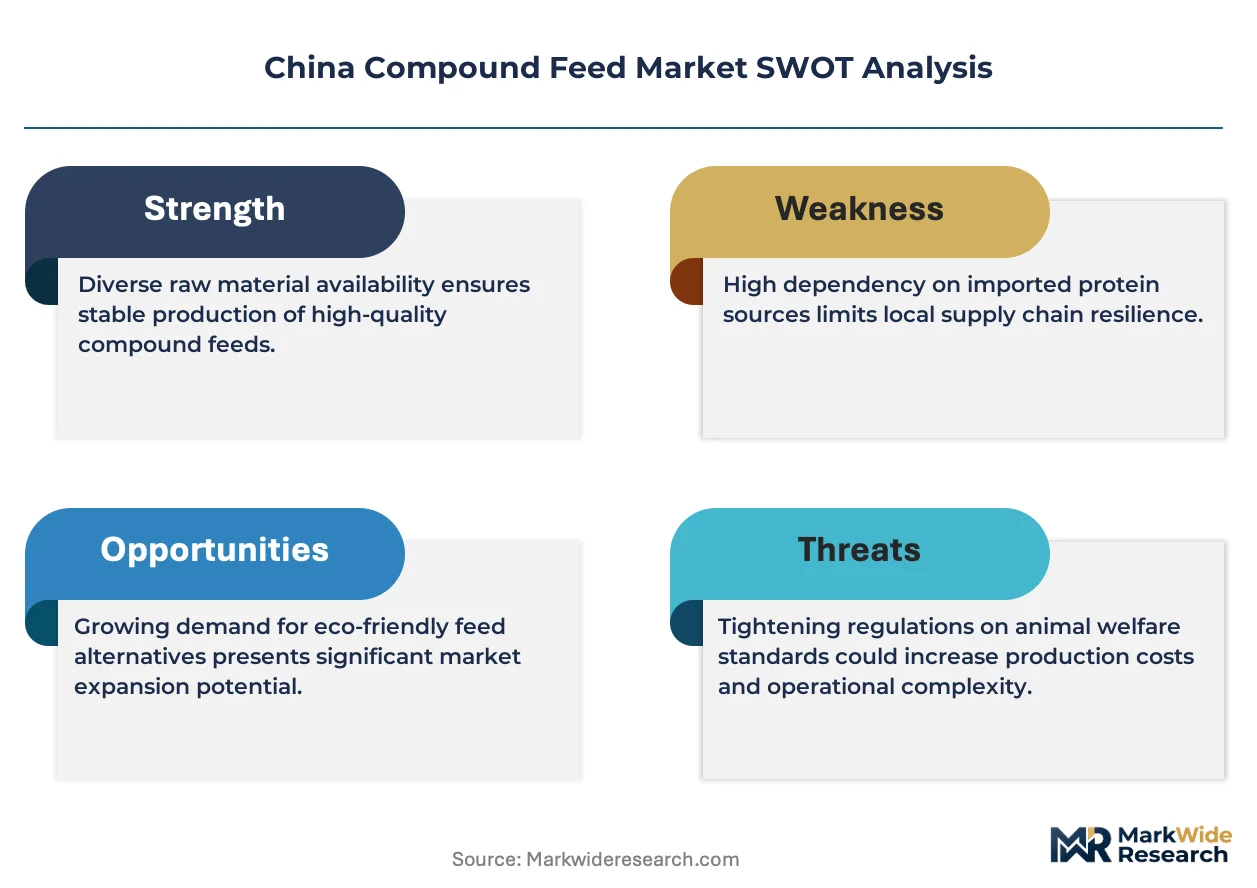
Provincial feed mill capacity in Shandong and Henan is shifting toward higher-output facilities with automated batching and pelleting lines. New Hope Group leverages backward integration into poultry breeding and processing to secure captive offtake for its compound feed output. Wen's Foodstuff Group anchors its position through company-owned farm networks across southern China that consume feed at scale. Haid Group specializes in aquaculture nutrition, sustaining R&D intensity for species-specific formulations that command premium positioning.
Compound feed refers to manufactured mixtures of grains, protein meals, vitamins, and minerals formulated to deliver complete nutritional profiles for livestock and farmed fish, typically processed through grinding, mixing, conditioning, and pelleting to achieve standardized digestibility and shelf stability. Pelleted feed dominates volume due to reduced waste and improved feed conversion ratios in confined operations, while liquid feed gains traction in automated swine finishing systems. Corn and soybean meal anchor ingredient formulations, though wheat substitution is accelerating in northern provinces where local grain supply shortens logistics loops.
SAMR enforces feed labeling and additive standards under national GB codes, while MEE oversight of livestock waste discharge shapes formulation choices toward lower-nitrogen excretion profiles. China's dual carbon goals pressure mills to audit energy use in drying and extrusion stages, favoring facilities with captive biogas recovery. Stakeholders must monitor how provincial feed safety inspections and carbon intensity benchmarks reshape capital allocation between legacy mill upgrades and greenfield builds.
Market Dynamics
SAMR's tightening antibiotic residue limits under revised GB standards are forcing mills to reformulate around enzyme-based and probiotic additives, compressing legacy product lines while opening premium positioning for compliant nutrition systems.
Growth Catalysts
- Intensive aquaculture expansion:Shrimp and finfish operations in Guangdong and Fujian provinces are scaling feed offtake as pond density rises and export certification requirements harden.
- Dual carbon goals pressure:Provincial energy audits favor mills with captive biogas recovery from anaerobic digesters, accelerating capital flow toward greenfield builds with integrated waste-to-energy systems.
- Yangtze River Delta clustering:Integrated pork and poultry operations concentrate near Nanjing and Shanghai processing hubs, shortening feed-to-slaughter logistics loops and locking in volume contracts.
Market Restraints
- Input cost volatility:Corn and soybean meal price swings squeeze formulation margins, forcing mills toward wheat substitution in northern provinces where local grain supply dampens transport exposure.
- Regulatory friction:MEE livestock waste discharge standards impose lower-nitrogen excretion profiles that conflict with traditional high-protein formulations, requiring costly R&D pivots.
- Supply concentration risk:Automated batching and pelleting equipment depends on German and Danish engineering suppliers, exposing capacity expansion timelines to import clearance bottlenecks.
Strategic Opportunities
- Species-specific aquaculture nutrition:Premium formulations for high-value marine species remain underpenetrated in Fujian coastal zones, rewarding R&D intensity with margin expansion.
- Automated swine finishing systems:Liquid feed delivery technology converges with precision livestock farming sensors, enabling real-time consumption monitoring that cuts waste.
- Central China greenfield positioning:Henan's emerging high-output mill clusters access shorter wheat supply chains while serving pork belt demand radiating from Zhengzhou logistics nodes.
Industry Challenges
- Formulation talent scarcity:Mills struggle to recruit nutritionists fluent in enzyme-based additive interactions and probiotic stability under variable storage conditions.
- Legacy system integration:Automated lines require retrofitting older conditioning and extrusion stages, creating downtime risk during peak seasonal demand windows.
- Certification timeline compression:SAMR feed safety inspection cycles are shortening, forcing quality control teams to accelerate documentation throughput without headcount expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Compound Feed Market |
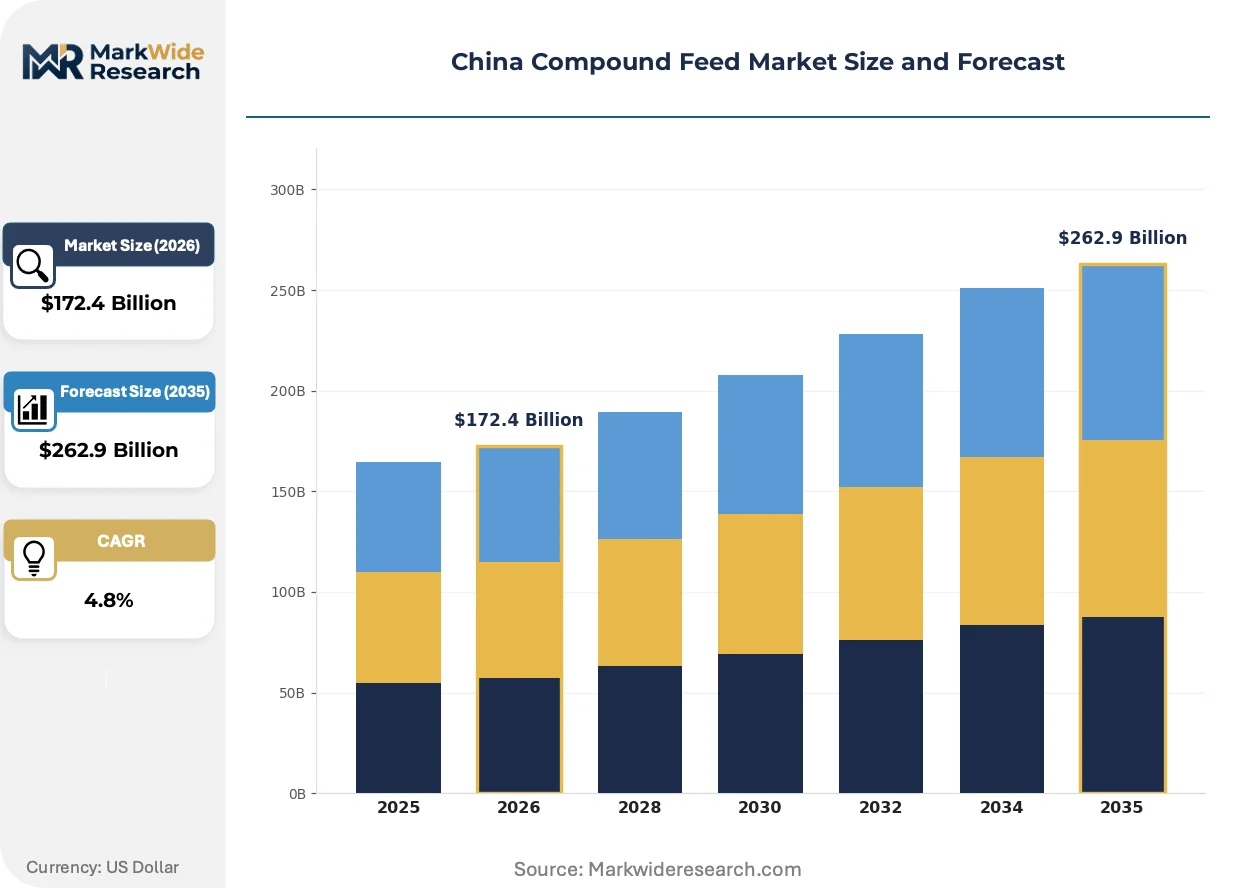
| Market Size in 2026 | $172.4 Billion |
| Market Size in 2035 | $262.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pelleted Feed, Crumbled Feed, Mash Feed, Liquid Feed Ingredient Type: Corn, Soybean Meal, Wheat, Barley Animal Type: Poultry, Ruminants, Swine, Aquaculture Distribution Channel: Online Retail, Traditional Retail, Direct Sales, Distributors |
| Companies Covered | New Hope Group, Wen’s Foodstuff Group, CP Group, Haid Group, Tongwei Group, Zhengda International Group, Wellhope Agri-Tech, Shandong Backbone Group, Cargill Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Compound Feed Market Strategic Shifts
Formulation science is pivoting from commodity grain blends toward functional additive systems that modulate gut microbiota and nitrogen excretion, compressing the competitive gap between volume players and nutrition specialists.
Enzyme-based feed additives are overtaking traditional antibiotic growth promoters in commercial swine and poultry rations. Large integrators in Shandong and Sichuan are adopting phytase and protease cocktails at scale to meet export residue standards. This transition is compressing margins for mills slow to secure enzyme supplier partnerships and technical service capabilities.
MEE oversight of livestock waste discharge is hardening nitrogen and phosphorus emission caps that cascade into formulation mandates. Mills must now model excretion profiles during recipe development, not merely nutrient density. Southern coastal provinces with dense aquaculture zones face the steepest compliance curves, accelerating demand for precision nutrition software.
Integrated pork and poultry operators are consolidating procurement decisions at the corporate level, displacing decentralized mill relationships. Wen's Foodstuff and New Hope Group centralize feed sourcing across company-owned farm networks, extracting volume discounts and formulation co-development rights. This concentration is most visible in Guangdong, where captive offtake agreements now cover over half of commercial feed volume.
China Compound Feed Market Segmentation
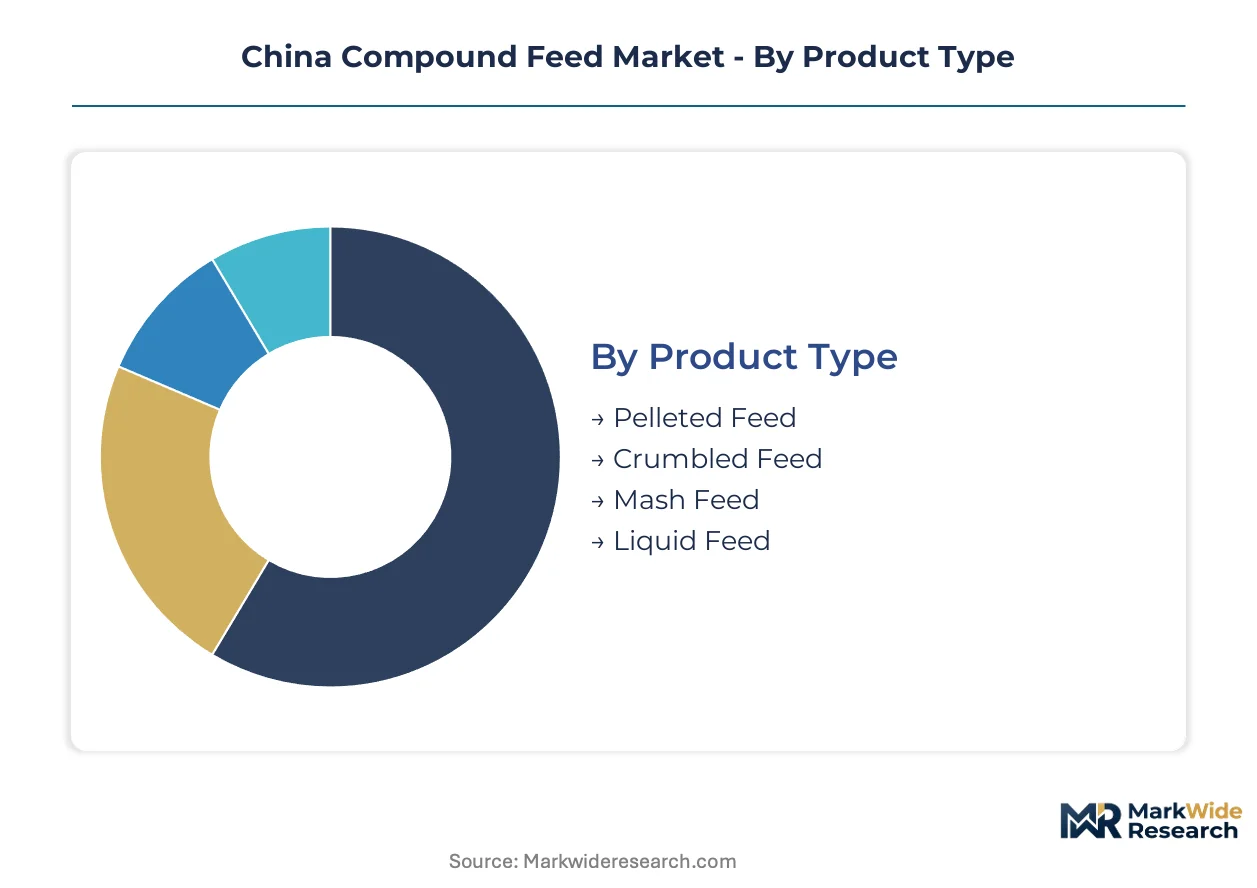
Product form and ingredient sourcing decisions in China's compound feed market carry significant capital implications. Automated pelleting lines and liquid feed systems demand differentiated equipment investments, while grain procurement strategies reshape mill location economics across provincial supply zones.
Product Type:
Pelleted feed requires the heaviest upfront capital, with conditioning towers and extrusion presses dominating facility buildouts.
- Pelleted Feed:Thermally processed cylinders formed through steam conditioning and die extrusion, achieving standardized durability and reduced feed waste. Yangtze River Delta pork integrators specify pellet durability indices above 95 percent to minimize fines in automated handling systems, locking in volume contracts with mills possessing captive pelleting capacity.
- Liquid Feed:Pumpable slurries blending grains, protein meals, and additives with controlled viscosity for pipeline delivery. Guangdong swine finishing operations are installing liquid feed infrastructure to enable real-time consumption monitoring and precision nutrient dosing, though tank farm investments exceed dry feed systems by substantial margins.
- Crumbled Feed:Pellets broken into smaller particles for young poultry and starter rations, requiring secondary roller mills.
- Mash Feed:Unprocessed ground blends retaining meal consistency, common in backyard operations and ruminant feeding.
Pelleted feed absorbs the bulk of installed capacity; liquid feed is expanding most quickly.
Ingredient Type:
Grain procurement patterns segment mills by geographic exposure to price volatility and transport cost structures.
- Corn:Primary energy source anchoring formulations across all species, typically comprising 50-70 percent of ration mass. Shandong mills source corn from northeastern provincial reserves, though interprovincial rail capacity constraints create seasonal procurement bottlenecks that favor facilities with captive grain elevators.
- Soybean Meal:Standardized protein concentrate derived from solvent-extracted soybeans, specifying 44-48 percent crude protein content. Coastal mills in Jiangsu and Zhejiang leverage port access to imported soybean crush, while inland operators face 15-20 percent cost premiums from domestic transport.
- Wheat:Substitute energy grain accelerating in northern provinces where local harvests shorten supply chains.
- Barley:Lower-energy alternative favored in ruminant rations and certain aquaculture applications.
Corn and soybean meal command dominant formulation shares; wheat substitution is climbing fastest in Henan and Hebei mill networks.
Animal Type:
Species-specific nutrition requirements dictate formulation complexity and margin capture potential across customer segments.
- Poultry:High-density broiler and layer operations demanding precise amino acid balancing and rapid feed conversion optimization. Shandong's vertically integrated poultry processors source feed through captive mill networks, extracting volume discounts that compress margins for independent suppliers.
- Aquaculture:Species-specific formulations for shrimp and finfish requiring premium protein sources and water stability engineering. Fujian coastal zones show steepest growth in marine species nutrition, where export certification requirements harden residue standards and reward R&D-intensive suppliers.
- Swine:Largest volume segment with tiered formulations across breeding, nursery, and finishing phases.
- Ruminants:Cattle and sheep feed concentrated in northern pastoral provinces with lower formulation sophistication.
Poultry consumes the greatest feed tonnage; aquaculture is gaining share fastest on value-added premium positioning.
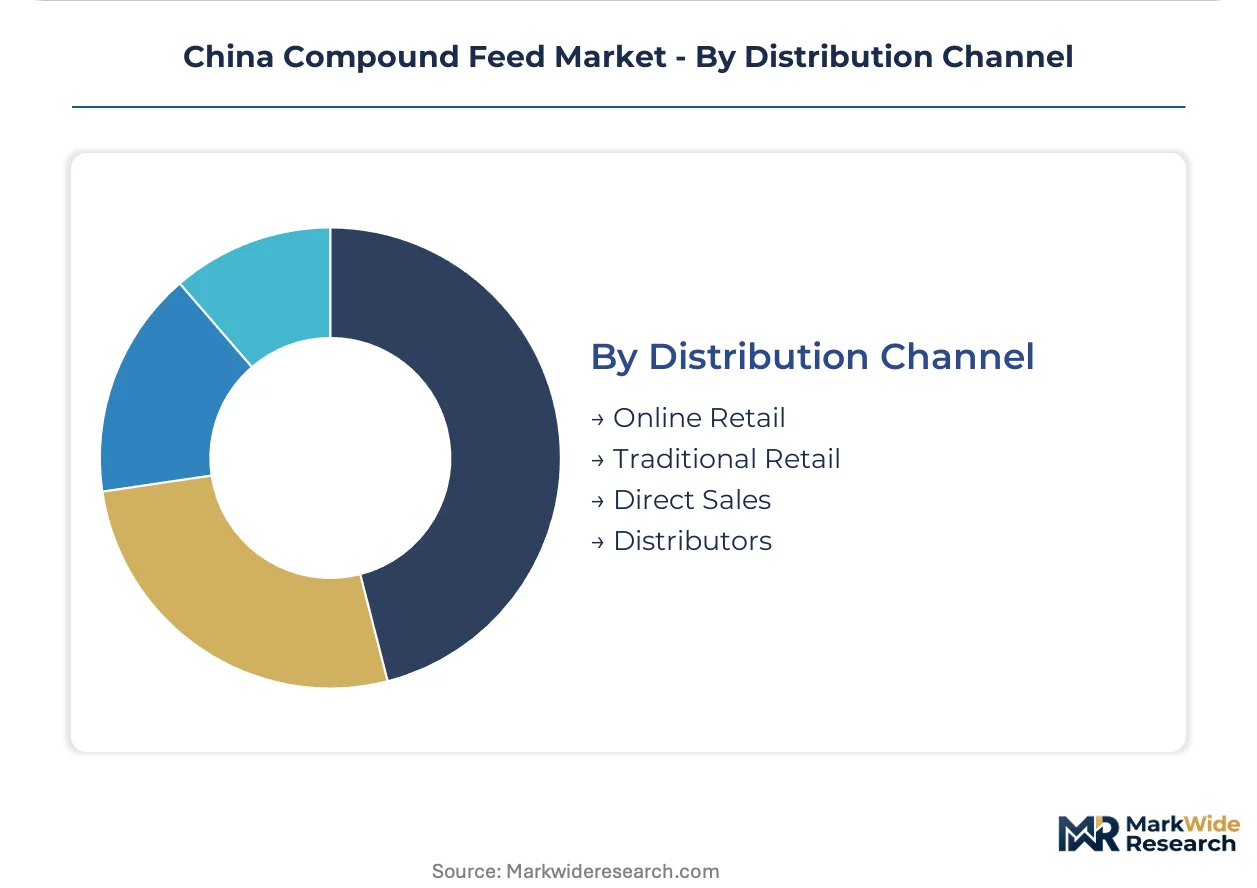
Distribution Channel:
Channel selection reflects customer scale and the economics of logistics coordination versus relationship management.
- Direct Sales:Mill-to-farm contracting for large integrators with predictable volume profiles and formulation co-development requirements. Wen's Foodstuff and New Hope Group centralize procurement through direct relationships, displacing distributor intermediaries across southern China.
- Distributors:Regional wholesalers aggregating smallholder demand and providing credit extension services. Henan's distributor networks retain relevance for backyard poultry and swine operations lacking scale for direct mill relationships.
- Traditional Retail:Feed stores and agricultural supply cooperatives serving fragmented farm bases.
- Online Retail:Emerging platform-based procurement for specialty additives and smaller volume orders.
Direct sales channels capture the majority of commercial volume; distributor relationships are contracting most rapidly as integrator consolidation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn harvests in northeastern Jilin and Heilongjiang provinces anchor China's compound feed geography, with rail corridors funneling grain toward coastal mill clusters. Provincial feed safety regimes and dual carbon enforcement reshape capacity placement across major production zones.
Shandong Province
Vertically integrated poultry processors drive feed offtake as automated broiler houses expand across the Jiaodong Peninsula. SAMR's antibiotic residue limits under revised GB standards force mills toward enzyme-based formulations. Qingdao and Yantai mill clusters are retrofitting pelleting lines with captive biogas recovery to meet provincial energy audits.
Guangdong Province
Intensive shrimp and finfish aquaculture scales feed demand as export certification requirements harden residue standards. MEE nitrogen discharge caps cascade into lower-excretion formulation mandates. Zhanjiang and Shantou coastal zones concentrate species-specific nutrition R&D for premium marine species.
Jiangsu Province
Port-accessible soybean crush capacity anchors protein meal supply for Yangtze River Delta pork and poultry integrators. Dual carbon goals pressure mills to audit drying and extrusion energy use. Nanjing and Nantong feed terminals lock in volume contracts through direct sales to company-owned farm networks.
Sichuan Province
Swine finishing operations in the Chengdu-Chongqing corridor absorb growing liquid feed volumes for precision nutrient dosing. Provincial feed safety inspections compress certification timelines for quality control teams. Deyang and Meishan mill clusters are expanding wheat substitution to dampen corn price volatility exposure.
Fujian Province
Marine aquaculture zones drive premium formulation demand as pond density rises and water stability engineering requirements tighten. SAMR labeling enforcement under national GB codes shapes additive procurement decisions. Xiamen and Fuzhou coastal mills specialize in high-value species nutrition with R&D intensity commanding margin premiums.
China Compound Feed Market Competitive Environment
Global majors compete with regional champions across formulation technology and captive offtake agreements, producing a tiered structure where scale-driven integrators face off against species-specific specialists. The vendor base clusters around three archetypes: vertically integrated agribusiness conglomerates with backward control over breeding and processing, aquaculture nutrition specialists with intensive R&D capabilities, and diversified feed manufacturers serving fragmented smallholder demand through distributor networks. Dominant competitive moves include capacity consolidation through mill network expansion and strategic partnerships securing captive grain elevator access.
Among China-based integrated operators, New Hope Group and Wen's Foodstuff Group exemplify the conglomerate archetype through company-owned farm networks that centralize procurement decisions and extract volume discounts. Haid Group occupies a specialist position within aquaculture nutrition, sustaining R&D intensity for species-specific formulations. These three entities collectively represent how competitive positioning in China's compound feed sector depends on securing captive offtake channels and aligning formulation capabilities with tightening SAMR safety regimes.
| Leading Market Players |
|---|
| New Hope Group |
| Wen's Foodstuff Group |
| CP Group |
| Haid Group |
| Tongwei Group |
| Zhengda International Group |
| Wellhope Agri-Tech |
| Shandong Backbone Group |
| Cargill Inc. |
| Others |
Value Chain & Pricing Dynamics
SAMR's tightening antibiotic residue limits under revised GB standards are compressing legacy formulation margins while rewarding mills that bundle technical service and compliance certification into nutrition system contracts. This procurement preference shift forces supply response toward enzyme supplier partnerships and captive R&D capabilities, elevating pricing power for compliant nutrition specialists.
Pricing Analysis
Service bundling separates premium nutrition providers from commodity volume players, with technical support and residue compliance warranties commanding substantial markups over unbundled feed products. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and formulation complexity, with aquaculture nutrition showing widest spreads. Cost compression in standard-tier poultry rations is intensifying because wheat substitution and distributor disintermediation squeeze legacy mill margins. Backyard smallholders remain most price-sensitive, while integrated pork and poultry operators prioritize feed conversion ratios over unit cost.
Supply Chain Analysis
Rail freight costs from northeastern Jilin and Heilongjiang corn reserves to coastal mill clusters anchor location economics, with interprovincial capacity constraints favoring facilities with captive grain elevators. Raw material flows draw from domestic soybean crush in Jiangsu and Zhejiang port zones, imported protein meals, and accelerating wheat harvests in Henan and Hebei. Single-source vulnerability concentrates in German and Danish automated batching equipment, exposing expansion timelines to import clearance bottlenecks. Distribution runs through direct mill-to-farm contracting for large integrators and regional wholesalers for fragmented smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's compound feed sector is consolidating around compliance-capable nutrition specialists as SAMR inspection cycles compress and dual carbon audits disqualify legacy facilities. Weaker players lacking captive biogas recovery or enzyme formulation expertise face forced exit.
For Market Incumbents: Cement defensive positioning through backward integration into poultry breeding networks that lock in captive offtake volume. Expand high-output mill capacity in Henan to exploit shorter wheat supply chains while retrofitting legacy conditioning lines with biogas recovery systems that satisfy provincial energy audits. SAMR's accelerating certification timelines threaten mills without automated quality documentation throughput.
For New Entrants and Emerging Players: Precision nutrition software for nitrogen excretion modeling offers a technology-first wedge into southern coastal aquaculture zones where MEE discharge caps cascade into formulation mandates. Target Fujian marine species operations with underpenetrated demand for water-stable premium rations. Partner with coastal liquid feed infrastructure providers to bypass capital-intensive tank farm investments.
For Investors and Strategic Acquirers: The window for entry favors aquaculture nutrition specialists with demonstrated R&D intensity and export certification track records. Long-term viability hinges on species-specific formulation capabilities that sustain margin premiums through regulatory tightening. Watch for provincial feed safety inspection failures as inflection indicators accelerating forced asset sales.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Formulation Partnership | Secures technical capabilities for SAMR-compliant additive systems while compressing legacy product lines. |
| Captive Biogas Recovery Installation | Qualifies mills for provincial dual carbon energy audits and shortens payback periods on drying operations. |
| Direct Mill-to-Farm Contracting | Displaces distributor intermediaries and extracts volume discounts from Wen's Foodstuff and New Hope Group networks. |
| Species-Specific R&D Expansion | Captures premium positioning in Fujian marine aquaculture zones with hardening export residue standards. |
| Wheat Substitution Infrastructure | Dampens corn price volatility exposure in northern Henan and Hebei mill networks through local grain sourcing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with feed mill operations directors, provincial agriculture bureau officials, enzyme supplier technical service leads, and integrated poultry procurement managers. SAMR GB standard revision documents, MEE livestock discharge notifications, and China Feed Industry Association production statistics provided triangulation points. Bottom-up volume modeling across provincial mill networks converged with top-down demand estimates from animal protein consumption forecasts.
Granularity-level modeling deployed species-specific formulation tiers, product form distinctions between pelleted and liquid systems, and geographic supply zone segmentation across northeastern corn reserves and coastal soybean crush capacity. CAGRs were derived from production capacity expansion pipelines and animal inventory projections across the analysis window. Feed conversion ratio improvements from enzyme adoption and nitrogen excretion compliance costs informed margin trajectory assumptions.
Several conditions sit outside the modeled scope, including abrupt SAMR regulatory reversals, extreme corn-soybean price dislocations, and trade policy disruptions affecting German equipment imports. Forecasts reflect assumptions about continued integrator consolidation and dual carbon enforcement intensity that could shift with provincial leadership transitions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Cut Flower Market