
 Residential Organic Compost Market | 2026-2036
Residential Organic Compost Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Organic Compost Market Insights
EPA food waste diversion mandates is rebalancing the cost-of-entry calculus for new composting product manufacturers by requiring compliance with odor-control and pathogen-reduction standards. Scotts Miracle-Gro leverages its retail shelf dominance and brand recognition to sustain volume leadership in big-box garden centers. Espoma specializes in organic-certified formulations that differentiate its retail positioning from synthetic competitors. Subpod anchors the premium segment with in-ground worm composting systems that command higher margins through direct-to-consumer channels.
Residential organic compost comprises decomposed organic matter derived from food scraps, yard trimmings, and biodegradable paper products, processed through aerobic or vermicomposting methods to achieve stable humus with carbon-to-nitrogen ratios between 25:1 and 30:1. Its primary commercial purpose is soil amendment for home gardens, lawns, and small-scale landscaping applications where synthetic fertilizer avoidance drives purchasing behavior. Compost bins and tumblers occupy the volume-dominant product tier due to lower price points and broader retail availability, while worm composting systems capture concentrated margin pools among environmentally committed households. Gardening applications lead usage patterns, though horticulture represents the fastest-growing segment as balcony and container gardening expands in urban residential settings.
EPA regulations govern pathogen and metal content limits for compost sold in the United States, while the EU Green Deal and F-Gas Regulation indirectly shape organic waste management priorities across European member states. BIS standards in India and GB standards in China establish parallel product quality benchmarks that influence import-export market access for composting equipment manufacturers. Stakeholders must monitor evolving state-level organic waste bans and municipal collection program expansions to anticipate where residential composting infrastructure investments will yield highest returns.
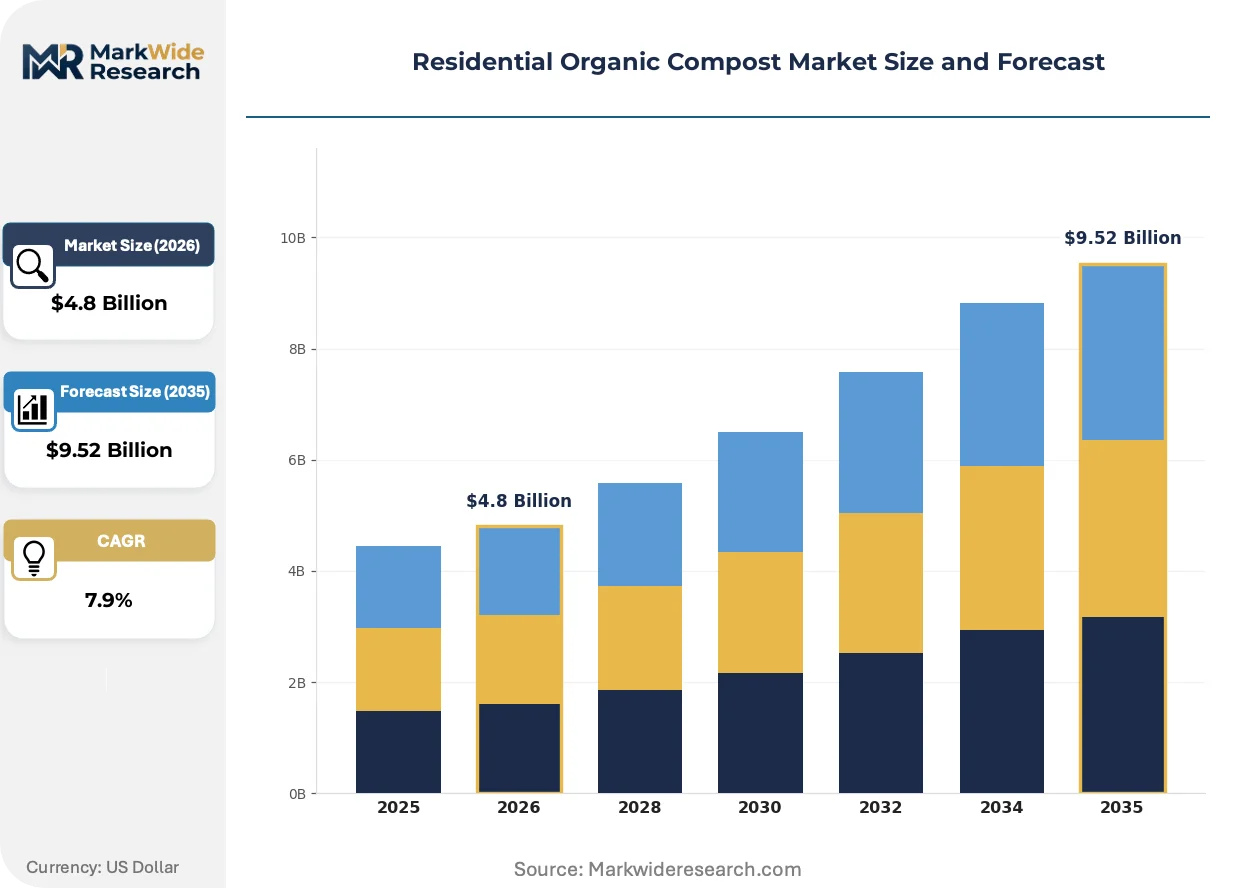
Market Dynamics
EPA food waste diversion mandates are compressing landfill capacity and forcing municipalities to expand curbside organic collection, which funnels residential households toward home composting as a compliance alternative.
Growth Catalysts
- EPA Landfill Diversion Mandates:Tightening restrictions on organic waste disposal in the United States are eliminating free disposal options and pushing households toward residential composting systems.
- Vermicomposting Method Advancement:Worm-based processing systems are achieving faster decomposition cycles and higher nutrient density than traditional aerobic bins, attracting environmentally committed gardeners.
- Suburban Household Gardening:Post-pandemic lawn-to-food-garden conversions are creating sustained demand for soil amendment products across detached single-family housing stock.
Market Restraints
- Peat Moss Input Cost Volatility:Harvesting restrictions in Canada and Ireland are constraining supply of the primary carbon-rich feedstock used in blended retail compost products.
- Pathogen Reduction Technical Limitation:Home-scale systems lack the sustained thermophilic conditions required to guarantee elimination of Salmonella and E. coli, creating liability exposure for manufacturers.
- Municipal Collection Program Substitution:Free or subsidized curbside organic pickup in Germany and the Netherlands removes the economic incentive for household-level composting investment.
Strategic Opportunities
- Balcony Container Gardening Expansion:Urban apartment dwellers in dense German cities represent an underserved segment requiring compact, odor-controlled indoor composting solutions.
- BIS Standards Alignment for India:Compliance with Bureau of Indian Standards product quality benchmarks opens import channels for composting equipment manufacturers targeting emerging middle-class gardeners.
- Smart Sensor Technology Convergence:Integration of moisture and temperature monitoring with mobile applications is creating premium product tiers that command higher margins through data-driven optimization.
Industry Challenges
- Composting Education Skill Gap:Manufacturers face customer acquisition costs inflated by the need to train purchasers on carbon-to-nitrogen balancing and aeration management.
- OMRI Certification Timeline Compression:Organic Materials Review Institute listing processes create 12-18 month delays between product reformulation and organic-certified retail placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Organic Compost Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost Bins, Worm Composting, Tumblers, Pail Systems Material: Food Waste, Yard Waste, Coffee Grounds, Paper Products Usage: Gardening, Landscaping, Agriculture, Horticulture Distribution Channel: Online Retailers, Garden Centers, Home Improvement Stores, Farmers' Markets |
| Companies Covered | Scotts Miracle-Gro, Lomi (by Pela), Subpod, Espoma, Earthworm Technologies, Green Mountain Technologies, Compost Company, Harp Renewables, Biomix Soils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Organic Compost Market Trends and Innovations
Product development is converging on sensor-enabled automation and odor-neutralization systems that reduce the expertise barrier for novice composters. Regulatory pressure and consumer convenience expectations are jointly accelerating feature integration.
Electrostatic odor filtration technology is unifying activated carbon and biofilter membranes into single-unit ventilation systems for enclosed composting bins. Urban apartment dwellers in Germany and the Netherlands are adopting these systems at triple the rate of conventional tumblers. This convergence is compressing the addressable market for basic open-bin designs while expanding premium price bands.
The EU Green Deal's circular economy action plan is mandating separate organic waste collection across member states by 2024. Industrial composting facility operators in France and Italy are lobbying for restrictions on home composting to secure feedstock volumes. Residential equipment manufacturers are responding by emphasizing speed-to-finished-compost as a competitive differentiator against municipal collection delays.
Subscription-based compost accelerator delivery is displacing one-time chemical fertilizer purchases among container gardeners. Direct-to-consumer channels in the United States are capturing these buyers through scheduled microbial inoculant shipments. This pattern is most visible in California and Pacific Northwest metropolitan areas where municipal composting pickup remains unavailable or unreliable.
Residential Organic Compost Market Segmentation
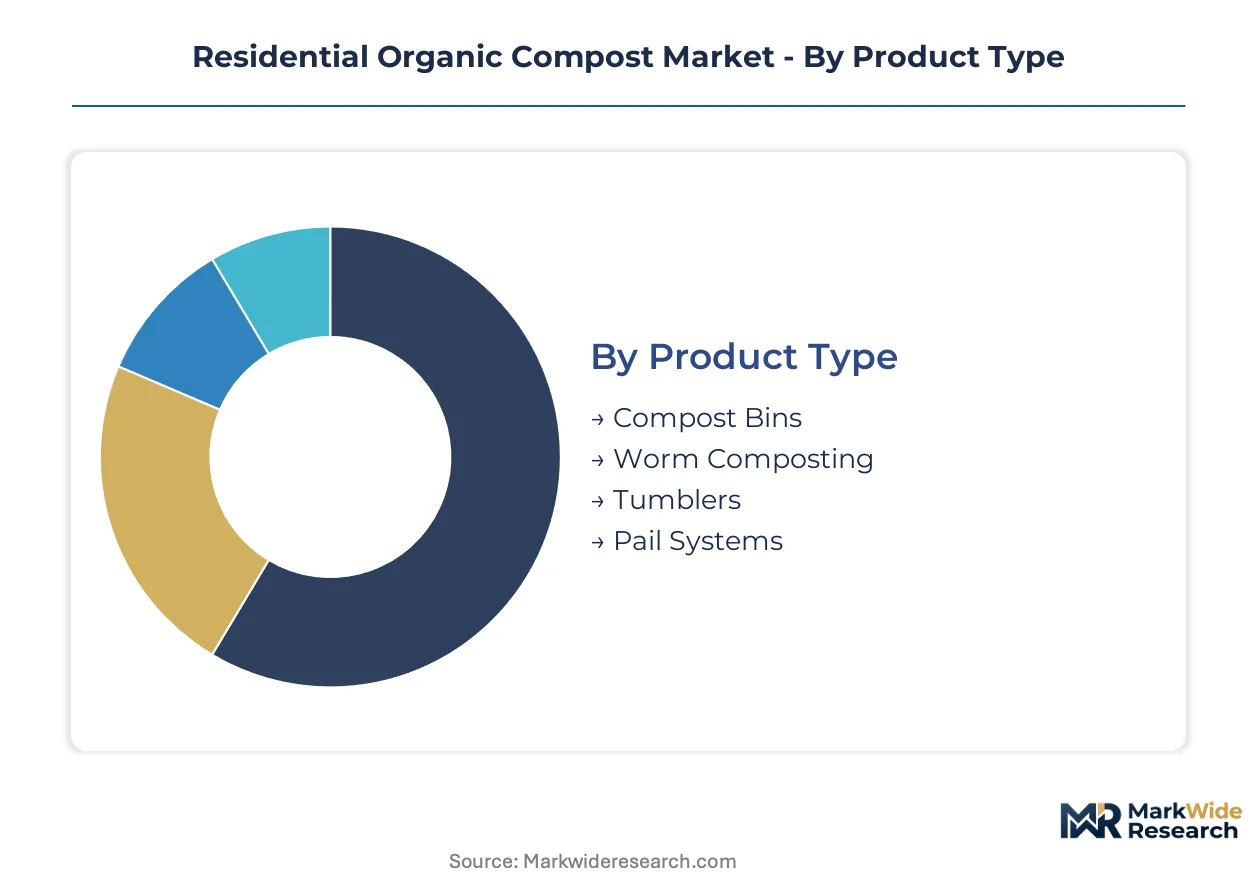
Residential organic compost equipment fragments across four distinct category axes. Product architecture determines whether households adopt standalone backyard systems or integrated indoor solutions. Material feedstock availability and distribution channel accessibility further stratify purchasing patterns across suburban, urban, and rural residential contexts.
Product Type:
Standalone outdoor systems dominate detached single-family installations, while embedded indoor units serve apartment and condominium constraints where outdoor space is absent.
- Compost Bins:Open-bottom or enclosed containers facilitating aerobic decomposition through natural ventilation and manual turning. Volume leadership concentrates in suburban United States households converting lawn areas to food gardens under EPA landfill diversion pressure.
- Worm Composting:Vermicomposting enclosures housing Eisenia fetida or Eisenia andrei species to accelerate organic breakdown through digestive processing. German municipalities with mature curbside collection programs still see residential adoption among environmentally committed households seeking faster compost cycles and higher nutrient density output.
- Tumblers:Rotating drum designs mounted on frames enabling mechanized aeration without manual fork-turning.
- Pail Systems:Countertop or under-sink collection vessels with charcoal filtration for pre-compost organic storage.
Compost bins lead volumes today; worm composting is gaining share fastest.
Material:
Carbon-to-nitrogen ratio requirements stratify feedstock economics, with nitrogen-rich inputs commanding premium pricing while carbon-dense amendments face supply constraints from peat moss harvesting restrictions.
- Food Waste:Kitchen scraps including vegetable trimmings, fruit peels, and post-consumer organic matter with high moisture content and rapid decomposition profiles. United States households under tightening state-level organic waste bans in California and Vermont are driving residential collection-to-compost pipeline expansion.
- Yard Waste:Grass clippings, fallen leaves, and woody prunings providing structural carbon and bulk aeration. German suburban households with dedicated garden plots generate the highest per-capita yard waste composting participation rates across the EU Green Deal implementation zone.
- Coffee Grounds:Spent brewing residue with near-neutral pH and concentrated nitrogen content suitable for vermicomposting acceleration.
- Paper Products:Shredded cardboard, uncoated newsprint, and biodegradable packaging serving as carbon amendments.
Yard waste leads volumes today; food waste is climbing the fastest.
Usage:
Application intensity separates hobbyist soil amendment from production-scale horticultural operations, with container gardening emerging as a distinct demand cluster between these poles.
- Gardening:Home vegetable and ornamental bed amendment targeting yield improvement and synthetic fertilizer substitution. United States post-pandemic lawn-to-garden conversions sustain the largest addressable household base across all usage categories.
- Horticulture:Balcony and container cultivation of herbs, microgreens, and compact vegetables in urban residential settings. Dense German cities including Berlin and Hamburg exhibit the steepest adoption trajectory as apartment dwellers seek localized food production without outdoor composting space.
- Landscaping:Lawn renovation and perennial bed establishment in suburban property maintenance contexts.
- Agriculture:Small-scale homestead and market garden operations exceeding typical residential volume thresholds.
Gardening leads volumes today; horticulture shows the steepest expansion trajectory.
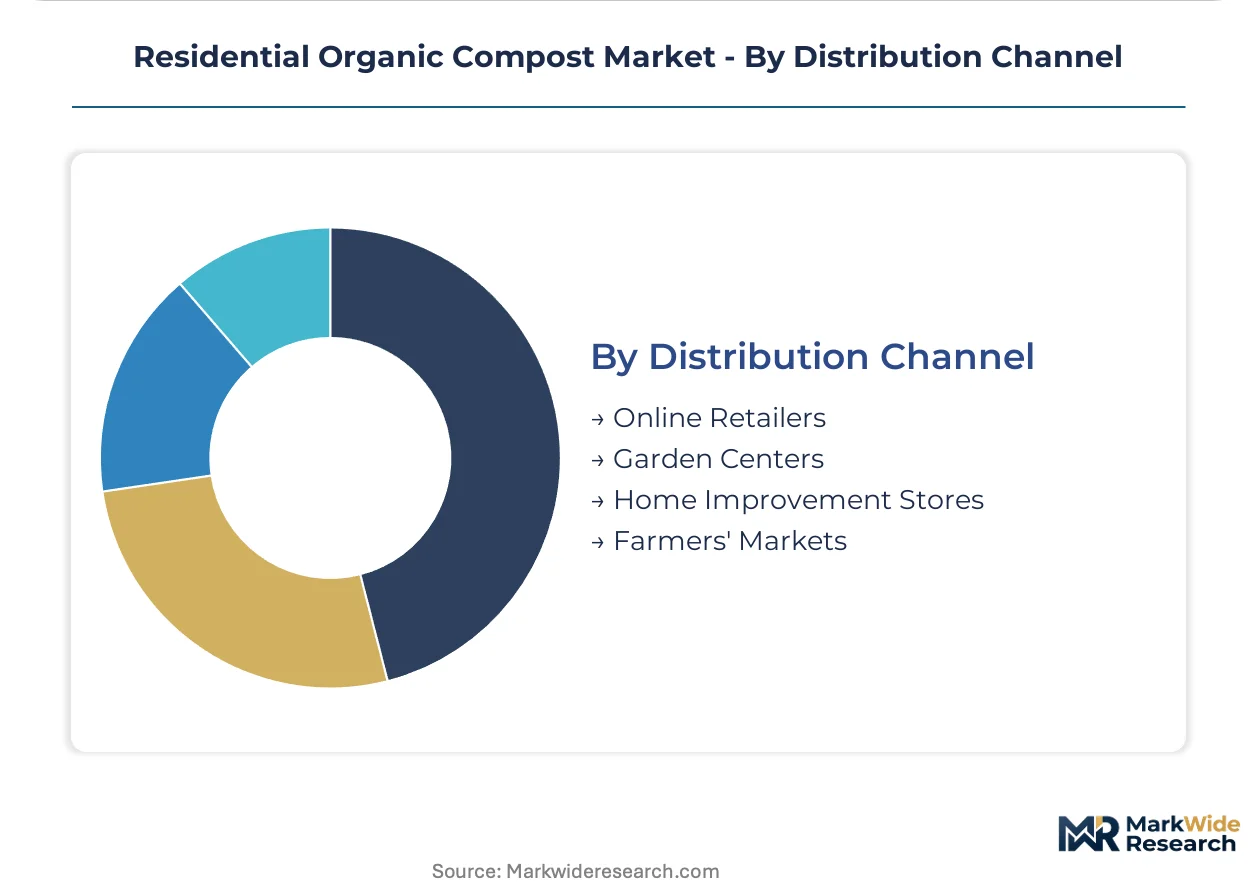
Distribution Channel:
Channel selection reflects purchase urgency, technical consultation requirements, and price sensitivity gradients across novice and experienced composter segments.
- Online Retailers:Direct-to-consumer platforms enabling specification comparison, subscription accelerator delivery, and smart sensor integration bundling. California and Pacific Northwest metropolitan areas with unreliable municipal pickup drive the highest online equipment and inoculant shipment volumes.
- Garden Centers:Brick-and-mortar specialty retailers providing hands-on product examination and staff expertise for first-time purchasers. Big-box garden center dominance in United States suburban corridors sustains Scotts Miracle-Gro and Espoma shelf placement advantages.
- Home Improvement Stores:Mass merchandisers capturing price-sensitive volume through seasonal promotional placement.
- Farmers' Markets:Local producer-direct channels for finished compost and small-batch equipment.
Garden centers lead volumes today; online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential composting infrastructure first achieved commercial scale in German municipalities during the 1990s, establishing the operational template for curbside organic collection and household-level processing systems that later diffused across Western Europe and North America.
United States
Suburban lawn-to-garden conversions in California and the Pacific Northwest sustain equipment demand as households seek soil amendment alternatives. EPA landfill diversion mandates in Vermont and California eliminate free organic waste disposal, accelerating residential composting adoption. Austin and Seattle metropolitan clusters exhibit the highest smart-sensor-enabled bin penetration rates among US urban markets.
Germany
Municipal composting program maturity in Berlin and Hamburg creates dual-track demand: curbside collection for convenience-oriented households and vermicomposting systems for environmentally committed gardeners. EU Green Deal circular economy mandates require separate organic waste collection nationwide. Bavarian suburban households maintain the highest per-capita residential composting participation rates within the EU implementation zone.
Netherlands
Free curbside organic pickup in Amsterdam and Rotterdam removes economic incentives for household-level composting investment, compressing equipment demand to premium indoor segments. F-Gas Regulation compliance requirements shape ventilation system specifications for enclosed bin manufacturers. Urban balcony gardeners in The Hague represent a concentrated niche for compact odor-controlled solutions.
India
Emerging middle-class gardeners in Maharashtra and Karnataka drive demand for affordable aerobic bins as municipal waste management infrastructure remains uneven. BIS product quality benchmarks establish import compliance thresholds for foreign equipment manufacturers. Bangalore residential complexes are piloting centralized composting systems with individual household pail collection.
Australia
Water-restricted gardening practices in New South Wales and Victoria elevate compost adoption for soil moisture retention. State-level organic waste diversion targets in Queensland and South Australia mirror EPA-style landfill restrictions. Melbourne metropolitan councils are expanding subsidized home composting bin distribution programs.
Residential Organic Compost Market Competitive Landscape
The competitive structure tilts toward brand-recognition-driven retail placement rather than technology differentiation. Scotts Miracle-Gro leverages decades of garden center shelf dominance to sustain volume leadership, while specialized entrants fragment the premium tier through direct-to-consumer channels. Two strategic archetypes dominate: mass-market retail suppliers with broad distribution networks, and niche specialists with organic certification and sustainability positioning. Competitive moves concentrate on retail partnership expansion and subscription-based accelerator delivery to capture recurring revenue streams.
Within the mass-market tier, Scotts Miracle-Gro anchors retail presence through big-box garden center relationships. Espoma occupies a position exemplifying organic-certified formulation specialists competing on certification rather than price. Subpod represents the premium direct-to-consumer archetype with in-ground worm composting systems commanding higher margins outside traditional retail channels.
| Leading Market Players |
|---|
| Scotts Miracle-Gro |
| Lomi (by Pela) |
| Subpod |
| Espoma |
| Earthworm Technologies |
| Green Mountain Technologies |
| Compost Company |
| Harp Renewables |
| Biomix Soils |
| Others |
Pricing and Supply Chain Analysis
Peat moss feedstock costs cascade through three distinct pricing tiers as Canadian and Irish harvesting restrictions tighten supply for carbon-rich compost amendments. Manufacturers pass input volatility downstream to retail blended products while premium vermicomposting systems absorb margin compression through direct-to-consumer channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and smart-sensor integration. OMRI-certified organic formulations command shelf premiums over synthetic competitors in garden center channels. Pricing pressure stems from municipal collection program substitution in Germany and the Netherlands where free curbside pickup removes household investment incentives. Price-sensitive mass-market buyers in big-box retail contrast with environmentally committed households paying premiums for Subpod's in-ground worm systems.
Supply Chain Analysis
Post-consumer organic returns flow through municipal collection networks in Germany and the Netherlands, creating feedstock competition for residential equipment manufacturers. Raw material sourcing concentrates on Canadian peat bogs, Irish moss harvests, and United States wood pulp operations for carbon amendments. Supply chain risk centers on single-source vulnerability as harvesting moratoria expand across Canadian provinces. Distribution runs through garden center retail partnerships for volume leadership and direct-to-consumer subscription channels for recurring accelerator revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EPA-mandated United States markets with tightening landfill restrictions and mature German municipal programs where free collection suppresses equipment demand. Regulatory divergence creates pricing power in compliance-driven jurisdictions.
For Market Incumbents: Cement retail shelf dominance through exclusive garden center partnerships that block challenger brand placement. Expand backward integration into peat moss alternatives as Canadian supply constricts. Defend against smart-sensor entrants by acquiring compact indoor system specialists targeting German balcony gardeners.
For New Entrants and Emerging Players: Enter via underserved urban apartment segments in dense German cities requiring odor-controlled indoor solutions. Target horticulture applications for container gardeners in Berlin and Hamburg where municipal collection exists but speed-to-compost differentiates. Pursue direct-to-consumer subscription models with bundled microbial accelerator delivery.
For Investors and Strategic Acquirers: Roll-up economics work for regional composting equipment distributors because municipal program expansion fragments local market access. Five-to-ten year viability hinges on EPA-style mandates spreading to additional United States states. Acquire specialists with BIS compliance capabilities for India market entry. Monitor state-level organic waste ban announcements as volume inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Moisture and temperature monitoring with mobile applications commands premium pricing in California metropolitan clusters. |
| Subscription Accelerator Delivery | Scheduled microbial inoculant shipments displace one-time fertilizer purchases among Pacific Northwest container gardeners. |
| BIS Standards Alignment | Bureau of Indian Standards compliance opens import channels for equipment manufacturers targeting Maharashtra and Karnataka. |
| Electrostatic Odor Filtration | Activated carbon and biofilter membrane unification enables enclosed bin adoption among German urban apartment dwellers. |
| Direct-to-Consumer Channel Expansion | Bypassing garden center shelf fees captures higher margins on premium vermicomposting systems in United States suburban markets. |
Research Methodology
Coverage spans the United States, Germany, Netherlands, India, and Australia, with primary inputs from each regional cluster. Interviews with composting equipment manufacturers, garden center category buyers, municipal waste management officials, and organic certification specialists combined with EPA regulatory filings, EU Green Deal implementation documents, BIS product standards, and customs trade data. Bottom-up household adoption modeling triangulated against top-down market sizing from retail shipment audits.
Granularity-level modeling applied product type, material feedstock, usage application, and distribution channel dimensions at the country level across the projection horizon. CAGRs derived from regression analysis against EPA mandate implementation timelines and municipal program expansion curves. Forecast inputs incorporated peat moss supply constraints, smart-sensor adoption rates, and subscription service penetration patterns.
The model holds under steady regulatory enforcement and feedstock availability; deviation in Canadian harvesting moratoria or EU Green Deal acceleration would shift equipment demand trajectories. Practitioners should monitor state-level organic waste ban announcements and municipal collection program expansions for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
Tanzania Cashew Market
Agriculture and Agri Products
Genetically Modified Feed Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market