
 Indonesia Animal Feed Market | 2026-2036
Indonesia Animal Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Animal Feed Market Intelligence
East Java's feed mill corridor is broadening output to serve expanding poultry operations across Central and East Java provinces. Charoen Pokphand Indonesia leverages its integrated hatchery-to-slaughterhouse network to secure captive demand for formulated feeds. Japfa Comfeed Indonesia sustains geographic dominance through mill placements near corn and soybean meal transit routes. Malindo Feedmill differentiates via specialized aquaculture feed lines targeting shrimp and tilapia producers in Sulawesi and Kalimantan.
Animal feed comprises nutritionally complete or supplemental formulations designed to deliver metabolizable energy, crude protein, lysine, and trace minerals to livestock and aquaculture species, with typical broiler grower feeds containing 20-22% protein and 3,200 kcal/kg energy density. Complete feed occupies the largest value share as smallholder farmers lack formulation expertise and prefer ready-to-use rations. Pellet form leads volume due to reduced feed wastage and improved feed conversion ratios in intensive poultry systems. Aquaculture producers represent the fastest-growing customer type as shrimp and finfish farming expand in Sulawesi and Papua.
BIS-equivalent national standards and the Ministry of Agriculture's feed safety regulations govern maximum aflatoxin levels and antibiotic growth promoter prohibitions, compelling mills to invest in quality certification. The Indonesian Food and Drug Authority and the National Agency for Drug and Food Control coordinate import permits for feed additives and premix vitamins, shaping supplier access and formulation costs. Stakeholders must monitor enforcement consistency across provincial agricultural offices and anticipate tighter residue testing protocols that will favor mills with in-house laboratories and traceability systems.
Market Dynamics
Integrated poultry operations across Java are consolidating feed procurement under captive supply arrangements, compressing spot-market liquidity and favoring mills with backward integration into hatchery networks.
Growth Catalysts
- Ministry of Agriculture mycotoxin enforcement:Stricter aflatoxin limits under national feed safety standards compel commercial farms to upgrade to certified formulated feeds, expanding addressable market for compliant mills.
- Shrimp aquaculture expansion:Sulawesi and Kalimantan producers are scaling intensive pond systems that require nutritionally complete aquafeeds with precise protein-to-energy ratios.
- East Java feed mill clustering:Geographic concentration of integrated broiler farms near Surabaya creates dense demand corridors that reduce logistics costs for proximate suppliers.
Market Restraints
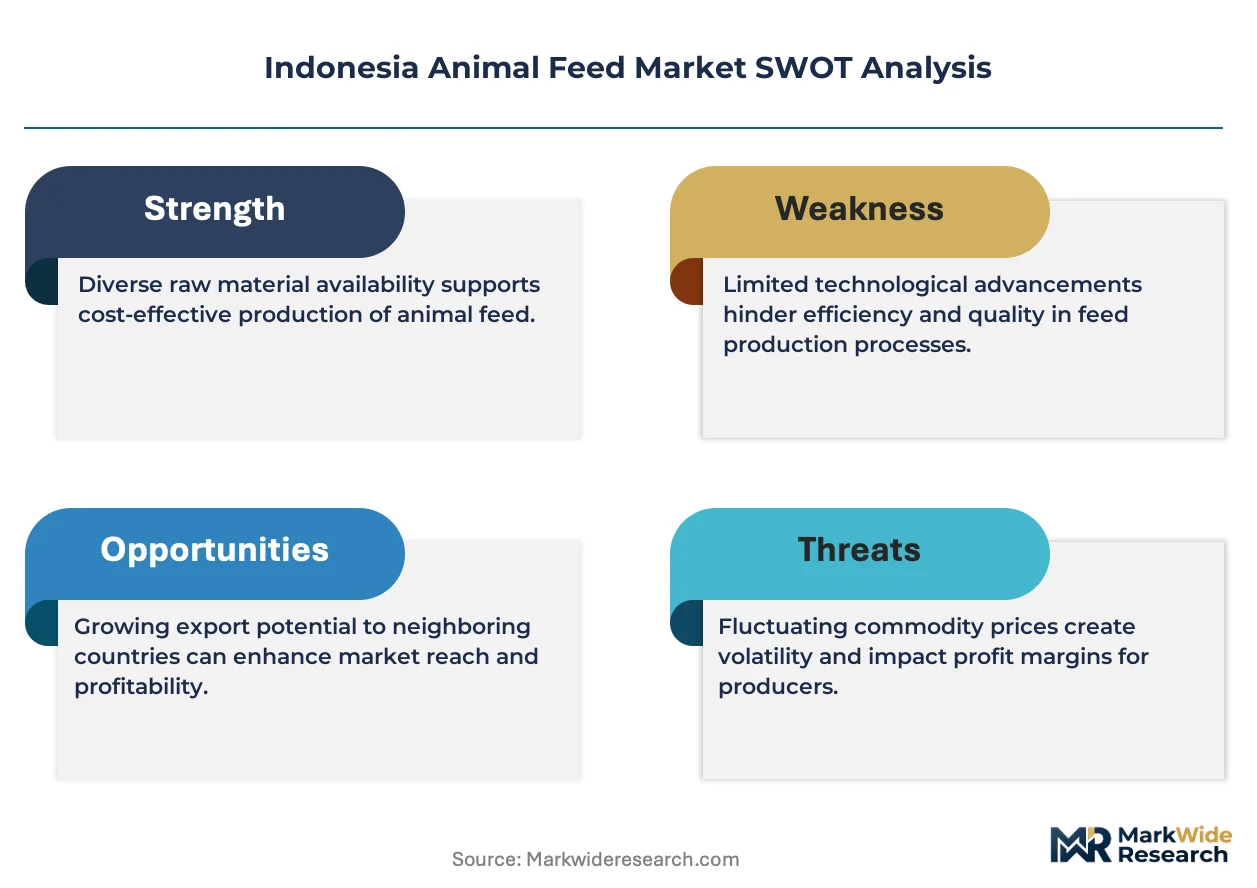
- Corn price volatility:Domestic corn supply deficits force mills to absorb import parity swings, compressing formulation margins during El Niño harvest disruptions.
- Soybean meal import dependency:Over 60% of protein inputs arrive through a limited set of bulk handling terminals, creating bottleneck risk at Tanjung Priok and Surabaya ports.
- Antibiotic growth promoter prohibitions:Ministry of Agriculture bans on sub-therapeutic additives force reformulation cycles that elevate R&D costs without immediate price recovery mechanisms.
Strategic Opportunities
- Papua aquaculture frontier:Underdeveloped shrimp and finfish farming regions lack local feed mill presence, creating first-mover advantage for mobile mixing units or satellite facilities.
- Traceability system mandates:Anticipated BPOM (Indonesian Food and Drug Authority) requirements for additive chain-of-custody documentation favor mills with in-house laboratory investments.
- Pellet-to-extruded feed transition:Advanced extrusion technology for floating aquafeeds is absorbing interest from tilapia producers seeking improved feed conversion ratios in lake-based systems.
Industry Challenges
- Formulation chemist scarcity:Qualified nutritionists capable of balancing metabolizable energy and amino acid profiles across species-specific diets command premium compensation that mid-tier mills struggle to match.
- Quality certification timelines:SNI (Indonesian National Standard) accreditation for feed safety management requires 12-18 month validation cycles that delay market entry for new facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Animal Feed Market |
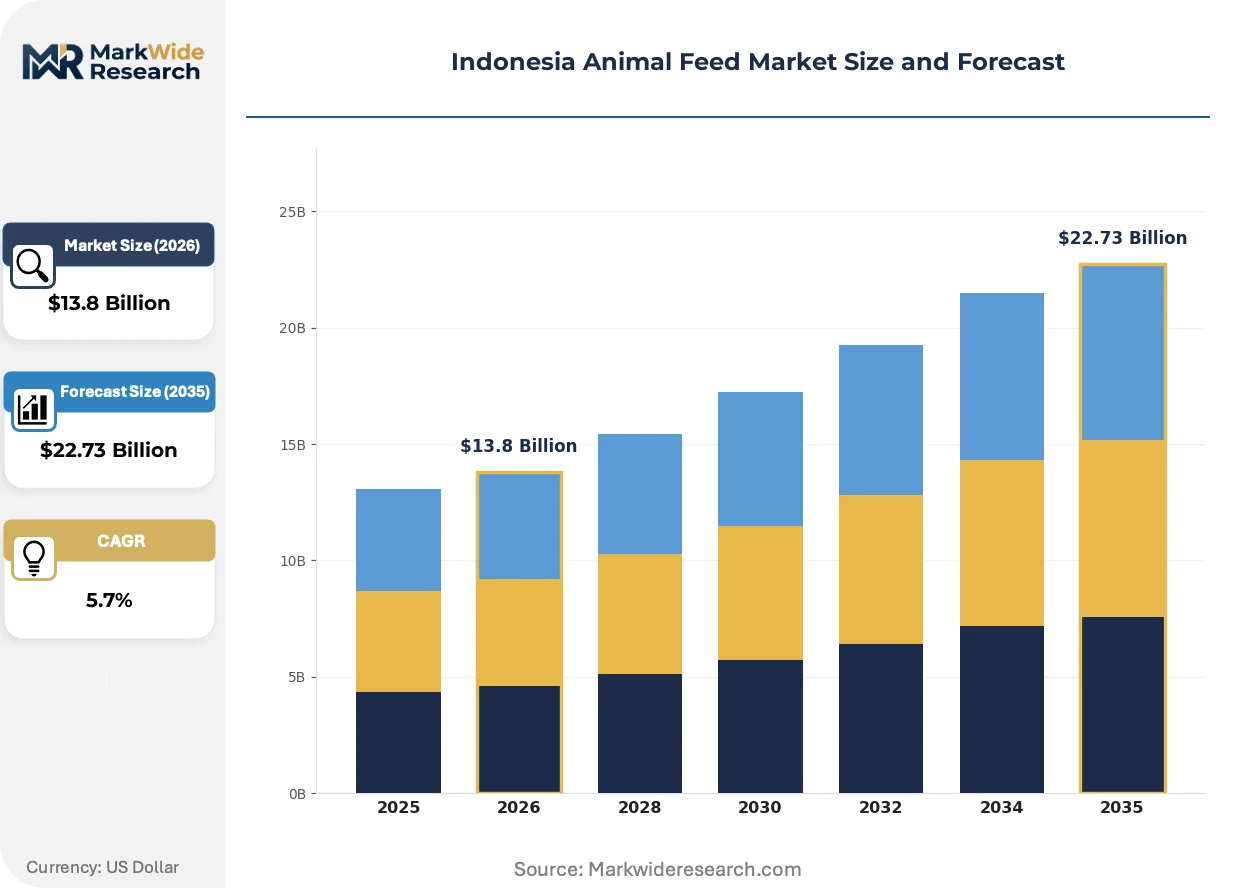
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Concentrate Feed, Supplementary Feed, Premix Feed Form: Pellets, Crumbles, Mash, Liquids Customer Type: Livestock Farmers, Poultry Farmers, Aquaculture Producers, Feed Distributors Distribution Channel: Online Retail, Wholesalers, Feed Mills, Local Stores |
| Companies Covered | CJ Indonesia, New Hope Group, Charoen Pokphand Indonesia, BASF SE, Cargill Indonesia, Japfa Comfeed Indonesia, Malindo Feedmill, Evonik Industries, Sierad Produce, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Animal Feed Market Strategic Shifts & Innovations
Digital feed formulation platforms and alternative protein sourcing are compressing traditional input dependencies while regulatory pressure on residue testing intensifies capital requirements for quality infrastructure.
Enzyme-supplemented feed additives are absorbing growing attention from broiler integrators seeking to unlock phosphorus and amino acid availability from plant-based ingredients. Large-scale operations in Central Java are piloting phytase and protease cocktails at commercial scale. This adoption is absorbing conventional mineral premix volumes while reducing environmental phosphate loading in manure management systems.
Indonesia's Ministry of Agriculture is tightening antibiotic residue surveillance through expanded BPOM coordination with provincial agricultural offices. Feed mills now face mandatory lot testing for banned growth promoters before distribution clearance. Broiler-focused formulators in East Java are responding fastest, deploying rapid diagnostic capabilities to preempt regulatory detention.
Smallholder farmers are consolidating purchasing through cooperative aggregation models that bypass traditional distributor markups. These collectives in West Java negotiate direct mill contracts for bulk complete feeds, displacing fragmented retail channel dependence. The shift concentrates procurement volume with fewer transaction counterparties, compressing working capital cycles for integrated suppliers serving this segment.
Indonesia Animal Feed Market Segmentation
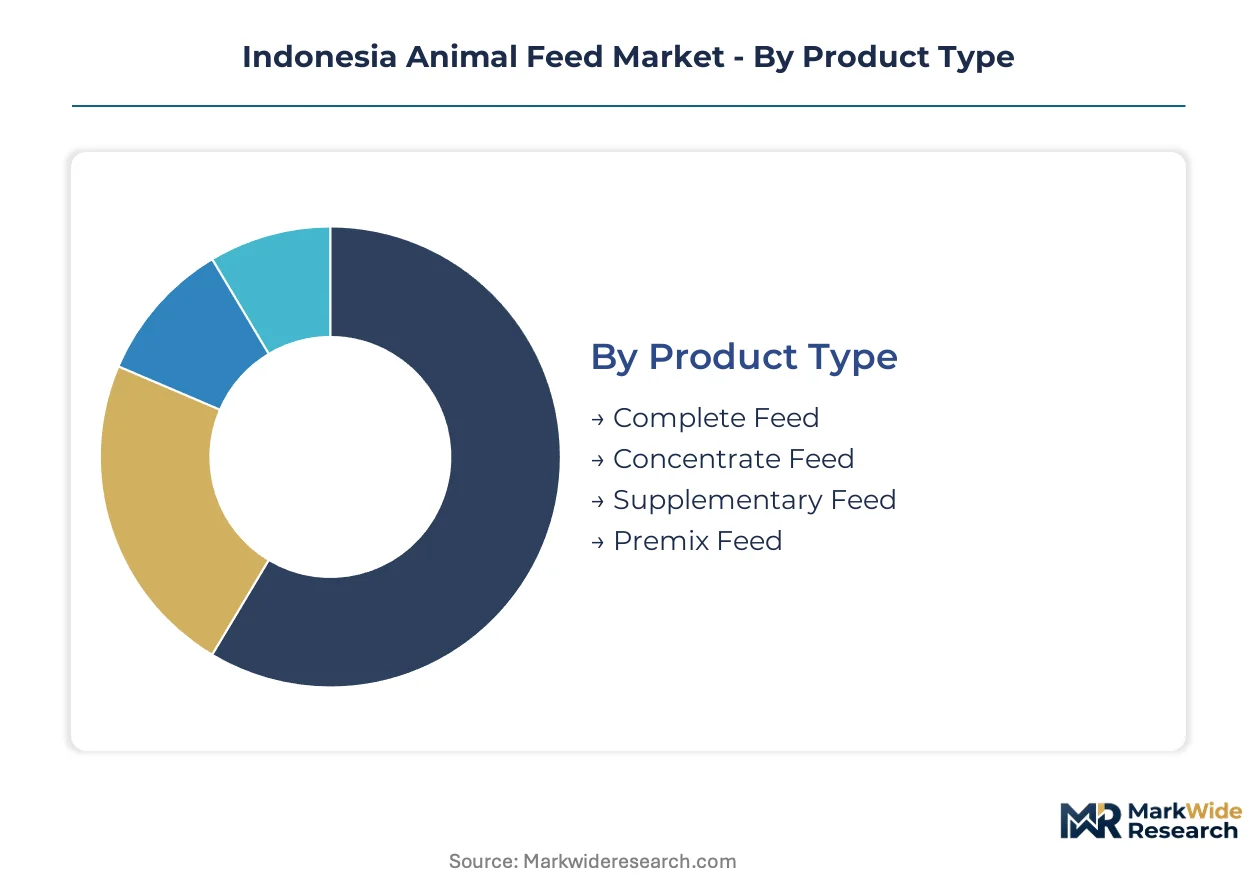
Indonesia's animal feed market fragments across formulation complexity, physical form, and buyer sophistication. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape supplier positioning across Java's integrated operations and outer island aquaculture frontiers.
Product Type:
Cost tier separates buyers in this category — large integrators absorb premium complete feeds while smallholders trade labor for savings through concentrates and premixes.
- Complete Feed:Nutritionally balanced rations containing 20-22% crude protein and 3,200 kcal/kg metabolizable energy, ready for direct consumption without supplementation. Procurement concentrates among East Java's integrated broiler farms under captive supply arrangements with Charoen Pokphand Indonesia and Japfa Comfeed Indonesia, driven by Ministry of Agriculture mycotoxin enforcement that disqualifies on-farm mixing. Volume sits with Complete Feed; growth tilts toward Premix Feed.
- Concentrate Feed:Protein-rich formulations requiring grain dilution at farm level, typically 35-40% crude protein content. Demand clusters in Central Java smallholder cooperatives that aggregate purchasing power to bypass distributor markups, constrained by formulation chemist scarcity that limits precise amino acid balancing.
- Supplementary Feed:Mineral and vitamin additives complementing basal rations for specific production stages. West Java dairy operations utilize these for lactation phase transitions.
- Premix Feed:Micro-ingredient blends containing trace minerals, vitamins, and enzymes at inclusion rates below 1%. Sulawesi shrimp producers are scaling premix adoption for precise pond management.
Margin compression is sharpest in Complete Feed; differentiation opportunities concentrate in Premix Feed enzyme formulations.
Form:
Application environment dictates physical form selection — intensive housing systems favor pellets while open-water aquaculture demands specialized extrusion.
- Pellets:Compressed cylindrical feeds produced through steam conditioning and die extrusion, reducing feed wastage by 15-20% compared to mash. East Java broiler integrators specify pellet durability indices above 95% for automated feeding systems, with demand reinforced by antibiotic growth promoter prohibitions that elevate feed conversion ratio sensitivity. Volume sits with Pellets; growth tilts toward Liquids.
- Crumbles:Broken pellet fragments sized for starter-phase poultry and juvenile shrimp. Kalimantan tilapia hatcheries specify crumbles for fry transition periods.
- Mash:Unpelletized ground mixtures retaining ingredient particle identity. Smallholder layer operations in West Java persist with mash for cost minimization despite higher labor requirements.
- Liquids:Suspension or solution formulations for medication delivery and precision aquafeeding. Papua's emerging shrimp frontier is piloting liquid additive systems for automated pond dosing.
Equipment lock-in favors Pellets among existing integrators; greenfield aquaculture sites are evaluating Liquids for labor substitution.
Customer Type:
Volume scale and technical sophistication create four distinct procurement profiles with diverging price elasticity and certification requirements.
- Livestock Farmers:Cattle and swine producers purchasing grower and finisher rations, with demand concentrating in North Sumatra's palm oil integration zones where plantation byproducts supplement commercial feeds. Procurement is shifting toward cooperative aggregation models that displace fragmented retail channel dependence.
- Poultry Farmers:Broiler and layer operations spanning integrated corporate farms and independent smallholders. East Java's feed mill corridor serves this segment through mill placements near corn and soybean meal transit routes, with BIS-equivalent national standards governing maximum aflatoxin levels. Volume sits with Poultry Farmers; growth tilts toward Aquaculture Producers.
- Aquaculture Producers:Shrimp and finfish farming operations in Sulawesi, Kalimantan, and Papua requiring species-specific protein-to-energy ratios. These buyers are expanding most quickly as intensive pond systems scale, with Malindo Feedmill targeting this segment through specialized aquaculture feed lines.
- Feed Distributors:Intermediary aggregators serving remote outer island markets lacking direct mill access. These channel players face compression as cooperative models consolidate procurement volume with fewer transaction counterparties.
Procurement consolidation is accelerating among Poultry Farmers; technical specification complexity is climbing fastest among Aquaculture Producers.
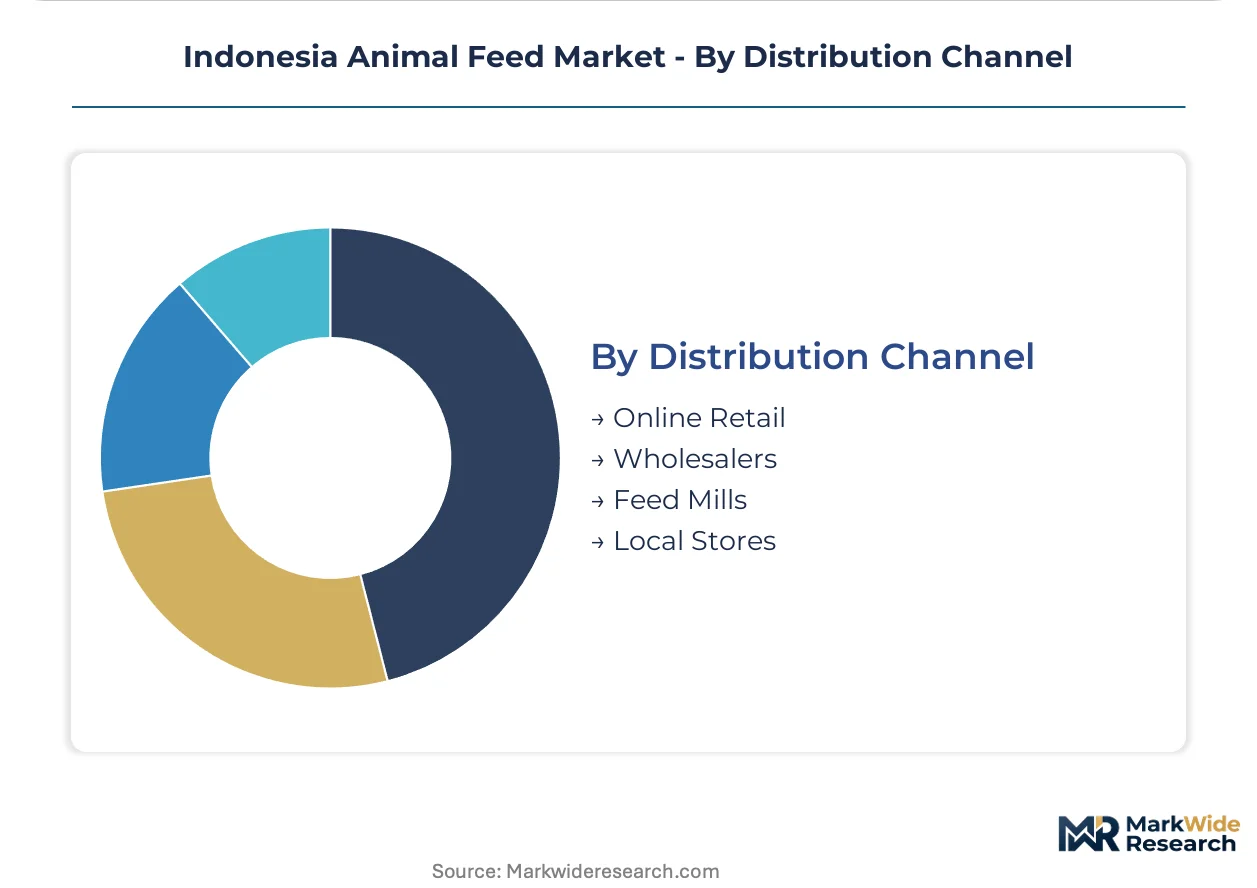
Distribution Channel:
Supply chain configuration determines working capital cycles and traceability system investments required for regulatory compliance.
- Wholesalers:Bulk aggregators handling 20-50 ton shipments from mill to sub-distributor or large farm gate. Surabaya and Jakarta terminals anchor this channel, with operations constrained by SNI accreditation timelines that delay market entry for new facility investments.
- Feed Mills:Direct mill-to-farm supply relationships predominant among East Java integrated operations. Charoen Pokphand Indonesia leverages its hatchery-to-slaughterhouse network to secure captive demand through this channel.
- Local Stores:Village-level retailers serving smallholder cash purchases in 25-50 kg bags. West Java cooperative aggregation is displacing this channel's historical dominance.
- Online Retail:Digital platforms for premix and additive ordering, currently nascent but absorbing interest from formulation chemists seeking direct ingredient sourcing.
Channel power is concentrating with Feed Mills; Online Retail is gaining share fastest among specialty additive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Java's corn-soybean transit corridors anchor Indonesia's feed production geography, with Surabaya's port infrastructure handling the bulk of imported protein inputs that supply mill clusters across Java and outer island distribution networks.
East Java
Integrated broiler farms and feed mill clusters dominate procurement volumes across Surabaya and Malang corridors. The Ministry of Agriculture enforces stricter mycotoxin limits under national feed safety standards, compelling commercial operations to upgrade formulation protocols. Charoen Pokphand Indonesia leverages its hatchery-to-slaughterhouse network to secure captive demand for formulated feeds throughout the province.
Central Java
Smallholder cooperatives aggregate purchasing power to bypass traditional distributor markups in Semarang and Yogyakarta hinterlands. BPOM coordination with provincial agricultural offices is tightening antibiotic residue surveillance through expanded lot testing mandates. Feed mills serving this segment face compressed working capital cycles as cooperative procurement concentrates volume with fewer transaction counterparties.
West Java
Dairy operations and layer farms utilize supplementary feeds for lactation phase transitions across Bandung and Bogor districts. SNI accreditation for feed safety management requires 12-18 month validation cycles that delay market entry for new facility investments. Local store networks historically serving village-level cash purchases face displacement as cooperative aggregation models consolidate procurement.
Sulawesi
Shrimp aquaculture expansion drives demand for nutritionally complete aquafeeds with precise protein-to-energy ratios across intensive pond systems in South Sulawesi. Malindo Feedmill targets this segment through specialized aquaculture feed lines. Papua's emerging shrimp frontier is piloting liquid additive systems for automated pond dosing, creating first-mover positioning opportunities.
Sumatra
North Sumatra's palm oil integration zones supply plantation byproducts that supplement commercial feeds for cattle and swine producers. Domestic corn supply deficits force mills to absorb import parity swings during El Niño harvest disruptions. Feed distributors serving remote outer island markets lacking direct mill access face channel compression as cooperative models consolidate procurement volume.
Indonesia Animal Feed Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue aquaculture specialization and enzyme formulation niches. The market exhibits tiered concentration with integrated poultry operators commanding captive supply arrangements while independent mills compete for spot-market liquidity. Three archetypes dominate: hatchery-integrated conglomerates, geography-anchored mill operators, and aquaculture-focused specialists. Competitive intensity centers on backward integration into protein input sourcing and geographic expansion toward underpenetrated outer island frontiers.
Among hatchery-integrated conglomerates, Charoen Pokphand Indonesia and Japfa Comfeed Indonesia exemplify scale-driven positioning through mill placements near corn and soybean meal transit routes. Malindo Feedmill occupies a specialist position within the aquaculture tier, representing differentiation through species-specific formulation capabilities. These three companies anchor the competitive structure, with their respective archetypes shaping procurement consolidation patterns across Java's integrated operations and outer island aquaculture development corridors.
| Leading Market Players |
|---|
| CJ Indonesia |
| New Hope Group |
| Charoen Pokphand Indonesia |
| BASF SE |
| Cargill Indonesia |
| Japfa Comfeed Indonesia |
| Malindo Feedmill |
| Evonik Industries |
| Sierad Produce |
| Others |
Cost & Logistics Intelligence
Formulation chemist scarcity in East Java's feed mill corridor widens labor-cost differentials between premium certified mills and economy-tier operators. These workforce gaps translate directly into pricing-tier spreads, as mills with in-house laboratory capabilities command substantial premiums over competitors dependent on external quality validation.
Pricing Analysis
Certification-bundling separates premium mills from unbundled economy suppliers, with SNI-accredited facilities wrapping lot-testing guarantees into contract terms while standard operators charge testing fees separately. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with integrated poultry operations locking in long-term offtake contracts. Cost compression in the economy tier is intensifying because smallholder cooperative aggregation concentrates procurement volume with fewer counterparties. Independent smallholders exhibit highest price sensitivity, captive integrators lowest.
Supply Chain Analysis
Return flows of rejected feed lots and mycotoxin-contaminated batches create reverse-logistics burdens that premium mills absorb through laboratory screening while economy operators face detention costs. Geographic supply concentration centers on the United States, Brazil, and Argentina for soybean meal, with domestic corn sourcing fragmented across Java and Sumatra. Raw material dependencies rest on imported protein inputs, domestic grain harvests, and enzyme additive premixes. Single-source vulnerability at Tanjung Priok and Surabaya port terminals creates bottleneck exposure. Distribution runs through direct mill-to-farm arrangements for integrated operations and wholesaler aggregators for cooperative smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's animal feed market functions as a supply-constrained environment where qualified formulation chemist scarcity props pricing premiums for certified mills. Capacity bottlenecks in laboratory infrastructure and SNI accreditation timelines constrain rapid supply response.
For Market Incumbents: Acquire in-house laboratory assets to preempt BPOM traceability mandates and lock in certification premiums before SNI validation timelines extend further. Consolidate backward integration into hatchery networks to secure captive demand against cooperative aggregation displacement. Channel control through direct mill-to-farm relationships represents the critical defensive lever against wholesaler compression. For New Entrants and Emerging Players: Launch via mobile mixing units or satellite facilities targeting Papua's aquaculture frontier, where local feed mill absence creates first-mover positioning. Sulawesi shrimp producers represent the most penetrable segment given species-specific formulation complexity that incumbent generalists under-serve. Direct digital procurement platforms for premix and enzyme sourcing offer the clearest go-to-market angle to bypass established distributor markups. For Investors and Strategic Acquirers: Re-rating potential sits with aquaculture-focused specialists given shrimp aquaculture expansion and technical specification complexity that commands margin premiums. Long-term viability favors mills with demonstrated enzyme formulation capabilities and traceability system investments ahead of anticipated BPOM chain-of-custody mandates. Watch for enforcement consistency shifts across provincial agricultural offices as the key inflection signal for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hatchery Networks | Charoen Pokphand Indonesia's captive demand model demonstrates volume security against cooperative aggregation. |
| In-House Laboratory Investment | BPOM lot-testing mandates favor mills with rapid diagnostic capabilities for preemptive regulatory clearance. |
| Specialized Aquaculture Feed Line Development | Malindo Feedmill's Sulawesi positioning captures shrimp producer demand for precise protein-to-energy ratios. |
| Enzyme Formulation R&D Partnership | Phytase and protease adoption by Central Java broiler integrators reduces environmental phosphate loading. |
| Satellite Facility Deployment | Papua's underdeveloped feed mill presence creates first-mover advantage for mobile mixing unit operators. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with feed mill operations directors, poultry farm procurement managers, aquaculture pond system operators, and Ministry of Agriculture provincial enforcement officers. Secondary sources included GPMT (Indonesian Feed Mill Association) production statistics, BPOM additive import permit databases, BPS agricultural trade records, and SNI accreditation registries. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates.
Data-stream reconciliation across production surveys, import manifests, and distribution channel audits informed the analytical framework. Segmentation dimensions spanned product type complexity, physical form specifications, customer sophistication tiers, and regional production clusters. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement trajectories and input cost volatility assumptions. Corn price elasticity and enzyme adoption curves served as industry-specific forecast inputs across the projection horizon.
El Niño harvest disruptions, Ministry of Agriculture enforcement consistency variations, and cooperative aggregation penetration rates are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory timeline adherence and protein input sourcing stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
North America Aloe Vera Market