
 Aviation Fuel Additives Market | 2026-2036
Aviation Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Fuel Additives Market Analysis
The customer base for aviation fuel additives is broadening beyond legacy full-service carriers to encompass low-cost airlines, cargo operators, and fixed-base operators managing private fleets. BASF SE leverages its global manufacturing footprint to supply antioxidant packages across multiple regulatory jurisdictions. Innospec Inc. specializes in military-grade formulations that meet stringent thermal stability requirements for defense applications. Afton Chemical Corporation anchors its position through deep relationships with major oil companies that control into-plane refueling infrastructure at hub airports.
Aviation fuel additives are chemical formulations blended into jet fuel at concentrations typically ranging from 5 to 300 parts per million to enhance thermal stability, prevent microbial contamination, and improve low-temperature operability. These additives perform critical functions including oxidation inhibition, corrosion protection, and ice crystal suppression during flight operations at altitude. Cold flow improvers command significant attention as operators extend routes into polar and high-altitude environments where wax crystallization threatens fuel system integrity. The application split reveals commercial aviation as the dominant consumption channel, while military aviation demands specialized biocide and antioxidant combinations that resist battlefield storage conditions. Delivery mode preferences are shifting toward on-site mixing systems at major hub airports, reducing logistics complexity for high-volume consumers.
ASTM International governs jet fuel additive specifications through D1655 and D7566 standards that determine market access for new chemistries in the United States. The European Union's REACH regulation and F-Gas framework constrain biocide formulations and cold flow additive chemistries deployed across EU member state airports. Military procurement channels operate under DEF STAN 91-91 and MIL-DTL-83133 specifications that create separate qualification pathways distinct from commercial aviation. Stakeholders must monitor evolving sustainability mandates from ICAO's Carbon Offsetting and Reduction Scheme as alternative aviation fuels gain regulatory traction and reshape additive compatibility requirements.
Market Dynamics
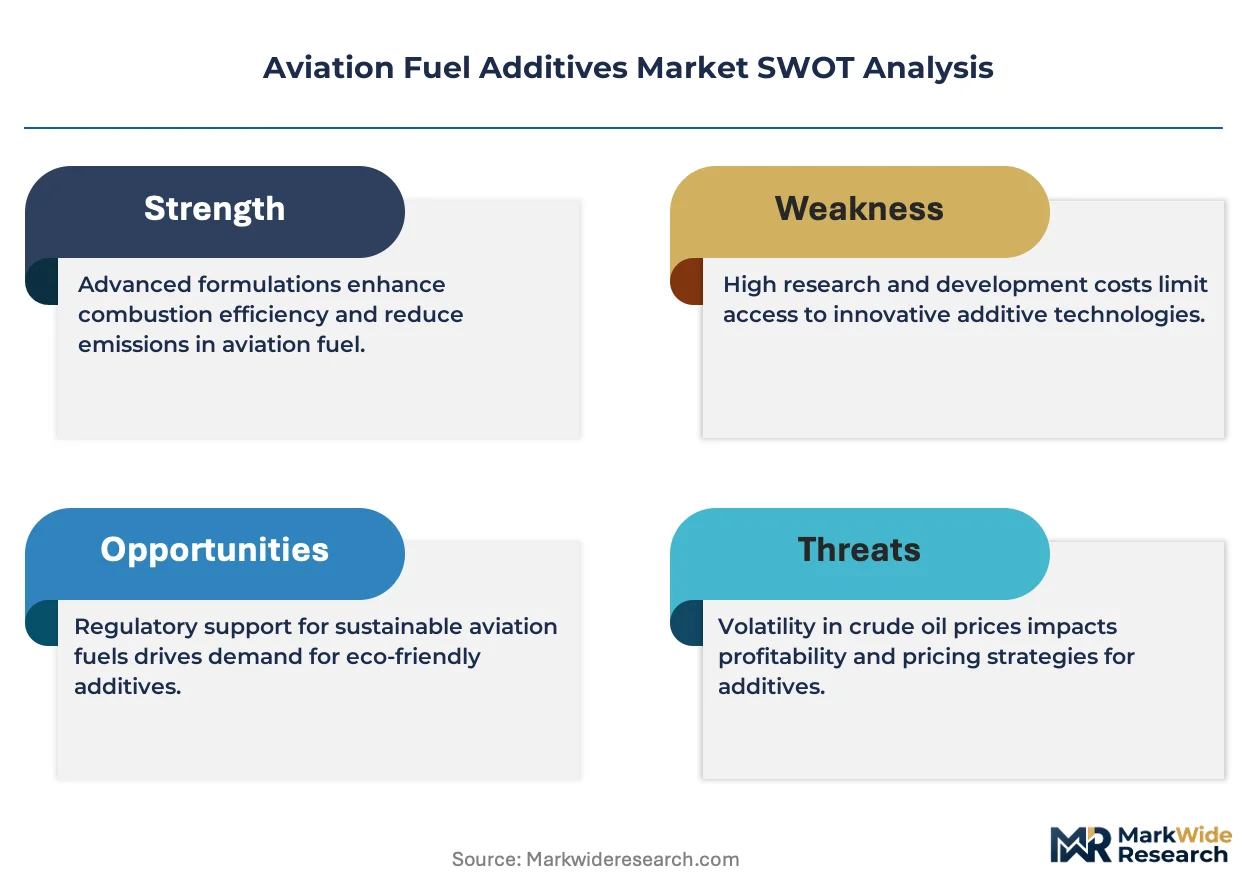
The aviation fuel additives sector is undergoing structural compression as sustainable aviation fuel (SAF) mandates force reformulation of antioxidant and detergent packages to maintain compatibility with hydroprocessed esters and fatty acids.
Growth Catalysts
- DEF STAN 91-91 military procurement:Defense aviation contracts are expanding additive volumes through NATO-aligned thermal stability specifications that mandate specialized antioxidant combinations for battlefield storage resilience.
- High-altitude airport expansion:China's civil aviation authority is accelerating cold flow improver approvals to support winter operations at airports above 2,500 meters elevation where wax crystallization threatens fuel system integrity.
- ASTM D7566 alternative fuel standards:Synthetic paraffinic kerosene pathways are creating additive compatibility testing demand as blend ratios increase in commercial jet fuel supply chains.
Market Restraints
- Naphtha feedstock volatility:Cold flow improver production depends on ethylene-vinyl acetate copolymers whose pricing tracks naphtha cracking economics in Northeast Asian petrochemical hubs.
- REACH biocide restrictions:ECHA's biocidal product regulation is constraining microbiocide formulations used in European Union airport fuel farms, forcing costly re-qualification of existing chemistries.
- Single-source antioxidant supply:Hindered phenol antioxidant precursors concentrate among three German chemical manufacturers, creating vulnerability in global aviation supply chains.
Strategic Opportunities
- India's DGFT import reclassification:Fuel system cleaner tariff restructuring is creating localized blending opportunities for domestic carriers seeking to reduce landed cost of finished additive packages.
- On-site mixing infrastructure:Hub airports in Singapore and Dubai are installing automated dosing systems that displace drum-based logistics for high-volume antioxidant and corrosion inhibitor delivery.
- ICAO CORSIA carbon accounting:Additive manufacturers can capture value from fuel efficiency claims as airlines seek verified drag reduction and combustion improvement credits under offsetting schemes.
Industry Challenges
- SAF-additive compatibility testing:Hydroprocessed renewable jet fuels exhibit divergent polarity profiles that destabilize existing detergent dispersant packages, requiring extended engine test cell validation timelines.
- Multi-jurisdiction qualification:Additive suppliers must maintain parallel ASTM D1655, DEF STAN 91-91, and Chinese GB 6537 certification streams with non-harmonized test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Fuel Additives Market |
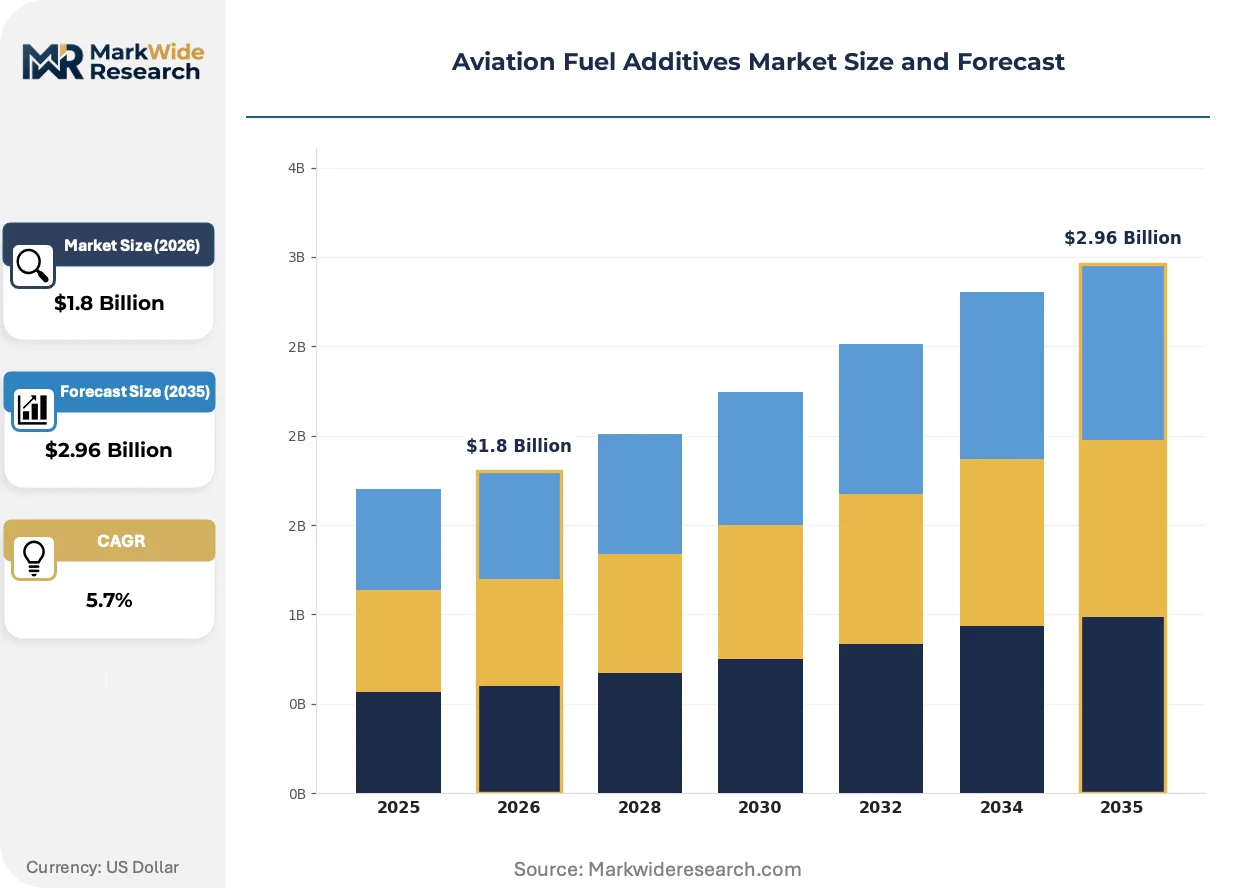
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Fuel System Cleaners, Biocides, Cold Flow Improvers Application: Commercial Aviation, Military Aviation, General Aviation, Helicopters Delivery Mode: Bulk Delivery, Packaged Delivery, On-Site Mixing, Mobile Units End User: Airlines, Private Jet Owners, Military Operators, FBOs |
| Companies Covered | Afton Chemical Corporation, BASF SE, Innospec Inc., Dorf Ketal Chemicals, Chevron Oronite Company LLC, Baker Hughes Company, The Lubrizol Corporation, Evonik Industries AG, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Fuel Additives Market Emerging Trajectories
Formulation science is pivoting toward molecular architectures that function across conventional jet fuel and emerging synthetic blends without separate qualification tracks.
Polymeric cold flow improvers is converging with machine learning-driven pour point prediction models. Major oil companies operating European hub airports are deploying these systems to optimize additive dosing rates in real-time based on temperature forecasting. This convergence is compressing the traditional laboratory-based qualification cycle for new fuel batches.
REACH F-Gas framework amendments are restricting fluorinated surfactants previously used in anti-icing additives. European fuel suppliers are reformulating with non-fluorinated alternatives that meet identical ASTM D4171 thermal stability benchmarks. Military aviation applications remain exempt, creating a bifurcated specification environment between NATO commercial and defense supply chains.
Carrier procurement functions are consolidating additive purchasing through integrated fuel supply agreements rather than standalone chemical contracts. Low-cost airlines operating Southeast Asian routes are leading this transition, bundling antioxidant and biocide costs into into-plane fuel pricing. This pattern is most visible in Indonesia and Vietnam where fuel farm infrastructure supports direct injection capabilities.
Aviation Fuel Additives Market Segmentation
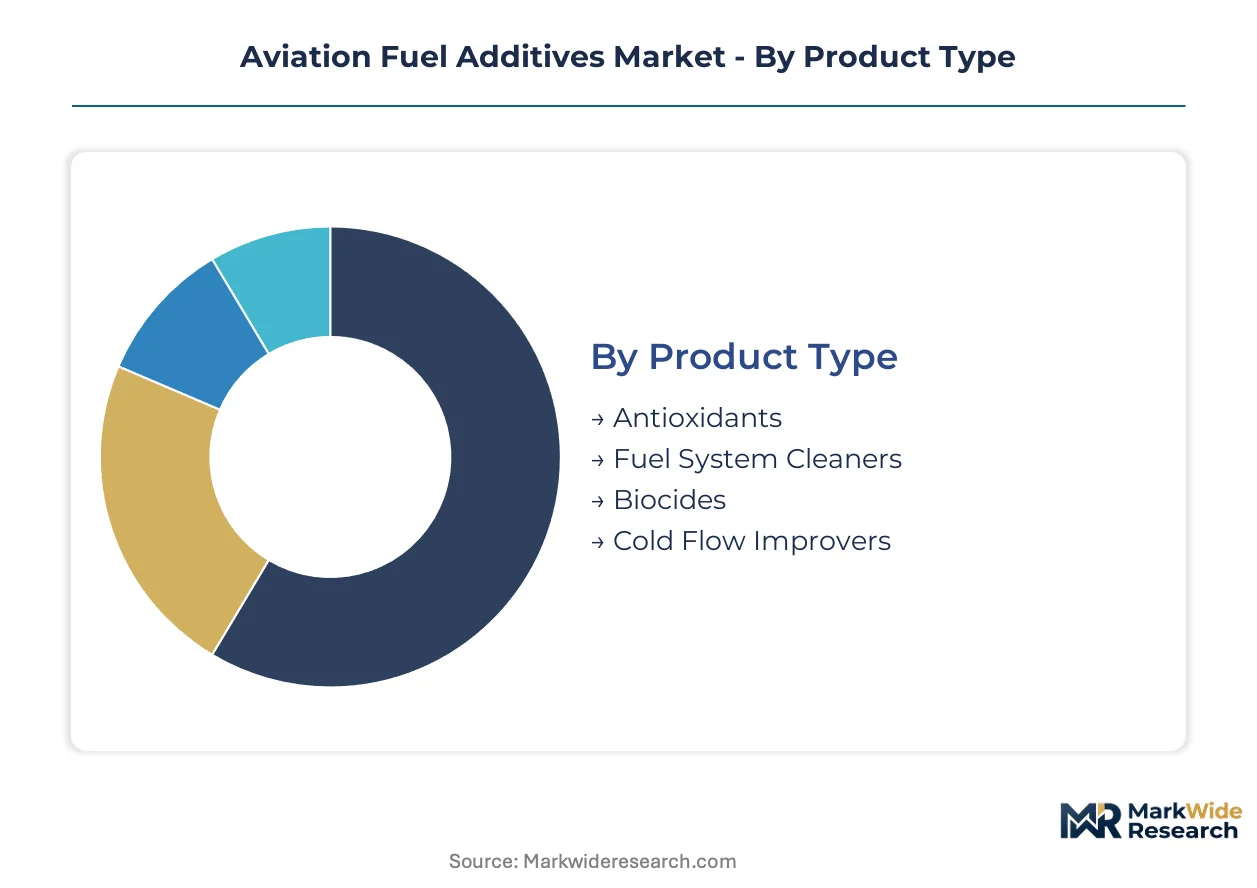
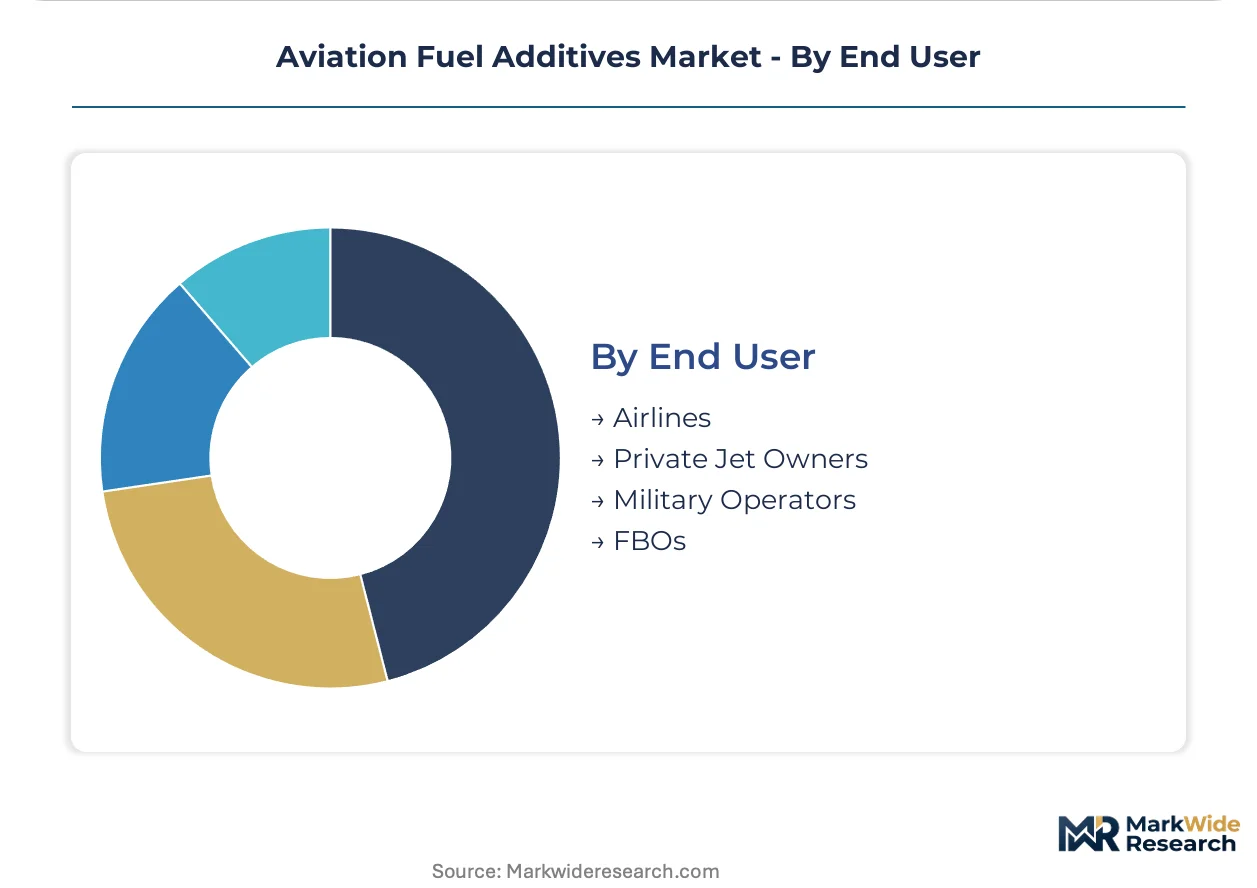
Aviation fuel additive procurement varies sharply by operational context, with commercial airlines demanding high-volume antioxidant packages while military operators prioritize battlefield storage resilience. Understanding these segment boundaries clarifies where formulation investments concentrate and which delivery infrastructures warrant capital deployment.
Product Type:
Certain additive chemistries operate as embedded components within finished jet fuel specifications, while others function as standalone remedial treatments applied at point of use.
- Antioxidants:Hindered phenol and aminic compounds inhibit oxidation at concentrations between 10 and 24 parts per million, preserving fuel thermal stability during extended storage. Full-service carriers operating trans-Pacific routes from Singapore and Dubai drive procurement volumes as extended flight cycles demand longer fuel residence times in aircraft tanks.
- Cold Flow Improvers:Ethylene-vinyl acetate copolymers and polymeric esters suppress wax crystallization, enabling operations below minus 40 degrees Celsius. China's civil aviation authority is accelerating approvals for these chemistries to support winter operations at high-altitude airports above 2,500 meters elevation where fuel gelling threatens system integrity.
- Fuel System Cleaners:Detergent-dispersant packages remove deposits from injector nozzles and fuel control units.
- Biocides:Microbiocidal formulations combat microbial contamination in airport fuel farm storage tanks.
Antioxidants lead volumes today; cold flow improvers are gaining share fastest.
Application:
Cost tier differentiation separates high-frequency scheduled operations from intermittent or specialized flight profiles, with per-flight-hour additive economics driving distinct procurement patterns.
- Commercial Aviation:Scheduled passenger and cargo carriers consume additive packages at scale through into-plane fueling agreements, with hub airports in India and Indonesia supporting direct injection infrastructure. India's DGFT import reclassification for fuel system cleaners is reshaping procurement patterns as domestic carriers seek localized blending to reduce landed costs.
- Military Aviation:Defense operators demand specialized antioxidant and biocide combinations meeting DEF STAN 91-91 thermal stability specifications for battlefield storage resilience. NATO-aligned procurement channels operate under qualification pathways distinct from commercial aviation, creating separate supply streams.
- General Aviation:Private and business aircraft operators purchase lower volumes through FBO retail channels.
- Helicopters:Rotary-wing platforms require tailored cold flow packages for hover operations in adverse weather.
Commercial aviation anchors current demand; military aviation exhibits the steepest expansion trajectory as defense budgets realign.
Delivery Mode:
Supply concentration around major petrochemical hubs favors certain logistics configurations over others, with infrastructure density determining viable delivery economics.
- On-Site Mixing:Automated dosing systems at hub airports displace drum-based logistics for high-volume antioxidant and corrosion inhibitor delivery. Singapore and Dubai have installed these systems to optimize additive dosing rates in real-time based on temperature forecasting.
- Bulk Delivery:Tanker truck and pipeline shipments serve major fuel farm operations with continuous consumption profiles.
- Packaged Delivery:Drum and tote containers reach smaller airports lacking dedicated blending infrastructure.
- Mobile Units:Truck-mounted mixing equipment provides contingency additive deployment for remote or emergency operations.
On-site mixing leads volumes today; mobile units are climbing the fastest as distributed operations multiply.
End User:
Customer maturity and technical sophistication vary, with integrated fuel procurement functions consolidating purchasing power among large operators while fragmented users accept premium pricing for convenience.
- Airlines:Network carriers and low-cost operators bundle additive costs into integrated fuel supply agreements rather than standalone chemical contracts. Southeast Asian budget carriers in Indonesia and Vietnam are leading this transition where fuel farm infrastructure supports direct injection capabilities.
- Military Operators:Defense procurement functions operate under MIL-DTL-83133 specifications with extended qualification timelines and sole-source supply constraints.
- Private Jet Owners:Individual aircraft operators purchase through FBO retail channels with limited price leverage.
- FBOs:Fixed-base operators aggregate demand across multiple private fleets, creating modest volume consolidation.
Airlines dominate current procurement; FBOs are expanding most quickly as private fleet activity recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent clusters in Germany's Ruhr region and China's Yangtze River Delta anchor the industry's technical development. These workforce concentrations support additive formulation laboratories and qualification testing facilities that serve airlines worldwide.
United States
The FAA governs jet fuel additive approvals under ASTM D1655 and D7566 specifications that determine market access for new chemistries. Military procurement through MIL-DTL-83133 creates parallel demand streams distinct from commercial aviation. Houston's petrochemical corridor hosts blending operations and technical service centers serving North American carriers.
China
China's civil aviation authority is accelerating cold flow improver approvals to support winter operations at high-altitude airports above 2,500 meters elevation. GB 6537 standards provide the domestic regulatory framework for additive qualification. The Yangtze River Delta concentration around Shanghai includes manufacturing facilities and airport fuel farm infrastructure at Pudong International Airport.
Germany
ECHA's REACH regulation and F-Gas framework constrain biocide formulations and cold flow additive chemistries deployed across EU member state airports. Three German chemical manufacturers concentrate hindered phenol antioxidant precursor production. The Cologne-Düsseldorf industrial corridor maintains technical centers for additive formulation and engine test cell validation.
India
DGFT import reclassifications for fuel system cleaners are reshaping procurement patterns as domestic carriers seek localized blending to reduce landed costs. The BIS maintains fuel quality standards that reference ASTM specifications with local adaptations. Maharashtra's Mumbai-Pune industrial zone hosts distribution infrastructure serving domestic airline hubs.
Singapore
Changi Airport's automated dosing systems displace drum-based logistics for high-volume antioxidant and corrosion inhibitor delivery. The country's national standards body aligns with ASTM and DEF STAN specifications for regional trade facilitation. Jurong Island's petrochemical complex supports additive manufacturing and into-plane fueling infrastructure for Southeast Asian routes.
Aviation Fuel Additives Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the aviation fuel additives sector. The market structure shows moderate consolidation around petrochemical majors and specialized chemical manufacturers with aviation-specific qualifications. Three archetypes dominate: global diversified chemical conglomerates with aviation divisions, specialized fuel additive pure-plays with deep regulatory expertise, and oil company captive suppliers controlling into-plane infrastructure. Competitive moves center on qualification streamlining across multiple jurisdictions and on-site mixing infrastructure deployment at hub airports.
Among the diversified chemical conglomerates, BASF SE leverages global manufacturing footprints to supply antioxidant packages across regulatory jurisdictions. Innospec Inc. and Afton Chemical Corporation exemplify the specialized pure-play archetype, with the former occupying a position in military-grade formulations and the latter anchoring relationships with major oil companies controlling refueling infrastructure. These three companies represent distinct strategic postures: geographic breadth, defense specialization, and supply chain integration.
| Leading Market Players |
|---|
| Afton Chemical Corporation |
| BASF SE |
| Innospec Inc. |
| Dorf Ketal Chemicals |
| Chevron Oronite Company LLC |
| Baker Hughes Company |
| The Lubrizol Corporation |
| Evonik Industries AG |
| LANXESS AG |
| Others |
Supply Flow & Price Mechanics
Specialized chemical conglomerates with aviation divisions anchor supply-side ownership patterns, concentrating antioxidant precursor production among three German manufacturers and enabling coordinated pricing discipline across ASTM D1655 and DEF STAN 91-91 qualified product tiers. This ownership concentration permits margin defense through volume commitments from major oil companies controlling into-plane infrastructure, while bundling additive costs into integrated fuel supply agreements compresses price transparency for low-cost carriers in Southeast Asia.
Pricing Analysis
The bundled-versus-unbundled service split separates pricing structures across customer archetypes, with network carriers negotiating contract-based long-term offtake through into-plane agreements while fixed-base operators absorb per-unit transactional premiums for drum-based packaged delivery. Price differentiation centers on certification grade—DEF STAN 91-91 military specifications command substantial premiums over commercial ASTM tiers—and volume scale, as hub airports with automated dosing infrastructure secure preferential rates. Pricing pressure stems from India's DGFT import reclassification for fuel system cleaners, which intensifies cost compression in localized blending channels. Low-cost airlines exhibit highest price sensitivity due to thin operating margins, while military procurement functions demonstrate lowest sensitivity given sole-source supply constraints and extended qualification timelines.
Supply Chain Analysis
Direct-to-airline channels through major oil company fuel farm operators handle hyperscale demand from network carriers at Dubai and Singapore hub airports, displacing traditional drum logistics with real-time dosing systems. Geographic supply concentrates in Germany for hindered phenol antioxidant precursors, China for ethylene-vinyl acetate cold flow improver polymers, and the United States for corrosion inhibitor packages. Raw material dependencies draw from naphtha cracking economics in Northeast Asian petrochemical hubs, hindered phenol feedstocks from Ruhr region chemical manufacturers, and specialty amine compounds from Gulf Coast refiners. Single-source vulnerability in antioxidant precursor supply creates structural risk, as three German manufacturers control global output. Distribution runs through oil company captive networks at major airports, supplemented by regional chemical distributors serving secondary markets lacking direct injection infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cold flow improver segments, where China's high-altitude airport expansion and SAF compatibility testing requirements enable premium pricing for qualified formulations. Cost-down potential emerges from on-site mixing infrastructure deployment, which eliminates drum logistics and reduces per-unit delivery overhead for high-volume consumers.
For Market Incumbents: Deploy qualification streamlining investments to compress parallel ASTM D1655, DEF STAN 91-91, and Chinese GB 6537 certification timelines, defending share against emerging pure-play specialists. Deepen backward integration into hindered phenol precursor production to reduce exposure to German chemical manufacturer supply concentration. Channel control through exclusive into-plane infrastructure agreements at expanding hub airports in India and Indonesia anchors volume retention against oil company captive suppliers. For New Entrants and Emerging Players: India's DGFT import reclassification opens a window for localized blending operations serving domestic carriers seeking landed cost reduction on fuel system cleaners. Target cold flow improver supply to China's civil aviation authority approval queue, where high-altitude airport expansion creates demand acceleration outside established incumbent relationships. Pursue military-grade formulation partnerships with NATO-aligned procurement channels operating under DEF STAN 91-91 specifications, where qualification barriers deter commodity competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking automated dosing infrastructure but holding airport fuel farm relationships convertible to on-site mixing deployments. Long-term viability favors additive manufacturers with demonstrated SAF compatibility testing capabilities, as hydroprocessed renewable jet fuel blend ratios rise across commercial aviation. Watch ICAO CORSIA carbon accounting methodology revisions as the signal for fuel efficiency claim monetization opportunities in antioxidant and drag reduction additive categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive supply of hindered phenol antioxidants from German chemical manufacturers reduces single-source vulnerability. |
| On-Site Mixing Infrastructure Deployment | Automated dosing systems at Changi Airport and Dubai International displace drum logistics for high-volume carriers. |
| SAF Compatibility Testing Investment | Extended engine test cell validation for hydroprocessed renewable jet fuel formulations captures emerging blend ratio demand. |
| Military Qualification Streamlining | Parallel DEF STAN 91-91 and MIL-DTL-83133 certification paths access NATO defense procurement expansion. |
| Localized Blending Joint Venture | DGFT tariff restructuring partnerships in India reduce landed costs for domestic airline fuel system cleaner procurement. |
Methodological Framework
Bottom-up airline procurement modeling reconciled against top-down additive manufacturing capacity tracking forms the analytical core of this study. Primary interviews with fuel procurement managers at network and low-cost carriers, technical directors at oil company fuel farm operators, regulatory affairs leads at additive manufacturers, and distribution channel partners in Southeast Asia and India combined with secondary validation from ASTM International specification documents, ECHA REACH biocidal product regulation filings, customs trade data from DGFT and Chinese General Administration of Customs, and SEC 10-K disclosures from listed chemical conglomerates. Triangulation across these sources ensures volume estimates reflect actual into-plane consumption rather than manufacturer shipment data alone.
Historical trendline analysis of antioxidant, cold flow improver, and biocide consumption patterns across commercial and military aviation established baseline growth trajectories. The projection framework models segmentation dimensions including product type chemistry, application channel, delivery mode infrastructure tier, and end-user procurement sophistication, with CAGRs derived from elasticity-adjusted demand curves across the analysis window. Industry-specific forecast inputs incorporate China's civil aviation authority approval velocity for high-altitude airport additives and ICAO CORSIA carbon offset accounting methodology evolution.
Revisions become necessary when SAF mandate acceleration, REACH biocide restriction expansion, or military procurement realignment materialize outside modeled scenarios. Forecasts reflect assumptions regarding sustained naphtha feedstock availability, continued ASTM-DEF STAN specification harmonization, and stable oil company into-plane infrastructure control. Periodic stress-testing of base assumptions against regulatory filing patterns and airline fleet expansion announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Smart Gas Solutions Market
Fuels
Germany Bunker Fuel Market
Fuels
Global Turbine Oil Market
Fuels
Turbine Drip Oil Market
Fuels
Heavy Fuel Oil Market
Fuels
India Petrol Station Market
Fuels
Italy Chemical Logistics Market
Fuels
Aviation Fuel Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Oil Dispenser Market
Fuels
Solid Recovered Fuel Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
China Bunker Fuel Market