
 LNG As a Fuel Market | 2026-2036
LNG As a Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
LNG As a Fuel Market Foresight
Conventional marine fuel oil is shifting toward LNG bunkering as sulfur content regulations tighten and price spreads favor gas-to-liquid substitution. Royal Dutch Shell leverages its integrated LNG supply chain to dominate European and Asian bunkering corridors. TotalEnergies anchors its position through long-term offtake agreements with major shipping lines. China National Petroleum Corporation competes on domestic infrastructure scale along China's coastal manufacturing belt.
LNG as a fuel denotes liquefied natural gas cooled to minus 162 degrees Celsius for storage and transport, then vaporized for combustion in modified dual-fuel engines or gas turbines. Marine applications lead adoption due to International Maritime Organization emission mandates and port infrastructure buildout, while power generation segments sustain growth through grid balancing and coal displacement strategies. Cryogenic tank technology occupies the highest margin pool due to specialized materials and vacuum insulation requirements, though vaporization systems extend fastest as small-scale distribution networks proliferate. Direct sales channels dominate utility and industrial contracts, yet truck loading differentiates service levels for remote mining and manufacturing sites.
The International Maritime Organization enforces MARPOL Annex VI sulfur caps that mandate LNG compatibility for vessels calling at major ports. The EPA regulates stationary source emissions from LNG-fired power generation under Clean Air Act frameworks, while China's MEE enforces dual carbon goals that accelerate coal-to-gas switching in industrial heating. Stakeholders must monitor regulatory timing divergence between marine fuel mandates and power sector decarbonization schedules to align capital deployment with enforcement windows.
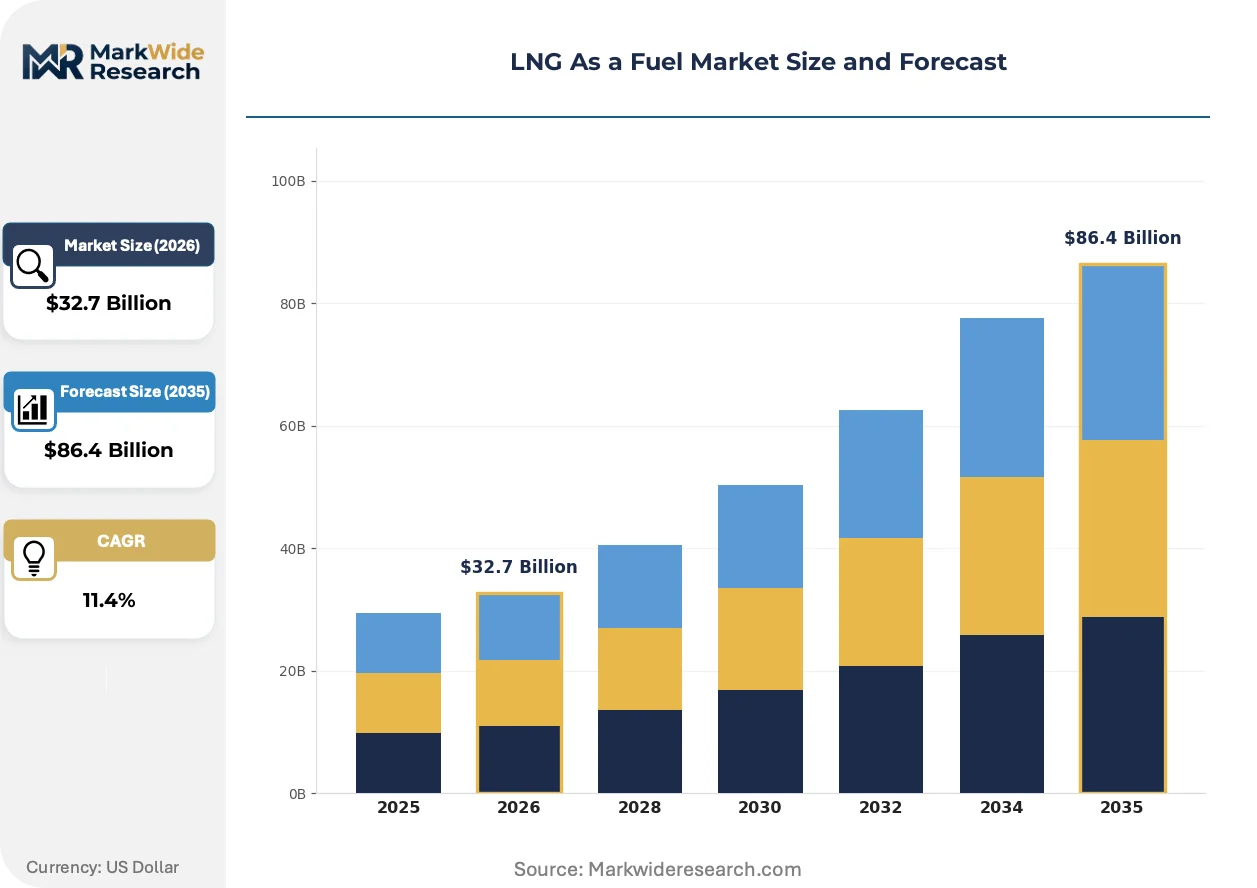
Market Dynamics
The International Maritime Organization's MARPOL Annex VI sulfur regulations are compressing marine fuel substitution timelines, forcing vessel operators to commit capital to LNG bunkering infrastructure ahead of enforcement deadlines.
Growth Catalysts
- IMO MARPOL Annex VI sulfur caps:The regulation mandates maximum 0.5% sulfur content in marine fuels, eliminating conventional heavy fuel oil for most oceangoing vessels and creating immediate LNG compatibility requirements at major bunkering hubs.
- Dual-fuel engine technology:Wärtsilä and MAN Energy Solutions have commercialized marine engines capable of seamless fuel switching, removing operational risk for shipping lines evaluating LNG adoption.
- Asian port corridor buildout:Singapore, Shanghai, and Busan are constructing dedicated LNG bunkering terminals with simultaneous vessel-to-ship transfer capabilities, concentrating demand along the world's busiest container routes.
Market Restraints
- Cryogenic storage material costs:Specialized nickel-alloy steels and vacuum insulation systems for minus 162 degree Celsius containment carry 3-4x capital intensity versus conventional fuel tanks, compressing project returns.
- Bunkering infrastructure concentration:European and East Asian suppliers control 80% of global LNG bunkering vessel capacity, creating supply security concerns for operators in South America and Africa.
- Methane slip technical limitation:Unburned methane emissions from dual-fuel engines partially offset CO2 benefits, exposing operators to emerging lifecycle GHG regulations in the EU and California.
Strategic Opportunities
- India coastal manufacturing belt:Jawaharlal Nehru Port and Mundra Port lack LNG bunkering infrastructure despite handling 40% of India's container traffic, presenting first-mover terminal development positions.
- Power generation grid balancing:Peaker plants in Texas and Germany are retrofitting for LNG to displace coal during renewable intermittency events, creating demand outside marine applications.
- EU Green Deal Fit for 55 package:The regulation's FuelEU Maritime initiative imposes well-to-wake GHG intensity limits from 2025, accelerating demand for biomethane and synthetic LNG blending.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized welders and insulation technicians for vacuum-jacketed piping command 40% wage premiums, constraining project execution timelines.
- Type C tank certification complexity:Bureau Veritas and DNV classification societies maintain divergent pressure vessel standards, forcing redundant testing for globally trading vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG As a Fuel Market |
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $86.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Marine, Power Generation, Industrial Heating, Heavy-Duty Vehicles Distribution Channel: Direct Sales, LNG Terminals, Pipelines, Truck Loading End User: Utilities, Shipping Companies, Manufacturing, Oil & Gas Technology: Cryogenic Tank, Regasification Units, Vaporization Systems, LNG Carriers |
| Companies Covered | Royal Dutch Shell, ExxonMobil Corporation, TotalEnergies, BP, Chevron Corporation, QatarEnergy, Cheniere Energy, ConocoPhillips, China National Petroleum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG As a Fuel Market Shifts & Advancements
Marine propulsion technology is pivoting from fuel flexibility toward dedicated gas optimization, while regulatory frameworks harden around lifecycle emissions accounting rather than point-source pollution alone.
Membrane containment systems for Type B LNG tanks are consolidating as the dominant architecture for newbuild containerships. Mediterranean Shipping Company and CMA CGM have specified GTT Mark III technology for 24,000 TEU vessels under construction at Korean yards. The technology is consolidating market share by reducing cargo space sacrifice versus earlier spherical designs, compressing rival containment approaches to niche applications.
The EU FuelEU Maritime regulation introduces binding well-to-wake GHG intensity reduction requirements escalating through 2050. Vessel operators must now account for upstream methane leakage and liquefaction energy inputs, not solely stack emissions. European short-sea shipping routes face immediate compliance pressure, accelerating demand for biomethane certificates and synthetic methane offtake agreements.
Shipping lines are unbundling fuel procurement from vessel charter contracts, creating independent LNG bunkering procurement desks. Container operators now negotiate direct supply agreements with portfolio players rather than accepting bundled fuel from shipowners. This pattern is most visible on Asia-Europe trades where CMA CGM and Maersk have established dedicated marine fuel trading functions in Singapore.
LNG As a Fuel Market Segmentation
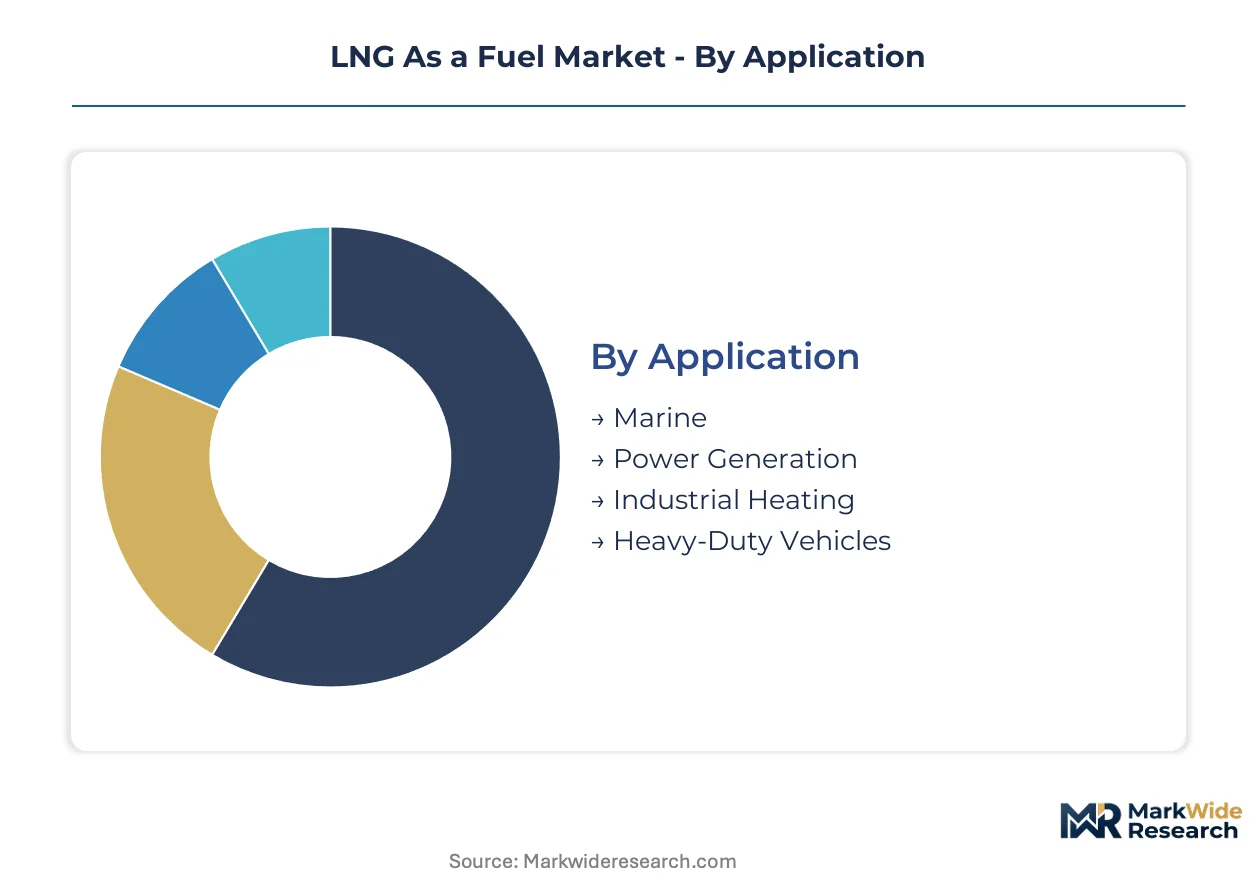
LNG as a fuel market segmentation reveals how marine bunkering concentrates revenue while industrial heating and power generation diversify demand. Technology splits separate high-margin cryogenic containment from commoditized distribution infrastructure. Understanding these fault lines exposes where capital deployment earns premium returns versus commodity compression.
Application:
Marine bunkering commands volume leadership through IMO regulatory mandates, while power generation and industrial segments compete on margin through grid balancing and coal displacement economics.
- Marine:Deep-sea vessels and short-sea shipping routes consume LNG bunkering at Singapore, Shanghai, and Rotterdam terminals. IMO MARPOL Annex VI sulfur caps eliminate heavy fuel oil compatibility, forcing fleet operators to contract LNG supply ahead of enforcement windows.
- Power Generation:Peaker plants in Texas and Germany retrofit turbines for LNG combustion to manage renewable intermittency. Grid operators value rapid ramp rates and lower CO2 intensity versus coal baseload, though methane leakage accounting under EU regulations complicates environmental claims.
- Industrial Heating:Steel and cement manufacturers in China's coastal provinces switch from coal to LNG under MEE dual carbon enforcement.
- Heavy-Duty Vehicles:Long-haul trucking corridors in California and Germany pilot LNG refueling for freight decarbonization.
Today's leader: Marine. Tomorrow's challenger: Power Generation.
Distribution Channel:
Direct sales anchor utility-scale contracts with volume certainty, while truck loading and terminal access differentiate service tiers for remote industrial sites and maritime bunkering flexibility.
- Direct Sales:Portfolio players negotiate long-term offtake agreements with shipping lines and power utilities. These contracts bundle supply security with price indexation, locking in baseload volumes across multi-year tenors.
- LNG Terminals:Import facilities at Rotterdam, Singapore, and Shanghai offer break-bulk services for small-scale distribution. Terminal operators monetize storage capacity and send-out flexibility during demand spikes.
- Pipelines:Dedicated LNG vaporization and pipeline injection serves power generation clusters in Germany and Japan.
- Truck Loading:Cryogenic tanker trucks deliver to mining sites and manufacturing plants beyond pipeline reach.
Direct sales dominate contract value. Truck loading expands addressable geography fastest.
End User:
Shipping companies drive technology roadmaps through dual-fuel engine specifications, while utilities and manufacturing segments compete on procurement scale and delivery reliability.
- Utilities:Grid operators in Germany and Texas contract LNG for peaker plant dispatch during renewable shortfalls. Procurement desks prioritize interruptible supply terms and rapid response capabilities over long-term price locks.
- Shipping Companies:Container lines and bulk operators specify LNG-compatible newbuilds at Korean and Chinese yards. CMA CGM and Mediterranean Shipping Company have established dedicated marine fuel trading functions to unbundle bunkering from vessel charters.
- Manufacturing:Steel and chemical producers in China and India source LNG for process heat under emissions compliance pressure.
- Oil & Gas:Upstream operators consume LNG for drilling power and remote facility fuel.
Shipping companies set technical standards. Utilities scale procurement volume.
Technology:
Cryogenic containment captures the highest margin pool through specialized materials and vacuum engineering, while vaporization systems commoditize as small-scale distribution networks proliferate.
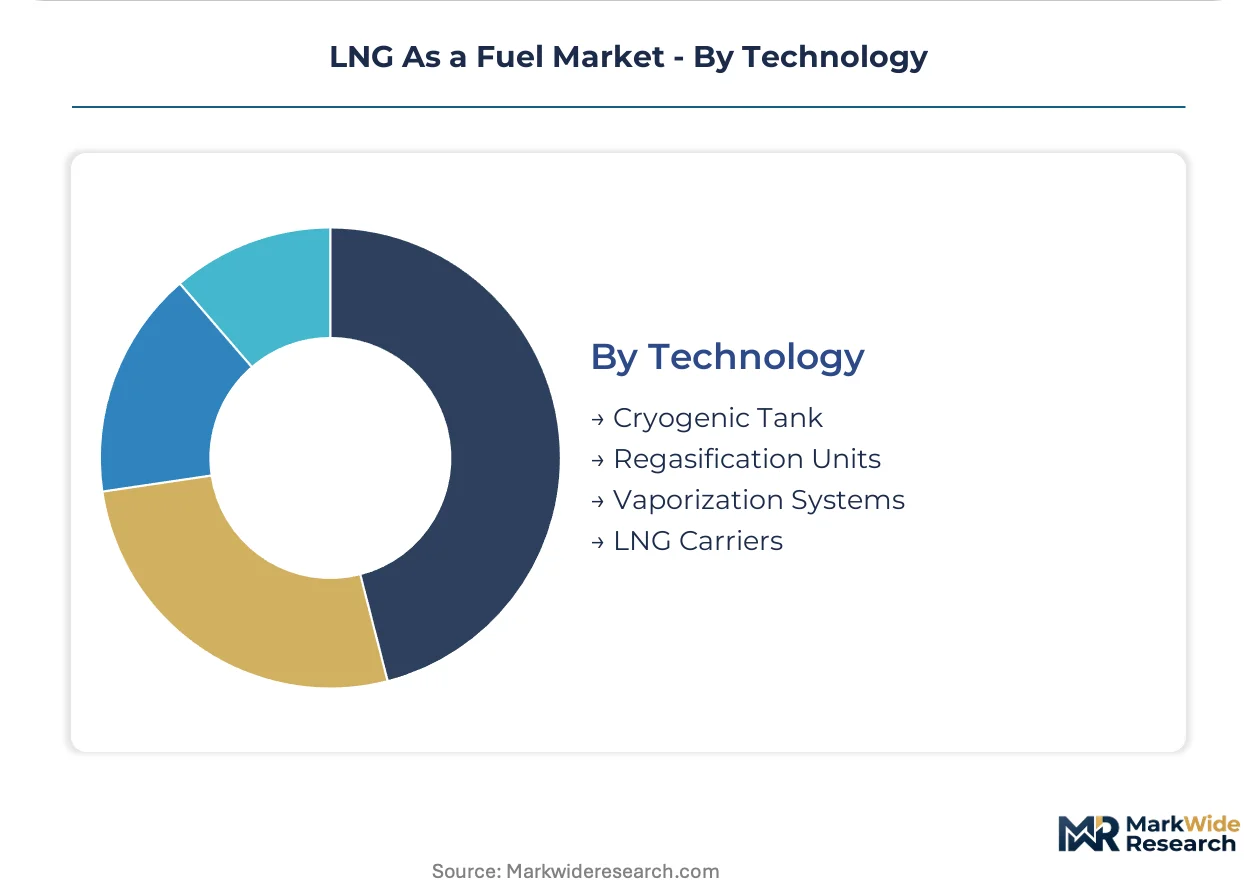
- Cryogenic Tank:Type C pressure vessels and GTT membrane systems store LNG at minus 162 degrees Celsius. Nickel-alloy steels and vacuum insulation command 3-4x capital intensity versus conventional fuel tanks, creating barrier-to-entry margins for certified fabricators.
- Vaporization Systems:Ambient air and submerged combustion units convert LNG to gaseous fuel for pipeline injection or direct combustion. Modular skid-mounted designs reduce installation timelines for remote power and industrial sites.
- Regasification Units:Onshore and floating terminals process import cargoes for grid injection.
- LNG Carriers:Specialized vessels transport liquefied cargo between production and consumption markets.
Cryogenic tanks defend margin concentration. Vaporization systems face price pressure from replication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's port corridor anchors LNG bunkering infrastructure buildout, with vessel-to-ship transfer capabilities concentrating demand along Asia's busiest container routes. The city-state's Maritime and Port Authority mandates LNG-ready terminal specifications ahead of IMO enforcement windows.
Singapore
Jurong Island's integrated energy cluster supports LNG storage and bunkering operations for deep-sea vessels. The Maritime and Port Authority requires LNG-compatible infrastructure at new terminal developments. Tuas Port expansion incorporates dedicated LNG bunkering berths for 24,000 TEU containerships.
China
Shanghai's Yangshan Port and Ningbo-Zhoushan anchor LNG bunkering demand along the Yangtze River Delta manufacturing belt. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate coal-to-gas switching in coastal provinces. Guangdong's Pearl River Delta terminals process import cargoes for industrial heating applications.
Germany
Wilhelmshaven and Brunsbüttel terminals serve North Sea shipping routes and grid balancing peaker plants. The EU Green Deal's FuelEU Maritime initiative imposes well-to-wake GHG intensity limits from 2025. Hamburg's port authority contracts LNG supply for short-sea shipping along Baltic corridors.
United States
Texas Gulf Coast export terminals and California's Long Beach port anchor North American LNG fuel demand. The EPA regulates stationary source emissions from LNG-fired power generation under Clean Air Act frameworks. Houston's energy trading desks structure long-term offtake agreements with container shipping lines.
South Korea
Busan Port's LNG bunkering infrastructure serves Korean shipyards constructing dual-fuel newbuilds. The Ministry of Trade, Industry and Energy supports LNG adoption through port development subsidies. Ulsan's industrial cluster consumes LNG for petrochemical process heat under emissions compliance pressure.
LNG As a Fuel Market Competitive Landscape
Global majors compete with regional champions across integrated supply chain control, with European and Asian portfolio players dominating bunkering corridors while national oil companies anchor domestic infrastructure. The market structure concentrates around vertically integrated energy majors capable of spanning liquefaction, shipping, and terminal operations. Three archetypes prevail: integrated majors with global LNG portfolios, national oil companies with captive domestic demand, and independent terminal operators specializing in small-scale distribution. Competitive moves center on long-term offtake contracting and strategic port terminal concessions.
Within the integrated major tier, Royal Dutch Shell and TotalEnergies exemplify portfolio breadth across European and Asian bunkering corridors. China National Petroleum Corporation anchors the national oil company archetype through domestic infrastructure scale along China's coastal manufacturing belt. Among independent terminal specialists, Cheniere Energy occupies a position focused on North American export capacity and Gulf Coast supply origination.
| Leading Market Players |
|---|
| Royal Dutch Shell |
| ExxonMobil Corporation |
| TotalEnergies |
| BP |
| Chevron Corporation |
| QatarEnergy |
| Cheniere Energy |
| ConocoPhillips |
| China National Petroleum Corporation |
| Others |
Supply & Pricing Matrix
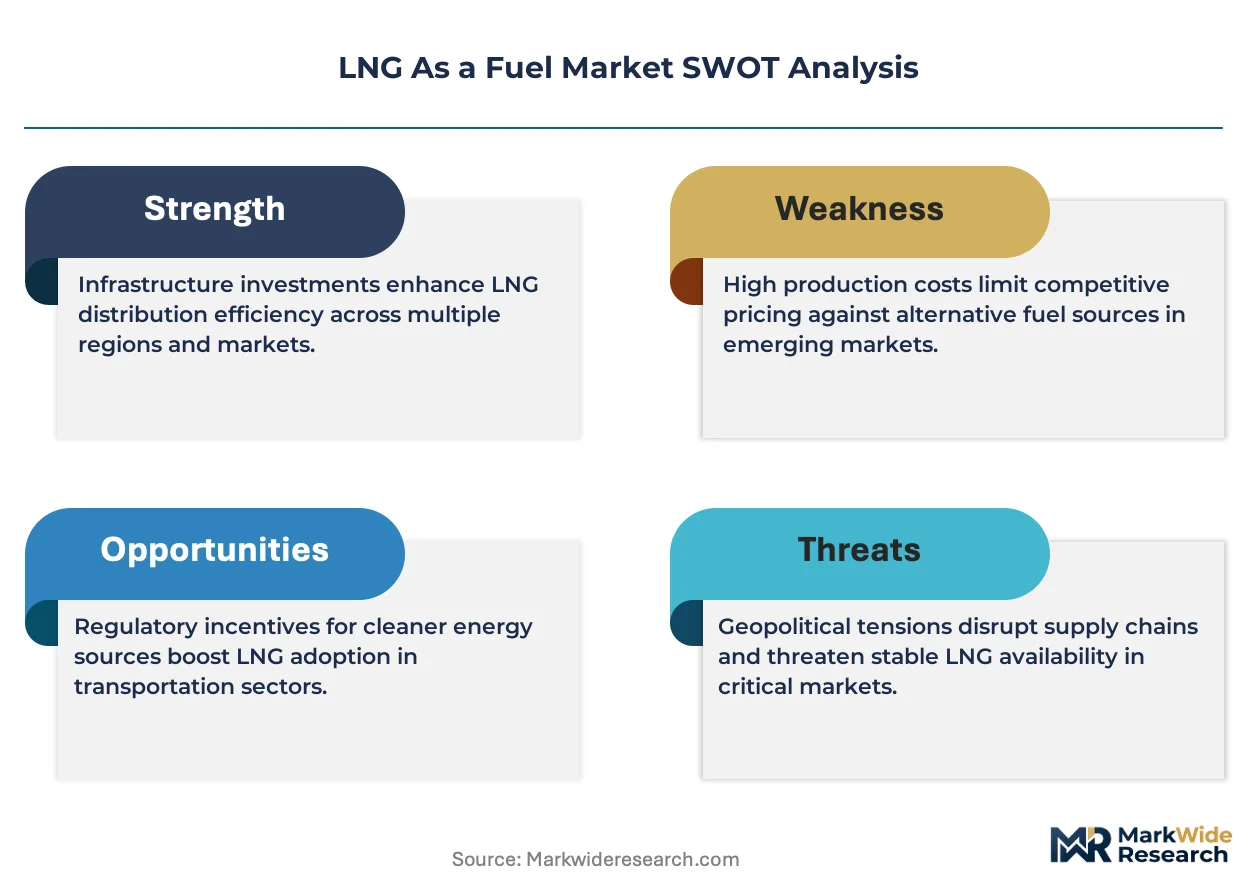
Nickel-alloy steel costs for cryogenic containment flow from specialty metallurgy producers through three pricing tiers that separate membrane tank fabricators from Type C pressure vessel manufacturers and commoditized vaporization skid assemblers.
Pricing Analysis
Input-cost pass-through from liquefaction energy and specialized welding labor drives contract-based long-term offtake structures that dominate marine bunkering procurement. Price differentiation hinges on certification grade from Bureau Veritas versus DNV classification societies and volume scale commitments from container shipping lines. Cost compression in standard vaporization skids is intensifying because modular designs replicate across Asian fabrication yards. Small-scale industrial buyers exhibit highest price sensitivity, while integrated shipping companies with dedicated trading desks leverage procurement scale for preferential terms.
Supply Chain Analysis
Dual-sourcing requirements from major shipping lines mandate qualification of both Korean and Chinese tank fabricators for membrane containment systems. Supply concentrates in South Korea, China, and Japan for cryogenic engineering, with France and Norway anchoring classification and certification services. Raw material dependencies span nickel-alloy steels from specialty mills, vacuum insulation materials, and precision cryogenic valves. Single-source vulnerability concentrates in membrane technology licensing from GTT. Distribution runs through dedicated LNG bunkering vessels and terminal break-bulk services at Singapore, Rotterdam, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European FuelEU Maritime enforcement creates compliance cost premiums that Asian-flag operators can avoid through Singapore bunkering corridors.
For Market Incumbents: Deploy long-term offtake contracting to lock in shipping line relationships ahead of IMO enforcement windows. Deepen backward integration into cryogenic tank fabrication through Korean yard partnerships to defend margin position against modular vaporization competitors. Address methane slip technical limitations through engine technology R&D to preempt EU lifecycle GHG regulations.
For New Entrants and Emerging Players: Launch via small-scale terminal access at Jawaharlal Nehru Port and Mundra Port to capture India's coastal manufacturing belt before infrastructure buildout. Target power generation grid balancing in Texas and Germany where peaker plant retrofits create procurement demand outside marine bunkering saturation. Pursue biomethane certificate trading as a differentiated service layer under FuelEU Maritime blending mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic engineering talent scarcity constrains project execution timelines for independent terminal operators. Long-term viability favors vertically integrated portfolio players spanning liquefaction, shipping, and bunkering infrastructure over pure-play distribution specialists. Monitor EU methane leakage accounting rules as the signal to watch for valuation inflection across dual-fuel engine manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Shell and TotalEnergies anchor European bunkering corridors through multi-year shipping line contracts with price indexation clauses. |
| Capacity Buildout | Singapore's Tuas Port expansion incorporates dedicated LNG bunkering berths for 24,000 TEU containerships under MPA mandates. |
| Technology Licensing | GTT Mark III membrane systems consolidate market share by reducing cargo space sacrifice versus spherical tank designs. |
| Backward Integration | CNPC leverages domestic infrastructure scale along China's coastal manufacturing belt to control terminal access. |
| Green Certification Program | FuelEU Maritime's well-to-wake GHG intensity limits accelerate demand for biomethane certificates and synthetic methane blending. |
Research Methodology
Coverage spans Singapore, China, Germany, the United States, and South Korea, with primary inputs from each combining interviews with marine fuel procurement managers, LNG terminal operators, EPC contractors, and classification society surveyors. Secondary validation draws from IMO MARPOL submissions, port authority development plans, EIA liquefaction data, and FERC export terminal filings. Bottom-up project pipelines and top-down regulatory mandate timelines were triangulated to establish market sizing.
Rate-of-change decomposition separated volume growth from price trajectory across marine bunkering, power generation, and industrial heating applications over the projection horizon. Segmentation dimensions modeled include application type, distribution channel, end-user archetype, and technology tier. CAGRs were derived from enforcement timeline analysis for IMO sulfur caps and EU FuelEU Maritime phases, cross-referenced with vessel orderbook data from Korean and Chinese yards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory timing divergence between marine fuel mandates and power sector decarbonization schedules. Forecasts reflect assumptions regarding dual-fuel engine adoption curves and port infrastructure completion timelines. Deviation in EU methane leakage accounting stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Smart Gas Market
Fuels
Italy Chemical Logistics Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
China LNG Bunkering Market
Fuels
Wood Charcoal Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Industrial Fuel Filter Market
Fuels
Storage Tank Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Diesel Fuel Water Separator Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Australia Coal Market
Fuels
Fuel Grinder Market
Fuels
Global Methane Hydrate Market
Fuels
LPG Gas Cylinder Market
Fuels
Coal Gasification Market