
 Europe Food Spread Market | 2026-2036
Europe Food Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Spread Market Foresight
CE marking under the EU Food Information to Consumers Regulation is unwinding competitive access for non-compliant importers. Ferrero International S.A. leverages its hazelnut supply chain to dominate the premium segment across Southern Europe. Unilever PLC anchors its position through deep retail distribution in the United Kingdom and Benelux markets. Nestlé S.A. differentiates via R&D intensity in reduced-fat and functional spread formulations.
Europe food spreads comprise semi-solid edible preparations formulated from dairy fats, vegetable oils, nuts, or emulsified blends, processed through churning, homogenization, or roasting-and-grinding to achieve spreadable viscosity at ambient temperatures; their primary commercial purpose is to deliver flavor, fat content, and convenience to bread-based consumption occasions. The product-type dimension shows butter and cream cheese commanding mature margin pools in Northern Europe, while plant-based spreads within the ingredient-source category are capturing the fastest volume growth as German and Dutch retailers expand shelf space for dairy alternatives. Chunky and flavored textures in the texture dimension sustain premium pricing in artisanal channels, whereas squeeze-bottle packaging in the packaging-type dimension is displacing tubs in convenience-oriented households across France and Spain.
EFSA nutrition and health claims standards, EU Green Deal agricultural targets, and national trans-fat caps under REACH-aligned food safety frameworks collectively constrain formulation choices and compel label transparency across member states. ECHA scrutiny of pesticide residues in nut supply chains further tightens procurement requirements for peanut butter and hazelnut spread producers. Stakeholders must monitor evolving CSRD disclosure obligations on Scope 3 agricultural emissions and decide whether to absorb compliance costs or restructure supplier networks toward certified sustainable oilseed and dairy operations.
Market Dynamics
EFSA clean-label guidelines are pressuring reformulations across the continent, forcing manufacturers to strip artificial additives and disclose processing methods while maintaining shelf stability and taste profiles that European consumers expect from breakfast spreads.
Growth Catalysts
- EU Green Deal agricultural targets:Subsidies for sustainable oilseed cultivation are expanding raw material availability for plant-based spreads in Germany and the Netherlands.
- German breakfast-table pivot:Households in Europe's largest economy are systematically replacing dairy fats with nut and vegetable oil alternatives, creating volume pull through retail channels.
- High-pressure processing:Cold-pasteurization technology is extending clean-label product shelf life without synthetic preservatives, unlocking distribution reach for artisanal producers.
Market Restraints
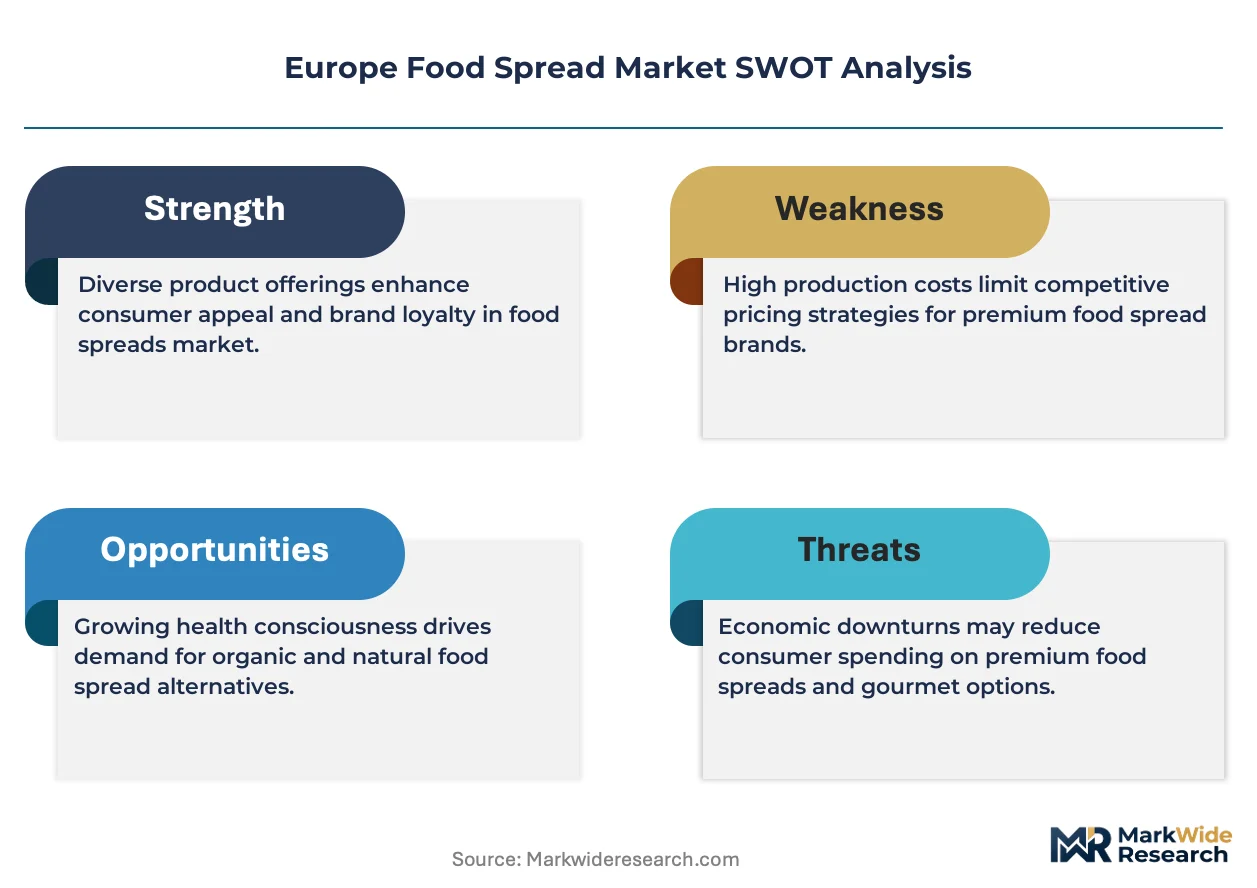
- Hazelnut supply concentration:Turkish and Italian orchards dominate raw nut inputs, exposing spread manufacturers to climate-driven crop volatility and price spikes.
- REACH-aligned trans-fat caps:National food safety frameworks are banning partially hydrogenated oils, forcing costly reformulation of legacy recipes and production line retooling.
- Palm oil substitution economics:Certified sustainable alternatives command 15-40% premia, compressing margins for mid-tier producers unable to pass costs to price-sensitive consumers.
Strategic Opportunities
- CSRD Scope 3 disclosure mandates:Early compliance with agricultural emissions tracking requirements positions suppliers as preferred partners for carbon-accounting retailers.
- Polish and Romanian modern trade:Underpenetrated discount and convenience channels in these expansion markets offer first-mover shelf space for value-positioned spread brands.
- Squeeze-bottle convenience formats:Portion-control packaging is capturing commuter and single-person household segments in France and Spain where tub formats dominate.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists capable of replacing synthetic emulsifiers with natural alternatives command premium compensation, constraining mid-cap development pipelines.
- ECHA pesticide residue compliance:Nut supply chain testing and certification timelines are extending procurement cycles, forcing inventory carry costs or supplier switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Spread Market |
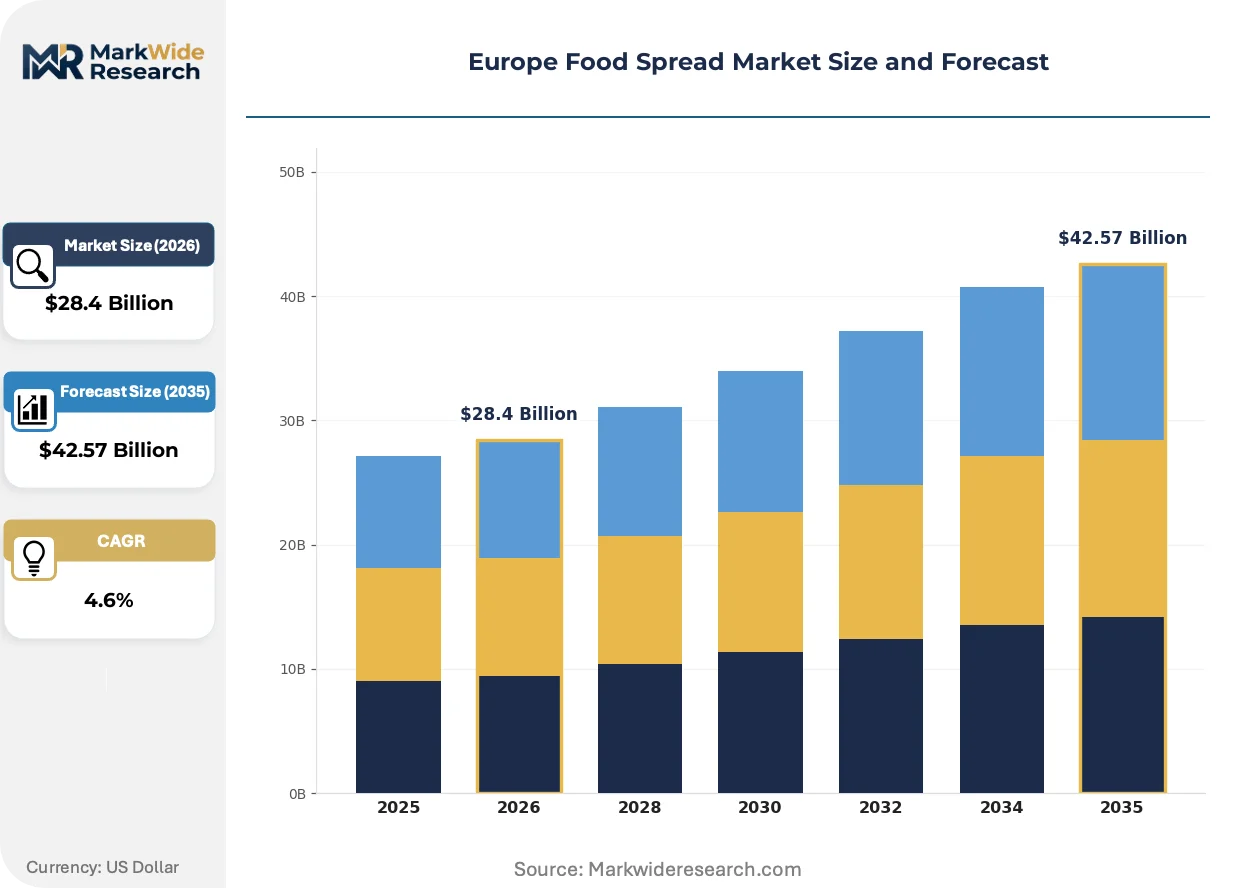
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $42.57 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Cream Cheese, Peanut Butter Ingredient Source: Dairy, Nut-Based, Plant-Based, Animal Fat Texture: Chunky, Smooth, Flavored, Unsweetened Packaging Type: Tub, Jar, Squeeze Bottle, Pouch |
| Companies Covered | Unilever PLC, Hero Group, Ferrero International S.A., Orkla ASA, Andros Group, Nestlé S.A., Kraft Heinz Company, The Hershey Company, Lindt & Sprüngli AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Spread Market Shifts & Advancements
Reformulation science and packaging engineering are converging to resolve the central tension between clean-label purity and mass-market shelf stability, with regulatory pressure accelerating investment cycles across European manufacturing facilities.
High-pressure processing equipment is miniaturizing from industrial-scale systems to modular units suitable for mid-tier co-manufacturers. Regional spread producers in Belgium and Austria are adopting these compact systems to launch clean-label lines without capital-intensive facility builds. The technology is miniaturizing barriers to entry, fragmenting premium segment supply away from consolidated multinationals toward agile specialists.
EFSA nutrition and health claims standards are tightening evidentiary requirements for functional spread positioning. Manufacturers must now submit clinical trial data to support immunity or digestive health messaging, elevating regulatory affairs staffing and documentation costs. Reduced-fat and fortified variants face the steepest compliance burden, with several brands withdrawing borderline claims rather than funding substantiation studies.
Breakfast consumption patterns are fragmenting across generational lines, with younger households in urban France and Italy treating spreads as snack and dessert ingredients rather than bread toppings. This pivot is compressing traditional volume channels while expanding premium positioning opportunities through recipe collaboration content and cross-category placement with baking mixes. Retailers are responding with dedicated "flexible occasion" shelf sets that merge spreads with adjacent categories.
Europe Food Spread Market Segmentation
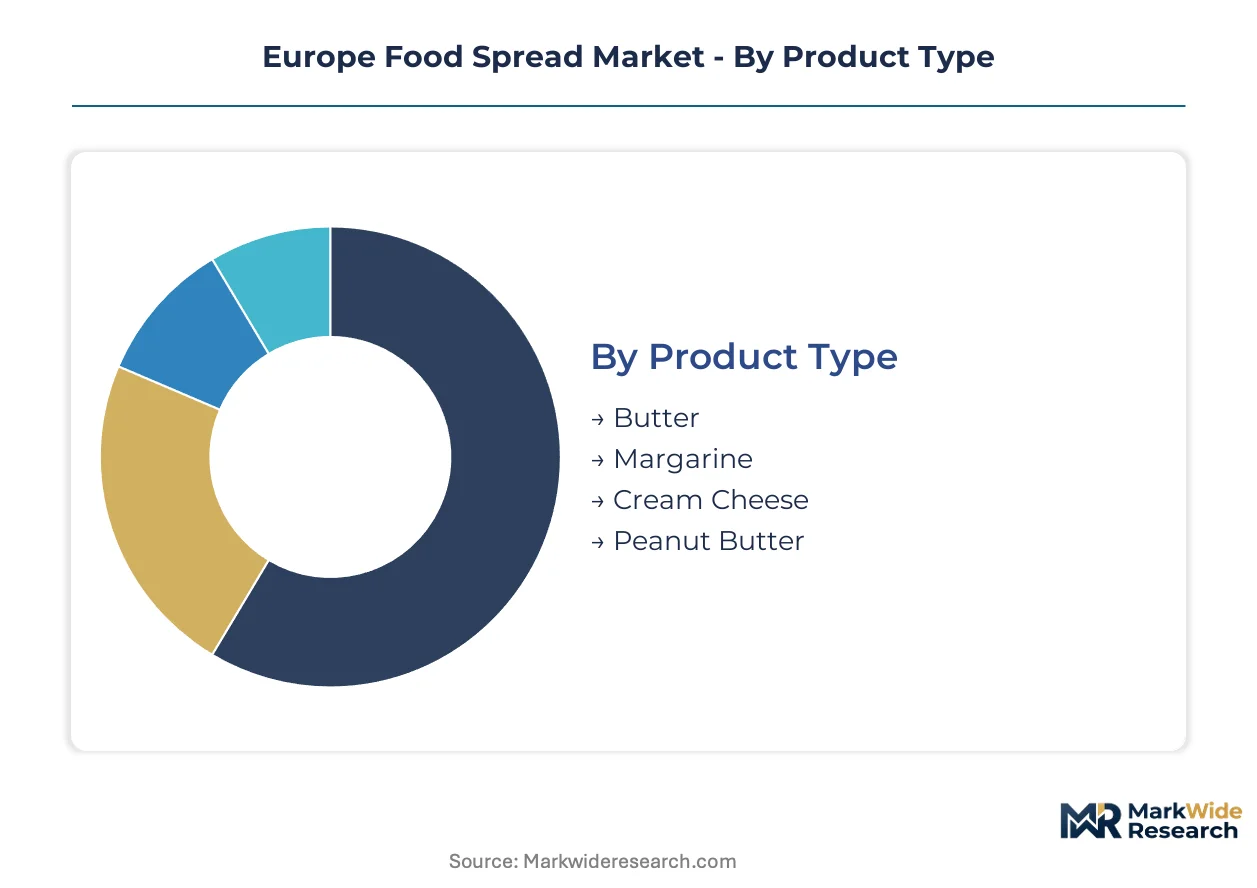
Spread manufacturers across Europe navigate divergent regulatory pressures and consumption rituals that reshape how product lines are architected. Segmentation decisions determine whether brands capture margin in premium artisanal channels or volume in discount retail. The analysis examines four structural dimensions that govern competitive positioning.
Product Type:
EFSA nutrition claims standards apply unevenly across dairy and plant-based formulations, creating compliance cost tiers that favor incumbents with regulatory affairs infrastructure.
- Butter:Churned dairy fat with minimum 80% milkfat content under EU dairy standards. Northern European households in Germany and Denmark sustain volume through traditional breakfast rituals, though REACH-aligned trans-fat scrutiny is forcing reformulation of blended spreads containing butter fractions.
- Margarine:Emulsified vegetable oil and water mixture with fat content ranging from 10% to 90%. German retailers are expanding private-label margarine shelf space as plant-based demand accelerates, yet palm oil substitution economics compress margins for mid-tier producers.
- Cream Cheese:Fresh acid-coagulated cheese with spreadable texture and 33% milkfat standard. Bagel and bakery channels in the United Kingdom and Netherlands concentrate demand.
- Peanut Butter:Roasted peanut paste with optional stabilizers and sweeteners. ECHA pesticide residue compliance extends procurement cycles for nut supply chains.
Established volume favors butter; emerging adoption favors margarine.
Ingredient Source:
Cost-to-produce spreads stratify across certification requirements, with organic and sustainable oilseed premiums reaching 40% above conventional inputs.
- Dairy:Milkfat and milk protein derivatives from bovine sources. French and Italian per-capita consumption remains highest for premium cultured butter variants.
- Nut-Based:Hazelnut, almond, and peanut preparations with roasted-and-ground processing. Turkish and Italian orchard concentration exposes supply chains to climate volatility.
- Plant-Based:Vegetable oil emulsions from sunflower, rapeseed, and olive sources. German breakfast-table pivot is systematically displacing dairy fats with these alternatives.
- Animal Fat:Rendered lard and tallow formulations, primarily in Eastern European traditional recipes. Polish and Romanian discount channels sustain residual demand.
Plant-based spreads are climbing the fastest as EU Green Deal subsidies expand sustainable oilseed cultivation.
Texture:
Processing intensity and equipment configuration determine which texture variants manufacturers can produce profitably at scale.
- Chunky:Coarse particle suspension with visible nut or fruit fragments. Artisanal channels in Belgium and Austria command premium pricing for small-batch production.
- Smooth:Homogenized particle size below 50 microns for uniform spreadability. Mass-market retail across France and Spain depends on this format for family consumption.
- Flavored:Infused with chocolate, honey, or spice inclusions. High-pressure processing technology is extending clean-label shelf life without synthetic preservatives.
- Unsweetened:No added sugars under EFSA nutrition claims standards. Health-positioned variants face steepest evidentiary burden for functional messaging.
Smooth textures dominate volume throughput; chunky variants gain share fastest in premium positioning.
Packaging Type:
Format selection shapes distribution economics and consumption occasion targeting across household structures.
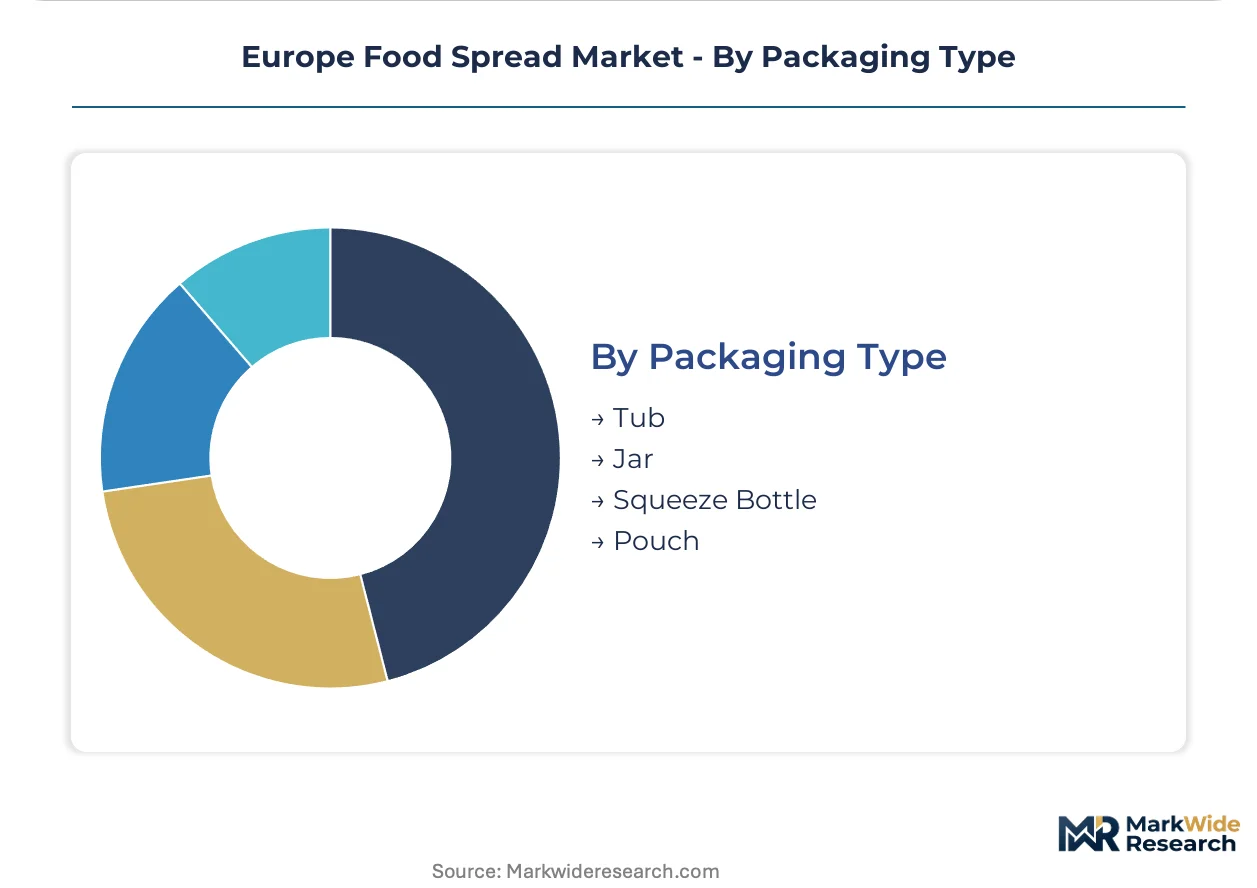
- Tub:Rigid plastic or paperboard containers with resealable lids. Traditional family-size format retains dominance in Benelux and Scandinavian markets.
- Jar:Glass or PET containers with screw-top closures. Premium nut-based spreads in France and Italy favor this format for shelf presence.
- Squeeze Bottle:Flexible plastic with flip-top dispensing. Commuter and single-person households in France and Spain are displacing tubs with this convenience format.
- Pouch:Flexible film with tear-and-squeeze functionality. Portion-control applications in foodservice and travel channels.
Tub formats anchor established volume; squeeze bottles capture steepest expansion trajectory among convenience-oriented segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal agricultural subsidies are redirecting oilseed cultivation toward sustainable feedstocks, reshaping raw material availability for spread manufacturers across member states. EFSA clean-label enforcement and national trans-fat caps under REACH-aligned frameworks are forcing simultaneous reformulation and supply chain restructuring. Demand concentrates in Northern European dairy traditions and Mediterranean nut-based premium positioning.
Germany
Breakfast-table substitution of dairy fats with plant-based alternatives is accelerating volume through retail channels. Federal Ministry of Food and Agriculture bioeconomy incentives support domestic rapeseed and sunflower oil processing. Berlin-Brandenburg and North Rhine-Westphalia host the densest co-manufacturing clusters for clean-label margarine production.
France
Premium nut-based spreads command the highest per-capita consumption in urban centers and artisanal channels. ANSM and DGCCRF enforcement of EFSA nutrition claims standards elevates compliance costs for functional positioning. The Île-de-France and Provence-Alpes-Côte d'Azur regions concentrate demand for squeeze-bottle convenience formats among single-person households.
Italy
Hazelnut supply chain integration with confectionery traditions sustains premium pricing for roasted-and-ground preparations. Ministry of Health trans-fat regulations align with EU-wide REACH frameworks, forcing legacy recipe adjustments. Piedmont's confectionery cluster around Alba anchors raw nut procurement and small-batch processing expertise.
United Kingdom
Deep retail distribution networks sustain volume for cream cheese and blended spread categories. Food Standards Agency enforcement of front-of-pack labeling rules is compressing margins for reformulated lines. Greater London and the Southeast dominate convenience-format adoption among commuter households.
Netherlands
Private-label plant-based spread manufacturing is expanding through German and Benelux retail partnerships. Dutch Food and Consumer Product Safety Authority alignment with ECHA pesticide residue protocols extends nut supply chain certification timelines. The Randstad corridor concentrates R&D facilities for emulsion technology and high-pressure processing equipment.
Europe Food Spread Market Competitive Landscape
Player mix skews toward diversified multinational food conglomerates with integrated supply chains and regional specialists commanding artisanal premium tiers. Consolidation pressure operates through scale advantages in regulatory compliance and procurement leverage against concentrated nut suppliers. Three archetypes dominate: hazelnut supply chain integrators, dairy-fat portfolio incumbents, and clean-label agile specialists. Competitive moves center on backward integration into sustainable oilseed operations and technology licensing for cold-pasteurization shelf-life extension.
Within the diversified conglomerate tier, Unilever PLC and Nestlé S.A. occupy positions defined by retail distribution depth and R&D infrastructure for reduced-fat formulations. Ferrero International S.A. exemplifies the supply chain-integrated archetype through its hazelnut procurement concentration in Turkish and Italian orchards. These three anchors represent distinct strategic vectors: mass-market volume leverage, functional innovation capability, and premium raw material control.
| Leading Market Players |
|---|
| Unilever PLC |
| Hero Group |
| Ferrero International S.A. |
| Orkla ASA |
| Andros Group |
| Nestlé S.A. |
| Kraft Heinz Company |
| The Hershey Company |
| Lindt & Sprüngli AG |
| Others |
Supply & Pricing Matrix
Scale economies in hazelnut roasting and emulsion processing concentrate margin capture among Turkish and Italian orchard-integrated manufacturers, establishing price floors that mid-tier plant-based spread producers struggle to breach without EFSA-compliant clean-label certification investments.
Pricing Analysis
Certification level under EFSA nutrition claims and EU organic standards creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by clean-label compliance depth and sustainable oilseed sourcing. Pricing pressure stems from palm oil substitution economics as certified sustainable alternatives command supply premia. Discount retailers in Germany and Poland exhibit highest price sensitivity, while artisanal channels in France and Italy absorb premium positioning.
Supply Chain Analysis
Inventory carry costs are extending procurement cycles as ECHA pesticide residue testing timelines stretch nut supply chain certification. Raw material concentration centers on Turkish and Italian hazelnut orchards, German and Dutch rapeseed processing, and Malaysian and Indonesian certified sustainable palm sources. Climate-driven crop volatility in Mediterranean growing regions poses structural single-source vulnerability. Distribution runs through consolidated retail partnerships in Northern Europe and fragmented traditional trade in Eastern European expansion markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA clean-label enforcement and EU Green Deal subsidy structures are accelerating a technological inflection toward cold-pasteurization and sustainable oilseed processing, compressing legacy formulation margins while rewarding early compliance investments.
For Market Incumbents: Compound defensive positioning through backward integration into certified sustainable oilseed operations and high-pressure processing equipment licensing. Threats from agile clean-label specialists and REACH-aligned trans-fat reformulation mandates demand accelerated R&D staffing in natural emulsifier substitution. Channel control through exclusive retail partnerships in Benelux and Scandinavian markets provides margin protection.
For New Entrants and Emerging Players: Anchor in Polish and Romanian discount channel white space where private-label plant-based spread penetration remains underdeveloped. Squeeze-bottle convenience formats targeting single-person households in urban France and Spain represent the most penetrable segment. Go-to-market execution should prioritize co-manufacturing partnerships with Belgian and Austrian compact high-pressure processing facilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clean-label agile specialists with modular cold-pasteurization capabilities and established EFSA compliance documentation. Long-term viability over the coming decade hinges on Scope 3 agricultural emissions tracking infrastructure and supplier network restructuring toward certified sustainable operations. Watch CSRD disclosure adoption rates among major retailers as the inflection signal for preferred supplier status allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Oilseed Operations | Captures EU Green Deal subsidies while securing margin against certified sustainable input premia. |
| High-Pressure Processing Equipment Licensing | Extends clean-label shelf life without synthetic preservatives, unlocking distribution for artisanal producers. |
| CSRD Scope 3 Compliance Infrastructure | Positions suppliers as preferred partners for carbon-accounting retailers under emerging disclosure mandates. |
| Polish and Romanian Discount Channel Expansion | Secures first-mover shelf space in underpenetrated modern trade expansion markets. |
| Squeeze-Bottle Convenience Format Introduction | Captures commuter and single-person household segments displacing traditional tub formats. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with spread manufacturing executives, regulatory affairs specialists, retail category buyers, and sustainable sourcing directors; and secondary validation through EFSA guidance documents, EU Green Deal agricultural subsidy records, ECHA pesticide residue protocols, and Nielsen retail audit data across European markets. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators ensured cross-verification.
Across the analysis window, forecasts employed segmented modeling by product type, ingredient source, texture profile, and packaging format, with additional dimensioning by national regulatory cluster and retail channel structure. CAGRs derived from historical trajectory analysis adjusted for policy inflection points including REACH-aligned trans-fat implementation timelines and CSRD disclosure phase-ins. Forecast inputs incorporated hazelnut crop yield volatility patterns and sustainable oilseed cultivation subsidy uptake rates.
Decision-makers should treat outputs as directional under assumptions of continued EFSA clean-label enforcement and stable EU agricultural subsidy frameworks; material deviation in regulatory timelines or climate-driven supply disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Canned Food Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Cook-In-Bags Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market