
 Microwavable Foods Market | 2026-2036
Microwavable Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Microwavable Foods Market Analysis
Premium clean-label tiering is rotating the competitive landscape toward higher-margin offerings. Nestlé leverages its frozen meal specialization across European and North American retail networks. Tyson Foods anchors protein-forward microwavable lines through its integrated poultry supply chain. Conagra Brands competes on scale in the ready-to-eat segment with broad distribution coverage.
Microwavable foods comprise pre-cooked or partially prepared food products formulated for rapid thermal reconstitution in microwave ovens, typically requiring one to six minutes at power outputs between 600 and 1,200 watts. These products employ modified atmosphere packaging, susceptors, or steam-venting films to control moisture migration and achieve texture parity with conventional preparation. Frozen meals command the largest value pool due to entrenched household penetration and extended shelf stability, while flexible pouches gain share fastest in the packaging category through reduced material costs and improved microwave energy distribution. Online retail channels now capture disproportionate growth in distribution as direct-to-consumer fulfillment infrastructure matures.
The U.S. FDA governs nutrition facts panel disclosures and sodium reduction targets for prepared foods, while the EU Green Deal and F-Gas Regulation shape sustainable packaging mandates across European supply chains. BIS standards in India establish microwave safety and migration limits for food-contact materials in this expanding market. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between reformulation investments versus packaging redesign to maintain market access.
Market Dynamics
Dual-income household formation in metropolitan corridors is compressing meal preparation windows and elevating convenience to a non-negotiable purchase criterion, forcing reformulation trade-offs between shelf stability and clean-label positioning.
Growth Catalysts
- Urban household compression:Single-person and dual-income units in dense metropolitan clusters treat microwave reconstitution as default meal preparation, expanding addressable occasions beyond traditional frozen dinner positioning.
- FDA sodium reduction mandates:The U.S. FDA's updated nutrition labeling requirements for prepared foods compel manufacturers to reformulate legacy portfolios, creating first-mover advantage for clean-label specialists.
- Susceptor film advancement:Steam-venting and susceptor-integrated packaging technologies now achieve texture parity with conventional oven preparation, removing the quality barrier that historically limited category expansion.
Market Restraints
- Input cost volatility:Polypropylene and polyester resin prices fluctuate with petrochemical feedstock markets, squeezing flexible pouch economics and forcing material substitution decisions.
- Supply concentration risk:Modified atmosphere packaging equipment and barrier film production concentrates among German and Japanese machinery suppliers, creating vulnerability to regional logistics disruptions.
- Substitution pressure:Meal-kit delivery services and quick-service restaurant mobile ordering capture occasion share among time-constrained urban consumers, particularly in coastal U.S. and Western European markets.
Strategic Opportunities
- Indian regulatory alignment:BIS microwave safety and migration limit standards for food-contact materials create a compliance moat for early entrants in this underpenetrated market.
- Direct-to-consumer channel maturation:Cold-chain fulfillment infrastructure now supports frozen and chilled microwavable delivery at viable unit economics, bypassing traditional retail slotting fee structures.
- EU Green Deal packaging pivot:Extended producer responsibility frameworks and F-Gas Regulation compliance requirements favor recyclable mono-material pouches over multi-layer barrier constructions.
Industry Challenges
- Reformulation-capability scarcity:Food scientists capable of balancing sodium reduction targets with flavor delivery and microwave-specific moisture management command premium compensation and limited availability.
- Legacy asset stranding:Existing tray-sealing and carton-filling lines require capital-intensive retrofit or replacement to handle next-generation susceptor-integrated and paper-based packaging formats.
- Certification timeline compression:Migration testing for new food-contact materials under FDA, EFSA, and BIS jurisdictions extends commercialization cycles by 18-24 months versus historical baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwavable Foods Market |
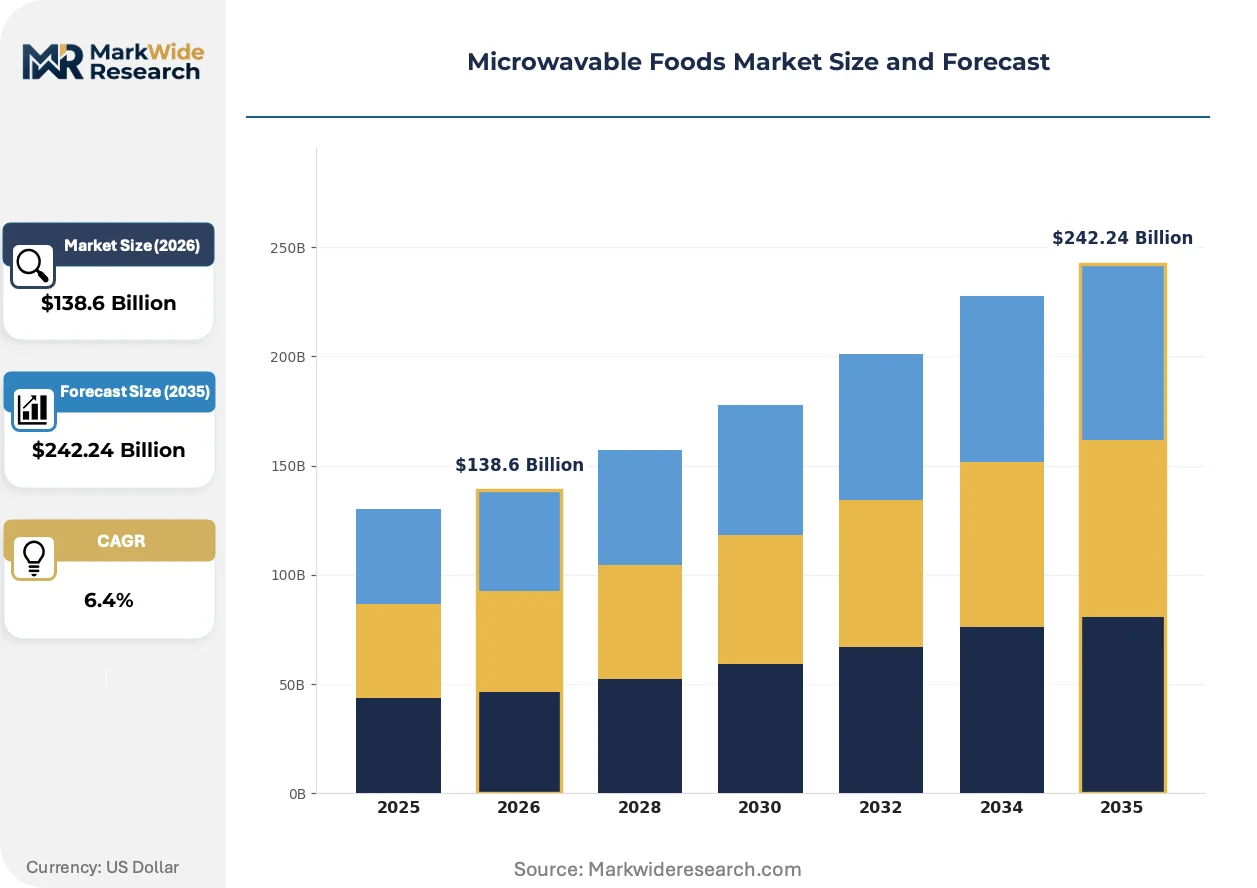
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $242.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Ready-to-Eat, Snacks, Vegetables Packaging Type: Flexible Pouches, Trays, Boxes, Cans End User: Households, Cafeterias, Restaurants, Convenience Stores Distribution Channel: Supermarkets, Online Retail, Convenience Shops, Wholesale |
| Companies Covered | General Mills, Unilever, Nestlé, Tyson Foods, Campbell Soup Company, Conagra Brands, McCain Foods, Kellogg Company, Kraft Heinz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwavable Foods Market Emerging Trajectories
Susceptor-integrated packaging and steam-venting film technologies are collapsing the quality gap between microwave and conventional preparation, while regulatory pressure on sodium content and packaging sustainability forces simultaneous reformulation and material redesign.
Smart susceptor technology is miniaturizing energy distribution control within flexible pouch constructions. Susceptor patterns now target specific food zones—crisping breading while protecting moisture in protein centers. Frozen meal manufacturers in the United States and Germany are adopting these films at accelerated procurement cycles. The technology is miniaturizing the performance differential that previously justified oven preparation, compressing competitive advantage toward packaging engineering rather than recipe differentiation.
The EU F-Gas Regulation and national extended producer responsibility frameworks are mandating recyclable mono-material packaging by 2030. Multi-layer barrier films containing metallized layers or incompatible polymers face phase-out timelines. Frozen meal producers serving French and German retail networks are accelerating paper-based and polypropylene mono-material trials. This regulatory pressure is shifting technical investment from shelf-life extension toward end-of-life material recovery.
Urban consumers are unbundling meal occasions from traditional dayparts and preparation rituals. Breakfast protein bowls, ethnic street-food formats, and global cuisine adaptations now populate microwave portfolios previously dominated by Western comfort foods. Quick-commerce and direct-to-consumer fulfillment channels in Tokyo, Seoul, and New York capture disproportionate volume growth. This behavioral fragmentation rewards SKU proliferation and regional taste localization over standardized global platforms.
Microwavable Foods Market Segmentation
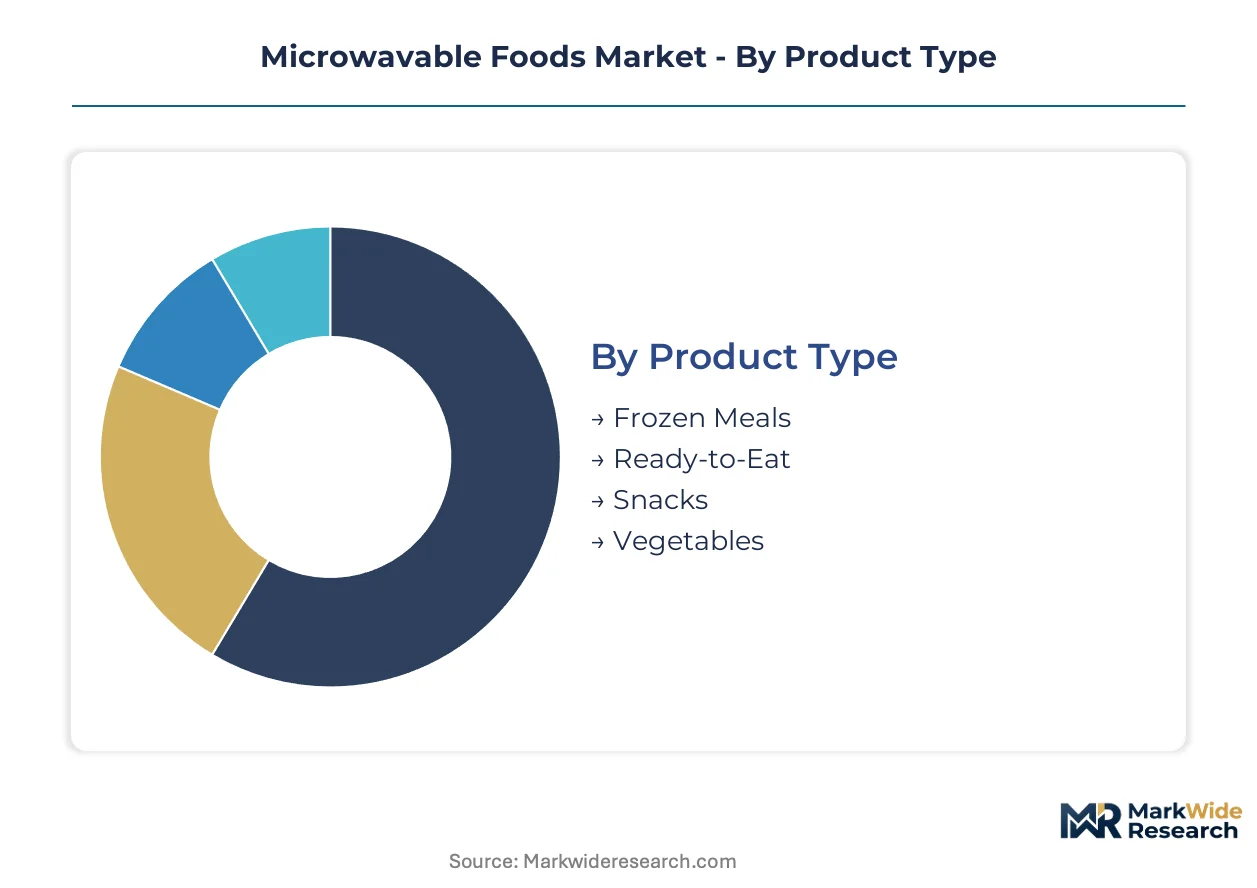
Microwavable food segments diverge sharply between domestic pantry stocking and foodservice procurement channels. Packaging format selection and distribution channel alignment determine margin capture and regulatory exposure across each product tier.
Product Type:
Frozen meals and ready-to-eat lines dominate export flows to metropolitan clusters in Germany, Japan, and South Korea, while snack and vegetable segments serve primarily domestic convenience channels.
- Frozen Meals:Pre-cooked protein-starch-vegetable combinations packaged for extended frozen storage. Demand concentrates in dual-income households across Tokyo, Seoul, and New York where microwave reconstitution replaces conventional cooking. Susceptor-integrated trays now achieve texture parity with oven preparation.
- Ready-to-Eat:Shelf-stable formulations requiring no freezing, employing retort or modified atmosphere preservation. German and French retail networks drive adoption through chilled ready-meal sections in urban supermarkets.
- Snacks:Single-serve savory and sweet items targeting impulse consumption. Convenience store chains in Japan and South Korea anchor volume.
- Vegetables:Steamable bagged produce with vented film technology. U.S. household penetration remains highest.
Frozen meals command the established base. The steepest expansion runs through ready-to-eat formats.
Packaging Type:
Cost tiering separates premium susceptor-integrated solutions from commodity formats, with material selection directly determining microwave performance and sustainability compliance.
- Flexible Pouches:Multi-layer or mono-material films with steam-venting features, reducing material costs versus rigid alternatives. Tokyo and New York quick-commerce channels favor pouches for last-mile efficiency.
- Trays:Polypropylene or crystallized PET constructions with lidding films, dominating frozen meal presentation in German and U.S. retail.
- Boxes:Paperboard-based formats with susceptor laminates, gaining share in EU markets facing F-Gas Regulation pressure.
- Cans:Traditional metal containers for shelf-stable ready-to-eat soups and pasta. Emerging market distribution relies on can durability.
Trays retain the volume base. Flexible pouches climb the fastest as cold-chain infrastructure matures.
End User:
Application context dictates formulation priorities, with foodservice operators demanding holding stability and retail channels emphasizing visual appeal.
- Households:Individual and family-size portions with clean-label positioning. FDA sodium reduction targets reshape U.S. product development.
- Cafeterias:Institutional bulk formats with extended holding tolerance. School and corporate feeding programs in France and Germany specify nutritional compliance.
- Restaurants:Back-of-house speed-scratch components reducing labor intensity. Fast-casual chains in South Korea deploy microwave proteins.
- Convenience Stores:Grab-and-go single serves with extended ambient shelf life. Japanese konbini chains set global format standards.
Households anchor revenue. Convenience stores gain share fastest through 24-hour urban access.
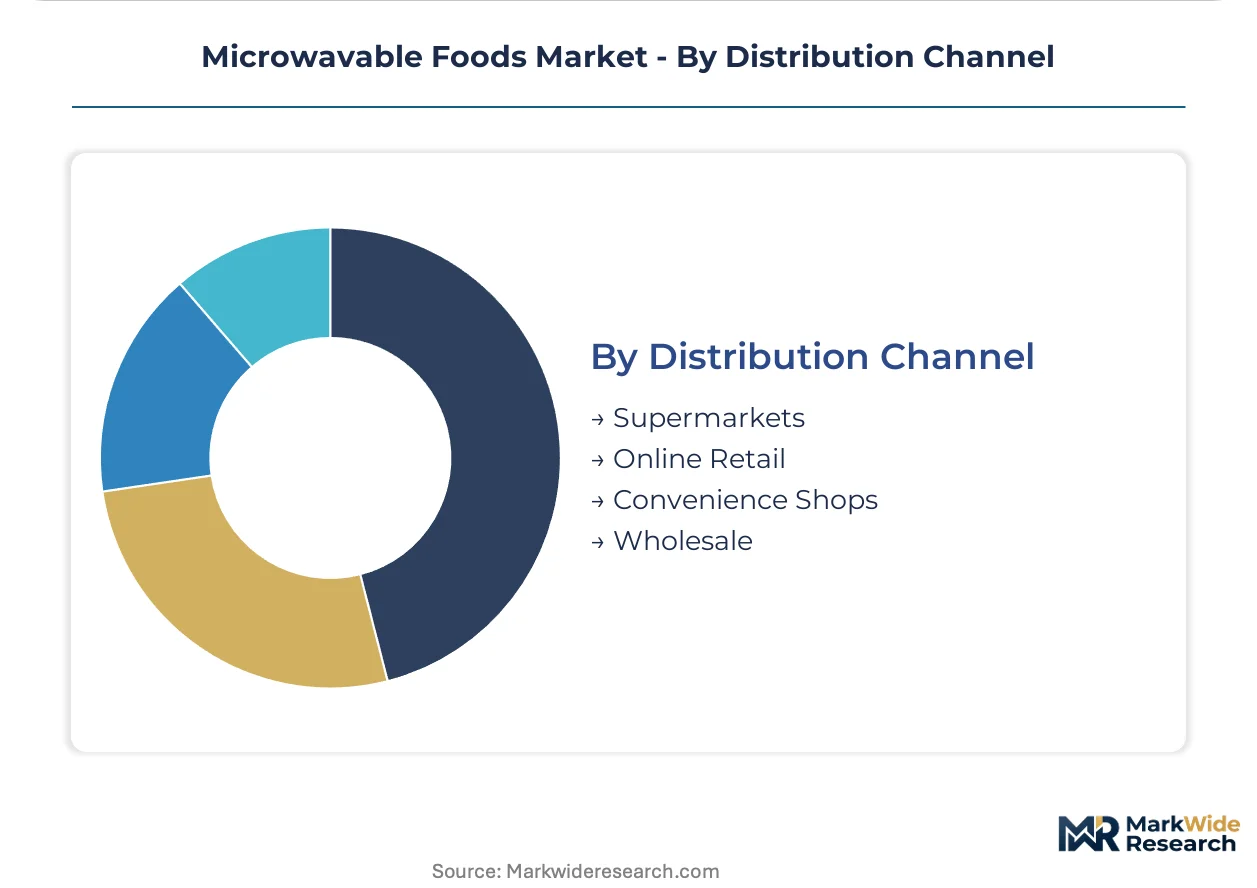
Distribution Channel:
Customer type stratification separates planned pantry stocking from immediate consumption, with channel selection determining packaging durability requirements.
- Supermarkets:Full-category frozen and chilled sections with promotional slotting. German and U.S. chains dominate procurement scale.
- Online Retail:Direct-to-consumer frozen fulfillment requiring robust cold-chain logistics. Seoul and New York metro areas demonstrate viable unit economics.
- Convenience Shops:Limited-assortment immediate consumption focused. Japanese operators maintain highest SKU density.
- Wholesale:Bulk institutional supply to cafeterias and restaurant groups. Price sensitivity favors economy-tier formulations.
Supermarkets maintain the established base. Online retail shows the steepest trajectory as fulfillment infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modified atmosphere packaging equipment and barrier film production concentrates among German and Japanese machinery suppliers, creating vulnerability to regional logistics disruptions. Frozen meal demand clusters in metropolitan corridors across four continents, with regulatory divergence forcing localized formulation strategies.
United States
Dual-income households in New York and Los Angeles treat microwave reconstitution as default meal preparation, expanding addressable occasions beyond traditional frozen dinner positioning. The FDA's updated nutrition labeling requirements and sodium reduction targets compel manufacturers to reformulate legacy portfolios. Chicago anchors protein-forward microwavable lines through integrated poultry supply chain concentration.
Germany
Urban supermarkets in Berlin and Munich drive chilled ready-meal adoption through dedicated retail sections with promotional slotting intensity. The EU Green Deal and F-Gas Regulation mandate recyclable mono-material packaging by 2030, forcing material substitution decisions. Bavarian packaging engineers trial paper-based and polypropylene mono-material formats ahead of compliance deadlines.
Japan
Convenience store chains in Tokyo and Osaka maintain highest SKU density for single-serve savory and sweet impulse items. METI standards govern microwave safety and energy efficiency labeling for domestic appliances, indirectly shaping product format specifications. Yokohama quick-commerce channels favor flexible pouches for last-mile efficiency in dense metropolitan clusters.
South Korea
Fast-casual restaurant operators in Seoul deploy microwave proteins as back-of-house speed-scratch components reducing labor intensity. MFDS establishes food-contact material migration limits and microwave safety protocols for expanding retail channels. Busan-Ulsan manufacturing corridors supply susceptor-integrated packaging films across East Asian export markets.
India
Single-person household formation in Mumbai and Delhi-NCR compresses meal preparation windows and elevates convenience purchase criteria. BIS standards establish microwave safety and migration limits for food-contact materials, creating compliance moats for early entrants. Gujarat packaging converters invest in modified atmosphere equipment to serve underpenetrated domestic demand.
Microwavable Foods Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with packaging engineering specialists commanding premium positioning against scale-driven food manufacturers. The vendor base stratifies across three tiers: integrated multinationals with frozen meal specialization, protein-forward supply chain anchors, and ready-to-eat scale competitors with broad distribution coverage. Consolidation pressure concentrates among tray-sealing and carton-filling equipment suppliers, while brand competition fragments across taste localization and clean-label positioning. Dominant competitive moves include strategic partnerships for suscriptor film procurement and geographic expansion into quick-commerce fulfillment corridors.
Within the integrated multinational tier, Nestlé and Unilever occupy positions defined by frozen meal specialization across European and North American retail networks. Tyson Foods anchors protein-forward microwavable lines through its integrated poultry supply chain concentration in the United States. Conagra Brands exemplifies scale-driven competition in the ready-to-eat segment with broad distribution coverage across domestic supermarket channels.
| Leading Market Players |
|---|
| General Mills |
| Unilever |
| Nestlé |
| Tyson Foods |
| Campbell Soup Company |
| Conagra Brands |
| McCain Foods |
| Kellogg Company |
| Kraft Heinz |
| Others |
Supply Flow & Price Mechanics
FDA sodium reduction mandates and EU F-Gas Regulation compliance requirements simultaneously gate supplier qualification and stratify price tiers across frozen and chilled microwavable segments. Manufacturers must absorb reformulation and packaging redesign costs to maintain retail access, compressing margins at the economy tier while premium clean-label offerings capture widening price spreads.
Pricing Analysis
FDA sodium reduction targets dictate the pricing tier structure across U.S. retail channels. Three-tier pricing separates premium clean-label lines with reformulated low-sodium profiles from standard legacy portfolios and economy private-label alternatives. Certification investment for BIS compliance in India and EFSA alignment in Europe adds fixed cost layers that price differentiation amplifies. Pricing pressure stems from polypropylene resin volatility and susceptor film procurement bottlenecks. Institutional buyers in cafeteria and wholesale channels exhibit highest price sensitivity, while direct-to-consumer households tolerate premium positioning for texture-parity susceptor formats.
Supply Chain Analysis
Germany and Japan anchor modified atmosphere packaging equipment and barrier film production for global microwavable supply chains. German machinery suppliers concentrate tray-sealing and carton-filling systems, while Japanese manufacturers dominate susceptor-integrated film innovations. Polypropylene and polyester resin inputs draw from petrochemical feedstock markets with volatile pricing. Single-source vulnerability concentrates in specialized susceptor coating technologies and steam-venting film laminates. Distribution runs through integrated cold-chain networks serving retail supermarkets, with quick-commerce channels in Seoul and New York demanding pouch-format flexibility for last-mile efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meal-kit delivery services and quick-service restaurant mobile ordering threaten occasion share among time-constrained urban consumers, forcing incumbents to defend shelf positioning through simultaneous quality upgrading and cost discipline.
For Market Incumbents: Fortify susceptor film procurement partnerships with Japanese and German suppliers to lock in texture-parity technology ahead of competitor adoption. Accelerate paper-based and polypropylene mono-material packaging trials to preempt EU Green Deal compliance deadlines. Vertical integration into poultry supply chains, following Tyson Foods' model, defends protein-forward positioning against private-label erosion.
For New Entrants and Emerging Players: Direct-to-consumer cold-chain fulfillment infrastructure gaps in Indian metropolitan corridors offer white-space entry with lower slotting fee barriers than saturated Western retail. BIS certification investment creates compliance moats against delayed multinational entrants. Target Mumbai and Delhi-NCR single-person households with ethnic street-food format localization, leveraging regional taste fragmentation that global platforms under-serve.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across susceptor-integrated packaging manufacturing due to equipment specialization and migration testing timeline extensions. Long-term viability favors acquisition targets with established FDA, EFSA, and BIS regulatory dossiers rather than greenfield certification plays. Watch for susceptor film procurement bottlenecks as early inflection signal for margin compression across tier-two manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Susceptor Film Technology Partnership | Japanese and German suppliers control texture-parity packaging innovation essential for quality positioning. |
| Mono-Material Packaging Transition | EU F-Gas Regulation mandates recyclable formats by 2030, forcing material substitution ahead of compliance deadlines. |
| Direct-to-Consumer Channel Buildout | Cold-chain fulfillment infrastructure in Seoul and New York demonstrates viable unit economics bypassing retail slotting fees. |
| Clean-Label Reformulation Investment | FDA sodium reduction targets compel legacy portfolio overhaul, creating first-mover advantage for compliant specialists. |
| Indian Regulatory Certification | BIS microwave safety and migration limits establish compliance moats in underpenetrated metropolitan demand clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA enforcement actions, EFSA scientific opinions, BIS technical standards, and trade customs data for food-contact materials. Conversations with frozen meal brand managers, retail category buyers, packaging equipment engineers, and cold-chain logistics operators informed demand and supply-side validation. Secondary sources include SEC 10-K filings for listed food manufacturers, EU Green Deal implementation guidance, and migration testing protocol documentation from notified bodies. Bottom-up SKU-level volume builds triangulate against top-down category expenditure estimates from retail audit databases.
Segmentation dimensions modeled span product type, packaging format, end-user application, and distribution channel across the projection horizon. Product type segmentation captures frozen meals, ready-to-eat, snacks, and vegetables with distinct shelf-life and preservation technology requirements. Packaging analysis disaggregates flexible pouches, trays, boxes, and cans by material composition and microwave performance characteristics. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Susceptor film penetration rates and sodium reduction reformulation timelines serve as category-specific forecast inputs.
Forecasts assume regulatory continuity in FDA nutrition labeling, EU F-Gas Regulation, and BIS food-contact material regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated EU packaging mandates, input cost spikes in petrochemical feedstocks, and faster-than-expected meal-kit delivery service substitution in coastal U.S. and Western European markets. Recalibration cycles align with material shifts in regulatory enforcement patterns and susceptor technology procurement availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Wet Pet Food Market
Packaged Foods
Freekeh Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Brio Bowls Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Global Breakfast Cereals Market
Packaged Foods
Reduced Salt Packaged Foods Market