
 Asia Pacific Compact Dishwasher Market | 2026-2036
Asia Pacific Compact Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Compact Dishwasher Market Insights
Modular bundling of compact dishwashers with water-softener cartridges and detergent-subscription services is hardening as the dominant configuration pattern. BSH (Robert Bosch GmbH) leverages its established service infrastructure to anchor premium positioning in Japan and South Korea. Haier Group Corporation competes through localized manufacturing scale and distribution depth across China's tier-two cities. Midea Group specializes in cost-optimized portable units that occupy the mass-market channel in Southeast Asia.
A compact dishwasher is a reduced-footprint dishwashing appliance typically measuring under 60 centimeters in width, designed for installation in kitchens with limited cabinet or counter space, using spray-arm wash systems with water consumption below 10 liters per cycle. The built-in segment leads value contribution where permanent kitchen renovation permits integration, while countertop variants capture the fastest volume growth among urban renters and temporary housing residents. Smart-features technology differentiates margin pools as Wi-Fi-enabled cycle programming and usage analytics command price premiums in Australia and Japan. Energy-efficient models sustain regulatory compliance advantages as BIS, GB standards, and Australia's energy-rating scheme tighten minimum thresholds.
China's SAMR enforces GB standards on water and energy efficiency that determine market access for domestic and imported compact dishwashers. India's BIS mandatory labeling scheme and Australia's energy-rating program shape consumer visibility and purchasing decisions across price tiers. Japan's METI Top Runner program accelerates efficiency benchmarks that manufacturers must meet for commercial placement. Stakeholders must monitor how harmonization between national efficiency regimes affects cross-border product-platform economics and certification costs.
Market Dynamics
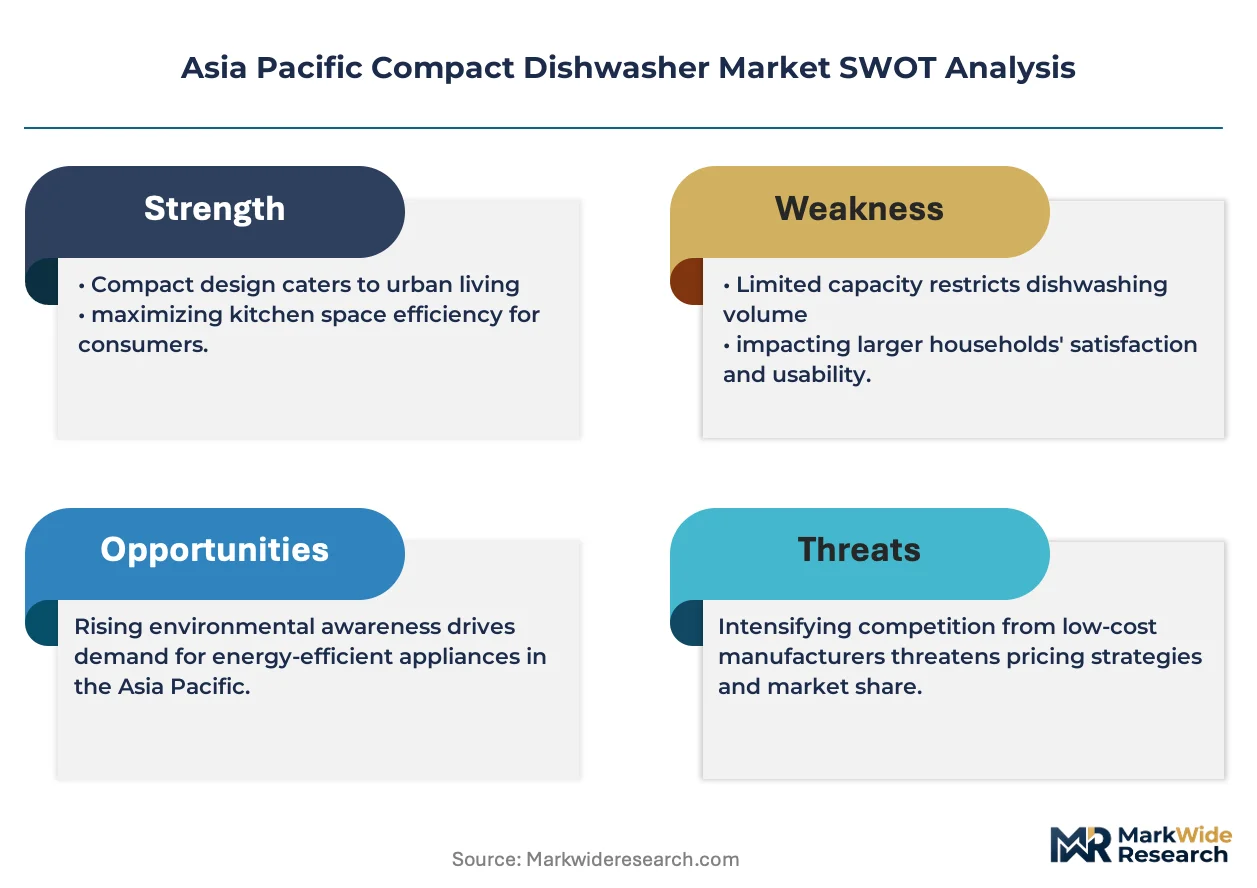
Urban kitchen space constraints across Asia Pacific's dense metropolitan cores are compressing appliance footprints and forcing modular design architectures that trade capacity for install flexibility. This spatial pressure is redrawing competitive boundaries between built-in and portable configurations.
Growth Catalysts
- Nuclear-family formation:India's rising share of two-income households in Mumbai, Bengaluru, and Delhi NCR generates first-time appliance purchases for compact units suited to rental kitchens.
- BIS mandatory labeling:India's energy-efficiency disclosure requirements create visibility advantages for certified models and accelerate replacement cycles among efficiency-conscious buyers.
- Countertop Wi-Fi integration:Smart-cycle programming via mobile applications commands price premiums in Japan and Australia, expanding margin pools for connected variants.
Market Restraints
- Stainless steel input volatility:Sheet metal and electronic component cost swings compress manufacturing margins, particularly for mass-market portable units.
- Water-pressure infrastructure gaps:Inconsistent municipal supply across Southeast Asian secondary cities limits countertop dishwasher performance and elevates return rates.
- Manual dishwashing substitution:Domestic labor availability and cultural washing habits in South Asia delay adoption despite appliance accessibility.
Strategic Opportunities
- Vietnam and Philippines penetration:These markets show sub-5% dishwasher ownership with accelerating condominium construction, creating white space for compact-format entry.
- Detergent-subscription bundling:Recurring revenue models attached to hardware sales improve lifetime value metrics and reduce customer acquisition costs.
- GB standards harmonization:China's SAMR efficiency benchmarks, if adopted regionally, would streamline certification costs for multi-country product platforms.
Industry Challenges
- Multi-regulatory certification timelines:Sequential BIS, GB, and METI approval processes delay product launches by 8-14 months and fragment R&D resource allocation.
- Legacy kitchen retrofit integration:Plumbing and electrical adaptation for older housing stock in Japan and South Korea requires specialized installation services that constrain volume scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Compact Dishwasher Market |
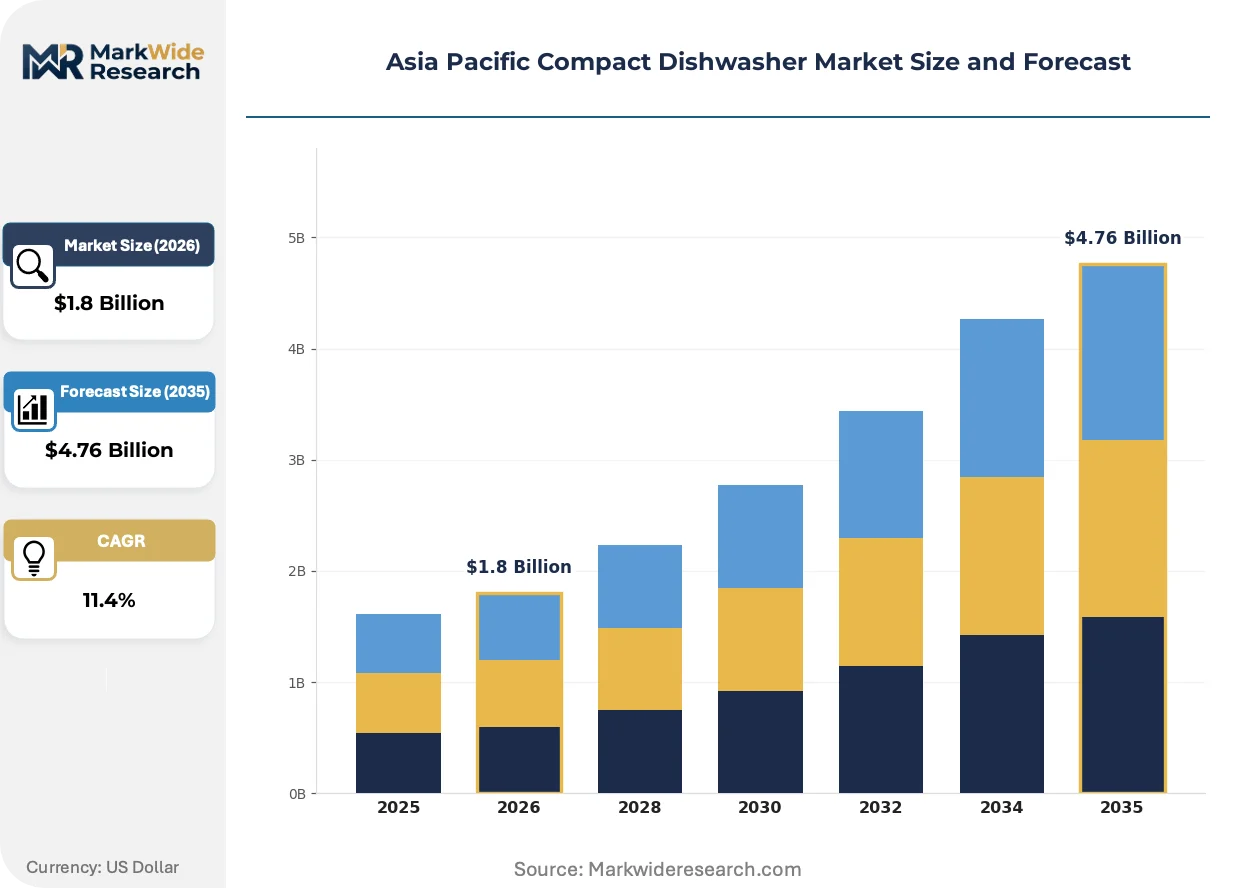
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Countertop, Drawer End User: Household, Commercial, Hospitality, Catering Technology: Energy-Efficient, Smart Features, Standard, High-Temperature Size: 1-2 Place Settings, 3-4 Place Settings, 5-6 Place Settings, Others |
| Companies Covered | Whirlpool Corporation, BSH (Robert Bosch GmbH), Electrolux AB, Haier Group Corporation, LG Electronics Inc., Midea Group, Dyson, Mabe, Siemens AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Compact Dishwasher Market Trends and Innovations
Product architecture in Asia Pacific compact dishwashers is pivoting from standalone appliances toward integrated kitchen-system components. This shift is compressing traditional category boundaries and elevating software-enabled service layers as differentiation vectors.
Ultrasonic cleaning modules are expanding into premium countertop segments as an adjunct to conventional spray-arm systems. Japanese appliance buyers in Tokyo and Osaka are adopting hybrid-configuration units that reduce water consumption below six liters per cycle. This dual-technology approach is expanding into adjacent price tiers as manufacturing scale drives module cost curves downward.
China's SAMR enforcement of revised GB water-efficiency thresholds is tightening market-access requirements for both domestic and imported compact dishwashers. Manufacturers must recalibrate pump and heating-element specifications to maintain compliance, with built-in integrated units facing the steepest redesign burden. Korean and Japanese exporters are responding by pre-certifying platforms to China's updated testing protocols ahead of enforcement deadlines.
Appliance-as-a-service models are disrupting traditional ownership patterns among Australian and Japanese urban renters. Subscription-based countertop programs bundle hardware, maintenance, and detergent supply into monthly fees, displacing outright purchase for transient housing populations. Property-management companies in Sydney and Melbourne are piloting these arrangements as amenity differentiators in competitive rental markets.
Asia Pacific Compact Dishwasher Market Segmentation
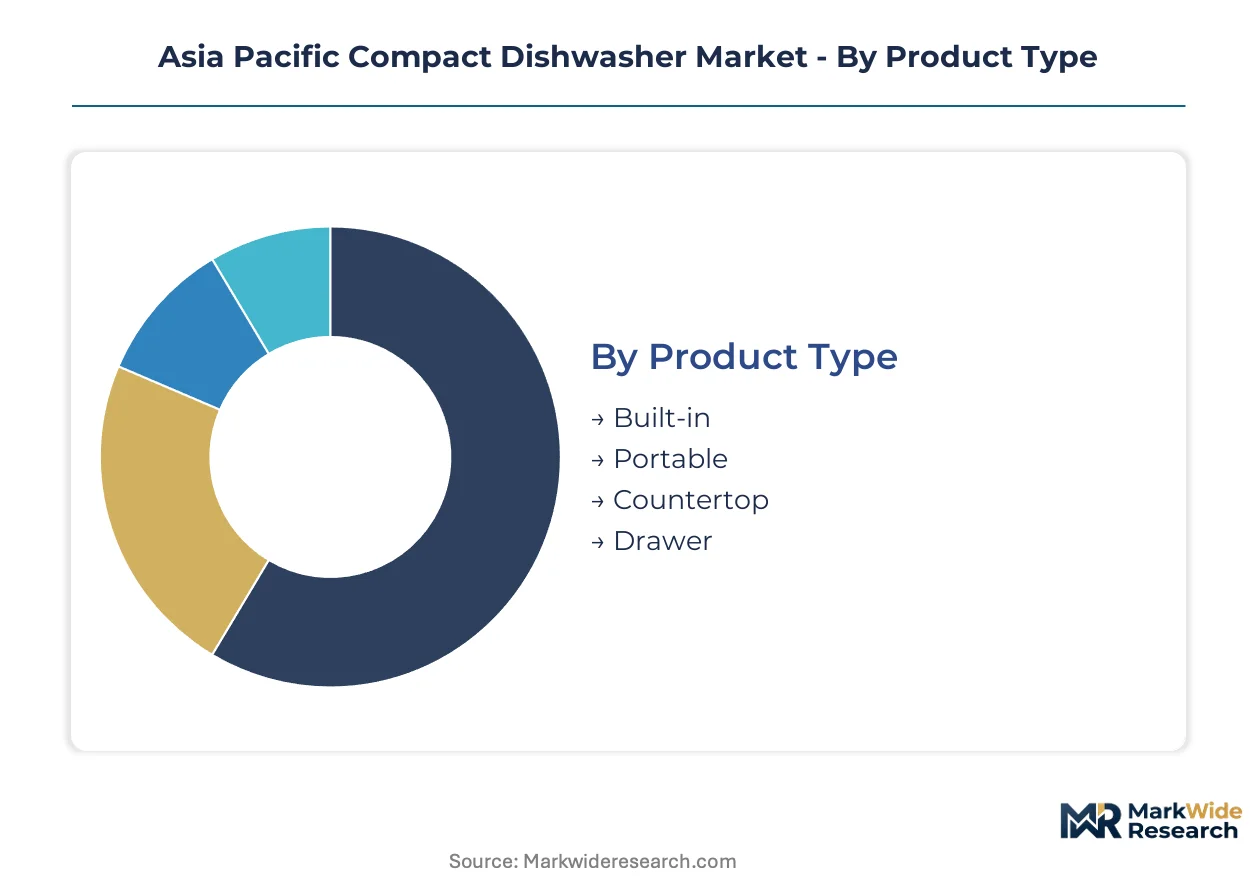
Compact dishwasher segmentation in Asia Pacific reflects divergent regulatory burdens and installation constraints across urban housing typologies. Each category channels distinct certification requirements, from China's GB water-efficiency mandates to Japan's METI Top Runner benchmarks, shaping manufacturer platform strategies.
Product Type:
Built-in units carry the heaviest certification load, requiring GB compliance for China, BIS labeling for India, and METI approval for Japan. Portable and countertop variants face lighter regulatory entry but encounter fragmented municipal water-pressure standards across Southeast Asian secondary cities.
- Built-in:Permanent cabinet-integrated units measuring 45-60 centimeters in width demand plumbing and electrical hardwiring. Seoul and Tokyo apartment renovations drive replacement demand where kitchen retrofit budgets permit permanent installation.
- Portable:Freestanding units with wheeled mobility and temporary hose connections dominate rental housing in Mumbai and Bengaluru. Water-pressure adaptability constraints limit performance consistency across Indian tier-two municipal supplies.
- Countertop:Surface-mounted compact units under 55 centimeters wide target single-person households in Osaka and Sydney. Wi-Fi-enabled variants command price premiums through subscription-bundling models.
- Drawer:Pull-out compartment designs with independent wash zones suit premium kitchen renovations in Melbourne and Auckland. Dual-drawer configurations reduce per-cycle water consumption below seven liters.
Built-in sits at the top of the volume ranking, with countertop climbing the fastest.
End User:
Cost tiers stratify sharply across end-user categories, with hospitality and commercial segments absorbing premium pricing for durability specifications while household demand concentrates in entry-level portable configurations.
- Household:Nuclear-family units in Delhi NCR and Shanghai purchase 3-4 place setting capacities as first-time appliances. Rental tenure uncertainty favors countertop and portable formats over permanent installation.
- Commercial:Small restaurants and cafés in Bangkok and Jakarta require rapid-cycle units with stainless-steel interiors. High-frequency usage patterns prioritize pump durability over water-efficiency ratings.
- Hospitality:Boutique hotels in Kyoto and Queenstown specify whisper-quiet operation below 45 decibels for guest room proximity. Custom panel integration matches interior design specifications.
- Catering:Event-service operators in Singapore and Hong Kong demand rapid-deployment portable units with generator compatibility. Temporary venue contracts require equipment mobility and minimal installation lead times.
Household generates absolute volume leadership, though hospitality shows the steepest expansion trajectory as tourism recovery accelerates replacement cycles.
Technology:
Application contexts determine technology adoption, with energy-efficiency and smart features penetrating premium residential segments while high-temperature systems dominate commercial hygiene requirements.
- Energy-Efficient:Pump and heating-element optimization reduces per-cycle consumption below eight liters. Australia's energy-rating program and India's BIS labeling create procurement visibility advantages for certified models.
- Smart Features:Wi-Fi-enabled cycle programming and usage analytics integrate with property-management platforms in Sydney and Melbourne rental markets. Subscription-service bundling displaces outright ownership among transient populations.
- Standard:Conventional mechanical controls without connectivity occupy mass-market channels in Vietnam and Philippines. Price sensitivity limits feature penetration where dishwasher ownership remains below five percent.
- High-Temperature:Sanitization cycles exceeding 70 degrees Celsius satisfy HACCP requirements for food-service operators in Seoul and Tokyo. Commercial warranty terms extend to five years for pump and heating components.
Energy-Efficient holds volume dominance, with Smart Features gaining share fastest as rental-housing as-a-service models expand.
Size:
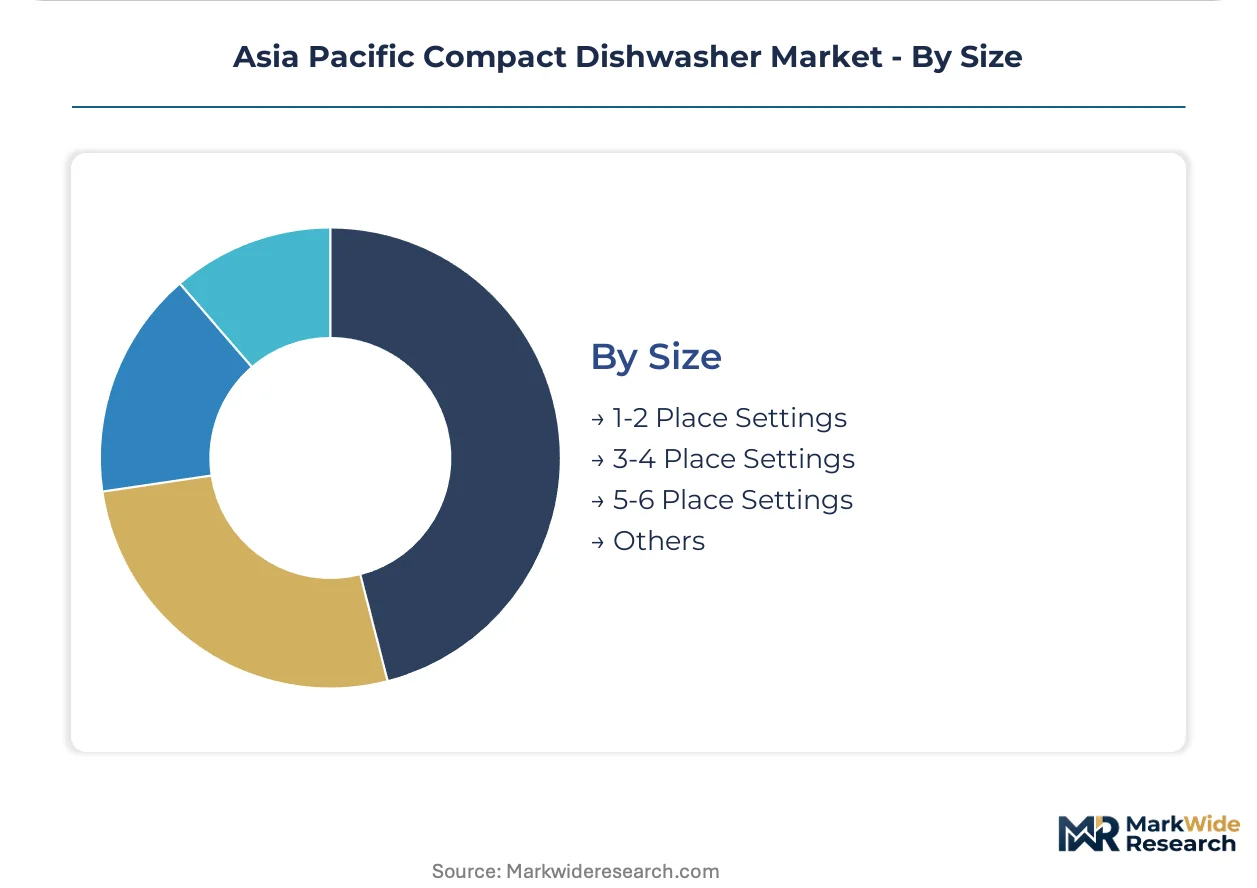
Customer type and kitchen footprint constraints segment size demand, with urban renters and temporary housing residents compressing capacity requirements while family formations sustain mid-size preferences.
- 1-2 Place Settings:Single-basin countertop units under 45 centimeters wide serve solo dwellers in Hong Kong micro-apartments. Ultrasonic cleaning modules reduce water consumption below six liters in premium Japanese variants.
- 3-4 Place Settings:Dual-spray-arm configurations balance capacity against install flexibility for couples in Bengaluru and Ho Chi Minh City rental stock. This segment captures the broadest price-tier distribution.
- 5-6 Place Settings:Family-scaled portable and drawer units accommodate small households in Sydney suburbs and Auckland. Weekend entertaining usage patterns justify capacity premiums over daily operation.
- Others:Specialized configurations including single-drawer and ultra-compact under-sink designs target retrofit constraints in legacy Tokyo and Osaka housing stock. Custom plumbing adaptation services extend manufacturer revenue capture.
3-4 Place Settings leads absolute shipments, with 1-2 Place Settings expanding most quickly as urban residential footprints compress across Asia Pacific metropolitan cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compact dishwasher manufacturing first scaled in Japan during the 1980s urban housing boom, then migrated production to South Korea and China as supply chains restructured around cost-optimized assembly. This historical trajectory now distributes competitive presence across four distinct national markets with divergent regulatory and demand profiles.
China
Shanghai and Beijing apartment renovations drive built-in unit demand where kitchen retrofit budgets permit permanent installation. SAMR enforces GB water-efficiency standards that determine market access for domestic and imported compact dishwashers. The Yangtze River Delta manufacturing cluster around Suzhou and Ningbo hosts localized production platforms serving both domestic consumption and regional export.
Japan
Tokyo and Osaka micro-apartments compress residential footprints below 40 square meters, elevating countertop and drawer configurations over full-size alternatives. METI's Top Runner program accelerates efficiency benchmarks that manufacturers must meet for commercial placement. Kanto region distributors concentrate premium smart-feature inventory for single-person households in central Tokyo wards.
India
Mumbai, Bengaluru, and Delhi NCR generate first-time appliance purchases from two-income nuclear families occupying rental kitchens. BIS mandatory energy-efficiency labeling creates procurement visibility advantages for certified models. Maharashtra and Karnataka state distributors prioritize portable units with water-pressure adaptability for inconsistent municipal supply.
South Korea
Seoul apartment dwellers in Gangnam and Mapo districts favor compact built-in units during kitchen renovation cycles. Korean manufacturers align pump specifications with both domestic efficiency codes and China's GB export requirements. Gyeonggi-do province assembly plants supply regional markets with platforms pre-certified to multiple national testing protocols.
Australia
Sydney and Melbourne rental markets pilot appliance-as-a-service subscription models among transient urban populations. The national energy-rating program shapes consumer visibility and purchasing decisions across price tiers. Property-management companies in New South Wales bundle Wi-Fi-enabled countertop units as amenity differentiators in competitive leasing markets.
Asia Pacific Compact Dishwasher Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and smart-feature dimensions. The market structure consolidates around three to four integrated appliance groups with established service infrastructure, while portable specialists fragment the entry-level tier. Strategic archetypes include full-line appliance conglomerates with backward integration into compressor and pump manufacturing, electronics specialists leveraging display and connectivity module expertise, and cost-optimized fabricators serving mass-market channels. Dominant competitive moves include geographic expansion through localized assembly partnerships and portfolio diversification into subscription-service bundling.
Among Asia-Pacific-based manufacturers, Haier Group Corporation and Midea Group occupy positions within the scale-driven archetype, while BSH (Robert Bosch GmbH) anchors the premium-tier service-integrated segment. These three exemplify divergent strategic postures: Chinese conglomerates leverage manufacturing depth and distribution breadth, while German-engineered positioning commands price premiums through established aftermarket infrastructure. LG Electronics Inc. and Samsung affiliates represent the electronics-specialist vector where display technology and connectivity integration create differentiation.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| BSH (Robert Bosch GmbH) |
| Electrolux AB |
| Haier Group Corporation |
| LG Electronics Inc. |
| Midea Group |
| Dyson |
| Mabe |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
China's GB water-efficiency standards gate qualified component supply and premium-tier pricing access, compressing margins for manufacturers unable to certify pump and heating-element specifications while rewarding pre-certified platforms with pricing power in regulated channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi-enabled subscription-bundled units from certified mid-market SKUs and unconnected mass-market portables. Price differentiation hinges on METI Top Runner compliance and after-sales service bundling, with Japanese and Australian buyers absorbing premiums for connected variants. Pricing pressure stems from stainless steel input volatility, compressing margins for mass-market portable fabricators. Commercial hospitality buyers show lowest price sensitivity, while Indian rental households concentrate demand in entry-tier portable configurations.
Supply Chain Analysis
Certification to China's SAMR GB standards, India's BIS labeling, and Japan's METI protocols gates supplier qualification, fragmenting component sourcing across regulatory jurisdictions. Manufacturing concentrates in China, South Korea, and Vietnam, with the Yangtze River Delta hosting pump and heating-element assembly. Raw material dependencies center on stainless steel sheet, electronic control modules, and water-pressure adaptors. Single-source vulnerability runs through specialized pump suppliers serving multi-regulatory platforms. Distribution runs through appliance retail chains in developed markets and distributor networks in Southeast Asian secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with Japanese and Australian demand shifting decisively toward Wi-Fi-enabled premium specifications that reward certified manufacturers with sustained margin pools.
For Market Incumbents: Deepen backward integration into pump manufacturing to buffer stainless steel cost volatility and accelerate multi-regulatory pre-certification timelines. Lock in exclusive service infrastructure partnerships in Seoul and Tokyo to defend against emerging portable specialists. Prioritize certification investment for China's revised GB water-efficiency thresholds ahead of enforcement deadlines. For New Entrants and Emerging Players: Property-management companies in Sydney and Melbourne represent the most penetrable channel partner type, with subscription-bundling models displacing outright purchase among transient renters. Target Vietnam and Philippines condominium developers for compact-format specification during pre-construction phases. Anchor go-to-market strategy through detergent-subscription recurring revenue rather than hardware margin alone. For Investors and Strategic Acquirers: Roll-up economics work for regional portable specialists with established BIS certification and Maharashtra distribution networks because regulatory fragmentation prevents global players from cost-effectively penetrating India's rental-housing corridors. Long-term viability favors platforms with service-layer subscription attach rates above hardware-only competitors. Watch METI efficiency benchmark acceleration as the signal indicating premium-tier margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Regulatory Pre-Certification | Parallel BIS, GB, and METI approval cuts 8-14 month launch delays for Korean and Japanese exporters. |
| Subscription-Service Bundling | Detergent-subscription models improve lifetime value metrics for Australian property-management channel partners. |
| Ultrasonic Module Integration | Hybrid spray-arm and ultrasonic configurations reduce water consumption below six liters for Osaka premium buyers. |
| Localized Assembly Partnerships | Vietnam and Philippines penetration leverages condominium construction acceleration in sub-5% ownership markets. |
| Water-Pressure Adaptability R&D | Pump specification flexibility addresses inconsistent municipal supply across Indian tier-two cities and Southeast Asia. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance product managers, regulatory compliance officers at SAMR and BIS, property-management procurement leads in Sydney, and distributor principals in Maharashtra and Karnataka. Secondary validation drew from SAMR GB standard filings, BIS mandatory labeling registries, METI Top Runner benchmark publications, and Australia energy-rating program databases. Bottom-up shipment modeling and top-down macroeconomic anchoring provided cross-verification.
Comparable-period anchoring tied projection assumptions to historical efficiency-regulation adoption curves and rental-housing formation trends across the analysis window. Segmentation dimensions spanned product type, end-user category, technology tier, and regional regulatory cluster. CAGRs were derived from fitted adoption curves reflecting urbanization density and nuclear-family household formation. Industry-specific inputs included water-pressure infrastructure quality indices and condominium construction permits for Vietnam and Philippines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to METI efficiency benchmark acceleration and stainless steel commodity volatility. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and rental-tenure duration patterns. Deviation in China's SAMR enforcement intensity or India's BIS labeling compliance rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Digital Showers Market
Appliances
Mexico Laundry Appliances Market
Appliances
Egypt Microwave Ovens Market
Appliances
Industrial Gas Stove Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
Microwave Oven Market
Appliances
Middle East Water Heater Market
Appliances
Egypt Dishwashers Market
Appliances
Germany Consumer Appliances Market
Appliances
Asia Pacific Water Heater Market
Appliances
North America Microwave Oven Market
Appliances
Wall Oven Market
Appliances
India Washing Machine Market
Appliances
Electric Rice Cooker Market
Appliances
Electric Hand Dryer Market
Appliances
Commercial Microwave Ovens Market