
 Large Cooking Appliance Market | 2026-2036
Large Cooking Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Large Cooking Appliance Market Intelligence
The unbundling of cooking functions into separate, specialized appliances like steam ovens and induction cooktops is decoupling the traditional all-in-one range from new kitchen designs. Whirlpool Corporation leverages its extensive distribution network to offer bundled appliance packages to large-scale home builders. Meanwhile, Miele & Cie. KG differentiates through premium, modular units that cater to high-end custom kitchens. Haier Group Corporation competes on smart-home connectivity features across its diverse product portfolio.
Large cooking appliances encompass stationary kitchen equipment designed for thermal food preparation, including ovens, ranges, and cooktops. These devices operate using gas, electricity, or induction technologies, with power ratings typically exceeding 1,500 watts. The residential application segment constitutes the largest share, driven by replacement cycles and housing market trends. Within product types, integrated oven and cooktop ranges remain a volume leader, but standalone induction cooktops represent the fastest-growing category due to their energy efficiency.
Energy efficiency standards, such as the US EPA's ENERGY STAR program, mandate performance levels for appliances sold in North America. In Europe, CE marking and the RoHS directive govern product safety and hazardous substance content, impacting material selection. Future profitability will depend on manufacturers' ability to innovate around smart features while complying with increasingly stringent global energy consumption regulations.
Market Dynamics
The convergence of smart home ecosystems and stringent energy efficiency mandates is the central force shaping the large cooking appliance market. This dynamic compels manufacturers to innovate on both connectivity features and material science to meet consumer expectations and regulatory thresholds simultaneously.
Growth Catalysts
- Energy Efficiency Regulations:The European Union's updated energy labeling rules for household appliances are pushing manufacturers to adopt more efficient technologies, like induction, and redesign components to lower overall energy consumption, stimulating replacement demand.
- Urban Housing Construction:A surge in new residential construction and kitchen renovations, particularly in major urban areas across India and Brazil, creates consistent demand for both integrated ranges and standalone cooking appliances.
- Smart Home Integration:Consumer interest in connected kitchens drives the adoption of appliances with Wi-Fi connectivity, remote diagnostics, and integration with voice assistants, creating a new basis for product differentiation and value.
Market Restraints
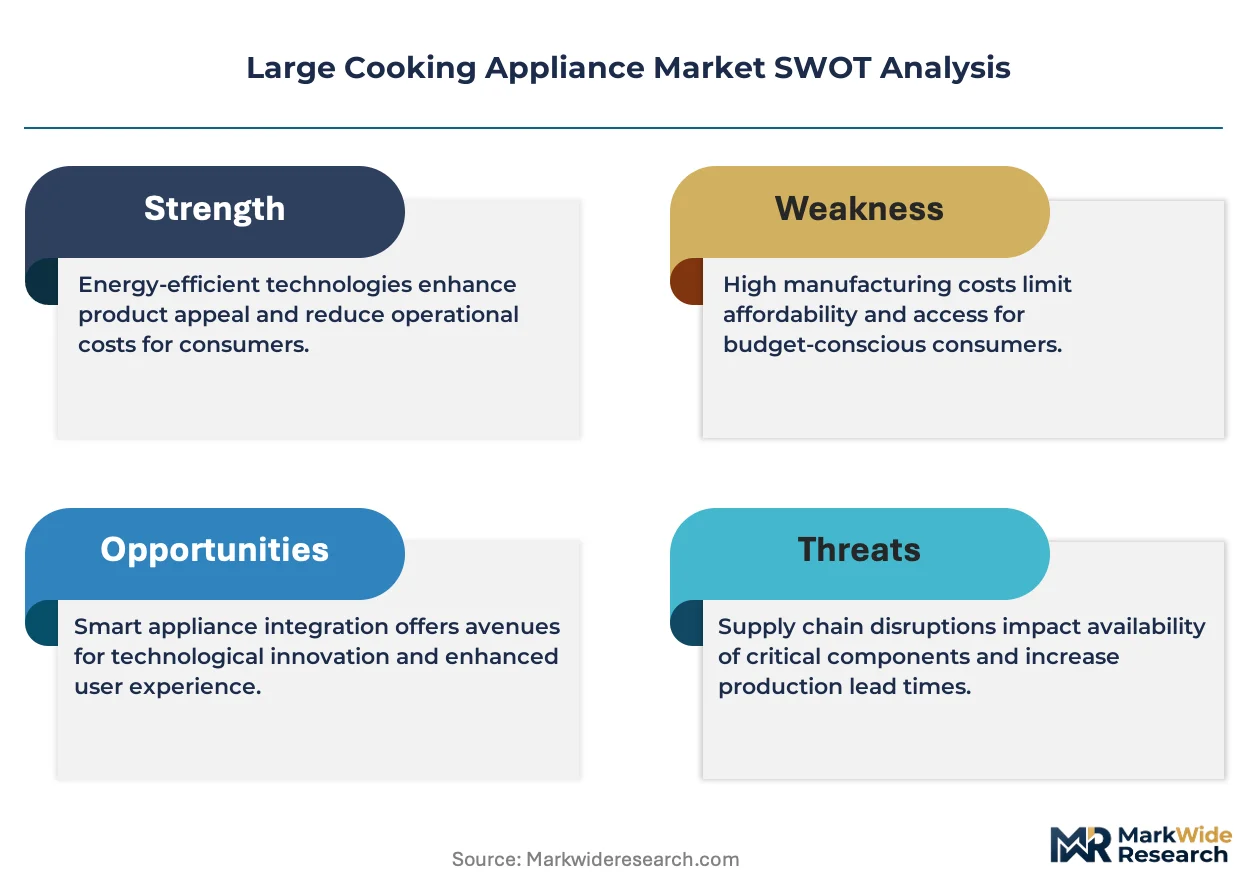
- Input Cost Volatility:Fluctuations in the prices of essential raw materials, including stainless steel, copper for wiring, and semiconductor components for smart controls, create margin pressure and complicate long-term production planning.
- Regulatory Compliance Burden:Adherence to substance-specific regulations like the EU's RoHS directive restricts the use of certain materials, requiring costly reformulation of components and complex supply chain verification processes.
- Countertop Appliance Substitution:The proliferation of powerful, multi-functional countertop devices like combination air fryer ovens presents a substitution threat, especially in smaller urban dwellings where space is limited and a full-size range is not required.
Strategic Opportunities
- Modular Product Systems:Developing modular cooking units, such as individual steam ovens, sous-vide modules, and specialized cooktops, allows manufacturers to cater to the high-end custom kitchen segment and increase average revenue per project.
- Aftermarket Service Expansion:Offering subscription-based services for smart appliances, including guided cooking content, predictive maintenance alerts, and automated consumable replenishment, opens new recurring revenue streams beyond the initial hardware sale.
- Emerging Market Penetration:Targeting middle-class households in fast-growing secondary cities across Southeast Asia represents a significant opportunity, as rising disposable incomes and urbanization fuel first-time purchases of modern kitchen appliances.
Industry Challenges
- Software Development Talent Gap:A scarcity of skilled software engineers and user experience designers capable of creating intuitive and secure connected appliance platforms presents an operational bottleneck for traditionally hardware-focused manufacturers.
- Interoperability and Standardization:Ensuring seamless connectivity between appliances from different brands and across various smart home platforms, such as Google Home and Amazon Alexa, remains a significant technical and strategic challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Cooking Appliance Market |
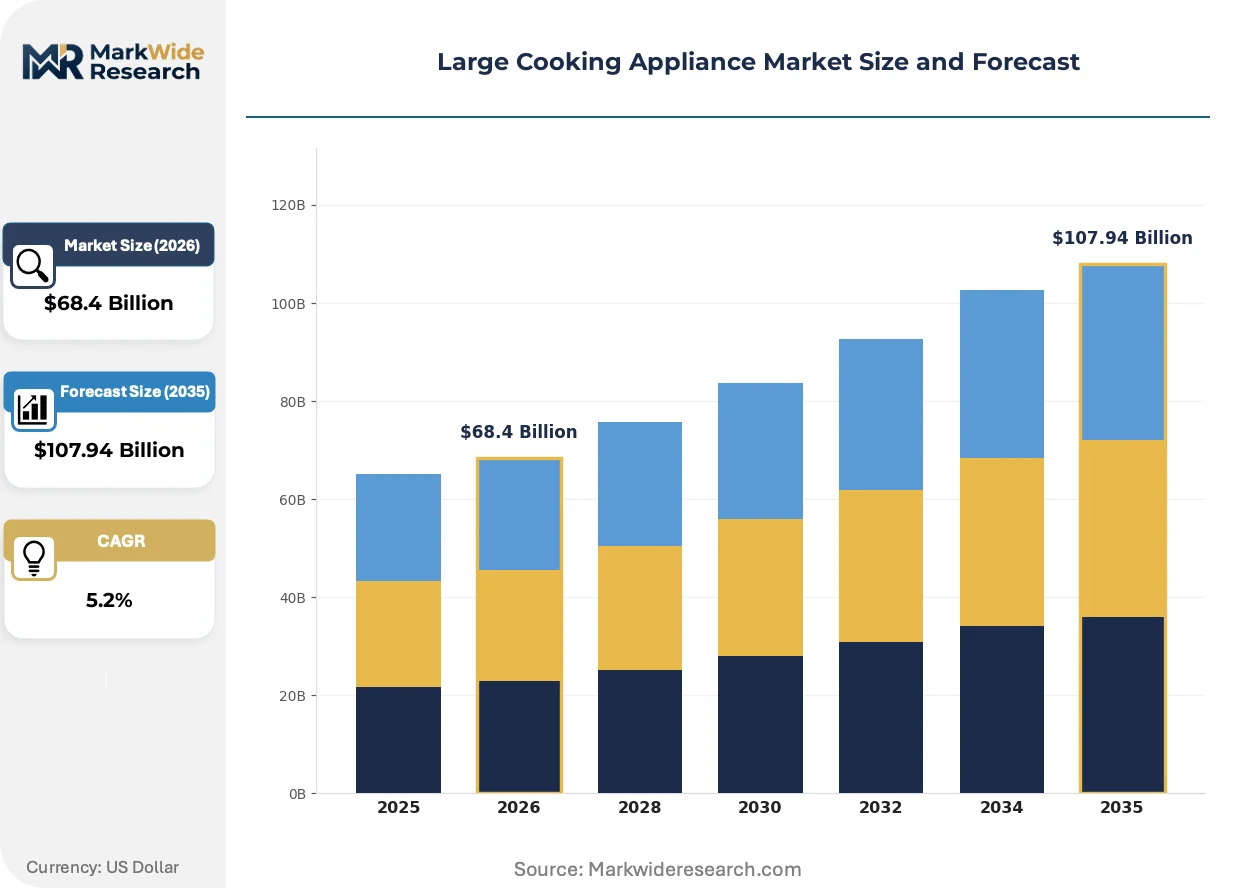
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Ranges, Cooktops, Hoods Application: Residential, Commercial, Industrial, Hospitality End User: Households, Restaurants, Cafes, Catering Services Distribution Channel: Online Retailers, Specialty Stores, Warehouse Clubs, Direct Sales |
| Companies Covered | Whirlpool Corporation, GE Appliances, LG Electronics Inc., Samsung Electronics Co. Ltd., BSH Hausgeräte GmbH, AB Electrolux, Haier Group Corporation, Robert Bosch GmbH, Miele & Cie. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Cooking Appliance Market Strategic Shifts & Innovations
Product design is shifting from monolithic, all-in-one units toward modular, specialized components that offer greater flexibility. This unbundling of cooking functions is driven by software intelligence and a growing consumer preference for customized kitchen environments tailored to specific culinary styles.
Modular cooking components, including separate induction hobs, steam ovens, and warming drawers, allow for personalized kitchen configurations. High-end residential consumers and custom kitchen designers are the primary adopters, seeking to move beyond the traditional range. This trend is decentralizing the appliance suite, breaking the all-in-one oven-cooktop model into discrete, high-performance stations that can be arranged freely within a kitchen layout.
The US EPA's ENERGY STAR program sets performance benchmarks that directly influence product engineering. This framework establishes energy consumption ceilings for appliances, forcing manufacturers to invest in more efficient compressors, insulation, and heating elements. Standalone induction cooktops and convection ovens are the most affected categories, with compliance becoming a key marketing differentiator in the North American market.
A notable behavioral shift involves the procurement of complete kitchen appliance suites by large-scale home builders and developers. This model bypasses traditional consumer-facing retail channels, concentrating purchasing power with a smaller number of high-volume buyers. The practice is most visible in new master-planned communities and multi-family housing projects across the United States and in rapidly urbanizing corridors in Brazil.
Large Cooking Appliance Market Segmentation
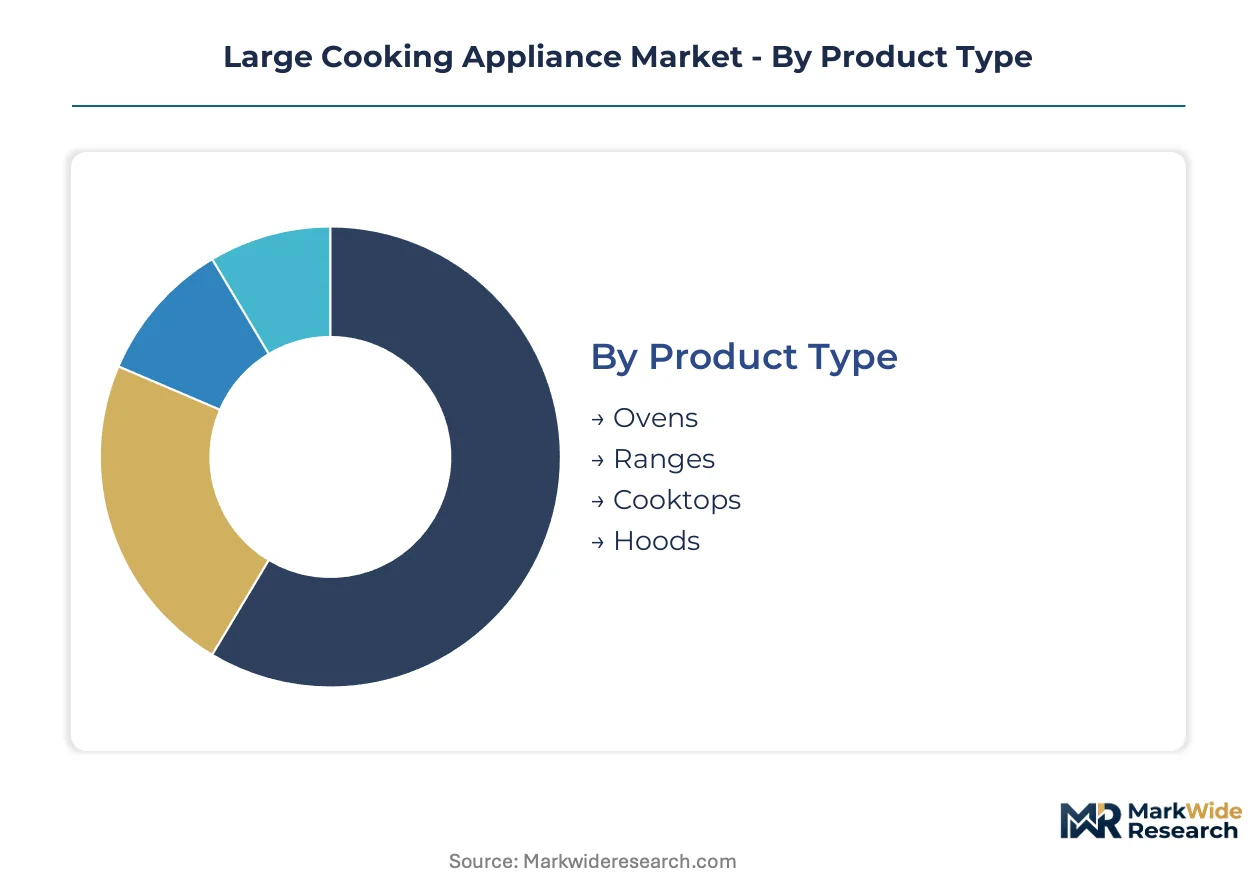
Market segmentation provides a granular view of the large cooking appliance landscape, highlighting the distinct product types, application areas, end-user profiles, and distribution mechanisms. Understanding these divisions is crucial for manufacturers to tailor product development, marketing strategies, and sales efforts effectively across diverse consumer and professional needs.
Product Type:
The functional design and thermal output characteristics define product type segmentation, influencing kitchen utility and culinary capabilities.
- Ranges:Integrated oven and cooktop units remain a volume leader, offering comprehensive thermal preparation capabilities. Demand concentrates in new housing construction and kitchen renovations across India and Brazil.
- Cooktops:Standalone induction cooktops represent the fastest-growing category, providing precise temperature control and energy efficiency. North American consumers prioritize these units for their lower operating costs and modern aesthetics.
- Ovens:These standalone units specialize in thermal food preparation, often featuring convection or steam functions for varied cooking methods.
- Hoods:Ventilation systems designed to remove smoke, steam, and odors from the cooking area, integral to modern kitchen design.
Mature deployment sits with Ranges. Newer deployment is concentrated in Cooktops.
Application:
End-use environment dictates application segmentation, reflecting diverse operational demands and usage patterns.
- Residential:This segment encompasses appliances used in private homes for daily thermal food preparation, constituting the largest market share. Replacement cycles and housing market trends drive consistent demand in urban centers.
- Hospitality:Appliances deployed in hotels, resorts, and cruise ships for high-volume, professional cooking environments. Demand is tied to new establishment openings and extensive kitchen upgrades.
- Commercial:This category includes appliances used in institutional kitchens, catering services, and cafeterias, requiring durability and capacity.
- Industrial:Large-scale cooking equipment utilized in food processing plants and industrial-grade food production facilities.
The Residential segment commands the largest volume. The Hospitality sector exhibits consistent professional-grade demand.
End User:
The scale and frequency of usage define end user segmentation, impacting appliance durability and feature sets.
- Households:Individual consumer units purchasing appliances for domestic use, driven by personal preferences, smart home integration, and replacement needs.
- Restaurants:Professional kitchens requiring robust, high-performance cooking appliances for continuous operation and diverse menu offerings.
- Cafes:Establishments focused on beverage preparation and light meals, often utilizing smaller-footprint cooking equipment.
- Catering Services:Businesses providing food for events, requiring versatile and often portable cooking solutions.
Households represent the primary purchasing entity. Restaurants drive demand for specialized, heavy-duty equipment.
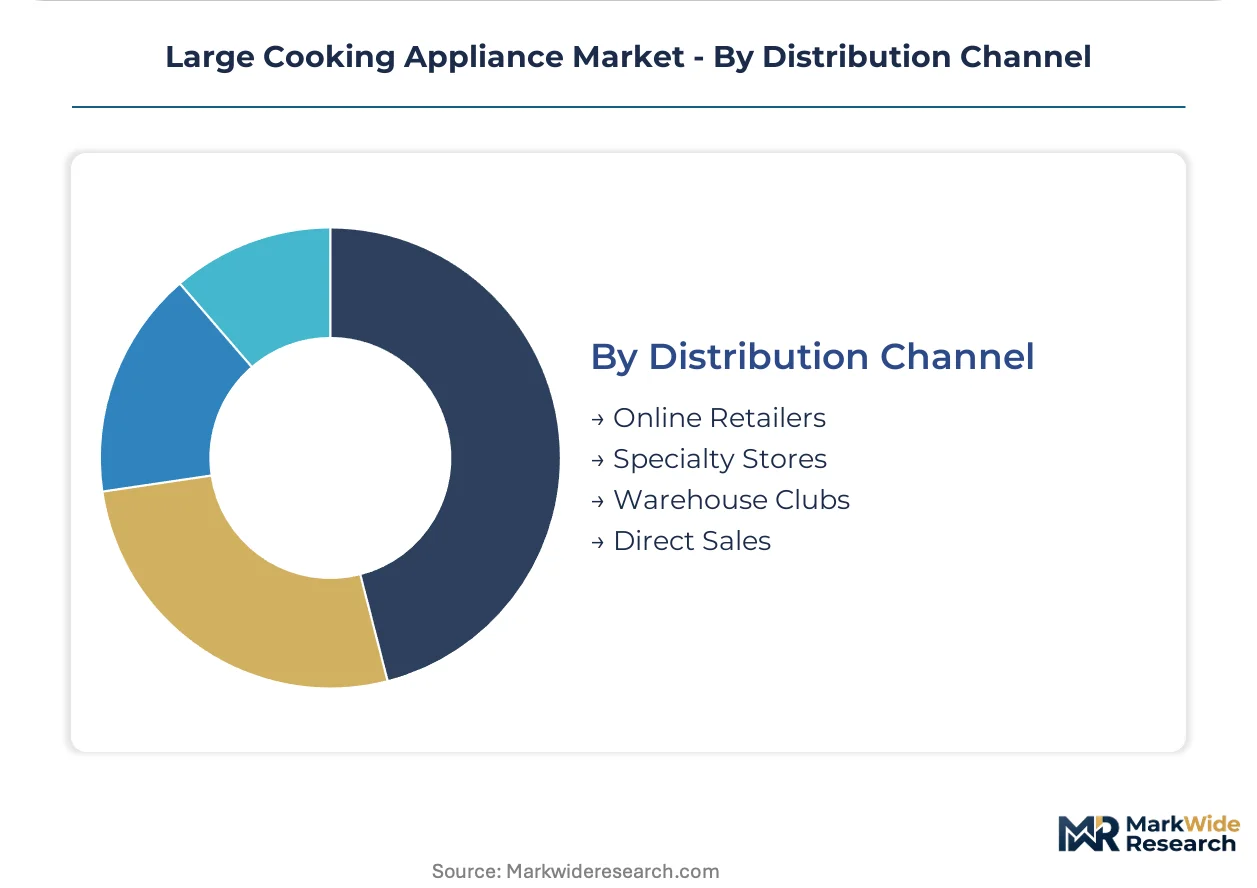
Distribution Channel:
The accessibility and purchasing journey define distribution channel segmentation, influencing consumer reach and product availability.
- Online Retailers:E-commerce platforms offering a wide selection of cooking appliances, benefiting from convenience and competitive pricing for urban consumers.
- Direct Sales:Manufacturers selling directly to large-scale home builders and developers, particularly for new master-planned communities in the United States and Brazil.
- Specialty Stores:Dedicated appliance showrooms providing expert consultation, installation services, and a curated selection of premium brands.
- Warehouse Clubs:Retailers offering bulk purchasing and discounted pricing for a more limited range of appliance models to members.
Online Retailers are expanding their market penetration. Direct Sales channels capture large-scale project demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The large cooking appliance market exhibits a distinct divide between established manufacturing centers and burgeoning consumption hubs. Production capabilities often concentrate in specific regions, while demand growth is increasingly driven by urbanization and rising incomes in emerging economies, creating varied regional dynamics for manufacturers.
United States
Demand in the United States is influenced by replacement cycles, new housing starts, and consumer interest in smart home integration. The US EPA's ENERGY STAR program mandates performance levels for appliances, pushing manufacturers toward more efficient designs. Major metropolitan areas, including those in California and the Northeast Corridor, show consistent demand from both new construction and kitchen renovation projects.
Germany
Germany drives demand for premium, modular cooking units and energy-efficient appliances within Europe. EU energy labeling rules and the RoHS directive significantly influence product design and material selection for manufacturers operating here. Companies in Bavaria and North Rhine-Westphalia focus on high-end manufacturing and cater to custom kitchen segments across the continent.
India
India represents a significant growth catalyst due to rapid urbanization and a surge in new residential construction. The Bureau of Indian Standards (BIS) guides product quality and safety, impacting market entry and design. Major urban centers like Mumbai and Delhi-NCR are experiencing high demand for both integrated ranges and standalone cooking appliances, fueled by middle-class expansion.
Brazil
Brazil's market expansion is tied to new housing construction and kitchen renovations, particularly in its major urban areas. The country's national health surveillance agency, ANVISA, sets product safety standards for appliances sold domestically. São Paulo and Rio de Janeiro are key centers for master-planned communities and multi-family housing projects, driving large-scale appliance procurement.
China
China's market is characterized by strong consumer interest in smart-home connectivity and a diverse product portfolio. National GB standards dictate product specifications and energy efficiency, influencing local and international manufacturers. The Yangtze River Delta region, with its dense urban population and manufacturing base, is a hub for both production and consumption of advanced cooking appliances.
Large Cooking Appliance Market Key Industry Players
The competitive structure tilts toward a tiered model, encompassing global conglomerates, specialized premium manufacturers, and regional players. This market features large diversified appliance groups alongside niche providers catering to specific segments. Dominant competitive moves include portfolio diversification into smart home ecosystems and strategic geographic expansion, particularly into high-growth urban markets.
Among the global players, Whirlpool Corporation exemplifies market leadership through an extensive distribution network, offering bundled appliance packages. Miele & Cie. KG occupies a position in the premium segment, specializing in modular units for high-end custom kitchens. Haier Group Corporation, a Chinese conglomerate, anchors the smart-home connectivity vector across its diverse product portfolio, integrating appliances into broader smart home ecosystems.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| GE Appliances |
| LG Electronics Inc. |
| Samsung Electronics Co. Ltd. |
| BSH Hausgeräte GmbH |
| AB Electrolux |
| Haier Group Corporation |
| Robert Bosch GmbH |
| Miele & Cie. KG |
| Others |
Cost & Logistics Intelligence
Large-scale home builders' procurement concentrates demand, influencing project-based pricing for appliance suites. This model bypasses traditional retail markups.
Pricing Analysis
Margin tightening in the volume segment stems from input cost volatility and intense competition. The dominant pricing model is a hybrid of per-unit transactional sales and contract-based long-term offtake for large developers. Brand premium and certification level, such as ENERGY STAR compliance, drive significant price differentiation. Households acquiring standalone units exhibit higher price sensitivity, while high-end custom kitchen designers prioritize features over cost.
Supply Chain Analysis
Direct sales channels to large-scale home builders characterize a significant portion of appliance distribution. Online retailers expand market penetration for individual consumers. Production capabilities concentrate in China, Germany, and South Korea for components and finished goods. The industry draws from stainless steel, copper for wiring, and semiconductor components. Commodity price volatility for metals and electronics presents a structural supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The large cooking appliance market is navigating a technology-transition phase. Induction cooking technology is steadily displacing traditional electric coil and gas cooktops.
For Market Incumbents: Anticipate continued margin pressure from input cost volatility and competitive pricing in the volume segment. Invest in R&D for advanced energy efficiency and smart home integration to counter substitution threats from countertop appliances. Consolidate component sourcing to mitigate supply chain risks. Control over distribution channels remains a critical lever.
For New Entrants and Emerging Players: Begin with targeting the modular product systems segment, focusing on specialized steam ovens or smart induction hobs. Focus on consumers seeking custom kitchen environments in major urban areas. Offer subscription-based aftermarket services for predictive maintenance. Partner with interior designers and custom home builders as a go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized manufacturers with strong intellectual property in smart features within Germany's premium segment. The market offers long-term viability over a five-to-ten-year window, driven by smart home adoption and energy efficiency mandates. Companies specializing in modular components or advanced software platforms represent attractive acquisition targets. Watch for consolidation among component suppliers as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Modularization | Catapults offerings into high-end custom kitchen segments, increasing average revenue per project. |
| Smart Home Ecosystem Integration | Enhances user experience and creates differentiation in connected appliance offerings for consumers. |
| Energy Star Certification Investment | Boosts marketability and ensures compliance with North American energy efficiency standards. |
| Aftermarket Service Subscription | Generates recurring revenue streams beyond the initial hardware sale and builds customer loyalty. |
| Emerging Market Distribution Expansion | Captures demand from rising middle-class households in fast-growing secondary cities. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for market sizing. The study combined these with primary interviews from product development executives, procurement managers, and kitchen designers. Bottom-up and top-down triangulation validated volume and value figures. Interviews with appliance retailers also provided qualitative insights.
Data-stream reconciliation integrated historical trends with projected growth drivers across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and connectivity features. CAGRs were derived from a multi-variable regression model. Forecast inputs included housing starts and energy efficiency regulation updates.
Underlying measurement precision varies by segment; residential and ranges carry tighter precision than industrial applications. Forecasts reflect assumptions regarding raw material stability and consumer spending patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
Egypt Dishwashers Market
Appliances
Oman Dishwashers Market
Appliances
Mexico Washing Machine Market
Appliances
Mini Refrigerator Market
Appliances
US Portable Washing Machines Market
Appliances
United States Multi-Functional Oven Market
Appliances
Triple Barrel Waver Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Global Electric Water Heaters Market
Appliances
Household Beauty Appliances Market
Appliances
Window Air Conditioners Market
Appliances
Asia Pacific Water Heater Market
Appliances
GCC Microwave Oven Market