
 Europe Microwave Oven Market | 2026-2036
Europe Microwave Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microwave Oven Market Foresight
Specialist appliance retail chains across Western Europe is reconfiguring procurement relationships with manufacturers seeking tighter inventory turns. Whirlpool Corporation leverages its manufacturing footprint in Italy and Poland to sustain replenishment speed for these channels. Samsung Electronics competes through direct-to-retailer logistics programs that bypass traditional wholesale tiers. AB Electrolux anchors its position via exclusive product lines developed for specific retail banners in Scandinavia and the Benelux.
A microwave oven is an electric appliance that generates electromagnetic radiation at frequencies near 2.45 GHz to excite water molecules and produce thermal energy for cooking, reheating, or defrosting food, typically operating at power levels between 600 and 1,200 watts. The primary commercial purpose spans residential meal preparation and foodservice operations requiring rapid thermal processing without conventional fuel combustion. Built-in microwave configurations command premium positioning within kitchen renovation cycles, while countertop units dominate volume through lower entry prices and replacement frequency. Convection technology variants capture margin pools by combining radiant and forced-air heating for expanded cooking functionality.
The EU Ecodesign Directive and REACH frameworks govern energy efficiency thresholds and substance restrictions in microwave oven manufacturing, compelling redesigns of magnetron assemblies and interior coatings. CE marking requirements administered by national market surveillance authorities in Germany, France, and Italy shape product compliance costs and market access timelines. Stakeholders must monitor forthcoming ecodesign tier upgrades and material disclosure obligations to anticipate redesign cycles and supplier qualification demands.
Market Dynamics
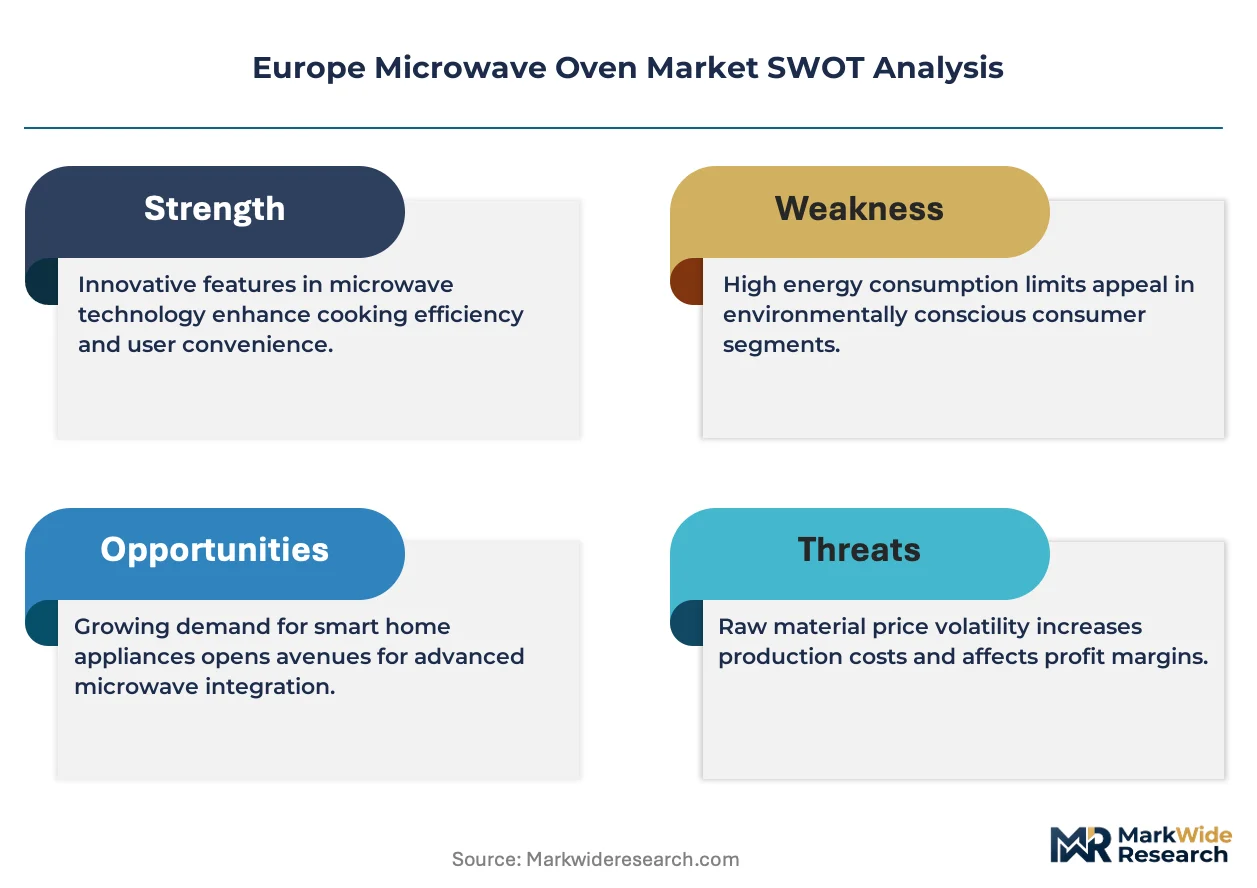
The EU Ecodesign Directive's standby power thresholds are compressing design cycles for magnetron assemblies while specialist retail chains demand faster replenishment from Italian and Polish manufacturing clusters.
Growth Catalysts
- REACH substance restrictions:Manufacturers redesigning interior coatings to eliminate restricted substances are unlocking premium positioning in German and French kitchen renovation channels.
- Urban rental household formation:Compact countertop configurations capture replacement demand across metropolitan rental markets in the United Kingdom and the Netherlands.
- Convection technology convergence:Forced-air heating integration expands cooking functionality for residential meal preparation segments seeking single-appliance versatility.
Market Restraints
- Magnetron supply concentration:Core component sourcing clusters in East Asian manufacturing regions create vulnerability for European assembly operations.
- CE marking timeline friction:National market surveillance authorities in Italy and Germany extend product certification durations, delaying commercial launches.
- Built-in configuration cost structure:Premium kitchen renovation cycle dependency limits volume expansion compared to countertop replacement frequency.
Strategic Opportunities
- Benelux retail banner exclusives:Underserved specialist chains seek differentiated product lines with regional specification customization.
- EU Green Deal ecodesign tier upgrades:Anticipated standby power threshold reductions reward early redesign investment with compliance lead time.
- Direct-to-retailer logistics bypass:Electronics manufacturers eliminating wholesale tiers capture margin and velocity advantages in Scandinavian distribution.
Industry Challenges
- Magnetron engineering talent scarcity:Specialized electromagnetic design expertise concentrates with legacy suppliers, constraining in-house development.
- Material disclosure obligation complexity:REACH documentation requirements demand supplier qualification systems that smaller component vendors struggle to satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microwave Oven Market |
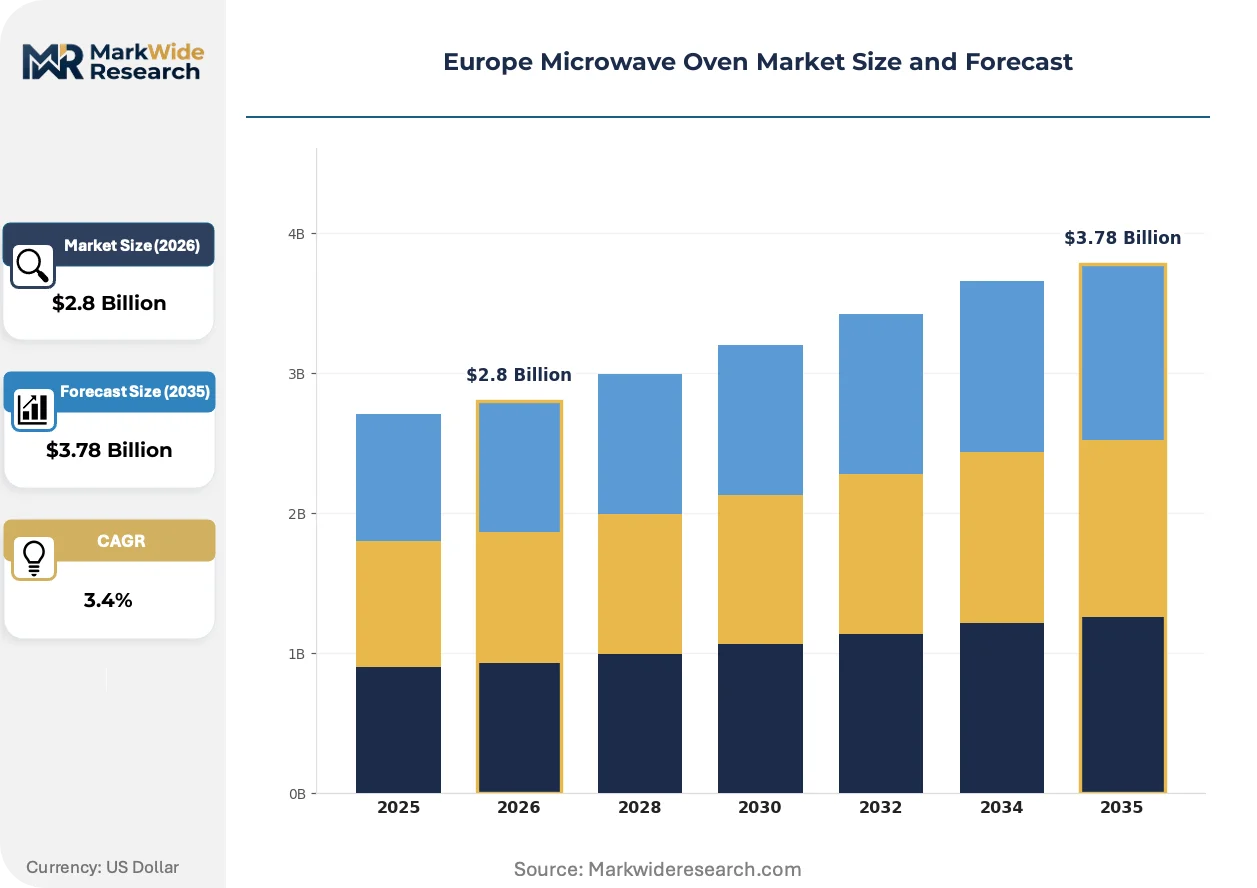
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Over-the-range, Commercial Technology: Convection, Grill, Solo, Sensor End User: Household, Restaurants, Cafés, Institutions Distribution Channel: Online, Supermarkets, Appliance Retailers, Direct Sales |
| Companies Covered | Samsung Electronics, Whirlpool Corporation, LG Electronics, Panasonic Corporation, Illinois Tool Works Inc, Sharp, Haier, Midea Group, AB Electrolux, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microwave Oven Market Shifts & Advancements
Smart connectivity integration is reconfiguring control interfaces and energy management protocols across residential appliance categories. Manufacturers now compete on software-enabled functionality rather than thermal performance alone.
Inverter power control technology is virtualizing traditional magnetron fixed-output architecture. Premium residential segments in Germany and France adopt variable power delivery for precise temperature management. This capability is virtualizing the distinction between reheating and cooking functionality, compressing separate appliance categories into unified configurations.
The EU Ecodesign Directive's forthcoming tier upgrades mandate lower standby power consumption thresholds for household appliances. Manufacturers must redesign power supply architectures and control board sleep states to maintain market access. Built-in microwave configurations face the steepest redesign burden due to integrated installation complexity and longer replacement cycles.
Specialist appliance retail chains now demand vendor-managed inventory programs with weekly replenishment commitments. This model displaces traditional seasonal buy-in patterns across Western European distribution. Scandinavian and Benelux markets exhibit the most advanced adoption, with inventory risk transferring upstream to manufacturers.
Europe Microwave Oven Market Segmentation
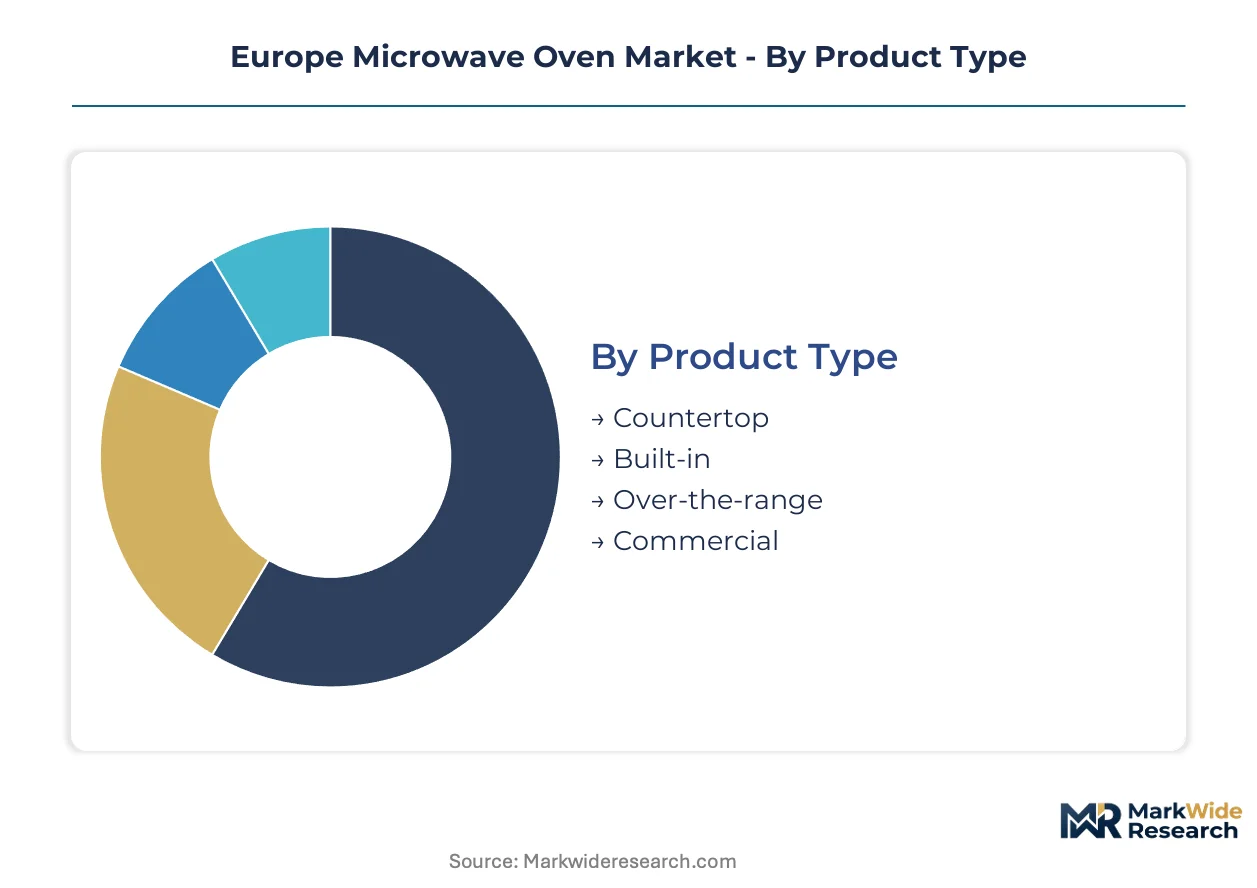
Microwave oven segmentation in Europe reflects divergent service intensity, installation complexity, and replacement cadence across residential and commercial channels. Each dimension shapes margin architecture, channel strategy, and regulatory exposure differently.
Product Type:
After-sales service intensity varies sharply across installation configurations, with built-in units demanding specialized technician networks and countertop models relying on retail exchange programs.
- Countertop:Freestanding units with plug-and-play deployment dominate volume through lower price points and rapid replacement cycles. Demand concentrates in urban rental households across the United Kingdom and the Netherlands, driven by mobility-driven appliance turnover and limited kitchen modification rights.
- Built-in:Integrated cabinet installations requiring custom trim kits and electrical hardwiring command premium positioning within kitchen renovation cycles. German and French residential markets anchor demand, constrained by extended replacement timelines and installer capacity bottlenecks.
- Over-the-range:Combined ventilation-cooking units targeting space-constrained kitchens see selective adoption in Benelux and Scandinavian new-build housing.
- Commercial:Heavy-duty stainless-steel configurations with accelerated duty cycles serve foodservice operations in institutional and high-throughput restaurant settings.
Countertop holds the largest share; momentum sits with built-in configurations as kitchen renovation spending persists.
Technology:
Cost tier stratification separates premium inverter-driven systems from entry-level magnetron architectures, with convection variants capturing expanded functionality premiums.
- Convection:Forced-air circulation combined with radiant heating enables roasting and baking functions beyond standard microwave reheating. German and French premium residential segments drive adoption, seeking single-appliance versatility to compress countertop footprint.
- Grill:Quartz or sheath-heating elements add browning capability for protein preparation. Mediterranean markets show elevated preference for grilled texture replication in compact formats.
- Solo:Basic magnetron-only configurations serve price-sensitive replacement demand and secondary kitchen installations.
- Sensor:Humidity and temperature feedback systems automate power adjustment based on steam detection, reducing user intervention.
Convection commands the premium tier; sensor technology is climbing the fastest as manufacturers integrate smart connectivity protocols.
End User:
Volume concentration sits with residential households, while margin pools concentrate in commercial segments with specialized durability requirements and service contract attachment.
- Household:Individual and family residential units represent the foundational demand base, with replacement cycles averaging shorter in rental versus owner-occupied housing.
- Restaurants:Quick-service and casual dining operations require rapid thermal processing for prep-line efficiency, driving demand for commercial-grade power ratings and stainless-steel construction.
- Cafés:Limited-menu beverage-focused establishments adopt compact countertop units for pastry warming and light meal preparation.
- Institutions:Healthcare, education, and corporate catering facilities specify heavy-duty configurations with extended warranty and preventive maintenance programs.
Household anchors absolute volume; institutions show the steepest expansion trajectory as outsourcing of foodservice operations accelerates.
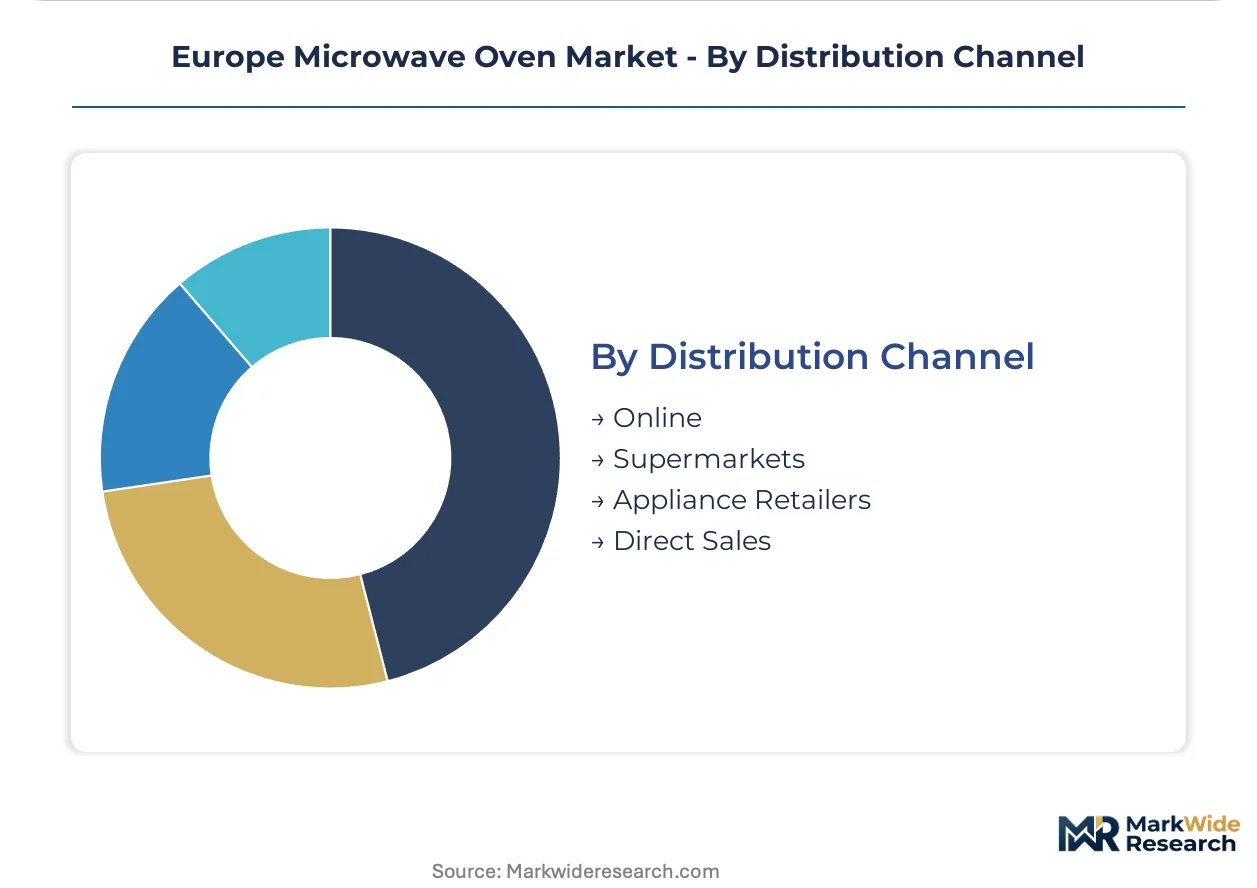
Distribution Channel:
Customer type and purchase urgency shape channel selection, with planned renovation projects favoring specialist consultation and urgent replacement driving online and mass retail.
- Online:E-commerce platforms capture convenience-oriented replacement demand and specification research for subsequent in-store conversion, with delivery logistics becoming a competitive battleground.
- Supermarkets:Mass merchandisers move entry-level countertop units through high-traffic locations, emphasizing promotional pricing and impulse purchase capture.
- Appliance Retailers:Specialist chains provide installation coordination and extended service contracts, dominating built-in and premium convection sales.
- Direct Sales:Manufacturer-controlled channels bypass wholesale margins for large-format commercial and institutional procurement.
Appliance retailers retain the largest share; online channels are gaining share fastest as logistics investments compress delivery windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor connects Rotterdam to Milan and underwrites appliance distribution velocity across the continent's densest manufacturing belt.
Germany
Kitchen renovation spending and premium built-in demand anchor the region's largest national market. The Federal Environment Agency enforces standby power thresholds under the EU Ecodesign Directive that compress design cycles for control board architectures. Manufacturing clusters in North Rhine-Westphalia host assembly operations serving specialist retail chains with weekly replenishment commitments.
United Kingdom
Urban rental household formation drives countertop replacement frequency in London and Manchester metropolitan zones. The Office for Product Safety and Standards administers CE marking recognition post-Brexit, creating parallel compliance pathways for imported units. Distribution centers in the Midlands handle cross-channel logistics for e-commerce platforms compressing delivery windows.
France
Convection technology adoption concentrates in Île-de-France and Auvergne-Rhône-Alpes residential renovation markets. ANSM and environmental regulators coordinate REACH substance disclosure enforcement for interior coating materials. Industrial operations in Hauts-de-France specialize in magnetron component sourcing for regional assembly networks.
Italy
Compact appliance demand from Mediterranean rental markets sustains countertop volume in Milan and Rome corridors. The Ministry of Economic Development implements EU Green Deal ecodesign tier upgrades through national market surveillance protocols. Manufacturing clusters in Lombardy and Emilia-Romagna produce trim kits and integrated installations for built-in configurations.
Netherlands
Space-constrained housing in the Randstad drives over-the-range and compact format preference. The Human Environment and Transport Inspectorate enforces energy labeling requirements that shape procurement specifications for retail banners. Rotterdam port infrastructure handles component imports for redistribution to Polish and Italian assembly operations.
Europe Microwave Oven Market Competitive Landscape
On the supply side, the industry is structured around three tiers: diversified appliance conglomerates with captive manufacturing, electronics specialists leveraging component synergies, and private-label fabricators serving retail banners. Strategic archetypes include vertically integrated volume producers, technology licensors monetizing inverter control patents, and regional specialists capturing renovation-channel premiums. Competitive moves concentrate on direct-to-retailer logistics bypass programs and exclusive product line development for specific retail banners.
Within the diversified conglomerate tier, Whirlpool Corporation and AB Electrolux exemplify European manufacturing footprint strategies, anchoring positions through Italian and Polish assembly clusters. Samsung Electronics occupies a position representing electronics-first entrants competing through supply chain velocity rather than appliance heritage. These three entities illustrate distinct archetype approaches: captive regional production, retail banner exclusivity, and direct logistics integration.
| Leading Market Players |
|---|
| Samsung Electronics |
| Whirlpool Corporation |
| LG Electronics |
| Panasonic Corporation |
| Illinois Tool Works Inc |
| Sharp |
| Haier |
| Midea Group |
| AB Electrolux |
| Others |
Supply & Pricing Matrix
Magnetron supply concentration in East Asian manufacturing clusters compresses pricing power across European assembly operations while simultaneously forcing tiered sourcing strategies that separate premium inverter configurations from entry-level magnetron architectures. This single-source dependency for core electromagnetic components determines both the spread between countertop and built-in pricing tiers and the geographic shape of component procurement networks.
Pricing Analysis
Volume-discount tiering structures stratify across premium convection-inverter systems, standard grill-equipped configurations, and economy solo magnetron units. Price differentiation rests on certification grade under EU Ecodesign standby power thresholds and after-sales service bundling through specialist retail channels. Pricing pressure stems from REACH compliance costs for interior coating redesigns, with German and French kitchen renovation buyers showing lowest price sensitivity while UK urban rental households exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Chinese component suppliers and Polish assembly operations dominates supply chain risk calculus for European manufacturers. Magnetron sourcing concentrates in China, South Korea, and Japan, while final assembly clusters in Italy and Poland draw from these inputs. Distribution runs through the Rhine-Alpine freight corridor connecting Rotterdam port infrastructure to Milan manufacturing hubs, with vendor-managed inventory programs transferring replenishment risk upstream to appliance producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe microwave oven market sits at a post-regulatory-shock recovery phase as EU Ecodesign tier upgrades compress design cycles and force capital redeployment toward compliance-ready architectures. Kitchen renovation spending persistence across Germany and France provides the cyclical demand floor justifying near-term positioning.
For Market Incumbents: Harden magnetron supply security through dual-source qualification programs spanning Japanese and South Korean component vendors. Deepen captive production of inverter control assemblies in Polish manufacturing clusters to offset REACH-driven coating cost inflation. Channel control through exclusive retail banner relationships in Scandinavia and Benelux defends margin pools against direct-to-retailer logistics entrants.
For New Entrants and Emerging Players: Mid-market convection configurations for Netherlands and UK urban rental households represent the most penetrable entry point given incumbent concentration in premium built-in segments. Direct-to-retailer logistics bypass programs for Scandinavian specialist chains unlock velocity advantages without wholesale tier margin sacrifice. White-label fabrication for private-label retail banners in Southern Europe offers lowest-barrier volume accumulation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technology licensors with inverter control patent portfolios over capital-intensive assembly operators. Long-term viability hinges on software-enabled functionality differentiation rather than thermal performance commoditization. Acquisition target archetypes include regional specialists with captive Scandinavian retail relationships. The signal to watch is EU Green Deal ecodesign tier announcement timing for compliance investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Patent Licensing | Monetizes variable power control architectures across German and French premium residential segments. |
| Direct-to-Retailer Logistics Bypass | Eliminates wholesale margin extraction for Samsung Electronics and LG Electronics in Scandinavian distribution. |
| REACH-Compliant Coating Redesign | Unlocks kitchen renovation channel access through ANSM-enforced substance disclosure compliance. |
| Vendor-Managed Inventory Programs | Transfers replenishment risk to Whirlpool Corporation and AB Electrolux for Benelux specialist chains. |
| Smart Connectivity Protocol Integration | Virtualizes control interfaces beyond thermal performance for residential meal preparation segments. |
Research Methodology
Cross-validation between primary interviews with appliance category managers, magnetron procurement leads, and specialist retail chain buyers anchors the qualitative findings against secondary validation from SEC 10-K filings, EU Ecodesign regulatory impact assessments, and customs trade data. Bottom-up triangulation across product type, technology tier, and distribution channel dimensions converges with top-down macroeconomic overlay analysis.
Calibration against historical replacement cycle data and kitchen renovation spending indices shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include installation configuration, heating technology architecture, end-user category, and geographic regulatory cluster. CAGRs derive from regression analysis against household formation rates and ecodesign compliance cost trajectories, with inverter adoption curves and standby power threshold schedules as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Eurozone construction activity and cross-border freight cost indices would shift the trajectory for built-in configuration demand and component import economics. Forecasts reflect documented assumptions regarding regulatory implementation timelines and magnetron supply availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
France Household Side by Side Refrigerator Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Global Electric Water Heaters Market
Appliances
United States Electric Kettle Market
Appliances
Electric Hand Dryer Market
Appliances
Electrical Appliances Plastics Market
Appliances
US Washing Machine Parts Market
Appliances
Electric Ranges Market
Appliances
GCC Dishwashers Market
Appliances
United States Washing Machine Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Window Air Conditioners Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Laundry Dryer Market
Appliances
Turkey Washing Machine Market
Appliances
Middle East and Africa Commercial Dishwashers Market