
 United States Electronics and Appliance Stores Market | 2026-2036
United States Electronics and Appliance Stores Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electronics and Appliance Stores Market Outlook
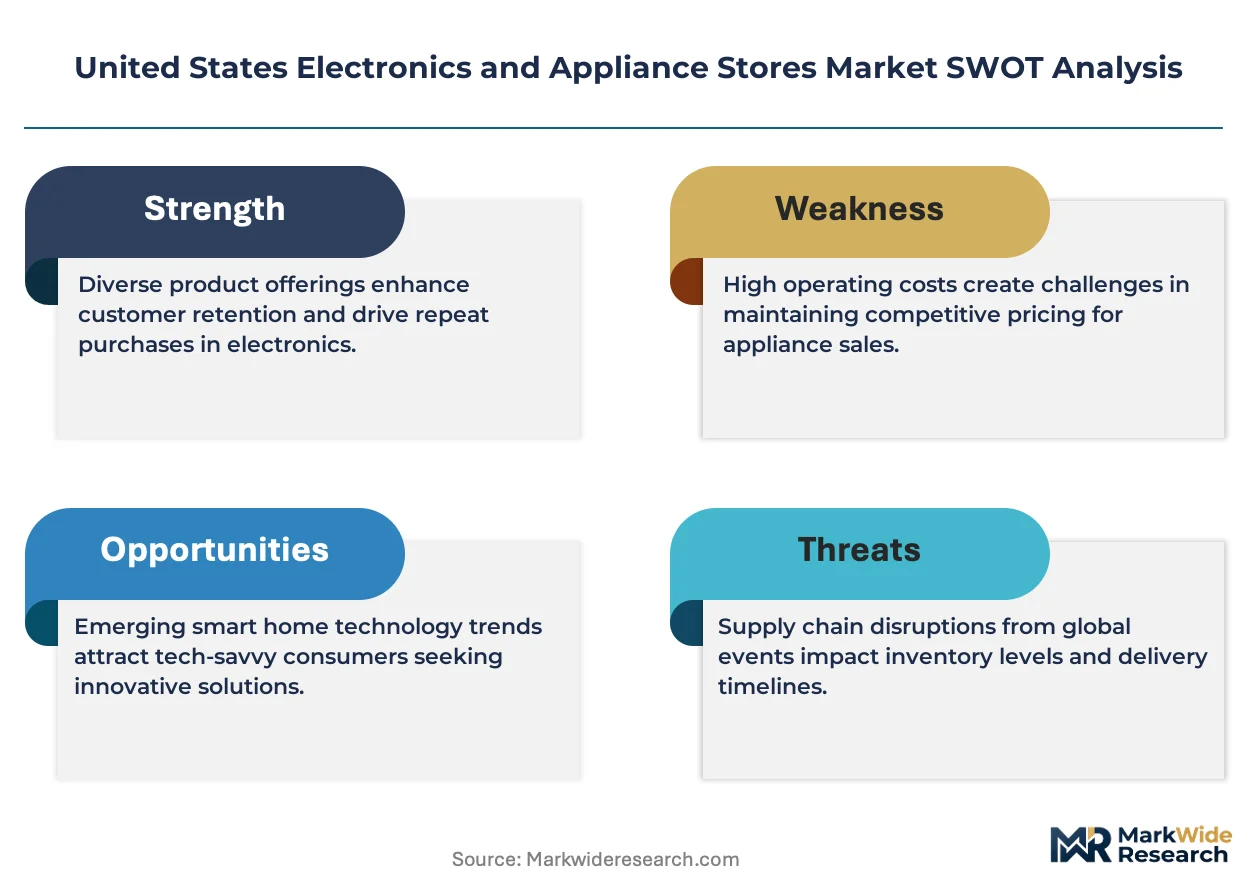
Domestic appliance manufacturing capacity in the southeastern United States is decoupling from overseas component dependency as reshoring incentives take hold. Best Buy Co., Inc. leverages its Geek Squad services to sustain recurring revenue attachment rates on big-ticket installations. Amazon.com, Inc. anchors same-day electronics fulfillment through dense last-mile node expansion. Apple Inc. controls premium positioning via direct retail experience design that competitors struggle to replicate.
United States Electronics and Appliance Stores comprise physical and digital retail establishments specializing in consumer durables including televisions with 4K and 8K resolution specifications, compression-cycle refrigeration systems, and front-load washing platforms with variable spin speeds, serving residential replacement cycles and new household formation. The product type dimension shows refrigerators and smart televisions capturing margin pools as replacement intervals shorten and screen size preferences expand. Customer type dynamics reveal educational institutions and government procurement channels gaining structural importance as bulk technology refresh programs institutionalize volume purchasing.
Federal Trade Commission advertising standards and Department of Energy certification requirements shape product labeling and efficiency minimums that determine market access eligibility. State-level building codes in California and New York impose additional appliance efficiency tiers that filter national assortment planning. Stakeholders must monitor Federal Communications Commission equipment authorization processes for emerging IoT device categories that increasingly dominate store assortments.
Market Dynamics
The Department of Energy's appliance efficiency standards are compressing manufacturer product cycles while suburban smart home adoption pulls connected inventory through retail channels faster than replacement intervals alone would dictate.
Growth Catalysts
- DOE Efficiency Standards:Federal minimums for compression-cycle refrigeration and variable-speed washing platforms force inventory turnover, creating sustained replacement demand across Texas, Florida, and California housing markets.
- Smart Home Protocol Convergence:Matter and Thread interoperability standards reduce consumer friction in connected device ecosystems, accelerating attachment rates for IoT-enabled appliances in new household formation.
- Educational Bulk Procurement:Federal E-Rate program subsidies and state technology refresh mandates institutionalize volume purchasing through certified electronics channels, shifting demand from consumer to institutional buyers.
Market Restraints
- Semiconductor Input Volatility:Display driver ICs and power management chips remain concentrated in Taiwan and South Korea foundries, exposing television and appliance pricing to geopolitical supply shocks.
- California Title 20/24 Overlap:State appliance efficiency tiers exceed federal DOE minimums, forcing national retailers to fragment assortment planning or absorb compliance costs for non-compliant SKUs.
- Last-Mile Density Thresholds:Same-day fulfillment economics require population density levels that exclude rural and ex-urban markets from service parity, capping addressable market expansion.
Strategic Opportunities
- Southeastern Reshoring Corridors:Georgia and Tennessee manufacturing incentives attract compressor and motor assembly capacity, reducing overseas component dependency for domestic appliance brands.
- Installation Service Unbundling:Geek Squad-style white-glove setup and ongoing maintenance contracts create recurring revenue streams independent of hardware margins in premium suburban segments.
- FCC Equipment Authorization Pre-Certification:Early engagement with emerging IoT device categories enables first-mover shelf placement as connected appliance SKUs proliferate.
Industry Challenges
- Field Technician Scarcity:Refrigerant handling certification and smart home network diagnostics require cross-trained labor pools that vocational pipelines have not scaled to match demand in high-growth Sun Belt metros.
- Legacy System Integration Friction:Retrofit installations of connected appliances into pre-2010 residential electrical infrastructure trigger contractor coordination delays and customer satisfaction erosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electronics and Appliance Stores Market |
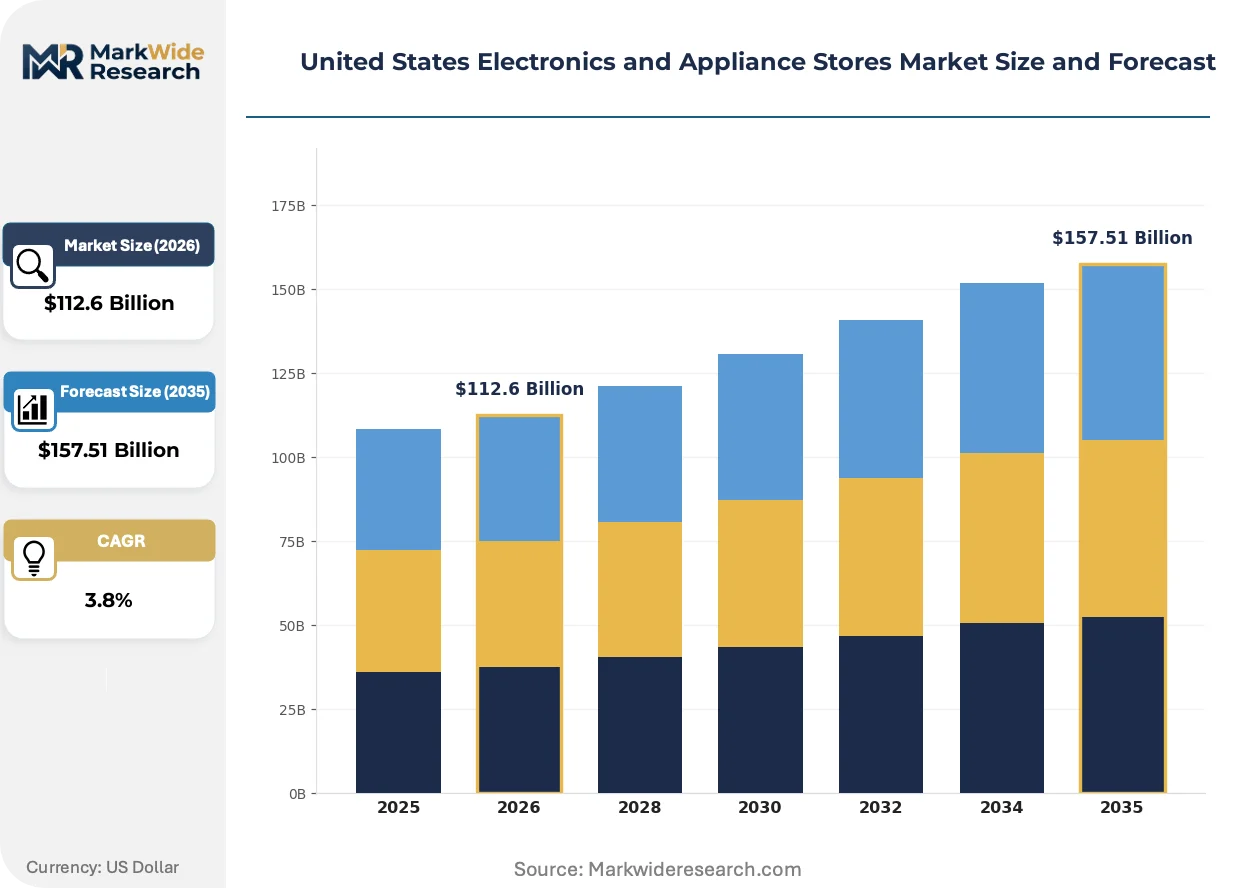
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $157.51 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Televisions, Laptops, Refrigerators, Washers Customer Type: Households, Businesses, Educational Institutions, Government Sales Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales Technology: Smart Technology, LED, IoT Devices, Energy Efficient Appliances |
| Companies Covered | Amazon.com, Inc., Best Buy Co., Inc., Apple Inc., Lowe’s Companies, Inc., Home Depot, Inc., Costco Wholesale Corporation, Walmart Inc., Target Corporation, GameStop Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electronics and Appliance Stores Market Strategic Shifts
Retail assortment planning is compressing around three converging forces: unified control protocols dissolving ecosystem lock-in, efficiency regulations accelerating product obsolescence, and fulfillment infrastructure redefining service expectations.
Smart home control platforms are unifying previously siloed appliance, lighting, and security systems under single-interface management. Suburban households with Matter-certified hubs now expect seamless interoperability across refrigerator, washing platform, and entertainment device categories. This protocol convergence is unifying purchase decisions around ecosystem compatibility rather than standalone brand preference, compressing vendor switching costs.
The FTC's Green Guides enforcement and DOE EnergyGuide label accuracy requirements are tightening advertising claims around appliance efficiency. Manufacturers now face civil penalty exposure for overstated consumption metrics, forcing recertification investments and label redesign cycles. California's Title 20 appliance database mandates are extending this scrutiny to online listings, requiring retailers to maintain real-time compliance documentation.
Service unbundling is separating hardware transactions from installation, maintenance, and disposal obligations. Premium suburban buyers increasingly purchase extended protection plans and same-day setup through separate contractual vehicles rather than bundled point-of-sale offers. Texas and Florida markets exhibit the highest attachment rates for these unbundled services, correlating with higher average screen sizes and connected appliance penetration.
United States Electronics and Appliance Stores Market Segmentation
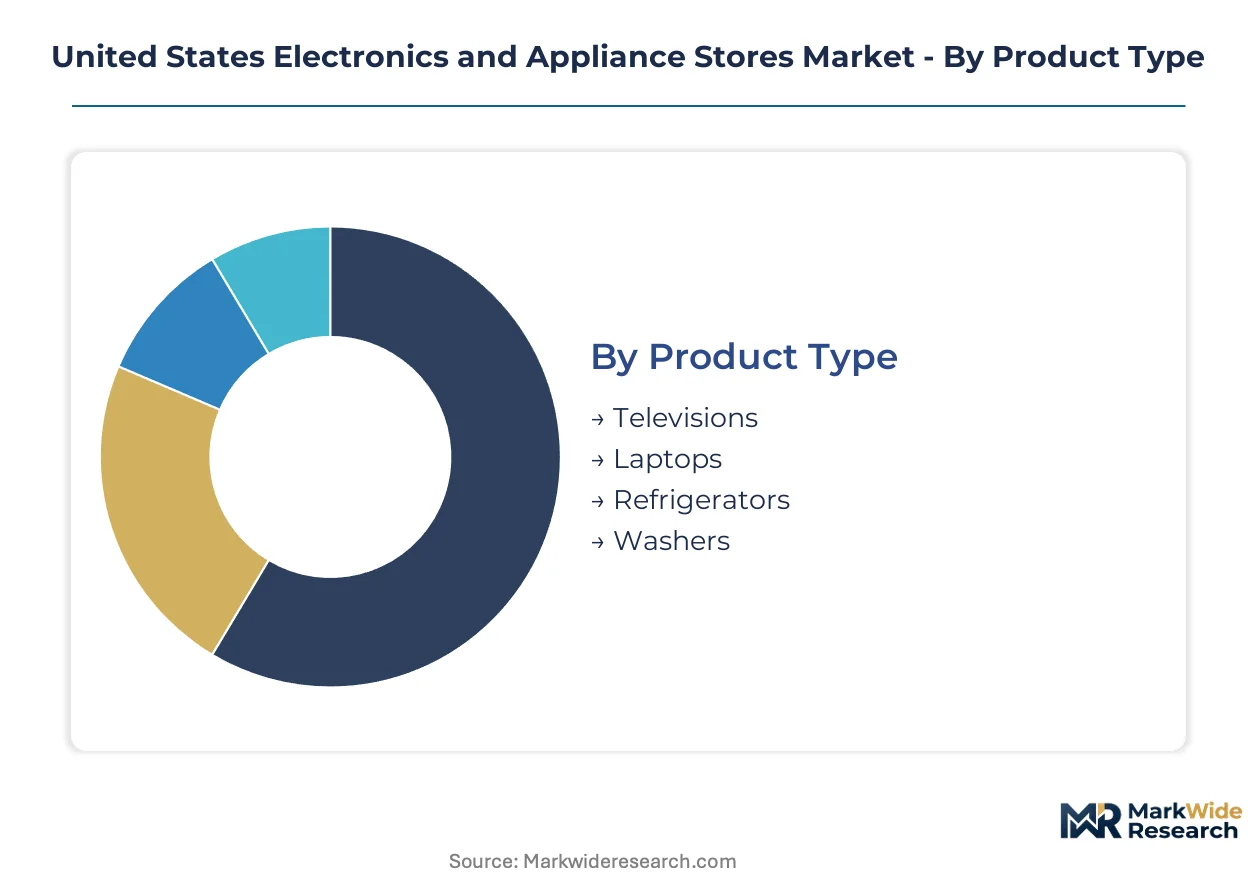
Electronics and appliance retailers configure inventory, staffing, and fulfillment infrastructure around distinct buyer profiles and product specifications. Segmentation reveals where margin pools concentrate and which technology transitions warrant capital allocation.
Product Type:
Purchase frequency and replacement intervals drive assortment depth decisions across retail formats.
- Televisions:4K and 8K resolution specifications dominate shelf space as screen size preferences expand beyond 65 inches in Texas and California suburban markets. Replacement cycles compress below seven years as display technology advances.
- Refrigerators:Compression-cycle systems with variable-speed compressors capture premium positioning under DOE efficiency standards. Demand concentrates in Florida and California where housing construction and population migration trigger replacement waves.
- Laptops:Educational bulk procurement and remote work infrastructure sustain volume through certified channels.
- Washers:Front-load platforms with variable spin speeds align with federal efficiency minimums and water conservation codes in drought-affected states.
Refrigerators lead on scale; televisions lead on momentum.
Customer Type:
Procurement patterns diverge sharply between transactional household purchases and institutional volume contracting.
- Households:Suburban smart home adoption accelerates connected appliance purchases through ecosystem compatibility considerations rather than standalone brand loyalty.
- Educational Institutions:Federal E-Rate program subsidies and state technology refresh mandates institutionalize volume purchasing through certified electronics channels, shifting demand from consumer to institutional buyers.
- Businesses:Corporate technology refresh programs prioritize fleet standardization and extended warranty terms over point-of-sale pricing.
- Government:Procurement compliance requirements and bulk scheduling create predictable demand windows that contrast with household replacement volatility.
Households dominate transaction volume; educational institutions dominate contract value growth.
Sales Channel:
Fulfillment economics and service attachment rates vary dramatically by channel configuration.
- Online Retail:Same-day fulfillment infrastructure requires population density thresholds that exclude rural markets, capping addressable expansion in ex-urban geographies.
- Brick-and-Mortar:Geek Squad-style installation services sustain recurring revenue attachment rates on big-ticket appliances in premium suburban segments.
- Wholesale:Contractor and builder supply relationships concentrate in southeastern reshoring corridors where domestic manufacturing capacity expands.
- Direct Sales:Manufacturer-controlled retail experience design captures premium positioning that competitors struggle to replicate.
Brick-and-mortar leads on service revenue per unit; online retail leads on geographic expansion velocity.
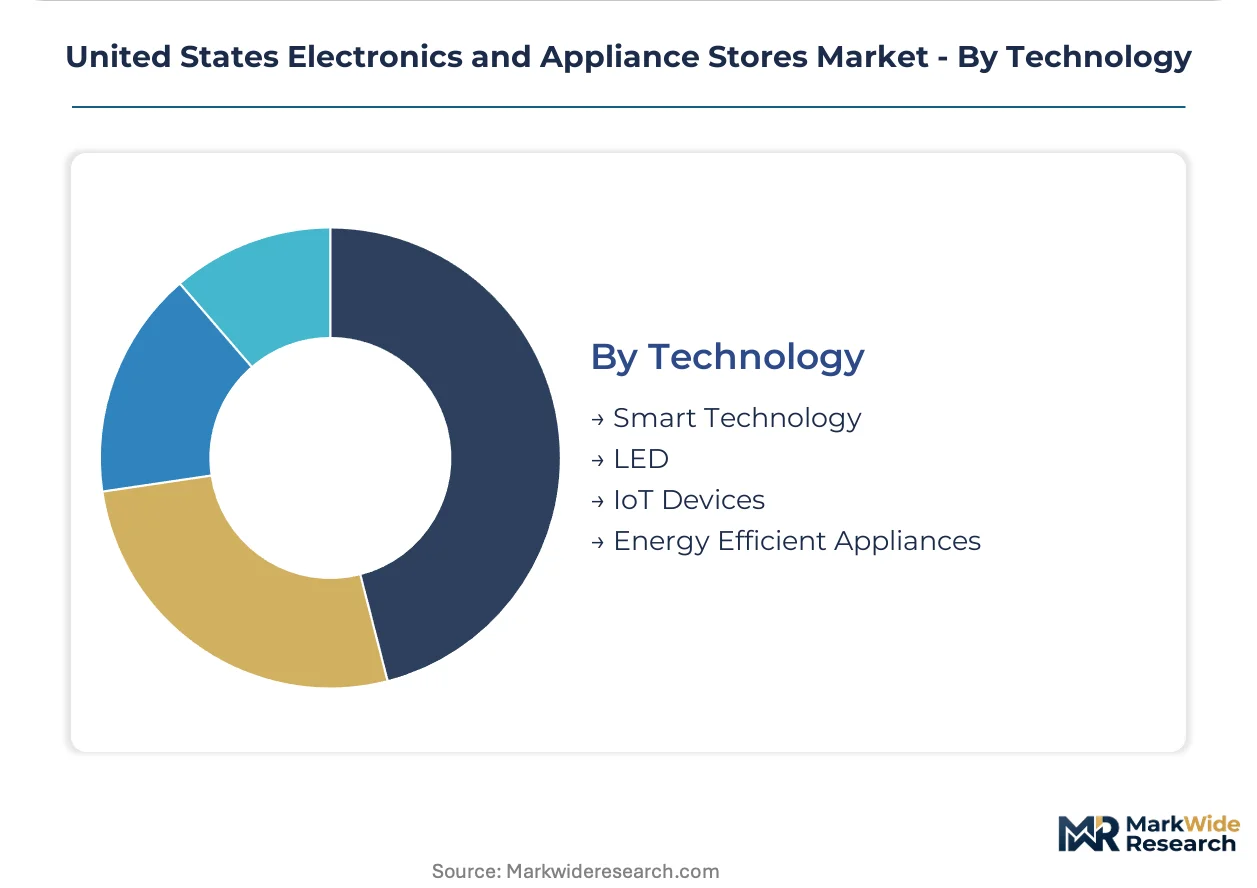
Technology:
Regulatory certification requirements and interoperability standards determine market access eligibility.
- Smart Technology:Matter and Thread protocol convergence reduces consumer friction in connected device ecosystems, unifying purchase decisions around hub compatibility.
- IoT Devices:FCC equipment authorization processes for emerging categories enable first-mover shelf placement as connected appliance SKUs proliferate.
- LED:Display backlighting efficiency meets DOE standby power requirements while supporting thinner form factors.
- Energy Efficient Appliances:California Title 20 and Title 24 tiers exceed federal minimums, fragmenting assortment planning for national retailers.
Energy efficient appliances lead on regulatory compliance scale; IoT devices lead on innovation momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas housing starts outpace California migration flows, yet both states concentrate appliance replacement demand through distinct regulatory and demographic channels. Sub-regional performance diverges sharply across Sun Belt metros, Rust Belt legacy infrastructure, and coastal efficiency mandates.
Texas
Houston and Dallas-Fort Worth construction permits drive compression-cycle refrigerator turnover as new household formation accelerates. The Texas Commission on Environmental Quality coordinates with federal DOE standards without overlaying additional efficiency tiers. Domestic appliance assembly clusters in the Dallas metro benefit from southeastern reshoring incentives targeting compressor manufacturing.
California
Silicon Valley smart home penetration and Los Angeles basin housing density create concentrated demand for Matter-certified connected appliances. Title 20 and Title 24 building codes impose efficiency standards exceeding federal minimums, fragmenting retailer assortment planning. The Central Valley logistics corridor anchors last-mile fulfillment nodes serving same-day delivery economics.
Florida
Miami and Tampa metro migration inflows sustain replacement cycles for high-humidity refrigeration systems and hurricane-season standby power equipment. The Florida Building Code adopts DOE baselines without state-specific overlays, simplifying compliance for national retailers. Jacksonville distribution centers serve as southeastern wholesale hubs for contractor supply relationships.
Southeast Region
Georgia and Tennessee manufacturing incentives attract motor and compressor assembly capacity away from overseas dependency. Atlanta's logistics infrastructure supports regional distribution for domestic appliance brands reducing Asian component exposure. State vocational programs in Georgia address field technician certification gaps for refrigerant handling and smart home diagnostics.
Northeast Corridor
New York Metro and Greater Boston educational institutions channel federal E-Rate subsidies into bulk technology procurement through certified electronics channels. State energy efficiency programs in New York and Massachusetts exceed federal minimums, creating compliance complexity for national assortment planning. Legacy pre-2010 residential electrical infrastructure in older housing stock triggers contractor coordination delays for connected appliance retrofits.
United States Electronics and Appliance Stores Market Competitive Environment
Big-box retailers anchor one tier; pure-play electronics specialists hold differentiated service positions. The vendor structure concentrates around omnichannel operators with fulfillment density and installation service capabilities. Two strategic archetypes dominate: ecosystem-integrated platform operators and white-glove service attachers. Competitive moves center on last-mile node expansion and unbundled maintenance contract proliferation.
Within the platform-operator tier, Amazon.com, Inc. and Walmart Inc. exemplify scale-driven fulfillment economics, while Best Buy Co., Inc. occupies a position bridging transactional retail with recurring service revenue. Apple Inc. represents the direct-to-consumer archetype through controlled retail experience design. These three anchors illustrate how competitive positioning stratifies across logistics velocity, service attachment, and brand-controlled distribution channels.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Best Buy Co., Inc. |
| Apple Inc. |
| Lowe's Companies, Inc. |
| Home Depot, Inc. |
| Costco Wholesale Corporation |
| Walmart Inc. |
| Target Corporation |
| GameStop Corporation |
| Others |
Value Chain & Pricing Dynamics
Refrigerant handling technicians in Georgia and Tennessee command wage premiums that compress margin spreads between economy and premium appliance tiers. Labor scarcity in these southeastern reshoring corridors forces manufacturers to absorb certification costs or pass them through tiered pricing structures.
Pricing Analysis
Capacity additions in Georgia and Tennessee are reshaping price floors for compression-cycle refrigeration systems as domestic assembly reduces overseas freight exposure. Three-tier pricing structure across premium, standard, and economy levels separates DOE-certified efficiency tiers from baseline compliance models. Price differentiation hinges on EnergyGuide label positioning and same-day delivery eligibility through population-dense nodes. Cost compression in economy tiers intensifies because semiconductor input volatility from Taiwan and South Korea squeezes display-driven product margins. Educational institutions exhibit lowest price sensitivity due to federal E-Rate subsidy insulation, while rural households face highest sensitivity where last-mile density thresholds exclude service parity.
Supply Chain Analysis
Workforce availability constraints in southeastern manufacturing geographies tether component assembly to vocational pipeline output rates. Taiwan, South Korea, and China anchor display driver IC and power management chip supply for televisions and smart appliances. Raw material dependencies center on rare earth magnets for compressor motors, copper refrigerant tubing, and glass substrate for panel production. Single-source vulnerability concentrates in Taiwan foundry capacity for advanced node semiconductors. Distribution runs through Jacksonville and Atlanta logistics nodes serving wholesale contractor channels and direct retail fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Electronics and Appliance Stores Market operates as a regulatory compounder where Department of Energy efficiency standard escalations institutionalize replacement demand cycles. Federal minimum compression-cycle requirements and California Title 20 overlays continuously refresh installed base obsolescence.
For Market Incumbents: Extend installation service unbundling into recurring maintenance contracts before pure-play service aggregators capture suburban white-glove segments. Vertical integration into southeastern compressor manufacturing secures supply continuity against Taiwan semiconductor chokepoints. Best Buy's Geek Squad model demonstrates attach rate defensibility that transactional retailers cannot replicate without cross-trained field technician investment.
For New Entrants and Emerging Players: Capture educational bulk procurement channels where E-Rate certification barriers filter established competitors from volume contract eligibility. Underpenetrated rural ex-urban markets offer white-space expansion for regional wholesale distributors with contractor relationship density. Go-to-market positioning through Matter-certified smart home ecosystem partnerships reduces consumer friction in connected appliance categories.
For Investors and Strategic Acquirers: Private equity firms with facility services platforms are the most active acquirer in this space, targeting installation and maintenance providers with refrigerant handling certification infrastructure. Long-term viability centers on recurring revenue attachment rates decoupled from hardware transaction cyclicality. Watch FCC equipment authorization pre-certification pipelines as inflection indicator for IoT-enabled SKU proliferation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Installation Service Unbundling | Geek Squad-style contracts generate recurring revenue independent of hardware margins in Texas and Florida suburbs. |
| Southeastern Manufacturing Reshoring | Georgia and Tennessee incentives attract compressor assembly capacity reducing Taiwan component dependency. |
| Matter Protocol Certification | Hub compatibility standardization dissolves ecosystem lock-in and accelerates suburban smart home attachment rates. |
| Educational Channel Certification | E-Rate program compliance filters national competitors from institutional bulk procurement volume. |
| Last-Mile Node Expansion | Central Valley logistics corridors anchor same-day fulfillment economics excluding rural market parity. |
Study Parameters
Direct dialogue with retail category managers, appliance manufacturing procurement directors, FCC equipment authorization specialists, and vocational training program administrators anchored qualitative assessment. Secondary validation drew from Department of Energy certification databases, Federal Communications Commission equipment authorization filings, E-Rate program disbursement records, and southeastern state manufacturing incentive disclosures. Bottom-up store-level transaction modeling and top-down housing formation projections were triangulated against regional migration flow data.
Segmentation outputs across product type, customer category, sales channel, and technology protocol dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from replacement cycle compression rates under efficiency standard escalations and smart home penetration curves in suburban household formation. Forecast inputs incorporated DOE rulemaking timelines, Matter protocol adoption velocity, and semiconductor foundry capacity allocation patterns.
DOE rulemaking delays, Taiwan semiconductor supply disruptions, and Matter protocol fragmentation are the dominant revision risks to installed base turnover assumptions. Forecasts reflect documented assumptions around efficiency standard enforcement consistency and housing construction permit trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Egypt Microwave Ovens Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Washing Appliances Market
Appliances
Portable Mini Fridge Market
Appliances
Qatar Dishwashers Market
Appliances
Water Heater Market
Appliances
Electric Ranges Market
Appliances
Hairdryer Market
Appliances
Germany Consumer Appliances Market
Appliances
Vacuum Cleaner Market
Appliances
Automatic Dishwasher Market
Appliances
Lightwave Microwave Oven Market
Appliances
Europe Induction Hobs Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Cooler Connected to the Mains Market
Appliances
Qatar Microwave Ovens Market