
 Electric Dryers Market | 2026-2036
Electric Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Dryers Market Intelligence
Apartment-dwelling millennials and Gen Z renters is realigning demand toward compact, stackable electric dryers that fit constrained laundry spaces. Whirlpool Corporation leverages its North American dealer network to sustain bulk-order relationships with multi-family housing developers. Samsung Electronics Co., Ltd. competes through connected-home ecosystems that integrate dryers with smart appliances. Electrolux AB anchors European market share through heat pump specialization and stringent energy-label compliance.
An electric dryer is a forced-air convection appliance that removes moisture from textiles via heated air circulation, typically operating at drum temperatures between 125°F and 135°F with moisture-sensor termination to prevent over-drying. The primary commercial purpose is rapid, automated fabric drying for residential households, commercial laundromats, and institutional facilities requiring high throughput with minimal labor. Front-load configurations command premium positioning due to ergonomic design and stacking compatibility, while heat pump technology captures margin pools through superior energy coefficients that reduce operating costs. Compact capacity segments serve fastest-growing urban density patterns, whereas large-capacity vented systems retain dominance in suburban single-family installations where venting infrastructure exists.
EPA Energy Star certification and DOE minimum efficiency standards shape product development trajectories and factory gate compliance costs for manufacturers selling into the United States. Ecodesign and Energy Labeling regulations in Europe mandate progressive efficiency tier escalations that disqualify conventional vented models from top ratings. Stakeholders must monitor regulatory divergence between efficiency-first jurisdictions and price-sensitive emerging markets where enforcement capacity varies.
Market Dynamics
Heat pump technology is absorbing premium positioning as regulatory pressure tightens energy-efficiency mandates across residential and commercial segments, compressing margins for conventional vented systems while rewarding early adopters with operating-cost advantages.
Growth Catalysts
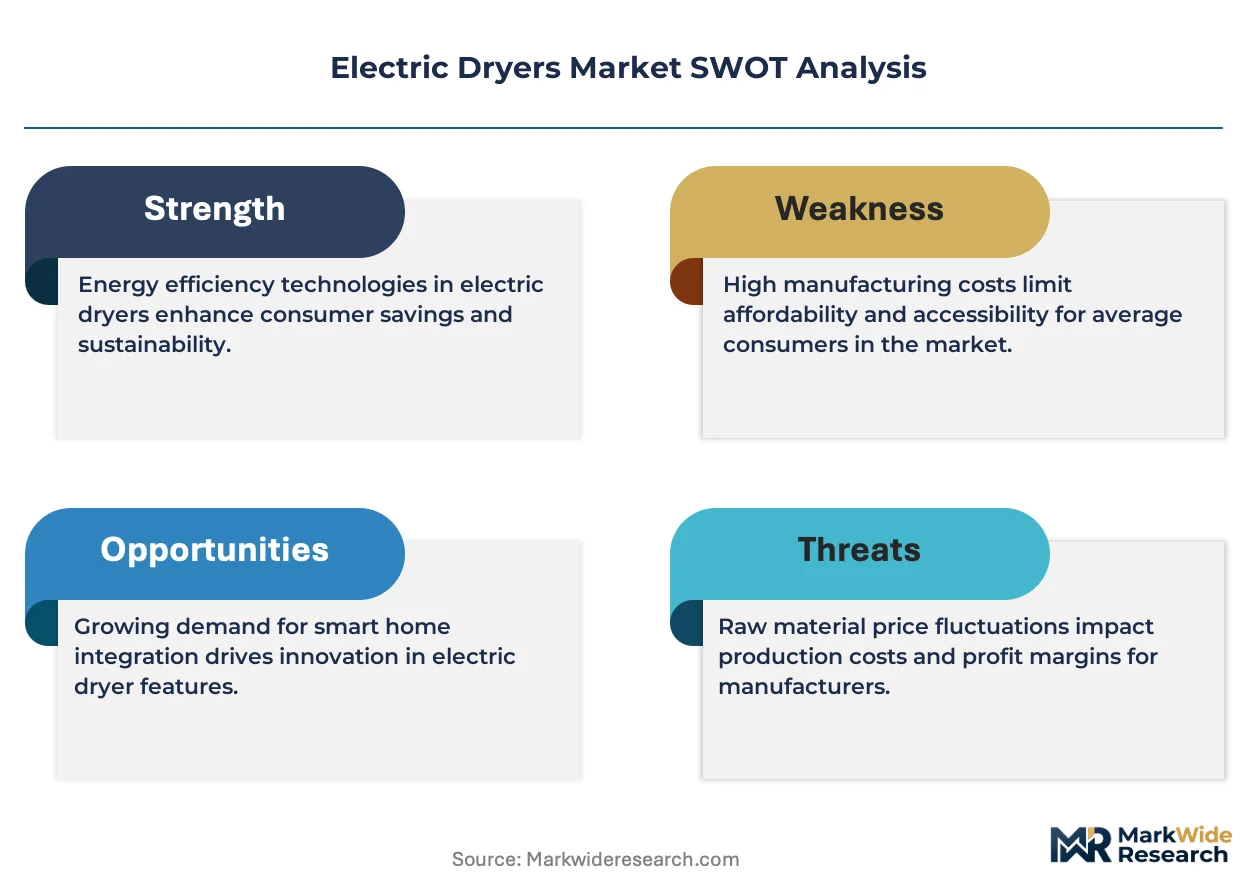
- EPA Energy Star certification:United States manufacturers accelerate product redesign to meet escalating federal efficiency thresholds, unlocking rebate eligibility and retail placement advantages.
- Urban apartment density:Compact and stackable configurations capture demand from millennial and Gen Z renters in constrained laundry spaces across high-rise developments.
- Ecodesign requirements:European Union regulations progressively disqualify conventional vented models from top energy ratings, redirecting procurement toward heat pump alternatives.
Market Restraints
- Heat pump cost premium:Advanced refrigeration components and inverter drives elevate factory-gate pricing versus legacy vented systems, constraining penetration in price-sensitive segments.
- Copper and steel volatility:Raw material input swings compress margin predictability for manufacturers maintaining inventory across extended production cycles.
- Venting infrastructure lock-in:Existing ductwork in suburban single-family housing creates substitution friction against heat pump retrofits.
Strategic Opportunities
- India urbanization wave:Tier-1 and Tier-2 city apartment construction creates first-mover positioning for compact dryer configurations in underpenetrated households.
- Smart home convergence:Integration of moisture-sensor dryers with connected appliance ecosystems opens subscription-service and predictive-maintenance revenue streams.
- DOE minimum efficiency standards:Anticipated tier escalations create regulatory tailwind for manufacturers with advanced heat pump portfolios ready for compliance acceleration.
Industry Challenges
- Refrigerant technician scarcity:Heat pump service requirements outpace qualified installation and repair workforce availability in distributed residential markets.
- Dual certification timelines:Simultaneous EPA Energy Star and DOE compliance testing extends product launch cycles and strains R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Dryers Market |
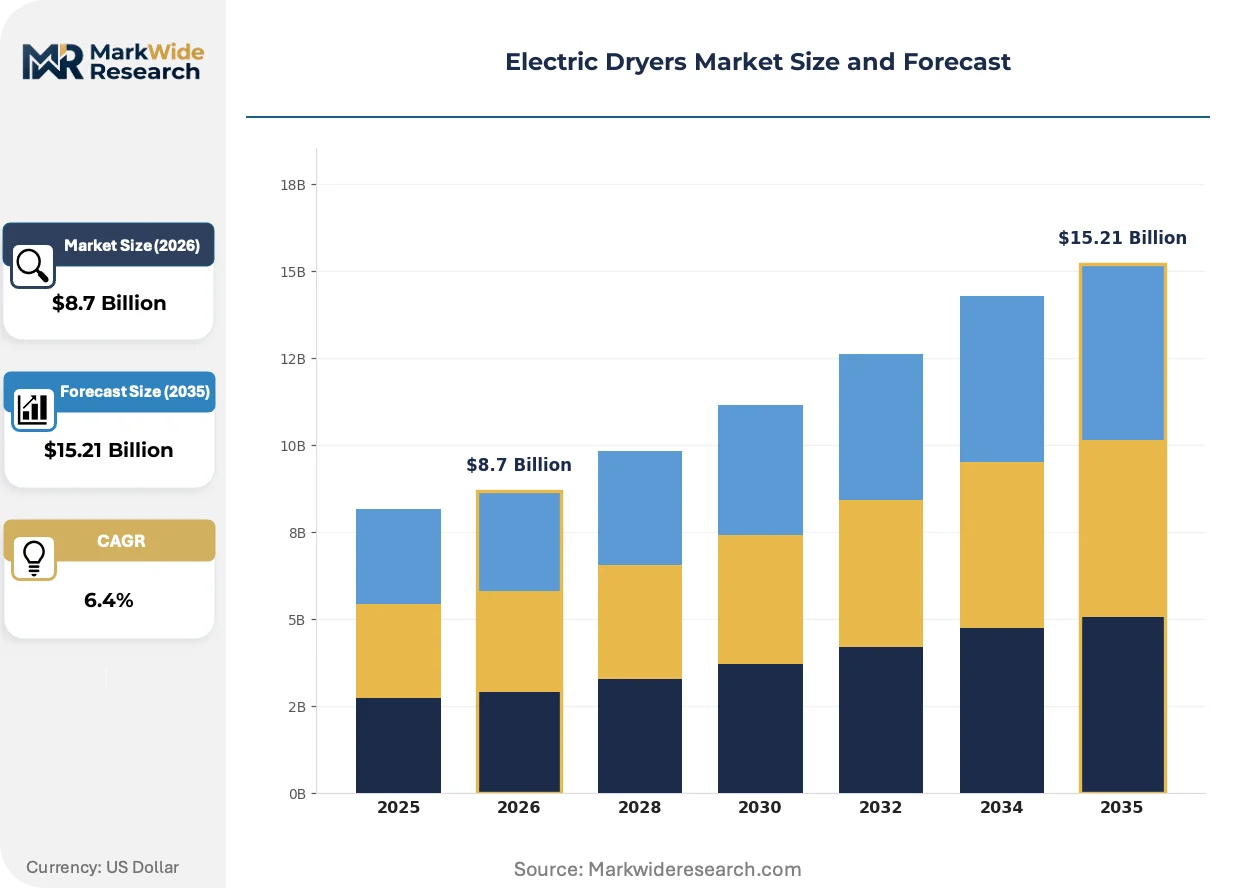
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable, Front-Load, Top-Load, Compact End User: Residential, Commercial, Hospitality, Healthcare Technology: Vented, Condenser, Heat Pump, Hybrid Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Samsung Electronics Co., Ltd., Whirlpool Corporation, Electrolux AB, LG Electronics, Haier Group Corporation, Robert Bosch GmbH, GE, Midea, Speed Queen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Dryers Market Strategic Shifts & Innovations
Product development trajectories center on thermal efficiency breakthroughs, regulatory compliance automation, and space-constrained design optimization. Manufacturers are repositioning around operating-cost value propositions rather than upfront price competition.
Inverter-driven heat pump dryers are absorbing market share from resistance-heating alternatives by delivering coefficient-of-performance advantages that cut residential electricity consumption. Multi-family housing developers in Germany and the Netherlands specify these systems to meet building-code efficiency requirements. The technology is absorbing margin pools previously captured by vented-system manufacturers.
REACH and F-Gas Regulation in Europe are restricting refrigerant chemistries and global-warming-potential thresholds for heat pump appliances. Manufacturers face reformulation costs and supply-chain requalification for compliant working fluids. Product portfolios targeting Nordic and Benelux markets are prioritizing propane and isobutane alternatives.
Millennial and Gen Z renters are prioritizing lease-inclusive appliance packages over unit ownership, shifting procurement authority toward property managers and institutional landlords. Bulk purchasing agreements with multi-family developers are displacing traditional retail channel dominance. This concentration is most pronounced in United States coastal metros and German university towns.
Electric Dryers Market Segmentation
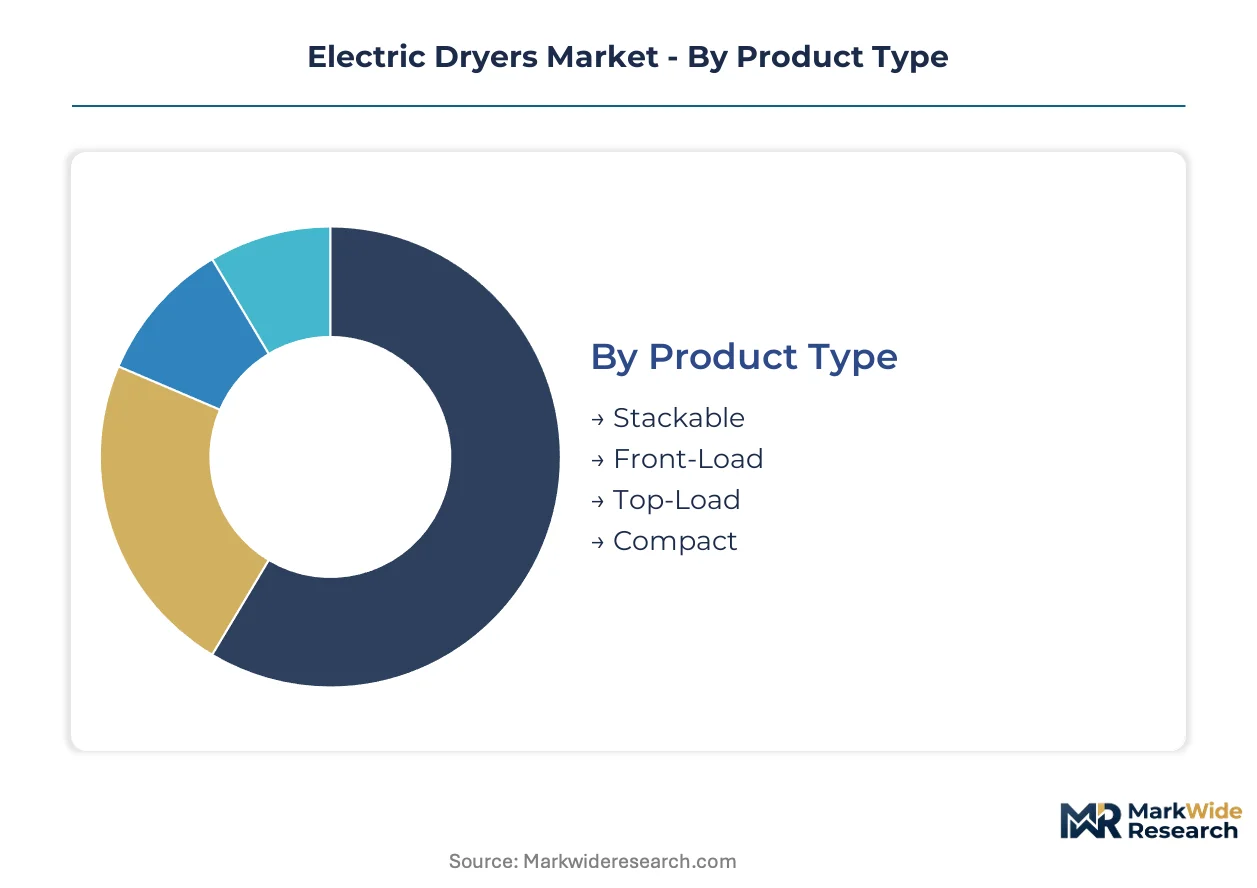
Electric dryer procurement patterns diverge sharply across housing stock age, utility infrastructure, and regulatory exposure. Manufacturers configure product portfolios around replacement-cycle timing rather than uniform feature distribution.
Product Type:
Replacement cycles in multi-family housing are compressing as developers specify space-optimized configurations for new construction.
- Stackable:Vertical integration of washer-dryer pairs enables floor-space recovery in high-rise apartments. German and Dutch social housing authorities now mandate stackable specifications for new-build tenders.
- Front-Load:Horizontal drum orientation permits ergonomic loading and dryer-over-washer stacking. North American suburban households with dedicated laundry rooms favor this format for capacity optimization.
- Top-Load:Vertical drum access suits aging-in-place demographics and traditional utility room layouts. Rural US markets retain preference for familiar mechanical controls.
- Compact:Under-counter and closet-installation formats serve Tokyo micro-apartments and London converted flats. 24-inch width standards dominate Japanese builder specifications.
Volume placements concentrate in Front-Load; the faster expansion belongs to Compact.
End User:
Cost tier stratification separates capital-expense buyers from operating-expense optimizers across institutional and residential procurement.
- Residential:Single-family replacement demand centers on energy-label compliance and smart-home compatibility. California Title 24 building codes now require electric dryer readiness in new construction.
- Commercial:Coin-op laundromats and multi-housing laundry rooms prioritize throughput reliability and payment-system integration. Card-reader retrofit cycles drive equipment refresh timing.
- Hospitality:On-premise laundry operations for hotels and resorts balance linen quality preservation with labor minimization. Heat pump systems reduce utility costs in European Union properties.
- Healthcare:Hospital and long-term care facilities demand infection-control temperatures and programmable cycle documentation. Joint Commission accreditation standards influence specification requirements.
Procurement scale favors Residential; margin capture tilts toward Healthcare.
Technology:
Application context determines whether venting infrastructure or energy efficiency governs technology selection.
- Vented:External ducting expels moist air directly, enabling lower first-cost positioning. US suburban housing stock with existing ductwork sustains this segment's replacement base.
- Condenser:Closed-loop moisture collection suits apartments without external venting access. UK private rental sector specifications increasingly favor condenser over vented for installation flexibility.
- Heat Pump:Refrigeration-cycle heat recovery delivers coefficient-of-performance advantages. Ecodesign regulations in France and Italy now exclude vented models from top efficiency tiers.
- Hybrid:Dual-mode systems switch between heat pump and resistance heating for speed-critical loads. Premium positioning targets households with time-of-use electricity rate structures.
Installed base dominance rests with Vented; steepest expansion trajectory belongs to Heat Pump.
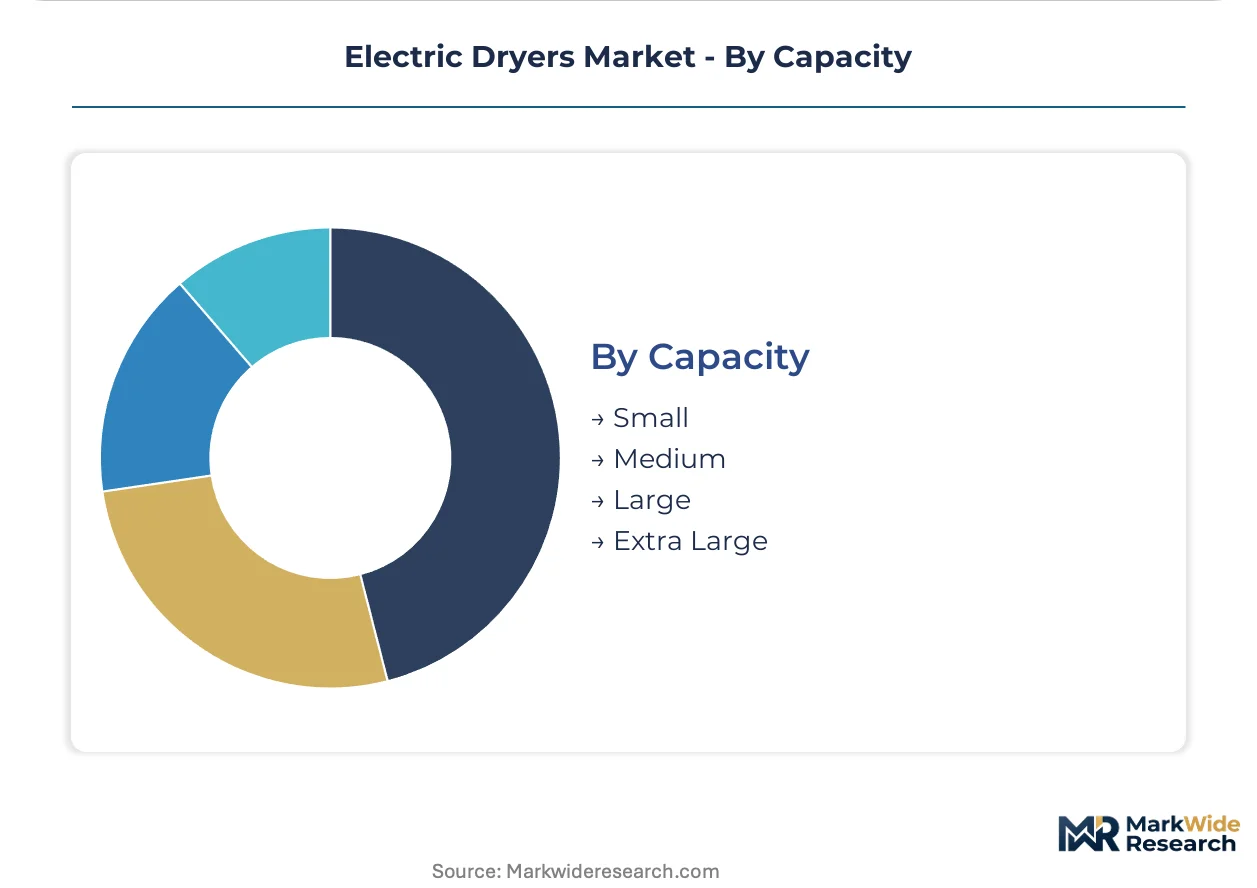
Capacity:
Customer type and geography jointly determine drum volume requirements across household composition patterns.
- Small:3.4-4.3 cubic foot drums serve single-person households and secondary vacation properties. Scandinavian cabin and studio apartment markets sustain this tier.
- Medium:4.4-5.8 cubic foot range captures standard North American family configurations. Builder-grade specifications for US entry-level housing cluster here.
- Large:5.9-7.0 cubic foot capacity supports multi-child households and bedding bulk loads. Australian and Canadian suburban markets show concentration in this segment.
- Extra Large:7.1+ cubic foot drums address commercial throughput and oversized item requirements. US laundromat operators and hospitality linen services specify this tier.
Revenue concentration sits with Medium; share gains are climbing the fastest in Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households drive replacement-cycle compression as energy-efficiency mandates tighten appliance standards. China and India dominate volume expansion through urban apartment construction. European regulatory pressure redirects procurement toward heat pump alternatives.
United States
Suburban single-family housing sustains large-capacity vented-system demand through existing ductwork infrastructure. EPA Energy Star certification thresholds escalate federal compliance requirements for manufacturers. California Title 24 building codes in Los Angeles and San Diego metros now mandate electric dryer readiness in new residential construction.
Germany
Social housing authorities specify stackable heat pump configurations for multi-family new-build tenders. Ecodesign regulations progressively disqualify conventional vented models from top efficiency tiers. The Rhine-Ruhr industrial corridor concentrates manufacturing capacity for inverter-driven compressor components serving Benelux export markets.
China
Tier-1 and Tier-2 city apartment dwellers drive compact and stackable configuration demand in underpenetrated households. GB standards and MIIT efficiency directives shape domestic product certification requirements. The Yangtze River Delta manufacturing cluster around Shanghai anchors production scale for export-oriented dryer assembly.
India
Urban millennial renters in Mumbai and Bangalore create first-mover positioning for compact dryer configurations. BIS appliance safety standards and CEA energy labeling programs govern market entry compliance. The Delhi-NCR corridor attracts distribution infrastructure investment as northern India apartment construction accelerates.
Japan
Tokyo micro-apartment specifications sustain 24-inch width compact dryer standards for builder installations. METI Top Runner program mandates progressive efficiency improvements for residential appliances. The Kansai region around Osaka hosts specialized component suppliers for heat pump refrigeration systems.
Electric Dryers Market Key Industry Players
North American producers anchor one tier; East Asian electronics conglomerates hold volume-scale positioning. The vendor base separates into three strategic tiers: diversified appliance conglomerates with connected-home ecosystems, regional specialists with heat pump technology depth, and contract manufacturers serving private-label retail channels. Competitive moves concentrate on regulatory pre-certification racing and bulk procurement agreements with multi-family housing developers.
Within the diversified conglomerate tier, Samsung Electronics Co., Ltd. and LG Electronics exemplify scale-driven platform strategies, while Whirlpool Corporation occupies a position anchoring North American dealer network relationships. Electrolux AB represents European specialization archetypes with stringent energy-label compliance positioning. These named entities illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Whirlpool Corporation |
| Electrolux AB |
| LG Electronics |
| Haier Group Corporation |
| Robert Bosch GmbH |
| GE |
| Midea |
| Speed Queen |
| Others |
Cost & Logistics Intelligence
Inverter-driven compressor adoption in heat pump dryers simultaneously elevates factory-gate cost structures and concentrates component sourcing around specialized refrigeration manufacturing clusters. This technology transition compresses margins for vented-system assemblers while rewarding early movers with pricing power in efficiency-premium segments.
Pricing Analysis
Volume placements cluster in medium-capacity vented systems where price competition is fiercest, while margin capture concentrates in heat pump configurations certified to EPA Energy Star and EU Ecodesign top tiers. Price differentiation rests on energy-label grade and smart-home integration depth, with connected-appliance ecosystems commanding brand premiums. Cost compression in entry-level vented segments is intensifying because of steel and copper volatility, while price sensitivity peaks among multi-family housing developers procuring bulk appliance packages.
Supply Chain Analysis
Ocean freight rate fluctuations and container availability constraints shape landed cost predictability for finished dryer imports from China, South Korea, and Mexico into North American distribution hubs. Component sourcing draws from Chinese steel mills for drum fabrication, Japanese inverter manufacturers for heat pump drives, and German compressor specialists for refrigeration-cycle assemblies. Single-source vulnerability concentrates in semiconductor-dependent motor controllers. Distribution runs through big-box retail chains, multi-family developer bulk procurement, and e-commerce direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump technology mandates and refrigerant regulation compliance costs are consolidating the vendor base, forcing capital-constrained assemblers toward exit or acquisition.
For Market Incumbents: Extend heat pump certification portfolios ahead of anticipated DOE tier escalations to capture regulatory tailwinds. Deepen backward integration into inverter-compressor production through captive supply agreements with Japanese or German component specialists, insulating margin structures from raw material volatility and refrigerant reformulation costs. For New Entrants and Emerging Players: Capture first-mover positioning in India's Tier-2 city apartment construction wave through compact dryer configurations tailored to BIS safety standards and CEA energy labeling. White-space availability concentrates in northern India distribution infrastructure gaps, with go-to-market execution hinging on property-manager bulk procurement relationships rather than retail channel buildout. For Investors and Strategic Acquirers: Re-rating potential sits with regional heat pump specialists given Ecodesign regulatory acceleration across France, Italy, and Germany. Long-term viability over a multi-year horizon favors acquisition targets with established refrigeration-cycle service networks and pre-certified product portfolios. The inflection signal to monitor is social housing authority tender specifications shifting from vented to heat pump mandates in Benelux and Nordic markets.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Certification Acceleration | EPA Energy Star and EU Ecodesign pre-qualification unlocks rebate eligibility and retail placement advantages. |
| Backward Integration into Compressors | In-house production of inverter-driven refrigeration components reduces exposure to copper pricing volatility. |
| Multi-Family Developer Partnerships | Bulk procurement agreements with institutional landlords displace traditional retail channel dominance. |
| Smart Home Platform Integration | Connected-appliance ecosystems enable subscription-service and predictive-maintenance revenue streams. |
| India Distribution Infrastructure Buildout | Delhi-NCR corridor investment captures northern India apartment construction acceleration. |
Research Approach
Independent corroboration across appliance manufacturing executives, multi-family housing developers, and energy regulator policy officers underwrites the qualitative findings in this study. Primary fieldwork engaged product engineering directors at diversified appliance conglomerates, procurement managers at institutional landlords, and refrigerant supply chain specialists. Secondary validation drew from EPA Energy Star certification databases, EU Ecodesign regulatory filings, and customs trade records for steel and copper imports. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Rate-of-change decomposition across the analysis window separates replacement-cycle compression, technology substitution effects, and geographic demand migration. Segmentation dimensions modeled include product type, end-user category, technology architecture, and capacity tier alongside regional regulatory cluster exposure. CAGRs were derived from fitted growth curves applied to historical shipment data and policy-mandated efficiency transition timelines. Key forecast inputs incorporate social housing tender specifications and building-code electrification mandates.
The model holds under steady regulatory enforcement and commodity price bands; deviation in refrigerant supply restrictions or tariff regime shifts would alter manufacturer margin trajectories. Forecasts reflect documented assumptions about technology adoption curves and replacement timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Bahrain Microwave Ovens Market
Appliances
Mini Washing Machine Market
Appliances
India Washing Machine Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Oman Microwave Ovens Market
Appliances
Cooker Hoods Market
Appliances
Dishwasher Market
Appliances
Triple Barrel Waver Market
Appliances
Cooler Connected to the Mains Market
Appliances
Sanitary Towel Machine Market
Appliances
United States Multi-Functional Oven Market
Appliances
Portable Dishwasher Market
Appliances
Small Appliances Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Colombia Appliances and Electronics Market