
 United Kingdom Handheld Vacuum Cleaners Market | 2026-2036
United Kingdom Handheld Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Handheld Vacuum Cleaners Market Insights
Lithium-ion battery chemistry is consolidating around nickel-manganese-cobalt formulations that extend runtime without adding weight. Dyson leverages proprietary cyclone technology to sustain premium positioning across cordless portfolios. Shark anchors its UK presence through direct-to-consumer channel control, while Vax competes aggressively on price in the wet-and-dry segment.
United Kingdom handheld vacuum cleaners are portable suction devices typically weighing under three kilograms, powered by rechargeable lithium-ion cells or mains electricity, designed for spot cleaning, vehicle interiors, and confined residential spaces. Battery-powered units now dominate volume shipments as motor efficiency improvements deliver suction comparable to corded predecessors. The hospitality end-user segment generates outsized margin pools due to durability requirements and fleet replacement cycles, whereas online retail channels capture the fastest growth trajectory among distribution pathways.
The UK Office for Product Safety and Standards enforces electrical equipment regulations that mandate CE marking compliance, while the Waste Electrical and Electronic Equipment Directive shapes end-of-life collection obligations and recycling cost structures. BSI standards for electromagnetic compatibility further constrain design choices for manufacturers seeking market access. Stakeholders must monitor pending revisions to energy labelling frameworks that could redefine efficiency benchmarks and reorder competitive rankings.
Market Dynamics
The UK handheld vacuum cleaner market is being restructured by lithium-ion battery supply chain localization following the government's 2027 petrol and diesel vehicle ban, which has redirected cell manufacturing investments toward cordless appliance applications.
Growth Catalysts
- Professional cleaning services:Fleet replacement cycles across Greater London, Birmingham, and Glasgow generate consistent demand for durable cordless units capable of daily commercial use.
- WEEE Directive compliance infrastructure:Established end-of-life collection networks reduce recycling cost uncertainty for manufacturers and retailers operating in the UK market.
- Nickel-manganese-cobalt cell chemistry:Advances in energy density enable runtime extension without weight penalties, expanding addressable use cases for spot-cleaning applications.
Market Restraints
- Lithium carbonate price volatility:Raw material input fluctuations compress margin predictability for battery-powered product lines.
- East Asian cell concentration:Dependence on concentrated battery supply sources creates exposure to trade policy shifts and logistics disruptions.
- CE marking friction:BSI electromagnetic compatibility testing requirements extend product development timelines and raise compliance costs for new market entrants.
Strategic Opportunities
- Hospitality sector fleet contracts:Hotel and serviced apartment chains present untapped recurring revenue potential through standardized equipment specifications.
- Online direct-to-consumer channels:Digital-first distribution models bypass traditional retail markups and capture margin previously allocated to intermediaries.
- Energy labelling revision anticipation:Proactive redesign for pending efficiency benchmark changes positions manufacturers to capture shelf space during regulatory transition periods.
Industry Challenges
- Motor control firmware development:Shortage of embedded systems engineers with power electronics expertise constrains product iteration velocity.
- BSI certification queue lengths:Extended electromagnetic compatibility testing backlogs delay time-to-market for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Handheld Vacuum Cleaners Market |
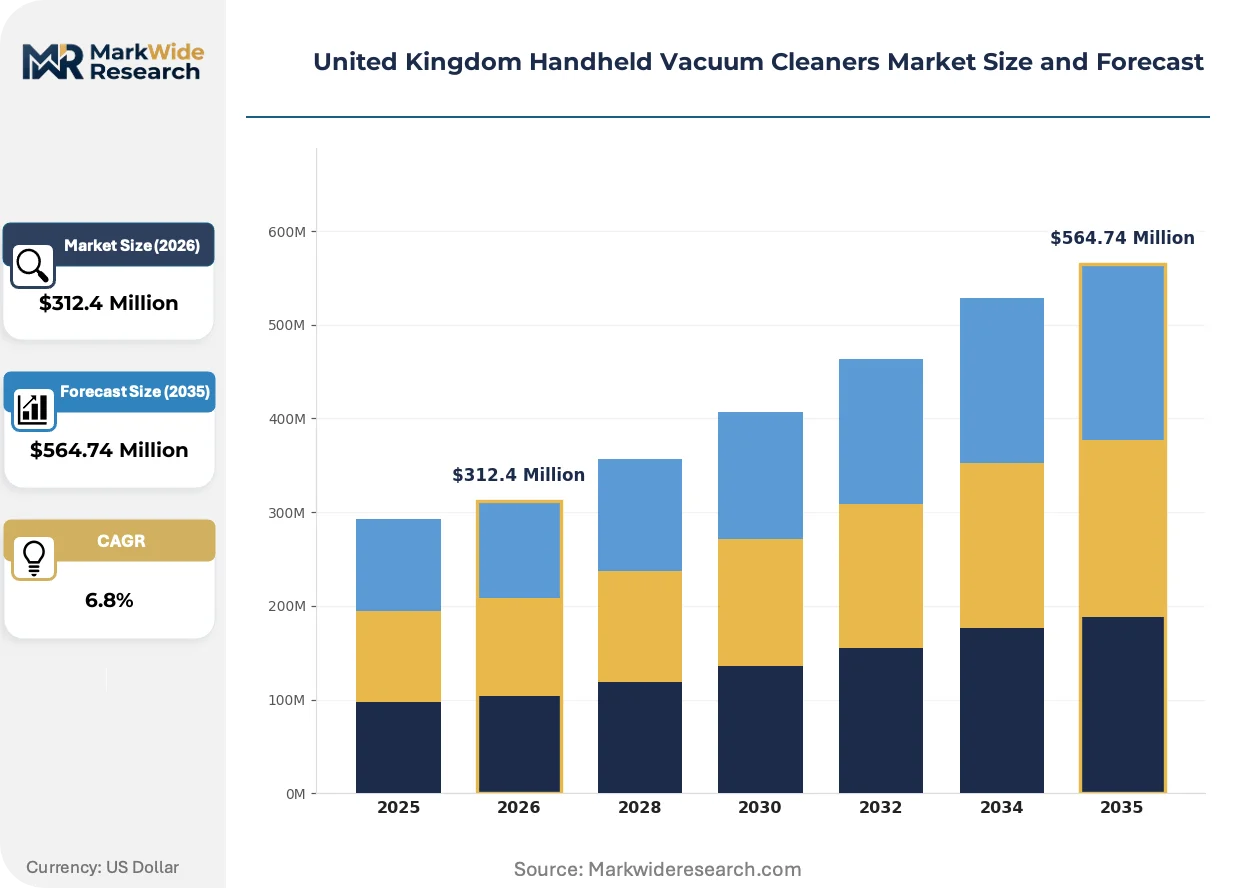
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Powered, Corded, Stick-Vacuum, Wet&Dry Application: Household, Automotive, Commercial, Industrial End User: Personal Use, Hospitals, Hospitality, Cleaning Services Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Dyson, Shark, Bissell, Dirt Devil, Hoover, Vax, Miele, Electrolux, Kenwood, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Handheld Vacuum Cleaners Market Trends and Innovations
Digital intelligence integration and circular economy mandates are compressing product development cycles while elevating performance expectations across the UK handheld vacuum segment.
Smart suction adjustment is automating power management in response to surface detection. Hospitality cleaning crews operating across London hotel chains are adopting sensor-equipped units at accelerated replacement rates. This capability is automating labor allocation decisions by reducing operator training requirements and standardizing cleaning outcomes across variable floor materials.
Pending revisions to UK energy labelling frameworks are tightening efficiency disclosure requirements for rechargeable appliances. Manufacturers must redesign motor and battery systems to meet stricter runtime-per-watt benchmarks before implementation. Cordless product portfolios face the most significant compliance burden, with redesign timelines compressing against regulatory deadlines.
Subscription-based equipment refresh programs are displacing outright purchase models among commercial cleaning contractors. Direct-to-consumer platforms and manufacturer-owned service networks are capturing relationships previously managed through independent distributors. This shift concentrates most visibly across Greater London, where professional cleaning density supports predictable fleet utilization metrics.
United Kingdom Handheld Vacuum Cleaners Market Segmentation
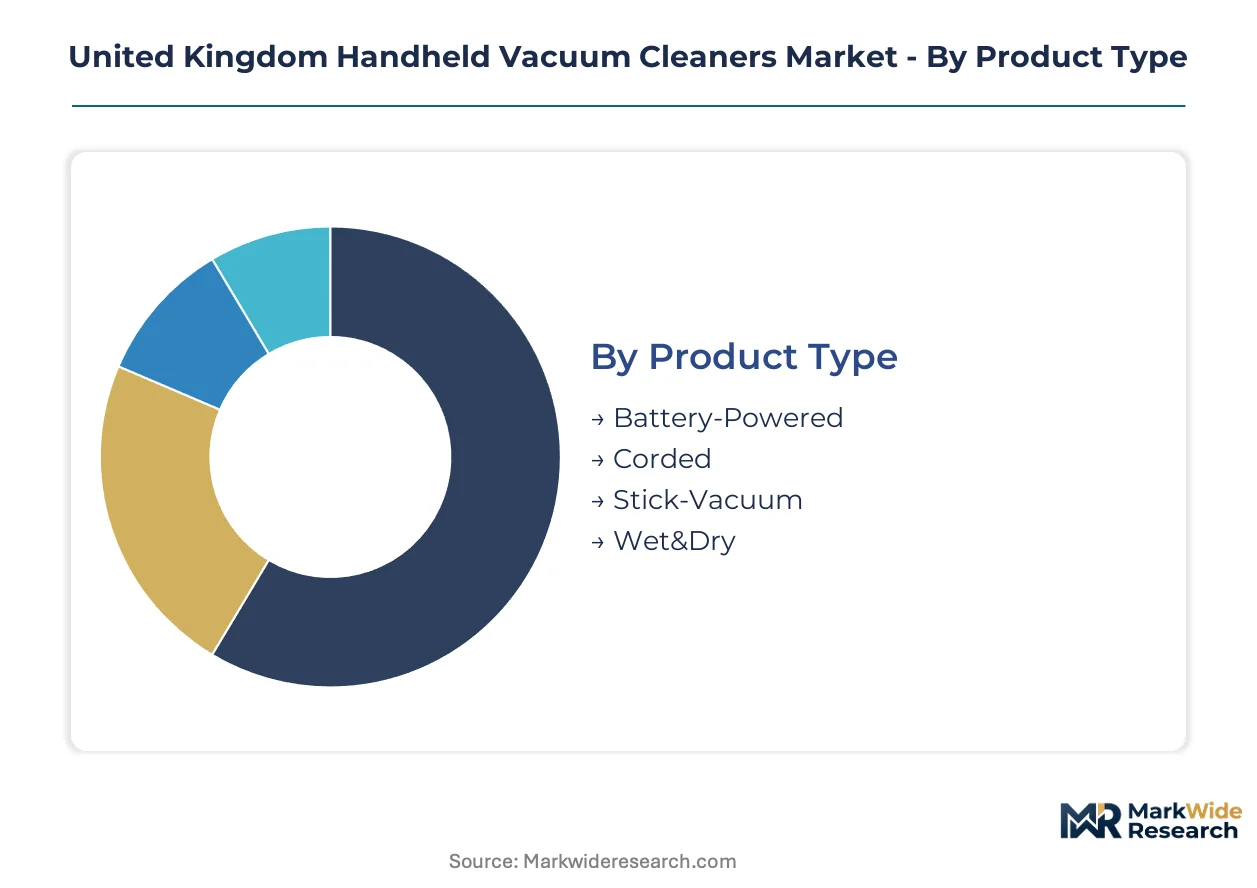
Segmentation in the UK handheld vacuum cleaner market reveals divergent capital requirements and margin structures across power configurations and customer types. Manufacturers allocate R&D budgets unevenly based on battery chemistry investments versus corded motor refinement. Channel strategy and end-user durability specifications further differentiate competitive positioning.
Product Type:
Battery-powered configurations demand the highest upfront capital commitment due to lithium-ion cell integration and power management firmware development.
- Battery-Powered:Cordless units utilizing nickel-manganese-cobalt cells deliver runtime exceeding 40 minutes at suction ratings matching corded alternatives. London-based professional cleaning services drive replacement demand for fleet standardization across multiple sites.
- Corded:Mains-powered designs require minimal battery procurement but face declining addressable market as UK rental stock modernizes toward cordless-ready specifications. Manchester apartment conversions increasingly omit accessible power outlets in favor of rechargeable appliance compatibility.
- Stick-Vacuum:Convertible floor-to-handheld formats capture dual-use households seeking single-device coverage.
- Wet&Dry:Sealed motor housings enable liquid recovery for spill response and vehicle detailing applications.
Battery-powered models absorb the bulk of installed manufacturing capacity; stick-vacuum configurations are expanding most quickly among urban households seeking space-efficient storage solutions.
Application:
Commercial deployments generate superior margin profiles through volume procurement contracts and accelerated replacement cycles compared to intermittent residential use.
- Commercial:Daily-use durability specifications command premium pricing from facility management contractors operating across Birmingham and Glasgow office clusters. Fleet telemetry integration enables predictive maintenance scheduling that reduces total cost of ownership.
- Hospitality:Hotel housekeeping protocols standardize on lightweight units for rapid room turnover, with procurement centralized at chain headquarters rather than property level.
- Household:Spot-cleaning frequency concentrates among pet owners and parents of young children in dense urban neighborhoods.
- Automotive:Detailing specialists and individual vehicle owners prioritize compact nozzle geometries for cabin crevice access.
- Industrial:Workshop environments require enhanced filtration for metal particulate and construction debris recovery.
Commercial applications absorb the bulk of installed capacity; hospitality deployments are climbing the fastest as serviced apartment construction accelerates across Greater London.
End User:
Institutional procurement patterns diverge sharply from individual purchase behavior in specification rigor and supplier qualification requirements.
- Cleaning Services:Contract cleaners operating multi-site portfolios standardize equipment to reduce training overhead and spare parts inventory. Fleet utilization metrics in London exceed 6 hours daily, driving demand for rapid-charge battery systems.
- Hospitals:Infection control protocols mandate sealed systems with HEPA filtration and surface disinfection compatibility for clinical environments.
- Personal Use:Individual purchasers prioritize weight minimization and storage footprint over runtime specifications.
- Hospitality:Hotel operators balance guest-visible design aesthetics with housekeeping staff ergonomic requirements.
Cleaning services absorb the bulk of installed capacity; hospital procurement is gaining share fastest as NHS facility privatization expands outsourced environmental services contracts.
Distribution Channel:
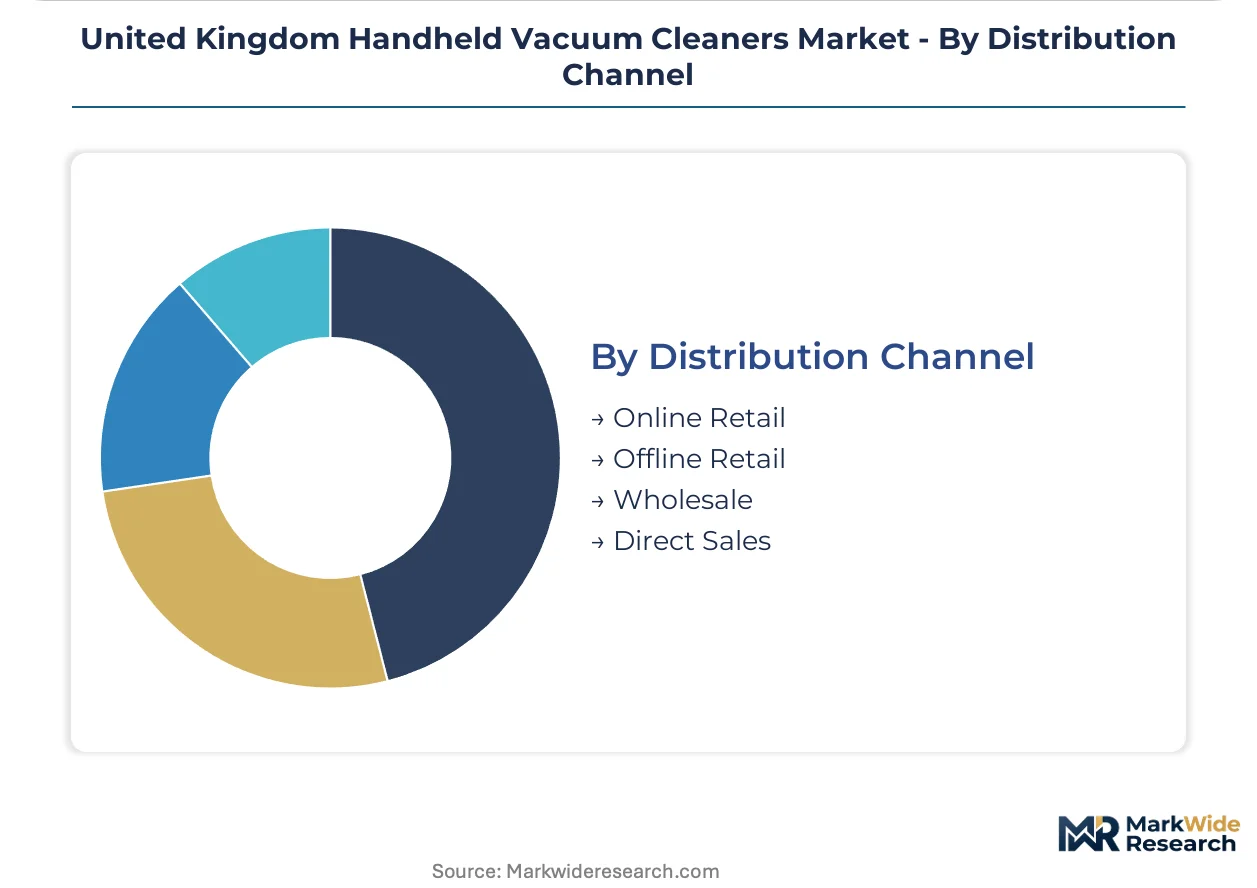
Channel selection determines margin capture and customer relationship depth, with direct models requiring substantial platform investment but eliminating intermediary economics.
- Online Retail:Marketplace platforms and brand-owned storefronts aggregate comparison shoppers and enable subscription-based refresh programs. Digital-first entrants bypass traditional retail slotting fees that burden established competitors.
- Direct Sales:Manufacturer-controlled channels capture full margin and generate utilization data for product development feedback loops.
- Offline Retail:Currys and John Lewis provide tactile evaluation opportunities that reduce return rates for premium-priced units.
- Wholesale:Distributor networks serve independent cleaning contractors with credit terms and localized service support unavailable through direct channels.
Online retail absorbs the bulk of installed sales volume; direct sales channels are expanding most quickly as manufacturers invest in proprietary service infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional cleaning services in Greater London, Birmingham, and Glasgow generate the densest demand clusters for cordless handheld units, with fleet procurement patterns rippling outward through regional distributor networks.
London and Southeast England
Hospitality sector procurement concentrates in Westminster and Kensington hotel chains, where housekeeping fleet standardization drives bulk replacement cycles. The UK Office for Product Safety and Standards enforces CE marking and electromagnetic compatibility testing that shapes product qualification timelines. Croydon distribution hubs serve contract cleaners operating across the Home Counties with rapid-charge battery systems.
Midlands
Birmingham office clusters generate commercial cleaning demand for durable daily-use specifications, with facility management contractors standardizing equipment across multi-site portfolios. The Waste Electrical and Electronic Equipment Directive mandates end-of-life collection infrastructure that reduces recycling cost uncertainty for manufacturers. Coventry logistics corridors channel inventory to independent cleaning contractors throughout the West Midlands.
North England
Manchester apartment conversions increasingly omit accessible power outlets, accelerating cordless adoption among urban renters in dense residential neighborhoods. Pending revisions to UK energy labelling frameworks tighten efficiency disclosure requirements for rechargeable appliances. Leeds distribution centers supply professional cleaning fleets operating across Yorkshire commercial parks.
Scotland
Glasgow hospitality and office cleaning services sustain consistent replacement demand, with procurement centralized through Edinburgh-based facility management groups. BSI electromagnetic compatibility standards constrain design choices for manufacturers seeking Scottish market access. Aberdeen's serviced apartment construction pipeline expands addressable fleet contract opportunities for cordless equipment suppliers.
Wales
Cardiff and Swansea urban regeneration projects modernize rental stock toward cordless-ready specifications, narrowing corded unit addressable market. The UK government's 2027 petrol and diesel vehicle ban redirects battery supply chain investments toward cordless appliance applications. Newport logistics nodes connect Welsh cleaning contractors to England-based distributor networks.
United Kingdom Handheld Vacuum Cleaners Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier incumbents defending position through proprietary technology while value-oriented competitors compete on price in wet-and-dry configurations. Market structure concentrates around three to four dominant branded portfolios, with tiered differentiation separating cyclone-technology specialists from motor-efficiency optimizers. Strategic archetypes include premium technology licensors, direct-to-consumer channel controllers, and aggressive price competitors in utility segments. Capacity expansion into lithium-ion battery integration and geographic push into hospitality fleet contracts represent the dominant competitive moves reshaping positioning.
Within the premium technology tier, Dyson anchors proprietary cyclone positioning, while Shark exemplifies direct-to-consumer channel control. Vax occupies the aggressive price-competitor archetype in wet-and-dry segments. These three named players represent distinct strategic vectors: technology differentiation, distribution disintermediation, and segment-focused cost leadership.
| Leading Market Players |
|---|
| Dyson |
| Shark |
| Bissell |
| Dirt Devil |
| Hoover |
| Vax |
| Miele |
| Electrolux |
| Kenwood |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap appliance specialists anchor UK manufacturing capacity, constraining aggressive price competition while channeling procurement discipline through established distributor relationships. Their ownership structure limits access to capital for vertical integration, forcing reliance on external cell suppliers and compressing margin recovery during lithium carbonate volatility.
Pricing Analysis
Volume shipments concentrate in economy-tier cordless units while margin pools concentrate in premium hospitality specifications. Three-tier pricing structure across premium cyclone-technology, standard motor-efficiency, and economy wet-and-dry levels separates Dyson from Shark from Vax. Pricing pressure stems from lithium carbonate input fluctuations compressing battery-powered product lines. Commercial cleaning services exhibit lowest price sensitivity due to fleet standardization requirements, while individual household purchasers drive hardest bargain comparison.
Supply Chain Analysis
Lithium-ion cell supply rests on concentrated manufacturing in China, South Korea, and Japan, with nickel-manganese-cobalt cathode chemistry drawing from Indonesian nickel and Chilean lithium feedstocks. Power management semiconductors hinge on Taiwanese foundry output, while molded plastic housings source from domestic UK injection specialists. Single-source vulnerability concentrates in advanced battery management integrated circuits. Distribution runs through Croydon and Coventry logistics hubs serving regional cleaning contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK handheld vacuum manufacturing operates as a supply-constrained market where lithium-ion cell allocation bottlenecks prop pricing discipline for qualified buyers. Capacity scarcity at qualified cell suppliers limits volume expansion regardless of downstream demand signals.
For Market Incumbents: Lock in multi-year cell supply agreements with Korean and Japanese manufacturers before hospitality fleet contract renewal cycles accelerate. Prioritize rapid-charge battery system R&D to defend against emerging direct-to-consumer entrants. CE marking compliance investments create switching costs that protect Greater London cleaning service relationships. For New Entrants and Emerging Players: Enter via wet-and-dry utility segments where Vax price positioning leaves room for specification-matching at lower marketing overhead. Target independent cleaning contractors in Birmingham and Glasgow through wholesale distributor credit terms unavailable to direct-channel incumbents. Pursue hospitality fleet telemetry integration as differentiated service layer. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with established BSI certification relationships and underutilized UK assembly capacity. Five-to-ten year viability hinges on battery chemistry transition execution rather than brand equity accumulation. Watch lithium carbonate futures curves as inflection signal for margin recovery timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Supply Agreement | Long-term cobalt and lithium offtake secures production continuity against commodity volatility. |
| Rapid-Charge R&D Program | Battery management firmware advances address London cleaning service fleet utilization requirements. |
| Hospitality Fleet Telemetry | Predictive maintenance integration captures recurring revenue from serviced apartment construction pipeline. |
| Direct-to-Consumer Platform | Digital channel control eliminates retail markup capture and generates product development feedback loops. |
| CE Marking Acceleration | Compressed electromagnetic compatibility testing timelines improve time-to-market for regulatory transition periods. |
Research Methodology
Multi-period observation of lithium-ion cell pricing, professional cleaning fleet replacement cycles, and hospitality construction permits anchored the trend analysis, supplemented by interviews with product development directors at branded manufacturers, procurement leads at facility management contractors, channel sales heads at distributor networks, and compliance officers at BSI testing laboratories. Secondary validation drew from UK Office for Product Safety and Standards enforcement records, Waste Electrical and Electronic Directive collection statistics, customs import data for battery cells, and energy labelling framework consultation documents. Bottom-up shipment estimates triangulated against top-down spending analysis across consumer and commercial end-use segments.
Input-output matrices mapped battery chemistry costs through motor assembly to finished goods pricing across power configuration, application, and channel segmentation dimensions. CAGRs derived from logistic curve fitting to adoption saturation patterns within urban rental stock modernization and professional service fleet standardization trends. Forecast inputs incorporated lithium supply chain investment announcements, pending energy labelling efficiency benchmark revisions, and hospitality sector construction pipeline data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium carbonate price spike scenarios or extended BSI certification queue conditions. Assumptions reflect stable UK-EU trade arrangements and continued NHS facility privatization expanding outsourced environmental services contracts. A small set of triggers—cell manufacturing capacity expansion announcements, energy labelling implementation dates, and hospitality sector M&A consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
US Washing Machine Parts Market
Appliances
Japan Laundry Appliances Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Colombia Appliances and Electronics Market
Appliances
GCC Dishwashers Market
Appliances
North America Compact Dishwasher Market
Appliances
Garments Steamer Market
Appliances
Egypt Microwave Ovens Market
Appliances
Israel Laundry Appliances Market
Appliances
Colombia Laundry Appliances Market
Appliances
North America Microwave Oven Market
Appliances
Qatar Microwave Ovens Market
Appliances
China Washing Machine Market
Appliances
Oman Microwave Ovens Market
Appliances
Dishwasher Market
Appliances
Hair Removal Appliances Market