
 Digital Showers Market | 2026-2036
Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Showers Market Analysis
Subscription-based leasing for bathroom fixtures is rewriting competitive access for mid-market developers. Kohler Co. leverages captive financing to extend its specification rate in North American hospitality projects. Hansgrohe anchors premium positioning through in-house thermostatic valve production. LIXIL Corporation competes across Asia-Pacific through distributed manufacturing scale.
A digital shower integrates electronically controlled water mixing, temperature regulation, and flow management through sensor arrays, solenoid valves, and programmable user interfaces delivering precise thermal output typically within 0.5 degrees Celsius. The primary commercial purpose centers on user safety, water conservation, and personalized bathing experience in residential and institutional settings. Smart product type variants capture expanding margin pools as Wi-Fi connectivity and app-based presets shift replacement cycles. Wall-mounted installation dominates volume due to retrofit compatibility, while ceiling-mounted systems concentrate in new-build luxury segments where concealed plumbing permits architectural integration.
EPA WaterSense certification and EU Ecodesign Directive frame minimum efficiency thresholds, compelling manufacturers to redesign valve architectures around reduced flow rates. CE marking under the EU Construction Products Regulation governs pressure safety and electromagnetic compatibility for connected shower controllers. Stakeholders must monitor divergence between regional connectivity standards as Matter protocol adoption in North America and proprietary smart home ecosystems in Asia-Pacific fragment interoperability requirements.
Market Dynamics
Water-efficiency mandates under EPA WaterSense and EU Ecodesign are compressing flow-rate tolerances and forcing valve architecture redesigns across the supply base. Manufacturers must now engineer around tighter thermal precision thresholds while maintaining user experience parity.
Growth Catalysts
- EU Ecodesign Directive:Mandated flow-rate reductions are accelerating replacement cycles in Western European residential retrofits as older fixtures fail compliance thresholds.
- Hospitality specification:Dubai and Singapore hotel chains are embedding smart shower systems as standard amenities to differentiate guest experience and meet sustainability credentials.
- Thermostatic valve miniaturization:Advances in ceramic disc and wax thermostatic element engineering are enabling concealed installation formats previously restricted to luxury new-builds.
Market Restraints
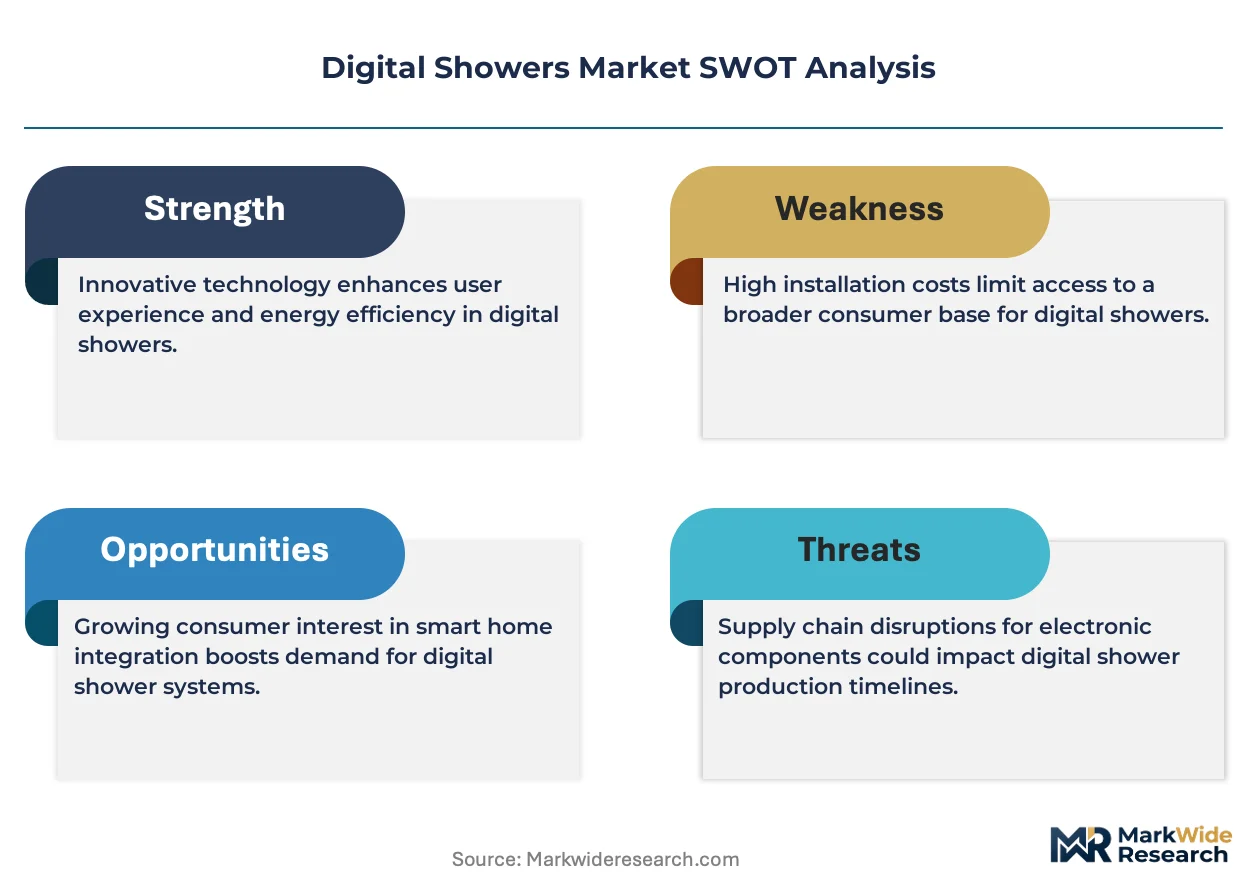
- Copper and brass input volatility:Foundry-grade copper price swings directly compress margin on mixer valve castings, the core cost driver in digital shower controllers.
- German supply concentration:Premium thermostatic valve production clusters heavily in southwestern Germany, creating single-source vulnerability for global OEMs.
- Legacy plumbing incompatibility:Existing high-pressure tank systems in older UK and French housing stock cannot support the low-flow, high-precision operation of digital controllers without full infrastructure replacement.
Strategic Opportunities
- Indian urban residential:Penetration of thermostatic mixing technology remains below 5% in tier-1 Indian cities, creating first-mover whitespace for localized temperature-control solutions.
- Matter protocol convergence:Cross-brand interoperability between shower controllers and home energy management systems opens subscription revenue streams for usage-based water monitoring.
- Commercial wellness facilities:Spa and thermal bath operators in Austria and Switzerland are specifying programmable hydrotherapy sequences as premium service differentiators.
Industry Challenges
- Electromechanical firmware certification:CE marking under the EU Construction Products Regulation requires extensive electromagnetic compatibility testing that extends product launch timelines by 8-14 months.
- Installer skill gaps:Commissioning of networked shower systems demands competencies in both plumbing and low-voltage electrical work that traditional trade training rarely combines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Showers Market |
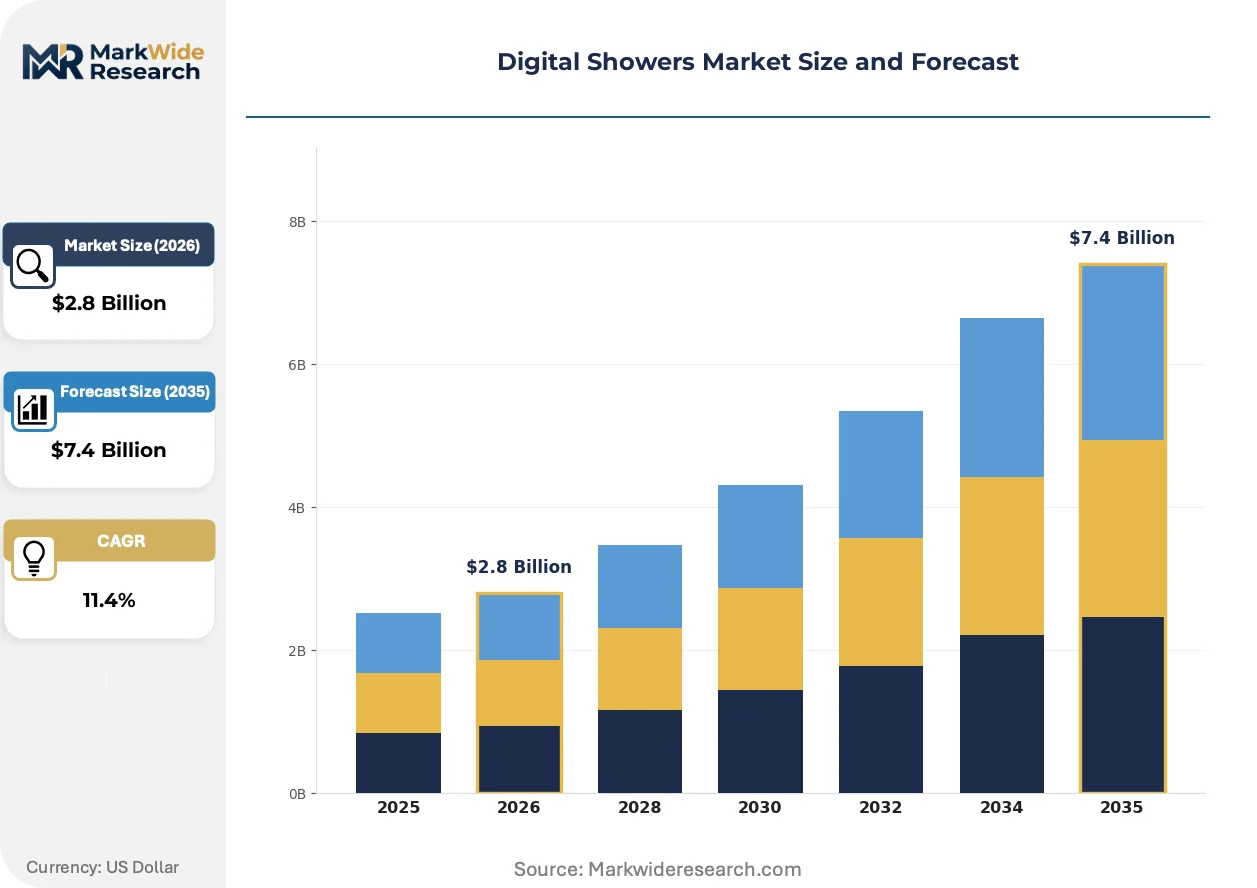
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostatic, Manual, Smart, Hybrid Installation Method: Wall-Mounted, Ceiling-Mounted, Freestanding, Built-in End User: Residential, Commercial, Hospitality, Healthcare Feature: Wi-Fi Connectivity, Remote Control, Touchscreen, Water Saving |
| Companies Covered | TOTO LTD., Aqualisa, Kohler Co., Delta Faucet, Hansgrohe, Moen Incorporated, LIXIL Corporation, Grohe, Roca Sanitario, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Showers Market Emerging Trajectories
Digital shower controllers are converging with building management systems and personal health platforms, transforming fixtures from isolated hardware into data-generating nodes. This connectivity shift is rewriting value capture models across residential and commercial specification channels.
Thermostatic mixing technology is collapsing the performance gap between concealed ceiling-mounted systems and exposed wall-mounted units. Boutique hotel developers in Portugal and Denmark are specifying flush-mounted controllers at mid-market price points previously reserved for basic exposed mixers. The technology is collapsing the traditional tiering between architectural and retrofit-compatible product lines.
EPA WaterSense certification thresholds are tightening maximum flow rates for showerheads sold in the United States, compelling manufacturers to redesign spray plate geometries around aerated and laminar flow patterns. California's Title 20 appliance efficiency regulations extend these constraints to thermostatic mixing valves themselves. Residential builders in Arizona and Nevada are now pre-specifying WaterSense-labeled digital controllers to preempt local water authority rebate compliance.
Subscription leasing for bathroom fixtures is displacing outright purchase in North American hospitality development. Mid-market hotel operators are transferring capital expenditure to operational budgets through fixture-as-a-service arrangements that bundle maintenance and technology refresh cycles. Procurement teams in Texas and Florida are piloting these models to reduce renovation downtime and obsolescence risk.
Digital Showers Market Segmentation
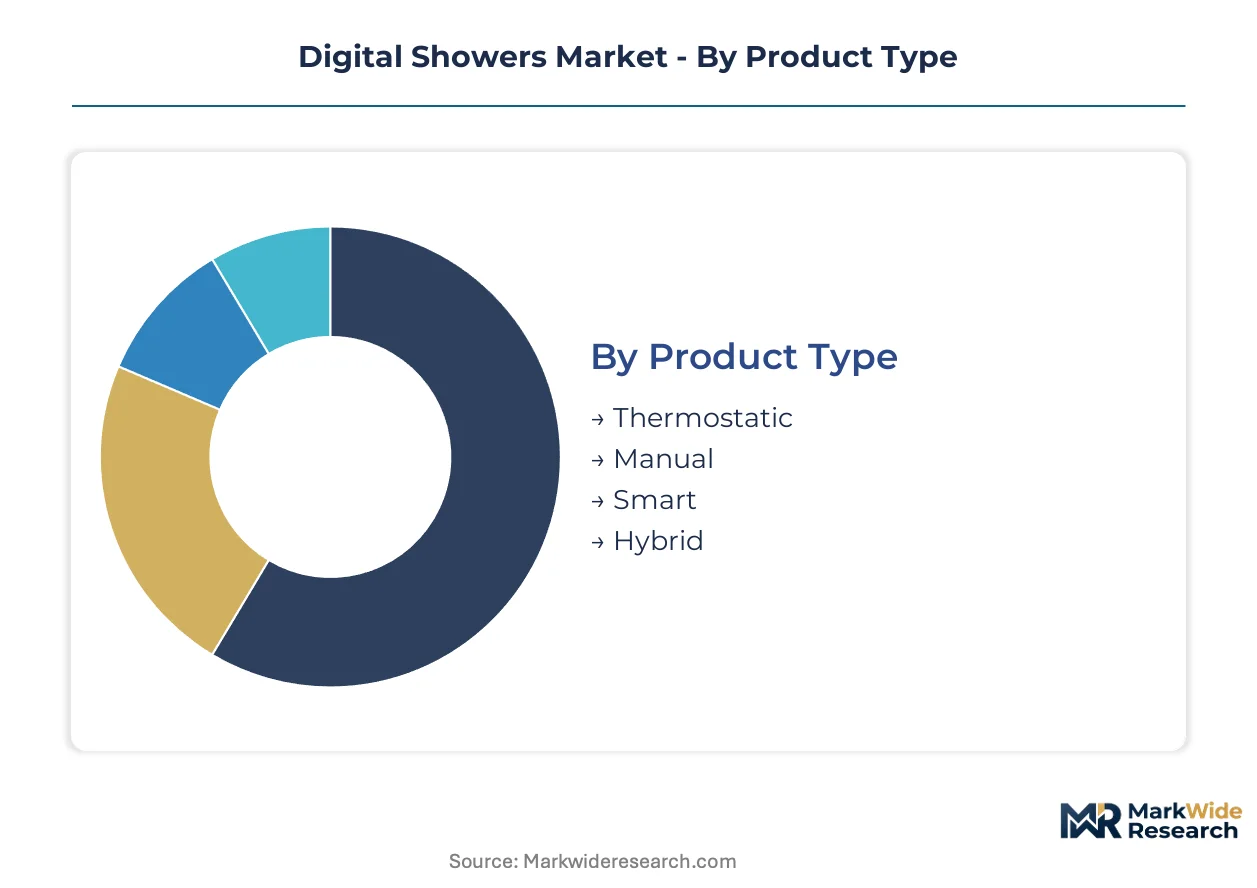
Digital shower architectures fragment across thermal control mechanisms, mounting configurations, and connectivity tiers. Each dimension carries distinct margin profiles, installation complexity, and replacement cycle dynamics that shape vendor positioning strategies.
Product Type:
Cost tier differentiation separates basic temperature stability from predictive, network-connected systems with usage analytics.
- Smart:Electronically controlled mixing with Wi-Fi integration, app-based presets, and usage telemetry. Hospitality chains in Dubai and Singapore specify these as standard amenities to meet sustainability credentials and differentiate guest experience. Premium positioning captures expanding margin pools as connected features shift replacement cycles.
- Thermostatic:Wax or ceramic disc elements maintain output temperature within 0.5 degrees Celsius regardless of inlet pressure fluctuations. German manufacturing clusters around Grohe and Hansgrohe supply global OEMs with precision valve assemblies, creating single-source vulnerability for premium tier producers.
- Manual:Traditional lever-operated mixing without electronic compensation. Builders in price-sensitive residential markets specify these where code compliance permits.
- Hybrid:Combines mechanical thermostatic cores with limited digital interfaces for preset storage. Mid-market developers in North American hospitality projects favor these for capital expenditure control.
Thermostatic variants command the established base. The steepest expansion runs through Smart systems.
Installation Method:
Application context dictates mounting geometry, with retrofit compatibility driving volume concentration and concealed architectural integration capturing premium specification.
- Wall-Mounted:Exposed valve bodies with surface plumbing connections dominate residential retrofit volumes. EPA WaterSense-certified controllers in this format accelerate replacement cycles in Western European housing stock as older fixtures fail compliance thresholds.
- Ceiling-Mounted:Concealed plumbing with flush control interfaces concentrates in new-build luxury segments. Boutique hotel developers in Portugal and Denmark now specify these at mid-market price points as thermostatic miniaturization collapses traditional tiering.
- Freestanding:Floor-mounted risers with independent supply connections serve wet-room and spa configurations. Commercial wellness facilities in Austria and Switzerland specify programmable hydrotherapy sequences on these platforms.
- Built-in:Fully recessed valve bodies with minimal visible hardware. High-rise residential towers in Singapore and UAE specify these for space efficiency and architectural clean lines.
Wall-Mounted systems anchor volume share. Ceiling-Mounted formats are climbing the fastest as concealed installation costs decline.
End User:
Customer type segmentation maps directly to procurement behavior, specification authority, and technology refresh cadence.
- Residential:Individual homeowners and multi-unit developers purchasing through retail and trade channels. Tier-1 Indian cities show underpenetration below 5% for thermostatic technology, creating first-mover whitespace.
- Hospitality:Hotel operators with centralized procurement and brand-standard compliance requirements. Subscription-based fixture leasing from Kohler Co. and competitors is rewriting competitive access for mid-market developers in Texas and Florida.
- Commercial:Office buildings, fitness centers, and institutional facilities with high-cycle usage patterns. Matter protocol convergence opens subscription revenue streams for usage-based water monitoring across these installations.
- Healthcare:Hospitals and long-term care facilities requiring anti-scald protection and infection control. CE marking under EU Construction Products Regulation governs electromagnetic compatibility for connected controllers in these sensitive environments.
Residential captures the volume base. Hospitality is gaining share fastest through specification consolidation and leasing model adoption.
Feature:
Technology maturity stratifies across connectivity protocols, interface modalities, and regulatory compliance tiers.
- Water Saving:Aerated spray plates and flow restrictors meeting EPA WaterSense and EU Ecodesign thresholds. California Title 20 extends constraints to thermostatic mixing valves themselves, forcing spray geometry redesigns.
- Wi-Fi Connectivity:Network integration enabling remote activation, usage tracking, and energy management system coupling. Proprietary smart home ecosystems in Asia-Pacific fragment interoperability requirements against Matter protocol adoption in North America.
- Remote Control:Handheld or wall-mounted wireless interfaces for temperature and flow adjustment. Installer skill gaps in combining plumbing and low-voltage electrical competencies constrain deployment velocity.
- Touchscreen:Capacitive or resistive panel interfaces for preset selection and diagnostic display. Extended electromagnetic compatibility testing for CE marking stretches product launch timelines by 8-14 months for these variants.
Water Saving features anchor regulatory compliance. Wi-Fi Connectivity is expanding most quickly as building management system integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision thermostatic valve assemblies to global OEMs while importing connected controller electronics from Asian supply chains. The United States runs a trade deficit in finished digital shower systems, offset by strong domestic fixture casting capacity. Singapore and Dubai function as specification gateways for hospitality-driven demand across their respective regions.
United States
EPA WaterSense certification thresholds are accelerating replacement cycles in Arizona and Nevada residential construction. California's Title 20 appliance efficiency regulations extend flow-rate constraints to thermostatic mixing valves themselves. Kohler Co. leverages captive financing to extend specification rates across Texas and Florida hospitality projects.
Germany
Grohe and Hansgrohe anchor premium manufacturing clusters in southwestern Germany supplying global OEMs with precision valve assemblies. CE marking under the EU Construction Products Regulation governs electromagnetic compatibility for connected shower controllers. Stuttgart-based engineering centers are driving thermostatic valve miniaturization for concealed ceiling-mounted formats.
China
MIIT standards and GB certification requirements are domesticating smart home connectivity protocols for shower controllers. Yangtze River Delta manufacturing bases are scaling ceramic disc valve production for cost-optimized thermostatic systems. Shanghai and Shenzhen electronics clusters supply solenoid valve arrays and sensor modules to global fixture assemblers.
United Arab Emirates
Dubai hospitality chains are embedding smart shower systems as standard amenities to differentiate guest experience and meet sustainability credentials. MOHAP and local water authority mandates are tightening flow-rate thresholds for new hotel construction. Dubai Design District specification teams are consolidating procurement around concealed ceiling-mounted formats for luxury tower developments.
India
Tier-1 cities show thermostatic mixing technology penetration below 5%, creating first-mover whitespace for localized temperature-control solutions. BIS certification requirements are gradually harmonizing with EU pressure safety standards for imported valve assemblies. Maharashtra and Karnataka residential developers are piloting digital controllers in premium high-rise projects.
Digital Showers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in valve casting and sensor supply. The vendor base stratifies across three tiers: full-stack bathroom platform owners, precision thermostatic valve specialists, and electronics-integrated fixture assemblers. Two dominant competitive moves are reshaping positioning: subscription-based fixture leasing displacing outright purchase in hospitality procurement, and backward integration into captive thermostatic valve production to defend margin pools.
Among Japanese platform integrators, TOTO LTD. and LIXIL Corporation exemplify scale-driven diversification across fixture categories and geographic markets. German specialists Hansgrohe and Grohe occupy positions anchored in precision thermostatic valve manufacturing clusters. These named entities represent the archetype spectrum from integrated bathroom platforms to component-specialist positioning.
| Leading Market Players |
|---|
| TOTO LTD. |
| Aqualisa |
| Kohler Co. |
| Delta Faucet |
| Hansgrohe |
| Moen Incorporated |
| LIXIL Corporation |
| Grohe |
| Roca Sanitario, S.A. |
| Others |
Supply Flow & Price Mechanics
Copper and brass input volatility determines both pricing tier spreads and supply chain shape in digital shower manufacturing. Foundry-grade copper price swings compress margin on mixer valve castings while forcing tiered pricing stratification across premium thermostatic and standard electronic controllers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from thermostatic precision certification and volume scale commitments. Pricing pressure stems from copper commodity volatility squeezing foundry margins. Hospitality procurement teams show lowest price sensitivity due to bundled leasing models, while residential retrofit contractors exhibit highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Extended payment terms from German valve specialists to Asian electronics assemblers lubricate working capital across the supply chain. Manufacturing gravity centers on southwestern Germany for precision thermostatic assemblies, China for ceramic disc valves and sensor modules, and the United States for domestic fixture casting. Raw material dependencies encompass foundry-grade copper, brass alloys, and rare-earth magnet components for solenoid actuators. Single-source vulnerability concentrates in German thermostatic element production. Distribution runs through specification-driven project channels for hospitality and retail plumbing merchant networks for residential replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital shower penetration sits below 5% in tier-1 Indian cities, signaling early-cycle expansion with substantial runway before saturation thresholds emerge.
For Market Incumbents: Pre-empt margin erosion from copper volatility by securing captive foundry capacity or long-term alloy supply agreements. Accelerate thermostatic valve miniaturization R&D to collapse cost premiums on concealed ceiling-mounted formats before Asian competitors replicate the technology. Defend specification relationships with Dubai and Singapore hospitality chains through bundled sustainability certification packages. For New Entrants and Emerging Players: Tier-1 Indian urban residential markets offer whitespace for localized temperature-control solutions adapted to pressure-variable infrastructure. Target mid-market North American hospitality developers with hybrid mechanical-digital controllers that balance capital expenditure control with guest experience differentiation. Pursue direct specification relationships with boutique hotel operators in Portugal and Denmark seeking flush-mounted aesthetics at accessible price points. For Investors and Strategic Acquirers: EU Ecodesign Directive flow-rate mandates reshape the acquisition landscape by accelerating replacement cycles and consolidating procurement authority among specification-capable platforms. Five-to-ten year viability favors component specialists with captive thermostatic valve production over pure-play electronics integrators. Monitor Matter protocol adoption velocity in North American residential as the signal indicating platform winner-take-all dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermostatic Valve Production | Hansgrohe and Grohe defend margin pools through in-house ceramic disc manufacturing in southwestern Germany. |
| Subscription-Based Fixture Leasing | Kohler Co. transfers hospitality capital expenditure to operational budgets across Texas and Florida projects. |
| Matter Protocol Certification | Cross-brand interoperability opens usage-based water monitoring revenue streams for building energy management coupling. |
| Concealed Ceiling-Mounted Format Expansion | Thermostatic miniaturization enables mid-market specification previously restricted to luxury new-build segments. |
| Indian Market Localization | Localized temperature-control solutions address sub-5% thermostatic penetration in tier-1 cities with pressure-adaptive engineering. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hotel procurement directors, plumbing merchant category managers, thermostatic valve engineering leads, and residential developer specification teams. Secondary validation drew from EPA WaterSense certification databases, EU Ecodesign Directive compliance filings, customs trade records for brass and copper alloy flows, and hospitality sustainability disclosure reports. Bottom-up unit shipment estimates triangulated against top-down construction spend allocations across residential, hospitality, and commercial wellness segments.
Calibration against historical replacement cycle data and regulatory compliance deadline phasing shaped volume projections across the analysis window. Segmentation dimensions encompassed product type, installation method, end user, and connectivity feature tier. CAGRs derived from fitted growth curves applied to penetration rate trajectories in underdeveloped markets and replacement acceleration in mandate-driven regions. Forecast inputs included copper price scenario modeling and hospitality construction pipeline tracking for Dubai, Singapore, and Portuguese boutique developments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese ceramic disc valve specialists or Indian market entrants would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
United States Commercial Laundry Appliances Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
South Africa Laundry Appliances Market
Appliances
Cooler Connected to the Mains Market
Appliances
North America Microwave Oven Market
Appliances
US Portable Washing Machines Market
Appliances
Triple Barrel Waver Market
Appliances
UAE Microwave Ovens Market
Appliances
Israel Laundry Appliances Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Toaster Ovens Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Washing Appliances Market
Appliances
Japan Laundry Appliances Market
Appliances
Minibar Refrigerators Market
Appliances
Consumer Appliances Market