
 Consumer Appliances Market | 2026-2036
Consumer Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Appliances Market Analysis
Residential household demand for connected kitchen ecosystems is decoupling from traditional replacement cycles as smart home integration becomes a primary purchase trigger. Samsung Electronics leverages its semiconductor supply chain to dominate connected refrigerator and oven platforms across Asia and North America. Whirlpool Corporation anchors its position in North American laundry through captive manufacturing scale and dealer network control. Miele differentiates in European premium segments through in-house production of proprietary motor and sensor systems.
Consumer appliances encompass electrically powered devices designed for domestic and light commercial tasks, typically operating at 110–240 volts with rated capacities from 0.5 kW countertop units to 5 kW+ built-in cooking systems, manufactured through stamped metal forming, injection molding, and automated coil winding of compressor or motor assemblies. Their primary purpose is to reduce manual labor in food preservation, preparation, cleaning, and climate control. Refrigerators generate the largest revenue pool within product type segmentation due to compressor technology complexity and replacement stickiness, while smart appliances within technology segmentation capture the fastest expansion as IoT-Enabled protocols standardize. Energy-Efficient models command margin premiums where regulators enforce minimum performance standards, and Traditional segments face compression in developed markets but sustain volume in price-sensitive developing economies.
The EU Ecodesign Directive and REACH chemical compliance frameworks in Europe, combined with EPA ENERGY STAR certification and DOE appliance standards in the United States, shape demand by mandating measurable efficiency thresholds and restricting hazardous substance use in coatings and refrigerants. China's GB standards and NMPA-aligned product safety certifications create parallel compliance layers for manufacturers serving domestic and export channels. Stakeholders must monitor regulatory divergence between efficiency test methodologies as divergent national standards threaten to fragment product platform strategies and inflate certification costs.
Market Dynamics
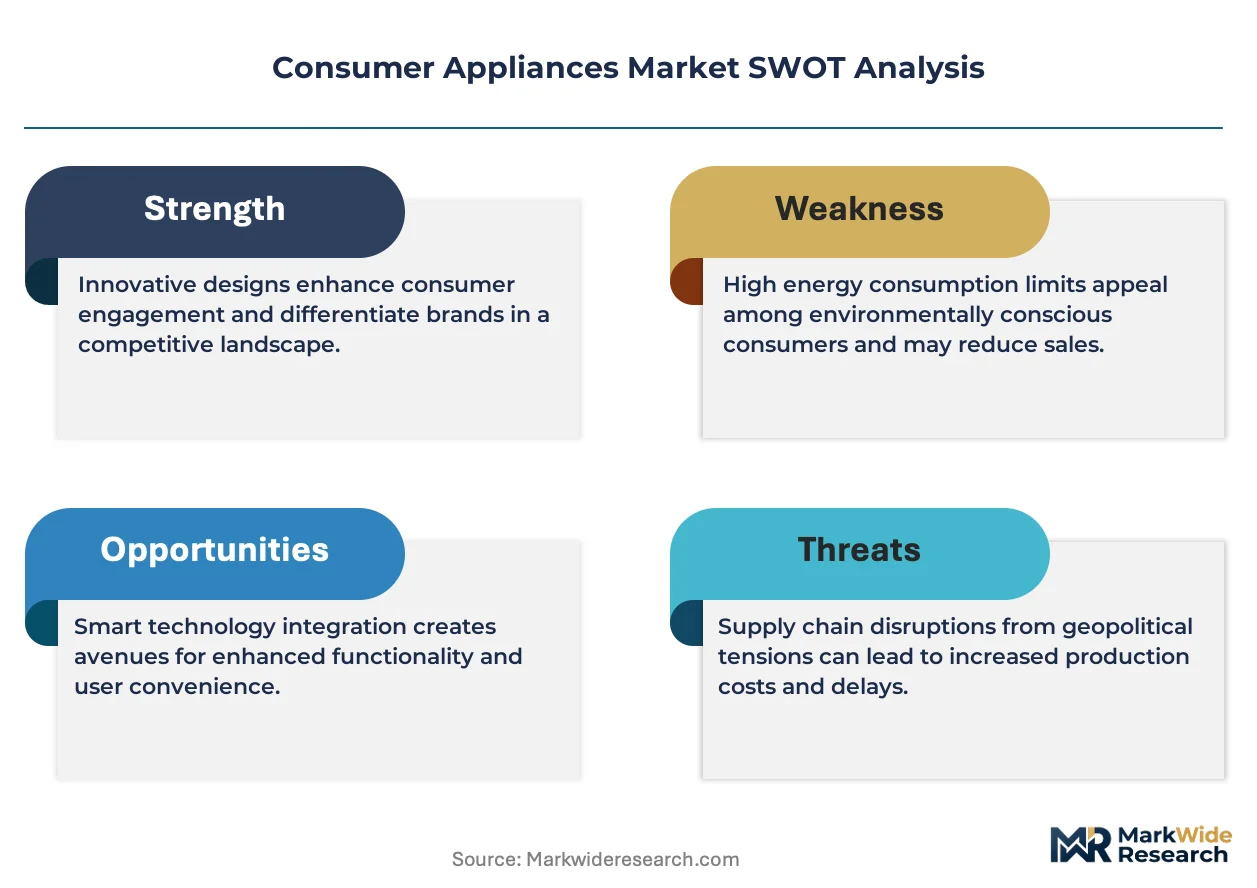
The EU Ecodesign Directive and tightening MEPS standards across multiple jurisdictions are forcing manufacturers into fundamental efficiency redesigns, compressing traditional product development cycles while accelerating connected feature integration as a differentiation lever.
Growth Catalysts
- Smart home protocol standardization:Matter and Thread protocols enable cross-brand interoperability, reducing consumer lock-in friction and accelerating replacement decisions in residential segments.
- Urban middle-class expansion:Concentrated demand growth in China, India, and the United States compresses replacement cycles as household formation rates outpace historical baselines.
- MEPS alignment:Minimum Energy Performance Standards in Australia, Canada, and South Korea create regulatory pull for inverter compressor and heat pump dryer technologies.
Market Restraints
- Copper and rare-earth magnet volatility:Compressor motor assemblies depend on concentrated Chilean copper and Chinese neodymium processing, exposing margin structures to commodity swings.
- Refrigerant transition friction:F-Gas Regulation phase-down timelines in Europe and Kigali Amendment implementation in developing markets force parallel R&D streams for HFO and natural refrigerant platforms.
- Semiconductor allocation constraints:Power management ICs and connectivity modules face foundry capacity prioritization toward automotive and data center customers.
Strategic Opportunities
- Service revenue attachment:Predictive maintenance subscriptions and consumable auto-replenishment models create recurring revenue streams alongside hardware sales.
- India PLI scheme:Production-linked incentive structures for white goods manufacturing attract component localization investments serving domestic and export demand.
- Heat pump convergence:Integration of space heating and water heating functions into appliance platforms captures electrification tailwinds from building decarbonization mandates.
Industry Challenges
- Embedded software talent scarcity:Firmware development for IoT security and edge AI inference competes with automotive and industrial automation sectors for limited engineering pools.
- Multi-jurisdiction certification stacking:Divergent efficiency test methodologies between DOE, EU, and GB standards inflate validation timelines and platform fragmentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Appliances Market |
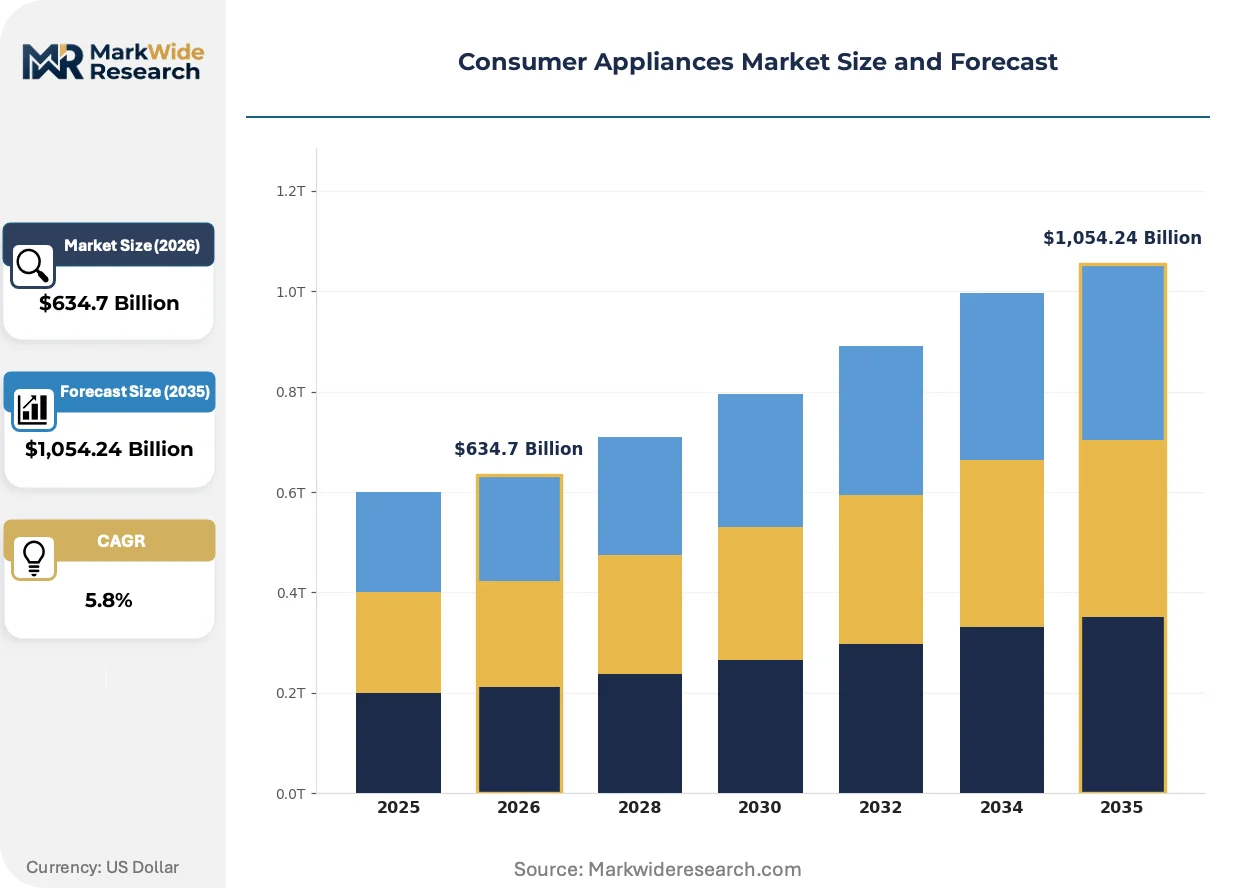
| Market Size in 2026 | $634.7 Billion |
| Market Size in 2035 | $1,054.24 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Microwaves End User: Households, Commercial Kitchens, Retailers, Hotels Technology: Smart Appliances, Energy-Efficient, Traditional, IoT-Enabled Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Direct Sales |
| Companies Covered | Samsung Electronics, Haier, Whirlpool Corporation, Sharp, Miele, GE Appliances, Bosch, Gaggenau, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Appliances Market Emerging Trajectories
Connected kitchen ecosystems are unifying previously discrete appliance categories through shared data layers and coordinated automation routines, compressing the traditional standalone replacement logic that governed household purchasing.
Edge AI inference engines embedded in refrigerator and oven control boards are unifying sensor fusion, inventory tracking, and cooking parameter optimization into single-chip architectures. Premium residential buyers in South Korea and the United States adopt these platforms fastest. This convergence is unifying hardware and software margin pools that previously separated across component suppliers and OEMs.
REACH chemical compliance frameworks and F-Gas Regulation phase-down schedules in Europe are mandating refrigerant transitions and restricted substance elimination in coatings. Manufacturers must maintain parallel product platforms for R600a, R290, and HFO variants. Built-in cooking systems and premium refrigerator lines face the steepest cost absorption pressure as certification timelines compress.
Direct-to-consumer channel expansion through manufacturer-owned websites and app-based purchasing is displacing traditional dealer and big-box retail intermediation in developed markets. Younger household formation cohorts in Germany and Japan demonstrate highest comfort with virtual configuration and remote installation scheduling. This disintermediation concentrates margin recovery toward OEMs while demanding last-mile logistics investments that previously fell to retail partners.
Consumer Appliances Market Segmentation
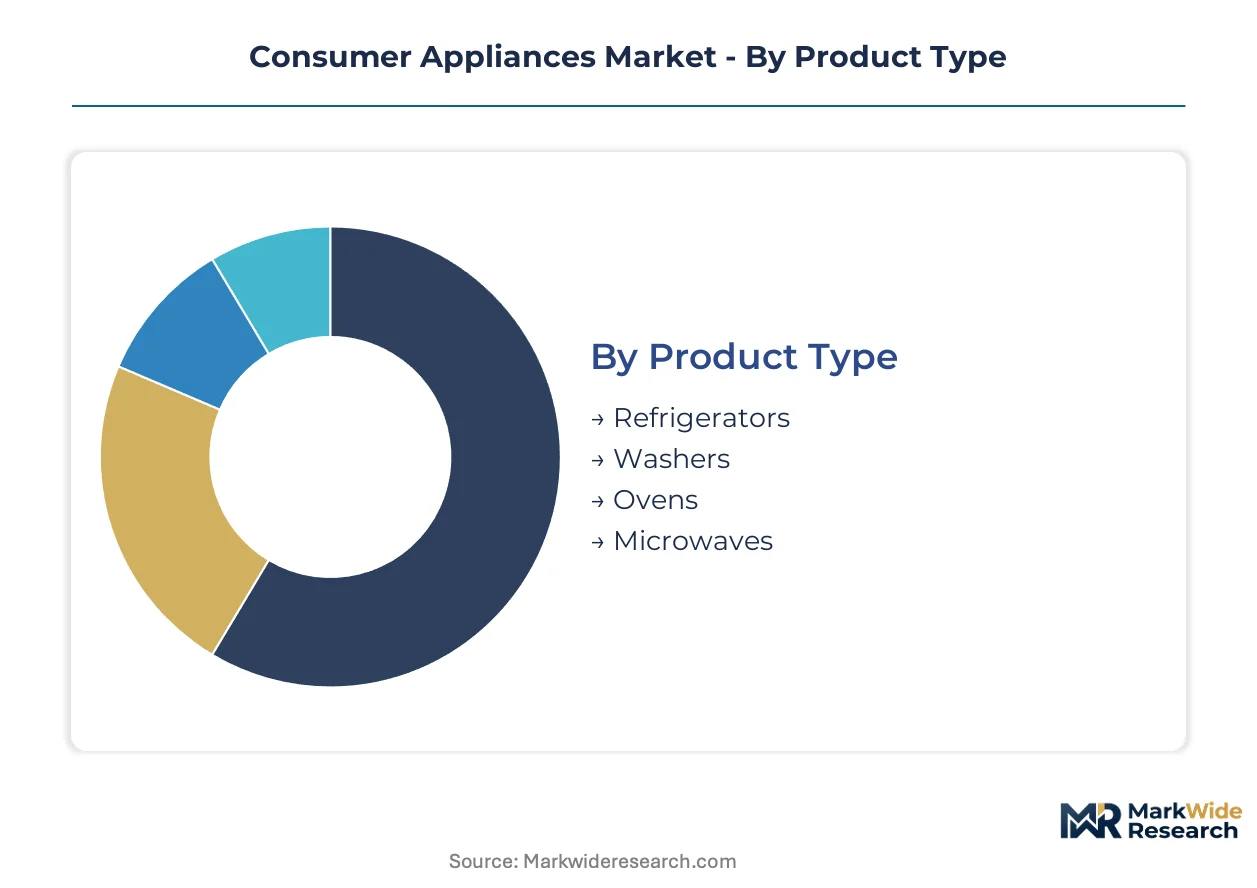
Appliance segmentation reveals how upgrade cycles fragment across technical sophistication, procurement channel, and end-use intensity. Understanding these splits helps manufacturers align platform investments with replacement triggers rather than generic household formation data.
Product Type:
Replacement cycles vary dramatically by mechanical complexity and installation friction, with built-in categories demanding longer planning horizons than plug-in alternatives.
- Refrigerators:Compressor-driven cooling systems rated 100–800 liters integrate variable-speed inverter motors and refrigerant circuits requiring sealed-system manufacturing. Demand concentrates in China and the United States where urban household formation drives side-by-side and French-door upgrades ahead of efficiency mandate deadlines.
- Washers:Front-load and top-load drum assemblies with direct-drive or belt-drive motor configurations span 5–12 kg capacity ratings. European and South Korean buyers prioritize heat pump dryer pairings as MEPS thresholds tighten, compressing replacement decisions around energy label jumps.
- Ovens:Built-in convection and steam-assist cooking systems with 2.5–5 kW heating elements serve kitchen renovation cycles.
- Microwaves:Countertop and over-range magnetron units at 600–1200 watts follow shortest replacement intervals.
Refrigerators sit at the top of the volume ranking, with washers climbing the fastest as heat pump convergence accelerates upgrade decisions.
End User:
Procurement authority and usage intensity create divergent specification requirements across residential and commercial buyers.
- Households:Individual purchase decisions prioritize connected feature integration and energy operating cost over acquisition price, with smart home ecosystem compatibility emerging as a primary filter.
- Commercial Kitchens:High-cycle operations demand NSF-certified stainless construction and rapid-recovery heating systems rated for continuous duty.
- Retailers:Display and storage appliances for food service resale emphasize reliability warranties and rapid parts availability.
- Hotels:In-room mini-bar and laundry specifications balance guest experience consistency with housekeeping labor reduction.
Households dominate absolute unit demand, while commercial kitchens expand most quickly as food service automation investments accelerate.
Technology:
Margin pools separate sharply between certified efficiency tiers and connectivity stacks, with regulatory pull forcing parallel platform maintenance.
- Smart Appliances:Wi-Fi and Thread-enabled control boards with edge AI inference engines unify sensor fusion and predictive maintenance algorithms. Adoption concentrates in South Korea and Germany where Matter protocol standardization reduces ecosystem lock-in friction.
- Energy-Efficient:Inverter compressors, vacuum insulation panels, and heat pump drying circuits meet ENERGY STAR and EU Ecodesign thresholds. Australian and Canadian regulatory calendars are compressing availability of legacy motor technologies.
- Traditional:Fixed-speed compressors and resistive heating elements sustain volume in price-sensitive developing markets.
- IoT-Enabled:Cloud-connected inventory tracking and recipe automation platforms generate service revenue attachment opportunities.
Energy-Efficient models command the largest installed base, with Smart Appliances gaining share fastest as protocol standardization reduces consumer hesitation.
Distribution Channel:
Channel selection determines margin recovery rates and last-mile service obligations, with disintermediation pressures reshaping traditional retail economics.
- Online Retail:Manufacturer-direct and marketplace platforms with virtual configuration tools and installation scheduling capture younger household formation cohorts in Japan and Germany.
- Specialty Stores:Dealer networks with in-house service technicians and financing programs anchor premium built-in cooking and refrigeration sales.
- Mass Merchandisers:Big-box retail with private-label sourcing and promotional bundling dominates North American replacement volume.
- Direct Sales:Builder and contractor channels with project-specification relationships capture new construction and renovation pipelines.
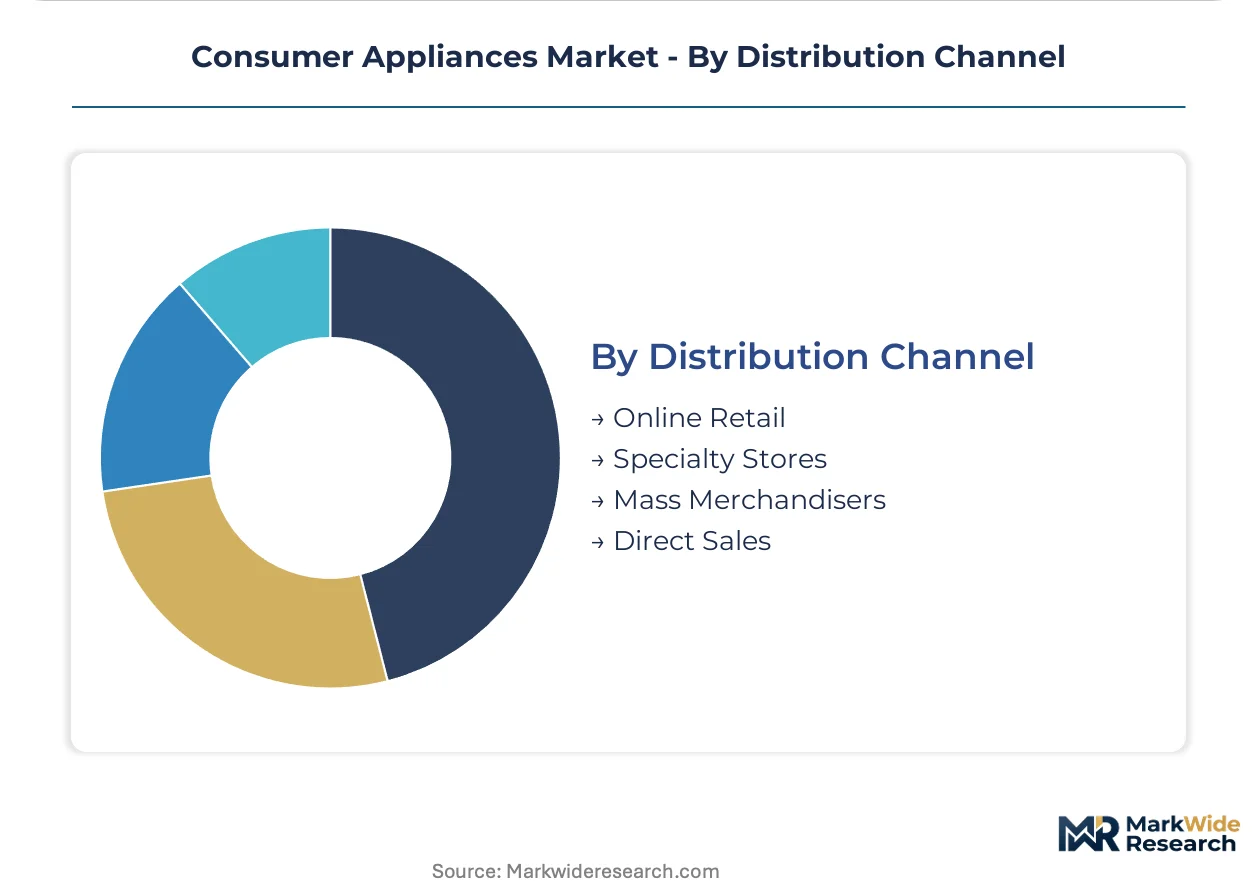
Mass Merchandisers retain the highest transaction volume, with Online Retail expanding most quickly as virtual configuration tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as manufacturers relocate assembly to jurisdictions with streamlined certification pathways and production-linked incentive structures. Cost-of-compliance gaps between mature and emerging economies now determine component sourcing decisions more than labor differentials alone.
China
Urban household formation in tier-one cities accelerates side-by-side refrigerator upgrades ahead of GB standards tightening. NMPA-aligned safety certifications and MIIT efficiency mandates compress product development timelines. The Yangtze River Delta concentration around Shanghai and Suzhou hosts captive compressor manufacturing clusters serving domestic and export demand.
United States
Residential renovation cycles and smart home ecosystem integration drive built-in cooking and connected refrigeration decisions. EPA ENERGY STAR certification and DOE appliance standards enforce minimum efficiency thresholds that phase out legacy motor technologies. The Southeast manufacturing corridor spanning Georgia and South Carolina attracts assembly investments seeking proximity to Atlantic shipping lanes.
Germany
Premium segment buyers prioritize heat pump dryer pairings and Matter protocol compatibility as replacement triggers. ECHA REACH frameworks and F-Gas Regulation phase-down schedules mandate refrigerant transitions and restricted substance elimination. The Baden-Württemberg industrial cluster around Stuttgart anchors in-house motor and sensor production for built-in cooking systems.
India
Urban middle-class expansion compresses replacement cycles for frost-free refrigerators and front-load washers. BIS standards and the PLI scheme for white goods manufacturing attract component localization investments. The Gujarat industrial corridor between Ahmedabad and Vadodara concentrates assembly capacity serving domestic demand and Middle East export channels.
South Korea
Early adoption of edge AI inference engines in refrigerator and oven control boards drives premium platform demand. MFDS-aligned product safety certifications and METI-influenced efficiency benchmarks shape export-oriented production. The Seoul Capital Area concentration anchors R&D integration between semiconductor and appliance divisions.
Consumer Appliances Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers add inverter compressor and heat pump assembly lines to capture MEPS-driven upgrade cycles. The vendor base stratifies across three tiers: diversified electronics conglomerates with captive semiconductor supply, specialized appliance OEMs with dealer network control, and premium specialists with in-house component production. Strategic archetypes include scale-driven platform players, vertical-integration specialists, and connectivity-first ecosystem builders. M&A activity and geographic diversification represent the dominant competitive moves as firms acquire regional brands and establish tariff-advantaged assembly hubs.
Among diversified electronics conglomerates, Samsung Electronics and LG Electronics exemplify the connectivity-first archetype through semiconductor-adjacent appliance platforms. Whirlpool Corporation occupies a position within the specialized OEM tier, representing dealer-network-dependent market presence. Miele sits within the premium specialist category, exemplifying in-house component production strategies.
| Leading Market Players |
|---|
| Samsung Electronics |
| Haier |
| Whirlpool Corporation |
| Sharp |
| Miele |
| GE Appliances |
| Bosch |
| Gaggenau |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists across Germany and Italy anchor premium appliance pricing discipline through captive motor production and multi-generational dealer relationships, while their supply choices concentrate component sourcing within EU regulatory orbits to minimize REACH compliance friction.
Pricing Analysis
Distributor margin layers absorb the steepest compression as direct-to-consumer channels disintermediate traditional retail markups in developed markets. Three-tier pricing structure across premium, standard, and economy levels separates Miele-tier built-in systems from mass-market private-label alternatives, with price differentiation driven by ENERGY STAR certification tier and after-sales service bundling. Pricing pressure stems from copper and rare-earth magnet cost volatility feeding through compressor motor assemblies. Commercial kitchen buyers exhibit lowest price sensitivity due to lifecycle cost accounting, while developing-market households face acute acquisition-price constraints.
Supply Chain Analysis
Certification gating through divergent DOE, EU Ecodesign, and GB efficiency test methodologies fragments platform strategies and elongates validation timelines for multi-jurisdiction launches. Component manufacturing concentrates in China, South Korea, and Germany, with inverter compressor assemblies drawing from Yangtze River Delta clusters and Baden-Württemberg motor specialists. Neodymium magnet and copper coil dependencies create single-source vulnerability through Chinese processing dominance. Distribution runs through manufacturer-direct platforms, specialty dealer networks, and mass merchandisers with varying last-mile service obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumer appliances constitute a late-cycle quality story as residential replacement decisions pivot from price-driven failure replacement to premium smart-home ecosystem integration.
For Market Incumbents: Cement dealer network loyalty through exclusive service technician certification programs and predictive maintenance subscription bundling. Defend against connectivity-first entrants from semiconductor-adjacent conglomerates by deepening in-house edge AI firmware development and Matter protocol interoperability investments. Prioritize captive compressor manufacturing scale in tariff-advantaged jurisdictions. For New Entrants and Emerging Players: Begin with white-glove installation and virtual kitchen configuration services targeting renovation-cycle households in Germany and Japan where direct-to-consumer comfort runs highest. Penetrate the heat pump dryer pairing segment as MEPS thresholds tighten in Australia and Canada. Leverage India PLI scheme localization for component cost parity serving Middle East export channels. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized OEMs with underutilized inverter compressor capacity and fragmented regional brand portfolios. Long-term viability hinges on software service revenue attachment rates and IoT security architecture differentiation. Watch heat pump convergence adoption curves in European renovation markets as electrification mandate inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Capacity Expansion | Captures MEPS-driven upgrade cycles in Australia, Canada, and South Korea regulatory calendars. |
| Edge AI Control Board Development | Unifies sensor fusion and predictive maintenance algorithms for Samsung-tier connectivity positioning. |
| Direct-to-Consumer Channel Buildout | Disintermediates retail markups through virtual configuration tools in German and Japanese markets. |
| Heat Pump Dryer Platform Integration | Consolidates space heating and water heating functions under building decarbonization mandates. |
| India Component Localization | Exploits PLI scheme incentives serving domestic demand and Middle East export channels. |
Methodological Framework
Coverage spans China, the United States, Germany, India, and South Korea, with primary inputs from each market's appliance manufacturing executives, regulatory compliance officers, retail category buyers, and aftermarket service heads. Secondary validation draws from MIIT efficiency disclosures, EPA ENERGY STAR certification databases, EU Ecodesign implementing measure texts, and customs trade records. Bottom-up unit shipment modeling triangulates against top-down value estimates from manufacturer revenue disclosures.
Granularity-level modeling operates at product-type, technology-tier, and distribution-channel intersections, with separate trajectories for smart, energy-efficient, traditional, and IoT-enabled platforms across the projection horizon. CAGRs derive from replacement-cycle compression analysis tied to urban household formation rates and regulatory mandate calendars. Industry-specific inputs include semiconductor allocation constraints for power management ICs and refrigerant transition timelines under F-Gas Regulation phase-down schedules.
Caveats apply where copper and rare-earth magnet commodity swings, semiconductor foundry capacity reprioritization, or divergent national efficiency test methodology divergence could materially shift the outlook. Forecasts reflect assumptions around Matter protocol adoption curves and MEPS alignment timelines. A model refresh is warranted upon material change in regulatory calendar synchronization or embedded software talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Shared Shoe Washing Machine Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
India Washing Machine Market
Appliances
North America Personal Care Appliances Market
Appliances
Kuwait Microwave Ovens Market
Appliances
UAE Gas Hobs Market
Appliances
Vacuum Cleaner Market
Appliances
Electric Ranges Market
Appliances
Personal Care Appliances Market
Appliances
Qatar Dishwashers Market
Appliances
Household Vacuum Cleaners Market
Appliances
Cooker Hoods Market
Appliances
Smart Connected Washing Machine Market
Appliances
APAC White Goods Market
Appliances
Colombia Appliances and Electronics Market
Appliances
Electric Hand Dryer Market