
 Sri Lanka Seed Market | 2026-2036
Sri Lanka Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Seed Market Analytics
Buyer concentration among Sri Lankan agricultural cooperatives is shifting toward fewer, larger procurement pools that negotiate volume-based supply contracts. Syngenta Group Co. Ltd leverages its hybrid vegetable portfolio to dominate premium segments. CIC Holdings PLC anchors its position through backward integration into seed processing and farmer extension networks. Bayer AG competes on trait-based differentiation in field crops.
Sri Lanka seeds comprise genetically stable or hybridized propagules with specified germination rates, moisture content below 8-12%, and varietal purity thresholds enforced under national seed policy; their primary purpose is to secure crop establishment, yield consistency, and pest resistance for commercial and subsistence farming. Vegetable seeds command the deepest margin pools due to short crop cycles and repeated purchase behavior, while hybrid seeds capture value through proprietary trait stacks and farmer loyalty. Open-pollinated seeds retain volume leadership among cost-sensitive paddy growers in the Dry Zone.
Sri Lanka's Department of Agriculture seed certification, the Seed Act enforcement framework, and FAO-aligned phytosanitary standards govern varietal release, import quotas, and field inspection protocols that directly shape market access timelines. The country's national agricultural regulator maintains a positive list for approved cultivars, forcing suppliers to navigate variety registration before commercialization. Stakeholders must monitor pending revisions to seed import tariffs and the expansion of climate-resilient breeding programs as determinants of competitive positioning.
Market Dynamics
Buyer consolidation among Sri Lankan agricultural cooperatives is compressing supplier margins while hybrid vegetable seed premiums expand. The Seed Act enforcement framework and Department of Agriculture certification protocols create dual barriers to market entry that favor established processors with backward integration into farmer extension networks.
Growth Catalysts
- Seed Act Certification Mandates:The Department of Agriculture's varietal release requirements and field inspection protocols elevate quality baselines, forcing substandard suppliers out and rewarding certified processors with preferential procurement access from North Central Province cooperatives.
- Vegetable Cultivation Expansion:Smallholder farmers in irrigated zones around Anuradhapura and Polonnaruwa are intensifying vegetable rotations, driving repeat purchase cycles for short-cycle hybrid seeds with proprietary trait stacks.
- Climate-Resilient Breeding Programs:National agricultural research stations are releasing drought-tolerant paddy varieties tailored to Dry Zone rainfall patterns, creating replacement demand for certified seed stocks among subsistence growers.
Market Restraints
- Import Quota Friction:The Department of Agriculture's positive list for approved cultivars and import licensing delays extend commercialization timelines by 18-24 months for foreign germplasm suppliers.
- Input Cost Volatility:Fertilizer subsidy fluctuations and fuel price shocks for irrigation pumping erode farmer working capital, compressing seed purchase budgets in marginal rainfall zones.
- Substitution Threat from Farm-Saved Seed:Open-pollinated paddy varieties retain 40-60% of farmer plantings through retained grain, limiting addressable market expansion for commercial certified seed.
Strategic Opportunities
- Eastern Province Underpenetration:Ampara and Batticaloa districts show sub-30% certified seed adoption in vegetable cropping, offering first-mover positioning for processors establishing local conditioning facilities.
- Digital Extension Channel Innovation:Mobile-based agronomy advisory platforms linked to seed purchase records are capturing farmer loyalty data and enabling predictive inventory placement ahead of planting windows.
- PLI-Aligned Domestic Processing:Sri Lanka's agricultural modernization incentives support backward integration into seed conditioning and coating infrastructure, reducing import dependency for treated vegetable seed.
Industry Challenges
- Phytosanitary Compliance Timeline Compression:FAO-aligned field inspection protocols and post-harvest testing requirements create certification bottlenecks during peak planting season demand surges.
- Trait Licensing Complexity:Hybrid vegetable seed producers face royalty stacking from multiple germplasm licensors, complicating margin structures for mid-tier processors without captive breeding programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Seed Market |
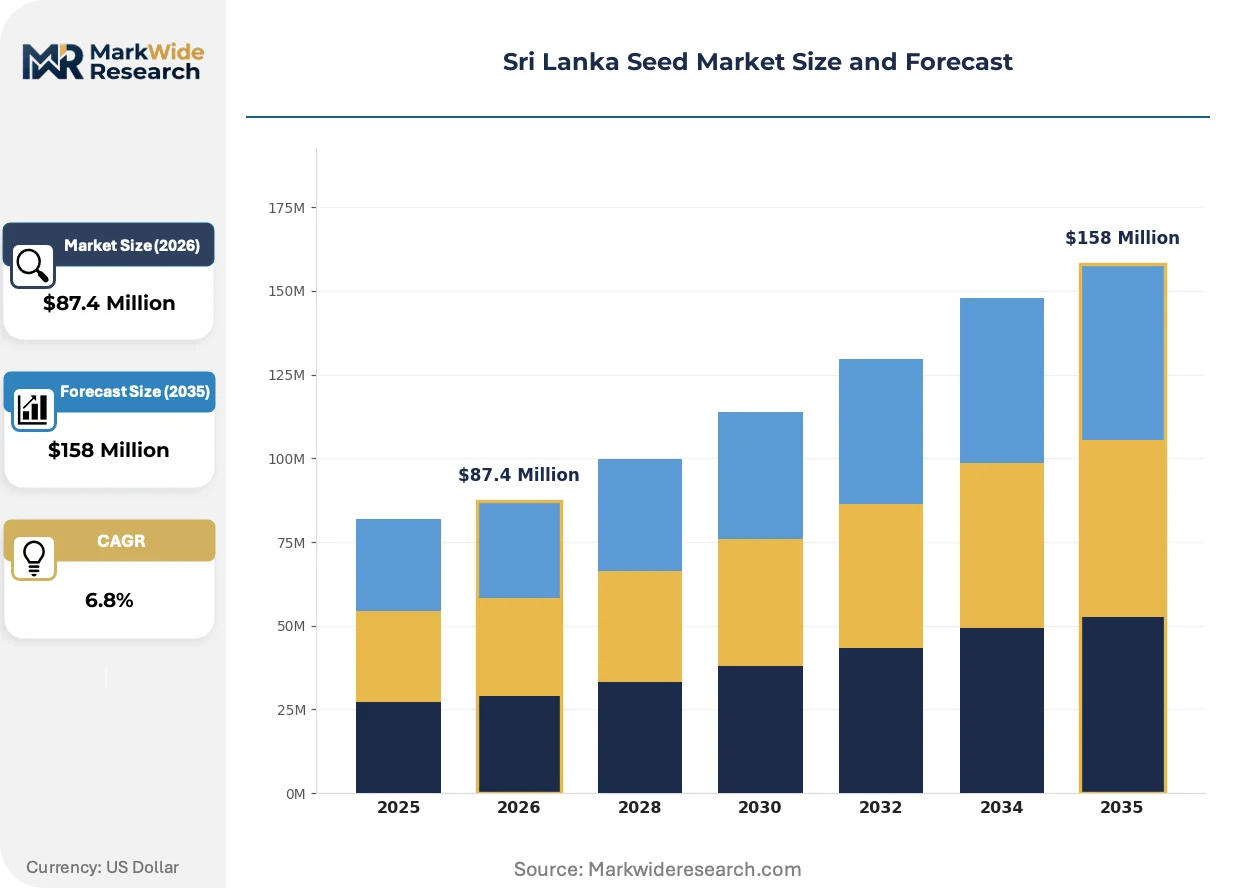
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Vegetable Seeds, Flower Seeds, Grain Seeds, Fruit Seeds End Use: Agricultural, Horticultural, Landscaping, Domestic Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Agricultural Cooperatives Product Line: Hybrid Seeds, Open-Pollinated Seeds, Organic Seeds, GMO Seeds |
| Companies Covered | East-West Seed Group B.V, Syngenta Group Co. Ltd, CIC Holdings PLC, Corteva Agriscience, Bayer AG, Hayleys PLC, UPL (Advanta Seeds), SunAgro Lanka, Troseed Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Seed Market Evolving Landscape
Precision agriculture tools and digital traceability systems are penetrating Sri Lankan seed distribution, while regulatory pressure on varietal purity accelerates laboratory testing adoption. These forces are compressing traditional supply chain hierarchies.
Seed coating automation incorporating polymer-based moisture retention and micronutrient layering is automating quality standardization previously dependent on manual batch processing. Medium-scale vegetable seed processors in Kurunegala and Kandy districts are retrofitting conditioning lines to capture premium pricing for treated seed. This technology is automating germination rate consistency and reducing post-sale farmer complaint volumes.
Sri Lanka's Department of Agriculture is tightening enforcement of the Seed Act's labeling and purity disclosure requirements, mandating laboratory certification for all commercially distributed vegetable and field crop varieties. Processors without in-house testing infrastructure face margin compression from third-party laboratory fees. The North Central Province's cooperative procurement pools are now requiring batch-specific germination certificates, shifting competitive advantage to vertically integrated suppliers.
Farmer purchasing through mobile-enabled cooperative aggregators is displacing traditional village-level retailer networks for hybrid vegetable seed. Younger smallholders in irrigated zones are pre-ordering certified seed through WhatsApp-linked cooperative channels with embedded agronomy support. This behavioral shift is most visible in Anuradhapura District's vegetable belts, where cooperative procurement now commands 35-45% of hybrid seed volume.
Sri Lanka Seed Market Segmentation
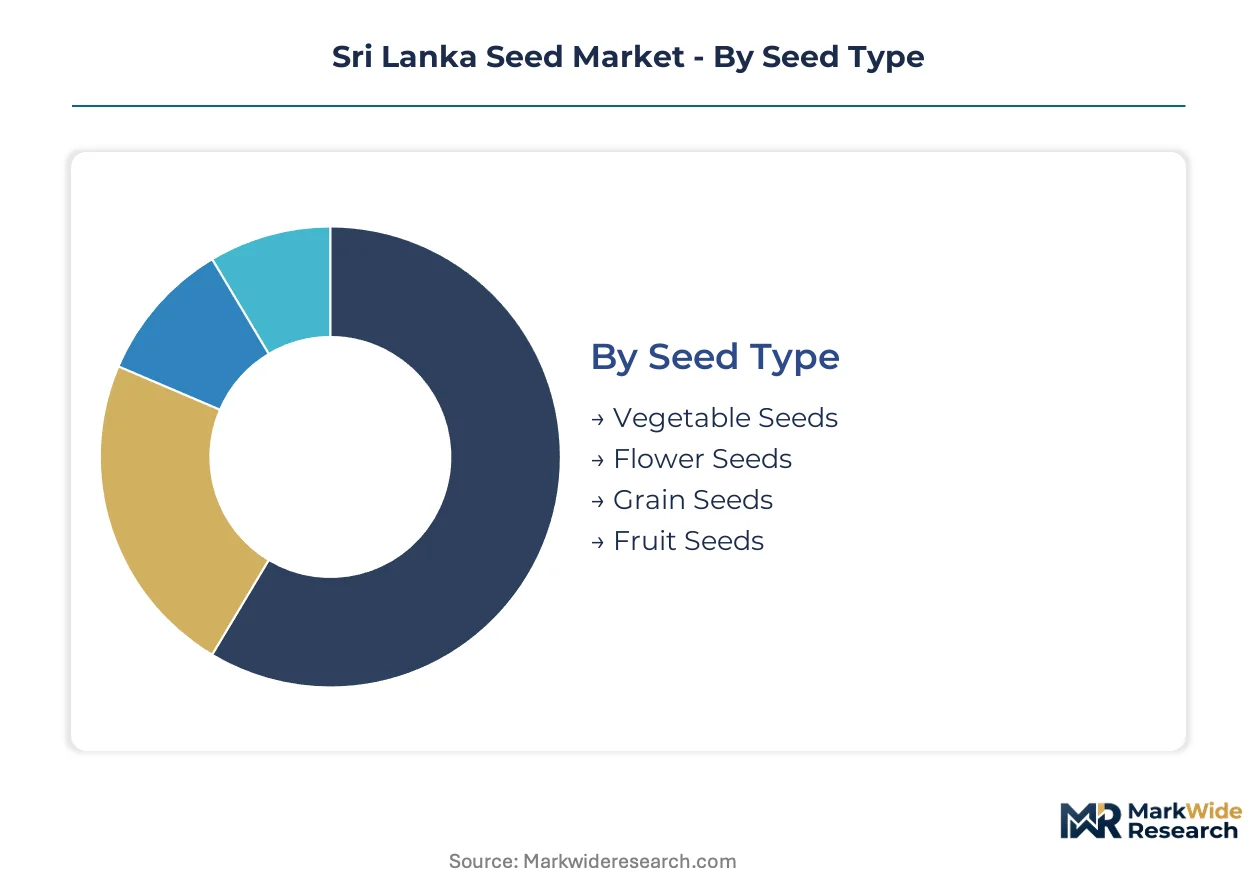
Sri Lanka's seed market fragmentation reflects divergent farmer economics across irrigated and rainfed zones. Segment boundaries sharpen where certification requirements intersect with cultivation intensity and buyer procurement consolidation.
Seed Type:
Volume leadership sits with staple crop propagation materials, while premium margins concentrate in short-cycle horticultural varieties requiring repeated annual purchase.
- Vegetable Seeds:Hybrid and open-pollinated propagules with specified germination rates above 85% and moisture content below 10%. Demand concentrates in North Central Province irrigated belts around Anuradhapura and Polonnaruwa, where smallholder farmers intensify rotations and generate repeat purchase cycles for proprietary trait stacks.
- Grain Seeds:Certified paddy and maize varieties with varietal purity thresholds enforced under the Seed Act. Dominates Dry Zone plantings through farm-saved retention of open-pollinated varieties, compressing commercial addressable market despite national food security prioritization.
- Flower Seeds:Ornamental and cut-flower varieties for export-oriented greenhouse operations and domestic landscaping. Compact demand base concentrated in Nuwara Eliya and Colombo district peri-urban zones.
- Fruit Seeds:Propagation materials for perennial orchard establishment including mango, papaya, and banana tissue culture alternatives. Long replacement cycles limit recurring revenue potential.
Today's leader: Grain Seeds. Tomorrow's challenger: Vegetable Seeds.
End Use:
Commercial cultivation drives certified seed uptake, while subsistence and amenity applications sustain open-pollinated and informal distribution channels.
- Agricultural:Commercial field and vegetable crop production requiring certified germplasm for yield consistency and pest resistance. Dominates procurement volume through cooperative aggregators in North Central and Eastern provinces.
- Horticultural:Intensive greenhouse and nursery operations demanding high-vigor hybrid varieties with uniform maturity windows. Concentrated in Colombo, Gampaha, and Kandy district peri-urban supply corridors serving domestic and export markets.
- Landscaping:Municipal, commercial property, and roadside beautification projects. Seasonal demand tied to government procurement calendars and monsoon planting windows.
- Domestic:Home garden and subsistence cultivation relying on retained grain, informal exchange, and uncertified local varieties. Limits commercial penetration in marginal rainfall zones with weak cooperative infrastructure.
Commercial agriculture anchors current procurement. Horticultural intensification offers the steepest expansion trajectory.
Distribution Channel:
Channel structure is bifurcating between cooperative-led volume aggregation and digital-enabled direct farmer relationships.
- Agricultural Cooperatives:Consolidated procurement pools negotiating volume-based supply contracts with certified processors. Command 35-45% of hybrid vegetable seed volume in Anuradhapura District through WhatsApp-linked pre-ordering and embedded agronomy support.
- Direct Sales:Processor-to-farmer relationships bypassing intermediary margins, typically for large-scale commercial operators and estate sector buyers.
- Retail Stores:Traditional village-level agro-dealer networks serving cash-and-carry farmers with limited cooperative membership. Losing share to mobile-enabled cooperative channels among younger smallholders.
- Online Platforms:Emerging digital marketplaces with batch-specific germination certificates and predictive inventory placement ahead of planting windows. Still sub-scale outside Colombo metropolitan delivery zones.
Cooperative consolidation defines present procurement gravity. Digital direct channels are gaining share fastest among irrigated zone vegetable growers.
Product Line:
Genetic architecture determines pricing power, with proprietary hybrids commanding loyalty premiums against commoditized open-pollinated alternatives.
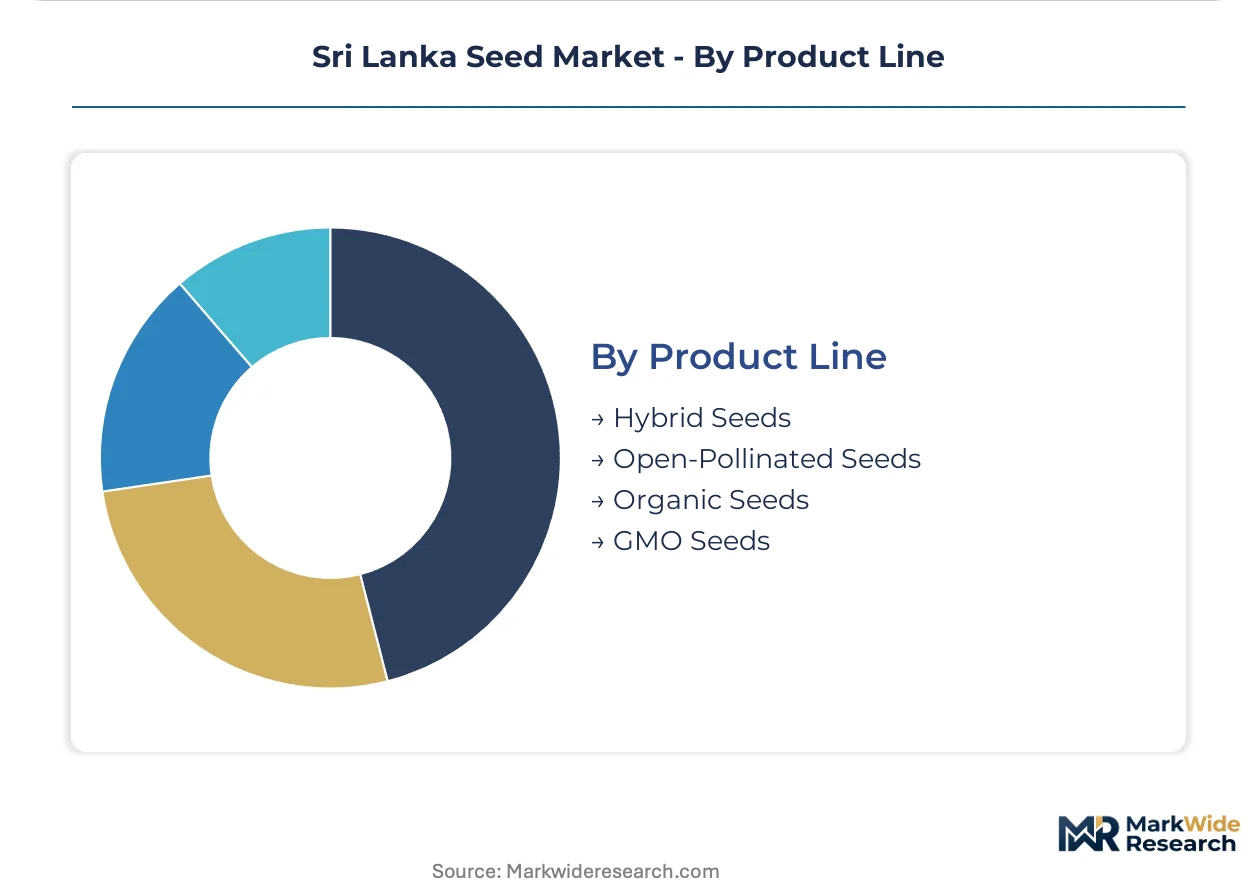
- Hybrid Seeds:First-generation crosses with trait stacks for yield, disease resistance, and uniformity. Capture premium pricing through farmer loyalty and repeated annual purchase requirements; proprietary germplasm limits farm-saving viability.
- Open-Pollinated Seeds:Genetically stable varieties permitting farmer retention and replanting. Retain volume leadership among cost-sensitive paddy growers in Dry Zone districts; 40-60% of plantings bypass commercial purchase entirely.
- Organic Seeds:Certified chemical-free propagation materials aligned with export market requirements and domestic premium niche. Limited domestic breeding infrastructure constrains supply scale.
- GMO Seeds:Genetically modified varieties with stacked input traits. Effectively absent from commercial distribution due to Department of Agriculture positive list restrictions and import licensing barriers.
Hybrid architecture dominates margin capture. Open-pollinated varieties retain planted area leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural extension officers and certified seed processors concentrate in the North Central Province, anchoring national distribution networks for hybrid vegetable and paddy varieties.
North Central Province
Anuradhapura and Polonnaruwa districts drive irrigated vegetable seed demand through intensified smallholder rotations. The Department of Agriculture's Seed Act enforcement mandates batch-specific germination certificates for cooperative procurement pools. Certified processors cluster around Anuradhapura's agricultural research stations to access varietal release protocols and farmer extension networks.
Western Province
Colombo and Gampaha districts concentrate horticultural greenhouse operations demanding high-vigor hybrid varieties. The country's national agricultural regulator maintains import licensing facilities at Colombo port, streamlining germplasm entry for established processors. Peri-urban seed conditioning facilities in Ja-Ela and Seeduwa serve export-oriented cut-flower and vegetable nursery clusters.
Eastern Province
Ampara and Batticaloa districts exhibit sub-30% certified seed adoption in vegetable cropping, creating first-mover positioning opportunities. The Department of Agriculture's Eastern regional offices administer field inspection protocols for new variety registration. Local conditioning infrastructure remains underdeveloped, forcing reliance on Western Province processors for treated vegetable seed.
Central Province
Kandy and Kurunegala districts host medium-scale vegetable seed processors retrofitting coating automation lines. The Seed Act's labeling requirements drive laboratory certification demand among processors without in-house testing infrastructure. Nuwara Eliya's elevation supports flower seed propagation for domestic landscaping and export greenhouse supply chains.
Southern Province
Hambantota and Matara districts balance paddy cultivation with emerging vegetable intensification in irrigated belts. FAO-aligned phytosanitary standards govern post-harvest testing requirements at regional Department of Agriculture facilities. Galle district's peri-urban corridors connect to Colombo-based digital extension platforms for hybrid seed pre-ordering.
Sri Lanka Seed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Sri Lanka's seed procurement channels. The market structure tiers between multinational germplasm licensors with proprietary trait stacks and domestic processors with backward integration into farmer extension networks. Three archetypes dominate: hybrid technology leaders, integrated domestic processors, and regional distribution specialists. Capacity expansion in seed conditioning infrastructure and strategic partnerships with agricultural cooperatives represent the primary competitive moves.
Within the multinational technology tier, Syngenta Group Co. Ltd and Bayer AG exemplify hybrid vegetable and field crop germplasm dominance through proprietary breeding programs. CIC Holdings PLC occupies a position among integrated domestic processors with captive seed processing and cooperative network penetration. These three anchors illustrate the competitive tension between foreign trait-licensing power and local backward integration advantages.
| Leading Market Players |
|---|
| East-West Seed Group B.V |
| Syngenta Group Co. Ltd |
| CIC Holdings PLC |
| Corteva Agriscience |
| Bayer AG |
| Hayleys PLC |
| UPL (Advanta Seeds) |
| SunAgro Lanka |
| Troseed Pvt Ltd |
| Others |
Value Network & Pricing Analysis
Seed coating automation incorporating polymer-based moisture retention and micronutrient layering simultaneously compresses per-unit processing costs and concentrates supply power among processors with captive conditioning infrastructure in Sri Lanka's North Central Province.
Pricing Analysis
Bundled agronomy advisory services now separate from bare seed transactions across cooperative procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects germination certification grade and embedded extension support. Pricing pressure stems from cooperative volume aggregation squeezing processor margins. Cost-sensitive paddy growers in Dry Zone districts exhibit highest price sensitivity, while horticultural greenhouse operators in Colombo district show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Netherlands and Thailand for hybrid vegetable germplasm imports. The supply chain draws from Indian paddy breeding programs, Chinese coating polymer inputs, and domestic conditioning facilities. Tariff exposure through Seed Act import licensing delays creates structural risk. Distribution runs through agricultural cooperative aggregators commanding 35-45% of hybrid vegetable volume in Anuradhapura District.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sri Lanka's seed market functions as a geographic-arbitrage play where Eastern Province processing infrastructure gaps create cost advantages against Western Province incumbents facing higher logistics and regulatory compliance burdens.
For Market Incumbents: Extend conditioning capacity into Ampara and Batticaloa districts to preempt first-mover entrants exploiting underpenetrated certified seed adoption. Defend against cooperative procurement consolidation by embedding digital agronomy platforms that capture farmer loyalty data. Invest in in-house laboratory certification infrastructure to offset third-party testing fees mandated by tightening Seed Act enforcement.
For New Entrants and Emerging Players: Enter via Eastern Province vegetable seed conditioning facilities serving sub-30% certified adoption districts. Target Batticaloa's irrigated belts with mobile-enabled cooperative aggregator partnerships replicating Anuradhapura's WhatsApp-linked pre-ordering models. Leverage Sri Lanka's agricultural modernization incentives for PLI-aligned domestic processing infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for medium-scale vegetable seed processors with retrofit coating automation lines because laboratory certification mandates are forcing margin compression on non-integrated competitors. The 5-10 year viability window favors targets with captive farmer extension networks and cooperative supply contracts. Watch for Seed Act tariff revisions as inflection indicator for import-dependent germplasm suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Conditioning | Captures premium pricing for treated seed under tightening Seed Act laboratory certification mandates. |
| Digital Extension Platform Development | Enables predictive inventory placement ahead of planting windows through farmer loyalty data capture. |
| Eastern Province Facility Establishment | Exploits sub-30% certified seed adoption in Ampara and Batticaloa districts before incumbent expansion. |
| Cooperative Procurement Partnership | Secures volume-based supply contracts with North Central Province aggregators displacing retail networks. |
| Climate-Resilient Variety Registration | Aligns with Department of Agriculture drought-tolerant paddy breeding programs driving replacement demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seed processing plant managers, agricultural cooperative procurement officers, Department of Agriculture certification inspectors, and farmer extension network coordinators with secondary validation against Seed Act regulatory filings, Department of Agriculture varietal release databases, FAO phytosanitary protocol documentation, and agricultural trade customs records. Bottom-up processor capacity assessments and top-down cooperative procurement volume estimates were triangulated for convergence.
Segment-weighting approaches modeled seed type, distribution channel, and genetic architecture dimensions across the analysis window. CAGRs derived from historical volume trajectories and projected cultivation intensity shifts. Forecast inputs incorporated irrigation infrastructure expansion timelines and climate-resilient breeding program release schedules from national agricultural research stations.
The model holds under stable Seed Act enforcement and cooperative procurement consolidation; deviation in import tariff revisions or fertilizer subsidy fluctuations would shift farmer working capital availability and seed purchase budgets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Buckwheat Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Organic Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Citrus Seeds Market
Seeds
Africa Vegetable Seed Market
Seeds
Lupin Market
Seeds
Garlic Chive Seeds Market
Seeds
China Forage Seed Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Global Grain Seed Market
Seeds
Caraway Seeds Market
Seeds
Apple Seed Oil Market
Seeds
Philippines Seed Market
Seeds
Ghana Seed Extract Market
Seeds
North America Forage Seed Market