
 Drought Tolerant Seeds Market | 2026-2036
Drought Tolerant Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Drought Tolerant Seeds Market Analytics
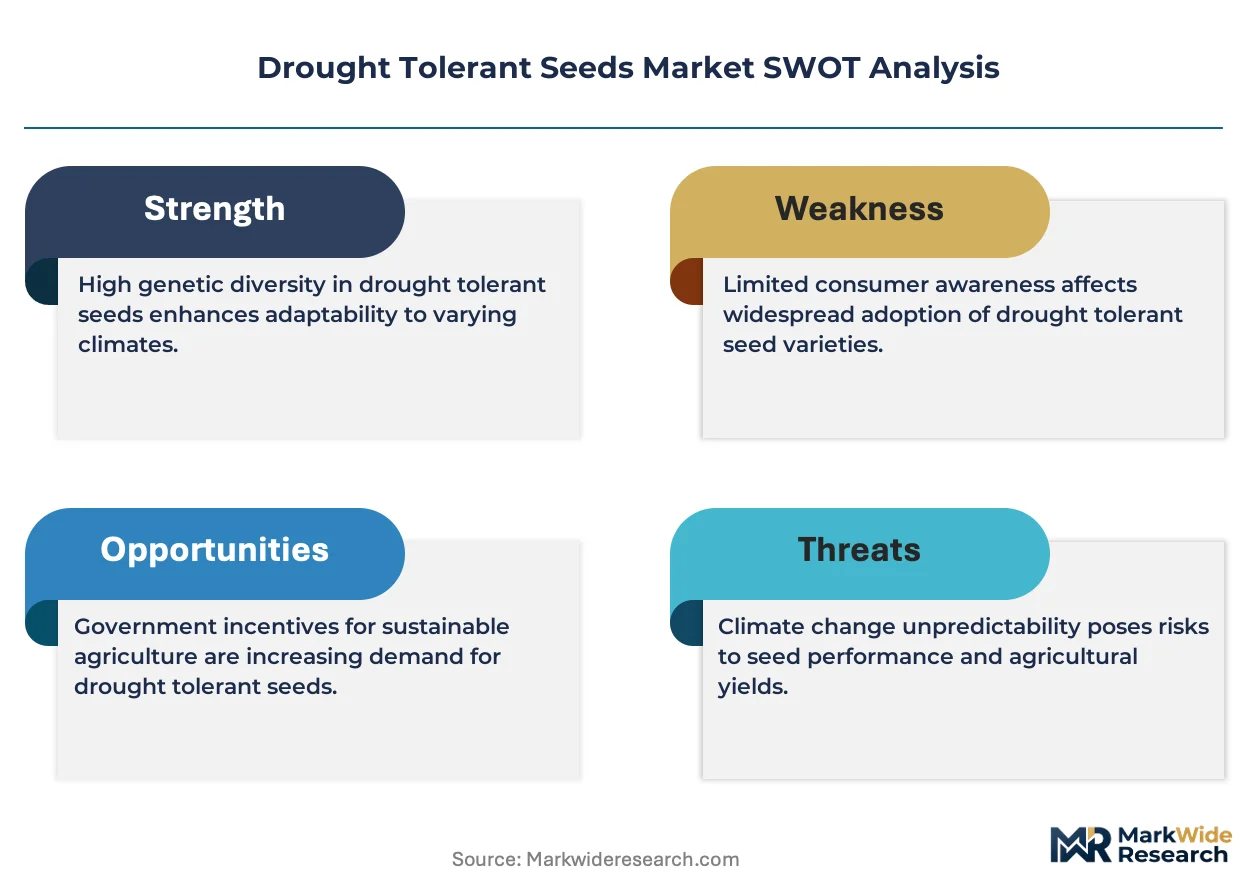
Multi-source germplasm licensing is broadening across the drought tolerant seeds sector as seed developers reduce reliance on captive trait pipelines. Corteva Agriscience leverages its proprietary water-optimization gene stacks to anchor North American corn and soybean positions. Bayer AG sustains global reach through integrated breeding platforms that span trait discovery to farmer-direct distribution. Syngenta competes via localized heat-stress screening networks that accelerate variety release in water-scarce growing belts.
Drought tolerant seeds comprise germplasm selected or engineered to maintain physiological function and yield stability under soil-moisture deficit conditions, typically incorporating traits such as deeper root architecture, cuticular wax enhancement, or osmotic adjustment mechanisms. Their primary purpose is to reduce crop failure risk and stabilize farmer incomes in rainfall-dependent agricultural systems. Hybrid seeds occupy the dominant value position due to farmer willingness to pay for yield consistency under variable precipitation, while genetically modified varieties capture the fastest expansion trajectory as stacked-trait approvals widen. Open-pollinated varieties retain significant share in subsistence and smallholder segments where seed-saving practices limit hybrid turnover.
The USDA regulates drought-tolerant biotech traits through coordinated EPA and FDA oversight, ensuring environmental and food-safety compliance before commercial release. India's BIS seed certification standards and the EU's REACH-derived trait assessment protocols shape market access timelines and product registration costs across their respective territories. Seed developers must monitor evolving gene-editing classification debates, as regulatory determinations on CRISPR-derived drought traits will reshape competitive investment thresholds and commercialization speed.
Market Dynamics
Climate-induced water stress across major cereal belts is forcing seed developers to accelerate multi-trait stacking programs, compressing traditional variety release cycles and reshaping R&D capital allocation priorities.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory sustainability targets for member states are expanding certified drought-tolerant seed procurement quotas among large-scale wheat and barley producers in France and Germany.
- CRISPR-Cas9 gene editing:Regulatory clarity on non-transgenic classification in select jurisdictions is shortening development timelines for water-use-efficiency traits in maize and sorghum germplasm.
- Brazil's Cerrado expansion:Soybean growers in Mato Grosso and Goiás are converting marginal pasture to row crop production, creating concentrated demand for hybrids validated under erratic rainfall patterns.
Market Restraints
- Parent seed supply concentration:Hybrid production depends on limited tropical winter nursery capacity in Argentina and Chile, creating geographic bottlenecks during counter-season multiplication cycles.
- Trait royalty stacking:Licensed water-optimization genes from multiple technology providers inflate per-unit seed costs beyond smallholder affordability thresholds in rain-fed African markets.
- EU REACH-derived trait assessment:Extended molecular characterization requirements for novel drought mechanisms delay product registration by 18-36 months versus conventional hybrid approvals.
Strategic Opportunities
- India's PLI scheme for agriculture:Production-linked incentives for domestic seed multiplication infrastructure are attracting foreign germplasm licensing partnerships targeting kharif season sorghum and pearl millet.
- Digital phenotyping convergence:Integration of satellite-derived vegetation indices with high-throughput field sensors is enabling predictive variety placement recommendations for extension services.
- Direct-to-farmer e-commerce channels:Mobile-enabled seed ordering platforms are bypassing traditional distributor networks in rural Kenya and Ethiopia, expanding addressable markets for open-pollinated drought-tolerant varieties.
Industry Challenges
- Quantitative genetics expertise scarcity:Breeding programs lack sufficient computational biologists capable of integrating genomic selection models with multi-environment yield trial data.
- Seed certification timeline compression:National variety release committees in water-stressed jurisdictions face backlogs exceeding 24 months, delaying farmer access to improved germplasm during critical climate adaptation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drought Tolerant Seeds Market |
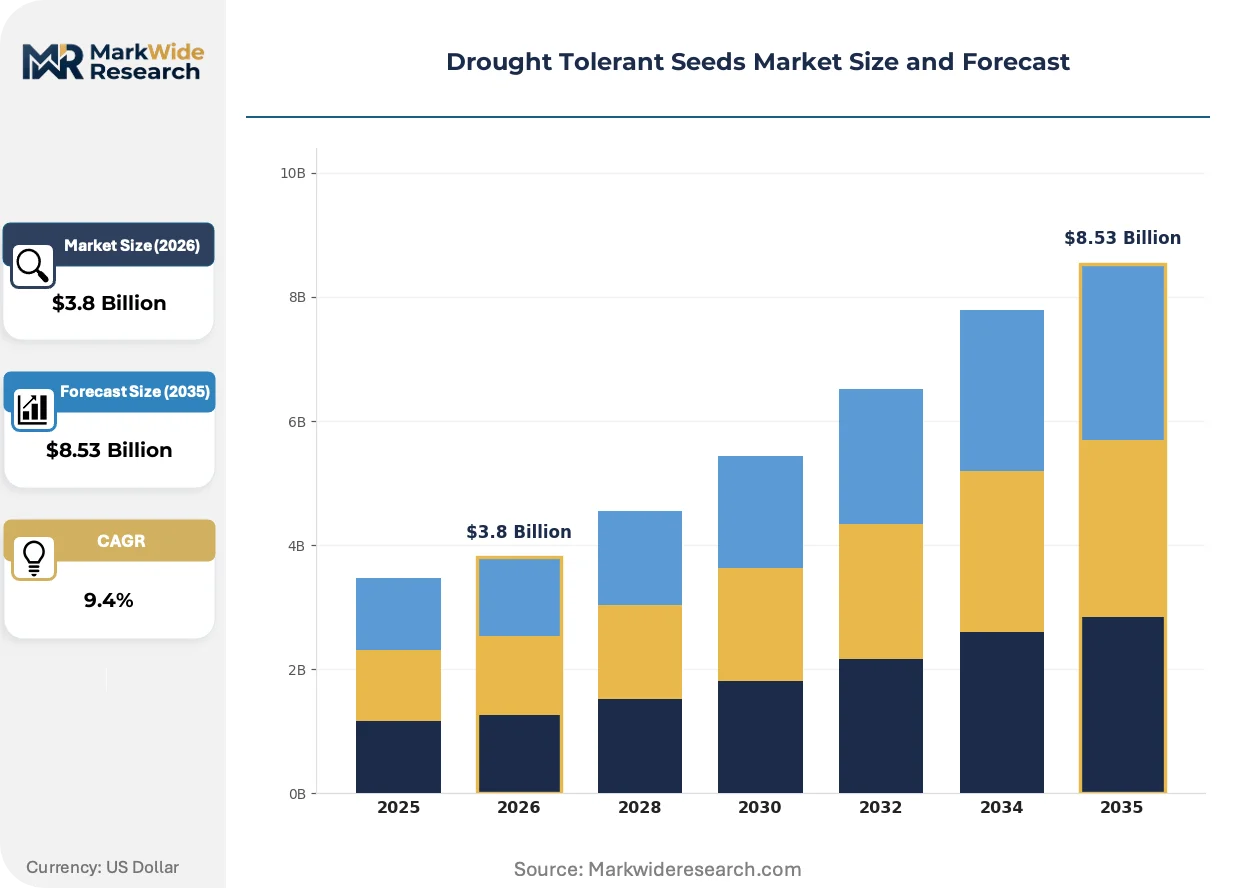
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetically Modified, Hybrid, Open-Pollinated, Traditional Varieties End Use Industry: Agriculture, Horticulture, Turf Management, Specialty Crops Distribution Channel: Retail, E-commerce, Direct Sales, Wholesalers Seed Treatment: Coated, Non-Coated, Treated, Untreated |
| Companies Covered | Corteva Agriscience, Bayer AG, Syngenta, BASF SE, KWS SAAT SE & Co. KGaA, UPL, Limagrain, Stine Seed Farm Inc., Mahyco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drought Tolerant Seeds Market Evolving Landscape
Open-source germplasm sharing initiatives and public-private trait licensing pools are disrupting proprietary R&D silos, accelerating collaborative breeding networks across semi-arid agricultural zones.
Speed breeding protocols combining controlled-environment rapid generation advancement with marker-assisted selection are decentralizing variety development authority from centralized corporate stations toward regional research consortia. National agricultural institutes in Mexico and Nigeria are adopting these compressed-cycle methods for drought-tolerant maize. The technology is decentralizing germplasm improvement ownership, enabling localized adaptation without full technology transfer dependencies.
India's BIS seed certification standards are tightening genetic purity thresholds for drought-tolerant hybrids, mandating enhanced field inspection protocols and molecular marker verification. This regulatory tightening elevates compliance costs for smaller seed enterprises while creating competitive moats for firms with captive quality control infrastructure. Sorghum and pearl millet segments face the steepest adaptation requirements given existing varietal diversity.
Farmer purchasing for drought-tolerant hybrids is migrating toward bundled input packages combining seed with crop insurance and weather-indexed credit instruments. Agri-fintech platforms in Kenya and Nigeria are displacing traditional cash-and-carry transactions with subscription-based risk management offerings. This behavioral shift concentrates buyer power among integrated service providers and compresses standalone seed distributor margins in East African markets.
Drought Tolerant Seeds Market Segmentation
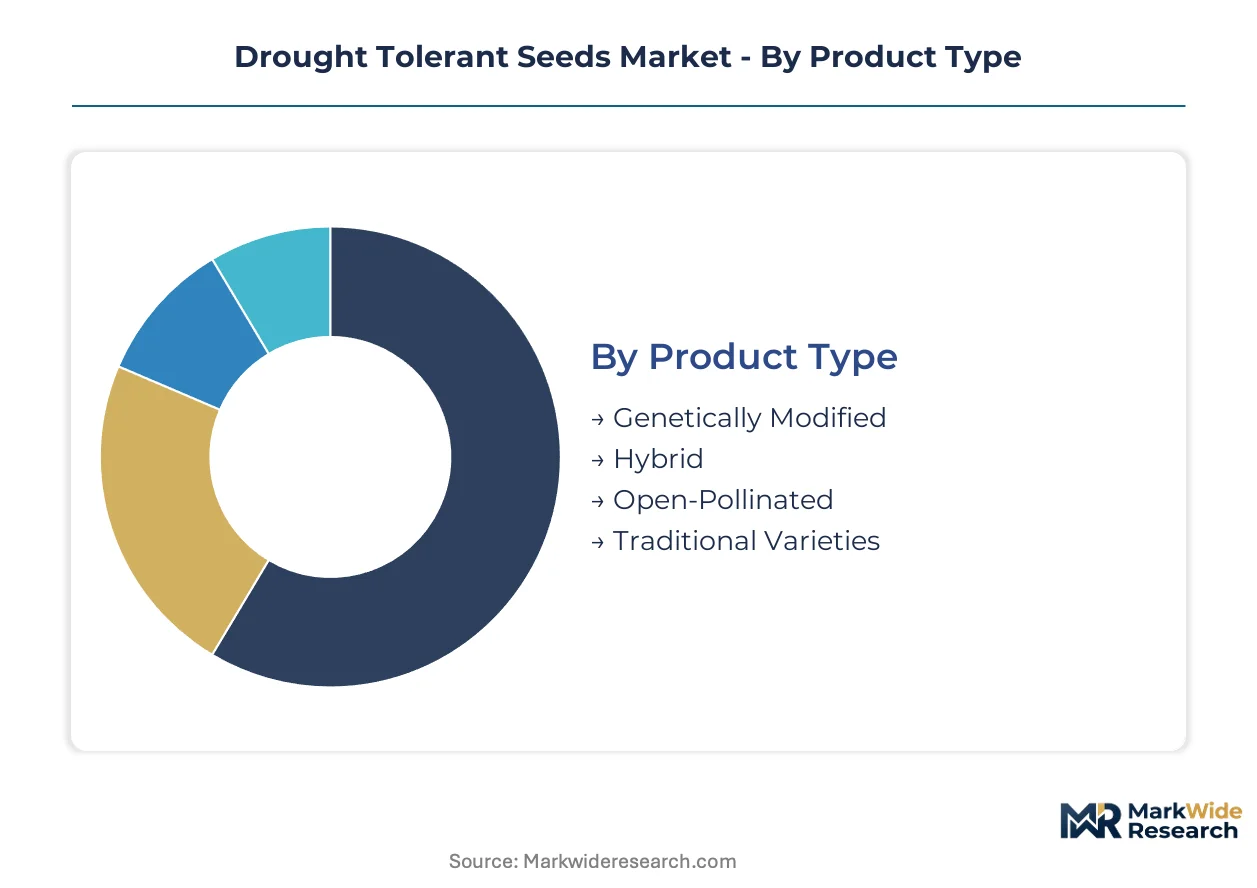
Drought tolerant seeds fragment across product architectures, end-use applications, and distribution pathways that each carry distinct margin profiles and farmer loyalty patterns. Understanding these fault lines reveals where breeding investments concentrate and which channels capture premium pricing.
Product Type:
Volume concentration sits with hybrid platforms, while genetically modified varieties command the steepest per-unit premiums and fastest regulatory-driven expansion curves.
- Genetically Modified:Engineered germplasm incorporating transgenic water-optimization traits such as drought-responsive promoter systems and enhanced abscisic acid signaling. Regulatory approvals in Brazil and the United States are accelerating farmer adoption in soybean and maize belts where irrigation infrastructure is sparse.
- Hybrid:Cross-pollinated varieties selected for heterosis-driven yield stability under moisture stress, dominating commercial row crop acreage. Corteva and Bayer anchor their revenue positions here through proprietary inbred line portfolios that farmers repurchase annually.
- Open-Pollinated:Self-fertile varieties permitting on-farm seed saving, retaining substantial share among subsistence sorghum and millet growers in India's Deccan Plateau and Ethiopia's highlands where input financing is constrained.
- Traditional Varieties:Landrace germplasm maintained through farmer selection over generations, persisting in marginal agro-ecological niches where modern breeding networks have limited penetration.
Today's leader: Hybrid. Tomorrow's challenger: Genetically Modified.
End Use Industry:
Application-driven segmentation separates commodity scale from specialized premium capture, with agriculture consuming the overwhelming majority of certified seed volumes.
- Agriculture:Field crop production of cereals, oilseeds, and pulses under rain-fed or deficit-irrigation regimes. India's kharif season sorghum and Brazil's Cerrado soybean operations represent the largest concentrated demand pools for certified drought-tolerant germplasm.
- Horticulture:Vegetable and fruit seed systems requiring precise moisture-stress tolerance for transplant establishment and fruit set. Tomato and pepper breeders in Spain's Almería and Mexico's Sinaloa valley are prioritizing rootstock vigor under saline-drought conditions.
- Turf Management:Bermudagrass and fescue varieties for golf course and municipal landscape maintenance in water-restricted jurisdictions such as California and Australia's Murray-Darling basin.
- Specialty Crops:Niche applications including drought-adapted forage species for livestock operations and cover crop mixes for regenerative agriculture transitions in France's Grand Est region.
Agriculture commands the volume base. Horticulture offers the margin expansion path.
Distribution Channel:
Channel selection reflects farmer scale and credit access, with direct sales capturing the largest accounts and e-commerce penetrating previously unreachable smallholders.
- Retail:Agro-dealer networks providing last-mile seed access with embedded technical advice. Kenya's certified stockist system and India's Krishi Vigyan Kendra linkages dominate smallholder procurement for open-pollinated millet and sorghum.
- E-commerce:Mobile-enabled platforms bypassing traditional distributor markups, expanding fastest in Ethiopia's Oromia region and Nigeria's northern states where logistics infrastructure is improving.
- Direct Sales:Breeder-to-grower contracts for large-scale commercial farms requiring volume guarantees and trait customization, prevalent in Mato Grosso's soybean operations and Australia's wheatbelt cooperatives.
- Wholesalers:Regional aggregators managing inventory risk and seasonal financing for downstream retailers, concentrated in India's Maharashtra and Telangana seed production hubs.
Retail anchors current penetration. E-commerce is climbing the fastest.
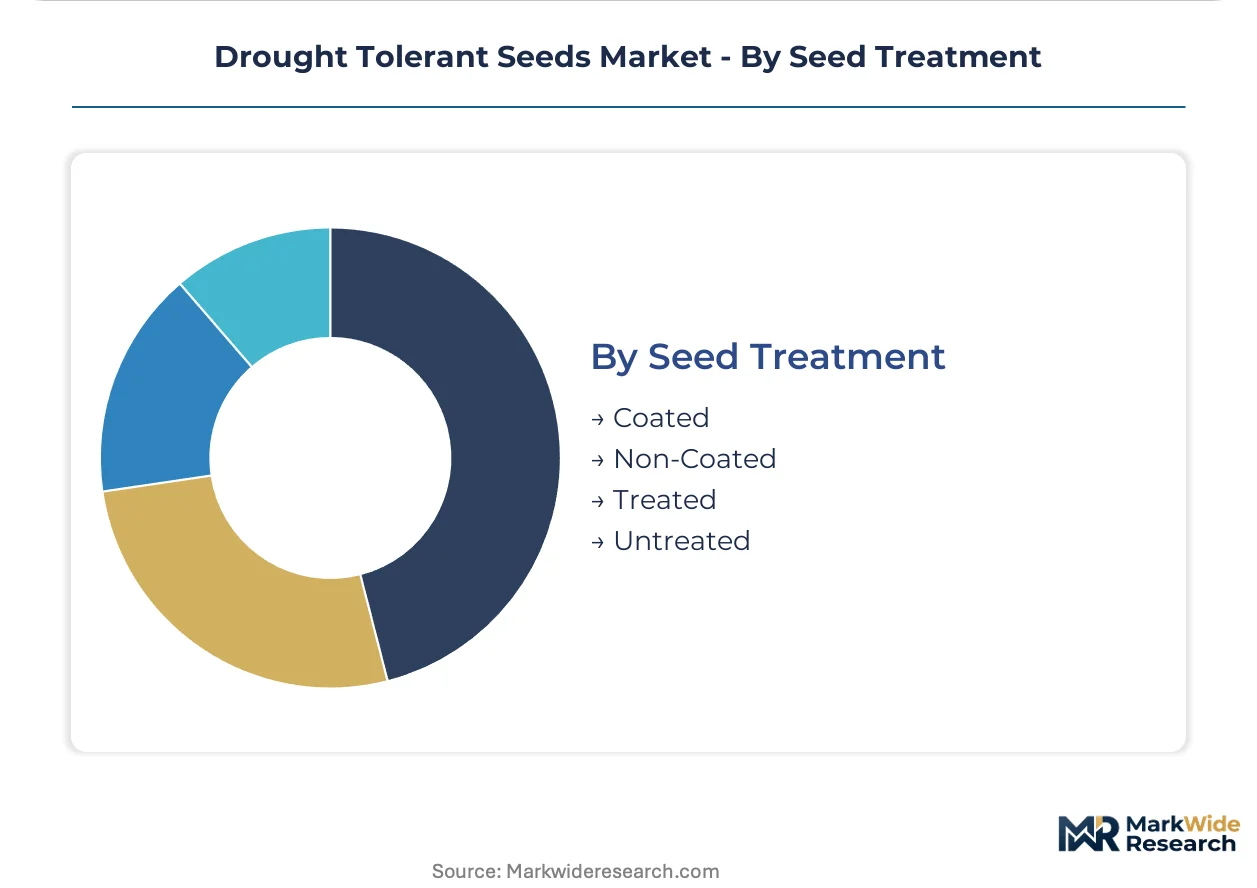
Seed Treatment:
Treatment status correlates with farmer risk tolerance and disease pressure, with coated seeds capturing premium positioning in high-value crop segments.
- Coated:Polymer-encapsulated seed with integrated fungicides, insecticides, and micronutrients enhancing early vigor under suboptimal moisture. Bayer's Poncho/Votivo platforms dominate corn and soybean deployment in the US Corn Belt.
- Treated:Chemically protected seed without full polymer film coating, standard for wheat and barley in France's Beauce region where fusarium pressure accompanies drought stress.
- Non-Coated:Bare seed for cost-sensitive applications and organic certification compliance, retaining share in India's rain-fed cotton belt where farmer-saved seed persists.
- Untreated:Unprotected germplasm for research trials and specific organic protocols, minimal commercial volume but required for regulatory reference standards.
Coated leads on value. Treated holds the volume position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado region anchors global drought-tolerant seed deployment, with Mato Grosso and Goiás soybean producers converting marginal pasture under erratic rainfall regimes. Demand clusters across semi-arid agricultural belts where irrigation infrastructure remains sparse and climate variability intensifies.
United States
Corn Belt farmers in Iowa and Illinois prioritize water-optimization hybrids as aquifer depletion restricts supplemental irrigation. The USDA coordinates EPA and FDA oversight for biotech trait approvals, ensuring environmental compliance before commercial release. Corteva's proprietary gene stacks dominate North American positions through farmer-direct distribution networks.
India
Deccan Plateau sorghum and pearl millet growers drive open-pollinated variety demand amid constrained input financing. The BIS seed certification standards tighten genetic purity thresholds, mandating enhanced field inspection protocols. Maharashtra and Telangana seed production hubs concentrate multiplication infrastructure for kharif season deployment.
Brazil
Cerrado soybean and maize producers face recurring water stress, expanding hybrid purchases validated under variable precipitation. ANVISA regulates biotech trait assessments alongside national variety release committees. Mato Grosso's conversion of marginal pasture creates concentrated demand pools for drought-validated germplasm.
Germany
Beauce region wheat and barley producers expand certified seed procurement under EU Green Deal Farm to Fork sustainability mandates. The EFSA and ECHA shape REACH-derived trait assessment protocols, extending molecular characterization timelines. KWS SAAT anchors European breeding positions through integrated inbred line portfolios.
China
North China Plain maize operations adopt drought-tolerant hybrids as groundwater withdrawal restrictions tighten. The NMPA and MEE coordinate gene-editing classification debates that reshape CRISPR-derived trait investment thresholds. Shandong Peninsula seed enterprises accelerate multi-trait stacking programs for water-scarce growing belts.
Drought Tolerant Seeds Market Competitive Landscape
Global majors compete with regional champions across germplasm licensing networks, creating a tiered structure where proprietary trait pipelines anchor premium positions. The vendor base concentrates among integrated breeding platforms and specialized regional developers. Three archetypes dominate: multinational agrochemical conglomerates with captive seed divisions, independent family-owned breeding enterprises, and public-sector research institutes with commercialization partnerships. Competitive moves center on multi-source germplasm licensing to reduce technology dependency and speed breeding protocol adoption to compress variety release cycles.
Within the integrated agrochemical tier, Corteva Agriscience, Bayer AG, and Syngenta exemplify divergent strategic positioning. Corteva leverages its water-optimization gene stacks to anchor North American corn and soybean positions. Bayer sustains global reach through breeding platforms spanning trait discovery to farmer-direct distribution. Syngenta competes via localized heat-stress screening networks that accelerate variety release in water-scarce growing belts.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer AG |
| Syngenta |
| BASF SE |
| KWS SAAT SE & Co. KGaA |
| UPL |
| Limagrain |
| Stine Seed Farm Inc. |
| Mahyco |
| Others |
Value Network & Pricing Analysis
Quantitative genetics expertise scarcity in North American breeding programs widens pricing-tier spreads between premium gene-stacked hybrids and economy open-pollinated varieties, as labor-cost differentials in computational biology talent pools concentrate value capture among integrated technology platforms.
Pricing Analysis
Input-cost pass-through from parent seed multiplication in Argentina and Chile's winter nursery systems shapes three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on trait royalty stacking intensity and genetic purity certification grade under BIS or OECD schemes. Pricing pressure stems from trait licensing fee accumulation in stacked-trait varieties, compressing margins in the mid-tier hybrid segment. Smallholder sorghum and millet growers in India's Deccan Plateau exhibit highest price sensitivity, while large-scale Cerrado soybean operators absorb premium positioning for validated water-optimization gene stacks.
Supply Chain Analysis
Reverse-logistics flows for certified seed quality complaints and replant guarantees create administrative friction in distributor networks, particularly for hybrid corn and soybean programs with high farmer performance expectations. Supply concentration centers on Argentina, Chile, and India for counter-season parent seed multiplication and tropical germplasm adaptation. Raw material dependencies include proprietary inbred line inventories, CRISPR reagent supplies, and polymer seed-coating chemistries. Single-source vulnerability in tropical winter nursery capacity during El Niño disruptions threatens multiplication cycle completion. Distribution runs through breeder-direct contracts for large-scale commercial farms and agro-dealer networks for smallholder open-pollinated variety access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drought tolerant seeds market functions as a stable compounder, with climate-driven varietal turnover in semi-arid cereal belts ensuring persistent replacement demand regardless of commodity price cycles.
For Market Incumbents: Cement market position through captive water-optimization gene stack development and backward integration into tropical winter nursery capacity in Argentina and Chile. The threat of CRISPR-derived non-transgenic varieties from emerging gene-editing specialists demands accelerated multi-trait stacking programs. Certification investment under tightening BIS genetic purity protocols creates defensive moats against smaller regional competitors lacking quality control infrastructure.
For New Entrants and Emerging Players: Smallholder pearl millet and sorghum growers in Ethiopia's highlands and Nigeria's northern states represent the most penetrable buyer archetype currently underserved by integrated multinational platforms. White-space targets include mobile-enabled e-commerce seed distribution bypassing traditional agro-dealer markups, and open-pollinated variety development for seed-saving farmer segments excluded from hybrid economics. Go-to-market execution should anchor on farmer-direct digital channels with embedded weather-indexed credit instruments.
For Investors and Strategic Acquirers: Integrated agrochemical conglomerates with captive seed divisions are the most active acquirer in this space, seeking germplasm libraries and regional breeding station networks. Long-term viability over a multi-year horizon rests on climate adaptation imperatives intensifying varietal replacement cycles. Acquisition targets should display proprietary trait pipelines or speed breeding protocol capabilities. Monitor regulatory determinations on CRISPR-derived drought trait classification as the critical inflection signal for gene-editing investment thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-trait Gene Stacking Program | Accelerates water-optimization trait deployment in Brazilian Cerrado soybean germplasm. |
| Speed Breeding Protocol Adoption | Compresses variety release cycles for drought-tolerant maize in Nigerian national institutes. |
| Mobile E-commerce Platform Launch | Bypasses distributor markups for smallholder millet growers in Ethiopia's Oromia region. |
| Tropical Nursery Capacity Expansion | Secures counter-season parent seed multiplication in Argentina against El Niño disruptions. |
| CRISPR Regulatory Clarity Investment | Positions for non-transgenic classification advantages in US EPA and FDA oversight pathways. |
Research Methodology
Bottom-up farmer adoption modeling reconciled against top-down germplasm licensing tracking forms the analytical core of this study. Primary interviews with seed development executives, regulatory affairs leads at national variety release committees, breeding station directors, and agro-dealer network managers combined with secondary validation from USDA trait approval databases, BIS seed certification records, ANVISA biotech assessments, and OECD varietal registration filings. Triangulation across these sources ensures supply-side and demand-side consistency in volume and value estimates.
Historical trendline analysis of certified seed deployment rates across semi-arid growing belts established baseline growth patterns. The projection framework models segmentation across product architecture, end-use application, and distribution channel dimensions throughout the forecast period. CAGRs derive from elasticity-adjusted adoption curves responding to climate stress indices and regulatory approval timelines. Industry-specific inputs include drought severity frequency in target geographies and stacked-trait regulatory pathway durations.
Underlying measurement precision varies by segment; genetically modified and hybrid categories carry tighter precision than open-pollinated and traditional variety segments due to more transparent licensing and certification records. Forecasts incorporate assumptions on regulatory clarity for gene-edited traits and climate variability patterns that could shift materially. Practitioners should monitor CRISPR classification determinations in major jurisdictions and El Niño frequency indices for early signals of multiplication cycle disruption or accelerated farmer adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Sprouted Grains and Seeds Market
Seeds
India Vegetable Seed Market
Seeds
Cannabis Seeds Market
Seeds
Flax Seed Market
Seeds
Pumpkin Seeds Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Safflower Seeds Market
Seeds
Vegetable Seed Protein Market
Seeds
E. Angustifolium Market
Seeds
Bangladesh Seed Market
Seeds
Thailand Seed Market
Seeds
Africa Vegetable Seed Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Europe Quinoa Seed Market
Seeds
Citrus Seeds Market
Seeds
Global Forage Seeds Market