
 Asia-Pacific Vegetable Seed Market | 2026-2036
Asia-Pacific Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vegetable Seed Market Outlook
China's state-backed seed breeding institutes is repositioning domestic vegetable germplasm development toward self-sufficiency targets. Syngenta Group leverages its regional R&D stations in Singapore and China to sustain hybrid tomato and pepper pipelines. Takii & Co., Ltd. anchors its Asia-Pacific presence through specialized brassica and solanaceous breeding programs in Japan and Southeast Asia.
Asia-Pacific vegetable seeds comprise genetically stabilized propagules selected for agronomic performance, disease resistance, and regional adaptability, with hybrid varieties produced through controlled cross-pollination of inbred parental lines to exploit heterosis for yield and uniformity. These seeds serve commercial farming, greenhouse cultivation, and research applications where germplasm quality directly determines harvest consistency and supply chain reliability. Hybrid seeds occupy the dominant value position due to farmer willingness to pay for performance predictability, while organic vegetable seed demand is expanding fastest among export-oriented cooperatives seeking certification compliance. Open-pollinated varieties retain significant volume share in subsistence and smallholder segments where seed-saving practices reduce input costs.
China's Ministry of Agriculture and Rural Affairs enforces varietal approval and seed labeling standards that restrict market access for unregistered foreign germplasm, while Japan's Plant Variety Protection and Seed Act governs breeder rights and import quarantine protocols. India's Seeds Act and accompanying regulatory framework administered by the Central Seed Committee mandates certification and truth-in-labeling for interstate commerce. Stakeholders must monitor evolving national seed policies and phytosanitary barriers as each major Asia-Pacific economy hardens germplasm sovereignty objectives.
Market Dynamics
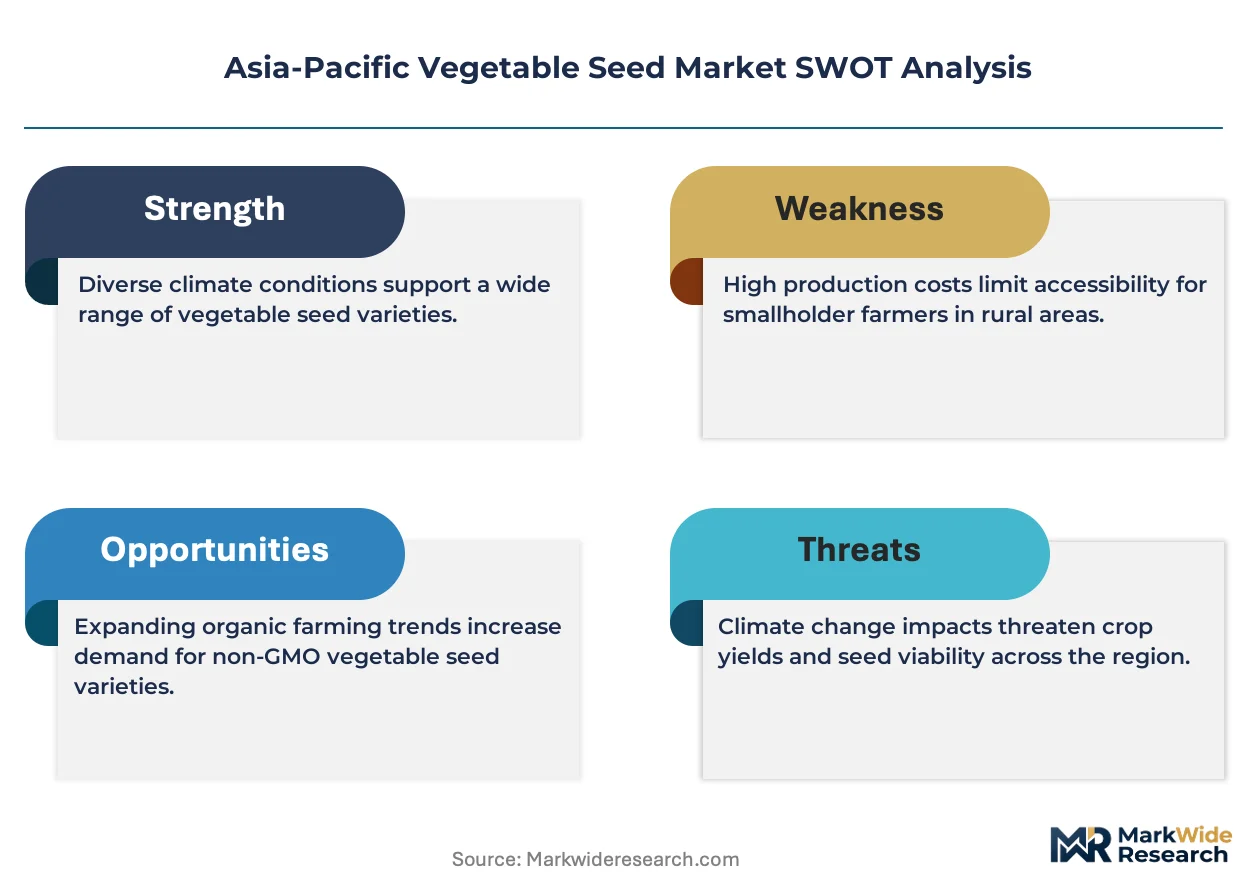
Protected agriculture expansion across India and Southeast Asia is pulling hybrid vegetable seed procurement into formal supply chains, while China's revised seed law hardens germplasm sovereignty barriers that foreign breeders must navigate.
Growth Catalysts
- Contract Farming Expansion:Processing and export-oriented vegetable operations in India's Indo-Gangetic Plain are consolidating acreage under formal seed procurement agreements with certified suppliers.
- Japan's Varietal Registration Reforms:Accelerated breeder rights recognition under the Plant Variety Protection and Seed Act is incentivizing domestic R&D investment in brassica and solanaceous lines.
- Greenhouse Infrastructure:Polyhouse and nethouse construction across Vietnam and Thailand is creating dedicated demand for heat-tolerant hybrid tomato and pepper germplasm.
Market Restraints
- Import Quarantine Protocols:Japan's phytosanitary inspection timelines for foreign germplasm create 18-24 month market access delays that freeze breeding pipeline schedules.
- Parental Line Concentration:Hybrid seed production depends on concentrated inbred line maintenance in China's Shandong and Hainan provinces, exposing supply to localized climate shocks.
- Subsistence Seed-Saving:Smallholder retention of open-pollinated varieties in Bangladesh and Myanmar limits addressable market for commercial hybrid offerings.
Strategic Opportunities
- Organic Certification Pathways:Export-oriented cooperatives in India's Maharashtra and Karnataka are sourcing untreated vegetable seed to meet EU organic equivalence standards.
- Gene Editing Convergence:CRISPR-based disease resistance traits are integrating with conventional hybrid breeding to compress varietal development timelines for bacterial wilt resistance.
- Direct-to-Grower Platforms:Digital seed marketplaces are bypassing traditional distributor layers to reach contract vegetable farmers in Vietnam's Central Highlands.
Industry Challenges
- Trait Stewardship Complexity:Managing intellectual property restrictions on proprietary inbred lines across multiple national breeder rights regimes requires specialized legal capacity.
- Climate Adaptation Lag:Existing hybrid varieties face performance degradation as heat stress and irregular monsoon patterns intensify across South Asian vegetable belts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vegetable Seed Market |
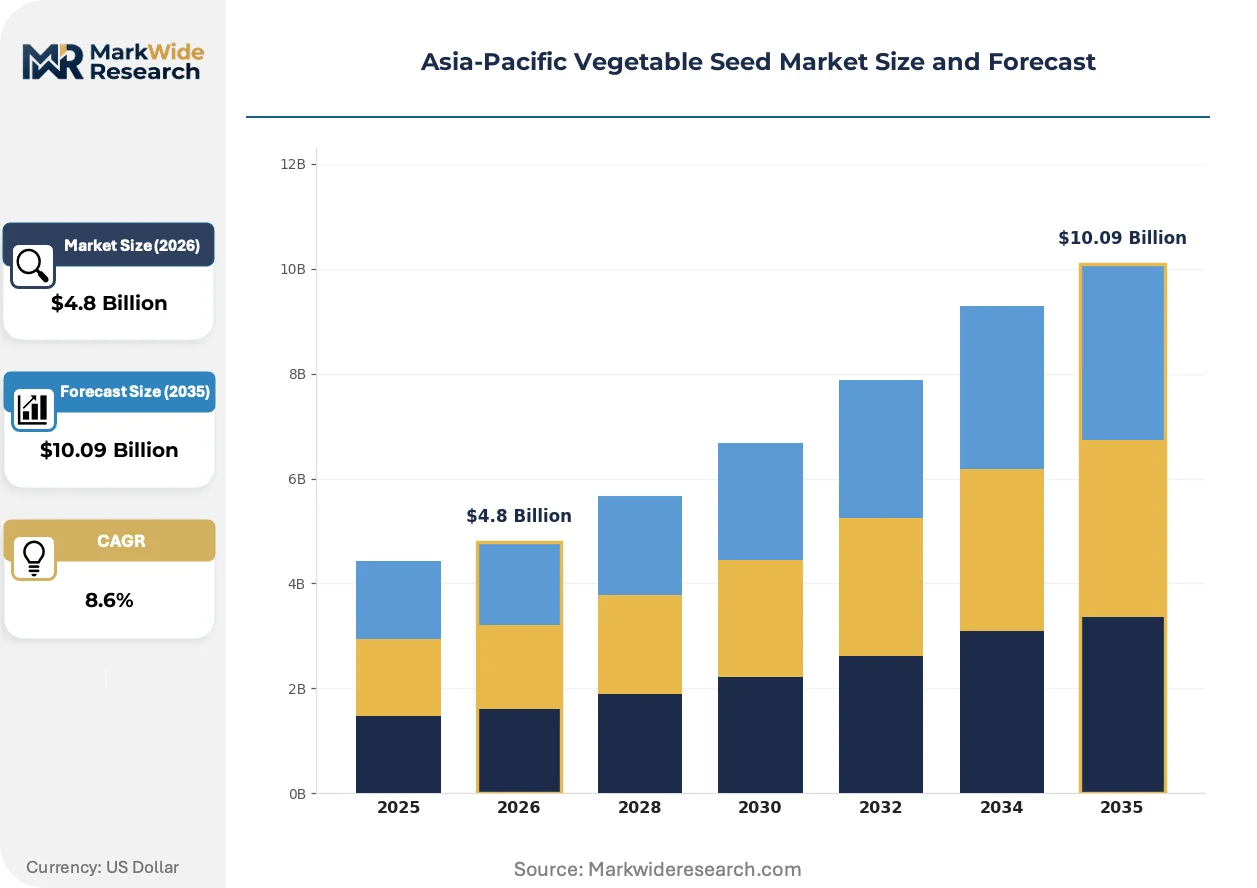
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Open-Pollinated, Organic, GMO End User: Farmers, Agricultural Cooperatives, Retailers, Seed Distributors Application: Commercial Farming, Home Gardening, Greenhouse Cultivation, Research Distribution Channel: Direct Sales, E-commerce, Wholesalers, Retail Stores |
| Companies Covered | Groupe Limagrain, BASF SE, Syngenta Group, Rijk Zwaan Zaadteelt en Zaadhandel BV, Takii & Co., Ltd., Bayer AG, East-West Seed, Gansu Dunhuang Seed Co., Ltd., Sakata Seed Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vegetable Seed Market Strategic Shifts
Digital phenotyping and molecular marker-assisted selection are compressing breeding cycles while regulatory tightening on germplasm movement forces localization of R&D infrastructure.
Marker-assisted backcrossing is integrating genomic selection with conventional field trialing to halve the time required for pyramiding multiple disease resistance traits in solanaceous crops. Leading breeding stations in Singapore and China are deploying this stack to maintain hybrid pipeline velocity. The technology is integrating pedigree management systems with climate-specific performance databases to enable predictive variety placement.
China's Ministry of Agriculture and Rural Affairs is enforcing revised varietal approval standards that mandate multi-location DUS testing for all imported germplasm prior to commercial release. This regulatory friction is forcing foreign seed houses to establish captive breeding stations within mainland China. Domestic vegetable seed producers are responding by accelerating inbred line development to substitute for restricted foreign parental material.
Export-oriented vegetable cooperatives are consolidating seed procurement under single-source certification-compliant suppliers to streamline audit documentation for EU and Japanese import protocols. This buyer concentration is displacing fragmented multi-vendor purchasing that previously dominated smallholder aggregation models. The shift is most visible in India's contract tomato and gherkin sectors supplying processing facilities in Maharashtra and Karnataka.
Asia-Pacific Vegetable Seed Market Segmentation
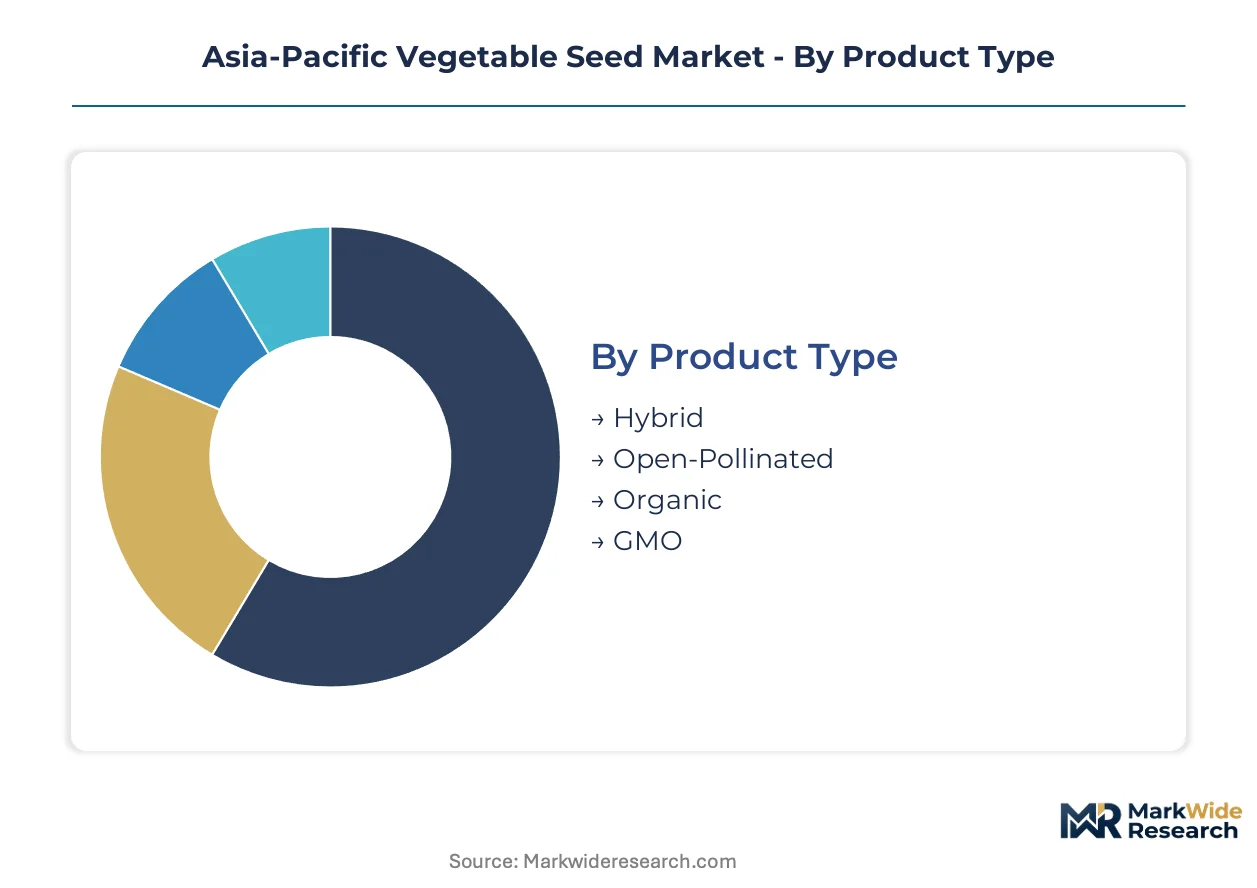
Vegetable seed procurement patterns across the Asia-Pacific diverge sharply by buyer sophistication and cultivation scale. Segment boundaries determine pricing tolerance, certification requirements, and channel access for germplasm suppliers.
Product Type:
Farmer willingness to pay for performance predictability and replanting restrictions drives product type selection across commercial and subsistence operations.
- Hybrid:Controlled cross-pollination of inbred parental lines exploits heterosis for yield uniformity and disease resistance. Procurement concentrates in India's contract tomato and gherkin sectors supplying Maharashtra processing facilities, where harvest consistency commands premium pricing.
- Open-Pollinated:Genetically stabilized varieties permit seed-saving across generations without trait degradation. Demand clusters in Bangladesh and Myanmar smallholder systems where input cost reduction overrides yield maximization objectives.
- Organic:Untreated seed stocks meeting EU organic equivalence standards for export-oriented cooperatives in Karnataka and Maharashtra.
- GMO:Transgenic trait integration for specific pest resistance profiles, subject to China's NMPA varietal approval and Japan's PMDA quarantine protocols.
Volume sits with Hybrid; growth tilts toward Organic.
End User:
Procurement scale and certification sophistication separate addressable customer tiers across the value chain.
- Farmers:Individual commercial growers and smallholders purchasing through distributor networks or direct-to-grower platforms. India's Indo-Gangetic Plain contract vegetable farmers are consolidating acreage under formal seed procurement agreements with certified suppliers.
- Agricultural Cooperatives:Aggregated buying power enables single-source certification-compliant procurement to streamline EU and Japanese import protocol documentation. Export-oriented vegetable cooperatives are displacing fragmented multi-vendor purchasing models.
- Retailers:Garden center and farm supply stores serving home gardening and small-scale cultivation segments.
- Seed Distributors:Intermediary layer managing inventory, logistics, and regional variety placement for breeding houses.
Transaction value concentrates with Agricultural Cooperatives; expansion velocity is steepest among Farmers adopting digital procurement channels.
Application:
Cultivation environment dictates germplasm specifications for stress tolerance and growth cycle management.
- Commercial Farming:Large-scale open-field production for fresh market and processing supply chains. China's Shandong Province contract vegetable farming for export markets is intensifying demand for heat-tolerant hybrid germplasm.
- Greenhouse Cultivation:Polyhouse and nethouse infrastructure across Vietnam and Thailand creates dedicated demand for climate-controlled hybrid tomato and pepper varieties.
- Home Gardening:Small-scale residential cultivation favoring open-pollinated heritage varieties and untreated organic stocks.
- Research:Institutional breeding programs and varietal development stations requiring parental line maintenance and genetic characterization capabilities.
Revenue generation centers on Commercial Farming; Greenhouse Cultivation is climbing the fastest as protected agriculture scales.
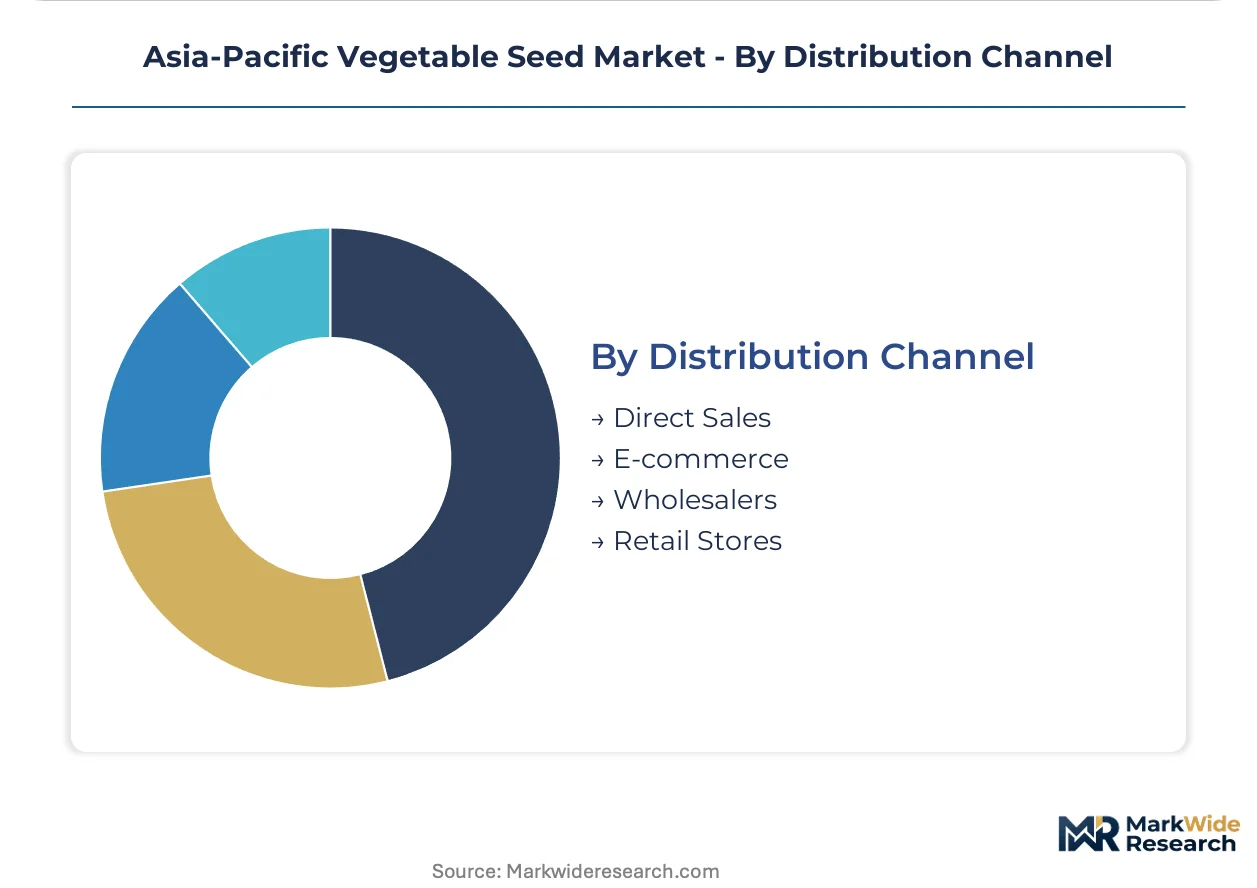
Distribution Channel:
Channel selection reflects buyer digital maturity and the urgency of varietal replacement cycles.
- Direct Sales:Breeding house field representatives placing hybrid contracts with large commercial operations and cooperatives.
- E-commerce:Digital seed marketplaces bypassing traditional distributor layers to reach contract vegetable farmers in Vietnam's Central Highlands.
- Wholesalers:Regional inventory aggregation serving fragmented smallholder markets across Bangladesh and Myanmar.
- Retail Stores:Physical farm supply and garden center presence for home gardening and local commercial grower segments.
Transaction volume flows through Direct Sales; E-commerce is gaining share fastest as digital infrastructure penetrates rural procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's concentrated hybrid seed production anchors Asia-Pacific germplasm supply, with Hainan Island's winter breeding nurseries cycling parental line development. China's seed law revisions and Japan's varietal registration protocols are hardening cross-border germplasm movement barriers across the region.
China
State-backed breeding institutes in Beijing and Shandong are accelerating inbred line substitution for restricted foreign parental material. The Ministry of Agriculture and Rural Affairs enforces multi-location DUS testing mandates for all imported germplasm prior to commercial release. Contract vegetable farming in Shandong Province for export markets is intensifying demand for heat-tolerant hybrid tomato and pepper germplasm.
India
Processing and export-oriented operations in the Indo-Gangetic Plain are consolidating acreage under formal seed procurement agreements with certified suppliers. The Central Seed Committee administers truth-in-labeling mandates and interstate certification requirements under the Seeds Act. Export-oriented cooperatives in Maharashtra and Karnataka are sourcing untreated vegetable seed to meet EU organic equivalence standards.
Japan
Accelerated breeder rights recognition under the Plant Variety Protection and Seed Act is incentivizing domestic R&D investment in brassica and solanaceous lines. METI oversees varietal registration timelines that create 18-24 month market access delays for foreign germplasm. Specialized breeding programs in Kansai and Kyushu regions are developing regionally adapted hybrid varieties for protected agriculture expansion.
Vietnam
Polyhouse and nethouse construction across the Central Highlands is creating dedicated demand for heat-tolerant hybrid tomato and pepper germplasm. The Ministry of Agriculture and Rural Development enforces phytosanitary certification for imported seed stocks. Digital seed marketplaces are bypassing traditional distributor layers to reach contract vegetable farmers in Lam Dong and Dak Lak provinces.
Thailand
Greenhouse infrastructure expansion in the Central Plains and Northern Highlands is pulling hybrid vegetable seed procurement into formal supply chains. The Department of Agriculture regulates varietal registration and seed quality standards for commercial distribution. Chiang Mai and Chiang Rai provinces are emerging as protected agriculture clusters driving demand for climate-controlled hybrid varieties.
Asia-Pacific Vegetable Seed Market Competitive Environment
Global majors compete with regional champions across breeding infrastructure and germplasm access. The market structures around three tiers: multinational agrochemical conglomerates with integrated seed divisions, specialized vegetable breeding houses with century-long varietal portfolios, and state-backed Chinese producers accelerating domestic substitution. Consolidation pressure intensifies as germplasm sovereignty policies force localization of R&D capacity. Strategic moves center on captive breeding station establishment and molecular marker platform licensing.
Within the multinational tier, Syngenta Group and Bayer AG exemplify integrated agrochemical-seed architectures with regional R&D stations in Singapore and China. Takii & Co., Ltd. and Sakata Seed Corporation represent specialized Japanese breeding houses with deep brassica and solanaceous lineages. Among Asia-Pacific regional champions, East-West Seed and Gansu Dunhuang Seed Co., Ltd. occupy positions bridging tropical adaptation expertise with state-backed domestic development mandates.
| Leading Market Players |
|---|
| Groupe Limagrain |
| BASF SE |
| Syngenta Group |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Takii & Co., Ltd. |
| Bayer AG |
| East-West Seed |
| Gansu Dunhuang Seed Co., Ltd. |
| Sakata Seed Corporation |
| Others |
Value Chain & Pricing Dynamics
Marker-assisted backcrossing platforms simultaneously compress breeding cycle economics and concentrate parental line maintenance in China's Shandong and Hainan provinces. This technological shift tightens cost structures for hybrid seed development while amplifying geographic supply dependencies.
Pricing Analysis
After-sales agronomic support and trait performance warranties are bundled with premium hybrid contracts to processing cooperatives in Maharashtra, while unbundled seed-only transactions dominate smallholder channels in Bangladesh and Myanmar. Three-tier pricing structure across premium certified, standard registered, and economy unlabeled tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from China's multi-location DUS testing mandates that extend foreign germplasm approval timelines and inflate regulatory compliance costs. Smallholder farmers in Myanmar exhibit highest price sensitivity, prioritizing seed-saving cost reduction over yield performance predictability.
Supply Chain Analysis
Direct-to-cooperative channels handle large-scale contract farmer demand in India's Indo-Gangetic Plain, while digital marketplaces penetrate Vietnam's Central Highlands. Parental line production concentrates in China's Shandong Province and Hainan Island winter nurseries, with secondary multiplication sites in Thailand's Central Plains. Hybrid seed output draws from concentrated inbred germplasm stocks, specialized pollination labor pools, and climate-controlled greenhouse infrastructure. Single-source vulnerability in China's parental line maintenance exposes regional supply to localized climate shocks and regulatory access restrictions. Distribution runs through breeding house field representatives for commercial operations and regional wholesalers for fragmented smallholder markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific vegetable seed markets are consolidating around germplasm sovereignty mandates that eliminate undercapitalized foreign players lacking captive R&D infrastructure in China and Japan.
For Market Incumbents: Acquire captive breeding stations in mainland China to satisfy Ministry of Agriculture and Rural Affairs multi-location DUS testing requirements. Secure inbred line development capacity in Shandong Province to substitute for restricted foreign parental material. State-backed Chinese producers accelerating domestic substitution represent the primary competitive threat. Vertical integration into regional pollination labor pools and greenhouse infrastructure anchors supply security. For New Entrants and Emerging Players: Begin with untreated organic seed procurement for EU-certified export cooperatives in Karnataka and Maharashtra, where buyer concentration creates single-source contract opportunities. Target Vietnam's Central Highlands greenhouse expansion corridor for heat-tolerant hybrid tomato and pepper germplasm placement. Digital marketplace partnerships with provincial agricultural extension services provide lowest-friction go-to-market access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational breeding houses seeking germplasm sovereignty compliance capacity. Long-term viability favors specialized vegetable breeding houses with century-long varietal portfolios and established breeder rights in Japan's brassica and solanaceous segments. Watch for inflection signals in China's varietal approval timeline compression for domestic versus foreign germplasm applicants.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Breeding Station Establishment | Satisfies China's Ministry of Agriculture DUS testing mandates for market access. |
| Organic Certification Pathway Investment | Aligns supply with EU equivalence standards demanded by Maharashtra processing cooperatives. |
| Gene Editing Platform Licensing | Accelerates bacterial wilt resistance trait integration for tropical hybrid pipelines. |
| Direct-to-Grower Digital Marketplace | Bypasses distributor layers to capture Vietnam Central Highlands greenhouse demand. |
| Inbred Line Substitution Program | Reduces dependency on foreign parental material restricted by germplasm sovereignty policies. |
Study Parameters
Independent corroboration across breeding station directors, seed distributor network managers, and contract farming procurement officers underwrites the qualitative findings. Primary field engagement with vegetable cooperative leadership in Maharashtra and Karnataka, plus regulatory affairs specialists at Japan's Ministry of Economy, Trade and Industry, grounds policy impact assessment. Secondary validation draws from Central Seed Committee certification records, Japan's Plant Variety Protection and Seed Act filings, and Vietnam Ministry of Agriculture phytosanitary documentation. Bottom-up acreage and procurement volume estimates triangulate against top-down breeding house pipeline disclosures.
Comparable-period anchoring to historical hybrid adoption curves in India's Indo-Gangetic Plain and China's Shandong Province calibrates the projection framework. Segmentation modeling spans product type, end user sophistication, cultivation application, and distribution channel digital maturity across the analysis window. CAGRs derive from breeder pipeline velocity, greenhouse infrastructure buildout schedules, and regulatory approval timeline assumptions. Climate stress projections and germplasm substitution rates inform scenario-weighted outcomes.
Underlying measurement precision varies by segment; commercial farming and greenhouse cultivation carry tighter precision than subsistence smallholder estimates. Forecasts reflect assumptions on regulatory timeline stability, parental line climate resilience, and digital marketplace penetration velocity. Seed sovereignty policy escalation and monsoon pattern disruption represent primary revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Watermelon Seeds Market
Seeds
Canary Seeds Market
Seeds
Africa Grain Seed Market
Seeds
Tomato Seed Market
Seeds
Sri Lanka Seed Market
Seeds
Rapeseed Market
Seeds
North America Forage Seed Market
Seeds
North America Vegetable Seed Market
Seeds
Flower Seed Market
Seeds
Custom Selected Seed Market
Seeds
Global Rice Seed Market
Seeds
Dodder Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
India Rice Seed Market
Seeds
Agricultural Seeder Market
Seeds
Europe Forage Seed Market