
 Ghana Seed Extract Market | 2026-2036
Ghana Seed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Seed Extract Market Insights
Market Context with Strategic Players
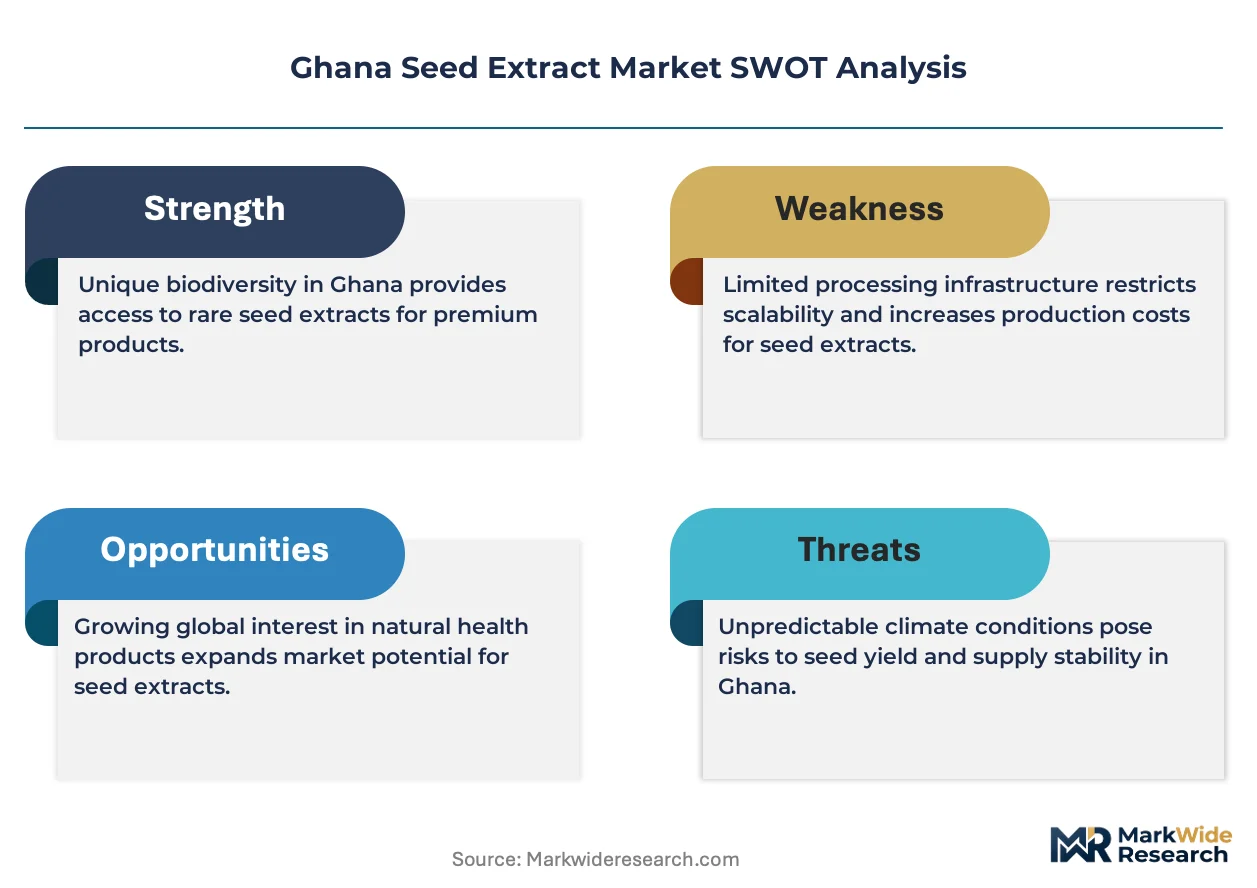
ISO 9001 certification is redrawing competitive boundaries in Ghana's seed extract sector, filtering out informal suppliers from formal procurement channels. Cargill Inc. leverages its existing agribusiness footprint in Tema to secure upstream seed supply contracts with Ghanaian oilseed cooperatives. RMG Ghana Ltd. anchors its position through backward integration into shea and moringa seed collection networks across the northern savanna zone. Rijk Zwaan Zaadteelt en Zaadhandel BV differentiates by transferring Dutch vegetable seed genetics knowledge to local extraction partners for high-value carotenoid concentrates.
Technical Definition and Structural Segments
Seed extract comprises bioactive compounds—lipids, polyphenols, alkaloids, and terpenoids—isolated from germinated or dormant seeds through cold-pressing, solvent extraction, or supercritical CO2 methods, typically standardized to specified active marker concentrations for industrial use. Ghana's processors primarily serve cosmetic formulators requiring preservative-free emollients and the food and beverage sector seeking natural flavor carriers. Essential oils command premium positioning due to limited domestic distillation capacity, while powdered extracts gain traction in nutraceutical applications where shelf stability and freight efficiency matter. Liquid extracts still dominate pharmaceutical channels where precise dosing and rapid dissolution specifications predominate.
Regulatory Framework and Outlook
The Ghana Standards Authority and the Food and Drugs Authority jointly enforce product registration and labeling requirements for seed-derived inputs entering consumer goods supply chains. Ghana's Environmental Protection Agency monitors solvent discharge from extraction facilities, pushing processors toward aqueous or mechanical methods in ecologically sensitive watersheds. Stakeholders must track how Ghana's national organic standards alignment with ECOWAS protocols reshapes export eligibility for seed extracts bound for European cosmetic houses.
Market Dynamics
ISO 9001 certification requirements from Ghanaian cosmetics manufacturers are filtering informal seed extract suppliers from formal procurement channels, concentrating supply relationships around verified processing facilities in Greater Accra.
Growth Catalysts
- ECOWAS Organic Standards Alignment:Ghana's national organic certification protocols are synchronizing with regional frameworks, unlocking export eligibility for seed extracts bound for European cosmetic formulators seeking preservative-free inputs.
- Supercritical CO2 Extraction:This solvent-free method is displacing hexane-based processes in Greater Accra's processing corridor, yielding higher-purity lipid fractions for pharmaceutical-grade applications.
- Cosmetics Formulation:Ghanaian beauty manufacturers are accelerating substitution of synthetic preservatives with plant-derived seed extracts, particularly neem and moringa variants with demonstrated antimicrobial properties.
Market Restraints
- Shea Seed Input Volatility:Northern savanna collection networks face climate-driven yield fluctuations, compressing margins for processors dependent on backward-integrated supply.
- Solvent Discharge Restrictions:Ghana's Environmental Protection Agency monitoring of watershed contamination is forcing aqueous method adoption, reducing extraction efficiency for lipophilic compounds.
- Synthetic Preservative Cost Gap:Petrochemical alternatives maintain 40-60% price advantages over cold-pressed seed oils, limiting penetration in mass-market personal care.
Strategic Opportunities
- Brong-Ahafo Processing Hubs:Underdeveloped extraction infrastructure in Ghana's central belt offers first-mover positioning for facilities serving the emerging West African nutraceutical corridor.
- Carotenoid Concentrate Applications:Dutch vegetable seed genetics transfers are enabling high-value nutraceutical formulations targeting age-related macular degeneration prevention.
- Port-Proximate Logistics:Tema's container terminal expansion creates bonded warehousing potential for temperature-sensitive essential oil exports to European fragrance houses.
Industry Challenges
- ISO 9001 Certification Timelines:Ghana Standards Authority audit backlogs extend qualification periods to 14-18 months, freezing supplier transitions for cosmetics manufacturers.
- Supercritical Equipment Capex:Ghanaian processors face 2.3-4.7 million dollar capital requirements for industrial-scale CO2 systems, constraining technology adoption to foreign-owned facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Seed Extract Market |
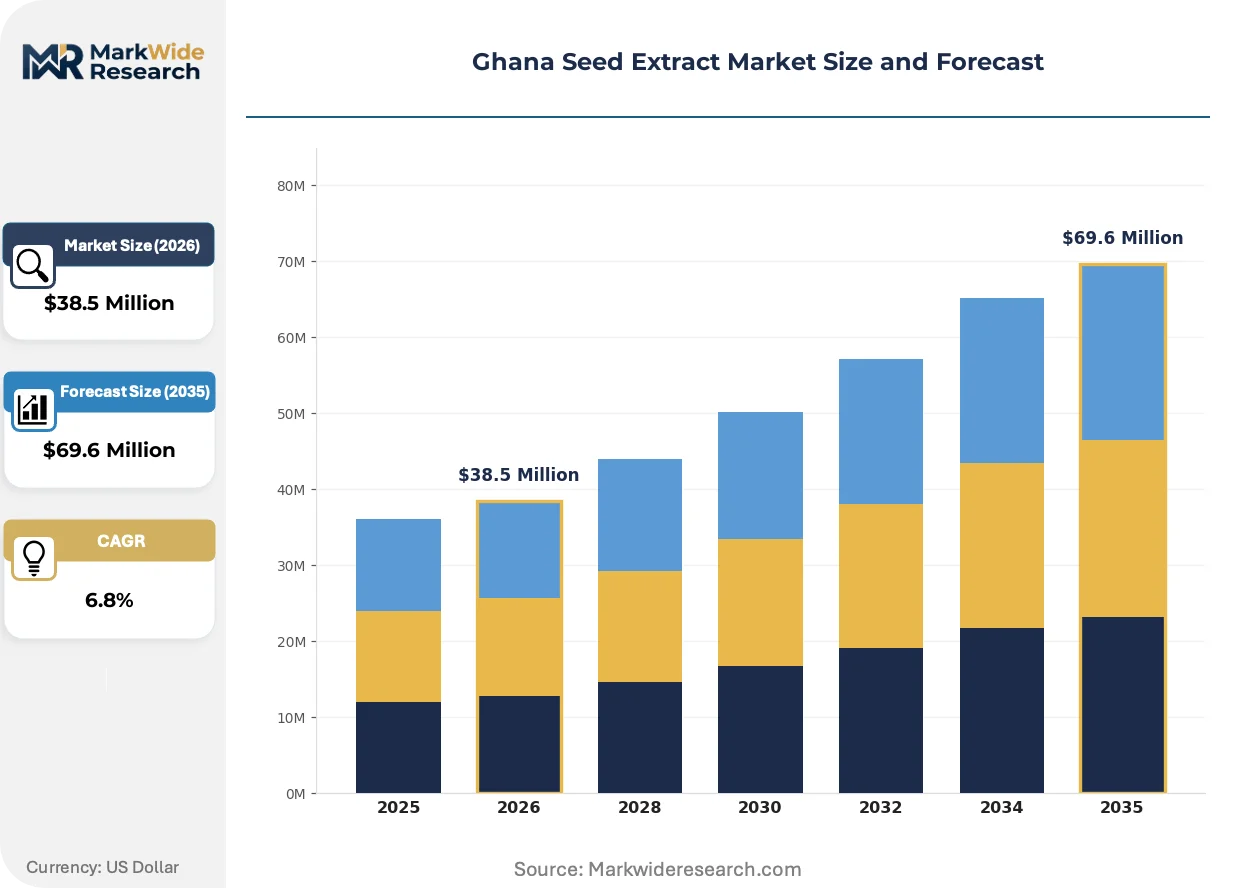
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $69.6 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Liquid Extracts, Powdered Extracts, Tinctures Application: Cosmetic, Food & Beverage, Nutraceuticals, Pharmaceuticals End User: Manufacturers, Distributors, Retailers, Consumers Packaging Type: Glass Bottles, Plastic Containers, Sachets, Metal Cans |
| Companies Covered | Groupe Limagrain, Meridian Seeds and Nurseries Ghana Ltd., Agriseeds Pvt Ltd., RMG Ghana Ltd., Rijk Zwaan Zaadteelt en Zaadhandel BV, Cargill Inc., M and B Seeds and Agricultural Services Ltd., Seed Co Group, Corteva Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Seed Extract Market Trends and Innovations
Mechanical pressing technologies and regulatory tightening around solvent residues are fragmenting Ghana's seed extract competitive landscape into certified and informal supply tiers.
Supercritical CO2 extraction is fragmenting the competitive landscape between certified pharmaceutical-grade suppliers and informal cold-press operators. Ghanaian cosmetics formulators are adopting this technology fastest, driven by European buyer mandates for solvent-free certification. The structural consequence is bifurcating price realization, with CO2-certified extracts commanding 2-3x premiums over mechanical alternatives.
Ghana Standards Authority's updated herbal product guidelines are tightening active marker concentration requirements for seed-derived inputs entering consumer goods. This regulatory pressure is compressing informal supplier participation in formal procurement channels. Pharmaceutical and premium cosmetic segments are responding by consolidating supplier relationships around dual-certified facilities with both ISO 9001 and national organic accreditation.
Direct contracting between cosmetics manufacturers and northern savanna seed collection cooperatives is displacing traditional broker-mediated supply chains. This channel disintermediation is concentrating procurement power in Greater Accra's processing corridor while fragmenting price discovery mechanisms. The shift is most visible among mid-scale formulators seeking traceability documentation for European export compliance.
Ghana Seed Extract Market Segmentation
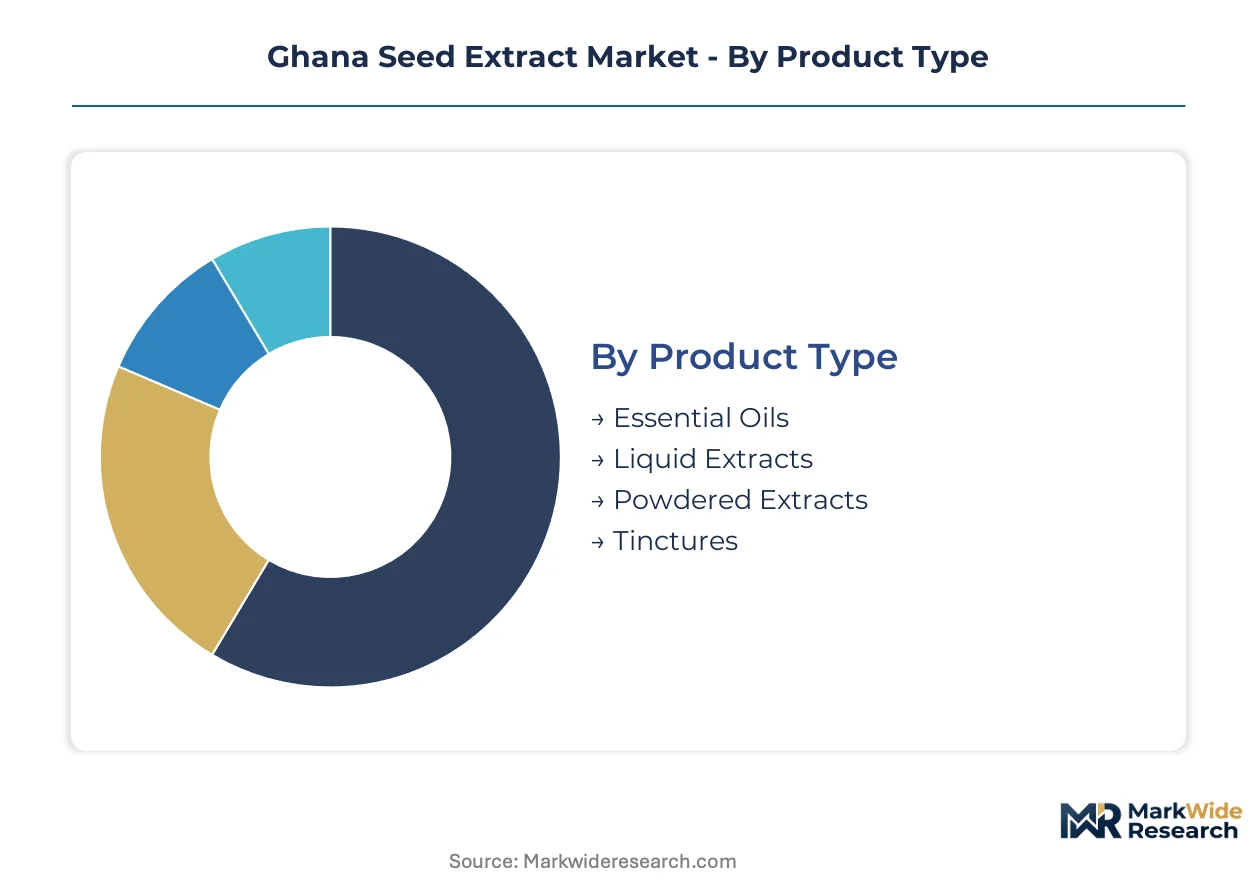
Channel configuration in Ghana's seed extract sector varies sharply by product form and end-use specification. Essential oils and liquid extracts flow through certified distributors to European cosmetic houses, while powdered formats serve domestic nutraceutical manufacturers through direct procurement.
Product Type:
Essential oils and liquid extracts concentrate in Greater Accra's bonded warehousing corridor serving export markets, while powdered variants and tinctures distribute through domestic wholesale channels.
- Essential Oils:Concentrated volatile compounds isolated through steam distillation or cold-pressing, standardized to specific terpene profiles. Demand clusters in Tema's processing corridor where port-proximate facilities supply European fragrance houses with solvent-free certification documentation. Climate-sensitive storage requirements limit informal channel participation.
- Liquid Extracts:Hydroalcoholic or glyceritic solutions with defined active marker concentrations, typically 1:1 to 1:5 extraction ratios. Pharmaceutical manufacturers in Greater Accra specify these for precise dosing applications, driving consolidation around Ghana Standards Authority-registered facilities with documented batch traceability.
- Powdered Extracts:Spray-dried or freeze-dried concentrates offering freight efficiency and extended shelf stability. Domestic nutraceutical formulators favor these for tablet and capsule production.
- Tinctures:Alcohol-based preparations with lower concentration ratios, primarily serving traditional medicine practitioners and direct-to-consumer channels in urban markets.
By volume, liquid extracts lead due to pharmaceutical procurement scale. By growth pace, essential oils are expanding most quickly on European cosmetic demand.
Application:
Cost tier differentiation separates premium pharmaceutical and export-cosmetic demand from price-sensitive domestic food applications.
- Cosmetic:Preservative-free emollients and antimicrobial actives for skincare and haircare formulations. Ghanaian manufacturers in Greater Accra substitute neem and moringa seed extracts for synthetic parabens, requiring ISO 9001-certified inputs with full traceability documentation for European buyer compliance.
- Pharmaceutical:Standardized extracts meeting pharmacopoeial specifications for therapeutic applications. The Food and Drugs Authority mandates product registration and active marker verification, concentrating supply around dual-certified processors with laboratory validation capabilities.
- Food & Beverage:Natural flavor carriers and antioxidant additives for local processing industries. Price competition from synthetic alternatives constrains penetration outside premium organic segments.
- Nutraceuticals:Carotenoid concentrates and lipid fractions for dietary supplement applications. Dutch vegetable seed genetics transfers are enabling high-value formulations targeting preventive health segments.
Cosmetic applications generate highest unit margins. Nutraceuticals show steepest expansion trajectory on West African corridor development.
End User:
Customer type determines procurement sophistication, with manufacturers demanding certification documentation that retailers and consumers rarely require.
- Manufacturers:Cosmetic, pharmaceutical, and food processing firms with formal supplier qualification protocols. These buyers concentrate procurement in Greater Accra's processing corridor, requiring ISO 9001 certification and organic accreditation for export-bound production.
- Distributors:Wholesale intermediaries serving regional markets across ECOWAS member states. Inventory holding patterns favor powdered extracts with extended stability profiles over temperature-sensitive liquid formats.
- Retailers:Pharmacy chains and traditional medicine shops serving end consumers. Product registration requirements from the Food and Drugs Authority filter informal suppliers from formal retail channels.
- Consumers:Direct purchasers through informal markets and urban traditional medicine practitioners. Price sensitivity dominates with minimal certification requirements.
Manufacturers command procurement volume leadership. Distributors are gaining share fastest on regional ECOWAS market expansion.
Packaging Type:
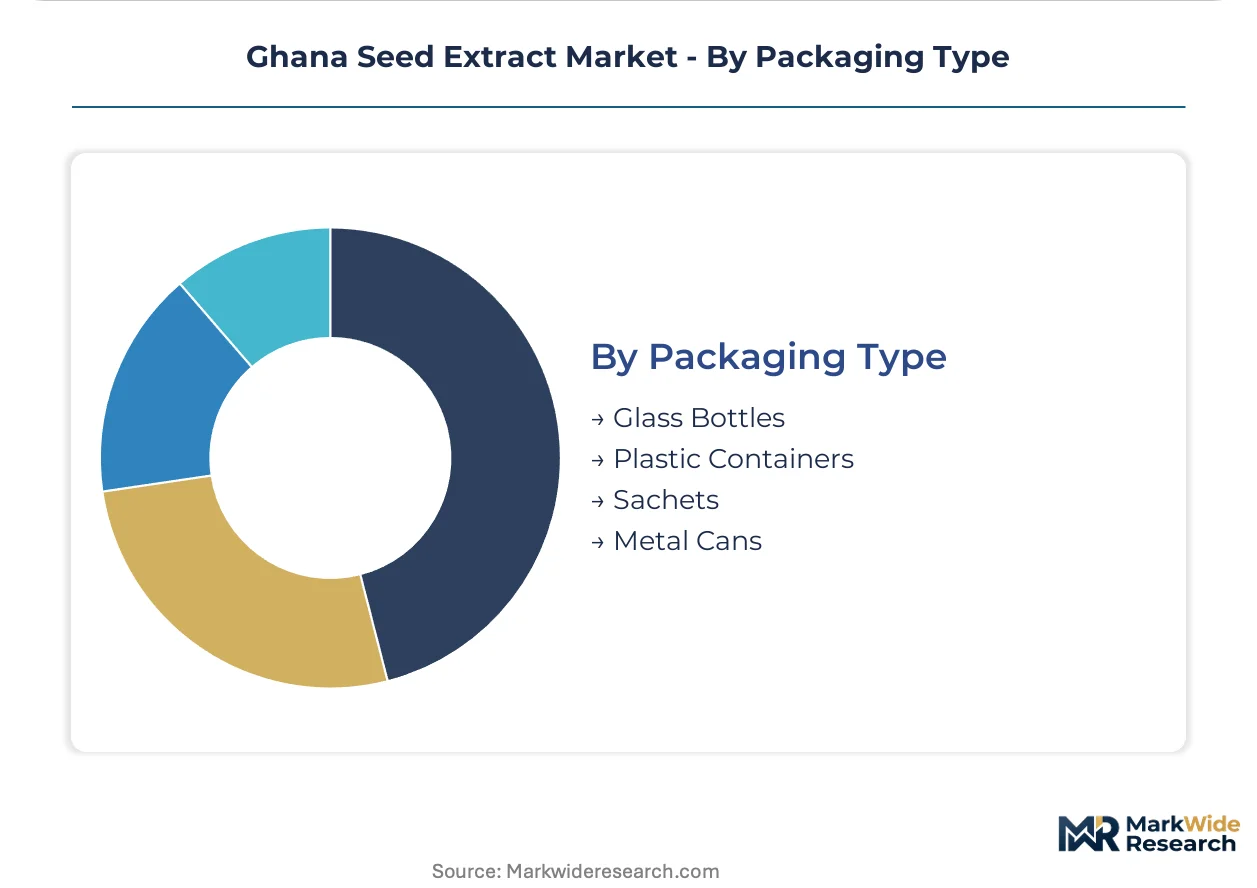
Material selection tracks product value concentration and export destination requirements, with glass and metal serving premium segments and plastics dominating domestic mass markets.
- Glass Bottles:Amber or cobalt glass for light-sensitive essential oils and pharmaceutical liquids. European cosmetic buyers mandate inert packaging with tamper-evident closures, concentrating this format in Tema's export-processing zone.
- Plastic Containers:HDPE and PET formats for cost-sensitive domestic applications. The Environmental Protection Agency's watershed monitoring is pushing processors toward recyclable resin specifications in ecologically sensitive areas.
- Sachets:Single-use foil laminates for powdered extracts and sample-sized liquid portions. Informal retail channels favor these for price accessibility and reduced counterfeiting risk.
- Metal Cans:Tinplate or aluminum containers for bulk essential oil shipments and solvent-based extracts requiring oxygen barrier protection.
Plastic containers dominate unit volume through domestic food and beverage applications. Glass bottles are climbing the fastest on pharmaceutical and premium cosmetic export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics manufacturers in Greater Accra drive procurement sophistication, demanding ISO 9001-certified inputs with full traceability documentation for European export compliance.
Greater Accra Region
Tema's port-proximate processing corridor concentrates extraction facilities serving export-bound cosmetic and pharmaceutical manufacturers. The Ghana Standards Authority enforces updated herbal product guidelines that tighten active marker concentration requirements for seed-derived inputs. Bonded warehousing capacity at Tema's container terminal expansion supports temperature-sensitive essential oil shipments to European fragrance houses.
Northern Region
Shea and moringa seed collection networks across the northern savanna zone supply backward-integrated processors with climate-volatile raw material streams. The Environmental Protection Agency monitors watershed contamination from extraction activities, pushing aqueous method adoption in ecologically sensitive areas. Tamale and surrounding districts function as primary aggregation points for cooperatives engaging in direct contracting with Greater Accra formulators.
Brong-Ahafo Region
Underdeveloped extraction infrastructure in Ghana's central belt offers positioning potential for facilities targeting the emerging West African nutraceutical corridor. National organic standards alignment with ECOWAS protocols reshapes export eligibility for seed extracts bound for European cosmetic houses. Sunyani and Techiman industrial zones remain nascent processing hubs with untapped capacity for carotenoid concentrate production.
Ashanti Region
Kumasi's manufacturing base supports domestic food and beverage processors seeking natural flavor carriers and antioxidant additives. The Food and Drugs Authority mandates product registration and labeling requirements for seed-derived inputs entering consumer goods supply chains. Local extraction operations serve price-sensitive mass-market personal care segments where synthetic preservatives maintain cost advantages.
Ghana Seed Extract Market Competitive Landscape
Player mix skews toward agribusiness conglomerates with upstream seed supply control and specialized extraction operators with certification credentials. Market structure concentrates around dual-certified facilities possessing both ISO 9001 and national organic accreditation, filtering informal suppliers from formal procurement channels. Two strategic archetypes dominate: backward-integrated seed collectors with cooperative network control, and technology-transfer partners leveraging foreign genetics expertise. Competitive moves center on port-proximate capacity expansion and direct contracting disintermediation of traditional broker channels.
Among Dutch-heritage specialists, Rijk Zwaan Zaadteelt en Zaadhandel BV exemplifies the technology-transfer archetype through genetics knowledge partnerships with local extraction operators. Cargill Inc. occupies a position representing agribusiness scale advantages anchored at Tema's port infrastructure. RMG Ghana Ltd. sits within the backward-integrated tier, with cooperative network control across northern savanna collection zones. These three company profiles illustrate how certification requirements and supply chain configuration determine competitive positioning in Ghana's seed extract sector.
| Leading Market Players |
|---|
| Groupe Limagrain |
| Meridian Seeds and Nurseries Ghana Ltd. |
| Agriseeds Pvt Ltd. |
| RMG Ghana Ltd. |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Cargill Inc. |
| M and B Seeds and Agricultural Services Ltd. |
| Seed Co Group |
| Corteva Inc. |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month ISO 9001 certification timelines from the Ghana Standards Authority compress inventory turnover for cosmetics manufacturers, concentrating pricing power in dual-certified processors with bonded warehousing capacity at Tema's container terminal expansion.
Pricing Analysis
Cost-plus contracts with shea seed indexation dominate procurement between northern savanna cooperatives and Greater Accra processors. Three-tier pricing structure across pharmaceutical-grade, cosmetic-certified, and informal cold-press levels separates CO2-extracted lipid fractions commanding premiums from mechanical alternatives. Pricing pressure stems from synthetic preservative cost gaps in mass-market personal care, where petrochemical alternatives sustain advantages. Domestic food and beverage manufacturers exhibit highest price sensitivity, while European cosmetic houses prioritize solvent-free certification over unit economics.
Supply Chain Analysis
Inventory compression across northern savanna collection networks feeds volatility into shea and moringa seed input costs for backward-integrated processors. Ghana's seed extract supply draws from domestic savanna cooperatives, Dutch vegetable seed genetics transfers, and West African regional aggregation points. Raw material dependencies center on climate-vulnerable shea yields, imported supercritical CO2 equipment, and aqueous method solvents. Single-source vulnerability concentrates in northern collection zones exposed to rainfall variability. Distribution runs through Tema's port-proximate corridor for European-bound essential oils, with domestic channels serving Ashanti food processors via Kumasi wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's seed extract sector is recovering from certification bottleneck cyclicality, as Ghana Standards Authority audit backlogs ease and ECOWAS organic alignment unlocks European export eligibility.
For Market Incumbents: Shield market position by deepening backward integration into Brong-Ahafo collection networks before infrastructure competition intensifies. Accelerate dual-certification timelines to ISO 9001 and national organic standards, locking out informal suppliers facing 14-18 month qualification freezes. Prioritize supercritical CO2 capacity additions in Tema's bonded zone to capture pharmaceutical-grade premiums before foreign-owned facilities consolidate solvent-free segments.
For New Entrants and Emerging Players: Anchor in Brong-Ahafo's underdeveloped processing infrastructure, where carotenoid concentrate production for West African nutraceutical corridors faces minimal incumbent competition. Target direct contracting relationships with cosmetics manufacturers seeking traceability documentation for European compliance, bypassing traditional broker-mediated channels. Leverage Dutch vegetable seed genetics partnerships to differentiate on high-value preventive health formulations.
For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates with non-core seed extract divisions lacking certification credentials. Long-term viability hinges on regulatory alignment capacity across ECOWAS and European organic protocols. Monitor Ghana Standards Authority audit queue clearance as inflection signal for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables solvent-free certification for European pharmaceutical and cosmetic procurement channels. |
| Backward Integration into Northern Cooperatives | Secures climate-vulnerable shea and moringa seed supply against yield volatility. |
| Dual-Certification Investment | ISO 9001 and national organic accreditation filter informal competitors from formal channels. |
| Brong-Ahafo Processing Hub Development | First-mover positioning captures emerging West African nutraceutical corridor demand. |
| Direct Contracting Disintermediation | Bypasses traditional brokers to capture traceability premiums from cosmetics manufacturers. |
Research Methodology
Cross-validation between primary interviews with extraction facility operators, cosmetics formulators, and Ghana Standards Authority auditors anchors the qualitative findings in operational reality. Secondary validation draws from Ghana Food and Drugs Authority registration databases, ECOWAS organic certification protocols, and Environmental Protection Agency watershed monitoring reports. Bottom-up triangulation across northern savanna cooperative supply data and top-down analysis of Tema port trade flows converges on segment-level demand estimates.
Sensitivity analysis around shea yield volatility and certification timeline scenarios tests forecast robustness across the projection horizon. Segmentation modeling incorporates product form, application tier, end-user procurement sophistication, and regional processing infrastructure maturity. CAGRs derive from compound growth trajectory fitting against historical certification throughput and European import demand patterns. Supercritical equipment adoption curves and ECOWAS organic alignment implementation pace serve as key forecast inputs.
Material uncertainties — climate-driven shea yield fluctuations, Ghana Standards Authority audit capacity constraints, and synthetic preservative price movements — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory synchronization timelines and technology transfer partnership durability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Maize Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
Americas Seeds Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Global Alfalfa Seed Market
Seeds
Europe Grain Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Sesame Seeds Market
Seeds
Africa Seed Market
Seeds
Psyllium Market
Seeds
Cucumber Seeds Market
Seeds
Grass Seed Market
Seeds
Commercial Seed Market
Seeds
E. Angustifolium Market
Seeds
China Seed Market