
 Sesame Seeds Market | 2026-2036
Sesame Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Sesame Seeds Market Analysis
Single-origin and traceable batch packaging is hardening as the default configuration for premium buyers, replacing anonymous bulk sourcing. Olam International leverages integrated origination networks across East Africa to sustain supply visibility. Dipasa USA Inc. anchors North American processing capacity with specialized roasting and hulling lines. Equinom competes through computational breeding platforms that optimize protein and oil profiles for food manufacturers.
Sesame seeds are the dried, flattened oval fruits of Sesamum indicum, typically containing 50-60% oil and 20-25% protein by weight, with hulling and roasting altering digestibility and shelf stability for commercial use. The food industry end user dominates volume, with hulled and toasted product types capturing the highest margin pools due to labor-intensive processing and flavor intensity premiums. Natural sesame retains volume leadership in oil extraction, while black sesame differentiates within confectionery and cosmetics applications.
The FDA enforces pathogen testing and foreign supplier verification for sesame imports under FSMA, while the EUs REACH framework governs pesticide residue thresholds for European entry. Indias FSSAI mandates aflatoxin limits and labeling standards for domestic and export-grade consignments. Stakeholders must monitor evolving allergen labeling requirements in major import jurisdictions, as sesame's classification as a major food allergen in the United States already triggers disclosure obligations that reshape formulation and sourcing protocols.
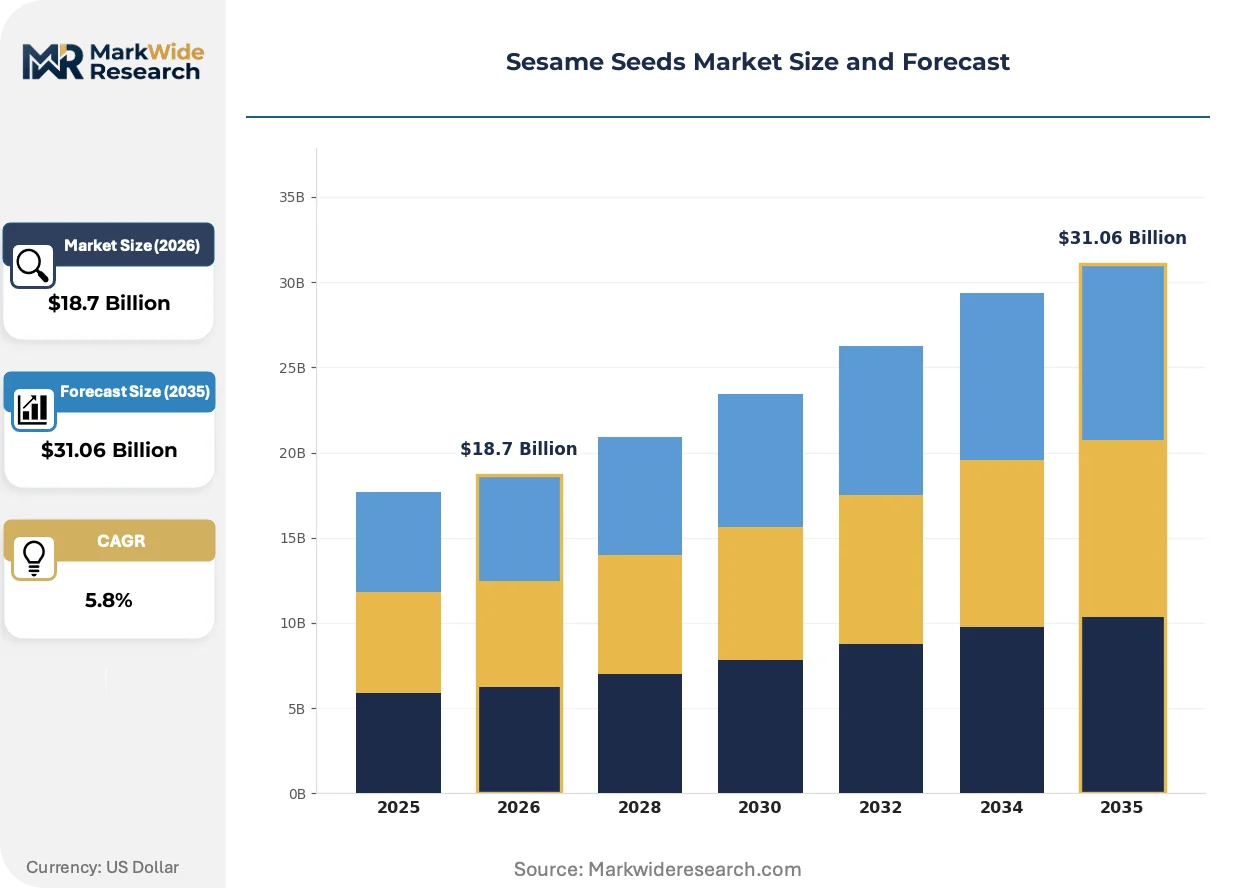
Market Dynamics
Smallholder consolidation across Sudan and Ethiopia is compressing origination networks, forcing exporters to rebuild traceability infrastructure or surrender premium pricing tiers to integrated processors with captive supply bases.
Growth Catalysts
- FSMA Traceability Mandates:The FDA's Food Safety Modernization Act compels importers to verify foreign supplier compliance, accelerating certified supply chain investments that lock in long-term offtake agreements with compliant origins.
- Bakery Premiumization:Artisanal bread producers and quick-service chains are scaling hulled sesame purchases for visual finish and flavor intensity in premium bun applications.
- Computational Breeding Platforms:Seed technology developers deploy genomic selection tools to optimize protein and oil profiles, reducing variety development cycles for food-grade specifications.
Market Restraints
- Input Cost Volatility:Fertilizer and irrigation energy costs swing with hydrocarbon markets, squeezing margins for smallholder-dependent supply chains without forward-contract coverage.
- Supply Concentration Risk:Sudan and Ethiopia collectively anchor exportable surplus, exposing buyers to geopolitical disruption and foreign exchange controls that stall shipment execution.
- Substitution Threat:Sunflower and rapeseed oils compete in bulk food manufacturing applications where sesame's flavor premium does not justify price differentials.
Strategic Opportunities
- Underpenetrated West African Origins:Nigeria and Burkina Faso harbor untapped acreage expansion potential with suitable agro-ecology for sesame cultivation and nascent export infrastructure.
- Cosmetics-Grade Black Sesame:Personal care formulators in South Korea and Japan are sourcing anthocyanin-rich black varieties for antioxidant positioning in premium skincare lines.
- EU Green Deal Alignment:Carbon border adjustment mechanisms and deforestation-free supply chain regulations reward exporters with verified sustainable sourcing credentials.
Industry Challenges
- Aflatoxin Certification Timelines:Laboratory testing backlogs and inconsistent sampling protocols delay lot release, compressing working capital cycles for traders managing perishable inventory.
- Hulling and Roasting Capex Intensity:Automated processing lines for food-grade product require seven-figure equipment investments that exclude smaller processors from margin-rich downstream segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sesame Seeds Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Hulled, Toasted, Black Application: Baking, Cooking Oil, Snacks, Confectionery End User: Food Industry, Cosmetics, Pharmaceuticals, Animal Feed Distribution Channel: Supermarkets, Online Retail, Wholesale, Others |
| Companies Covered | SunOpta, Sakhi Group, Olam International, ECOM Agroindustrial Corporation, Triangle Wholefoods, Equinom, HL Agro Products, Shyam Industries, Dipasa USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sesame Seeds Market Emerging Trajectories
Traceability infrastructure and processing automation are converging to split the market into two tiers: anonymous bulk commodity flows and verified, identity-preserved supply chains commanding persistent premiums.
Blockchain-enabled lot tracking is decentralizing provenance verification away from centralized certifiers toward distributed ledger systems that originators and importers jointly maintain. East African cooperatives and European retailers are piloting these platforms to compress audit costs and accelerate customs clearance. The technology is decentralizing trust architecture across the value chain, reducing reliance on third-party inspection bodies.
REACH pesticide residue thresholds are tightening entry requirements for European markets, forcing exporters to phase out active ingredients that lack ECHA approval. Testing laboratories in Sudan and Ethiopia are expanding chromatography capacity to pre-screen consignments before port loading. Specialty food distributors with EU retail relationships are most exposed, accelerating backward integration into controlled-application farming contracts.
Direct-origin contracting is displacing spot-market procurement among North American roasters and hullers seeking multi-year supply security. Large-scale bakery chains and ingredient houses are bypassing traditional traders to negotiate volume commitments with Ethiopian and Sudanese cooperatives. This pattern concentrates most visibly in the United States, where sesame's major allergen classification has heightened liability sensitivity and intensified documentation requirements.
Sesame Seeds Market Segmentation
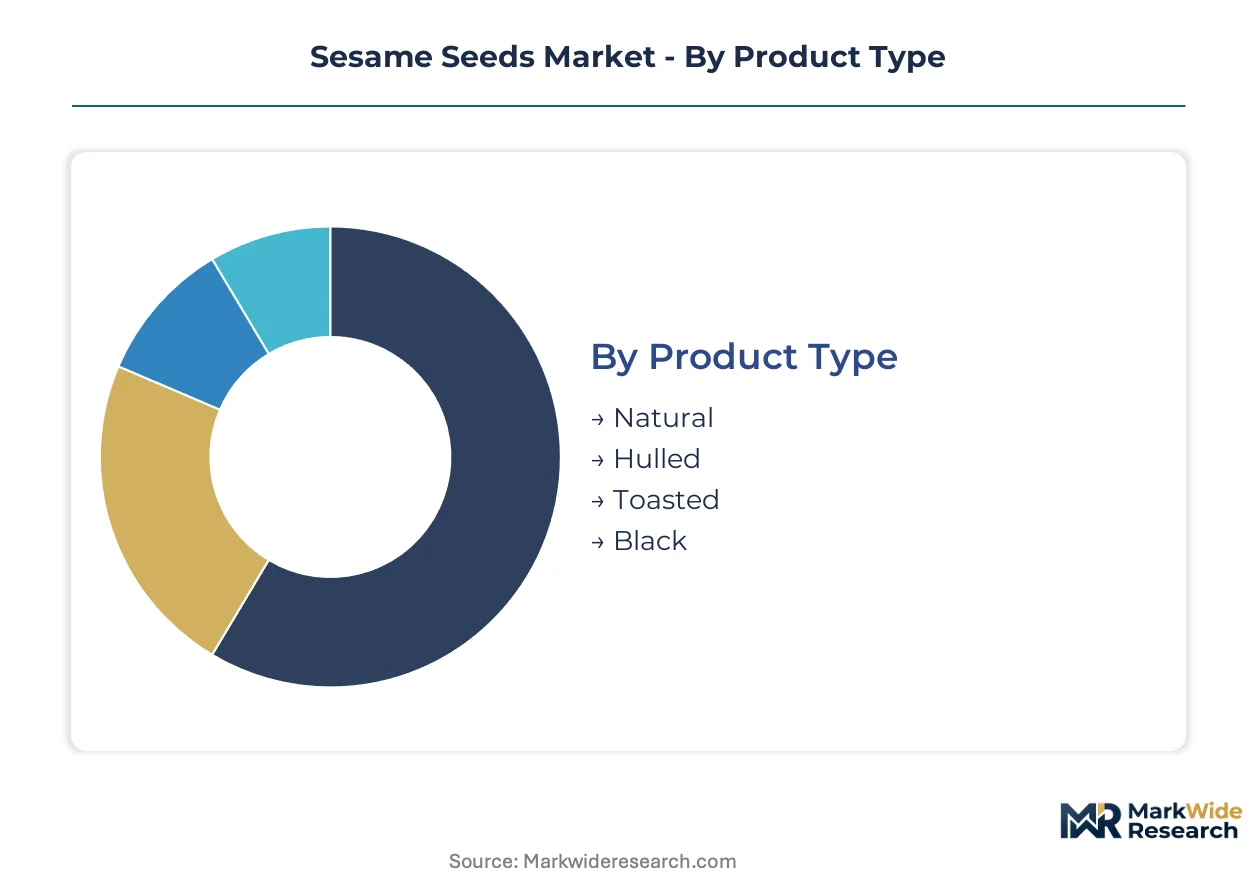
Sesame seed segmentation reflects divergent certification burdens across food-grade and industrial channels. FDA allergen disclosure rules, EU REACH residue thresholds, and FSSAI aflatoxin mandates each map to distinct product categories and end-use specifications.
Product Type:
FSMA traceability mandates and REACH pesticide screening apply differentially across processing intensities, with hulled and toasted variants facing heightened documentation requirements versus natural grades.
- Hulled:Mechanical removal of the fibrous outer coat yields 99.95% purity specifications essential for bakery applications. Sudanese and Ethiopian exporters are consolidating smallholder supply into certified lots to meet FDA foreign supplier verification protocols for North American quick-service chains.
- Toasted:Thermal processing at 160-180°C develops Maillard reaction compounds that intensify flavor profiles for premium bun finishes. Artisanal bread producers in the United States and Germany are locking in multi-year offtake agreements with integrated East African processors capable of lot-level pathogen documentation.
- Natural:Retains hull integrity for oil extraction efficiency, with 50-60% oil content by weight. Indian crushing mills dominate procurement.
- Black:Anthocyanin-rich pigmentation targets cosmetics formulators in South Korea and Japan. Anthocyanin antioxidant claims require MFDS and PMDA substantiation.
Leading the category by volume: Natural. Expanding most quickly: Hulled.
Application:
Margin structures diverge sharply between commodity oil extraction and value-added food manufacturing, with bakery and confectionery commanding persistent premiums over bulk industrial use.
- Baking:Visual finish requirements for hamburger buns and artisan loaves drive specification intensity. Bakery chains specify hull color consistency and roast level tolerances that exclude spot-market procurement.
- Confectionery:Black sesame paste and halva applications demand low moisture content and absence of bitter off-notes. Japanese and Taiwanese confectioners enforce pesticide residue limits stricter than Codex Alimentarius baselines.
- Cooking Oil:Flavor-neutral competition from sunflower and rapeseed constrains sesame penetration in bulk food manufacturing.
- Snacks:Roasted whole seed and tahini-based products occupy middle-tier positioning between commodity oil and premium bakery grades.
Highest margin capture: Confectionery. Steepest volume trajectory: Baking.
End User:
Food industry procurement dominates absolute tonnage, while cosmetics and pharmaceutical channels impose the most stringent purity and traceability specifications.
- Food Industry:Encompasses bakery, oil extraction, and condiment manufacturing. FSMA foreign supplier verification and EU deforestation-free supply chain regulations are compressing eligible supplier pools.
- Cosmetics:Black sesame antioxidant positioning in South Korean skincare requires MFDS cosmetic ingredient registration and stability testing documentation.
- Pharmaceuticals:Sesamin and sesamolin lignan extraction for nutraceutical applications demands GMP-compliant processing with heavy metal and microbial certification.
- Animal Feed:Defatted meal byproducts from oil crushing enter poultry and aquaculture rations with minimal regulatory burden.
Volume concentration: Food Industry. Specification intensity peak: Pharmaceuticals.
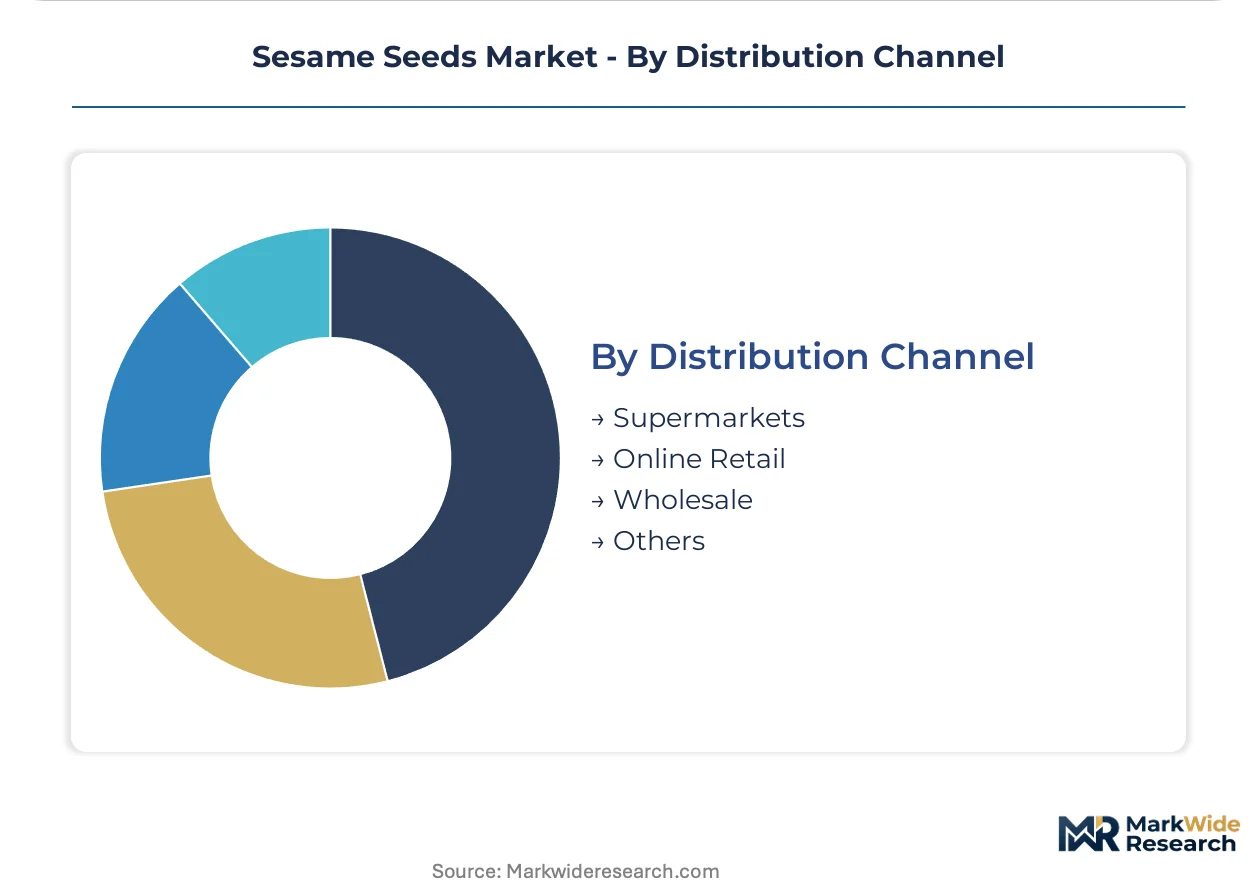
Distribution Channel:
Channel selection correlates directly with lot size and certification depth, with wholesale retaining commodity flows and online retail emerging for traceable specialty grades.
- Wholesale:Container-scale procurement by roasting and hulling facilities. Direct-origin contracting from Ethiopian and Sudanese cooperatives is displacing trader intermediation.
- Supermarkets:Packaged retail SKUs for home baking and condiment use. EU Green Deal alignment and carbon footprint labeling are becoming selection criteria.
- Online Retail:Single-origin and organic certifications command premium positioning. Blockchain-enabled provenance verification supports price differentiation.
- Others:Foodservice distributors and ingredient houses serving industrial accounts with customized specifications.
Dominant volume channel: Wholesale. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Africa and South Asia while consumption tilts toward North American and European food manufacturers. This geographic split shapes trade flows, regulatory compliance burdens, and investment patterns across origination and destination markets.
Sudan
Smallholder consolidation is compressing exportable surplus into fewer commercial channels. The country's national agricultural regulator enforces phytosanitary certificates for EU-bound shipments. Port Sudan handles the bulk of sesame exports, with traders investing in pre-shipment aflatoxin testing laboratories to reduce detention risk at European ports.
Ethiopia
Humera and Wollega growing regions supply high-oil-content white sesame prized by Middle Eastern and Asian buyers. The Ethiopian Food and Drug Authority aligns export standards with Codex Alimentarius baselines. Dire Dawa's processing cluster is attracting hulling and roasting investments from integrated traders seeking captive supply bases.
India
Gujarat and Rajasthan crushing mills dominate natural sesame procurement for domestic oil extraction and export. FSSAI mandates aflatoxin limits and labeling standards that reshape consignment preparation. Rajkot's commodity trading hub is pivoting toward food-grade certification to capture premium bakery and confectionery demand.
United States
Quick-service chains and artisanal bakeries drive hulled and toasted sesame consumption for premium bun applications. FDA's Food Safety Modernization Act compels foreign supplier verification programs that filter eligible import sources. Texas and California roasting facilities are expanding capacity to meet allergen-labeling compliance requirements.
Japan
Confectionery manufacturers and cosmetics formulators source black sesame varieties for antioxidant positioning. PMDA cosmetic ingredient registration requirements govern anthocyanin-rich imports for skincare applications. Kobe and Yokohama trading houses are deepening relationships with East African cooperatives for lot-level traceability documentation.
Sesame Seeds Market Vendor Landscape
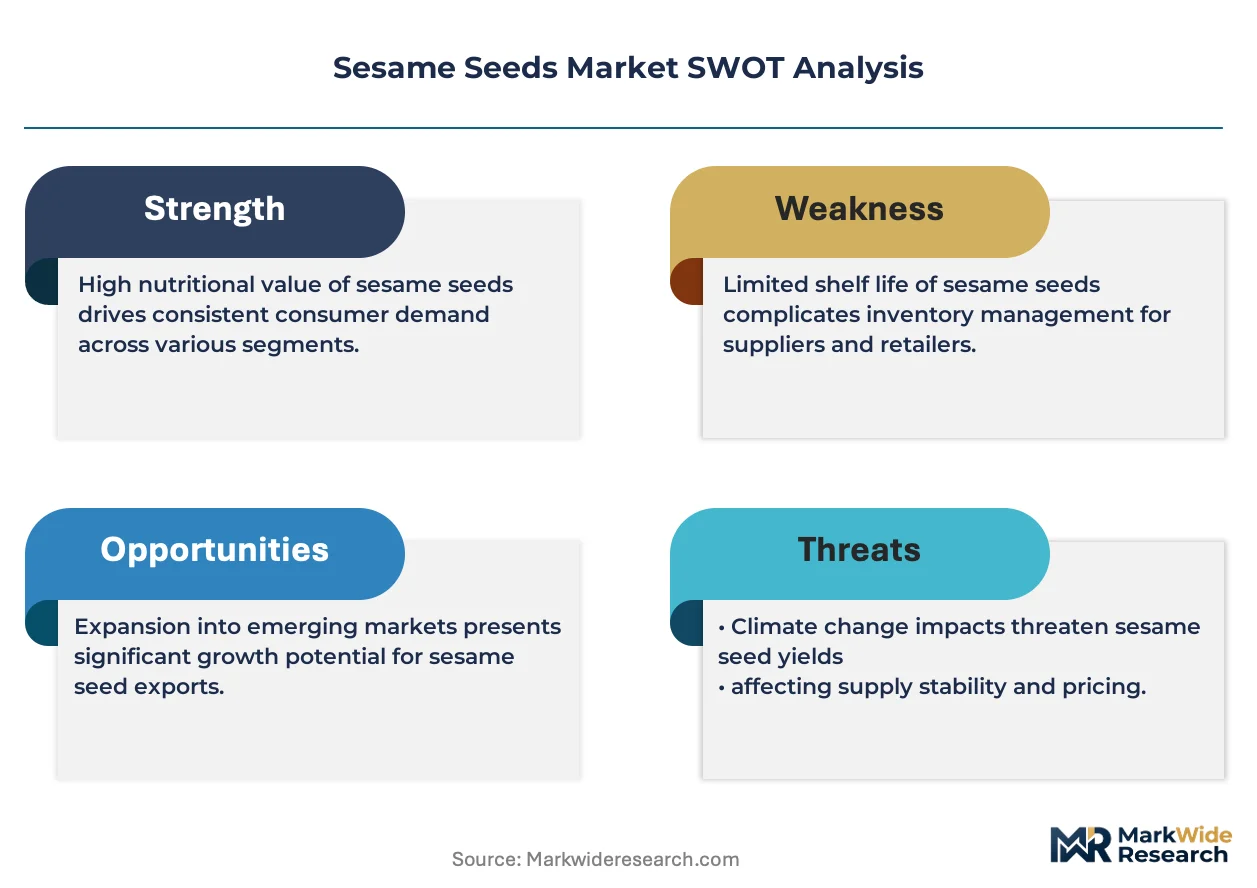
Diversified conglomerates compete with focused pure-play specialists across origination, processing, and distribution tiers. The market exhibits moderate concentration, with integrated traders commanding premium pricing through captive supply chains while regional processors compete on volume and proximity. Three archetypes dominate: East African origination-integrated exporters, North American specialized roasters and hullers, and seed technology developers deploying computational breeding platforms. Competitive dynamics center on backward integration into controlled-application farming and multi-year direct-origin contracting that displaces spot-market intermediation.
Among origination-integrated specialists, Olam International and ECOM Agroindustrial Corporation exemplify the trader-processor model with East African supply network control. Dipasa USA Inc. anchors North American downstream positioning through specialized processing infrastructure. Equinom occupies the seed technology tier, representing the computational breeding archetype that optimizes varietal development for food-grade specifications. These three collectively illustrate the market's strategic segmentation across upstream origination, midstream processing, and varietal innovation.
| Leading Market Players |
|---|
| SunOpta |
| Sakhi Group |
| Olam International |
| ECOM Agroindustrial Corporation |
| Triangle Wholefoods |
| Equinom |
| HL Agro Products |
| Shyam Industries |
| Dipasa USA Inc. |
| Others |
Supply Flow & Price Mechanics
North American quick-service chains and artisanal bakery buyers concentrate procurement power, anchoring contract-based long-term offtake pricing that rewards certified supply chains with persistent premiums over spot-market commodity flows.
Pricing Analysis
Margin tightening in hulled and toasted grades reflects FSMA compliance investments and automated hulling equipment amortization. Three-tier pricing structure across premium, standard, and economy levels separates identity-preserved certified lots from conventional food-grade and oil-extraction natural grades. Price differentiation hinges on certification depth and volume scale, with bakery chains least sensitive and oil crushers most responsive to raw seed cost swings.
Supply Chain Analysis
Direct-origin contracting from Ethiopian and Sudanese cooperatives to North American roasters is displacing trader intermediation. Geographic supply concentrates in Sudan, Ethiopia, and India, with crushing infrastructure drawing from Gujarat and Rajasthan mills. Input dependencies center on fertilizer, irrigation energy, and chromatography testing capacity. Single-source vulnerability in East African origination networks poses structural risk to shipment execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smallholder consolidation and aflatoxin certification bottlenecks constrain exportable surplus, propping pricing power for integrated processors with captive supply bases.
For Market Incumbents: Hedge against substitution threats from sunflower and rapeseed oils by deepening backward integration into controlled-application farming contracts in Ethiopia's Wollega region. Lock in multi-year offtake agreements with Sudanese cooperatives to defend margin position against spot-market volatility and FSMA traceability mandates that filter out non-compliant competitors. For New Entrants and Emerging Players: Launch via blockchain-enabled provenance platforms targeting online retail channels for organic and single-origin certifications. West African origins in Nigeria and Burkina Faso offer the most penetrable white-space for acreage expansion with suitable agro-ecology and nascent export infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor East African origination-integrated processors with pre-shipment testing laboratories and EU Green Deal alignment credentials. Watch aflatoxin certification timeline compression as the inflection signal for working capital efficiency gains across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Application Farming | Captive supply secures FSMA-compliant lots for North American quick-service chains. |
| Blockchain-Enabled Provenance Platform | Distributed ledger verification compresses audit costs for EU customs clearance. |
| Automated Hulling and Roasting Capacity Expansion | Seven-figure equipment investments exclude smaller processors from margin-rich segments. |
| West African Acreage Development | Nigeria and Burkina Faso harbor untapped cultivation potential with suitable agro-ecology. |
| Cosmetics-Grade Black Sesame Cultivation | Anthocyanin-rich varieties target South Korean MFDS-registered skincare formulators. |
Methodological Framework
Multi-period observation of export volume flows, certification adoption rates, and processing capacity utilization anchored the trend analysis, supplemented by interviews with Ethiopian cooperative managers, Sudanese export traders, North American roasting facility operators, and FSSAI compliance officers. Secondary validation drew from customs trade databases, FDA import refusal records, EFSA pesticide residue monitoring reports, and SEC filings of listed agribusiness conglomerates. Bottom-up acreage and yield estimates triangulated against top-down consumption surveys across food, cosmetics, and pharmaceutical end-use channels.
Input-output matrices mapped seed variety, processing intensity, and end-use application to value chain margin capture across the projection horizon. Segmentation dimensions modeled included product type, application vertical, end-user industry, and distribution channel. CAGRs derived from regression analysis of historical price series and elasticity-adjusted demand projections, with fertilizer cost indices and hydrocarbon-linked irrigation energy prices as key forecast inputs.
Geopolitical disruption in East Africa, ECHA REACH threshold tightening, and blockchain platform adoption velocity are the dominant revision risks to base case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Sri Lanka Seed Market
Seeds
South America Vegetable Seed Market
Seeds
South America Chia Seeds Market
Seeds
Carrot Seed Oil Market
Seeds
Europe Seed Market
Seeds
Organic Sesame Seed Market
Seeds
Agricultural Seeder Market
Seeds
Dragon Fruit Seeds Market
Seeds
India Vegetable Seed Market
Seeds
Europe Chia Seeds Market
Seeds
Cherry Tomato Seeds Market
Seeds
Global Soybean Seed Market
Seeds
Quinoa Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Cannabis Seeds Market
Seeds
Global Seed Market