
 France Food Emulsifiers Market | 2026-2036
France Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Emulsifiers Market Foresight
Direct sales channels from emulsifier manufacturers to French food processing units is tilting toward technical partnership models rather than transactional supply. Cargill Incorporated leverages its integrated oilseed processing footprint to secure consistent lecithin feedstock for bakery clients. Kerry Ingredients France SAS anchors its position through application-specific formulation labs in Brittany. SEPPIC competes in high-performance polysorbate grades for confectionery and dairy alternatives.
Food emulsifiers are surface-active agents that reduce interfacial tension between immiscible phases such as oil and water, typically comprising amphiphilic molecules with hydrophilic-lipophilic balance values between 3 and 16. These compounds stabilize emulsions, control crystallization, and improve texture in processed foods through mechanisms involving micelle formation and electrostatic repulsion. Mono- and diglycerides occupy the largest volume position due to their cost efficiency and broad regulatory acceptance across French bakery applications. Polysorbates generate premium margin pools where ultra-stable emulsions are required in dairy alternatives and dressings. Lecithin segments are accelerating as non-GMO and organic certification requirements reshape procurement from food processing units.
ANSM monitors food additive safety assessments while EFSA establishes maximum usage levels for emulsifiers under EU food law, with REACH compliance adding purity documentation burdens for fatty acid ester imports. France's DGCCRF enforces labeling transparency on processed foods containing E-number emulsifiers, directly influencing clean-label reformulation priorities. Stakeholders must monitor evolving EFSA re-evaluations of polysorbate toxicology and anticipate stricter origin disclosure rules for lecithin sources.
Market Dynamics
Clean-label reformulation pressure from ANSM and EFSA is forcing French food processors to abandon synthetic emulsifier codes while maintaining functional performance in industrial bakery and dairy alternative applications.
Growth Catalysts
- EFSA purity threshold tightening:Stricter documentation requirements for lecithin and mono-diglyceride formulations are accelerating investment in certified supply chains among Parisian industrial bakeries.
- Île-de-France processing corridor concentration:Clustering of dairy alternative producers around Parisian logistics hubs generates localized demand pull for high-performance emulsifier systems.
- Non-GMO certification acceleration:Organic procurement mandates from major French retail chains are reshaping lecithin sourcing patterns toward identity-preserved oilseed programs.
Market Restraints
- Sunflower lecithin supply volatility:Ukrainian-origin feedstock disruptions have compressed margins for European emulsifier manufacturers dependent on Black Sea oilseed flows.
- REACH documentation burdens:Fatty acid ester imports face escalating purity verification costs that disadvantage smaller French compounders against integrated multinationals.
- Enzymatic emulsifier substitution threat:Lipase-modified flour systems are displacing chemical emulsifiers in artisanal bread segments where E-number avoidance commands premium positioning.
Strategic Opportunities
- Brittany formulation laboratory expansion:Technical partnership models between emulsifier suppliers and regional seafood processors open white space for marine-origin lecithin applications.
- CSRD supply chain disclosure mandates:Incoming EU sustainability reporting rules create first-mover advantage for emulsifier producers with certified carbon-accounted production systems.
- Plant-based cheese texture engineering:Melting behavior optimization in fermented dairy alternatives represents underpenetrated application territory for polysorbate-grade specialists.
Industry Challenges
- Clean-label formulation skill scarcity:Industrial bakeries struggle to recruit food technologists capable of balancing E-number elimination with shelf-life extension in viennoiserie applications.
- Dual certification timeline compression:Simultaneous organic and non-GMO verification processes for lecithin suppliers extend qualification cycles beyond typical contract renegotiation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Emulsifiers Market |
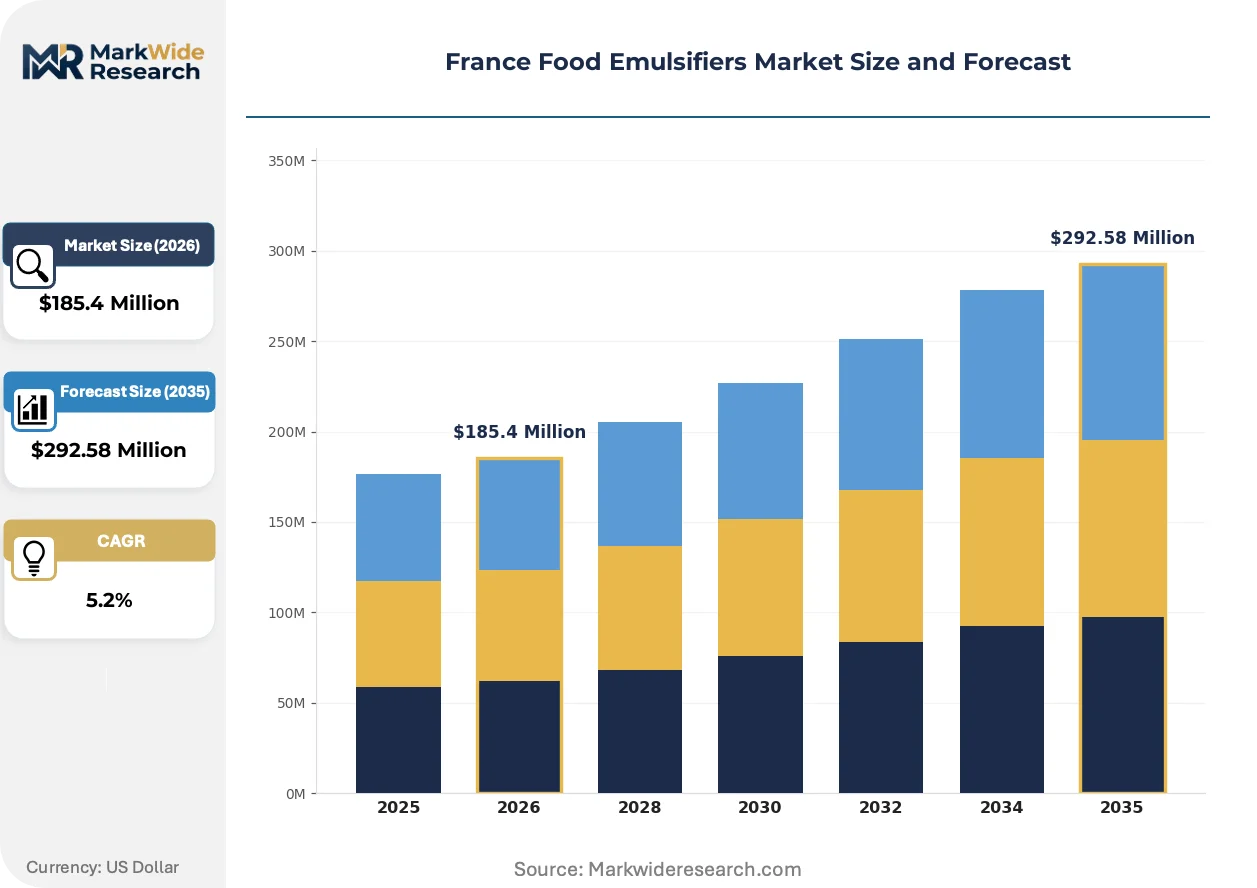
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $292.58 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono- and Diglycerides, Lecithin, Polysorbates, Esters of Fatty acids, Propylene Glycol Esters Application: Bakery, Confectionery, Dairy Alternatives, Dressings & Sauces, Beverages End User: Food Processing Units, Snack Manufacturers, Beverage Producers, Culinary Professionals Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialized Stores |
| Companies Covered | Cargill Incorporated, Caldic BV (Arlès Agroalimentaire), Henry Franc SAS, Novastell, Stearinerie Dubois, Kerry Ingredients France SAS, Palsgaard France SAS, Corbion France SAS, SEPPIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Emulsifiers Market Shifts & Advancements
Functional ingredient architecture in French food processing is pivoting toward label-friendly molecular engineering that preserves emulsion stability without triggering consumer rejection of additive codes.
Enzyme-modified lecithin technology is hybridizing hydrolyzed phospholipid functionality with organic certification eligibility. Brittany-based dairy alternative manufacturers are adopting these systems at pilot scale for oat-based barista formulations. The technology is hybridizing cost structures between commodity lecithin and premium synthetic emulsifiers, compressing mid-tier margin pools.
EFSA re-evaluation protocols for polysorbate toxicology are tightening maximum usage thresholds across confectionery categories. French regulators at ANSM are aligning national enforcement with pending EU-wide safety assessments, triggering preemptive reformulation investments among nougat and chocolate producers. High-performance polysorbate grades face accelerated substitution pressure in infant nutrition applications where safety margins command disproportionate regulatory scrutiny.
Buyer concentration among Île-de-France industrial bakeries is consolidating procurement decisions toward integrated technical service contracts. Traditional ingredient distribution through regional chemical wholesalers is yielding to direct manufacturer partnerships embedding application laboratories and regulatory compliance support. This channel restructuring is most visible in Parisian peripheral zones where plant-based dairy scale-ups negotiate multi-year supply agreements with attached formulation development resources.
France Food Emulsifiers Market Segmentation
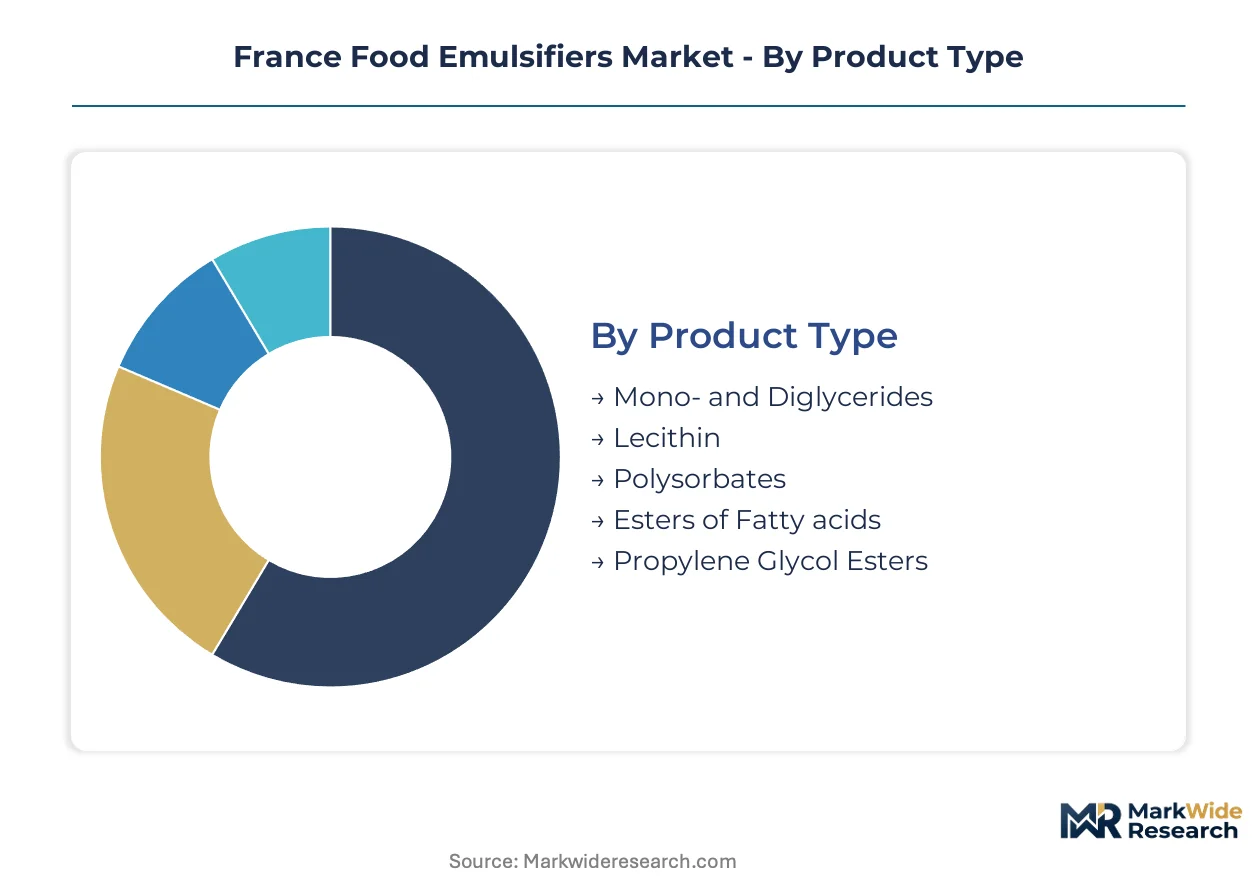
Emulsifier procurement patterns in France diverge sharply across product chemistries and end-use specifications. Technical service intensity and regulatory documentation burdens reshape how suppliers structure segment-specific value propositions for Parisian industrial bakeries versus Brittany seafood processors.
Product Type:
After-sales technical support requirements intensify with product complexity, as hydrolyzed lecithin and polysorbate grades demand ongoing formulation troubleshooting that commodity mono-diglycerides rarely require.
- Mono- and Diglycerides:These fatty acid esters of glycerol dominate volume flows through their cost efficiency and broad EFSA clearance for industrial bread applications. ANSM labeling enforcement has not displaced these workhorse emulsifiers from viennoiserie production in Île-de-France facilities, where shelf-life extension remains non-negotiable.
- Lecithin:Phospholipid mixtures from sunflower and rapeseed sources carry the heaviest certification burden among major emulsifier categories. Organic and non-GMO dual verification timelines stretch supplier-customer relationships, yet Brittany dairy alternative manufacturers absorb these friction costs for clean-label positioning in oat-based barista formulations.
- Polysorbates:Ethoxylated sorbitan esters command premium positioning where ultra-stable emulsions resist thermal stress in confectionery and infant nutrition. EFSA toxicology re-evaluations are compressing maximum usage thresholds, forcing ANSM-aligned reformulation investments.
- Esters of Fatty acids:Succinylated and acetylated variants serve niche texturizing roles in whipped toppings and frozen desserts.
- Propylene Glycol Esters:These lipophilic stabilizers find specialized deployment in cake gels and aerated confectionery systems.
By volume, Mono- and Diglycerides leads. By growth pace, Lecithin is ahead.
Application:
Application-specific margin structures reflect diverging technical barriers, with dairy alternatives commanding formulation laboratory investments that commodity bakery supply rarely justifies.
- Bakery:Industrial bread and viennoiserie production consumes emulsifier volumes through dough conditioning and crumb softening functions. Parisian peripheral zones concentrate procurement decisions among integrated technical service contracts that embed application laboratories.
- Dairy Alternatives:Fermented plant-based cheeses and oat barista milks represent the steepest expansion trajectory for high-performance emulsifier systems. Melting behavior optimization and protein stabilization demands pull polysorbate-grade specialists into multi-year supply agreements with attached formulation development resources.
- Confectionery:Nougat and chocolate applications face preemptive reformulation as EFSA polysorbate thresholds tighten.
- Dressings & Sauces:Mayonnaise and vinaigrette emulsions require intermediate HLB balance for cold-process stability.
- Beverages:Clouding agents and flavor emulsions in soft drinks utilize modified starch and gum arabic blends more heavily than synthetic emulsifiers.
Application concentration tilts toward Bakery for volume, though Dairy Alternatives expands most quickly.
End User:
Customer scale determines procurement modality, with large food processing units negotiating direct manufacturer partnerships while smaller operators remain tethered to wholesale distribution.
- Food Processing Units:Industrial bakeries and dairy alternative scale-ups in Île-de-France anchor demand through technical partnership models rather than transactional supply. These buyers consolidate procurement decisions toward integrated contracts embedding regulatory compliance support.
- Snack Manufacturers:Extruded and coated snack production utilizes emulsifiers for flavor encapsulation and anti-sticking functions.
- Beverage Producers:Juice and soft drink formulators prioritize cloud stability and flavor emulsion shelf life.
- Culinary Professionals:Artisanal bakers and restaurant kitchens represent fragmented demand for small-format lecithin and specialty ester grades.
Food Processing Units dominates segment revenue, yet procurement pattern divergence across customer scale reshapes channel economics.
Distribution Channel:
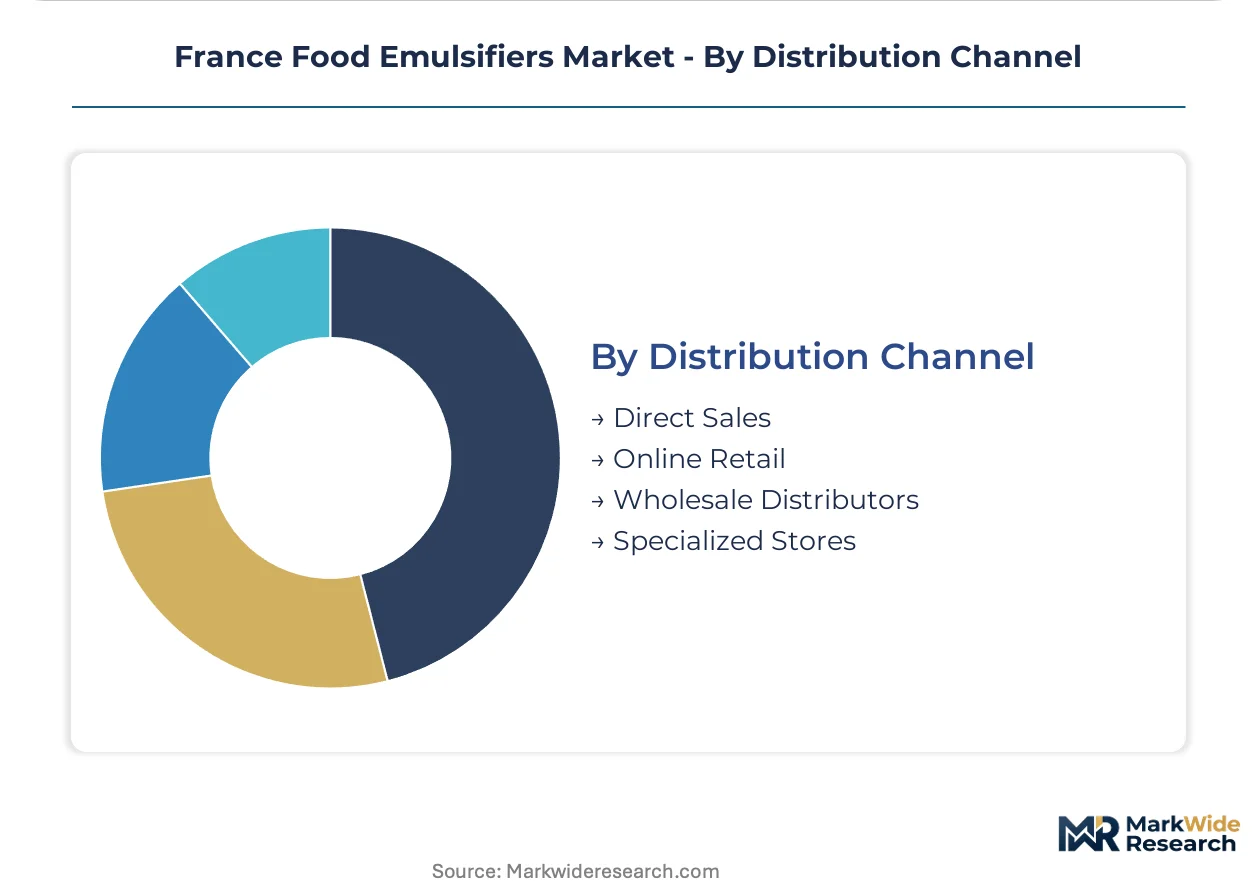
Channel selection reflects order size predictability and technical support requirements, with direct sales capturing relationship-intensive accounts and wholesale retaining fragmented smaller buyers.
- Direct Sales:Manufacturer-to-processor relationships dominate emulsifier flows for certified organic and non-GMO grades requiring origin documentation. These channels embed formulation laboratories and ANSM compliance support that wholesale distributors cannot replicate.
- Wholesale Distributors:Regional chemical wholesalers retain commodity mono-diglyceride volumes for mid-tier bakeries without clean-label mandates.
- Online Retail:Small-format specialty emulsifiers for culinary professionals and artisanal producers migrate toward digital procurement.
- Specialized Stores:Ingredient supply outlets serving independent bakers stock limited lecithin and ester varieties.
Direct Sales commands the highest value per kilogram, while Wholesale Distributors retains volume leadership in conventional grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Île-de-France while peripheral regions absorb supply-chain friction costs. Brittany and Hauts-de-France operate at margin compression due to logistics distance from oilseed processing hubs. ANSM regulatory alignment with EFSA standards creates uniform compliance costs that favor scale concentration around Parisian corridors.
Île-de-France
Industrial bakeries and dairy alternative scale-ups cluster in Parisian peripheral zones, driving consolidated procurement toward direct manufacturer partnerships. ANSM labeling enforcement tightens E-number disclosure requirements for processed foods distributed through national retail chains. Saint-Denis and Bobigny processing corridors anchor demand for certified organic lecithin systems with attached formulation laboratories.
Brittany
Seafood processors and oat-based barista formulation pilots generate specialized demand for marine-origin lecithin applications. EFSA purity documentation requirements extend qualification cycles for organic-certified emulsifier supply. Rennes and Saint-Brieuc host technical partnership models between regional dairy alternative manufacturers and emulsifier suppliers embedding application-specific labs.
Hauts-de-France
Artisanal bread segments face enzymatic emulsifier substitution pressure where E-number avoidance commands premium positioning. REACH compliance burdens for fatty acid ester imports disadvantage smaller compounders against integrated multinationals. Lille metropolitan bakeries navigate clean-label reformulation skill scarcity while maintaining shelf-life extension in viennoiserie production.
Auvergne-Rhône-Alpes
Confectionery producers in Lyon and Grenoble confront preemptive reformulation investments as EFSA polysorbate toxicology re-evaluations tighten maximum usage thresholds. Nougat and chocolate applications absorb escalating purity verification costs for high-performance emulsifier grades. Regional procurement tilts toward technical service contracts embedding regulatory compliance support.
Nouvelle-Aquitaine
Sunflower lecithin supply volatility from Ukrainian-origin feedstock disruptions compresses margins for processors dependent on Black Sea oilseed flows. Bordeaux and Toulouse industrial bakeries diversify sourcing toward identity-preserved rapeseed programs. CSRD supply chain disclosure mandates create first-mover positioning for producers with certified carbon-accounted production systems.
France Food Emulsifiers Market Competitive Landscape
Integrated multinationals and regional specialists split the market along certification intensity and technical service depth. The vendor base concentrates around three strategic archetypes: oilseed-integrated lecithin suppliers, application-specific formulation laboratories, and high-performance synthetic emulsifier specialists. Consolidation pressures favor backward integration into oilseed crushing and forward integration into embedded formulation partnerships. Geographic expansion through Brittany and Hauts-de-France technical service centers represents the dominant competitive move alongside portfolio diversification into enzyme-modified lecithin hybrids.
Among oilseed-integrated suppliers, Cargill Incorporated anchors the commodity lecithin tier through captive feedstock security. Kerry Ingredients France SAS and SEPPIC occupy distinct positioning vectors within the technical service-intensive segment, with the former exemplifying application laboratory embedding and the latter representing high-performance polysorbate specialization. These three companies collectively illustrate how competitive advantage in this market derives from supply chain control, regulatory compliance infrastructure, and formulation partnership depth rather than transactional price positioning alone.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Caldic BV (Arlès Agroalimentaire) |
| Henry Franc SAS |
| Novastell |
| Stearinerie Dubois |
| Kerry Ingredients France SAS |
| Palsgaard France SAS |
| Corbion France SAS |
| SEPPIC |
| Others |
Supply & Pricing Matrix
Ukrainian-origin sunflower lecithin feedstock concentration in Black Sea crushing corridors compresses margin pools for French compounders downstream, redirecting pricing power toward identity-preserved rapeseed programs and integrated oilseed processors with captive supply security.
Pricing Analysis
Configured-to-order pricing for certified organic and non-GMO lecithin systems commands substantial premiums over standard mono-diglyceride grades. Price differentiation rests on dual certification timelines and attached formulation laboratory services rather than commodity feedstock costs alone. Cost compression in mid-tier polysorbate segments is intensifying because EFSA toxicology re-evaluations are forcing reformulation investments. Industrial bakeries in Île-de-France exhibit lowest price sensitivity due to shelf-life non-negotiability, while artisanal bread segments absorb enzymatic substitution to avoid E-number disclosure.
Supply Chain Analysis
Extended payment terms from integrated multinationals are squeezing regional compounder liquidity, forcing smaller French distributors toward supply-chain finance facilities or exit. Raw material flows draw from Ukraine, Russia, and Argentina for sunflower lecithin, with rapeseed alternatives anchoring in European Union crushing capacity. Single-source vulnerability to Black Sea logistics chokepoints represents the dominant structural risk. Distribution runs through direct manufacturer partnerships for certified grades, while wholesale channels retain commodity mono-diglyceride volumes for mid-tier bakeries without clean-label mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France food emulsifiers sits in early-cycle expansion as dairy alternative scale-ups in Île-de-France and Brittany accelerate technical partnership demand for high-performance emulsion systems.
For Market Incumbents: Pre-empt enzymatic emulsifier substitution in artisanal bread segments by embedding application laboratories in Hauts-de-France technical service centers. Secure backward integration into identity-preserved rapeseed crushing to defend margin position against Ukrainian supply volatility. Prioritize CSRD-compliant carbon accounting infrastructure to capture first-mover advantage in sustainability disclosure mandates from Parisian retail chains. For New Entrants and Emerging Players: Establish a beachhead in marine-origin lecithin applications for Brittany seafood processors, where incumbent coverage remains thin and technical partnership models are nascent. Target oat-based barista formulation pilots in Rennes corridors as the most penetrable white space, leveraging enzyme-modified phospholipid hybrids that bridge commodity and premium positioning. Lead with regulatory compliance support bundled into supply agreements rather than transactional pricing. For Investors and Strategic Acquirers: Capital is best deployed toward application-specific formulation laboratories with embedded ANSM compliance infrastructure, as these assets command sustained premium pricing through the projection horizon. Acquisition targets should demonstrate dual organic-non-GMO certification capabilities and established relationships with Île-de-France dairy alternative scale-ups. Watch EFSA polysorbate threshold finalization as the critical inflection signal for reformulation investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captive rapeseed supply secures margin stability against Black Sea feedstock disruption for Île-de-France compounders. |
| Application Laboratory Embedding | Technical partnership models with Brittany dairy alternative manufacturers lock in multi-year supply agreements with attached formulation development. |
| Dual Certification Investment | Organic and non-GMO verification timelines extend supplier-customer relationships beyond typical contract renegotiation windows for lecithin procurement. |
| Enzyme-Modified Lecithin Hybrid Development | Hydrolyzed phospholipid functionality with organic eligibility compresses mid-tier margin pools between commodity and synthetic emulsifiers. |
| CSRD Supply Chain Disclosure Compliance | Certified carbon-accounted production systems create first-mover positioning with Parisian retail chain procurement mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANSM enforcement bulletins, EFSA scientific opinions, DGCCRF labeling inspection reports, and customs trade data for fatty acid ester imports. Primary interviews engaged plant managers at Île-de-France industrial bakeries, procurement leads at Brittany dairy alternative manufacturers, technical R&D directors at emulsifier compounders, and regulatory affairs specialists navigating REACH documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for food processing investment across French regions.
Forecast inputs considered product chemistry grade tiers, end-use application specifications, customer scale procurement modalities, and regional production hub clustering. Modeled dimensions spanned mono-diglyceride commodity flows, lecithin certification tiers, polysorbate performance grades, bakery versus dairy alternative demand splits, and direct sales versus wholesale channel economics. CAGRs were derived from segment-level growth trajectory analysis incorporating EFSA regulatory timeline assumptions and CSRD implementation pacing across the analysis window.
Stress conditions across Ukrainian feedstock availability, EFSA polysorbate threshold stringency, and enzymatic substitution penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory alignment timelines and certification adoption curves. Macroeconomic contraction, accelerated EFSA re-evaluation schedules, or breakthrough enzymatic emulsifier efficacy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Food Antimicrobial Additives Market