
 Asia-Pacific Food Preservatives Market | 2026-2036
Asia-Pacific Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Preservatives Market Outlook
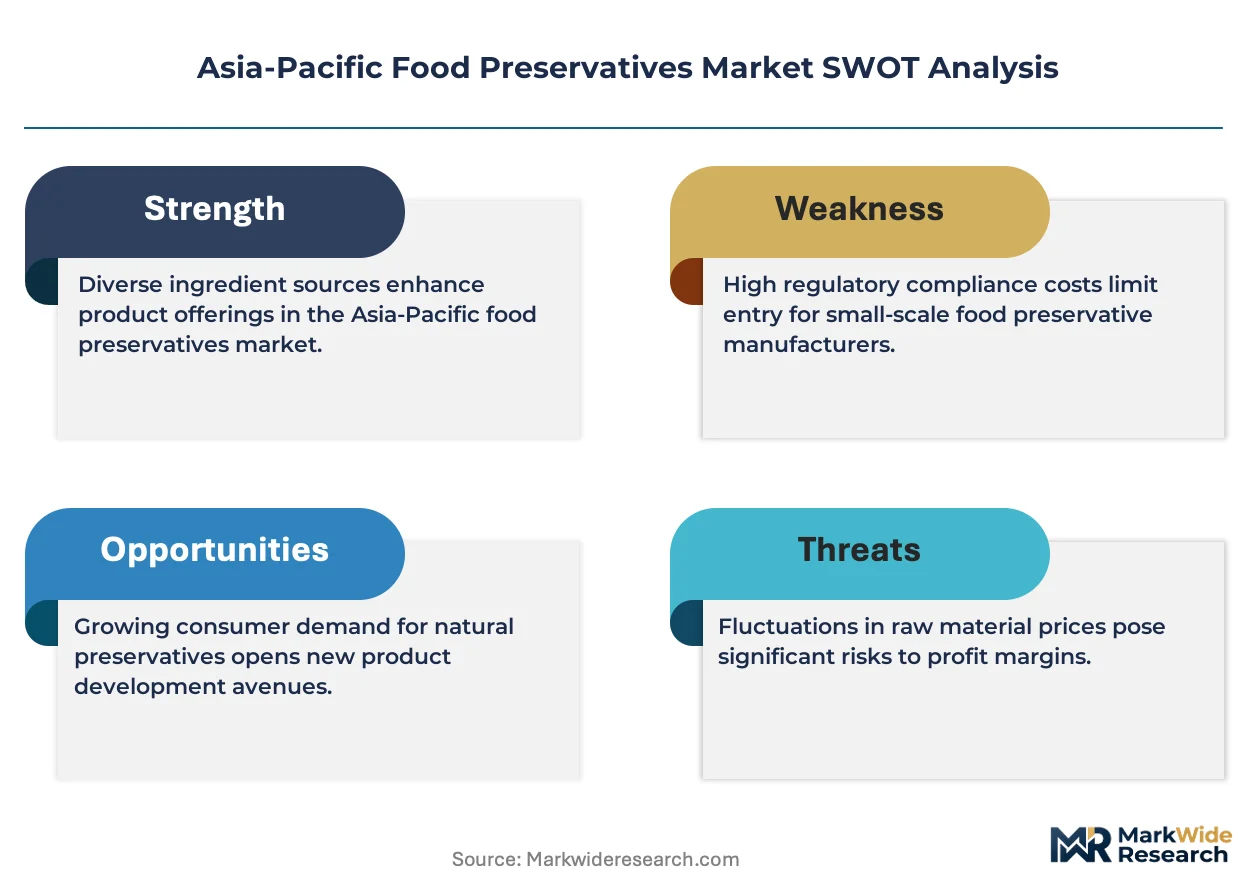
FSSAI licensing cycles and ISO 22000 certification requirements are rotating supplier eligibility across India and Southeast Asia, forcing reformulation investments before market access. Cargill Incorporated leverages its integrated supply chain from acidulants to antimicrobial blends across Thailand and Indonesia. Kerry Group sustains regional R&D facilities in Singapore that customize clean-label preservation systems for Japanese export specifications. BASF SE competes through synthetic antioxidant scale, though its positioning navigates tightening natural-label preferences in Australian retail channels.
Food preservatives comprise chemical or natural substances added at 0.01% to 0.5% concentration to inhibit microbial spoilage, enzymatic browning, or oxidative rancidity in packaged foods, typically via direct incorporation into product matrices or surface application in casings. Natural preservatives such as rosemary extract and cultured dextrose now command premium positioning as bakery manufacturers reformulate to meet retailer clean-label mandates. Chemical preservatives maintain volume dominance in meat products, where sodium nitrite and potassium sorbate deliver cost-effective shelf-life extension for mass-market processed proteins. Antioxidants represent the fastest-expanding functional class among beverage applications, driven by vitamin C and tocopherol demand in ready-to-drink formulations across tropical climates.
China's SAMR enforces GB 2760 additive standards that restrict benzoate levels in carbonated drinks, while Japan's Ministry of Health, Labour and Welfare maintains positive-list systems that block novel preservative entry without extensive safety documentation. India's FSSAI recently mandated QR-code-linked additive disclosure on packaged foods, accelerating manufacturer shifts toward recognizable ingredient declarations. Stakeholders must monitor divergence between ASEAN harmonization efforts and national reservation clauses that preserve country-specific maximum permitted levels.
Market Dynamics
Clean-label reformulation mandates from major retail chains are compressing procurement cycles for synthetic preservatives while accelerating natural alternative qualification timelines across Southeast Asian meat processing clusters.
Growth Catalysts
- China's SAMR enforcement of GB 2760 additive standards:Stricter benzoate limits in carbonated beverages are forcing manufacturers to seek compliant preservation alternatives, expanding the addressable market for natural acidulants and cultured dextrose systems.
- Processed meat sector expansion:Southeast Asian protein processors are building dedicated clean-label procurement functions to satisfy export specifications for Japanese and Australian retail channels, creating sustained demand for antimicrobial blends.
- FSSAI QR-code labeling mandate:India's requirement for additive disclosure transparency is accelerating manufacturer transitions toward recognizable ingredient declarations, privileging rosemary extract and vinegar-based preservation systems.
Market Restraints
- Natural preservative input cost volatility:Rosemary extract and tocopherol supply depends on agricultural harvest cycles in Spain and Morocco, creating margin compression for formulators locked into annual supply agreements.
- Technical shelf-life limitations:Clean-label alternatives deliver 15-30% shorter effective protection windows compared to synthetic nitrites in ambient-temperature meat applications, constraining distribution radius for reformulated products.
- Regulatory fragmentation across ASEAN:Country-specific maximum permitted levels for sorbates and benzoates prevent harmonized formulation strategies, forcing manufacturers to maintain multiple product SKUs for intra-regional trade.
Strategic Opportunities
- Indonesian bakery sector underpenetration:Traditional kue producers remain reliant on chemical preservation despite expanding modern retail distribution, creating conversion potential for cultured dextrose and fermented wheat flour systems.
- Vietnamese ready-to-drink beverage expansion:Tropical climate conditions and emerging cold-chain infrastructure gaps favor antioxidant-heavy formulation demand in vitamin C and green tea extract applications.
- Japan's positive-list system navigation:Extensive safety documentation requirements for novel preservatives create defensive moats for early movers who complete PMDA-compliant toxicology packages.
Industry Challenges
- ISO 22000 certification timeline compression:Supplier qualification cycles have shortened from 18 months to 9 months under retailer pressure, straining quality assurance team capacity and third-party audit availability.
- Reformulation R&D capex intensity:Clean-label transitions require dedicated pilot-scale production lines for sensory validation, with equipment utilization rates below 40% during multi-year qualification periods.
- Cross-border additive approval synchronization:Divergent national reservation clauses within ASEAN harmonization frameworks force parallel regulatory submissions, multiplying compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Preservatives Market |
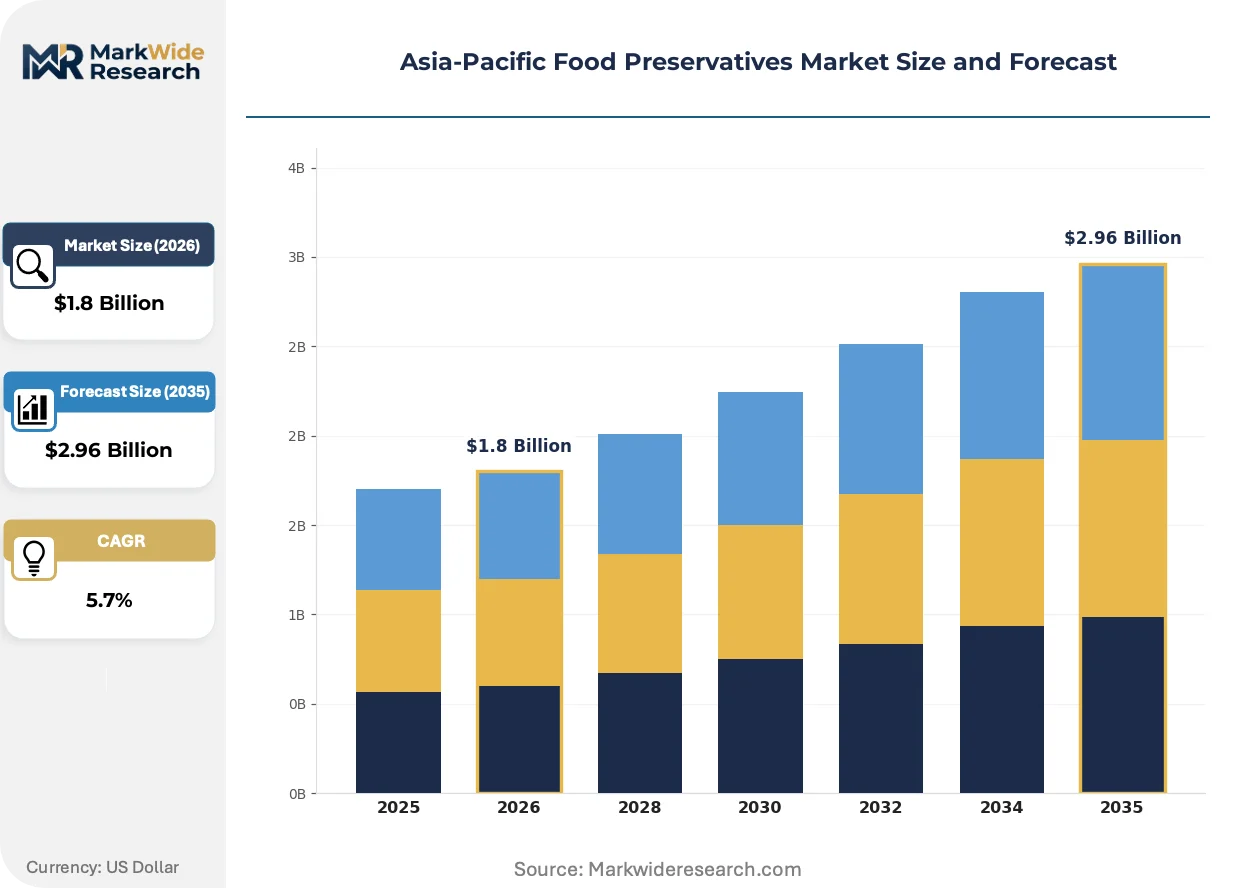
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Preservatives, Chemical Preservatives, Antioxidants, Antimicrobials Application: Bakery Products, Beverages, Dairy Products, Meat Products End User: Food Manufacturers, Retailers, Foodservice Providers, Households Formulation: Liquid, Powder, Granular, Emulsified |
| Companies Covered | Cargill Incorporated, Kerry Group, Koninklijke DSM N.V., DuPont, Archer Daniels Midland Company, BASF SE, Corbion N.V., Akzo Nobel N.V., Kemin Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Preservatives Market Strategic Shifts
Preservation technology is bifurcating between precision fermentation-derived antimicrobials and plant-extract systems, with adoption velocity determined by export market access requirements rather than domestic preference alone.
Precision fermentation for antimicrobial peptides is fragmenting supplier concentration in the natural preservation segment. Singapore-based biotech facilities are scaling cultured dextrose and nisin analog production for Japanese export-compliant meat applications. This distributed manufacturing model is eroding the volume advantages previously held by centralized European extract suppliers.
FSSAI's additive disclosure mandate is reshaping label architecture across Indian packaged food. The QR-code linkage requirement forces real-time supply chain traceability investments that smaller regional preservative blenders cannot fund. Bakery and snack manufacturers in Mumbai and Delhi processing clusters are consolidating supplier bases to three qualified partners maximum.
Buyer concentration among Southeast Asian supermarket chains is compressing switching cycles for preservative procurement. Centralized category management at Thai and Indonesian retail headquarters now mandates 12-month contract windows with performance clauses tied to clean-label achievement. This procurement centralization favors preservation system integrators who bundle acidulant, antimicrobial, and antioxidant functions under single-supplier accountability.
Asia-Pacific Food Preservatives Market Segmentation
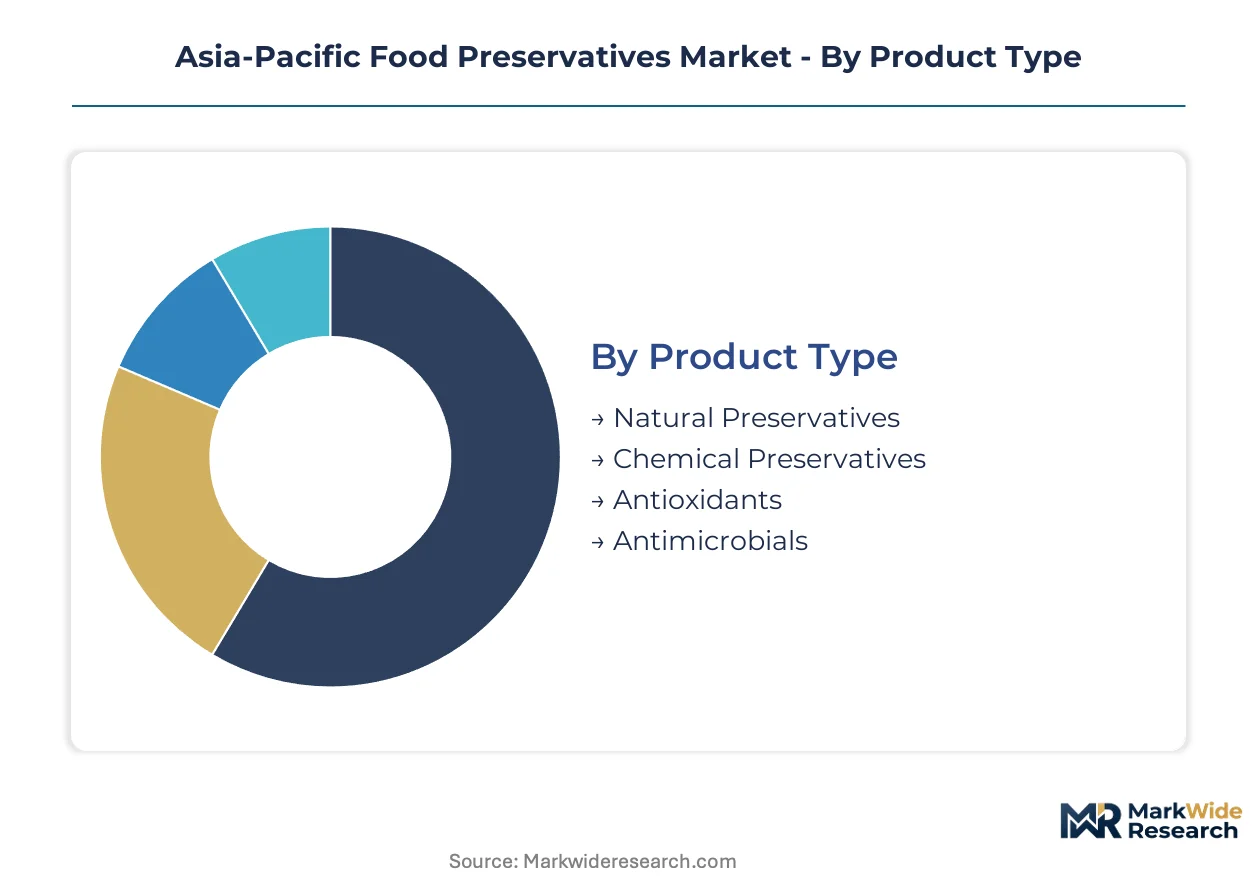
Segmentation reveals how preservation technology, application requirements, and supply chain configurations create distinct margin architectures across the Asia-Pacific food preservatives landscape. Each dimension shapes procurement decisions, regulatory compliance pathways, and supplier qualification intensity differently.
Product Type:
Margin pools concentrate in natural preservation systems where agricultural input scarcity and certification complexity sustain premium positioning, while chemical preservatives compete on volume scale and formulation reliability.
- Natural Preservatives:Derived from plant extracts such as rosemary and green tea, these systems command premium positioning through clean-label compliance for Japanese and Australian export channels. Demand concentrates in China's eastern seaboard processing clusters, where manufacturers reformulate to meet retailer mandates for recognizable ingredient declarations.
- Chemical Preservatives:Synthetic compounds including benzoates and sorbates deliver cost-effective shelf-life extension through precise antimicrobial action at low inclusion rates. Southeast Asian meat processors rely on these for mass-market distribution where ambient-temperature logistics dominate and price sensitivity constrains natural alternative adoption.
- Antioxidants:Ascorbic acid and tocopherol blends prevent lipid oxidation in tropical climate distribution.
- Antimicrobials:Nisin and cultured dextrose systems target Listeria control in refrigerated protein applications.
The dominant share belongs to chemical preservatives, while natural preservatives are closing the gap fastest.
Application:
Application-driven demand varies sharply by climate exposure, distribution infrastructure maturity, and retail channel consolidation intensity across the region.
- Meat Products:Processed proteins require dual-function preservation combining antimicrobial protection against pathogenic bacteria with antioxidant defense against rancidity. Thailand and Indonesia's expanding cold-chain networks enable nitrite-reduced formulations, though ambient segments still depend on synthetic preservatives.
- Beverages:Carbonated and ready-to-drink formulations face SAMR-enforced benzoate restrictions that accelerate natural acidulant adoption. Vietnam's tropical distribution conditions and emerging retail refrigeration gaps favor heavy antioxidant loading in vitamin C and green tea extract systems.
- Bakery Products:Mold inhibition drives propionate and cultured wheat flour demand in extended-shelf-life bread.
- Dairy Products:Fermented systems and HTST processing reduce preservative dependency in fresh segments.
Meat products anchor volume demand, though beverages are expanding most quickly on regulatory-forced reformulation.
End User:
End-user procurement sophistication determines whether preservation decisions prioritize cost minimization, label transparency, or supply chain traceability verification.
- Food Manufacturers:Integrated processors across China's Shandong and Jiangsu provinces drive bulk antimicrobial procurement for export-compliant meat and seafood production. FSSAI's QR-code disclosure mandate forces these manufacturers to consolidate supplier bases and invest in real-time ingredient traceability systems.
- Retailers:Centralized category management at Thai and Indonesian supermarket headquarters now mandates 12-month clean-label performance clauses. This procurement consolidation favors preservation system integrators who bundle acidulant, antimicrobial, and antioxidant functions under single-supplier accountability.
- Foodservice Providers:Limited cold-chain reach in tier-2 Vietnamese cities drives chemical preservative reliance.
- Households:Direct consumer purchases concentrate in vinegar-based and salt-curing traditional preservation.
Food manufacturers command the largest procurement volume, while retailers are gaining share fastest through centralized specification authority.
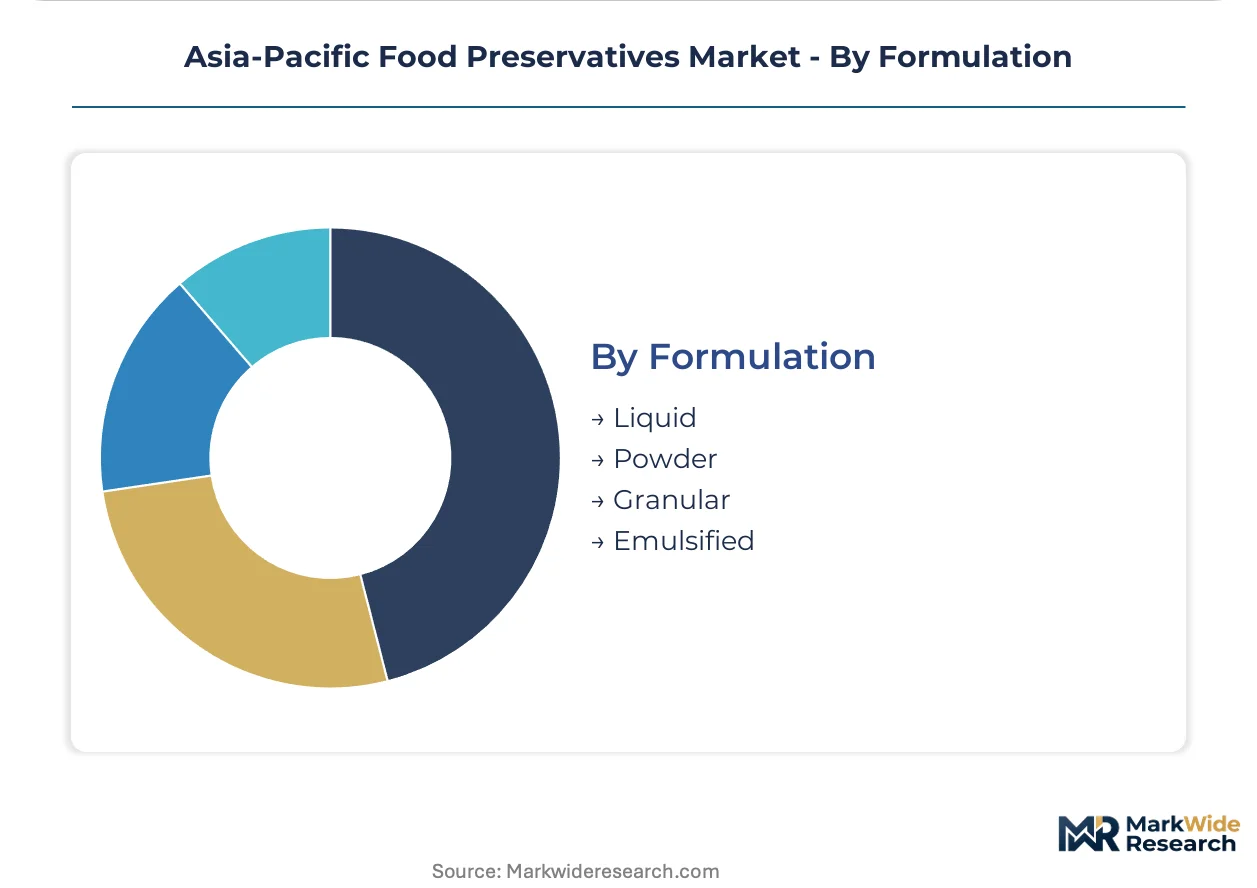
Formulation:
Form selection reflects processing equipment compatibility, dissolution kinetics requirements, and stability under regional humidity and temperature conditions.
- Liquid:Acidulant solutions and antimicrobial blends integrate directly into brine injection systems for processed meat operations. Indonesia's bakery sector underpenetration by modern preservation creates conversion potential for liquid cultured dextrose systems in automated dough conditioning.
- Powder:Dry blends of sorbates and benzoates offer extended stability and flexible dosing precision for small-batch manufacturers. India's FSSAI licensing cycles force reformulation investments that powder systems accommodate through equipment retrofit rather than line replacement.
- Granular:Free-flowing crystals suit dry-mix applications in seasoning and flour fortification.
- Emulsified:Lipid-dispersed antioxidants target high-fat bakery and confectionery matrices.
Liquid formulations hold the dominant position, though powder formats are climbing the fastest on small-manufacturer accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforcement of GB 2760 additive standards and FSSAI's QR-code labeling mandate are redirecting procurement flows across the region. China's eastern seaboard processing clusters anchor reformulation investment, while Southeast Asian meat processors build dedicated clean-label procurement functions.
China
Shandong and Jiangsu province food manufacturers drive bulk antimicrobial procurement for export-compliant meat production. SAMR's benzoate restrictions in carbonated beverages accelerate natural acidulant adoption. Qingdao and Shanghai processing clusters concentrate reformulation investment for Japanese retail compliance.
India
Mumbai and Delhi bakery clusters consolidate supplier bases to three qualified partners maximum under QR-code disclosure requirements. FSSAI licensing cycles rotate supplier eligibility, forcing reformulation investments before market access. Gujarat and Maharashtra food manufacturers invest in real-time ingredient traceability systems.
Japan
PMDA's positive-list system blocks novel preservative entry without extensive safety documentation. Kanto region beverage manufacturers seek compliant preservation alternatives for domestic distribution. Tokyo and Osaka processing clusters demand rosemary extract and tocopherol systems for retail channel access.
Thailand
Bangkok-centered meat processors expand cold-chain networks enabling nitrite-reduced formulations. Centralized category management at retail headquarters mandates clean-label performance clauses. Thai and Indonesian supermarket procurement consolidation favors preservation system integrators.
Vietnam
Tier-2 city foodservice providers rely on chemical preservatives where cold-chain infrastructure remains limited. Ho Chi Minh City beverage manufacturers load vitamin C and green tea extract antioxidants for tropical distribution. Emerging retail refrigeration gaps favor heavy antioxidant formulation demand.
Asia-Pacific Food Preservatives Market Competitive Environment
Player mix skews toward integrated multinational suppliers with acidulant-to-antimicrobial blend capabilities. Tiered concentration separates preservation system integrators from single-function specialists. Strategic archetypes include integrated supply chain operators, fermentation-derived antimicrobial specialists, and synthetic antioxidant scale players. Geographic expansion and portfolio diversification dominate competitive moves as manufacturers navigate divergent ASEAN regulatory frameworks.
Within the integrated supply chain tier, Cargill Incorporated and Kerry Group exemplify preservation system bundling across Thailand and Indonesia. Cargill leverages integrated acidulant-to-antimicrobial capabilities, while Kerry sustains Singapore-based R&D facilities customizing clean-label systems for Japanese export specifications. BASF SE occupies a position among synthetic antioxidant scale players, navigating tightening natural-label preferences in Australian retail channels.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Group |
| Koninklijke DSM N.V. |
| DuPont |
| Archer Daniels Midland Company |
| BASF SE |
| Corbion N.V. |
| Akzo Nobel N.V. |
| Kemin Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
FSSAI licensing cycles gate both supplier qualification and price differentiation simultaneously, compressing procurement timelines while fragmenting contract structures across India's reformulation-driven market. ISO 22000 certification requirements force parallel investments in traceability infrastructure, creating tiered access costs that separate integrated preservation system suppliers from single-function specialists.
Pricing Analysis
Annual cost-plus contracts with rosemary extract and tocopherol indexation dominate natural preservative procurement, while synthetic benzoate and sorbate agreements lock in volume-scaled unit economics. Price differentiation rests on clean-label certification tier and cold-chain delivery capability, with premium natural systems commanding substantial markups over chemical alternatives. Pricing pressure stems from agricultural input volatility in Mediterranean growing regions, tightening margins for formulators locked into fixed annual agreements. Small-batch bakery manufacturers in tier-2 Indian cities exhibit highest price sensitivity, whereas Japanese export-focused meat processors prioritize specification compliance over unit cost.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo and Singapore-Jakarta trade lanes elevates inbound logistics costs for European-sourced rosemary extract and Spanish tocopherol concentrates. Supply concentrates in China, India, and Thailand, with antimicrobial peptide fermentation scaling rapidly at Singapore-based biotech facilities. Raw material dependencies include Moroccan rosemary harvests, Chinese ascorbic acid production, and Indonesian palm-derived tocopherol fractions. Single-source vulnerability pervades natural extract supply, where climatic disruption in specific growing regions cascades through formulation availability. Distribution runs through regional blending facilities in Bangkok and Mumbai that customize preservation systems for national regulatory compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified toxicology documentation and precision fermentation scale-up capability constitute scarce assets that determine competitive survival, as regulatory barriers in Japan and India consolidate procurement around vertically capable suppliers.
For Market Incumbents: Secure PMDA-compliant safety dossiers for novel antimicrobial peptides before competitor submission windows close, while deepening backward integration into acidulant production to defend margin position against specialty chemical entrants. Expand Singapore R&D capacity to capture Japanese export specification demand as Kerry Group and Cargill intensify regional competition. For New Entrants and Emerging Players: Differentiate on precision fermentation-derived nisin analogs targeting Thailand's expanding refrigerated meat sector, where incumbent extract suppliers lack manufacturing presence. Target Vietnamese ready-to-drink beverage manufacturers with vitamin C and green tea extract antioxidant systems, leveraging tropical climate distribution gaps that favor heavy antioxidant loading. Pursue direct technical sales engagement with Jakarta-based bakery clusters converting from chemical to cultured dextrose preservation. For Investors and Strategic Acquirers: FSSAI's QR-code disclosure mandate reshapes the acquisition landscape toward preservation system integrators with real-time traceability infrastructure. Position for five-to-ten year viability around fermentation-derived antimicrobial specialists with completed Japanese regulatory packages, avoiding pure-play extract suppliers exposed to agricultural volatility. Monitor SAMR enforcement actions on benzoate levels as the signal indicating acceleration in natural acidulant substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Singapore-based biotech facilities erode European extract supplier volume advantages through distributed nisin analog production. |
| Backward Integration into Acidulants | Cargill's captive citric acid supply secures cost position for antimicrobial blend formulation across Thai meat processors. |
| PMDA Safety Documentation Investment | Early movers completing toxicology packages build defensive moats against novel preservative entry under Japan's positive-list system. |
| Real-Time Traceability System Deployment | FSSAI's QR-code mandate forces consolidation onto three qualified partners maximum in Mumbai and Delhi processing clusters. |
| Clean-Label R&D Facility Expansion | Kerry's Singapore customization centers capture Japanese export specification demand from reformulating Chinese manufacturers. |
Study Parameters
The analysis maps natural preservatives, chemical preservatives, antioxidants, and antimicrobials, each validated through formulation scientists at multinational suppliers, procurement directors at Southeast Asian meat processors, FSSAI regulatory consultants, and retail category managers in Thai supermarket headquarters. Primary interview findings triangulate against secondary sources including SAMR GB 2760 enforcement notices, FSSAI additive disclosure circulars, Japanese Ministry of Health positive-list updates, and ASEAN harmonization framework documents. Bottom-up volume estimates from application-level consumption patterns reconcile with top-down market sizing derived from supplier revenue disclosures across the analysis window.
Consistency checks validate volume and value outputs against customs trade data for preservative ingredient flows, SEC filings from listed suppliers, and industry association production statistics. The analytical framework segments by product type, application, end user, and formulation format across the projection horizon, with CAGRs derived from regression analysis of historical consumption growth adjusted for regulatory inflection timing. Forecast inputs incorporate cold-chain infrastructure build-out rates in Thailand and Vietnam, FSSAI licensing cycle compression effects, and SAMR enforcement intensity on benzoate restrictions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement pressure, stable agricultural harvest conditions in Mediterranean growing regions, and continued Japanese export market access would require recalibration. Forecasts reflect assumptions regarding clean-label transition velocity and fermentation technology cost curves, with practitioners keeping alternative scenarios live as ASEAN harmonization progress and national reservation clause divergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Protective Cultures Market